
 Depth Gauge Market | 2026-2036
Depth Gauge Market Size, Share, and Industry Trends Forecast 2026-2036
Depth Gauge Market Analysis
REACH compliance is expanding the cost-of-entry calculus for depth gauge manufacturers serving European industrial buyers. Mitutoyo leverages its captive metrology R&D infrastructure to sustain premium positioning across digital gauge lines. Starrett anchors its competitive stance through deep channel control in North American distribution networks.
A depth gauge measures the vertical distance from a reference surface to a feature bottom, typically employing hardened steel rules, micrometer screws, or piezoelectric transducers with resolution thresholds reaching 0.001 mm in laboratory-grade instruments. The device serves critical dimensional verification roles in machining, quality control, and underwater surveying applications. Digital gauges capture the dominant margin pool as manufacturers prioritize electronic measurement outputs for automated data logging, while ultrasonic gauges represent the fastest-expanding product category driven by non-destructive testing protocols in marine and aerospace end user segments. Electronic measurement technology leads volume deployment, though laser measurement systems command premium pricing in research applications requiring sub-micron accuracy.
FDA calibration standards shape medical device manufacturing demand in the United States, while CE marking and EU MDR frameworks govern European market access for precision instruments. ISO 17025 accreditation requirements are tightening across third-party calibration laboratories, forcing gauge vendors to document traceability chains or risk exclusion from certified procurement channels. Stakeholders must monitor how NIST and national metrology institutes recalibrate tolerance benchmarks, as these revisions cascade directly into product specification cycles and replacement demand timing.
Market Dynamics
Ultrasonic depth gauge adoption in marine hull inspection is compressing replacement cycles for mechanical gauges while forcing calibration infrastructure upgrades across European manufacturing bases.
Growth Catalysts
- EU MDR calibration mandates:Medical device manufacturers in Germany, France, and Italy now require ISO 17025 traceable depth gauges, creating certified procurement channels that lock out non-compliant vendors.
- Marine non-destructive testing expansion:Shipping operators in Rotterdam, Singapore, and Houston are deploying ultrasonic gauges for underwater hull surveys, displacing manual diver measurements.
- Laser interferometry:Research laboratories in Switzerland and Japan are integrating sub-micron laser depth systems for semiconductor metrology, opening premium application tiers.
Market Restraints
- Hardened steel rule supply concentration:Precision steel substrate production clusters in Sweden and Japan, exposing gauge manufacturers to alloy price volatility and single-source risk.
- REACH substance restrictions:ECHA classification of certain piezoelectric ceramics as Substances of Very High Concern is forcing material substitutions in ultrasonic transducer manufacturing.
- Mechanical gauge substitution ceiling:Digital and ultrasonic technologies are displacing traditional dial gauges in high-precision applications, capping residual demand to cost-sensitive maintenance shops.
Strategic Opportunities
- India precision engineering corridor:BIS standards harmonization with ISO 10360 is enabling depth gauge vendors to access automotive and aerospace quality control budgets in Pune and Chennai.
- CSRD supply chain disclosure:EU corporate sustainability reporting mandates are forcing tier-one manufacturers to document metrology equipment provenance, favoring vendors with transparent calibration chains.
- AI-assisted measurement convergence:Machine vision algorithms paired with depth gauges are enabling real-time defect classification in automated machining cells.
Industry Challenges
- Metrology technician scarcity:ISO 17025 calibration expertise concentrates in aging workforces across Stuttgart, Coventry, and Detroit, constraining laboratory expansion timelines.
- Legacy system integration friction:Digital gauge outputs require MES/ERP middleware that many mid-tier machine shops lack, delaying electronic measurement adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Depth Gauge Market |
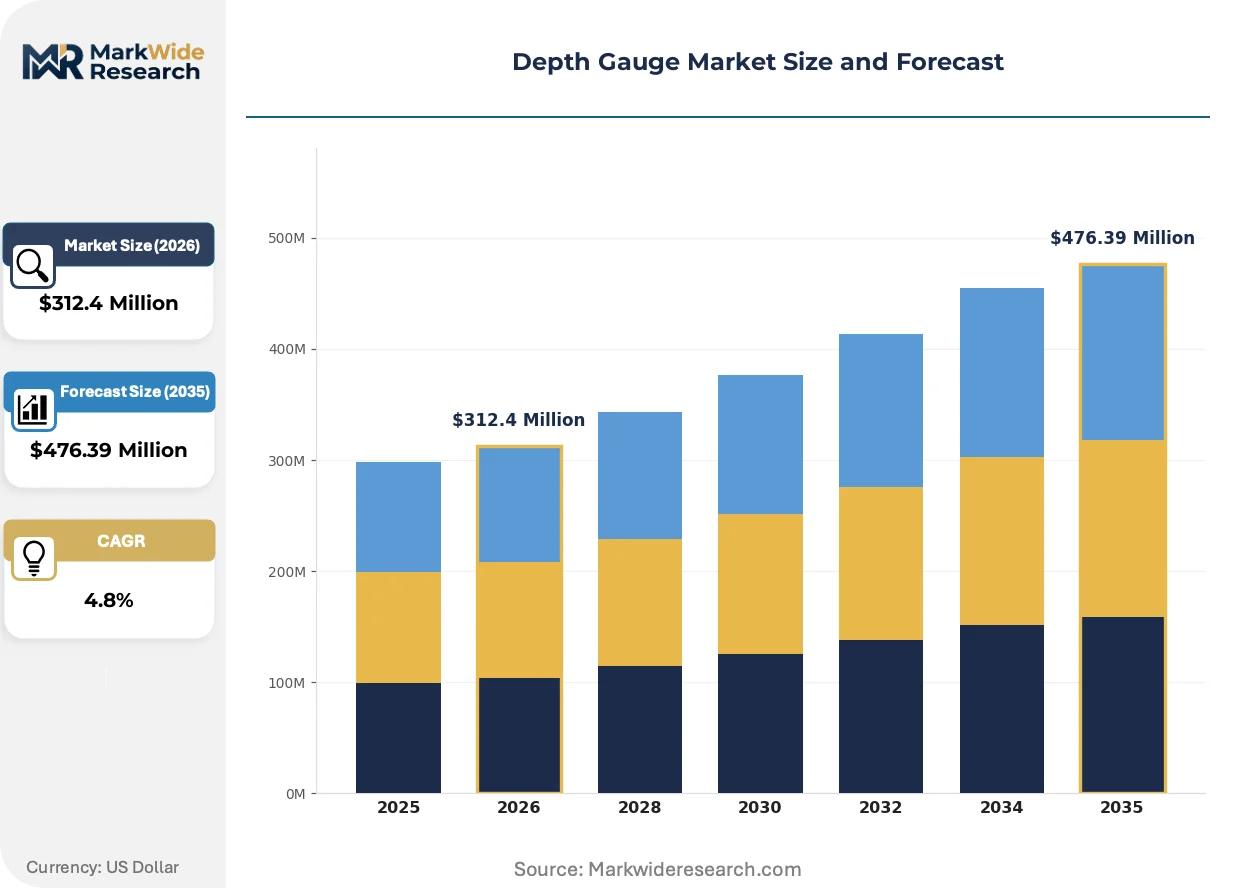
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Gauges, Vernier Depth Gauges, Mechanical Depth Gauges, Ultrasonic Gauges End User: Aerospace, Automotive, Construction, Marine Technology: Laser Measurement, Optical Measurement, Manual Measurement, Electronic Measurement Application: Inspection, Manufacturing, Research, Repair |
| Companies Covered | Mitutoyo, Starrett, Tesa, MAHR, Adolf Wurth GmbH & Co. KG, Beijing TIME High Technology, GURLEY Precision Instruments, Alpa Metrology, Baker Gauges India Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Depth Gauge Market Emerging Trajectories
Three interconnected shifts are restructuring competitive advantage: sensor fusion architectures, regulatory traceability mandates, and procurement centralization among tier-one manufacturers.
Ultrasonic phased-array technology is converging with digital signal processing to enable volumetric flaw detection alongside depth measurement. Aerospace MRO facilities in Toulouse and Seattle are piloting these systems for turbine blade inspection. The technology is converging with automated scanning robotics, compressing inspection throughput times by half versus manual point measurement.
EU MDR Article 10 technical documentation requirements now mandate calibration certificate retention for active implantable manufacturing equipment. German precision engineering clusters around Esslingen are upgrading gauge fleets to satisfy notified body audits. Digital gauge vendors with embedded certificate generation are capturing procurement preference in this compliance-driven replacement cycle.
Consolidated vendor management programs at automotive tier-ones are unbundling depth gauge procurement from broader metrology contracts. Buyers in Stuttgart and Detroit are negotiating direct calibration service agreements, bypassing traditional distribution markups. This pattern is most visible in powertrain machining operations where gauge volume justifies captive metrology engineering staff.
Depth Gauge Market Segmentation
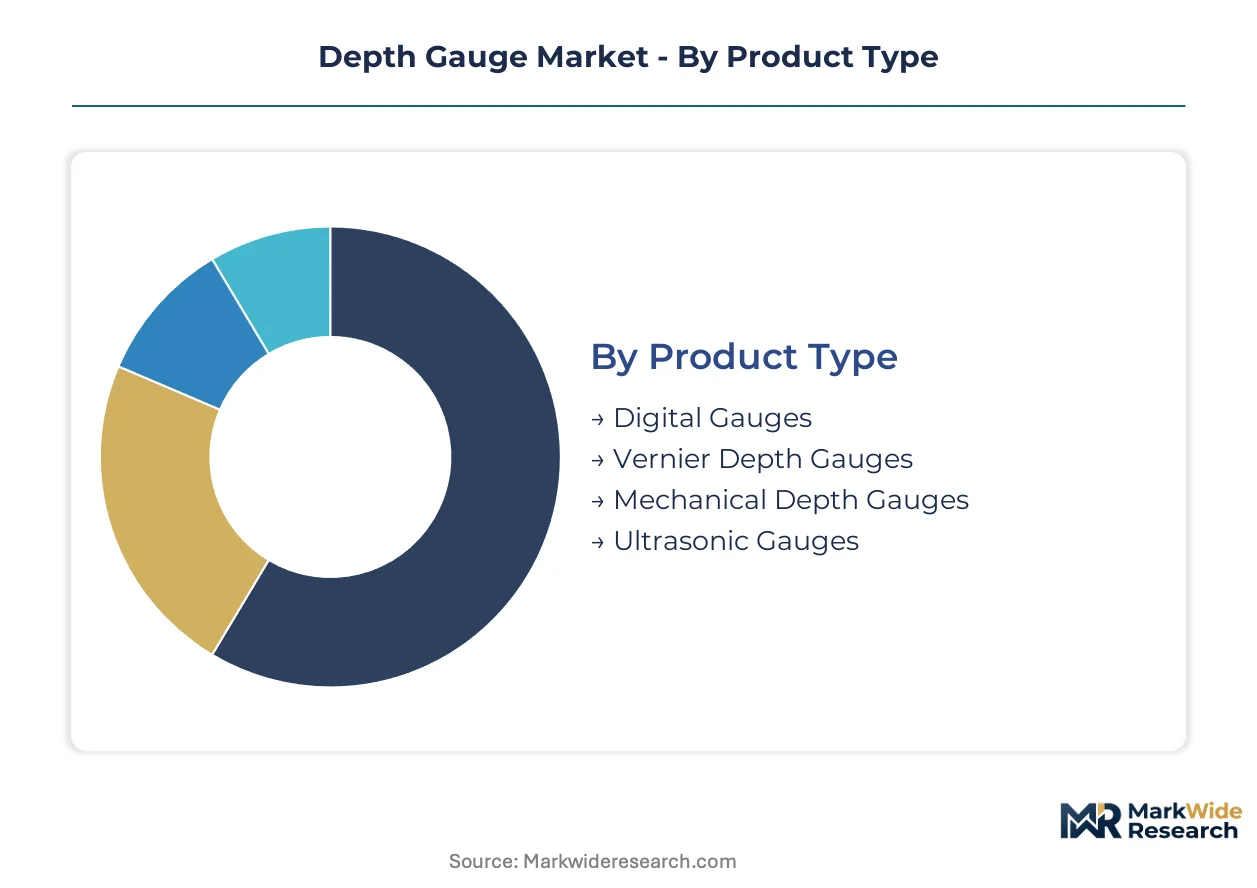
Technology differentiation and regulatory traceability requirements are fragmenting procurement patterns across depth gauge categories. Vendors must align product architectures with specific end-use certification demands to avoid channel exclusion.
Product Type:
Resolution thresholds and output formats separate premium digital lines from legacy mechanical alternatives.
- Digital Gauges:Electronic readout systems with RS-232/USB data logging interfaces dominate automated quality control stations. Automotive powertrain machining operations in Stuttgart and Detroit prioritize these units for SPC integration.
- Ultrasonic Gauges:Piezoelectric transducer arrays enable non-destructive thickness measurement through coatings and corrosion layers. Marine survey operators in Rotterdam and Singapore are displacing manual diver inspections with these systems for hull integrity verification.
- Vernier Depth Gauges:Hardened steel slide mechanisms with 0.02 mm resolution serve cost-sensitive maintenance workshops lacking calibration infrastructure.
- Mechanical Depth Gauges:Dial indicator configurations persist in legacy machining environments where electromagnetic interference compromises electronic reliability.
Digital gauges lead on scale; ultrasonic gauges lead on momentum.
End User:
Calibration stringency and volume procurement patterns vary sharply across industrial buyer segments.
- Automotive:Powertrain manufacturers enforce ISO 17025 traceable gauge fleets for crankshaft and cylinder block dimensional verification. CSRD disclosure mandates are forcing tier-one suppliers to document metrology equipment provenance.
- Aerospace:Turbine blade inspection protocols require sub-micron resolution systems with NIST-traceable certificates. MRO facilities in Toulouse and Seattle are piloting phased-array ultrasonic integration.
- Marine:Classification society rules are compressing drydock inspection intervals, expanding ultrasonic gauge deployment for underwater hull surveys.
- Construction:Structural steel fabrication tolerances drive demand for ruggedized mechanical gauges in field welding operations.
Automotive dominates procurement volume; aerospace commands premium pricing tiers.
Technology:
Measurement modality determines accuracy ceilings, environmental tolerance, and integration complexity.
- Electronic Measurement:Capacitive or inductive sensing elements with digital signal processing capture the dominant installed base. EU MDR calibration mandates are accelerating replacement of analog systems in medical device manufacturing.
- Laser Measurement:Interferometric principles achieve sub-micron resolution for semiconductor wafer metrology. Research laboratories in Switzerland and Japan absorb these systems despite five-figure unit costs.
- Manual Measurement:Vernier and micrometer screw mechanisms persist where power access is unreliable or operator training is limited.
- Optical Measurement:Machine vision triangulation systems are converging with depth gauges for automated defect classification in machining cells.
Electronic measurement anchors volume deployment; laser systems claim the steepest expansion trajectory in research applications.
Application:
Workflow integration requirements separate captive manufacturing gauges from portable field inspection units.
- Manufacturing:In-process dimensional verification demands hardened digital gauges with direct MES output. Stuttgart precision engineering clusters are upgrading fleets to satisfy notified body audits.
- Inspection:Third-party quality laboratories require ISO 17025 calibration documentation to maintain accreditation. Metrology technician scarcity in Coventry and Detroit is constraining laboratory expansion timelines.
- Repair:Maintenance operations prioritize portability and battery autonomy over absolute accuracy.
- Research:National metrology institutes drive demand for primary standard instruments with documented uncertainty budgets.
Manufacturing absorbs the largest gauge volume; inspection faces the tightest certification bottlenecks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision metrology manufacturing in the early 20th century, establishing calibration standards that now govern industrial measurement worldwide. This historical foundation shapes current demand patterns across manufacturing clusters in Stuttgart, Esslingen, and Dresden.
Germany
EU MDR calibration mandates and CSRD supply chain disclosure requirements drive gauge fleet upgrades across medical device and automotive sectors. The country's notified body audit protocols enforce ISO 17025 traceability for active implantable manufacturing equipment. Precision engineering corridors around Stuttgart and Esslingen are replacing analog systems with digital gauges featuring embedded certificate generation.
United States
FDA calibration standards for medical device manufacturing and NIST traceability requirements shape procurement in aerospace and defense applications. The country's national metrology institute periodically recalibrates tolerance benchmarks that cascade into product specification cycles. Detroit powertrain machining operations and Seattle-area aerospace MRO facilities anchor domestic demand for sub-micron resolution systems.
Japan
METI industrial standards harmonization with ISO 10360 and JIS certification requirements enable precision instrument exports across Asia-Pacific. Research laboratories in Nagoya and Tokyo absorb laser interferometry systems for semiconductor wafer metrology despite premium pricing. The country's piezoelectric ceramic supply chain feeds ultrasonic transducer manufacturing for marine non-destructive testing applications.
China
GB standards alignment with international metrology protocols and MIIT equipment certification programs accelerate domestic gauge production capacity. Automotive quality control budgets in Shanghai and Shenzhen are expanding as BIS-equivalent standards enable export market access. The Yangtze River Delta concentration of machine tool builders generates captive demand for hardened steel rule depth gauges.
India
BIS standards harmonization with ISO 10360 and PLI scheme incentives for precision manufacturing equipment open automotive and aerospace quality control budgets. CDSCO medical device regulations are tightening calibration documentation requirements for domestic manufacturers. Pune and Chennai precision engineering clusters are upgrading gauge fleets to satisfy tier-one supplier audit protocols.
Depth Gauge Market Vendor Landscape
The competitive structure tilts toward diversified metrology conglomerates with captive R&D infrastructure. Market concentration remains moderate, with premium digital gauge lines commanding procurement preference in certified manufacturing channels. Three archetypes dominate: precision engineering specialists with multi-decade calibration expertise, diversified industrial tool distributors leveraging channel density, and emerging Asian fabricators competing on cost-adjusted specifications. Capacity expansion and strategic partnerships represent the dominant competitive moves, as vendors secure alloy supply agreements and calibration laboratory accreditation.
Among diversified metrology specialists, Mitutoyo Corporation and Starrett anchor premium positioning through distinct capability vectors. Mitutoyo exemplifies the R&D-integrated archetype with captive metrology infrastructure sustaining digital gauge development. Starrett occupies a position defined by North American distribution network control, securing procurement relationships across maintenance and industrial tool channels. Adolf Wurth GmbH & Co. KG represents the industrial distribution archetype, leveraging European channel density to bundle depth gauges within broader metrology and fastening product portfolios. These three players illustrate how geographic origin and organizational structure shape competitive differentiation without requiring vertical integration into upstream steel substrate production.
| Leading Market Players |
|---|
| Mitutoyo |
| Starrett |
| Tesa |
| MAHR |
| Adolf Wurth GmbH & Co. KG |
| Beijing TIME High Technology |
| GURLEY Precision Instruments |
| Alpa Metrology |
| Baker Gauges India Private Limited |
| Others |
Supply Flow & Price Mechanics
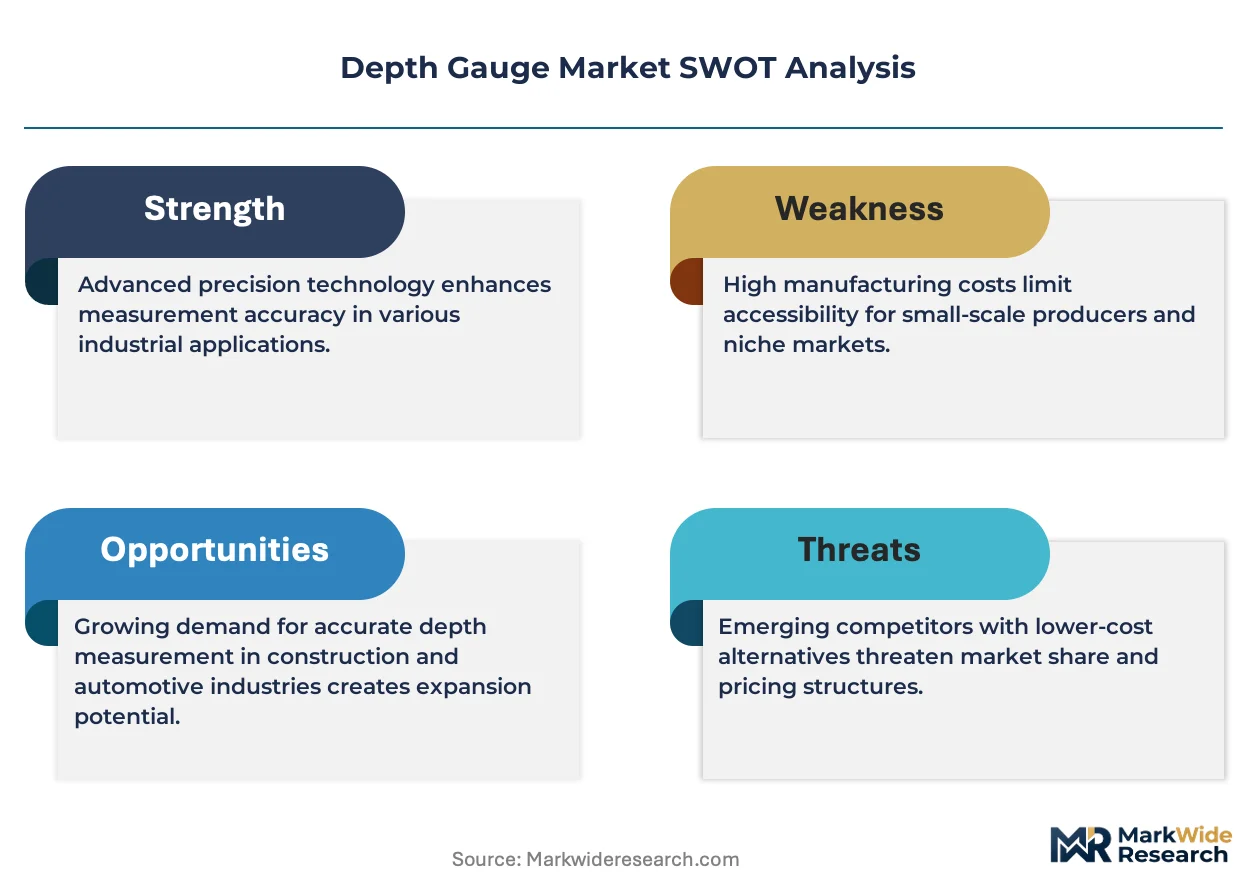
Phased-array ultrasonic gauge adoption in marine hull inspection is compressing cost structures for high-end digital systems while concentrating procurement leverage among calibration-certified vendors. This technology transition simultaneously elevates R&D amortization burdens and locks out uncertified competitors from EU MDR-compliant channels.
Pricing Analysis
Calibration service unbundling from hardware sales is fragmenting traditional pricing models. Three-tier pricing structure across premium, standard, and economy levels separates NIST-traceable laboratory systems from shop-floor digital units and vernier mechanical alternatives. Price differentiation hinges on ISO 17025 certification grade and embedded certificate generation capability. Margins are tightening due to REACH compliance costs in piezoelectric transducer manufacturing. Maintenance workshops in emerging markets exhibit highest price sensitivity, while German medical device manufacturers absorb premium tiers without volume negotiation.
Supply Chain Analysis
Refurbishment flows for precision steel rules and dial indicator mechanisms extend component lifecycles while constraining raw material demand elasticity. Supply concentrates in Sweden and Japan for hardened steel substrates, with piezoelectric ceramic sourcing anchored in Japanese specialty chemical producers. Alloy price volatility and single-source vulnerability in precision steel rule production expose gauge assemblers to input cost shocks. Distribution runs through industrial tool distributors and direct calibration service agreements with tier-one automotive manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The depth gauge market functions as a stable compounder anchored by regulatory recertification cycles that mandate periodic gauge fleet replacement regardless of economic conditions.
For Market Incumbents: Extend calibration laboratory accreditation networks into India and Southeast Asia before BIS standards harmonization matures. Lock in multi-year service contracts with Stuttgart and Detroit automotive clusters to defend against emerging Asian fabricators. Prioritize captive metrology R&D investment in AI-assisted measurement convergence to differentiate from commodity digital gauge producers. For New Entrants and Emerging Players: The gap between premium laser interferometry systems and economy vernier gauges offers white-space targeting for mid-tier digital units with ISO 10360 compliance. Focus initial penetration on India's Pune precision engineering corridor where PLI scheme incentives expand quality control budgets. Pursue partnership routes with European notified bodies to accelerate CE marking pathway credibility. For Investors and Strategic Acquirers: Valuations sit cheapest among diversified industrial tool distributors lacking captive calibration infrastructure. Five-to-ten-year viability favors vendors with backward integration into precision steel substrate supply or exclusive piezoelectric ceramic sourcing agreements. Monitor ECHA substance restriction announcements for forced material substitution triggers that would reshape competitive cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Accreditation Expansion | ISO 17025 certification unlocks EU MDR procurement channels in Esslingen medical device clusters. |
| AI-Assisted Measurement Development | Machine vision integration captures Stuttgart automotive demand for real-time defect classification. |
| Backward Integration into Steel Substrates | Captive precision steel rule production insulates margins from Swedish alloy price volatility. |
| Phased-Array Ultrasonic Platform Launch | Non-destructive testing convergence addresses Rotterdam marine survey operator replacement cycles. |
| Direct Service Agreement Negotiation | Bypassing distributor markups secures Detroit powertrain machining procurement preference. |
Methodological Framework
Multiple input streams — primary interviews with metrology laboratory directors, precision engineering procurement managers, and marine survey operators; secondary validation against SEC filings from diversified industrial tool manufacturers, EU MDR technical documentation databases, and Japanese METI industrial standards publications; plus customs trade data for hardened steel rule imports — were reconciled through bottom-up and top-down triangulation.
Historical shipment patterns were cross-referenced against panel input from gauge calibration technicians and automotive quality control engineers. The analytical framework segments by technology modality, end-use industry, certification tier, and regional regulatory cluster across the projection horizon. CAGRs were derived from replacement cycle timing, regulatory mandate implementation schedules, and technology substitution elasticity in marine non-destructive testing applications.
Caveats apply where REACH substance restriction expansions or NIST tolerance benchmark recalibrations could materially shift the outlook. Practitioners should monitor ECHA SVHC classification updates and notified body audit protocol changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Astrology Market
Others
India Home Automation Market
Others
North America Automotive LED Lighting Market
Others
Solar Lighting Tower Market
Others
Singapore Retail Market
Others
Global Recruitment and Staffing Market
Others
Pediatric Measuring Devices Market
Others
Global Car Wax Market
Others
Cremation Furnace Market
Others
Industrial PC Market
Others
Hardwood Market
Others
Global Social Networking Market
Others
North America Flexographic Printing Market
Others
Dried Egg Market
Others
Lepidolite Market
Others
Language Translation Device Market