
 Managed Video As a Service Market | 2026-2036
Managed Video As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Managed Video As a Service Market Insights
Subscription bundling of hosting, streaming, and API integration is consolidating buyer preference around full-stack managed offerings rather than point solutions. Microsoft leverages its Azure backbone to anchor enterprise video workloads, while Cisco Systems sustains hardware-software convergence for telecommunication providers. Amazon Web Services competes through edge delivery density, and Google differentiates via AI-powered content management layers.
Managed Video As a Service denotes a cloud-delivered operational model where providers assume full responsibility for video infrastructure provisioning, encoding, streaming, storage, and analytics on behalf of subscriber organizations. The architecture typically employs HLS and DASH protocols with adaptive bitrate streaming to ensure sub-five-second latency for live use cases across enterprise conferencing and broadcast media workflows. Deployment mode segmentation reveals hybrid cloud configurations capturing the dominant margin pool as enterprises retain on-premises encoding appliances while bursting peak loads to public infrastructure. End-user segmentation shows educational institutions generating the fastest uptake trajectory as virtual classroom standards harden, while media companies occupy the most mature demand tier with established content delivery network interconnections.
FCC guidelines on net neutrality and data prioritization shape bandwidth allocation for managed video traffic across United States networks, while GDPR and EU AI Act provisions in Europe constrain cross-border content analytics and facial recognition deployments. ISO/IEC 27001 certification requirements and SOC 2 Type II audits function as baseline market-access filters for enterprise procurement teams evaluating vendor shortlists. Stakeholders must monitor evolving encryption mandates and sovereign cloud localization rules as determinants of regional deployment feasibility and long-term contract structures.
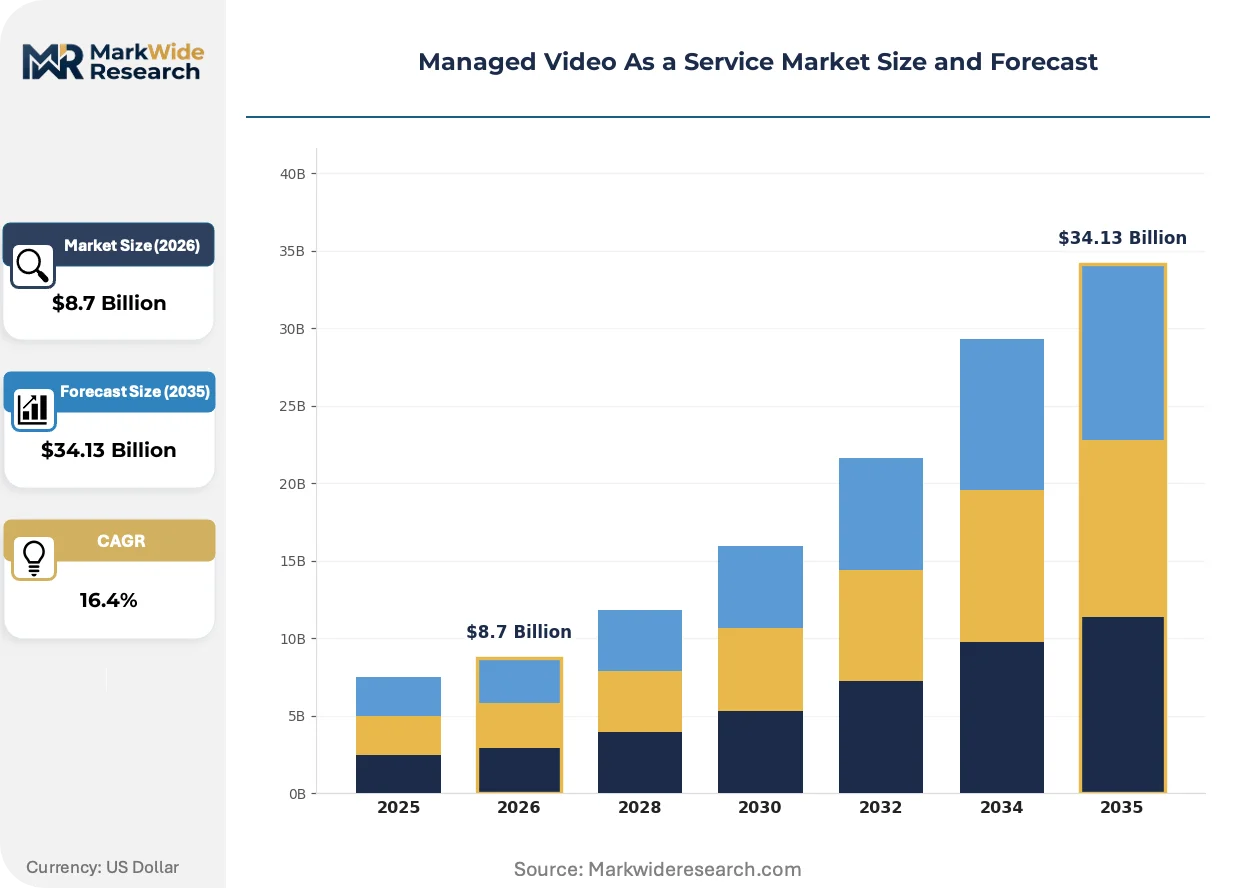
Market Dynamics
Hybrid cloud deployment architectures are fragmenting procurement authority between enterprise IT and line-of-business units, creating dual-vendor environments where encoding workloads split across on-premises appliances and burst-capacity public infrastructure.
Growth Catalysts
- GDPR Article 17 compliance:European enterprises are mandating automated content deletion pipelines, accelerating replacement of self-managed video archives with auditable SaaS retention policies.
- Healthcare diagnostic imaging:Radiology departments in the United States are integrating DICOM-compatible video streams into PACS workflows, requiring HIPAA-compliant managed infrastructure for teleconsultation.
- Low-latency WebRTC stacks:Browser-native real-time communication protocols are eliminating plugin dependencies, collapsing deployment friction for browser-based enterprise video applications.
Market Restraints
- Bandwidth cost volatility:Peering agreement disputes between tier-1 carriers and content delivery networks are injecting unpredictability into egress pricing for high-bitrate live streams.
- Encoder ASIC concentration:Taiwan-based semiconductor foundries dominate hardware-accelerated transcoding chip supply, creating single-source vulnerability for appliance-dependent hybrid deployments.
- EU AI Act facial recognition prohibitions:Automated biometric analysis in video analytics workflows faces operational suspension across European public sector deployments.
Strategic Opportunities
- Brazilian telemedicine expansion:ANVISA regulatory clarity on remote diagnostic video standards is opening subscription infrastructure demand among private hospital networks.
- Edge-AI convergence:On-device inference chips paired with cloud orchestration layers are enabling sub-100ms latency for interactive broadcast applications previously requiring dedicated fiber.
- India PLI scheme for data centers:Domestic cloud infrastructure incentives are reducing cross-border data transfer requirements for managed video providers serving Indian enterprise clients.
Industry Challenges
- SRE talent scarcity:Site reliability engineering expertise for 99.999% SLA video infrastructure remains concentrated among hyperscaler alumni, inflating compensation premiums for mid-market providers.
- SOC 2 Type II timeline compression:Enterprise procurement cycles now demand 12-month continuous audit trails prior to contract execution, extending vendor qualification periods.
- Legacy SIP interoperability:Decades-old session initiation protocol estates in financial services require costly gateway layers for WebRTC-native managed platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Managed Video As a Service Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hosting, Streaming, Content Delivery, API Integration End User: Enterprises, Media Companies, Educational Institutions, Telecommunication Providers Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Technology: Live Streaming, Video Conferencing, Video Analytics, Content Management |
| Companies Covered | Microsoft, Cisco Systems, Amazon Web Services, Google, Zoom Communications, Adobe, Avaya, RingCentral, Arkadin Cloud Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Managed Video As a Service Market Trends and Innovations
Computational video processing is migrating from centralized cloud regions toward distributed edge nodes, collapsing latency budgets while complicating orchestration architectures. This spatial redistribution demands new operational models for capacity planning and failure domain isolation.
AI-powered content moderation is automating real-time policy enforcement for live enterprise streams, replacing human reviewer pools with classifier pipelines trained on platform-specific acceptable use policies. Financial services compliance teams are adopting these systems for trader communications surveillance. The technology is automating detection of regulated speech patterns that previously required delayed post-hoc review.
FCC net neutrality restoration proceedings are reclassifying broadband providers as common carriers, subjecting managed video traffic to non-discrimination requirements that may reshape peering economics. Content delivery network operators face potential rate regulation for last-mile prioritization services. United States healthcare and education verticals are most exposed given their reliance on guaranteed bandwidth tiers for telehealth and virtual classroom delivery.
Consumption-based pricing is displacing committed-use contracts among mid-market enterprise buyers, compressing vendor revenue predictability while accelerating customer acquisition cycles. Annual upfront payments are giving way to monthly metered billing aligned with concurrent stream counts. This pattern is most visible in United States professional services and consulting verticals where project-based video collaboration demands fluctuate seasonally.
Managed Video As a Service Market Segmentation
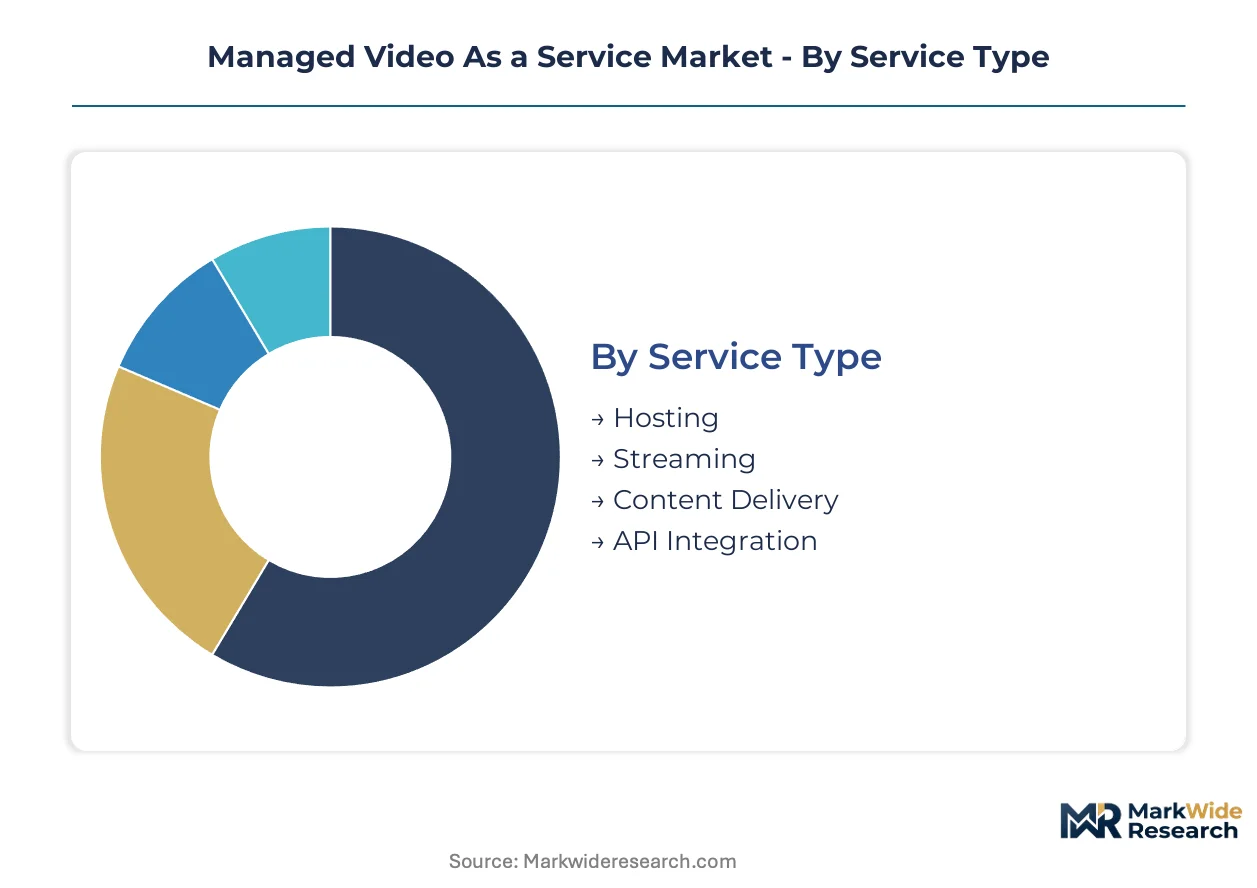
Segmentation in managed video services reveals how procurement authority splits across technical, organizational, and infrastructure dimensions. Buyers prioritize different certification bundles depending on whether they seek raw compute, network delivery, or compliance-layer functionality.
Service Type:
ISO/IEC 27001 and SOC 2 Type II certifications function as baseline market-access filters across all service types, though API Integration layers face additional GDPR Article 17 audit requirements for automated deletion pipelines.
- Hosting:Bare-metal and containerized compute provisioning for video storage and processing workloads. Financial services in the United States dominate procurement, driven by SEC record-keeping mandates for trader communications surveillance.
- Streaming:Adaptive bitrate delivery via HLS and DASH protocols with sub-five-second latency guarantees. Healthcare verticals in the United States concentrate demand, requiring HIPAA-compliant infrastructure for teleconsultation workflows.
- Content Delivery:Edge-distributed caching and origin shielding through CDN interconnection. Media companies with established network peering agreements represent the mature demand tier.
- API Integration:Programmatic interfaces for workflow orchestration and third-party system connectivity. Educational institutions generate accelerating uptake as virtual classroom standards harden and LMS interoperability becomes mandatory.
Leading the category by volume: Hosting. Growing fastest: API Integration.
End User:
Cost tier stratification separates enterprise buyers committing to annual contracts from project-based professional services firms preferring monthly metered billing aligned with concurrent stream counts.
- Enterprises:Large-scale deployments spanning conferencing, training, and executive broadcast use cases. Hybrid work policies in the United States sustain procurement across financial services and healthcare verticals with dedicated compliance teams.
- Media Companies:Broadcast-grade live production and OTT distribution with established CDN interconnections. This segment occupies the most mature demand tier with hardened disaster recovery requirements.
- Educational Institutions:Virtual classroom infrastructure and lecture capture systems. United States K-12 and higher education districts drive fastest expansion as federal connectivity subsidies stabilize procurement budgets.
- Telecommunication Providers:White-label video infrastructure resale and carrier-grade conferencing services. Cisco Systems sustains hardware-software convergence for this customer type through integrated appliance bundles.
Enterprise buyers commit the largest annual contract values. Educational institutions climb the fastest.
Deployment:
Margin concentration follows hybrid architectures where enterprises retain on-premises encoding appliances while bursting peak loads to public infrastructure, creating dual-vendor environments.
- Public Cloud:Fully outsourced infrastructure with consumption-based pricing and automatic scaling. Mid-market professional services firms prefer this mode for project-based collaboration demands that fluctuate seasonally.
- Private Cloud:Dedicated tenant environments with single-organization resource isolation. United States healthcare systems mandate this deployment for HIPAA-controlled diagnostic imaging workflows.
- Hybrid Cloud:Split workloads across on-premises encoding and public burst capacity. This configuration captures the dominant margin pool as procurement authority fragments between enterprise IT and line-of-business units.
- On-Premises:Fully self-managed infrastructure with capital-intensive appliance procurement. Financial services with legacy SIP estates require this mode for trader communications systems awaiting WebRTC migration.
Hybrid Cloud commands the highest vendor margins. Public Cloud expands most quickly among new entrants.
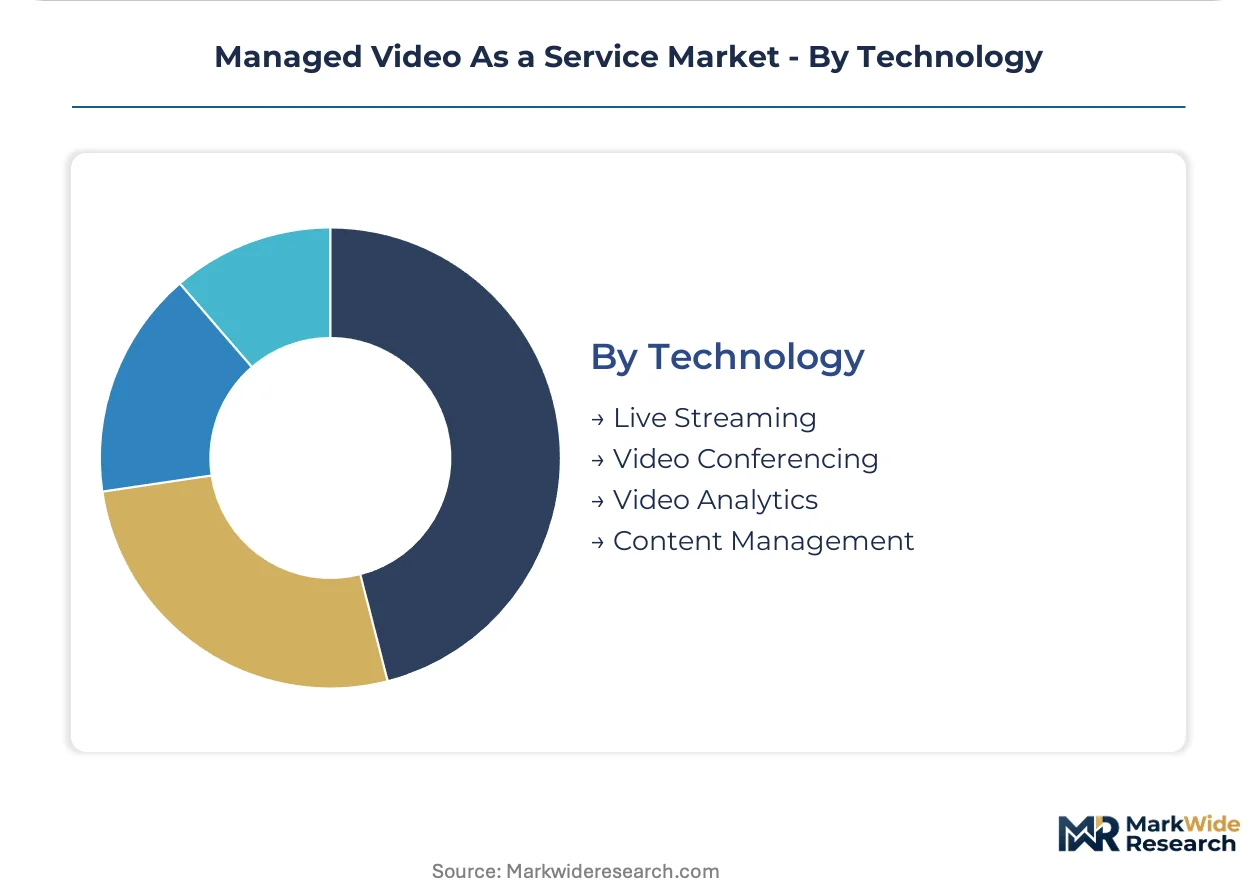
Technology:
Application maturity separates browser-native WebRTC stacks from legacy plugin-dependent systems, with AI-powered layers attracting premium pricing for real-time content moderation.
- Live Streaming:Real-time broadcast delivery with adaptive bitrate and multi-CDN failover. Media companies and telecommunication providers concentrate demand for sports and news workflows.
- Video Conferencing:Multi-party synchronous communication with screen sharing and recording. Enterprises in the United States sustain large-scale deployments as hybrid work policies stabilize.
- Video Analytics:AI-powered content moderation, facial recognition, and speech pattern detection. EU AI Act facial recognition prohibitions constrain European public sector deployments of this technology.
- Content Management:Metadata tagging, search, and archival with automated retention policies. GDPR Article 17 compliance mandates accelerate replacement of self-managed archives with auditable SaaS retention pipelines.
Video Conferencing holds the largest installed base. Video Analytics faces steepest expansion trajectory despite regulatory headwinds in Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the largest share of managed video infrastructure while semiconductor encoding hardware concentrates in East Asian manufacturing clusters. This production-consumption divide shapes procurement lead times and compliance requirements across deployment architectures.
United States
Financial services and healthcare verticals drive enterprise procurement through SEC record-keeping mandates and HIPAA telehealth expansion. FCC net neutrality proceedings subject managed video traffic to non-discrimination requirements affecting peering economics. Silicon Valley clusters anchor cloud-native provider development while New York metro financial institutions sustain premium compliance-tier demand.
Germany
Industrial automation and automotive engineering sectors adopt managed video for remote equipment diagnostics and supplier collaboration workflows. GDPR Article 17 automated deletion mandates accelerate replacement of self-managed archives with auditable SaaS retention pipelines. Munich and Stuttgart engineering clusters concentrate demand for ISO/IEC 27001-certified hybrid deployments with sovereign cloud localization.
India
Educational technology platforms and IT services exporters generate accelerating consumption as virtual classroom standards harden and federal connectivity subsidies stabilize procurement budgets. PLI scheme incentives for domestic data centers reduce cross-border transfer requirements for managed video providers serving enterprise clients. Bangalore and Hyderabad technology corridors anchor cloud infrastructure development with government-backed localization mandates.
Japan
Manufacturing quality assurance and remote maintenance applications sustain enterprise adoption across automotive and electronics supply chains. METI guidelines on data sovereignty influence hybrid cloud deployment preferences for sensitive industrial video analytics. Tokyo-Osaka industrial corridors concentrate demand for low-latency WebRTC stacks integrated with legacy factory automation systems.
Brazil
Private hospital networks and telemedicine platforms expand subscription infrastructure demand following ANVISA regulatory clarity on remote diagnostic video standards. Cross-border data compliance requirements favor managed service providers with local presence over direct hyperscaler relationships. São Paulo medical technology clusters anchor regional provider development for Latin American healthcare verticals.
Managed Video As a Service Market Competitive Landscape
The competitive structure tilts toward hyperscaler-backed platform providers with enterprise sales organizations. Microsoft, Amazon Web Services, and Google anchor the top tier through cloud infrastructure integration and consumption-based pricing models. Mid-market specialists compete through vertical-specific compliance certifications and hybrid deployment expertise. Dominant competitive moves include strategic partnerships with telecommunications carriers and portfolio diversification into adjacent collaboration software categories.
Within the hyperscaler tier, Microsoft and Amazon Web Services exemplify infrastructure-anchored positioning through Azure backbone integration and edge delivery density respectively. Google occupies a differentiated position through AI-powered content management layer development. Cisco Systems represents hardware-software convergence archetype for telecommunication provider segments with integrated appliance bundles. Zoom Communications anchors the browser-native real-time communication segment with WebRTC-native deployment models.
| Leading Market Players |
|---|
| Microsoft |
| Cisco Systems |
| Amazon Web Services |
| Zoom Communications |
| Adobe |
| Avaya |
| RingCentral |
| Arkadin Cloud Communications |
| Others |
Pricing and Supply Chain Analysis
Enterprise IT procurement teams in United States financial services anchor demand for SOC 2 Type II-certified managed video tiers, concentrating pricing power among hyperscaler-backed providers with continuous audit infrastructure.
Pricing Analysis
Margin tightening in mid-market subscriptions reflects consumption-based billing displacing annual upfront commitments as professional services firms demand monthly metered alignment with concurrent stream volatility. Three-tier pricing structure across premium compliance-certified, standard enterprise, and economy self-service levels separates buyers by audit trail requirements and SLA guarantees. Pricing pressure stems from hyperscaler density advantages compressing regional specialist margins. Healthcare systems exhibit lowest price sensitivity due to HIPAA-mandated infrastructure requirements, while K-12 education districts face acute budget constraints under federal subsidy timelines.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand while telecommunications carrier partnerships distribute white-label infrastructure to regional resellers. Taiwan-based semiconductor foundries and South Korean memory fabricators anchor hardware-accelerated encoding appliance supply, with United States cloud regions providing burst capacity orchestration. Encoder ASICs, high-bandwidth memory modules, and specialized video processing substrates constitute critical component dependencies. Single-source vulnerability in Taiwan semiconductor manufacturing threatens hybrid deployment timelines. Distribution runs through hyperscaler marketplaces, direct enterprise sales organizations, and carrier-integrated appliance bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards vertical integration into edge infrastructure and compliance certification layers as hyperscalers deepen control over encoding hardware and audit automation pipelines.
For Market Incumbents: Cement hybrid cloud deployment expertise through integrated appliance-software bundles that capture procurement authority fragmentation between enterprise IT and line-of-business units. Deepen SOC 2 Type II audit automation to compress vendor qualification periods that currently extend sales cycles. Acquire edge-AI inference chip capabilities to defend against WebRTC-native entrants threatening latency advantages in interactive broadcast applications.
For New Entrants and Emerging Players: Mid-market professional services firms with seasonal project-based collaboration demands represent the most penetrable buyer archetype, as their consumption-based billing preferences fall beneath hyperscaler enterprise sales floor thresholds. Brazilian private hospital networks expanding telemedicine infrastructure offer geographic white-space with ANVISA regulatory clarity reducing compliance entry barriers. Pursue API-first positioning with LMS interoperability as the wedge against incumbent conferencing bundles in educational technology.
For Investors and Strategic Acquirers: The window for entry favors hybrid deployment specialists with ISO/IEC 27001 certification infrastructure and established telecommunications carrier relationships. Mid-market providers with vertical-specific compliance automation and edge node density in underserved geographies represent viable acquisition targets. Monitor FCC net neutrality restoration proceedings as the signal indicating potential rate regulation reshaping CDN peering economics and margin structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Infrastructure Expansion | Reduces latency budgets below 100ms for interactive broadcast applications previously requiring dedicated fiber connectivity. |
| Compliance Certification Automation | Compresses SOC 2 Type II vendor qualification periods that currently demand 12-month continuous audit trails prior to contract execution. |
| API-First Platform Integration | Captures educational institution procurement as virtual classroom standards harden and LMS interoperability becomes mandatory. |
| Telecommunications Carrier Partnership | Enables white-label video infrastructure resale through Cisco Systems hardware-software convergence bundles. |
| AI-Powered Content Moderation Development | Automates real-time policy enforcement for financial services trader communications surveillance replacing delayed post-hoc review. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with enterprise IT procurement officers, cloud infrastructure architects, telecommunications carrier product managers, and compliance audit specialists provided qualitative validation. FCC proceedings documentation, SEC 10-K infrastructure expenditure disclosures, hyperscaler capex reports, and ISO certification registry databases supplemented quantitative foundations. Bottom-up service-type demand modeling and top-down enterprise spending allocation analysis were triangulated against vendor revenue disclosures.
Reconciliation of concurrent stream volume data, subscription pricing tiers, and deployment mode mix informed value projections across the analysis window. Segmentation dimensions modeled include service type, end-user vertical, deployment architecture, and technology layer with geographic regulatory cluster overlays. CAGRs were derived from fitted growth curves applied to baseline penetration estimates and projected enterprise video communication budget allocations. WebRTC adoption trajectories and GDPR Article 17 compliance cost curves served as industry-specific forecast modifiers.
Revisions become necessary when semiconductor supply disruptions, net neutrality reclassification outcomes, or EU AI Act enforcement interpretations materialize differently than baseline assumptions. Forecasts reflect documented expectations regarding hybrid work policy persistence, federal connectivity subsidy continuity, and edge-AI convergence timelines. Periodic stress-testing of base assumptions against actual vendor qualification cycle lengths and carrier peering agreement renegotiations is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Fibert Market
Others
Aluminium Clad Printed Circuit Board Market
Others
Storm Surge Barriers Market
Others
Italy Smart Home Market
Others
Durian Market
Others
Italy Automotive Adaptive Lighting System Market
Others
Middle East and Africa Medium Voltage Switchgear Market
Others
Air Separation Plant Market
Others
DNA Data Storage Market
Others
Dry Washer Market
Others
Binoculars Market
Others
Gas Holders Market
Others
Port Replicator Market
Others
Thailand Commercial Vehicles Lubricants Market
Others
Mobile Computing Devices Market
Others
Consumer Video Feedback Software Market