
 Global Sports and Fitness Wears Market | 2026-2036
Global Sports and Fitness Wears Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sports and Fitness Wears Market Outlook
ISO 14001 environmental management certification is bifurcating the competitive landscape between compliant suppliers and laggards in the sports and fitness wears sector. Nike Inc. leverages its vertically controlled manufacturing network to sustain premium positioning across multiple continents. Adidas AG anchors its European base while competing aggressively in Asian growth corridors through localized design centers.
Sports and fitness wears encompass engineered garments and footwear designed for physical activity, typically constructed from moisture-wicking synthetic blends or performance-treated natural fibers with specified breathability indices and compression ratings, serving both competitive athletic and recreational exercise applications. Footwear commands the largest value pool due to material complexity and replacement frequency, while activewear generates the fastest volume expansion as casual athletic styling permeates everyday wardrobes. The accessories category remains structurally fragmented, though margin pools concentrate in wearable-integrated products where technology leadership differentiates offerings.
The EU Green Deal and REACH chemical regulations constrain dye and finish chemistries for products entering European markets, while China's GB standards and dual carbon goals enforce domestic manufacturing emissions thresholds that reshape supplier qualification. The US EPA and state-level extended producer responsibility frameworks in California and New York increasingly govern post-consumer textile recovery obligations. Stakeholders must monitor how diverging regulatory stringency across these jurisdictions reshapes cost structures and sourcing geography decisions without assuming harmonization.
Market Dynamics
EU Green Deal textile sustainability mandates and China's dual carbon goals are forcing simultaneous supply chain reconfiguration across synthetic fiber sourcing, dye chemistry substitution, and manufacturing emissions compliance.
Growth Catalysts
- Athleisure normalization:Office dress codes in the United States and United Kingdom now routinely incorporate performance fabrics, expanding addressable demand beyond dedicated exercise occasions.
- REACH chemical restrictions:European regulatory pressure on perfluorinated compounds accelerates investment in bio-based water-repellent finishes, creating first-mover advantages for compliant suppliers.
- Domestic brand ascendance in China:Anta Sports and Li-Ning capture middle-class consumers in Shanghai and Beijing through localized design and patriotic positioning.
Market Restraints
- Petrochemical feedstock volatility:Polyester and elastane production remains tethered to oil price swings, compressing margin predictability for synthetic-dominant portfolios.
- Vietnam-Indonesia manufacturing concentration:Apparel assembly clusters in Southeast Asia face simultaneous wage inflation and electricity rationing risks.
- Mechanical recycling limitations:Current fiber-to-fiber recovery technologies degrade tensile strength below athletic performance thresholds, constraining circular economy claims.
Strategic Opportunities
- India manufacturing scale-up:PLI scheme incentives and improving port infrastructure position Gujarat and Tamil Nadu as alternatives to China-dominated sourcing.
- Wearable-integrated accessories:Biometric sensor embedding in compression garments opens recurring revenue streams through subscription analytics.
- California extended producer responsibility:State-level textile recovery mandates create service revenue potential for brands with reverse logistics infrastructure.
Industry Challenges
- ISO 14001 certification backlog:Third-party auditor capacity constraints delay supplier qualification timelines for brands targeting European retail distribution.
- Legacy ERP integration:Traceability software deployment for supply chain transparency requires costly middleware adaptation with existing procurement systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sports and Fitness Wears Market |
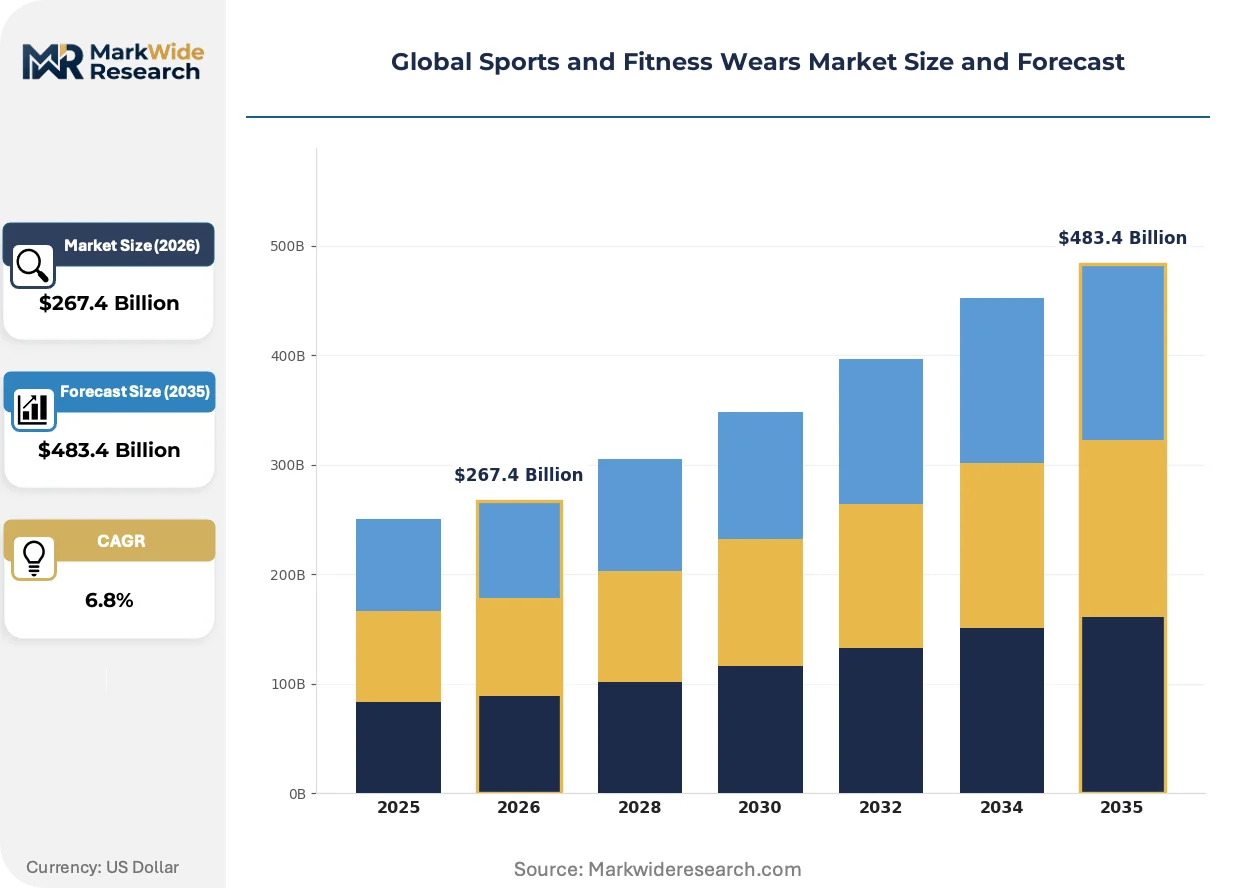
| Market Size in 2026 | $267.4 Billion |
| Market Size in 2035 | $483.4 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Footwear, Activewear, Accessories, Outerwear End User: Males, Females, Kids, Athletes Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Fitness Centers Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | Nike Inc., Adidas AG, Puma SE, Under Armour Inc., Lululemon Athletica Inc., Anta Sports Products Limited, ASICS Corporation, Li Ning Company Limited, Skechers USA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sports and Fitness Wears Market Strategic Shifts
Biomaterial innovation and regulatory chemistry constraints are accelerating material substitution timelines, while digital manufacturing compresses design-to-shelf cycles across all price tiers.
Mycelium-based leather alternatives are fragmenting the premium performance footwear segment. Adidas and smaller direct-to-consumer brands in Germany and the Netherlands integrate fungal-derived uppers into limited releases. Supply scarcity of cultivated mycelium sheets is fragmenting production scale, forcing brands to choose between exclusivity positioning and volume ambition.
EU Green Deal's textile sustainability requirements now mandate fiber composition disclosure and durability testing for all products entering European markets. Compliance costs fall disproportionately on mid-tier suppliers lacking in-house testing laboratories. Italian and Portuguese manufacturers respond by consolidating certification services through shared regional facilities.
Athleisure procurement by corporate uniform programs now specifies moisture-wicking and odor-resistance standards previously reserved for competitive athletics. Facility management vendors in the United States and Australia replace cotton-polyester blends with certified performance fabrics. This specification creep is most visible in healthcare and hospitality verticals where employee retention concerns elevate uniform comfort priorities.
Global Sports and Fitness Wears Market Segmentation
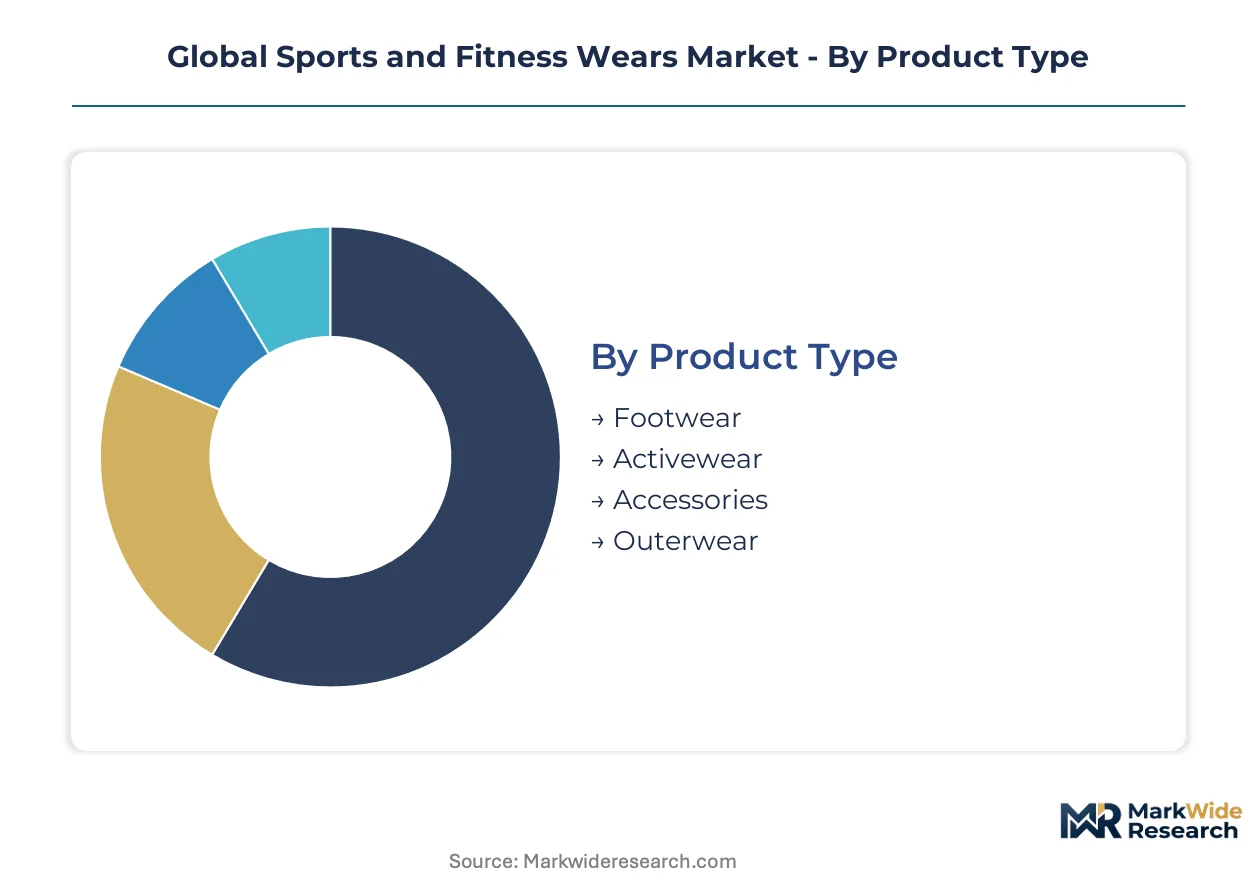
Sports and fitness wears segmentation reveals how product engineering, channel economics, and user physiology intersect to create distinct margin pools. Each dimension carries implications for inventory velocity, marketing spend allocation, and supply chain configuration.
Product Type:
Channel-mix dynamics vary sharply across product categories, with footwear dominating specialty retail while activewear penetrates mass-market distribution most aggressively.
- Footwear:Complex multi-material construction involving midsole foam engineering, outsole traction patterns, and upper breathability membranes commands the highest unit economics. Replacement cycles compress in competitive running segments where Shanghai and Beijing consumers prioritize performance validation through Strava data integration.
- Activewear:Moisture-wicking synthetic blends and seamless compression knitting now penetrate corporate uniform specifications beyond gym use. Demand concentrates in United States and United Kingdom office-adjacent segments where dress-code relaxation has normalized performance fabric daily wear.
- Accessories:Headbands, gloves, and equipment bags remain fragmented with technology-embedded variants capturing margin premiums.
- Outerwear:Weather-protective shells face EU Green Deal chemistry constraints on durable water-repellent finishes.
Footwear dominates installed base. Activewear is where expansion concentrates.
End User:
Physiological fit requirements and purchase authority patterns shape how brands allocate R&D and retail presence across user groups.
- Males:Traditional core segment with established size-run economies of scale in team sports and running categories. Purchase concentration in United States big-box retail and German specialty running stores sustains volume manufacturing.
- Females:Fastest-climbing segment driven by yoga-studio adjacent purchasing and social commerce discovery through Instagram and Xiaohongshu in China's tier-one cities. Design requirements around support engineering and aesthetic versatility command premium development cycles.
- Kids:Replacement-driven demand tied to school sports seasons and growth spurts with parents prioritizing durability over performance specifications.
- Athletes:Professional and competitive amateur tiers requiring customized fit and sponsorship-linked distribution through team-equipment managers.
Males anchor historical revenue. Females represent the steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin capture, brand control, and inventory risk exposure with digital infrastructure now table stakes across all tiers.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capture the fastest volume growth with return-rate management as the critical operational variable. Nike and Adidas deploy app-based membership ecosystems to reduce customer acquisition costs in United States and German markets.
- Specialty Stores:Running-focused retailers and yoga studios provide fit expertise and community programming that justifies price premiums. Concentration in Melbourne, London, and New York running districts supports brand storytelling.
- Supermarkets:Mass-market penetration for basic activewear with private-label compression from Tesco and Carrefour capturing value-conscious European households.
- Fitness Centers:Pro-shop and branded merchandise partnerships with Equinox, PureGym, and regional chains converting workout proximity into impulse purchasing.
Specialty stores dominate premium positioning. Online retail is where volume expansion concentrates.
Price Tier:
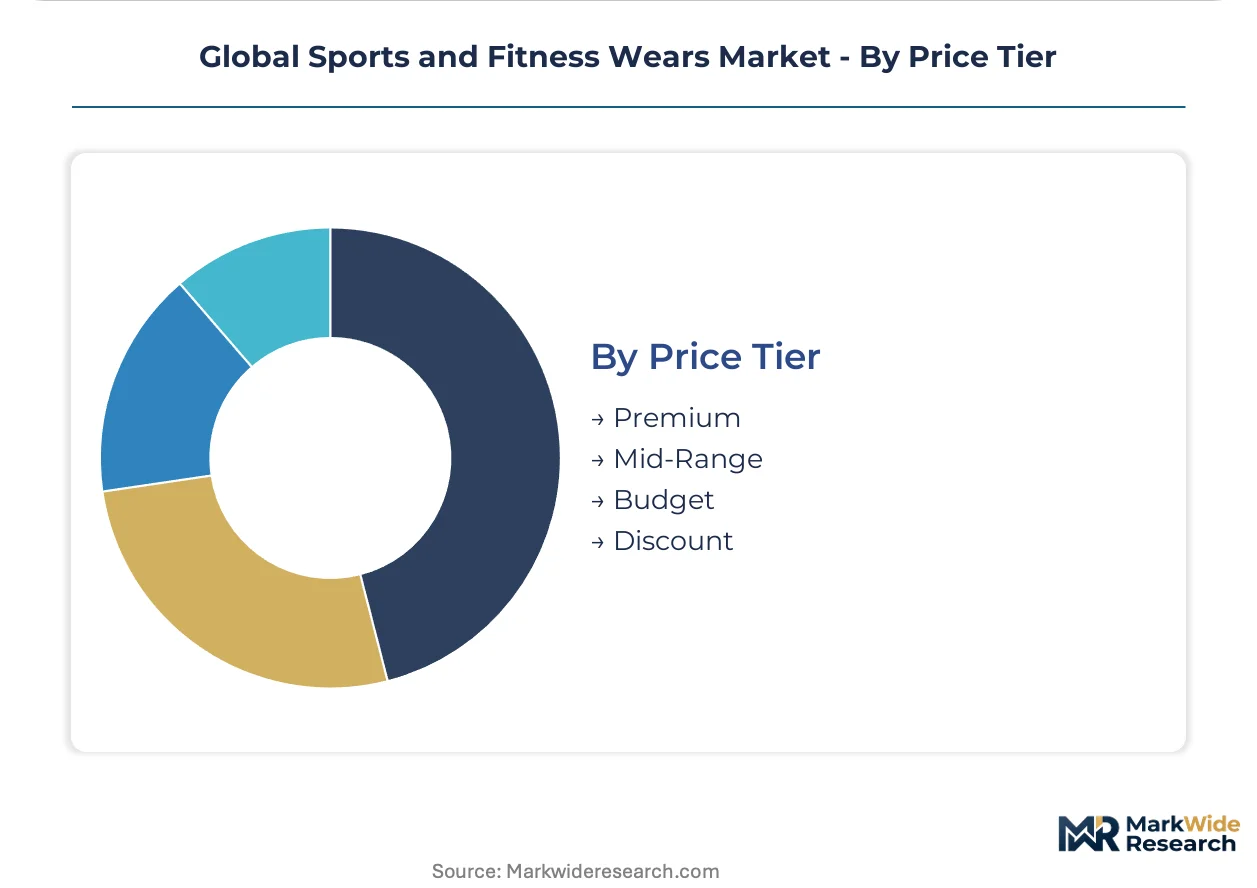
Cost-tier stratification maps to certification intensity, material sourcing geography, and warranty terms with limited crossover between adjacent tiers.
- Premium:ISO 14001-certified manufacturing, traceable fiber provenance, and extended durability warranties justify price multiples. Concentration in Japanese and Swiss markets where technical specification disclosure is mandatory.
- Mid-Range:Volume engine for mass-market brands balancing performance claims with accessible price points through Vietnam and Indonesia assembly.
- Budget:Functional basics for price-sensitive segments with compressed margin structures dependent on China-dominated supply chains.
- Discount:Closeout inventory and previous-season liquidation through outlet malls and flash-sale platforms with minimal brand control.
Mid-Range dominates unit volume. Premium is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in finished apparel exports, while Rotterdam's barge-rail intermodal links distribute European imports inland. These infrastructure assets shape where manufacturing clusters concentrate and how finished goods reach end consumers.
United States
Corporate uniform procurement now specifies moisture-wicking performance standards previously reserved for competitive athletics. California's extended producer responsibility framework imposes post-consumer textile recovery obligations on brands selling into the state. Los Angeles maintains specialty manufacturing for premium activewear with quick-turn sample capabilities serving direct-to-consumer brands.
Germany
Specialty running retail in Berlin and Munich sustains price premiums through community programming and gait analysis services. ECHA's REACH restrictions on perfluorinated compounds accelerate investment in bio-based water-repellent finishes among domestic suppliers. Bavaria's textile engineering clusters around Augsburg develop seamless knitting machinery for compression garment production.
China
Domestic brands capture middle-class consumers in Shanghai and Beijing through localized design and patriotic positioning. GB standards and dual carbon goals enforce manufacturing emissions thresholds that reshape supplier qualification protocols. Guangdong province's Pearl River Delta remains the dominant assembly hub despite wage pressures and electricity rationing risks.
India
PLI scheme incentives and improving port infrastructure position Gujarat and Tamil Nadu as alternatives to China-dominated sourcing. BIS certification requirements for textile imports create compliance barriers for unqualified suppliers. Tiruppur's knitwear cluster scales technical fabric production for export markets with improving dyehouse environmental compliance.
Vietnam
Apparel assembly clusters face simultaneous wage inflation and electricity rationing risks that compress margin predictability. The country's national environmental regulator enforces wastewater discharge standards that upgrade dyehouse capital requirements. Ho Chi Minh City and surrounding industrial zones concentrate footwear molding and final assembly operations for export brands.
Global Sports and Fitness Wears Market Competitive Environment
Listed leaders compete with private specialists across brand positioning and manufacturing scale. The market structure tiers between vertically integrated giants with captive supply networks and asset-light design houses outsourcing production. Three archetypes dominate: heritage sportswear houses with decades of athlete endorsements, direct-to-consumer challengers built on social commerce discovery, and domestic champions leveraging patriotic sentiment in home markets. Competitive moves concentrate on M&A for digital capabilities and strategic partnerships with biomaterial startups.
Within the heritage sportswear tier, Nike Inc. and Adidas AG occupy positions defined by decades of athlete sponsorship infrastructure and controlled retail networks. Anta Sports Products Limited exemplifies the domestic champion archetype, having consolidated multiple Chinese brands to capture middle-class consumers through patriotic positioning. These three entities represent distinct strategic paths: global scale with premium pricing, global scale with European design heritage, and regional dominance through acquisition-led consolidation.
| Leading Market Players |
|---|
| Nike Inc. |
| Adidas AG |
| Puma SE |
| Under Armour Inc. |
| Lululemon Athletica Inc. |
| Anta Sports Products Limited |
| ASICS Corporation |
| Li Ning Company Limited |
| Skechers USA Inc. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day fabric-to-shelf lead times for moisture-wicking synthetic blends concentrate pricing power with vertically integrated suppliers controlling Vietnam and Indonesia assembly clusters, while spot-market polyester buyers face margin compression from petrochemical feedstock volatility.
Pricing Analysis
Volume-discount tiering structures separate ISO 14001-certified premium suppliers from mid-range Vietnam-assembled and budget China-sourced tiers. Price differentiation hinges on certification grade and traceable fiber provenance, with brand premiums widening as EU Green Deal compliance costs concentrate in European distribution. Cost compression in synthetic-dominant portfolios intensifies because oil price swings transmit directly to elastane and polyester input costs. Corporate uniform buyers exhibit highest price sensitivity, while specialty running retailers absorb premiums for gait-analysis service bundling.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for brands dependent on Guangdong province's Pearl River Delta finishing clusters. Manufacturing concentrates in China, Vietnam, and Indonesia, with raw material dependencies spanning Taiwanese synthetic fiber, Korean elastane, and Chinese dye chemistry. Single-source vulnerability in mycelium-based leather alternatives constrains premium footwear scaling. Distribution runs through Rotterdam's barge-rail intermodal links for European inland penetration and Los Angeles quick-turn facilities for North American direct-to-consumer fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cyclical recovery anchored to professional athlete sponsorship budget restoration across North American leagues following pandemic-era compression.
For Market Incumbents: Compound brand equity through exclusive mycelium-based material partnerships that lock out fast-follower access, while accelerating backward integration into Gujarat and Tamil Nadu technical knitting capacity to offset Vietnam wage inflation risks.
For New Entrants and Emerging Players: Differentiate on biometric-embedded compression garments with subscription analytics revenue models, targeting white-space in healthcare and hospitality uniform verticals where specification creep toward performance fabrics remains underpenetrated by established athletic brands.
For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-premium play because regulatory chemistry constraints across EU REACH and China's dual carbon goals will structurally advantage certified suppliers with in-house testing infrastructure. Watch ISO 14001 auditor capacity expansion as the signal for qualification timeline normalization and mid-tier supplier consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomaterial Supply Agreement | Exclusive mycelium sourcing from Dutch or German cultivators locks premium positioning against Adidas and smaller DTC competitors. |
| Certification Infrastructure Investment | Shared regional testing facilities in Portugal or Italy spread EU Green Deal compliance costs across mid-tier supplier networks. |
| Reverse Logistics Buildout | California extended producer responsibility compliance converts textile recovery obligations into service revenue streams. |
| Wearable Technology Integration | Biometric sensor embedding in compression garments opens recurring subscription analytics revenue beyond unit sales. |
| India Manufacturing Scale-Up | PLI scheme incentives in Gujarat and Tamil Nadu diversify sourcing geography away from China-dominated supply chains. |
Study Parameters
Operator-level perspectives from brand supply chain directors, specialty retail buyers, dyehouse compliance officers, and corporate uniform procurement managers anchored the qualitative base, combined with secondary validation from customs trade records, SEC 10-K apparel segment disclosures, and EU ECHA regulatory filings. Bottom-up channel volume estimates and top-down macroeconomic absorption rates were triangulated to constrain forecast variance.
Sensitivity analysis across petrochemical price scenarios, regulatory implementation timelines, and auditor capacity constraints shaped the analytical framework. Segmentation dimensions modeled include product type, end user physiology, distribution channel economics, and price tier certification intensity. CAGRs were derived from historical elasticity patterns and projected substitution dynamics, with inputs from synthetic fiber production capacity announcements and athlete sponsorship contract value trajectories.
Material uncertainties — abrupt REACH chemistry scope expansions, electricity rationing disruptions in Vietnamese industrial zones, or mechanical recycling technology breakthroughs — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Aircraft Sensors Market
Others
Asia-Pacific Road Safety Market
Others
Solar Animal Repeller Market
Others
Belt Loader Market
Others
Mobile Computer Cart Market
Others
Hopper Dryers Market
Others
5G Tester Market
Others
Smart Badge Market
Others
North America Compressor Oil Market
Others
Global Duty-Free Retailing Market
Others
UK Cat Food Market
Others
Global Food Fiber Market
Others
Smart Home Controller Market
Others
UAE Location-Based Services Market
Others
Receiving Scales Market
Others
Fresh Apples Market