
 Military Sensors Software Market | 2026-2036
Military Sensors Software Market Size, Share, and Industry Trends Forecast 2026-2036
Military Sensors Software Market Outlook
Edge-native sensor fusion is reconfiguring how battlefield intelligence layers onto mobile platforms. Lockheed Martin Corporation leverages its satellite-to-shooter software pipelines to anchor demand in integrated air-and-missile defense. Raytheon Technologies sustains R&D intensity in cognitive electronic warfare algorithms that differentiate its offering from hardware-centric rivals. Northrop Grumman Corporation dominates distributed aperture software for next-generation combat aircraft, extending its footprint beyond traditional radar domains.
Military sensors software encompasses embedded codebases that process, correlate, and distribute signals from electro-optical, radio-frequency, and acoustic transducers across tactical networks, typically operating at sub-millisecond latency thresholds to support real-time decision loops in contested electromagnetic environments. Radar Systems command the largest installed base among product types, though AI-Based Analytics within the technology dimension captures expanding margin pools as militaries prioritize autonomous target recognition over raw data collection. Edge Computing architectures for forward-deployed units represent the fastest-growing structural segment, displacing cloud-reliant workflows in denied-area operations.
The US Department of Defense mandates open architecture compliance through its Software Modernization Strategy, while NATO's STANAG standards shape interoperability requirements for multinational coalition systems. The US FAA coordinates airspace deconfliction rules for military sensor platforms operating in national airspace, affecting deployment timelines for domestic training exercises. Stakeholders must weigh sovereign data residency requirements against the interoperability gains of shared sensor grids as allied procurement patterns diverge on cloud versus edge-first architectures.
Market Dynamics
Edge-native computing architectures are forcing a fundamental reconfiguration of military sensor software deployment models, compressing decision loops from seconds to milliseconds while severing dependency on contested satellite uplinks.
Growth Catalysts
- NATO STANAG interoperability mandates:Coalition forces require unified sensor fusion protocols, compelling defense contractors to develop modular software stacks that plug into multinational command networks.
- Indo-Pacific distributed sensing networks:Pentagon investments in island-chain surveillance infrastructure are accelerating procurement of mesh-networked sensor software for maritime domain awareness.
- AI-based target recognition:Autonomous classification algorithms reduce analyst workload while enabling engagement timelines that exceed human reaction speeds in high-threat electromagnetic environments.
Market Restraints
- Semiconductor supply concentration:Advanced FPGA and GPU fabrication for sensor processing relies heavily on East Asian foundry capacity, creating vulnerability to export control disruptions.
- Security clearance bottlenecks:Software development for classified sensor programs requires cleared personnel pools that defense primes struggle to replenish at velocity.
- Legacy hardware lock-in:Decades-old radar and electro-optical platforms in active service resist software-only upgrades, fragmenting addressable market for pure-play vendors.
Strategic Opportunities
- Five Eyes sensor grid integration:Australia, Canada, New Zealand, the UK, and the US are pooling aperture data, creating demand for cross-domain orchestration software that normalizes disparate national formats.
- Urban warfare electronic support:Dense signal environments in megacity combat zones require novel spectral deconfliction algorithms absent from current military portfolios.
- Software Modernization Strategy procurement reform:DoD directive 5000.87 accelerates software acquisition timelines, opening entry points for non-traditional vendors with DevSecOps credentials.
Industry Challenges
- Model verification and validation:Machine learning components in target recognition pipelines resist traditional software assurance methods, complicating safety certification for lethal autonomous systems.
- Cross-domain integration complexity:Fusing space, air, ground, and maritime sensor streams into coherent tracks demands middleware expertise scarce among hardware-centric defense suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Sensors Software Market |
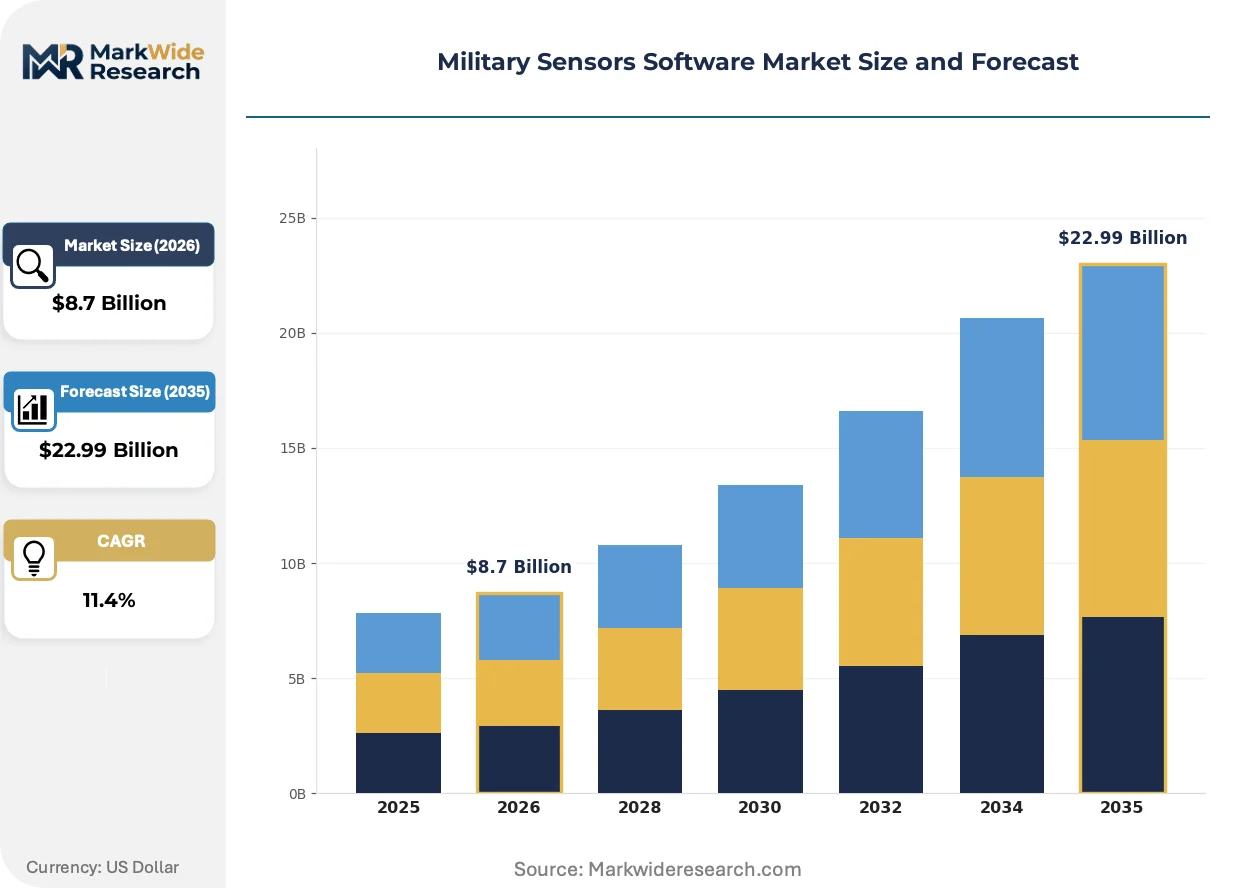
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Systems, Thermal Imaging, Acoustic Sensors, LiDAR Technology: AI-Based Analytics, Edge Computing, Cloud Integration, Signal Processing Application: Surveillance, Target Acquisition, Data Fusion, Reconnaissance End User: Defense Forces, Intelligence Agencies, Security Contractors, Military OEMs |
| Companies Covered | Honeywell International, Raytheon Technologies, Lockheed Martin Corporation, Thales Group, BAE Systems, Northrop Grumman Corporation, L3Harris Technologies, Elbit Systems, General Dynamics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Sensors Software Market Strategic Shifts
Software-defined sensor processing is dissolving the historical boundary between hardware acquisition and capability refresh, enabling military operators to field new detection modes through over-the-air updates rather than platform replacement cycles.
Containerized mission applications are collapsing the traditional separation between sensor control, signal processing, and data exploitation functions. Naval surface combatants and airborne early warning platforms are deploying Kubernetes-orchestrated workloads at the tactical edge, compressing integration timelines from years to months while reducing vendor lock-in through standardized interfaces.
The US Department of Defense Software Modernization Strategy mandates open architecture compliance across all new sensor programs, compelling primes to publish application programming interfaces that third parties can extend. This regulatory pressure fragments historically monolithic supply relationships, creating openings for specialized algorithm developers in electronic warfare and synthetic aperture processing niches previously captured by platform integrators.
Defense procurement officers are abandoning milestone-based acquisition in favor of continuous delivery contracts that tie vendor payments to operational capability demonstrations. The US Air Force Rapid Capabilities Office and similar units in the UK Ministry of Defence are piloting this model for next-generation warning systems, shifting risk from government program offices to contractors who must maintain software relevance across multi-decade platform lifecycles.
Military Sensors Software Market Segmentation
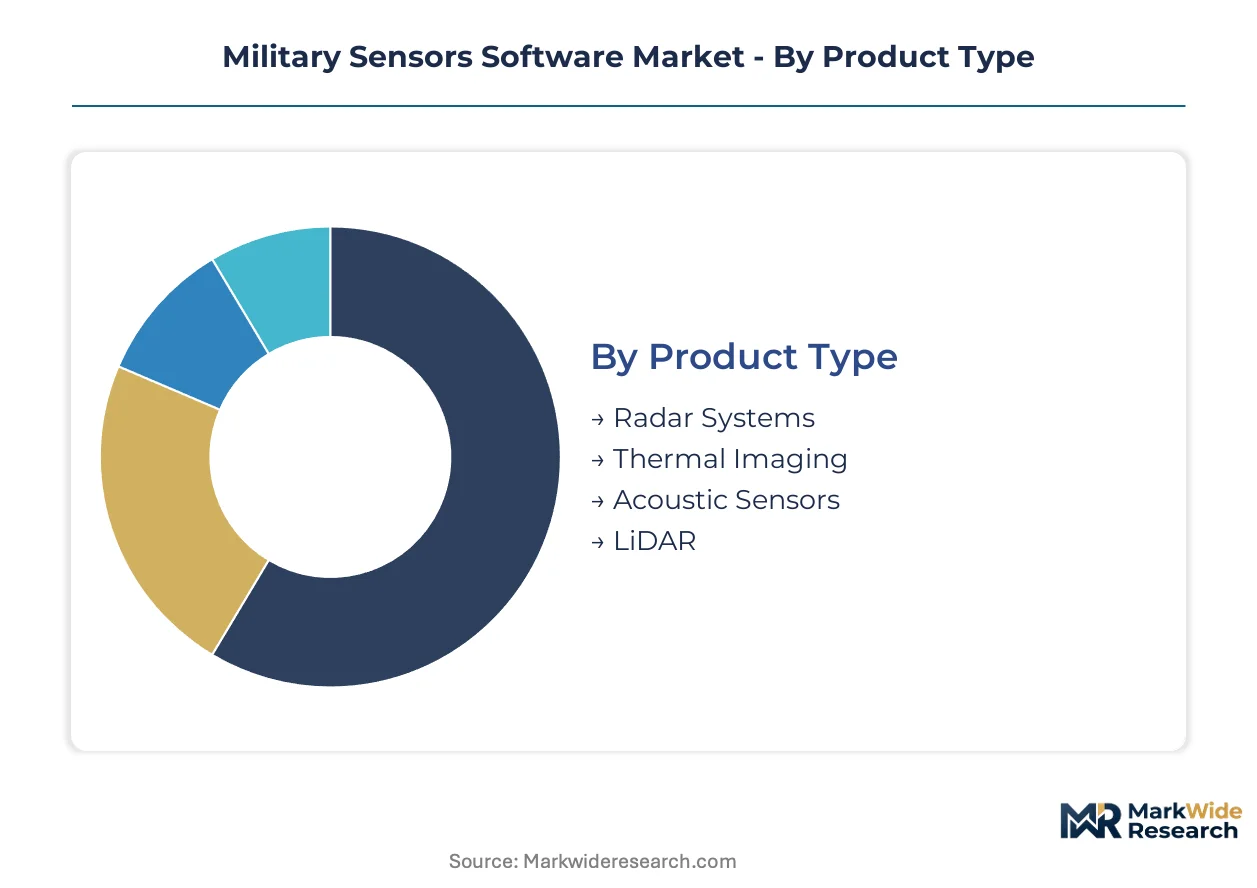
Military sensor software procurement cycles vary dramatically across product categories, with some platforms requiring decade-long certification timelines while others refresh through over-the-air updates. Understanding these velocity differentials shapes vendor resource allocation and partnership strategies.
Product Type:
Radar Systems and Thermal Imaging turn over slowly due to airworthiness certification requirements, while Acoustic Sensors and LiDAR refresh faster through modular software upgrades.
- Radar Systems:Embedded codebases process pulse-Doppler returns and synthetic aperture data for airborne and surface platforms. Pentagon spending on distributed sensing networks for Indo-Pacific operations concentrates demand in multi-function arrays that fuse tracks across coalition networks.
- Thermal Imaging:Infrared processing algorithms convert focal plane array outputs into actionable imagery under degraded visual conditions. NATO STANAG interoperability mandates drive procurement of common thermal formats for multinational ground vehicle programs.
- Acoustic Sensors:Passive sonar and gunshot detection systems deploy machine learning classification at the tactical edge.
- LiDAR:3D point cloud processing enables terrain mapping and obstacle avoidance for autonomous ground vehicles.
Radar Systems dominate installed base. Acoustic Sensors is where expansion concentrates.
Technology:
Edge Computing commands premium pricing for denied-area operations, while Cloud Integration spreads across lower-tier applications with less stringent latency requirements.
- AI-Based Analytics:Neural network pipelines perform autonomous target recognition, anomaly detection, and predictive maintenance on sensor streams. The US Department of Defense Software Modernization Strategy accelerates procurement of continuously learning algorithms that reduce analyst workload in contested electromagnetic environments.
- Edge Computing:Containerized workloads process data at the point of collection, severing dependency on contested satellite uplinks. Forward-deployed units across NATO island-chain surveillance infrastructure drive demand for sub-millisecond decision loops.
- Cloud Integration:Backend architectures aggregate multi-source intelligence for strategic analysis and long-term storage.
- Signal Processing:Digital filtering and spectral analysis routines form the foundational layer for all sensor modalities.
Signal Processing underpins every deployment. Edge Computing is climbing the fastest.
Application:
Surveillance and Reconnaissance operate on continuous delivery contracts, while Target Acquisition demands exhaustive safety certification for lethal autonomous systems.
- Surveillance:Persistent wide-area monitoring software correlates tracks across electro-optical, radar, and signals intelligence feeds. Maritime domain awareness missions in the Indo-Pacific concentrate procurement of mesh-networked sensor fusion for littoral operations.
- Target Acquisition:Precision engagement pipelines fuse multi-spectral data to generate fire control solutions within engagement timelines. Model verification and validation challenges complicate fielding of machine learning components in high-threat electromagnetic environments.
- Data Fusion:Middleware normalizes disparate sensor formats into coherent operational pictures for command networks.
- Reconnaissance:Route planning and sensor tasking software optimizes collection against priority intelligence requirements.
Surveillance captures the largest addressable market. Target Acquisition offers the steepest expansion trajectory.
End User:
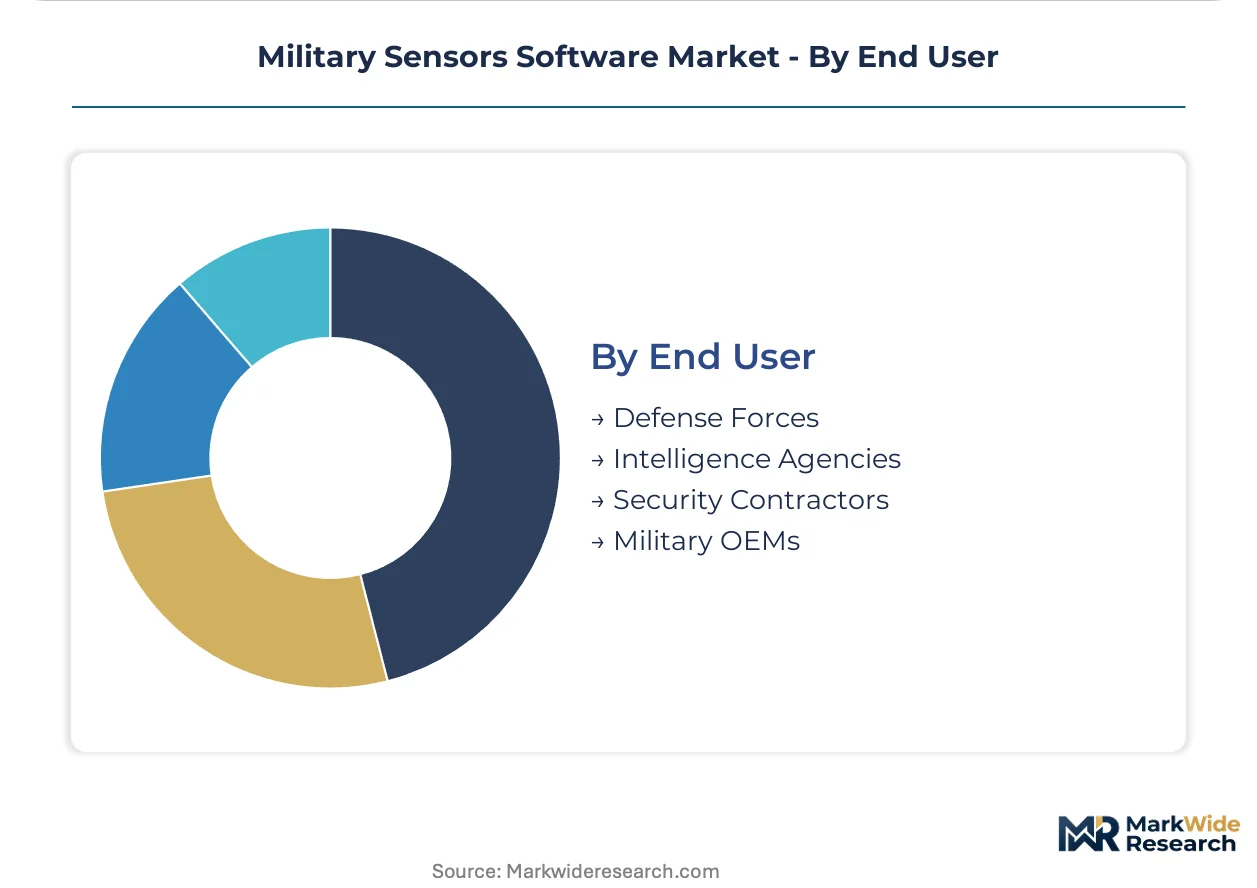
Defense Forces and Intelligence Agencies procure through traditional milestone-based acquisition, while Security Contractors and Military OEMs adapt faster to continuous delivery models.
- Defense Forces:Operational commands field sensor software across tactical aviation, naval surface combatants, and ground maneuver formations. The US Air Force Rapid Capabilities Office pilots alternative acquisition pathways that tie vendor payments to operational capability demonstrations.
- Intelligence Agencies:Signals intelligence and geospatial analysis units demand specialized processing for classified collection platforms. Security clearance bottlenecks constrain software development velocity for programs requiring cleared personnel pools.
- Security Contractors:Private sector providers support force protection and critical infrastructure monitoring with adapted military-grade algorithms.
- Military OEMs:Platform integrators embed sensor processing into airframes, vessels, and vehicles as original equipment.
Defense Forces anchor procurement volume. Military OEMs is where vendor competition intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement officers in the United States concentrate the largest share of military sensor software spending, with allied NATO members and Indo-Pacific partners following distinct acquisition rhythms shaped by national security priorities and coalition interoperability mandates.
United States
Pentagon investments in distributed sensing networks for Indo-Pacific operations drive procurement of mesh-networked sensor fusion platforms. The Department of Defense Software Modernization Strategy mandates open architecture compliance through directive 5000.87, accelerating software acquisition timelines. Greater Washington DC and Virginia defense corridors host prime contractor development centers where satellite-to-shooter software pipelines anchor integrated air-and-missile defense programs.
United Kingdom
The UK Ministry of Defence pilots continuous delivery contracts for next-generation warning systems, shifting risk from government program offices to contractors. NATO STANAG interoperability requirements shape procurement of modular software stacks for multinational command networks. London and Southeast England defense technology clusters concentrate algorithm development for electronic warfare and synthetic aperture processing applications.
Germany
Bundeswehr modernization programs prioritize sensor fusion for ground vehicle formations operating within NATO coalition structures. The country's national defense procurement office aligns requirements with EU defense industrial strategy frameworks. Bavaria and Baden-Württemberg host system integrators developing middleware for cross-domain orchestration of disparate national sensor formats.
Israel
Israel Defense Forces field cognitive electronic warfare algorithms for contested electromagnetic environments, with procurement patterns emphasizing autonomous target recognition capabilities. The country's national defense export control regulator coordinates technology transfer approvals for sensor software with dual-use applications. Tel Aviv and Haifa metropolitan areas concentrate specialist developers in signals intelligence and geospatial analysis niches.
Australia
Five Eyes sensor grid integration initiatives pool aperture data across Australia, Canada, New Zealand, the UK, and the US, creating demand for cross-domain orchestration software. The Australian Defence Force prioritizes maritime domain awareness missions through island-chain surveillance infrastructure investments. Canberra and Adelaide defense technology corridors support development of edge-native computing architectures for forward-deployed units.
Military Sensors Software Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure consolidated around platform-integrating primes and fragmented among algorithm developers. Tier-one contractors anchor procurement relationships through multi-decade platform lifecycles, while mid-tier specialists capture niches in electronic warfare and synthetic aperture processing. Dominant competitive moves include strategic partnerships for middleware expertise and portfolio diversification into DevSecOps service delivery models.
Among US-based defense primes, Lockheed Martin Corporation, Raytheon Technologies, and Northrop Grumman Corporation exemplify the platform-integrating archetype that dominates installed base relationships. These corporations occupy positions spanning satellite-to-shooter pipelines, cognitive electronic warfare algorithms, and distributed aperture software for next-generation combat aircraft. Elbit Systems represents the specialist tier with concentration in electro-optical and thermal imaging processing domains.
| Leading Market Players |
|---|
| Honeywell International |
| Raytheon Technologies |
| Lockheed Martin Corporation |
| Thales Group |
| BAE Systems |
| Northrop Grumman Corporation |
| L3Harris Technologies |
| Elbit Systems |
| General Dynamics Corporation |
| Others |
Value Chain & Pricing Dynamics
East Asian foundry concentration for advanced FPGA and GPU fabrication anchors cost structures across the military sensor software stack, concentrating margin capture with semiconductor suppliers while defense primes absorb volatility through long-term contracting mechanisms. Software licensing fees and integration services command premium positioning where edge-native architectures sever satellite dependency.
Pricing Analysis
Cost-plus contracts with labor-rate indexation dominate Pentagon procurement, insulating vendors from semiconductor price swings while capping upside. Price differentiation rests on security clearance tier and DevSecOps certification level, with uncleared developers competing on rate card alone. Cost compression in middleware integration is intensifying because primes must publish open APIs under Software Modernization Strategy mandates. Intelligence agencies show least price sensitivity given classified program requirements, while security contractors face ruthless rate competition.
Supply Chain Analysis
Contract manufacturing concentrates with TSMC for advanced silicon, Samsung Foundry for memory-intensive sensor processing, and domestic trusted foundries for radiation-hardened components. Raw material dependencies span gallium nitride substrates, indium phosphide wafers, and specialized ceramic packaging. Single-source vulnerability in EUV lithography equipment creates chokepoint exposure. Distribution runs through prime contractor integration facilities rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Military sensor software sits in early-cycle expansion as DoD directive 5000.87 accelerates software acquisition timelines, compressing fielding schedules from years to months and opening procurement to non-traditional vendors.
For Market Incumbents: Build switching-cost moats through embedded middleware in multi-decade platform lifecycles. Deepen integration with satellite-to-shooter pipelines to lock out modular competitors. Counter DevSecOps-native entrants by acquiring cleared personnel pools faster than security clearance bottlenecks allow. For New Entrants and Emerging Players: Pursue electronic warfare algorithm niches where hardware-centric primes lack software depth. Urban warfare spectral deconfliction offers the most penetrable white space absent from current military portfolios. Lead with continuous delivery credentials to bypass milestone-based procurement gatekeepers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier defense services firms holding cleared engineering benches. Five-to-ten year viability hinges on sustained Indo-Pacific distributed sensing network investments. Watch Five Eyes sensor grid integration milestones as inflection signal for cross-domain orchestration software demand.| Strategic Initiative | Industry Significance |
|---|---|
| Open Architecture Compliance Investment | DoD Software Modernization Strategy mandates API publication, fragmenting monolithic supply relationships. |
| DevSecOps Capability Buildout | Continuous delivery contracts displace milestone-based acquisition, shifting risk to vendors. |
| Edge-Native Computing Partnership | Forward-deployed NATO units demand sub-millisecond processing severed from satellite uplinks. |
| Five Eyes Sensor Grid Integration | Cross-domain orchestration software normalizes disparate national formats across allied networks. |
| Cleared Personnel Acquisition | Security clearance bottlenecks constrain development velocity for classified sensor programs. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with program managers at defense primes, procurement officers at Pentagon software directorates, DevSecOps leads at non-traditional vendors, and integration specialists at military OEMs. Secondary validation drew from DoD directive filings, NATO STANAG documentation, SEC 10-K disclosures from listed defense contractors, and congressional budget justification materials. Bottom-up segment sizing triangulated against top-down defense expenditure allocations.
Calibration against historical program fielding timelines anchored projections across the analysis window. Segmentation dimensions modeled include product type, technology architecture, application mission profile, and end-user procurement pathway. CAGRs derived from weighted program lifecycle assumptions and software refresh rate differentials. Inputs incorporated Pentagon Indo-Pacific spending trajectories and coalition interoperability mandate adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by venture-backed DevSecOps entrants would shift outcomes beyond modeled ranges. Quarterly review of DoD software acquisition directive amendments and Five Eyes sensor sharing agreement progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Stand-Up Pouch Valves Market
Others
Military 4D Printing Market
Others
Medical Simulation Market
Others
Cloud Advertising Market
Others
Versatile Video Coding Market
Others
North America Medical Simulation Market
Others
Vacuum Evaporators Market
Others
Senior Cat Food Market
Others
Ultra Mobile Devices (UMD) Market
Others
UK Real Estate Hospitality Market
Others
Buchner Funnels Market
Others
North America Astrology Market
Others
North America Printed Signage Market
Others
Latin America Contract Packaging Market
Others
North America Thermoformed Plastics Market
Others
Asia-Pacific Military 4D Printing Market