
 Global Lavender Extracts Market | 2026-2036
Global Lavender Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lavender Extracts Market Foresight
Personal care is restructuring lavender extract procurement priorities as cosmetic manufacturers shift from synthetic fragrance compounds to botanical actives with traceable provenance. Young Living Essential Oils leverages its captive cultivation base in Utah and Idaho to secure raw material consistency. NOW Foods competes on volume scale across mass-market retail channels. Alteya Group specializes in organic-certified distillates from Bulgarian lavender fields, anchoring premium positioning in European cosmetic supply chains.
Lavender extracts comprise volatile oil fractions, water-soluble hydrosol phases, and concentrated oleoresins obtained through steam distillation, solvent extraction, or supercritical CO2 processing, serving primarily as functional ingredients in fragrance, preservation, and therapeutic applications. Essential oil dominates value capture due to high linalool and linalyl acetate concentrations demanded by perfumery houses, while hydrosol is gaining traction among cleaning product makers seeking low-irritancy alternatives. Supercritical CO2 extraction, though capital-intensive, preserves heat-sensitive terpenoids that cosmetic manufacturers prize for antioxidant claims.
REACH in Europe mandates full substance registration for imported lavender oil volumes above one tonne annually, reshaping supplier qualification protocols for non-EU distillers. FDA oversight in the United States classifies lavender extracts as GRAS for food flavoring but imposes strict labeling when therapeutic claims appear in cosmetic marketing. USDA organic certification and ISO 9235 aromatic natural raw materials standards further segment accessible market tiers. Stakeholders must monitor evolving residue limits under ECHA review cycles and assess dual certification strategies that bridge cosmetic and food-grade demand pools.
Market Dynamics
Clean-label mandates from cosmetic formulators are restructuring lavender extract procurement, forcing distillers to abandon petrochemical solvents in favor of supercritical CO2 and certified organic steam distillation methods.
Growth Catalysts
- EU Green Deal solvent restrictions:REACH compliance deadlines are accelerating capital deployment into solvent-free extraction infrastructure across French and Bulgarian processing facilities.
- Fragrance house botanical substitution:Perfumery manufacturers are replacing synthetic linalool with steam-distilled lavender essential oil to meet ISO 9235 natural raw material specifications.
- Provence cluster distillation capacity:Concentrated cultivation and processing infrastructure in southeastern France is capturing premium contract volumes from cosmetic multinationals.
Market Restraints
- Supercritical CO2 equipment costs:Capital intensity for CO2 extraction systems exceeds conventional solvent units by multiples, freezing out smaller distillers.
- Monoculture disease vulnerability:Lavender cultivation concentration in Provence and Bulgarian Rose Valley exposes supply chains to Xylella fastidiosa outbreaks.
- Natural fragrance substitution:Synthetic biology-derived terpenoids from fermentation platforms threaten price premiums for botanical linalool.
Strategic Opportunities
- USDA organic certification arbitrage:Dual-certified organic/cosmetic grade extracts command pricing premiums in North American natural product retail channels.
- Hydrosol cleaning product applications:Low-irritancy floral waters are displacing synthetic fragrances in EU eco-label household formulations.
- Japanese cosmetic import demand:METI-aligned cosmetic safety standards favor documented provenance from European lavender cooperatives.
Industry Challenges
- Distiller skill scarcity:Mastery of terpenoid preservation during steam distillation is concentrating among aging artisan operators in Grasse and Kazanlak.
- ECHA substance dossier preparation:REACH registration timelines for lavender oil exceed 18 months, blocking non-EU suppliers from annual tonne-plus contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lavender Extracts Market |
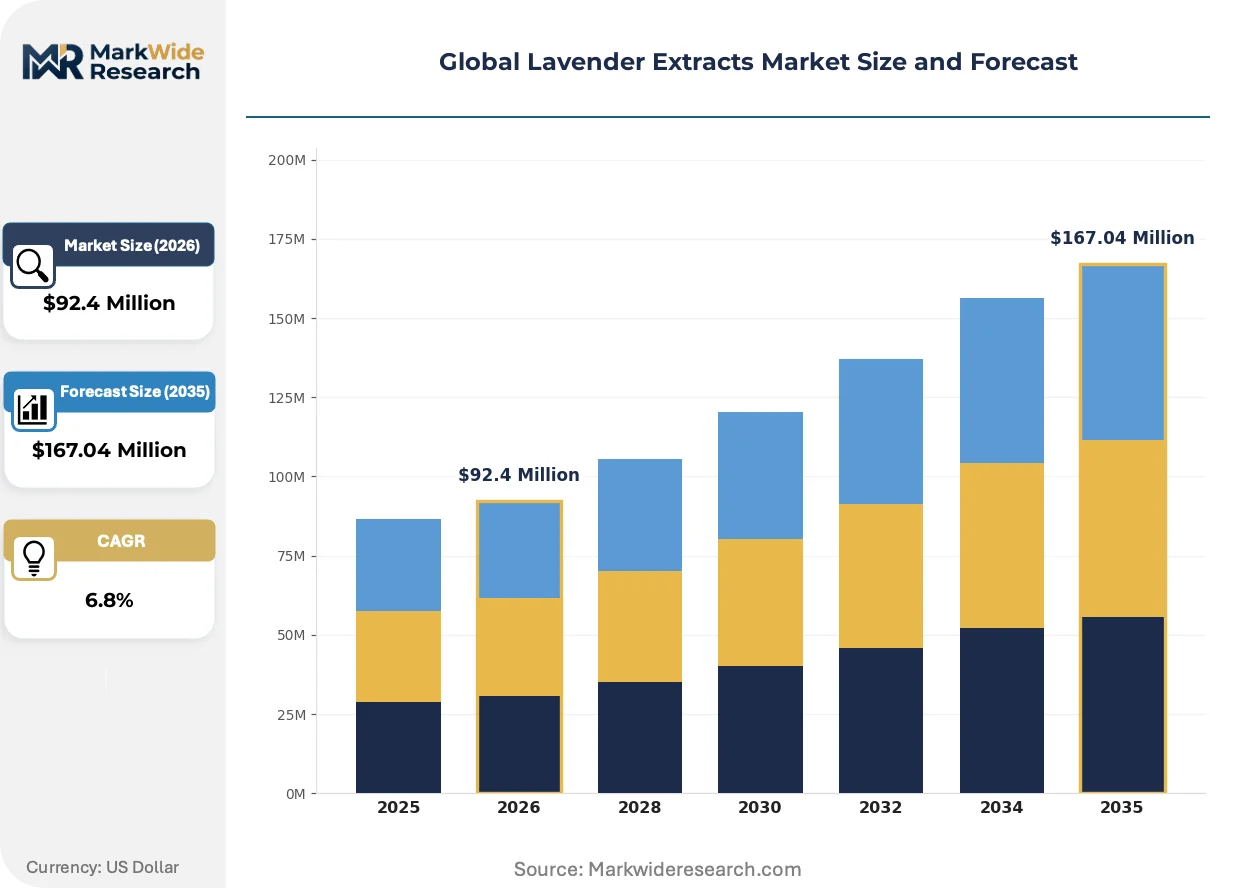
| Market Size in 2026 | $92.4 Million |
| Market Size in 2035 | $167.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oil, Absolute, Hydrosol, Oleoresin, Concentrate Extraction Method: Steam Distillation, Solvent Extraction, Cold Pressing, Supercritical CO2, Maceration Application: Aromatherapy, Personal Care, Household Products, Food Flavoring, Pharmaceuticals, Perfumery End Use Sector: Cosmetic Manufacturers, Food & Beverage Producers, Pharmaceutical Companies, Cleaning Product Makers, Fragrance Houses |
| Companies Covered | TERRA, Aura Cacia, Young Living Essential Oils, Mountain Rose Herb, The Body Shop, NOW Foods, Plant Therapy Essential Oils, NHR Organic Oils, Alteya Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lavender Extracts Market Shifts & Advancements
Extraction technology maturation and regulatory chemistry disclosure requirements are converging to favor capital-intensive processing methods over traditional solvent-based production.
Supercritical CO2 extraction is expanding into mid-scale distiller operations as equipment financing models mature. Cosmetic manufacturers seeking heat-sensitive terpenoid preservation for antioxidant marketing claims are specifying CO2-derived oleoresins in procurement tenders. This technology is expanding into price tiers previously served by hexane extraction, compressing margins for conventional solvent processors.
REACH Article 33 disclosure obligations are forcing full supply chain substance registration for lavender oil imports above one tonne annually. Non-EU distillers face qualification protocol overhauls to maintain access to cosmetic formulation houses. Bulgarian and French suppliers with pre-registered dossiers are capturing contract volumes from competitors in unregistered jurisdictions.
Clean-label procurement criteria now mandate batch-level provenance documentation from cultivation through distillation. Mass-market personal care brands are bypassing commodity brokers to contract directly with cooperative distillers in Provence. This pattern is most visible in French and German cosmetic supply chains, where ISO 9235 certification has become a table-stakes qualification.
Global Lavender Extracts Market Segmentation
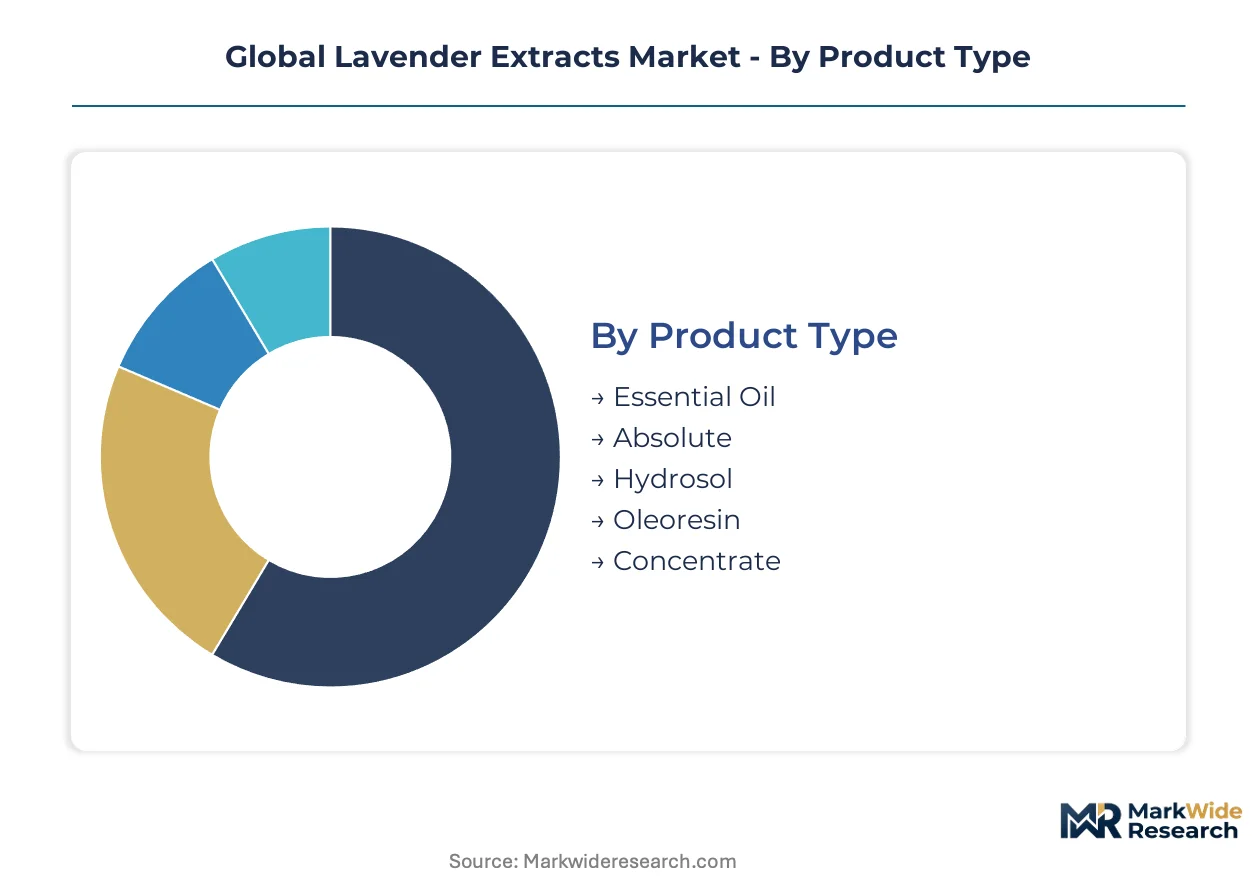
Lavender extract procurement decisions hinge on terpenoid concentration thresholds, regulatory compliance tiers, and end-use certification requirements. Formulators segment suppliers by extraction purity, solvent residue limits, and provenance documentation depth.
Product Type:
Buyers prioritize linalool content and heat-sensitivity preservation when selecting extract formats for specific functional applications.
- Essential Oil:Steam-distilled volatile fraction containing 25-45% linalool and 20-35% linalyl acetate. Fragrance houses in Grasse and perfume compounders in Geneva specify this grade for ISO 9235-compliant natural fragrance formulations, driving premium contract volumes from Provence distillers.
- Hydrosol:Aqueous co-product retaining water-soluble plant acids and trace volatiles. EU eco-label cleaning product manufacturers in Germany and the Netherlands displace synthetic fragrances with this low-irritancy alternative, accelerating procurement from Bulgarian organic cooperatives.
- Absolute:Solvent-extracted concentrate for fine perfumery requiring alcohol-soluble aromatic compounds.
- Oleoresin:Viscous extract combining essential oil and resinous fractions for therapeutic applications.
- Concentrate:Standardized strength format for mass-market personal care formulations.
Volume sits with Essential Oil; growth tilts toward Hydrosol.
Extraction Method:
Capital deployment and regulatory solvent restrictions differentiate processor capabilities across compliance tiers.
- Steam Distillation:Conventional thermal separation yielding standardized essential oil fractions. Bulgarian Rose Valley and Provence facilities dominate capacity for cosmetic-grade output, though heat degradation of sensitive terpenoids limits antioxidant claim applications.
- Supercritical CO2:Pressurized carbon dioxide extraction preserving heat-labile compounds including camphor and caryophyllene. French mid-scale distillers near Apt are expanding CO2 capacity to capture cosmetic antioxidant specification demand, despite equipment costs exceeding conventional solvent units.
- Solvent Extraction:Hexane or ethanol-based processing for absolute production.
- Cold Pressing:Mechanical expression preserving top-note volatiles for premium fragrance applications.
- Maceration:Oil-infusion technique for artisan-scale therapeutic product manufacturing.
Steam Distillation commands installed capacity; CO2 methods are climbing the fastest.
Application:
End-use regulatory frameworks and labeling requirements determine extract grade specifications and certification investments.
- Personal Care:Skincare and haircare formulations requiring REACH-registered cosmetic-grade documentation. Formulators in France and Germany bypass commodity brokers to contract directly with Provence cooperatives for batch-level provenance tracking.
- Perfumery:Fine fragrance compounding demanding ISO 9235 aromatic natural raw materials certification. Swiss and French fragrance houses substitute steam-distilled lavender for synthetic linalool to meet natural claim specifications.
- Aromatherapy:Therapeutic-grade inhalation and topical applications.
- Household Products:Eco-label cleaning and air care formulations.
- Food Flavoring:GRAS-status applications in confectionery and beverages.
- Pharmaceuticals:API and excipient uses requiring pharmacopeial compliance.
Personal Care generates current revenue concentration; Perfumery shows the steepest specification-driven margin expansion.
End Use Sector:
Procurement scale and certification sophistication separate mass-market volume buyers from premium specification purchasers.
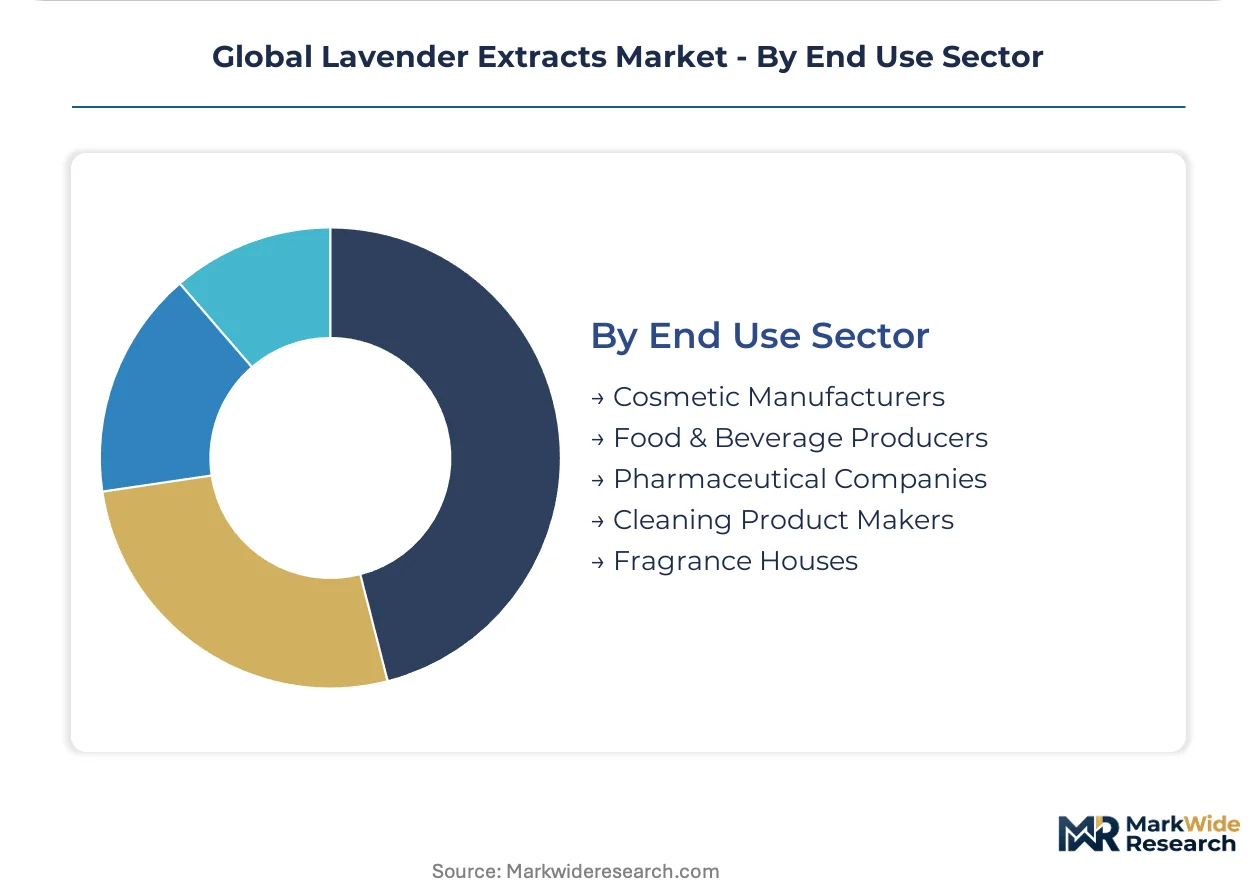
- Cosmetic Manufacturers:Multinational skincare brands and clean-label indie formulators driving organic certification arbitrage. North American natural product retailers command dual USDA organic and cosmetic-grade documentation, concentrating contract awards on Bulgarian and French certified suppliers.
- Fragrance Houses:Compounders specifying terpenoid profiles for luxury and mass-market perfume lines. Givaudan and Firmenich procurement tenders increasingly mandate CO2-derived fractions for heat-sensitive antioxidant marketing claims.
- Food & Beverage Producers:Flavoring applications requiring FDA GRAS or EFSA food additive compliance.
- Pharmaceutical Companies:Dosage form manufacturers seeking pharmacopeial-grade extracts.
- Cleaning Product Makers:Eco-formulation specialists in EU member states specifying hydrosol fractions for low-toxicity claims.
Cosmetic Manufacturers anchor procurement volume; Fragrance Houses are gaining share fastest through specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France and Bulgaria concentrate cultivation and distillation capacity, while the United States, Germany, and Japan drive formulation demand for cosmetic and fragrance applications. This production-consumption divide shapes trade flows and regulatory compliance investments across supplier networks.
France
Provence-Alpes-Côte d'Azur hosts the densest lavender cultivation and steam distillation infrastructure globally, with cooperatives around Apt and Grasse supplying ISO 9235-certified material to Swiss and French fragrance houses. REACH registration requirements under ECHA mandate full substance dossiers for exports exceeding one tonne annually. The Grasse perfume cluster is absorbing CO2 extraction capacity to preserve heat-sensitive terpenoids for antioxidant cosmetic claims.
Bulgaria
Kazanlak in the Rose Valley anchors organic-certified lavender oil production for North American natural product retailers demanding dual USDA organic and cosmetic-grade documentation. Bulgarian suppliers leverage pre-registered REACH dossiers to capture contract volumes from competitors in unregistered jurisdictions. Distillation cooperatives in the valley are expanding hydrosol output for EU eco-label cleaning product manufacturers in Germany and the Netherlands.
United States
Utah and Idaho cultivation bases supply captive raw material for vertically integrated essential oil brands serving domestic aromatherapy and personal care channels. FDA GRAS classification for food flavoring applications runs parallel to stricter cosmetic labeling requirements when therapeutic claims appear in marketing. Young Living Essential Oils leverages its Mountain West cultivation footprint to secure batch-level provenance documentation for premium positioning.
Germany
Formulators in North Rhine-Westphalia and Bavaria specify REACH-registered lavender extracts for clean-label skincare lines, bypassing commodity brokers to contract directly with Provence cooperatives. EU Green Deal solvent restrictions are accelerating procurement shifts toward CO2-derived fractions. German eco-label cleaning product makers are displacing synthetic fragrances with Bulgarian hydrosol imports.
Japan
Cosmetic safety standards aligned with METI favor documented provenance from European lavender cooperatives, creating import demand for French and Bulgarian certified material. Japanese fragrance compounders specify terpenoid profiles that favor steam-distilled essential oil over synthetic biology alternatives. Tokyo-based personal care brands are qualifying suppliers through extended batch documentation protocols.
Global Lavender Extracts Market Competitive Landscape
Top-tier vendors anchor premium positioning through captive cultivation and dual certification, while mid-scale distillers compete on volume scale and regional compliance coverage. The vendor base stratifies across three archetypes: vertically integrated cultivator-distillers with owned fields, cooperative federations aggregating smallholder output, and contract processors serving private-label demand. M&A activity concentrates on distillation capacity acquisition in Provence and Bulgaria, while technology licensing partnerships spread supercritical CO2 extraction methods to mid-scale operators.
Within the cultivator-distiller tier, Young Living Essential Oils and Alteya Group exemplify divergent geographic strategies—one leveraging Mountain West cultivation for North American supply security, the other anchoring premium positioning through Bulgarian organic certification. NOW Foods occupies a position at the scale-driven end of mass-market retail distribution. Aura Cacia and Plant Therapy Essential Oils sit within the specialty aromatherapy channel, representing brands that emphasize direct-to-consumer education and therapeutic-grade positioning.
| Leading Market Players |
|---|
| TERRA |
| Aura Cacia |
| Young Living Essential Oils |
| Mountain Rose Herb |
| The Body Shop |
| NOW Foods |
| Plant Therapy Essential Oils |
| NHR Organic Oils |
| Alteya Group |
| Others |
Supply & Pricing Matrix
Artisan distiller expertise concentration in Grasse and Kazanlak feeds directly into pricing-tier spreads across the lavender extract market, with labor-cost differentials between aging French masters and Bulgarian cooperative workers creating three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Margin tightening in CO2-derived fractions reflects capital equipment amortization burdens and REACH registration compliance costs. Price differentiation rests on certification grade and volume scale, with dual-certified organic/cosmetic extracts commanding substantial premiums over conventional steam-distilled grades. Cost-down pressure on solvent-extracted absolutes accelerates because EU Green Deal solvent restrictions are forcing processor conversion investments. Mass-market personal care manufacturers exhibit highest price sensitivity, while fragrance houses demonstrate lowest sensitivity due to specification-driven procurement.
Supply Chain Analysis
EU Green Deal local-content requirements and REACH substance registration mandates are reshaping sourcing patterns toward pre-registered European suppliers. Geographic supply concentration centers on France, Bulgaria, and the United States, with raw material dependencies drawing from lavender cultivation, distillation equipment, and certification audit services. Single-source vulnerability runs through Provence's monoculture exposure to Xylella fastidiosa. Distribution feeds from cooperative distillers through direct contracts with cosmetic multinationals, bypassing traditional commodity brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lavender extract market functions as a consolidation play where REACH registration timelines and supercritical CO2 capital requirements are forcing weaker, unregistered distillers out of annual tonne-plus contracts.
For Market Incumbents: Anchor premium positioning through captive cultivation investments in Provence or Bulgarian Rose Valley to secure batch-level provenance documentation. Deepen upstream control over distillation infrastructure to defend against synthetic biology-derived terpenoid substitution threats from fermentation platforms. Prioritize dual USDA organic and ISO 9235 certification maintenance to sustain pricing power in North American natural product retail channels. For New Entrants and Emerging Players: Capture white-space opportunity in Japanese cosmetic import demand, where METI-aligned safety standards favor documented European provenance but remain underpenetrated by Bulgarian organic cooperatives. Target EU eco-label cleaning product manufacturers in Germany and the Netherlands with hydrosol fraction specialization as the most penetrable application segment. Pursue equipment financing partnerships for mid-scale CO2 extraction capacity as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale French distillers near Apt given accelerating CO2 capacity deployment for antioxidant cosmetic claims. Long-term viability over the medium-term horizon favors targets with pre-registered REACH dossiers and established Provence or Kazanlak cultivation bases. Monitor ECHA substance review cycles as the key inflection signal for registration cost escalations that would accelerate distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Captures cosmetic antioxidant specification demand from Givaudan and Firmenich procurement tenders. |
| Dual Certification Investment | Unlocks premium pricing in North American natural product retail through USDA organic and ISO 9235 alignment. |
| Direct Cooperative Contracting | Bypasses commodity brokers to secure batch-level provenance documentation for French and German formulators. |
| Hydrosol Output Scaling | Displaces synthetic fragrances in EU eco-label cleaning products across German and Dutch manufacturing bases. |
| REACH Dossier Pre-Registration | Maintains market access for annual tonne-plus contracts under ECHA substance registration mandates. |
Research Methodology
Trade databases, ECHA registration filings, and customs export records formed the secondary backbone of this analysis, supplemented by primary interviews with distiller cooperative managers, cosmetic procurement leads at multinational formulators, fragrance house compounders, and EU eco-label cleaning product R&D directors. Bottom-up triangulation across cultivation area estimates, distillation capacity utilization rates, and end-use demand segments was cross-validated against top-down market sizing from regulatory compliance cost structures and certification audit volumes.
Historical trendline analysis of extraction technology adoption rates and certification penetration patterns informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, extraction method, application, and end-use sector alongside geographic regulatory cluster differentiation. CAGRs were derived from capacity expansion pipelines, substitution elasticity estimates between synthetic and botanical linalool, and compliance cost trajectory assumptions including supercritical CO2 equipment financing maturity and REACH registration fee schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Xylella fastidiosa outbreak severity, synthetic biology terpenoid platform cost curves, and EU Green Deal solvent restriction enforcement timelines. Forecasts reflect documented assumptions around cultivation yield stability and cooperative distiller consolidation rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Cosmetovigilance Market
Others
Aerospace Software Testing Market
Others
Global Hardware Acceleration Market
Others
Cremation Furnace Market
Others
Latin America IT Device Market
Others
Global Car Wax Market
Others
Education and Learning Analytics Market
Others
Allogeneic Human Chondrocyte Market
Others
Subtilisin Market
Others
Africa 3D Printing Construction Market
Others
Liquid-Cooled Heat Sink Market
Others
Mainframe Market
Others
Global Learning Analytics Market
Others
Safety Critical Software Testing Market
Others
Iran Commercial Vehicles Lubricants Market
Others
Advanced Fiber-Based Gasket Market