
 Folding Smartphone Market | 2026-2036
Folding Smartphone Market Size, Share, and Industry Trends Forecast 2026-2036
Folding Smartphone Market Insights
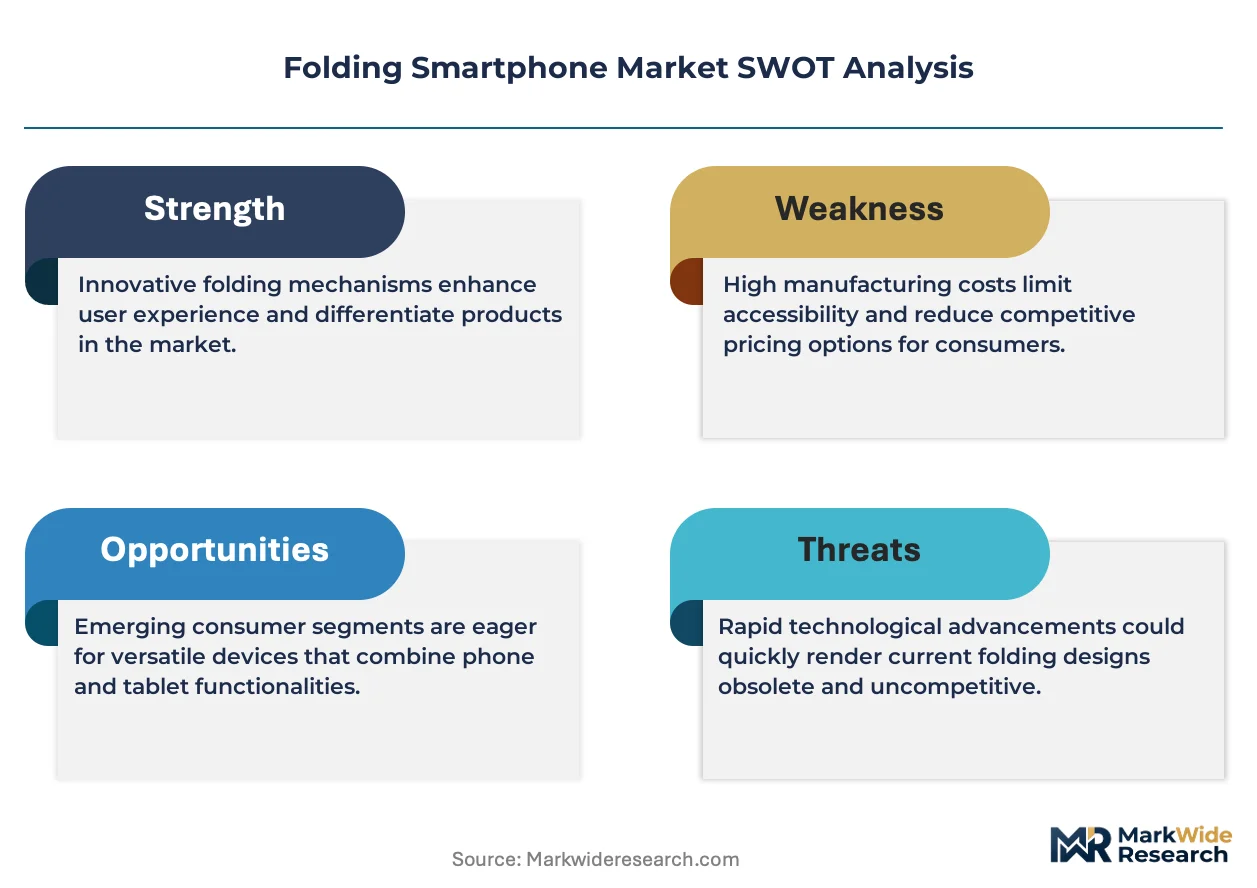
Multi-source panel supply for flexible OLED substrates is consolidating around a handful of qualified vendors. Samsung Electronics dominates upstream display manufacturing through captive production at its affiliate operations. Huawei Technologies sustains vertical integration into hinge mechanisms and proprietary composite layering. Xiaomi Corporation competes aggressively on cost-engineered flip-phone architectures.
A folding smartphone integrates a flexible organic light-emitting diode display with precision-engineered hinge assemblies rated for hundreds of thousands of bend cycles, serving consumers who require pocketable devices with tablet-scale screen real estate. Book-style configurations command premium positioning due to larger unfolded dimensions and productivity-oriented multi-tasking capabilities, while flip phones anchor volume sales through accessible price points and compact form factors. Glass-based cover materials face displacement pressure as composite substrates improve scratch resistance while reducing weight.
South Korea's national telecom regulator imposes radio-frequency certification standards that foldables must clear before domestic launch, while China's MIIT enforces mechanical reliability protocols for repeated flexing. The EU's RoHS and REACH frameworks restrict hazardous substances in hinge alloys and adhesive compounds, shaping material selection across export-bound production lines. Stakeholders must track how durability certification thresholds evolve in major certification regimes and calibrate warranty provisions accordingly.
Market Dynamics
China's MIIT durability mandates are compressing development cycles for foldable displays, forcing manufacturers to accelerate composite material qualification while recalibrating warranty structures against stricter mechanical reliability protocols.
Growth Catalysts
- Hybrid Workforce Equipment Policies:Enterprises across South Korea and Japan are standardizing book-style foldables for field engineers and sales teams, creating institutional procurement pipelines that bypass consumer retail channels.
- REACH and RoHS Material Compliance:The EU's substance restrictions on hinge alloys and adhesives are filtering non-compliant suppliers from export-bound production lines, concentrating procurement among qualified vendors with certified compound formulations.
- UTG-to-Composite Substrate Transition:Ultra-thin glass cover materials face displacement as polymer-based composites demonstrate equivalent scratch resistance at reduced weight, opening design latitude for thinner hinge assemblies.
Market Restraints
- Captive OLED Panel Supply:Flexible substrate manufacturing concentrates among affiliate operations of major Korean and Chinese electronics groups, limiting independent brand access to qualified display supply.
- MIIT Certification Timeline Friction:China's mechanical reliability protocols add 4-6 months to product launch schedules, compressing competitive windows against domestic rivals with established testing relationships.
- Input Cost Volatility in Rare-Earth Magnets:Neodymium and dysprosium price swings directly impact precision hinge actuator costs, eroding margin stability for mid-tier product positioning.
Strategic Opportunities
- India PLI Scheme for Electronics Manufacturing:Production-linked incentives for component assembly create landed-cost advantages for export-oriented foldable subassembly operations serving Middle Eastern and African markets.
- Healthcare Documentation Workflows:Hospital systems in Germany and Switzerland are piloting book-style foldables for bedside patient data entry, opening vertical-specific software and ruggedization requirements.
- Direct-to-Enterprise Distribution:BYOD policy relaxation at Fortune 500 headquarters is enabling manufacturer-direct volume contracts that disintermediate carrier subsidy models.
Industry Challenges
- Thin-Film Encapsulation Talent Scarcity:Process engineers with experience in multi-layer barrier deposition for flexible OLEDs command premium compensation, constraining R&D team scaling.
- Dual-Carbon Compliance Documentation:Supply chain emissions verification for EU CBAM alignment requires granular material provenance tracking that legacy ERP systems cannot support.
- Interoperability with Legacy Enterprise Security Stacks:Knox and Android Enterprise certification delays frustrate CIOs seeking immediate deployment of foldables within zero-trust network architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Folding Smartphone Market |
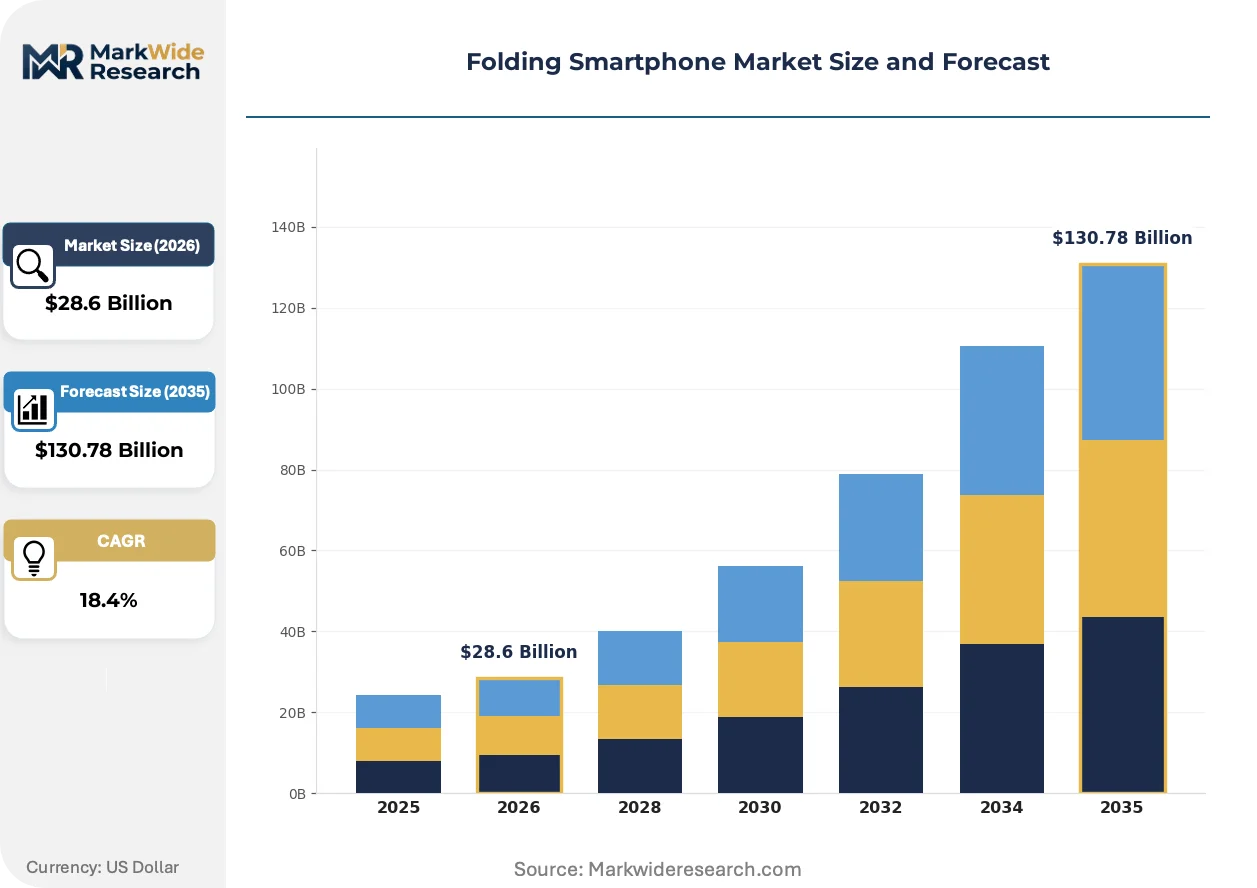
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $130.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Phones, Book Style, Rollable Phones, Hybrid Designs Material: Glass, Plastic, Metal, Composite Feature: 5G Connectivity, Multi-Tasking Capabilities, High Refresh Rate, Stylus Support End User: Tech Enthusiasts, Business Professionals, Students, Casual Users |
| Companies Covered | Samsung Electronics Co. Ltd., Huawei Technologies Co. Ltd., Motorola Mobility LLC, Vivo, Honor Device Co. Ltd., Oppo Mobile Telecommunications Corp. Ltd., Xiaomi Corporation, Google LLC, OnePlus Technology (Shenzhen) Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Folding Smartphone Market Trends and Innovations
Material science breakthroughs and procurement model evolution are compressing traditional product lifecycles while redistributing value capture across the foldable supply chain.
Advanced polymer composites with vapor-deposited ceramic hardcoats are integrating into cover window assemblies, replacing ultra-thin glass in cost-engineered flip-phone architectures. Chinese manufacturers are adopting these materials fastest, leveraging domestic chemical substrate supply chains to undercut Korean rivals on bill-of-materials costs. This integration is compressing price premiums between glass and composite-based product tiers.
Europe's RoHS substance restrictions are tightening allowable thresholds for cadmium and lead in hinge electroplating processes, forcing alloy reformulation across export-bound production lines. Korean and Vietnamese assembly plants are retooling electroplating baths to comply with the 2024 amendments, adding capital intensity to mid-tier manufacturing operations. Book-style foldables with larger hinge mechanisms face disproportionate compliance burden compared to compact flip designs.
Enterprise procurement teams are consolidating vendor relationships through multi-year device-as-a-service contracts that bundle hardware, insurance, and managed refresh cycles. Carrier retail channels in South Korea and Japan are losing volume to direct manufacturer enterprise sales teams with dedicated fleet management portals. This concentration is most visible in financial services and professional services verticals where standardization across hybrid workforces reduces IT support complexity.
Folding Smartphone Market Segmentation
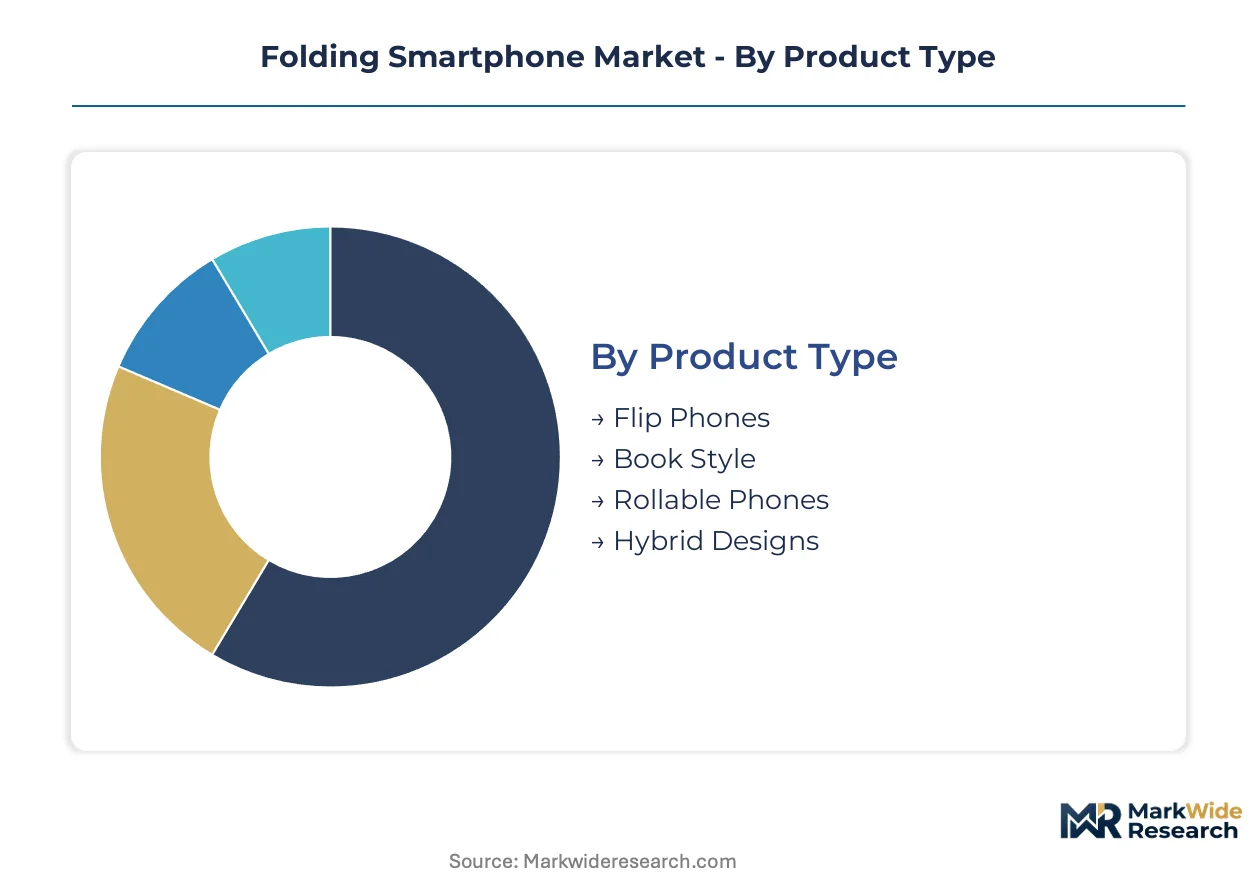
Segmentation in folding smartphones reveals how form factor, material science, and user workflow requirements partition demand across distinct hardware configurations and price bands. Each axis carries supply chain implications that reshape vendor positioning and procurement priorities.
Product Type:
Hinge complexity and unfolded screen area define the engineering trade-offs across form factor architectures.
- Book Style:Dual-panel designs with inward-folding hinges maximize unfolded display real estate for productivity workflows. Enterprise procurement teams in South Korea and Japan favor these units for field engineers requiring simultaneous document viewing and data entry.
- Flip Phones:Clamshell configurations fold vertically around compact hinge assemblies, prioritizing pocketability over screen expansion. Casual users in urban Chinese markets drive volume here, attracted by accessible price points and one-handed operation.
- Rollable Phones:Motorized extension mechanisms unspool flexible substrates from a cylindrical housing, eliminating crease-prone fold lines entirely. Early prototypes from select Chinese OEMs target tech enthusiasts seeking novel interaction paradigms.
- Hybrid Designs:Tri-fold or dual-axis hinge systems enable multiple rigidness configurations, though mechanical complexity elevates warranty costs and manufacturing defect rates.
Flip phones lead on scale; book-style leads on momentum.
Material:
Cover window and substrate selection directly impacts durability certification outcomes and bill-of-materials flexibility.
- Composite:Polymer substrates with vapor-deposited ceramic hardcoats match glass scratch resistance at 30-40% lower mass, enabling thinner hinge assemblies. Chinese manufacturers accelerate adoption fastest, leveraging domestic chemical supply chains.
- Glass:Ultra-thin chemically strengthened cover materials maintain premium positioning through optical clarity and tactile familiarity. Samsung Electronics anchors production through captive affiliate operations.
- Plastic:Polyimide and CPI substrates persist in entry-tier flip phones where cost minimization outweighs scratch resistance requirements.
- Metal:Titanium and aluminum alloys reinforce hinge housings and frame rails, with rare-earth magnet integration driving actuator precision in book-style mechanisms.
Glass dominates revenue capture; composite gains share fastest.
Feature:
Connectivity and input specifications segment procurement priorities across consumer and institutional buyers.
- 5G Connectivity:Sub-6GHz and mmWave radio integration is standard above mid-tier price points, with South Korea's spectrum allocation mandating compatibility for domestic certification.
- Multi-Tasking Capabilities:Split-screen software optimization and expanded virtual RAM support productivity workflows, appearing as standard in enterprise-bound book-style configurations.
- High Refresh Rate:120Hz and 144Hz adaptive panels differentiate gaming-oriented and premium consumer SKUs, elevating power consumption and thermal design requirements.
- Stylus Support:Active digitizer integration with pressure sensitivity targets creative professionals and healthcare documentation use cases in German and Swiss hospital pilots.
5G connectivity leads on scale; stylus support climbs the fastest.
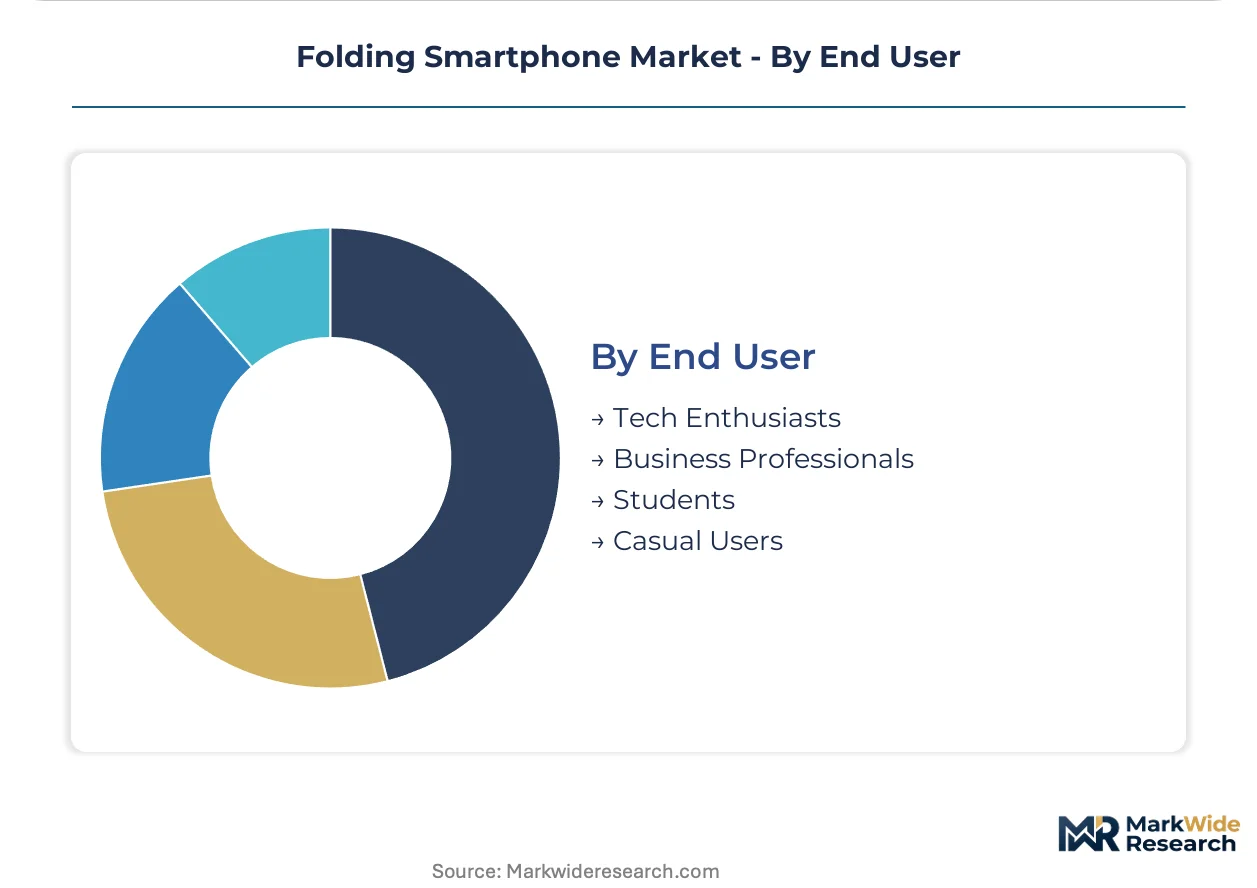
End User:
Buyer archetypes concentrate demand across distinct distribution channels and service bundling models.
- Business Professionals:Hybrid workforce equipment policies in financial services and professional services verticals standardize book-style foldables, bypassing carrier retail through direct manufacturer enterprise contracts.
- Tech Enthusiasts:Early adopters absorb premium pricing for novel form factors and limited-edition collaborations, generating disproportionate social media visibility that shapes mainstream perception.
- Students:Price-sensitive demand concentrates in flip-phone architectures with education-discount programs, particularly in Chinese and Indian campus retail channels.
- Casual Users:Replacement-cycle buyers prioritize brand familiarity and camera specifications over fold-specific features, representing latent demand for mainstream price compression.
Casual users lead on scale; business professionals show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Suwon anchors the global foldable smartphone supply chain through Samsung Electronics' vertically integrated display and device assembly operations, while Shenzhen and Beijing drive alternative ecosystem development through aggressive component localization and MIIT-mandated durability protocols.
South Korea
Seoul's enterprise procurement teams standardize book-style foldables for hybrid field workforces, creating institutional demand pipelines that bypass retail channels. The Korea Communications Commission enforces radio-frequency certification standards that domestic launches must clear before market entry. Suwon and Gumi concentrate precision hinge manufacturing and flexible OLED substrate production within Samsung Electronics' captive affiliate network.
China
Shenzhen's OEM ecosystem accelerates composite material adoption for cost-engineered flip-phone architectures targeting price-sensitive urban consumers. MIIT mandates stricter mechanical reliability testing for repeated flexing, adding 4-6 months to product launch schedules. Beijing and Dongguan host the densest clusters of hinge mechanism suppliers and polymer substrate fabricators serving domestic brands.
United States
Fortune 500 headquarters in New York and San Francisco relax BYOD policies to enable direct manufacturer enterprise contracts for field sales teams. The FCC maintains equipment authorization requirements for foldable radio-frequency emissions without fold-specific mechanical addenda. Austin and Seattle concentrate software engineering talent for multi-tasking optimization and enterprise security stack integration.
Japan
Tokyo's financial services and professional services verticals drive book-style adoption through standardized hybrid workforce equipment policies. METI coordinates industrial standards for flexible display durability without mandatory pre-market testing timelines. Osaka and Nagoya house precision component suppliers for hinge actuator systems and rare-earth magnet integration.
Germany
Munich and Frankfurt hospital systems pilot book-style foldables for bedside patient data entry, opening healthcare-specific ruggedization requirements. The EU's REACH and RoHS frameworks restrict cadmium and lead in hinge electroplating processes, forcing alloy reformulation across export-bound production lines. Dresden concentrates thin-film encapsulation research for flexible OLED barrier deposition.
Folding Smartphone Market Competitive Landscape
Global majors compete with regional champions across upstream display supply and downstream brand positioning, producing a tiered structure where captive OLED manufacturing separates premium positioning from cost-engineered alternatives. Korean electronics groups anchor the upper tier through affiliate-controlled flexible substrate production. Chinese OEMs occupy the volume tier through aggressive composite material localization and domestic supply chain leverage. The competitive arena centers on M&A for hinge mechanism IP and strategic partnerships for display panel allocation.
Among Korean electronics groups, Samsung Electronics Co. Ltd. exemplifies captive upstream integration, while Huawei Technologies Co. Ltd. represents vertical control over proprietary hinge architectures. Xiaomi Corporation occupies a position within the cost-optimization tier, leveraging domestic chemical substrate supply chains to compress bill-of-materials differentials.
| Leading Market Players |
|---|
| Samsung Electronics Co. Ltd. |
| Huawei Technologies Co. Ltd. |
| Motorola Mobility LLC |
| Vivo |
| Honor Device Co. Ltd. |
| Oppo Mobile Telecommunications Corp. Ltd. |
| Xiaomi Corporation |
| Google LLC |
| OnePlus Technology (Shenzhen) Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
EU REACH and RoHS substance restrictions gate qualified supply for export-bound hinge electroplating processes, concentrating procurement among vendors with certified alloy formulations and compressing premium-tier pricing access for book-style configurations with larger hinge mechanisms. This environmental compliance layer filters non-compliant suppliers from European distribution channels while elevating input costs for compliant production lines.
Pricing Analysis
Input-cost pass-through from rare-earth magnet price volatility directly impacts precision hinge actuator manufacturing, with neodymium and dysprosium swings eroding margin stability in mid-tier book-style positioning. Three-tier pricing structure across premium, standard, and economy levels separates Samsung's captive OLED-integrated flagship offerings from Xiaomi's composite-based cost-engineered alternatives and entry-tier plastic-substrate flip phones. Cost compression in the mid-tier is intensifying because Chinese manufacturers accelerate domestic polymer substrate adoption to undercut Korean rivals on bill-of-materials costs. Students and casual users in Chinese and Indian campus retail channels exhibit the highest price sensitivity, while enterprise procurement teams in financial services verticals demonstrate the lowest sensitivity due to standardized hybrid workforce equipment policies.
Supply Chain Analysis
Freight cost differentials between Korean affiliate-controlled flexible OLED substrate production and Chinese domestic chemical supply chains are redistributing assembly location decisions for export-oriented operations. Supply concentrates in South Korea for glass-based cover materials and flexible OLED manufacturing, in China for polymer substrate fabrication and hinge mechanism component clusters, and in Vietnam for electroplating retooling to meet EU compliance requirements. The supply chain draws from rare-earth magnet deposits for actuator precision, vapor-deposited ceramic hardcoats for composite scratch resistance, and ultra-thin glass chemistries for premium optical clarity. Single-source vulnerability in Samsung Display's captive panel allocation creates procurement bottlenecks for independent brands lacking established testing relationships with MIIT. Distribution runs through direct manufacturer enterprise sales teams with dedicated fleet management portals, bypassing carrier retail channels in South Korea and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where enterprise procurement teams standardize book-style foldables for hybrid field workforces, shifting demand toward premium specifications with multi-tasking capabilities and stylus support.
For Market Incumbents: Hedge against composite substrate displacement by accelerating in-house production of polymer-based cover window assemblies before Chinese rivals capture cost-engineered flip-phone volume. Samsung Electronics should defend its captive OLED allocation advantage through expanded enterprise direct contracts that bypass carrier subsidy models, while simultaneously investing in thin-film encapsulation talent retention as process engineers with multi-layer barrier deposition experience command premium compensation.
For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing opens a window for export-oriented foldable subassembly operations serving Middle Eastern and African markets with landed-cost advantages. Target healthcare documentation workflows in German and Swiss hospital systems as the most penetrable vertical-specific application, leveraging stylus-integrated book-style configurations for bedside patient data entry. Pursue device-as-a-service bundling with insurance and managed refresh cycles to disintermediate established carrier retail relationships.
For Investors and Strategic Acquirers: Roll-up economics work for hinge mechanism IP specialists because mechanical reliability certification requirements under MIIT and EU REACH are consolidating procurement among qualified vendors with proven compound formulations. The viable acquisition window spans five to ten years as material science breakthroughs compress traditional product lifecycles. Watch for inflection when enterprise BYOD policy relaxation at Fortune 500 headquarters accelerates manufacturer-direct volume contract signings that displace carrier subsidy models.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Qualification Acceleration | MIIT durability mandates compress development cycles for domestic Chinese manufacturers leveraging polymer substrate supply chains. |
| Direct-to-Enterprise Distribution Buildout | Samsung and Huawei bypass carrier retail through dedicated fleet management portals targeting financial services verticals. |
| Healthcare Vertical Ruggedization Partnership | German hospital systems pilot book-style foldables for bedside patient data entry with stylus-integrated active digitizers. |
| Thin-Film Encapsulation Talent Acquisition | Process engineers with multi-layer barrier deposition experience command premium compensation as R&D team scaling constrains. |
| EU REACH Compliance Electroplating Retool | Korean and Vietnamese assembly plants add capital intensity to eliminate cadmium and lead from hinge alloy formulations. |
Research Methodology
Coverage spans South Korea, China, Japan, Germany, and the United States, with primary inputs from each market combining interviews with display manufacturing executives, hinge mechanism procurement leads, enterprise IT fleet managers, regulatory affairs specialists at MIIT and REACH compliance consultancies, and secondary validation through SEC 10-K filings, Korea Communications Commission certification databases, EU ECHA substance restriction updates, and trade customs data for flexible OLED substrate flows. Bottom-up assembly cost modeling triangulates against top-down enterprise procurement pipeline estimates.
Rate-of-change decomposition separates volume expansion in flip-phone architectures from value capture in book-style enterprise configurations across the projection horizon. Segmentation dimensions modeled include form factor type, cover material substrate, connectivity specification, and end-user archetype with vertical-specific workflow requirements. CAGRs derive from installed base replacement cycles, enterprise standardization policy adoption curves, and composite material penetration rates in cost-engineered tiers. Industry-specific forecast inputs incorporate MIIT certification timeline friction and rare-earth magnet price volatility indices.
Revisions become necessary when MIIT mechanical reliability protocols extend certification timelines beyond current baselines, when EU REACH substance restrictions tighten allowable thresholds for hinge electroplating processes, or when enterprise BYOD policy relaxation accelerates faster than carrier channel displacement models assume. Stakeholders should weight assumptions against their own operating context for captive OLED access, composite material qualification status, and enterprise sales team deployment timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Aircraft Lighting Systems Market
Others
Bitcoin Mining Hardware Market
Others
3D Printing Construction Market
Others
Rotary Union Market
Others
Hydrostatic Testing Market
Others
Military 4D Printing Market
Others
Sound Reinforcement Market
Others
North America Video Conferencing Hardware Market
Others
Construction Wearables Market
Others
Electric Chainsaw Market
Others
Surgical Simulation Market
Others
Global Electroshock Weapons Market
Others
Taiwan Retail Market
Others
GCC Health and Wellness Market
Others
Reusable Wine Bags Market
Others
Medical Simulation Market