
 Consumer Video Feedback Software Market | 2026-2036
Consumer Video Feedback Software Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Video Feedback Software Market Analysis
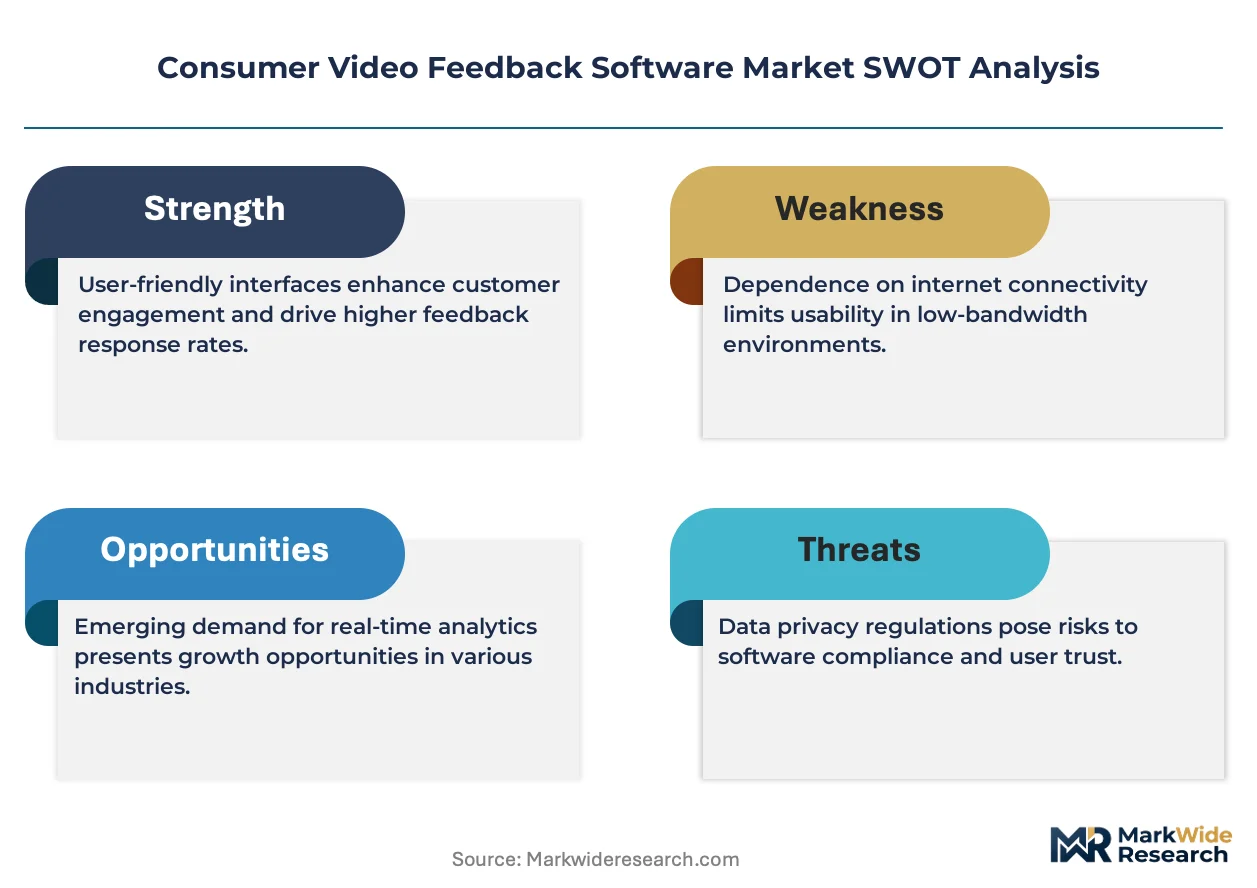
Enterprise-grade analytics dashboard functionality is unwinding the legacy survey-dominated feedback landscape. Dscout leverages its panel management infrastructure to sustain premium positioning among qualitative researchers. Medallia anchors enterprise experience management contracts through deep CRM integrations. Qualtrics competes across both academic and commercial sectors with modular survey-to-video pipelines.
Consumer video feedback software enables organizations to capture, store, and analyze recorded video responses from customers or research participants, typically incorporating time-stamped transcription, sentiment tagging, and collaborative annotation layers. These systems serve commercial and institutional buyers seeking unscripted, emotionally dense qualitative data that static text responses cannot replicate. Cloud-based deployment leads structural adoption due to elastic storage scaling and zero-latency global distribution of video assets. SaaS delivery models capture the fastest expansion as vendors bundle AI-powered transcription and automated highlight reel generation into recurring subscriptions. On-premises solutions occupy regulated niches where data sovereignty requirements override cost efficiency.
FDA oversight of software-as-a-medical-device intersects with HIPAA privacy mandates when video feedback platforms process patient-reported outcomes in healthcare settings. The EU AI Act imposes risk-classification obligations on automated sentiment analysis and facial emotion recognition features embedded in feedback tools. GDPR data minimization principles shape retention policies and consent workflows across European deployments. Stakeholders must monitor how divergent transatlantic AI transparency requirements will force architectural forks between American and European product instances.
Market Dynamics
Enterprise marketing teams are abandoning static survey instruments in favor of asynchronous video capture systems that yield emotionally dense qualitative signals from distributed participants. This shift compresses research timelines while expanding the volume of actionable feedback available to product teams.
Growth Catalysts
- GDPR-Aligned Consent Workflows:Automated data residency controls in the European Union reduce legal friction for cross-border research deployments. Vendors embed granular retention policies that satisfy CNIL and national data protection authorities.
- AI-Powered Transcription Engines:Natural language processing pipelines convert video responses into searchable text within minutes. UX research consultancies leverage this capability to accelerate insight generation for digital-native brands.
- Remote-First Research Protocols:Distributed workforce patterns sustain demand for unmoderated video feedback collection. Enterprise buyers in the United States prioritize platforms that eliminate geographic constraints on participant recruitment.
Market Restraints
- Cloud Storage Cost Volatility:Elastic compute pricing for high-resolution video assets compresses vendor margins during usage spikes. Tier-1 hyperscalers dictate infrastructure economics with limited negotiation leverage.
- FDA Software-as-Medical-Device Classification:Patient-reported outcome platforms in healthcare settings face heightened validation requirements. HIPAA privacy mandates compound compliance burdens for clinical research applications.
- Facial Emotion Recognition Substitutes:Biometric sentiment analysis tools from adjacent markets compete for budget allocation. Buyers question whether video feedback delivers incremental value over automated affect detection.
Strategic Opportunities
- EU AI Act Risk-Tier Positioning:Vendors that architect "limited risk" classification for automated sentiment features gain procurement preference. Early compliance investments create defensible positioning in European public-sector tenders.
- Patient-Reported Outcome Integration:Healthcare providers seek video feedback modules for chronic disease management programs. FDA validation pathways, once navigated, unlock recurring revenue from pharmaceutical sponsors.
- Academic-Commercial Hybrid Licensing:Universities with established research panels represent underpenetrated distribution channels. Platforms that bridge institutional procurement with enterprise-grade analytics capture dual-revenue streams.
Industry Challenges
- Qualitative Research Methodology Expertise:Platform vendors struggle to hire sufficient PhD-level researchers to support enterprise clients. Customer success teams lack depth in ethnographic analysis and thematic coding protocols.
- Legacy Survey System Integration:Enterprise buyers demand seamless data pipelines between video feedback platforms and established experience management suites. API standardization remains fragmented across vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Video Feedback Software Market |
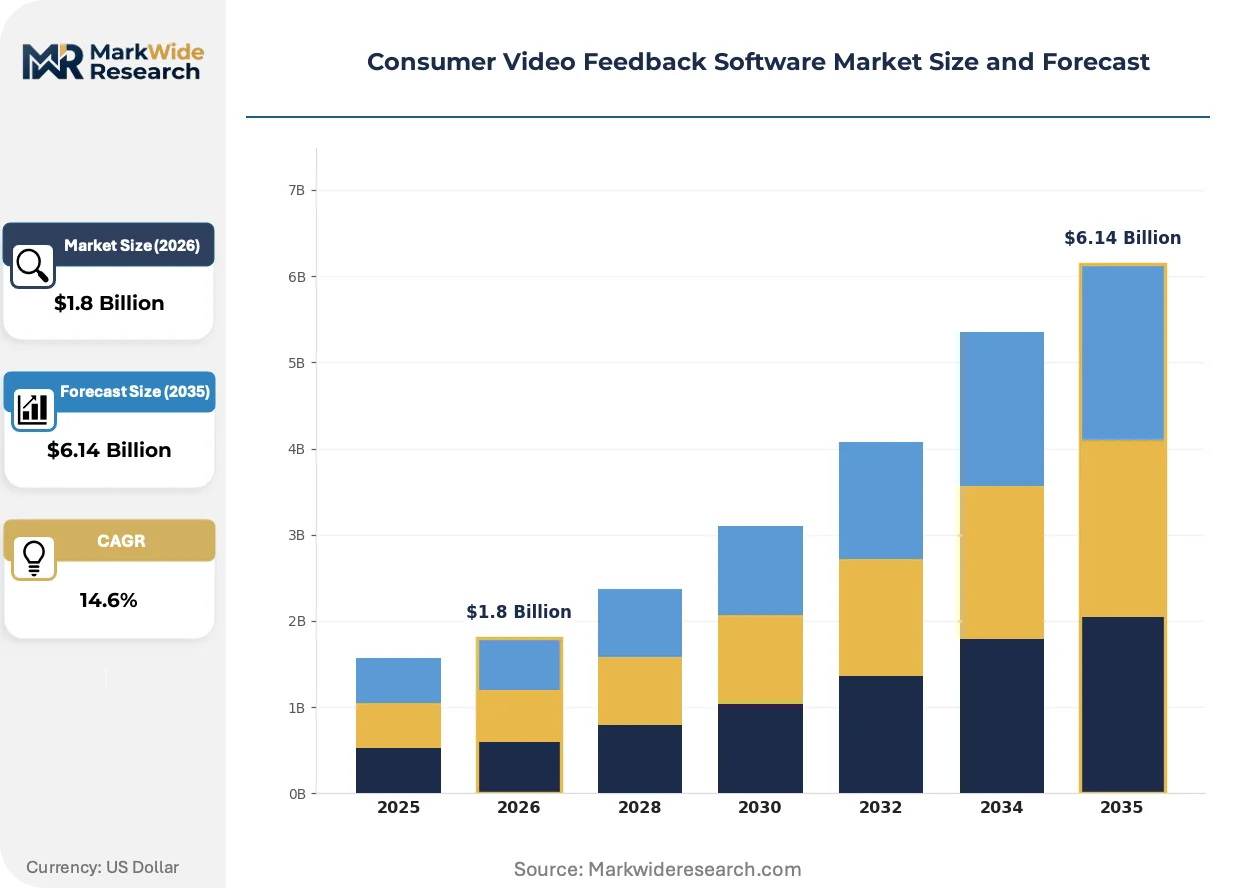
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Retailers, Marketers, Enterprises, Educators Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Solution: Feedback Collection, Analytics Tools, Management Systems, Engagement Platforms Feature: Screen Recording, Live Feedback, Analytics Dashboard, User Interface |
| Companies Covered | Dscout, Userfeel, UXtweak, Medallia, VideoAsk, Respondent, Forsta, Qualtrics, VideoPeel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Video Feedback Software Market Emerging Trajectories
Automated highlight reel generation and real-time collaborative annotation are compressing the insight-to-action cycle for distributed research teams. These capabilities reshape how organizations consume qualitative data at scale.
Multimodal AI pipelines that fuse transcription, sentiment scoring, and visual cue detection are supplanting human-only analysis workflows. Mid-market research consultancies adopt these tools to compete with larger agencies on turnaround speed. The technology is compressing project economics and forcing traditional qualitative shops to reposition around strategic interpretation rather than mechanical coding.
The EU AI Act's risk-classification framework imposes documentation burdens on automated emotion recognition features deployed in European jurisdictions. Vendors must maintain technical files and conformity assessments for "high-risk" biometric processing. Healthcare and financial services segments in Germany and France are front-loading compliance investments to avoid operational interruption.
Subscription-based platform access is displacing per-project licensing among enterprise buyers seeking predictable research budgets. Procurement teams consolidate vendor relationships and demand unlimited seat arrangements with annual commitments. This pattern concentrates most visibly in the United States, where digital-native brands operate continuous feedback loops rather than episodic research studies.
Consumer Video Feedback Software Market Segmentation
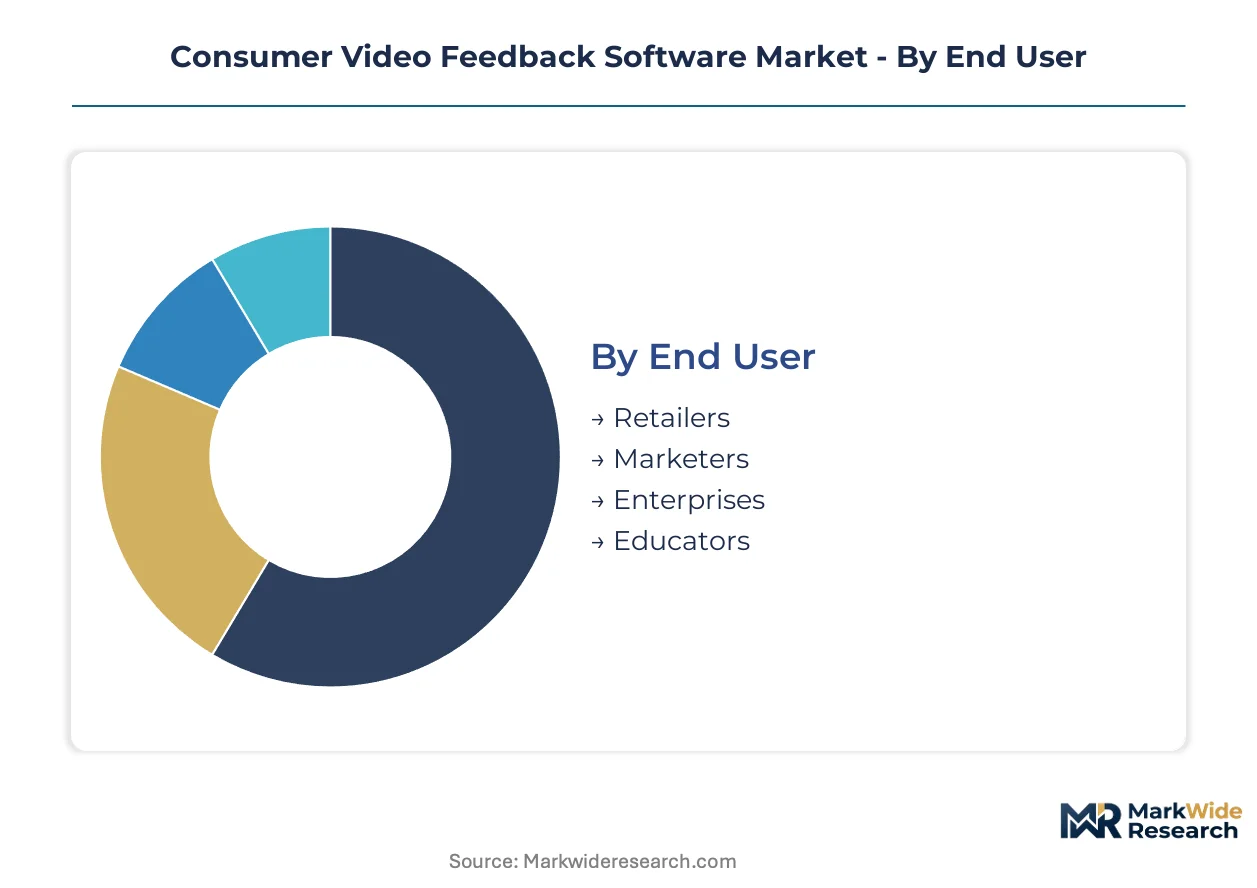
Segmentation in consumer video feedback software reveals how deployment constraints, feature requirements, and end-user sophistication reshape vendor product roadmaps. Buyers prioritize different capability bundles based on regulatory exposure and research methodology maturity.
End User:
Retailers and marketers concentrate demand in North America and Western Europe, while educators and enterprises show stronger uptake in domestic public-sector procurement cycles.
- Retailers:E-commerce operators deploy video feedback to capture unscripted customer reactions to digital storefronts and checkout flows. Demand clusters among direct-to-consumer brands in the United States seeking rapid iteration on product page design.
- Marketers:Brand teams use asynchronous video capture for campaign pre-testing and creative optimization. European marketing departments under GDPR jurisdiction prioritize platforms with automated consent workflows and EU data residency controls.
- Enterprises:Large organizations integrate video feedback into continuous experience management programs. Procurement teams favor unlimited-seat SaaS arrangements with annual commitments over per-project licensing.
- Educators:Universities and research institutions adopt video feedback for remote learning assessment and qualitative research panels. Academic buyers bridge institutional procurement with enterprise-grade analytics requirements.
Enterprises hold the largest share; momentum sits with marketers expanding continuous feedback loops.
Deployment:
Cost tier stratification separates hyperscale cloud deployments from compliance-driven on-premises installations with significant infrastructure overhead.
- Cloud-Based:Elastic storage scaling and zero-latency global distribution dominate commercial adoption. Tier-1 hyperscalers dictate infrastructure economics, compressing vendor margins during usage spikes for high-resolution video assets.
- SaaS:Recurring subscription models bundle AI-powered transcription and automated highlight reel generation. Digital-native brands in the United States drive fastest expansion through continuous feedback protocols rather than episodic research.
- On-Premises:Regulated healthcare and financial services segments deploy localized infrastructure to satisfy data sovereignty mandates. HIPAA privacy requirements and FDA software-as-medical-device classifications compound validation burdens.
- Hybrid:Organizations split sensitive processing on-premises while leveraging cloud analytics for non-regulated workloads. European buyers under GDPR data minimization principles favor this architecture for cross-border research.
SaaS captures the steepest expansion trajectory; on-premises retains strategic value in clinical and banking applications.
Solution:
Application maturity varies sharply between basic collection utilities and integrated management systems with multimodal AI pipelines.
- Analytics Tools:Natural language processing engines convert video responses into searchable text within minutes. UX research consultancies leverage this capability to accelerate insight generation and compete with larger agencies on turnaround speed.
- Management Systems:Platforms integrate transcription, sentiment scoring, and visual cue detection into unified workflows. Mid-market research shops adopt these tools to reposition around strategic interpretation rather than mechanical coding.
- Feedback Collection:Core video capture functionality with time-stamped recording and basic annotation layers. Price-sensitive academic buyers often select standalone collection modules over full-suite deployments.
- Engagement Platforms:Combined participant recruitment, incentive management, and community-building features. Panel management infrastructure sustains premium positioning among qualitative researchers with established respondent networks.
Management systems hold the largest share; analytics tools are climbing the fastest as AI transcription quality improves.
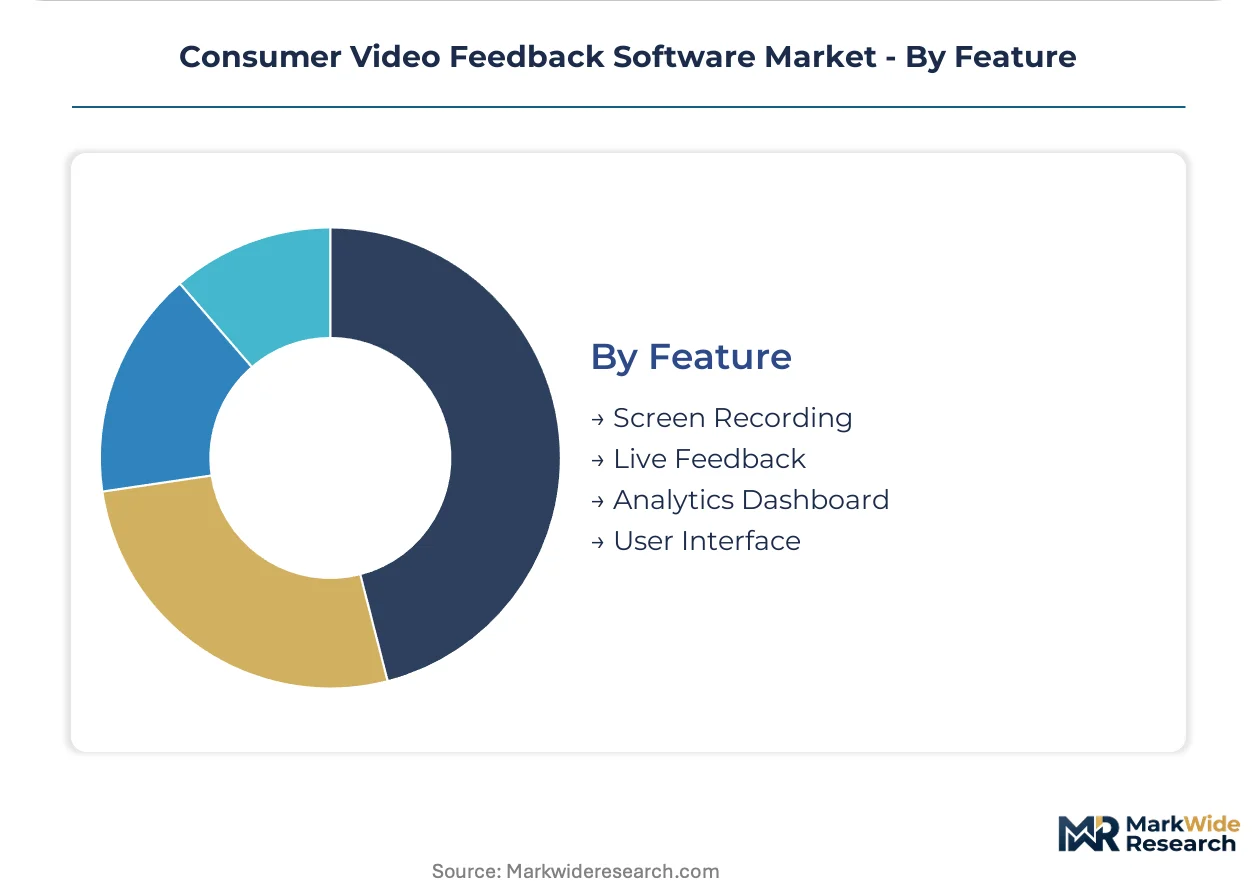
Feature:
Customer type differentiation separates technical power users requiring screen recording from executive buyers prioritizing dashboard visualization.
- Analytics Dashboard:Enterprise-grade visualization compresses the insight-to-action cycle for distributed research teams. Procurement teams consolidate vendor relationships around platforms with collaborative annotation and real-time sharing.
- Screen Recording:Captures participant device interactions alongside facial video for contextual behavioral analysis. Product teams at software companies rely on this feature to identify friction points in digital workflows.
- Live Feedback:Synchronous moderated sessions enable researcher-participant dialogue during video capture. Higher per-session costs limit adoption to specialized clinical and high-stakes commercial research.
- User Interface:Simplified participant-facing design reduces drop-off rates in unmoderated studies. Mobile-optimized interfaces expand recruitment pools beyond desktop-limited demographics.
Analytics dashboard holds the largest share; screen recording gains share fastest as remote usability testing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in consumer video feedback software favor net-importing jurisdictions where domestic platform development lags enterprise demand. The United States generates substantial outbound licensing revenue while European and Asian markets absorb foreign solutions under strict data residency frameworks.
United States
Digital-native brands and UX research consultancies drive platform subscriptions through continuous feedback protocols rather than episodic studies. FDA oversight intersects with HIPAA privacy mandates when platforms process patient-reported outcomes in healthcare settings. San Francisco Bay Area and New York City clusters concentrate vendor headquarters and enterprise sales operations.
Germany
Industrial enterprises and automotive manufacturers adopt video feedback for customer experience management in premium segments. GDPR data minimization principles shape retention policies and consent workflows across national deployments. Munich and Stuttgart industrial corridors host pharmaceutical and engineering firms requiring validated qualitative research tools.
United Kingdom
Financial services and media sectors deploy asynchronous video capture for rapid creative testing and customer insight generation. Post-Brexit data adequacy arrangements complicate cross-border research with EU participants. London fintech clusters and Manchester media production hubs represent concentrated demand centers.
Japan
Enterprise buyers prioritize platforms with localized interface design and culturally adapted sentiment analysis for domestic consumer research. METI guidelines on AI governance influence procurement criteria for automated transcription features. Tokyo and Osaka metropolitan areas concentrate headquarters of consumer electronics and retail conglomerates.
India
IT services exporters and domestic e-commerce operators expand adoption of video feedback tools for user research and quality assurance. The country's data protection framework under development creates uncertainty for cloud-first deployment architectures. Bengaluru and Hyderabad technology corridors host development centers serving global platform vendors.
Consumer Video Feedback Software Market Vendor Landscape
Listed leaders compete with private specialists across funding access and product velocity dimensions. The vendor base organizes into three tiers: established experience management suites with deep CRM integrations, qualitative research specialists with panel management infrastructure, and emerging tools focused on asynchronous video capture workflows. Competitive positioning hinges on M&A activity consolidating adjacent capabilities and API standardization efforts enabling seamless data pipelines with enterprise systems.
Within the experience management tier, Medallia and Qualtrics occupy positions anchoring enterprise contracts through integration breadth. Dscout exemplifies the qualitative research specialist archetype with panel-centric infrastructure sustaining premium positioning among methodologically sophisticated buyers.
| Leading Market Players |
|---|
| Dscout |
| Userfeel |
| UXtweak |
| Medallia |
| VideoAsk |
| Respondent |
| Forsta |
| Qualtrics |
| VideoPeel |
| Others |
Supply Flow & Price Mechanics
Hyperscale cloud infrastructure economics compress vendor margins while simultaneously erecting price floors that smaller competitors cannot match. Elastic compute pricing for high-resolution video assets concentrates pricing power among tier-1 hyperscalers, forcing SaaS vendors to absorb volatility or pass costs to enterprise buyers.
Pricing Analysis
Enterprise marketing teams anchor subscription pricing across three tiers: premium suites with AI-powered transcription and panel management, standard bundles with basic analytics, and economy tiers for standalone collection modules. Price differentiation rests on integration depth with CRM systems and compliance certification levels including GDPR-aligned data residency and FDA software-as-medical-device validation. Pricing pressure intensifies as facial emotion recognition tools from adjacent biometric markets compete for budget allocation, squeezing mid-market vendors. Academic buyers exhibit highest price sensitivity, while healthcare providers under HIPAA mandates demonstrate lowest sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
The United States and Ireland anchor cloud infrastructure provisioning for North American and European deployments respectively, with Singapore serving as Asia-Pacific hub for latency-sensitive video distribution. Tier-1 hyperscalers including AWS, Azure, and Google Cloud draw from specialized GPU clusters and custom AI accelerators for transcription pipeline processing. Single-source vulnerability concentrates in hyperscaler concentration risk, where infrastructure economics are dictated by three dominant providers. Distribution runs through direct enterprise sales teams supplemented by UX research consultancy channel partners who bundle platform access with methodological services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated affect detection systems threaten to displace video feedback platforms in budget-constrained buyer segments, forcing incumbents to articulate incremental value beyond raw emotional signal capture.
For Market Incumbents: Fortify platform differentiation by deepening vertical integration into panel management infrastructure and securing EU AI Act "limited risk" conformity assessments ahead of procurement cycles. Defensive investments in multimodal AI pipelines that fuse transcription, sentiment scoring, and visual cue detection will raise switching costs against biometric sentiment substitutes. For New Entrants and Emerging Players: Academic-commercial hybrid licensing gaps expose underpenetrated distribution channels where institutional procurement frameworks lag enterprise analytics requirements. White-space targets include university research panels seeking unlimited-seat arrangements and mid-market consultancies repositioning around strategic interpretation rather than mechanical coding. Go-to-market execution should emphasize API-first architectures that fragment legacy survey system integration chokepoints. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform vendors with validated FDA pathways and established healthcare revenue streams over pure-play asynchronous capture tools. Long-term viability hinges on recurring revenue concentration in pharmaceutical sponsor contracts and enterprise experience management consolidations. Watch for inflection signals in EU public-sector tender volumes where early AI Act compliance investments convert to procurement preference.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Early conformity assessment investments unlock defensible positioning in European public-sector tenders. |
| Panel Management Infrastructure Acquisition | Proprietary respondent networks sustain premium pricing power against commodity capture tools. |
| FDA Software-as-Medical-Device Validation | Validated pathways unlock recurring pharmaceutical sponsor revenue from patient-reported outcome programs. |
| Multimodal AI Pipeline Integration | Fused transcription-sentiment-visual analysis compresses project economics for mid-market consultancy clients. |
| Academic Licensing Program Expansion | Bridge procurement frameworks capture dual-revenue streams from institutional and commercial buyers. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with platform vendors, enterprise UX research directors, qualitative consultancy principals, and healthcare compliance officers; and secondary validation through SEC SaaS company filings, hyperscaler infrastructure capex disclosures, EU regulatory documentation, and clinical research procurement databases. Bottom-up triangulation across deployment model, end-user vertical, and feature tier segmentation was cross-checked against top-down market sizing from subscription revenue disclosures.
Across the projection horizon, value and volume outputs were modeled through elasticity-adjusted adoption curves and pricing tier stratification. Segmentation dimensions included deployment architecture, organization size band, vertical industry, integration complexity tier, and regional regulatory cluster. CAGRs were derived from historical subscription growth rates and forward-looking penetration assumptions for asynchronous video protocols, with specific inputs from remote-first research protocol permanence and GDPR-aligned consent workflow automation.
Forecasts assume regulatory continuity in FDA software classification regimes and EU AI Act implementation timelines; material policy shifts would require re-modeling of healthcare and European public-sector demand trajectories. Specific risks include cloud storage cost volatility from hyperscaler pricing adjustments and divergent transatlantic AI transparency requirements forcing product architecture forks. Recalibration cycles align with material shifts in enterprise procurement consolidation patterns and biometric substitute technology performance benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
North America IT Device Market
Others
Middle East Smart Home Market
Others
Europe Air Separation Unit Market
Others
Europe Aircraft Lighting Systems Market
Others
Small Office Home Office (SOHO) Servers Market
Others
Spinner Flask Market
Others
Live IP Broadcast Equipment Market
Others
Rotary Dial Machine Market
Others
Middle East and Africa Home Care Packaging Market
Others
GCC Cigarette Market
Others
Trusted Platform Module (TPM) Market
Others
Liquid-Cooled Heat Sink Market
Others
Halogen Free Flame Retardant Bopet Films Market
Others
Global Flexible PVC Films Market
Others
Subtilisin Market
Others
Wearable AI Market