
 Asia Pacific Automotive LED Lighting Market | 2026-2036
Asia Pacific Automotive LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Automotive LED Lighting Market Insights
The capability gap between integrated chip-scale manufacturers and pure-play assemblers is bifurcating competitive returns in Asia Pacific automotive LED lighting. Nichia Corporation leverages captive gallium nitride substrate production to sustain margin capture on high-luminance dies for matrix applications. KOITO MANUFACTURING CO., LTD. anchors its position through backward integration into optical design and thermal management for Japanese and Chinese OEM programs. Stanley Electric Co., Ltd. differentiates via laser LED prototyping capacity that commands premium positioning in Korean luxury vehicle supply chains.
Asia Pacific automotive LED lighting comprises solid-state electroluminescent devices fabricated on sapphire or silicon carbide substrates, emitting in the 450–550 nanometer range for white-light conversion through phosphor coatings, with thermal dissipation requirements typically exceeding 85°C junction temperatures for front-lamp endurance. The technology serves vehicle exterior and interior illumination with directional precision, energy efficiency, and programmable beam patterns that halogen or xenon architectures cannot replicate. Front lamps occupy the dominant value pool given regulatory complexity and optical performance thresholds, while matrix LED technology captures the fastest expansion trajectory as Chinese OEMs integrate adaptive driving beam functions. Factory-installed channels lead volume but aftermarket installation grows fastest in Southeast Asian markets where vehicle parc renewal outpaces new-car penetration rates.
China's MIIT enforces GB standards for automotive lighting photometric performance that effectively mandate LED adoption for new energy vehicle certification, while Japan's METI coordinates JIS standards with domestic suppliers to preserve export competitiveness. India's BIS has aligned automotive lighting regulations with UN ECE frameworks, compressing compliance timelines for halogen-dependent tier-2 suppliers. Stakeholders must monitor how China's dual carbon goals reshape energy-efficiency benchmarks for vehicle subsystems, and whether ASEAN harmonization of lighting standards accelerates cross-border component qualification.
Market Dynamics
Matrix LED headlamp systems are compressing supplier qualification timelines across Asia Pacific as Chinese OEMs accelerate adaptive driving beam integration for electric vehicle platforms, forcing tier-1 assemblers to secure thermal management and optical design capabilities ahead of procurement cycles.
Growth Catalysts
- MIIT GB Standards:China's Ministry of Industry and Information Technology enforces photometric performance requirements that effectively mandate LED adoption for new energy vehicle type approval, eliminating halogen pathways for domestic OEMs.
- Guangdong-Jiangsu Production Clusters:Concentrated assembly capacity in these provinces generates procurement scale for premium front-lamp modules, with joint ventures and domestic brands anchoring volume commitments.
- Gallium Nitride Substrate Maturation:Advances in GaN-on-silicon carbide epitaxy are reducing die costs for high-luminance applications, enabling matrix beam proliferation beyond luxury segments.
Market Restraints
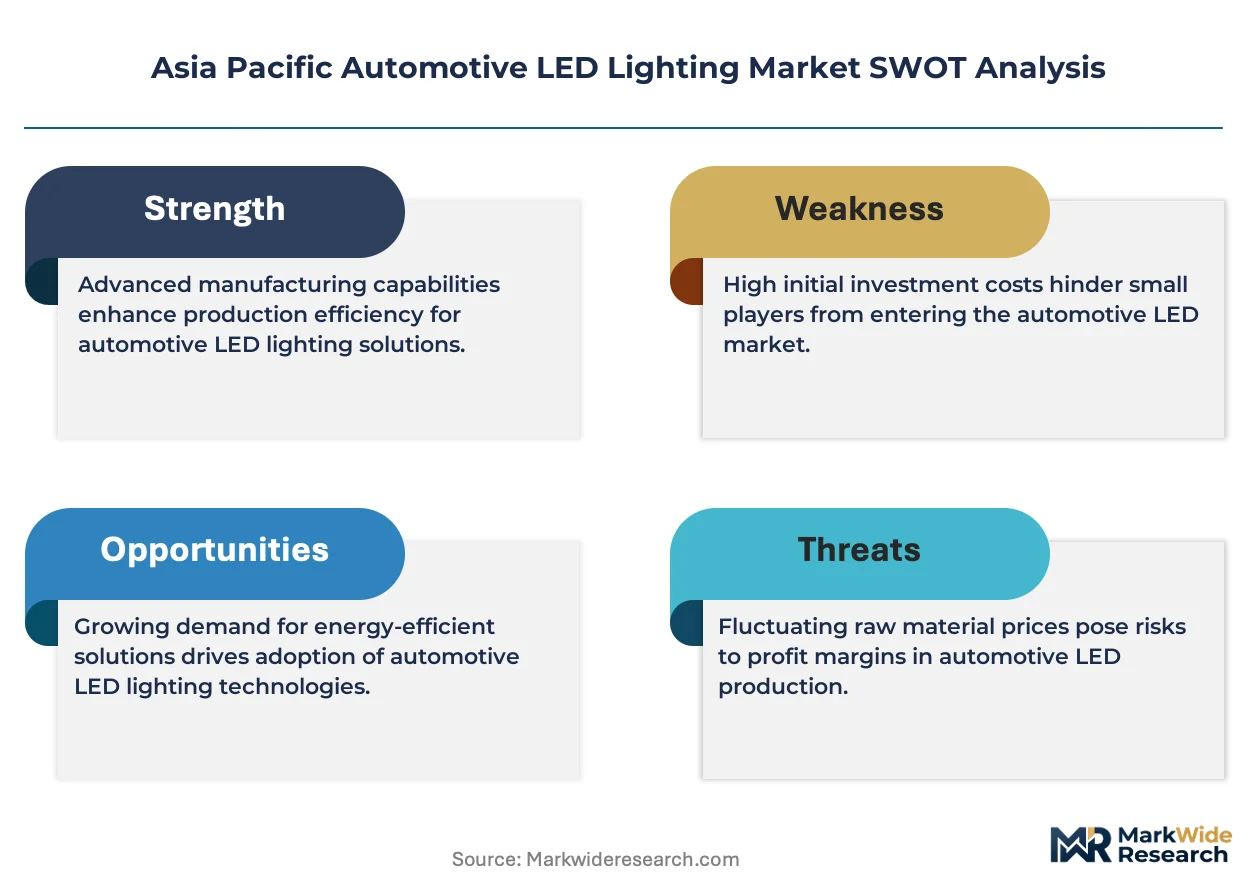
- Sapphire Substrate Supply Concentration:Captive production of high-purity sapphire boules concentrates among integrated chip-scale manufacturers, constraining pure-play assemblers' margin capture on high-performance dies.
- Thermal Management Complexity:Front-lamp endurance requirements exceeding 85°C junction temperatures demand specialized phosphor coatings and heat-sink architectures that inflate bill-of-material costs relative to halogen baselines.
- Halogen Parc Inertia:Southeast Asian vehicle fleets retain substantial halogen-installed base, compressing aftermarket LED conversion velocity where new-car penetration lags replacement demand.
Strategic Opportunities
- Indian BIS Compliance Compression:India's Bureau of Indian Standards alignment with UN ECE frameworks accelerates halogen-to-LED conversion timelines for tier-2 suppliers serving domestic OEMs and commercial vehicle segments.
- ASEAN Standard Harmonization:Cross-border component qualification protocols under development would reduce duplicate certification burdens for suppliers targeting Thailand, Indonesia, and Vietnam assembly operations.
- Laser LED Prototyping Capacity:Korean luxury vehicle supply chains command premium positioning for solid-state lighting architectures that combine laser excitation with phosphor conversion for extended-range high beams.
Industry Challenges
- Optical Design Talent Scarcity:Matrix beam calibration and adaptive driving beam algorithm development require specialized photonics expertise that concentrates among Japanese and German engineering centers, constraining Asia Pacific supplier scaling.
- Dual Carbon Goal Alignment:China's energy-efficiency benchmarks for vehicle subsystems are tightening faster than component qualification cycles, forcing simultaneous redesign of thermal dissipation and power electronics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Automotive LED Lighting Market |
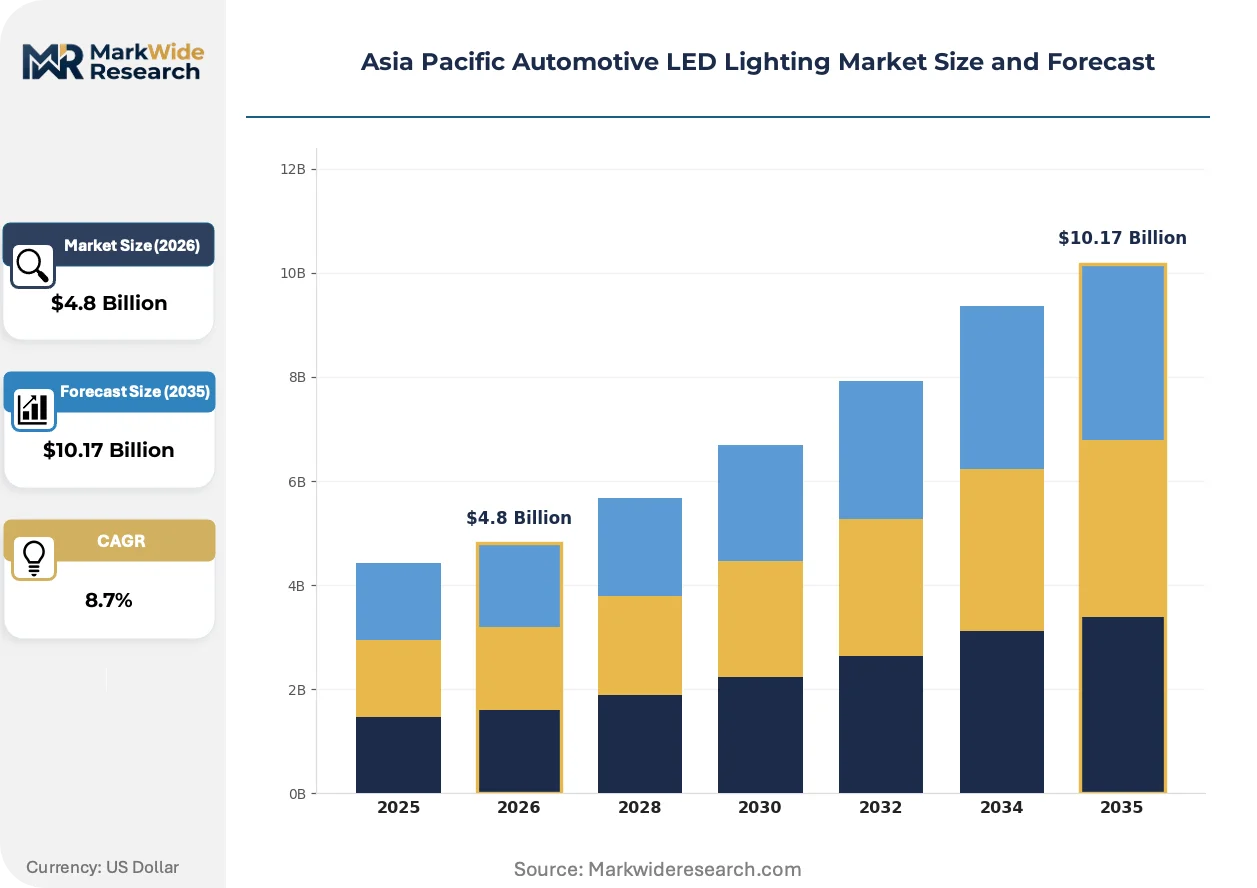
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Lamps, Rear Lamps, Interior Lamps, Ambient Lamps End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation Type: Factory Installed, Aftermarket Installation, Modular Systems, Integrated Solutions Technology: Standard LED, Adaptive LED, Matrix LED, Laser LED |
| Companies Covered | Valeo, Nichia Corporation, KOITO MANUFACTURING CO., LTD., HELLA GmbH and Co. KGaA, LG Innotek, Stanley Electric Co., Ltd., OSRAM GmbH, SL Corporation, Marelli Holdings Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Automotive LED Lighting Market Trends and Innovations
Silicon carbide substrate migration and phosphor-on-chip architectures are reshaping cost-performance tradeoffs across front-lamp and interior applications, while regulatory alignment pressures compress supplier differentiation windows.
Micro-LED pixel arrays for adaptive driving beam functions are displacing conventional matrix LED architectures in premium Chinese electric vehicle programs. NIO, BYD, and Xpeng integrate 10,000+ individually addressable pixels for glare-free high-beam projection. This density is displacing mechanical shutter systems and enabling real-time pedestrian highlighting through machine vision integration.
BIS energy-efficiency mandates for automotive lighting are compressing halogen-to-LED conversion timelines across India's tier-2 supplier base. Commercial vehicle segments face accelerated compliance deadlines relative to passenger car categories. Bus and truck OEMs in Maharashtra and Tamil Nadu are pre-qualifying LED module suppliers ahead of enforcement phases.
Aftermarket channel disintermediation is fragmenting traditional distributor networks across Southeast Asian markets. E-commerce platforms and direct-fit specialists capture growing share of replacement lamp demand. Indonesia and Philippines vehicle parc renewal patterns favor this channel shift where new-car penetration rates trail regional averages.
Asia Pacific Automotive LED Lighting Market Segmentation
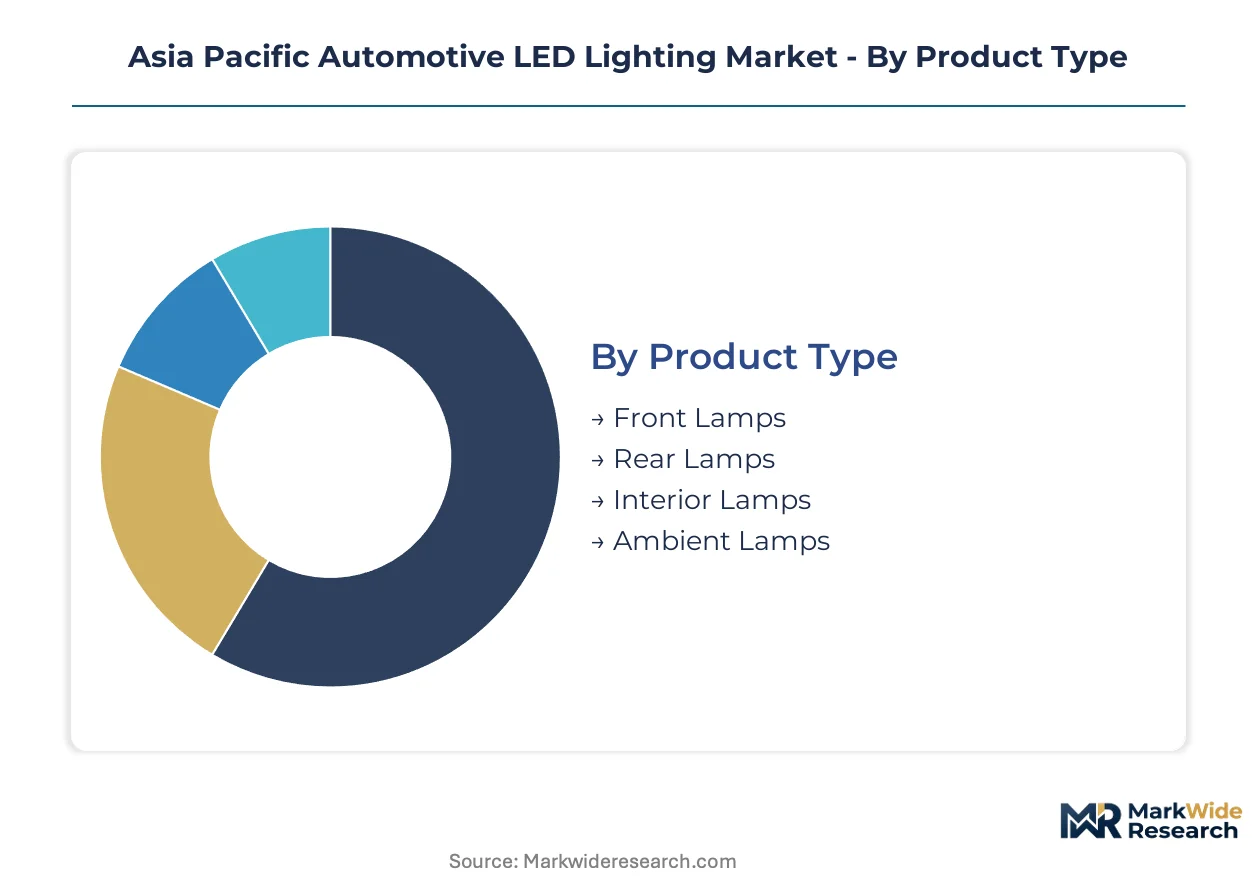
Segmentation in Asia Pacific automotive LED lighting reveals how regulatory pressure and supply chain concentration allocate value across technical tiers. Substitution dynamics from halogen and xenon architectures vary sharply by product position and installation channel.
Product Type:
Front-lamp assemblies face the most acute substitution pressure as MIIT GB standards eliminate halogen pathways for new energy vehicle certification in China.
- Front Lamps:Matrix and adaptive beam architectures dominate procurement from Guangdong and Jiangsu production clusters. Thermal management requirements exceeding 85°C junction temperatures elevate bill-of-material costs and favor suppliers with captive gallium nitride substrate production.
- Rear Lamps:Sequential turn indicators and full-width light bars are displacing conventional bulb architectures across Chinese and Korean OEM programs. Cost compression from standardized LED packages accelerates adoption in mass-market vehicle segments.
- Interior Lamps:Dome and map lighting conversions proceed faster in Japanese and Korean vehicle parc renewal cycles.
- Ambient Lamps:Programmable cabin lighting proliferates in premium electric vehicle platforms.
Front lamps retain volume leadership; ambient lamps hold the steepest expansion curve.
End User:
Procurement concentration among vehicle assemblers creates divergent margin structures based on qualification timelines and volume commitments.
- OEMs:Direct sourcing of premium front-lamp modules concentrates among Chinese domestic brands and joint ventures with dedicated LED supply agreements. MIIT certification requirements compress supplier selection windows for new energy vehicle programs.
- Tier-1 Suppliers:Thermal management and optical design capabilities determine qualification for matrix beam integration. Japanese and Korean tier-1s anchor regional procurement through backward integration into phosphor coating and heat-sink architectures.
- Aftermarket Providers:E-commerce platform penetration fragments traditional distributor networks across Indonesia and Philippines.
- Vehicle Assemblers:Modular procurement strategies reduce qualification burden for commercial vehicle segments in India.
OEMs command the dominant value pool; aftermarket providers are climbing the fastest.
Installation Type:
Factory channels capture technology premiums while aftermarket routes address parc renewal gaps in Southeast Asian markets.
- Factory Installed:Adaptive driving beam calibration and machine vision integration require specialized photonics expertise that concentrates among Japanese engineering centers. Chinese electric vehicle platforms mandate factory installation for warranty and regulatory compliance.
- Aftermarket Installation:Direct-fit specialists capture replacement lamp demand where new-car penetration trails vehicle parc renewal rates. Indonesia's vehicle fleet exhibits substantial halogen-installed base conversion potential.
- Modular Systems:Standardized connector architectures reduce installation complexity for commercial vehicle retrofits.
- Integrated Solutions:Full-lamp assembly replacement dominates premium segment aftermarket channels.
Factory installed channels anchor procurement volume; aftermarket installation gains share fastest.
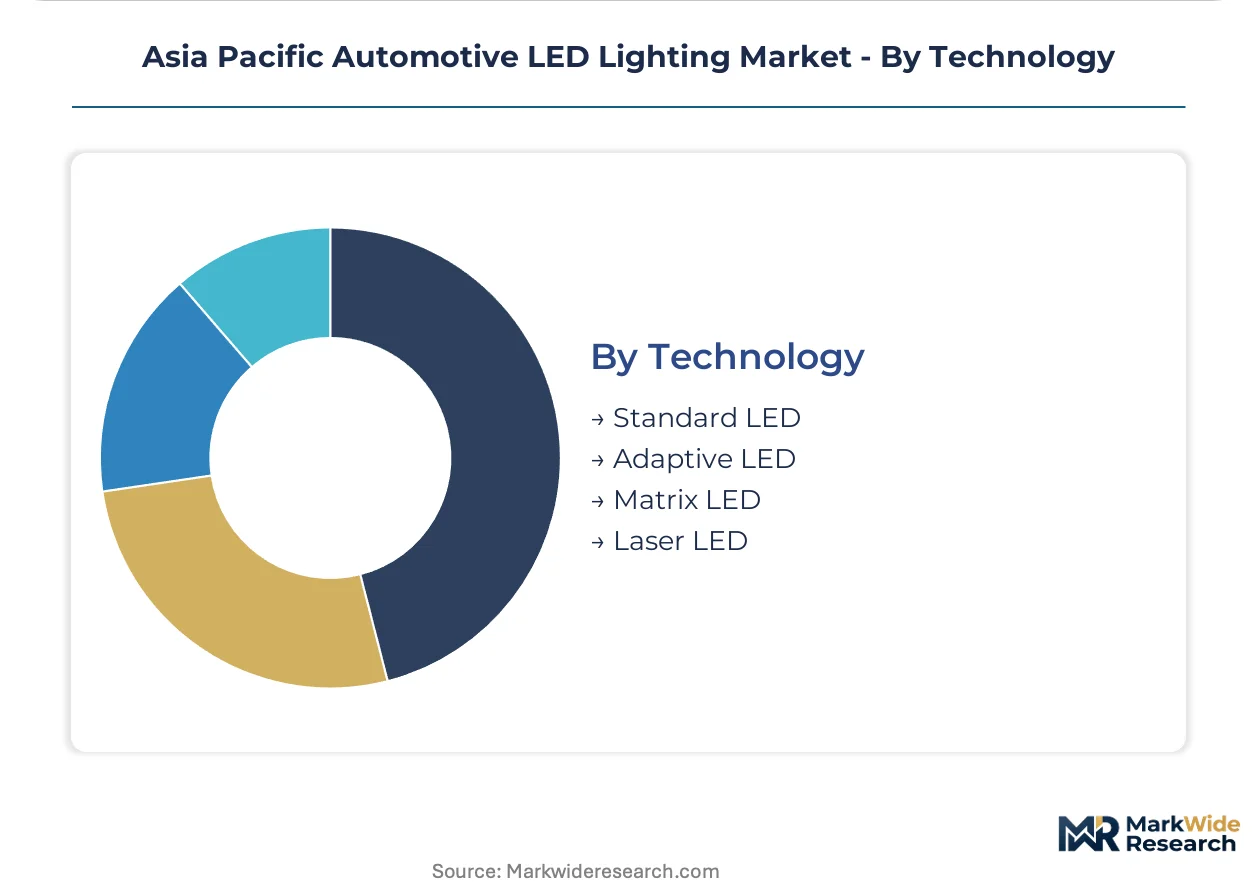
Technology:
Substrate migration from sapphire to silicon carbide is reshaping cost-performance tradeoffs across technical tiers.
- Standard LED:Phosphor-on-chip architectures and GaN-on-silicon epitaxy advances reduce die costs for interior and rear-lamp applications. Volume concentration in Chinese packaging houses enables aggressive pricing for mass-market OEM programs.
- Matrix LED:Micro-LED pixel arrays with 10,000+ individually addressable elements displace mechanical shutter systems in premium Chinese electric vehicles. NIO, BYD, and Xpeng integrate real-time pedestrian highlighting through machine vision coupling.
- Adaptive LED:Dynamic beam shaping responds to oncoming traffic detection in Korean luxury vehicle supply chains.
- Laser LED:Solid-state laser excitation with phosphor conversion extends high-beam range for extended-range lighting functions.
Standard LED retains volume leadership; matrix LED holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes automotive LED lighting through factory-installed premium front-lamp systems for electric vehicles, while India and Southeast Asian markets exhibit heavier aftermarket conversion of existing halogen parc. This consumption-mix differential shapes divergent supplier strategies across the region.
China
Domestic OEMs and joint ventures in Guangdong and Jiangsu provinces anchor procurement volumes for matrix LED headlamp assemblies. MIIT enforces GB standards for photometric performance that eliminate halogen pathways for new energy vehicle type approval. Guangdong production clusters generate scale commitments for adaptive driving beam modules serving BYD, NIO, and Xpeng platforms.
Japan
Japanese OEM programs demand backward integration into optical design and thermal management capabilities from tier-1 suppliers. METI coordinates JIS standards with domestic suppliers to preserve export competitiveness for Korean and Southeast Asian vehicle assembly operations. Kanto and Kansai industrial corridors concentrate engineering expertise for phosphor coating and heat-sink architectures.
India
Commercial vehicle segments in Maharashtra and Tamil Nadu face accelerated BIS compliance deadlines relative to passenger car categories. BIS alignment with UN ECE frameworks compresses halogen-to-LED conversion timelines for tier-2 suppliers serving domestic bus and truck OEMs. Tamil Nadu pre-qualification activity intensifies as enforcement phases approach for energy-efficiency mandates.
South Korea
Korean luxury vehicle supply chains command premium positioning for solid-state lighting architectures with extended-range high-beam functions. MFDS-equivalent automotive safety coordination supports domestic OEM integration of machine vision-coupled adaptive beam systems. Busan-Ulsan manufacturing corridors anchor procurement for laser LED prototyping capacity.
Indonesia
Vehicle parc renewal patterns favor aftermarket channel expansion where new-car penetration trails regional averages. E-commerce platforms and direct-fit specialists capture growing replacement lamp demand from substantial halogen-installed base conversion potential. Jakarta and Surabaya distribution networks fragment traditional distributor networks across the archipelago.
Asia Pacific Automotive LED Lighting Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Asia Pacific automotive LED lighting. Captive gallium nitride substrate production and optical design capabilities separate margin-capturing chip-scale manufacturers from pure-play assemblers. Three archetypes dominate: integrated substrate-to-module producers, tier-1 thermal management specialists, and aftermarket channel consolidators. Competitive moves concentrate on backward integration into phosphor coating and strategic partnerships for matrix beam calibration expertise.
Among Japanese-anchored tier-1 specialists, KOITO MANUFACTURING CO., LTD. and Stanley Electric Co., Ltd. occupy positions defined by thermal management and optical design integration. Nichia Corporation exemplifies the substrate-integrated archetype through captive gallium nitride production. These three entities represent distinct competitive vectors: module assembly leadership, laser LED prototyping capacity, and high-luminance die manufacturing.
| Leading Market Players |
|---|
| Valeo |
| Nichia Corporation |
| KOITO MANUFACTURING CO., LTD. |
| HELLA GmbH and Co. KGaA |
| LG Innotek |
| Stanley Electric Co., Ltd. |
| OSRAM GmbH |
| SL Corporation |
| Marelli Holdings Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Guangdong assembly clusters and gallium nitride substrate producers lock in supply access and price visibility for matrix LED headlamp modules. These arrangements insulate tier-1 suppliers from spot-market volatility in sapphire boule availability while compressing margin capture for pure-play assemblers lacking captive epitaxy capacity.
Pricing Analysis
After-sales service bundling drives lifetime value differentiation across installation channels. Three-tier pricing structure across premium, standard, and economy levels separates matrix beam assemblies with machine vision integration from conventional LED packages and basic interior retrofits. Price differentiation hinges on thermal management certification grade and volume scale commitments from Jiangsu joint ventures. Cost compression in standard LED tiers is intensifying because Chinese packaging houses expand GaN-on-silicon capacity. Fleet operators and commercial vehicle assemblers in India exhibit highest price sensitivity, while Korean luxury OEMs demonstrate lowest sensitivity due to performance-tier procurement mandates.
Supply Chain Analysis
China and Japan anchor substrate-to-module production for automotive LED lighting, with Taiwan supplying precision phosphor coatings. The supply chain draws from high-purity sapphire boules, gallium nitride epitaxy wafers, and specialized aluminum nitride heat-sink substrates. Single-source vulnerability concentrates in sapphire substrate supply among integrated chip-scale manufacturers. Distribution runs through tier-1 module assemblers directly to OEM platform engineering teams, bypassing traditional component distributors for factory-installed channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific automotive LED lighting sits in early-cycle expansion as MIIT GB standards eliminate halogen pathways for new energy vehicle certification across China. This regulatory tailwind accelerates matrix beam penetration beyond luxury segments into mass-market electric vehicle platforms.
For Market Incumbents: Fortify backward integration into phosphor coating and thermal management capabilities ahead of procurement cycle compression. Defend margin position against emerging Chinese packaging houses by securing long-term gallium nitride substrate offtake agreements. Prioritize certification investment for BIS compliance in Indian commercial vehicle segments where enforcement timelines accelerate.
For New Entrants and Emerging Players: Aftermarket channel disintermediation in Indonesia and Philippines presents service-layer gaps where incumbents under-serve halogen parc conversion demand. Target direct-fit specialist partnerships and e-commerce platform integration as the most penetrable route. Pursue modular procurement strategies for commercial vehicle retrofits in Maharashtra and Tamil Nadu.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tier-1 thermal management specialists with captive optical design capabilities. Long-term viability over the projection horizon favors acquisition targets with laser LED prototyping capacity serving Korean luxury supply chains. Watch ASEAN standard harmonization progress as the inflection signal for cross-border component qualification scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Captive gallium nitride supply secures margin capture on high-luminance dies for matrix applications. |
| Matrix Beam Calibration Partnership | Machine vision coupling expertise addresses optical design talent scarcity in Japanese engineering centers. |
| BIS Certification Pre-Qualification | Early compliance positioning captures tier-2 supplier consolidation in Indian commercial vehicle segments. |
| ASEAN Distribution Network Expansion | Direct-fit specialist channels exploit aftermarket fragmentation across Indonesia and Philippines vehicle parc. |
| Laser LED Prototyping Capacity Buildout | Extended-range high-beam functions command premium positioning in Korean luxury OEM supply chains. |
Research Methodology
Operator-level perspectives from OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and phosphor coating specialists anchored the qualitative base. Primary interviews combined with secondary validation from MIIT GB standard filings, BIS regulatory announcements, vehicle production databases, and customs trade records. Bottom-up assembly cost modeling and top-down market sizing triangulated volume estimates across the analysis window.
Sensitivity analysis tested forecast robustness against substrate cost trajectories and regulatory enforcement timing variations. Segmentation dimensions modeled include product type, installation channel, technology tier, vehicle propulsion architecture, and regional production cluster. CAGRs derived from installed base conversion rates and content-per-vehicle expansion for electric vehicle platforms. Forecast inputs incorporated thermal management cost curves and phosphor efficiency improvement trajectories.
Underlying assumptions cover MIIT certification timeline adherence and sapphire substrate supply stability, with deviation risk concentrated in ASEAN harmonization delays and gallium nitride epitaxy yield improvements. Forecasts reflect these conditions with explicit scenario boundaries. Recalibration cycles align with material shifts in dual carbon goal enforcement and BIS compliance phase transitions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
India 3D Printing Construction Market
Others
Bio-Imaging Technologies Market
Others
Cloud-Based Streaming Services Market
Others
Europe Flow Battery Market
Others
Vacuum Evaporators Market
Others
Smart Plug Market
Others
Workstation Desktops Market
Others
Surface Green Mining Market
Others
GCC Shisha Tobacco Market
Others
PCB Laminate Market
Others
Stichtite Market
Others
Mine Rescue Vehicle Market
Others
Automatic Barriers and Bollards Market
Others
Fluid Dispensing Systems Market
Others
Retail Media Platform Market
Others
Binoculars and Mounting Solutions Market