
 Twisted Pair Cable Market | 2026-2036
Twisted Pair Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Twisted Pair Cable Market Intelligence
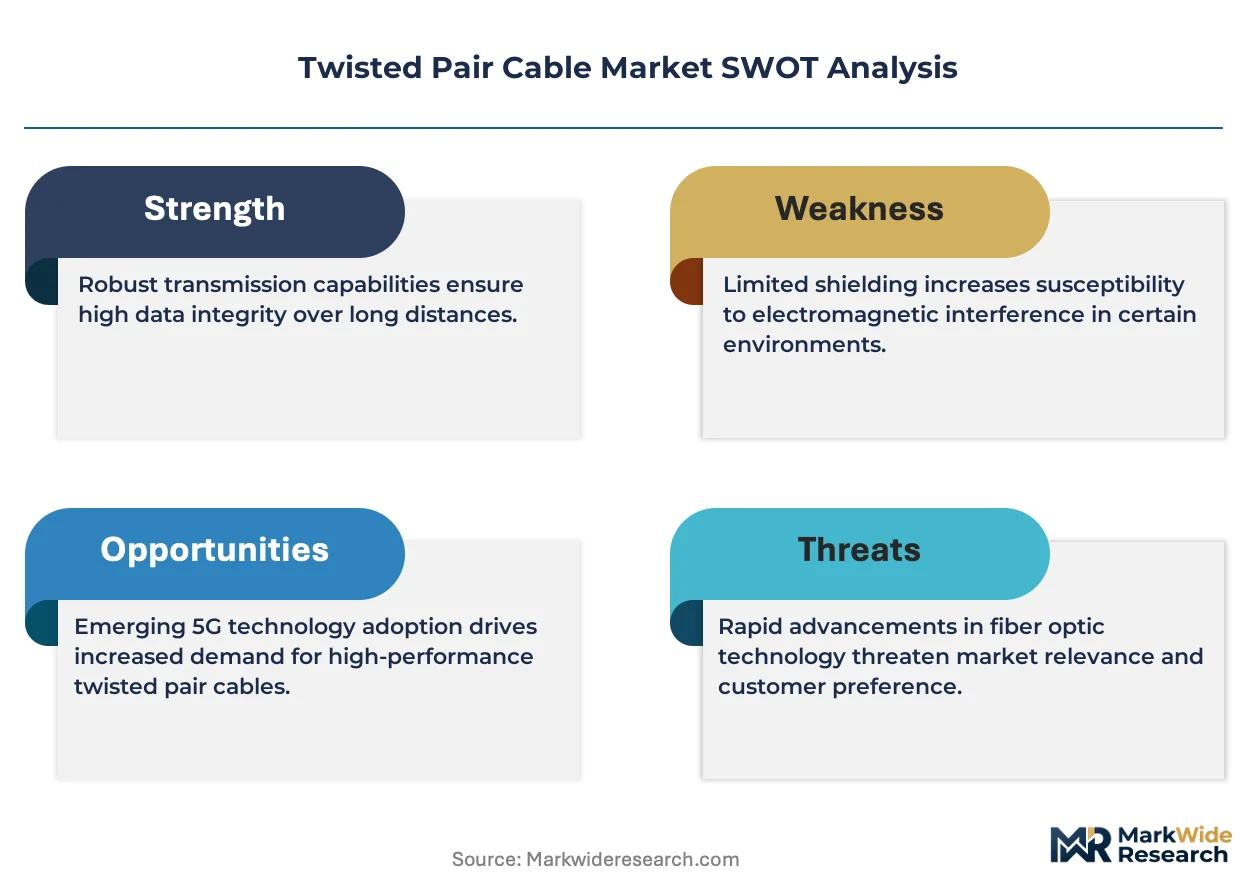
Project finance tied to smart city infrastructure is rewriting competitive entry barriers for mid-scale cable producers. Prysmian Group leverages its vertically integrated polymer compounding operations to control input costs across European and Asian manufacturing nodes. Belden Inc. anchors its position through specialized industrial Ethernet cables that withstand electromagnetic interference in automotive welding environments. Nexans competes by sustaining long-term supply agreements with national telecom carriers requiring Cat6a and Cat7 certification for fiber-to-the-building drop segments.
A twisted pair cable consists of two insulated copper conductors wound helically around each other to cancel electromagnetic interference, with characteristic impedance typically rated at 100 ohms for balanced signal transmission. Manufacturers extrude polyethylene or fluoropolymer dielectrics over solid or stranded copper, then apply shielding layers of aluminum foil or braided tin-plated copper where electromagnetic compatibility demands exceed baseline unshielded designs. Unshielded twisted pair dominates volume in commercial building cabling due to cost efficiency, while shielded and foiled variants capture margin pools in aerospace and manufacturing end user industries where signal integrity failures carry catastrophic liability. Cat6a technology leads data center application growth because its 500 MHz bandwidth supports 10 Gbps runs at full 100-meter channel lengths without active equipment.
The FCC's broadband equity standards in the United States, combined with the EU Green Deal's embodied carbon reporting through CSRD and China's GB standards for communication cable flame retardancy, collectively elevate compliance costs while locking out uncertified imports. ECHA's REACH restrictions on halogenated flame retardants are forcing reformulation of PVC jacket compounds toward low-smoke zero-halogen alternatives that add 8-15% to raw material bills. Stakeholders must monitor how regional certification divergence between TIA/EIA, ISO/IEC, and GB standards fragments procurement specifications and demands parallel qualification investments.
Market Dynamics
Data center operators are forcing a wholesale reconfiguration of copper infrastructure specifications as edge computing workloads migrate processing power toward network peripheries, compressing channel length tolerances and elevating signal integrity requirements beyond legacy Ethernet standards.
Growth Catalysts
- 5G Backhaul Buildout:China's MIIT infrastructure mandates are accelerating fiber-to-the-building deployments that require certified Cat6a and Cat7 drop cables for final subscriber connections.
- REACH Reformulation:ECHA's restrictions on halogenated flame retardants are compelling manufacturers to develop low-smoke zero-halogen jacket compounds that open premium positioning in aerospace and transit applications.
- FCC Broadband Equity:The United States is channeling public capital toward last-mile twisted pair modernization in underserved census tracts, creating sustained procurement volume through 2030.
Market Restraints
- Copper Price Volatility:LME copper futures fluctuation above historical baselines compresses margin predictability for producers lacking in-house polymer compounding capabilities.
- Certification Fragmentation:Parallel qualification requirements across TIA/EIA, ISO/IEC, and GB standards force redundant testing investments that lock out smaller regional manufacturers.
- Fiber Optic Substitution:Single-mode fiber is capturing bandwidth-intensive runs above 10 Gbps in greenfield data centers, constraining copper's addressable market at the performance frontier.
Strategic Opportunities
- Smart Factory Networks:Industrial Ethernet cable demand in automotive welding environments is outpacing supply of electromagnetic interference-resistant shielded variants certified to IEC 61000-4 standards.
- CSRD Carbon Reporting:The EU Green Deal's embodied carbon disclosure requirements are creating first-mover advantage for producers with verified lifecycle assessments and polymer recycling streams.
- Edge Computing Micro-Data Centers:Distributed processing architectures are proliferating 100-meter channel runs in retail and logistics facilities that favor copper economics over fiber transceiver costs.
Industry Challenges
- Compound Formulation Expertise:The transition from PVC to low-smoke zero-halogen jackets demands polymer chemistry capabilities scarce among mid-scale extrusion houses.
- Active Equipment Integration:Channel performance certification now requires coordinated testing with switch and router OEMs, extending qualification timelines and raising technical support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Twisted Pair Cable Market |
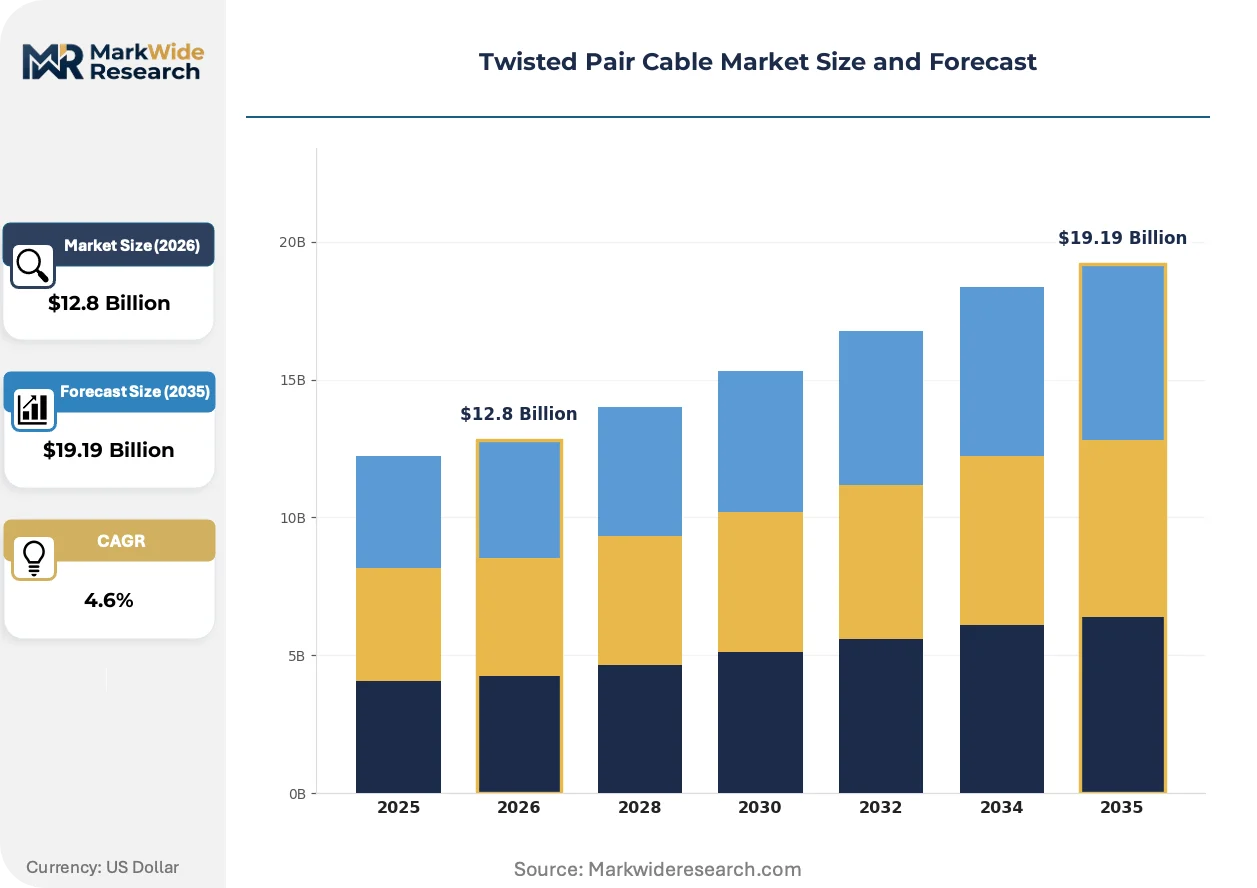
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unshielded Twisted Pair, Shielded Twisted Pair, Foiled Twisted Pair, Screened Twisted Pair Technology: Cat5e, Cat6, Cat6a, Cat7, Cat8 Application: Voice Transmission, Data Communication, Networking, Industrial Automation, Security Systems End User Industry: Telecommunications, Consumer Electronics, Data Centers, Aerospace, Manufacturing |
| Companies Covered | Belden Inc., W.L. Gore & Associates, Prysmian Group, Extron, Hitachi Cable America Inc., Nexans, SAB Bröckskes GmbH & Co. KG, Nikomax, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Twisted Pair Cable Market Strategic Shifts & Innovations
Signal transmission architectures are fragmenting as virtualization layers decouple physical cabling from endpoint functionality, compressing traditional hardware upgrade cycles and elevating software-defined network management platforms.
Alien crosstalk cancellation technology is virtualizing channel performance optimization in high-density data center environments. Hyperscale operators are deploying this approach in new buildouts across Northern Virginia and Frankfurt to maximize copper utilization before fiber migration. The technology is virtualizing hardware refresh decisions by extending Cat6a viability to 25 Gbps signaling through digital signal processing rather than physical cable replacement.
CSRD disclosure mandates are forcing polymer supply chain transparency throughout European manufacturing nodes. Cable producers must now document embodied carbon across polyethylene and fluoropolymer dielectric sourcing or face exclusion from public infrastructure tenders. French and German national carriers are prioritizing suppliers with verified Scope 3 emissions data in long-term supply agreement renewals.
Specification consolidation among hyperscale cloud buyers is compressing vendor diversity in procurement decisions. Amazon Web Services and Microsoft Azure are consolidating twisted pair sourcing to three qualified suppliers per region, displacing fragmented distributor networks. This concentration is most visible in Singapore and Dublin data center clusters where direct manufacturer relationships now dominate channel economics.
Twisted Pair Cable Market Segmentation
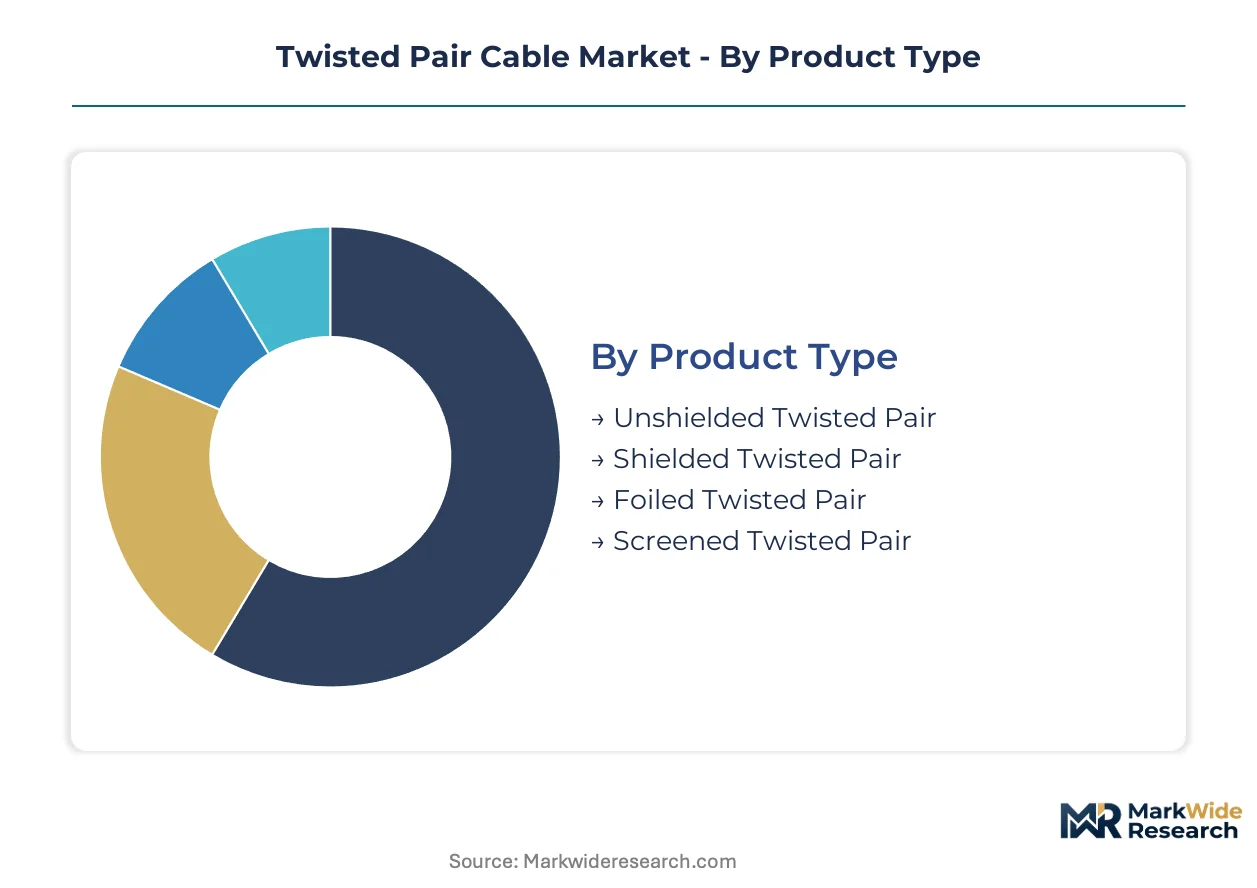
Twisted pair cable procurement decisions hinge on electromagnetic compatibility requirements, bandwidth specifications, and installation environment constraints. Each segmentation dimension carries distinct qualification protocols and margin structures that reshape vendor selection criteria across telecommunications infrastructure buildouts.
Product Type:
Replacement cycles vary sharply across shielding architectures, with unshielded variants turning over fastest in commercial retrofits while shielded designs persist for decades in industrial settings.
- Unshielded Twisted Pair:Polyethylene dielectric insulation wound around solid copper conductors without metallic shielding layers. Data center operators in Northern Virginia and Frankfurt specify this variant for horizontal distribution due to cost efficiency at 100-meter channel lengths. FCC broadband equity programs are channeling procurement volume toward Cat6a-certified unshielded drops in underserved US census tracts.
- Shielded Twisted Pair:Braided tin-plated copper or aluminum foil layers encase conductor pairs to attenuate electromagnetic interference. Automotive welding environments in Stuttgart and Detroit demand shielded variants certified to IEC 61000-4 standards where arc flash interference would corrupt standard Ethernet signaling. REACH reformulation mandates are elevating jacket costs for this premium tier.
- Foiled Twisted Pair:Aluminum foil wrapping provides baseline electromagnetic protection at intermediate price points. Smart factory networks in Shenzhen deploy foiled variants for 5G backhaul connections where moderate interference resistance suffices.
- Screened Twisted Pair:Combination foil and braid configurations address aerospace and transit applications requiring flame retardancy certification under ECHA low-smoke zero-halogen standards. French national rail procurement specifications favor screened architectures for tunnel infrastructure.
Unshielded twisted pair anchors the volume base while shielded twisted pair gains share at the steepest rate.
Technology:
Performance tiers stratify by bandwidth ceiling and channel length tolerance, with mid-range specifications capturing the bulk of current infrastructure investment while cutting-edge categories serve latency-sensitive edge computing workloads.
- Cat5e:100 MHz bandwidth rating supporting 1 Gbps transmission over 100 meters. Voice transmission and legacy building automation systems in aging European commercial real estate continue specifying Cat5e for cost-constrained refresh cycles.
- Cat6:250 MHz bandwidth with tighter twist ratios reducing crosstalk. German industrial Ethernet deployments specify Cat6 for machine-to-machine communication networks in automotive assembly plants.
- Cat6a:Augmented 500 MHz specification enabling 10 Gbps at full channel length without alien crosstalk degradation. Hyperscale operators in Singapore and Dublin are consolidating procurement around Cat6a for edge computing micro-data centers where fiber transceiver economics prove prohibitive. Alien crosstalk cancellation technology is extending Cat6a viability toward 25 Gbps signaling.
- Cat7:600 MHz bandwidth with individual pair shielding and mandatory grounding. China's MIIT infrastructure mandates are accelerating Cat7 deployment for fiber-to-the-building drop segments in 5G backhaul buildouts.
- Cat8:2000 MHz bandwidth supporting 25-40 Gbps over truncated 30-meter channels. Banking and high-frequency trading facilities in London and New York specify Cat8 for server-to-switch connections where copper latency advantages outweigh fiber alternatives.
Cat6a dominates current procurement volumes while Cat8 climbs the fastest among specifications gaining traction in latency-sensitive financial infrastructure.
Application:
Signal integrity requirements diverge sharply across use cases, with industrial environments demanding the most rigorous electromagnetic compatibility while voice transmission tolerates legacy specifications.
- Voice Transmission:Plain old telephone service and VoIP infrastructure requiring minimal bandwidth. Rural broadband modernization programs in the United States specify twisted pair for last-mile voice and data convergence.
- Data Communication:Enterprise local area networks and storage area networking. German manufacturing facilities are upgrading data communication backbones to support real-time production analytics.
- Networking:Internet protocol traffic routing and switching infrastructure. Edge computing architectures in retail and logistics facilities favor copper networking economics for distributed 100-meter channel runs.
- Industrial Automation:Programmable logic controller communication and sensor networks. Automotive welding environments specify electromagnetic interference-resistant shielded variants where signal corruption would halt production lines. CSRD carbon reporting requirements are penetrating automation procurement specifications in France and Germany.
- Security Systems:Closed-circuit television and access control signaling. Smart city infrastructure projects in China are integrating security system cabling with 5G backhaul deployments.
Networking commands the largest installed base while industrial automation expands most quickly amid factory digitization mandates.
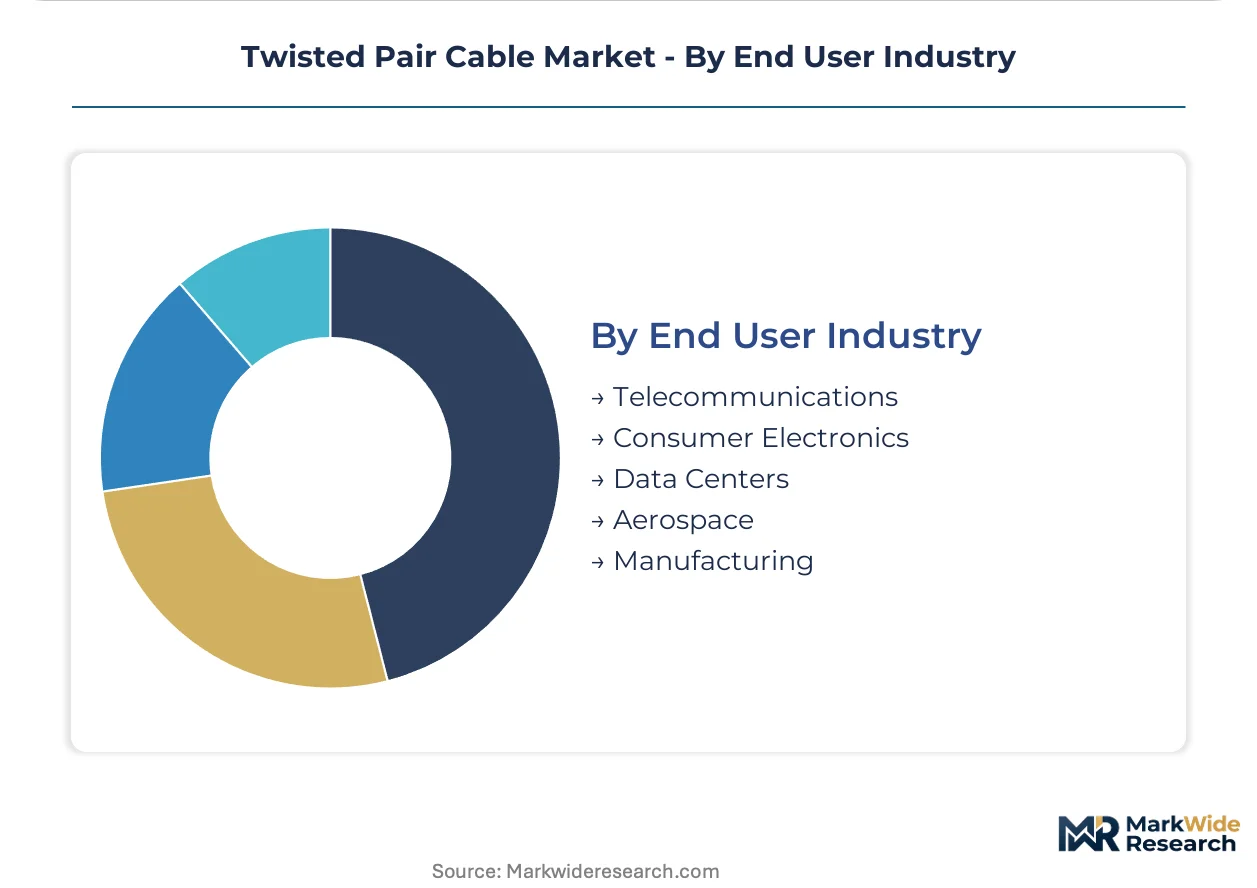
End User Industry:
Customer concentration and contract duration vary by sector, with data centers driving shortest procurement cycles through rapid technology refresh while aerospace programs lock in decade-long supply agreements.
- Telecommunications:National carriers and regional operators requiring certified drop cables for subscriber connections. China's domestic producers are expanding capacity to serve MIIT-mandated 5G infrastructure buildouts.
- Consumer Electronics:Residential networking equipment and patch cord assemblies. E-commerce distribution channels are compressing margins for standardized consumer-grade products.
- Data Centers:Hyperscale cloud operators and colocation facilities. Amazon Web Services and Microsoft Azure are consolidating twisted pair sourcing to three qualified suppliers per region, displacing fragmented distributor networks in Singapore and Dublin clusters.
- Aerospace:Aircraft avionics and in-flight entertainment systems. Low-smoke zero-halogen jacket requirements under ECHA REACH restrictions are reformulating material specifications for this liability-sensitive sector.
- Manufacturing:Factory automation and process control networks. Industrial Ethernet demand in automotive welding environments is outpacing supply of electromagnetic interference-resistant shielded variants.
Telecommunications retains the deepest installed base while data centers drive the steepest specification upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in copper-based connectivity infrastructure tilt toward net-import positions in Western markets while Asian manufacturing hubs maintain export surpluses. Currency volatility and freight cost fluctuations are reshaping regional sourcing strategies for data center and telecommunications infrastructure.
United States
FCC broadband equity programs are channeling public capital toward last-mile twisted pair modernization in underserved census tracts. The Infrastructure Investment and Jobs Act sustains procurement volume through 2030. Northern Virginia data center clusters drive Cat6a specification upgrades for edge computing workloads.
Germany
Industrial Ethernet demand in Stuttgart automotive welding environments outpaces supply of electromagnetic interference-resistant shielded variants. ECHA REACH restrictions on halogenated flame retardants force PVC-to-LSZH jacket reformulation. CSRD embodied carbon disclosure requirements penetrate procurement specifications for factory automation networks.
China
MIIT infrastructure mandates accelerate fiber-to-the-building deployments requiring certified Cat6a and Cat7 drop cables for 5G backhaul. Domestic cable producers expand capacity for smart factory networks. Shenzhen manufacturing clusters deploy foiled variants for moderate interference resistance in 5G infrastructure.
France
National rail procurement specifications favor screened twisted pair architectures for tunnel infrastructure under ECHA low-smoke zero-halogen standards. French national carriers prioritize suppliers with verified Scope 3 emissions data in long-term supply agreement renewals. Paris-region data centers consolidate vendor relationships amid hyperscale buyer concentration.
Japan
METI industrial digitization policies elevate factory automation cable specifications for machine-to-machine communication networks. Automotive assembly plants in Nagoya specify Cat6 for real-time production analytics. JIS standards alignment with IEC frameworks reduces redundant qualification burdens for export-oriented manufacturers.
Twisted Pair Cable Market Key Industry Players
On the supply side, the industry is consolidating around vertically integrated polymer compounders and specialized electromagnetic compatibility producers. Tiered competitive positioning separates volume-scale extrusion houses from premium-tier certification specialists. Three archetypes dominate: integrated material-science conglomerates, industrial-application specialists, and telecommunications-focused certification leaders. M&A activity concentrates polymer compounding capabilities, while strategic partnerships with switch and router OEMs extend channel performance qualification timelines.
Among European integrated producers, Prysmian Group and Nexans occupy positions anchored by long-term supply agreements with national telecom carriers. Belden Inc. exemplifies the industrial-specialist archetype through electromagnetic interference-resistant product positioning. These three names represent the consolidation trajectory visible in hyperscale cloud buyer vendor reduction strategies across Singapore and Dublin data center clusters.
| Leading Market Players |
|---|
| Belden Inc. |
| W.L. Gore & Associates |
| Prysmian Group |
| Extron |
| Hitachi Cable America Inc. |
| Nexans |
| SAB Bröckskes GmbH & Co. KG |
| Nikomax |
| TE Connectivity |
| Others |
Cost & Logistics Intelligence
Copper price volatility at the London Metal Exchange compresses margin predictability for extrusion houses lacking captive polymer compounding, forcing a three-tier pricing structure across premium, standard, and economy levels while concentrating supply chain control among vertically integrated European and Asian producers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across premium, standard, and economy tiers based on certification grade and volume scale. Cat6a and Cat7 certified cables command premiums due to TIA/EIA qualification costs, while unshielded Cat5e volumes face price erosion from distributor network compression. Hyperscale data center buyers exhibit lowest price sensitivity, prioritizing channel performance guarantees over unit economics.
Supply Chain Analysis
Polyethylene and fluoropolymer dielectric feedstocks flow from petrochemical complexes in China, South Korea, and Germany, with copper cathode sourcing tethered to Chilean and Peruvian mining output. REACH restrictions on halogenated flame retardants create regulatory chokepoints for PVC jacket formulations. Distribution runs through direct manufacturer relationships with hyperscale operators, displacing fragmented distributor networks in Singapore and Dublin clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around ECHA REACH and FCC broadband equity standards creates durable defensive moats for certified producers, as switching costs lock national carriers and hyperscale operators into long-term supply relationships.
For Market Incumbents: Entrench certification leadership by deepening backward integration into low-smoke zero-halogen polymer compounding, securing margin control against copper volatility. Expand capacity in Shenzhen and Northern Virginia to capture edge computing procurement concentration. Lock in decade-long supply agreements with French national rail and German automotive OEMs before REACH reformulation costs fully propagate. For New Entrants and Emerging Players: Establish a beachhead in industrial automation shielded variants, where electromagnetic interference-resistant cable supply trails demand in Stuttgart and Detroit welding environments. Target CSRD-compliant product positioning for EU factory automation networks, leveraging polymer recycling streams as a greenfield qualification pathway. Pursue direct OEM relationships with automotive Tier 1 suppliers rather than distributor channel penetration. For Investors and Strategic Acquirers: Mid-scale extrusion houses with demonstrated LSZH formulation capabilities represent the most defensible acquisition profile, as compound chemistry expertise scarcity widens competitive moats. Long-term viability hinges on 5G backhaul and smart factory network capex cycles. Watch for alien crosstalk cancellation technology maturation as a signal for Cat6a demand extension versus accelerated fiber substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Prysmian Group controls input costs across European and Asian manufacturing nodes through captive LSZH formulation. |
| Long-term Supply Agreement with National Carriers | Nexans sustains procurement volume through Cat6a and Cat7 certification for fiber-to-the-building drops per China MIIT mandates. |
| CSRD Carbon Reporting Verification | French and German carriers prioritize suppliers with verified Scope 3 emissions data in contract renewals. |
| Alien Crosstalk Cancellation Technology Deployment | Hyperscale operators in Northern Virginia extend Cat6a viability to 25 Gbps signaling without cable replacement. |
| Direct Manufacturer Relationship with Hyperscalers | Amazon Web Services and Microsoft Azure consolidate sourcing to three qualified suppliers per region, displacing distributors. |
Research Approach
The analysis maps unshielded, shielded, foiled, and screened architectures, each validated through procurement directors at hyperscale data center operators, plant engineers at automotive welding facilities, and regulatory affairs leads at cable manufacturers. Primary interviews with national carrier supply chain managers and polymer compounding technical directors combined with secondary validation from FCC broadband equity filings, ECHA REACH restriction updates, and MIIT infrastructure mandate disclosures. Bottom-up channel length and bandwidth specification modeling triangulates against top-down capex flow analysis from hyperscaler disclosures.
Fixed assumptions across the modeling period include sustained copper price volatility above historical baselines, continued REACH reformulation compliance deadlines, and FCC broadband equity program funding continuity. Segmentation dimensions span shielding architecture, performance tier from Cat5e through Cat8, end-use application, and regional regulatory cluster. CAGRs derive from installed base turnover rates and specification upgrade trajectories, with edge computing micro-data center proliferation and 5G backhaul buildout intensity as key demand-side inputs.
Sensitivities concentrate around fiber optic substitution acceleration, regional certification divergence between TIA/EIA and GB standards, and ECHA expansion of halogenated flame retardant restrictions. Forecasts reflect these assumptions with acknowledged revision triggers from macroeconomic copper demand shifts or hyperscale procurement consolidation beyond three suppliers per region. Cross-checking against hyperscaler direct disclosure of qualified vendor counts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
North America Wire and Cable Market
Cables
Type TC and Type TC-ER Cable (600 V) Market
Cables
North America Copper Wire and Cable Market
Cables
XLPE Cables Market
Cables
Military Cable Market
Cables
Magnetic Charging Cable Market
Cables
Radio Frequency Cables Market
Cables
Cable Flange Market
Cables
LED Cable Market
Cables
Multicore Cables Market
Cables
Sensor Cable Market
Cables
North America HVAC Cables Market
Cables
Japan Cables Market
Cables
Shipboard Cable Market
Cables
Insulated Wire and Cable Market
Cables
US Cables Market