
 Tape on Reel Feeder Market | 2026-2036
Tape on Reel Feeder Market Size, Share, and Industry Trends Forecast 2026-2036
Tape on Reel Feeder Market Analytics
Polymer composite tape guides are consolidating around ceramic-reinforced formulations that cut wear rates and extend service intervals. DEPRAG leverages its German engineering base to dominate precision pneumatic subsystems for European automotive lines. JUKI anchors high-volume electronics assembly with electric feeder architectures optimized for micro-component placement. CNSMT competes aggressively on cost-adjusted delivery cycles across Chinese contract manufacturing networks.
Tape on reel feeder equipment mechanically advances carrier tape through sprocket or pin-indexed drive mechanisms, presenting surface-mount components to pick-and-place heads at feed pitches typically ranging from 2 mm to 104 mm with positional accuracy below ±0.05 mm. Automatic feeders command the largest installed base owing to throughput requirements in smartphone and automotive electronics lines, while hybrid pneumatic-electric units represent the fastest-expanding technology segment as manufacturers balance speed against energy efficiency. Contract manufacturers occupy a disproportionate share of procurement volume due to their equipment refresh cadence and multi-client line configurations.
FCC equipment authorization rules constrain electromagnetic emissions from electric feeder motors deployed in US electronics facilities, while CE marking under the EU Machinery Directive mandates interlock guarding and emergency-stop integration for European installations. China's GB standards for industrial automation equipment, administered by SAMR, establish mechanical safety and reliability benchmarks that shape supplier qualification protocols. Stakeholders must monitor how dual carbon goals in Beijing and Brussels recast energy-efficiency specifications for factory automation subsystems.
Market Dynamics
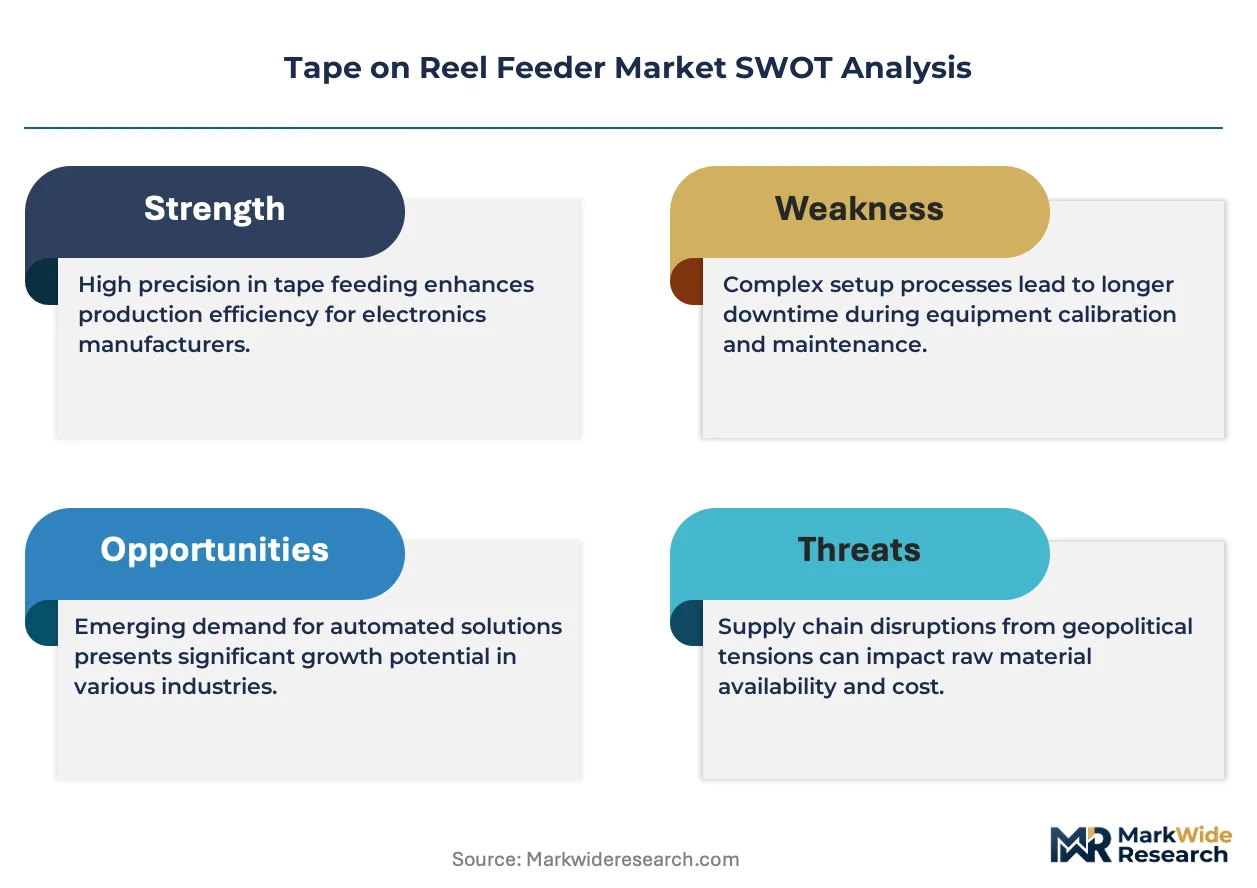
Electric actuator architectures are displacing pneumatic drive systems across East Asian electronics assembly lines, forcing feeder suppliers to retool motor subsystems and recalibrate positional accuracy specifications for micro-component placement.
Growth Catalysts
- ISO 14644 Cleanroom Mandates:Semiconductor OEMs in Taiwan and South Korea require certified feeder equipment for advanced packaging lines, accelerating replacement cycles.
- Electric Vehicle Electronics:Automotive tier-one suppliers in Germany and Japan are scaling automated feeder deployment for power module assembly.
- GB Standards Modernization:SAMR-administered mechanical safety benchmarks in China are disqualifying legacy pneumatic units from state-backed contract manufacturing tenders.
Market Restraints
- Neodymium Magnet Cost Volatility:Electric feeder motors depend on rare-earth supply chains concentrated in Chinese processing facilities.
- FCC Authorization Complexity:Electromagnetic emission testing for servo motors adds 8-12 weeks to US market entry timelines.
- Pneumatic Infrastructure Lock-in:Existing factory air compressor networks in Southeast Asian contract manufacturing clusters delay electric conversion ROI calculations.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging are creating first-mover advantages for feeder vendors qualifying under BIS automation standards.
- AI-Assisted Calibration:Machine vision integration with electric feeders enables real-time pitch correction without mechanical adjustment.
- EU Green Deal Alignment:Energy-efficiency specifications under the EU Machinery Directive favor electric architectures in European automotive electronics procurement.
Industry Challenges
- Mechatronics Talent Scarcity:Servo motor programming and precision mechanical integration skills are concentrated in Japanese and German engineering labor pools.
- Dual Certification Burden:Simultaneous CE marking and FCC authorization requirements force parallel testing workflows for multinational electronics OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tape on Reel Feeder Market |
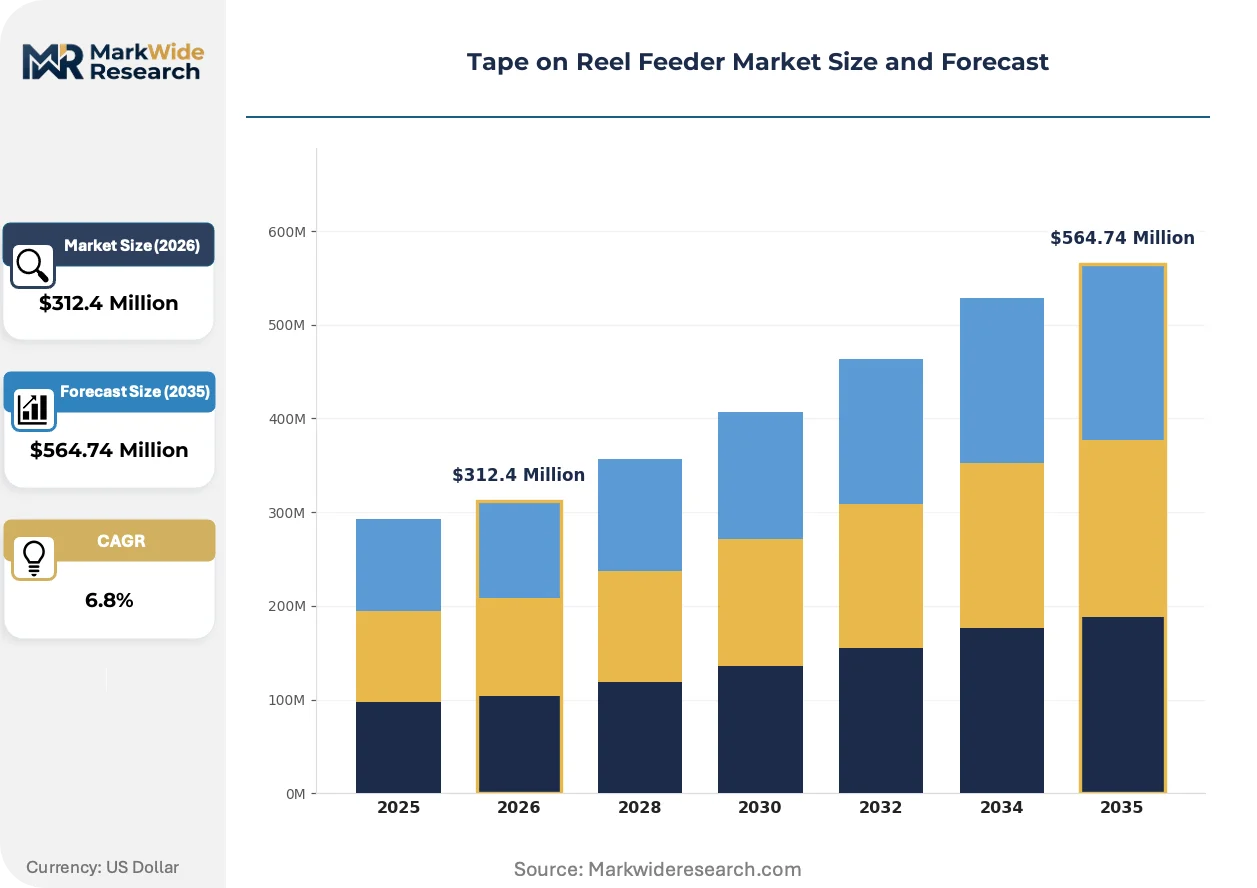
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Feeders, Automatic Feeders, Semi-Automatic Feeders, Custom Feeders Application: Electronics Assembly, Pharmaceutical Packaging, Automotive Manufacturing, Consumer Goods End User: OEMs, Tier-1 Suppliers, Contract Manufacturers, Research Institutions Technology: Pneumatic, Electric, Mechanical, Hybrid |
| Companies Covered | DEPRAG, JUKI, Capling, CNSMT, V-TEK International, NU-WAY Electronics, ESE, WIKIWAND, SMTnet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tape on Reel Feeder Market Evolving Landscape
Feeder technology is bifurcating between ultra-precision electric architectures for advanced packaging and cost-optimized hybrid systems for high-volume consumer electronics, with regulatory energy standards accelerating this segmentation.
Ceramic-reinforced polymer composite tape guides are expanding into high-wear applications previously dominated by hardened steel components. Smartphone assembly lines in South Korea and Vietnam are adopting these guides at the fastest clip. This material transition is expanding into feeder architectures that previously required quarterly guide replacement, compressing maintenance intervals to annual cycles.
China's GB standards for industrial automation equipment, administered by SAMR, now mandate mechanical safety interlocks and documented reliability testing for factory automation subsystems. European feeder suppliers must redesign guarding systems to access Chinese contract manufacturing networks. Japanese and German OEMs are responding by pre-certifying electric feeder platforms to both GB and CE specifications.
Contract manufacturers are consolidating procurement authority around equipment-as-a-service models that unbundle feeder hardware from maintenance and calibration obligations. This purchasing pattern is displacing traditional capital expenditure cycles in Taiwanese and Chinese electronics assembly networks. South Korean semiconductor packaging houses remain the exception, retaining in-house technical teams and direct equipment ownership.
Tape on Reel Feeder Market Segmentation
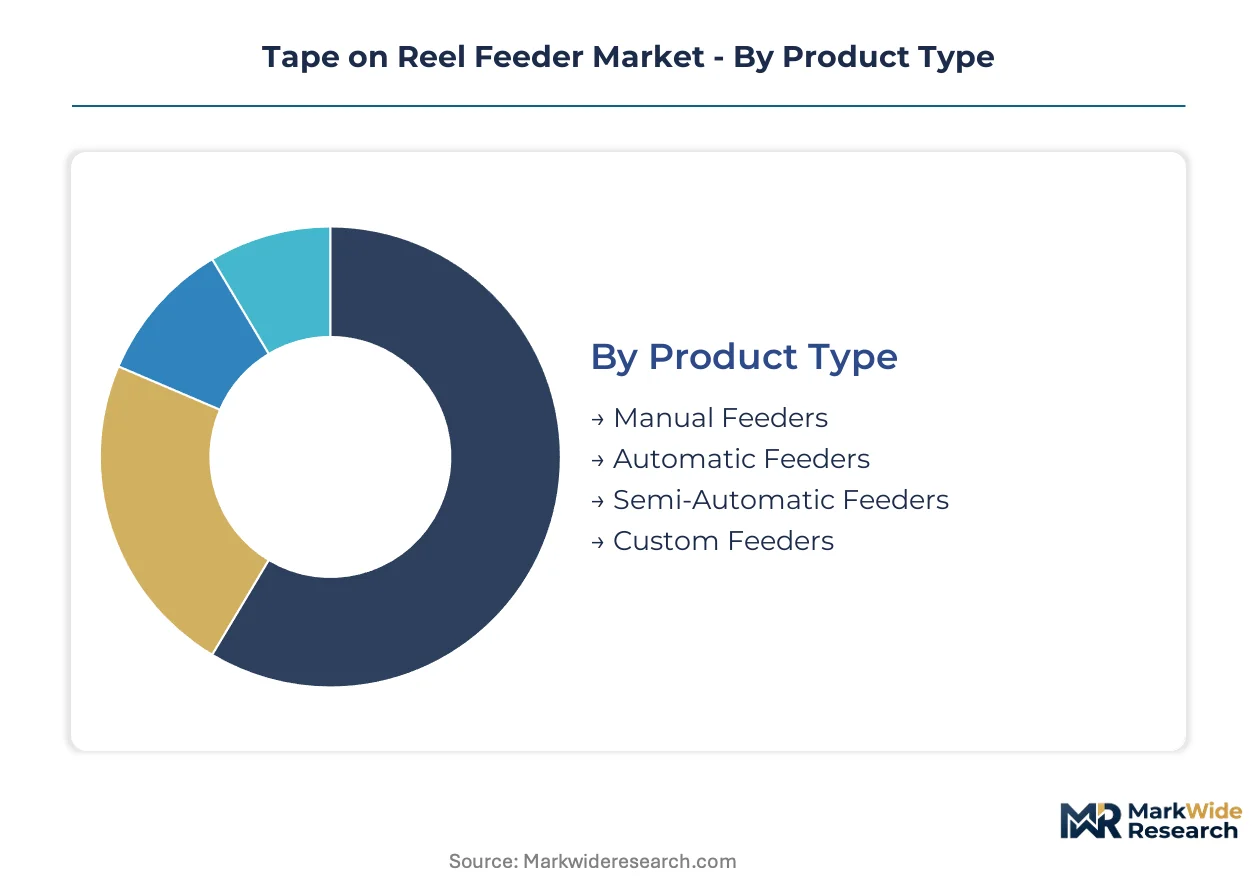
Equipment certification requirements fragment procurement patterns across the tape on reel feeder market, with ISO 14644 cleanroom mandates and regional safety standards governing which architectures qualify for specific production environments. Segmentation reveals how regulatory alignment shapes supplier qualification protocols and customer technology roadmaps.
Product Type:
CE marking under the EU Machinery Directive and FCC equipment authorization rules in the US create divergent compliance burdens across feeder architectures, with electric and automatic variants facing the most stringent electromagnetic and interlock testing protocols.
- Automatic Feeders:Sprocket or pin-indexed drive mechanisms advance carrier tape at feed pitches from 2 mm to 104 mm with positional accuracy below ±0.05 mm. Smartphone assembly lines in South Korea and Vietnam deploy these units at the highest density, driven by throughput requirements and ISO 14644 certification for advanced packaging operations.
- Manual Feeders:Operator-actuated tape advancement systems serve prototyping and low-volume production where changeover flexibility outweighs speed requirements. Research institutions in Germany and Japan maintain installed bases for pilot production of automotive power modules, though procurement volumes remain constrained by labor cost structures.
- Semi-Automatic Feeders:Hybrid actuation combining manual loading with motorized advancement addresses mid-volume contract manufacturing in Southeast Asian clusters.
- Custom Feeders:Application-specific architectures for non-standard tape widths or component geometries serve pharmaceutical packaging lines requiring validated changeover protocols.
Leading the category by volume: Automatic Feeders. Growing fastest: Custom Feeders.
Application:
End-use concentration determines which regional certification regimes dominate procurement specifications, with automotive and pharmaceutical applications facing the most layered approval requirements.
- Electronics Assembly:Surface-mount component placement for smartphones, servers, and automotive electronics commands the largest equipment installed base. Taiwan and South Korean semiconductor OEMs are expanding automated feeder deployment as electric actuator technology displaces legacy pneumatic systems in cleanroom environments.
- Automotive Manufacturing:Power module assembly for electric vehicles requires feeders qualified to IATF 16949 quality management standards alongside regional safety markings. Tier-one suppliers in Germany and Japan are scaling deployment for silicon carbide and gallium nitride packaging.
- Pharmaceutical Packaging:Validated feeder systems for drug delivery device assembly must satisfy FDA 21 CFR Part 11 electronic records requirements in the US and EMA GMP Annex 15 qualifications in Europe.
- Consumer Goods:Cost-optimized feeder architectures serve high-volume disposable electronics and appliance manufacturing in Chinese contract manufacturing networks.
Dominating procurement volume: Electronics Assembly. Steepest expansion trajectory: Automotive Manufacturing.
End User:
Equipment-as-a-service purchasing patterns concentrate differently across customer types, with contract manufacturers most receptive to unbundled maintenance and calibration obligations.
- Contract Manufacturers:Multi-client line configurations and accelerated refresh cadences drive disproportionate procurement volume. Taiwanese and Chinese electronics assembly networks are consolidating authority around service-based models that displace traditional capital expenditure cycles.
- OEMs:In-house technical teams and direct equipment ownership characterize semiconductor packaging houses in South Korea, where proprietary process knowledge supports captive maintenance capabilities.
- Tier-1 Suppliers:Automotive electronics specialists in Germany and Japan specify feeders integrated with broader assembly line automation platforms.
- Research Institutions:Pilot production and process development requirements favor flexible, reconfigurable feeder architectures with minimal validation overhead.
Capturing largest share: Contract Manufacturers. Expanding most quickly: Tier-1 Suppliers.
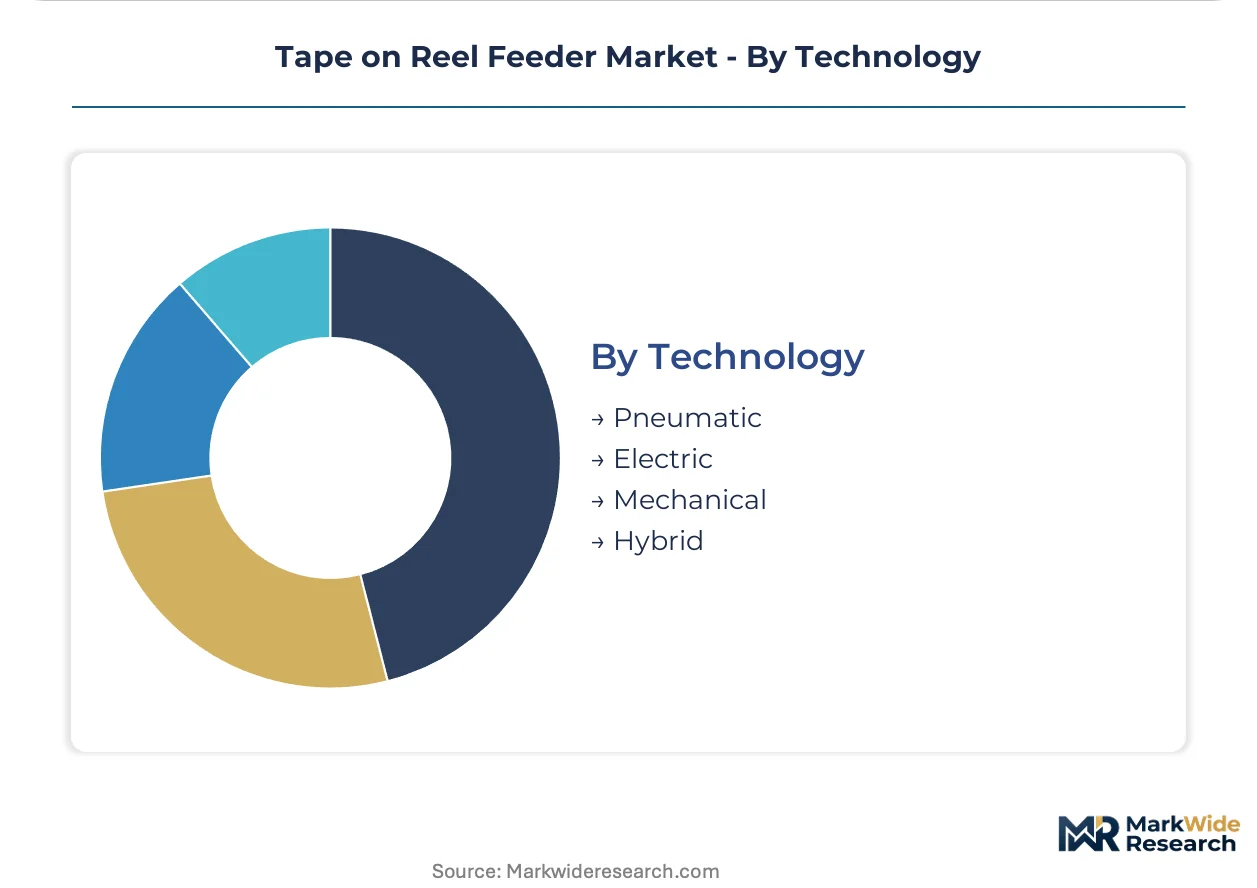
Technology:
Energy-efficiency specifications under the EU Machinery Directive and China's dual carbon goals are recasting technology selection criteria, accelerating displacement of pneumatic architectures.
- Electric:Servo motor drive systems with real-time position feedback enable micro-component placement at the tightest tolerances. GB standards administered by SAMR are disqualifying legacy pneumatic units from state-backed tenders, while neodymium magnet cost volatility constrains motor subsystem economics.
- Hybrid:Combined pneumatic-electric architectures balance speed against energy efficiency, representing the fastest-expanding technology segment as manufacturers navigate infrastructure transition timelines.
- Pneumatic:Compressed air drive systems retain installed base in Southeast Asian contract manufacturing clusters where existing compressor networks delay electric conversion ROI calculations.
- Mechanical:Cam and linkage mechanisms serve specialized applications requiring deterministic motion profiles without electronic control complexity.
Highest installed base: Electric. Gaining share fastest: Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian electronics manufacturing clusters absorb the majority of tape on reel feeder procurement, with Taiwan and South Korean semiconductor OEMs driving equipment refresh cycles as electric actuator architectures displace legacy pneumatic systems.
Taiwan
Semiconductor packaging houses in Hsinchu Science Park and Tainan Technology Industrial Park are expanding automated feeder deployment for advanced flip-chip and fan-out wafer-level packaging. ISO 14644 cleanroom certification requirements are accelerating replacement cycles among foundry operators. Kaohsiung-based contract manufacturers are consolidating procurement authority around equipment-as-a-service models that unbundle hardware from maintenance obligations.
South Korea
Seoul Capital Area semiconductor OEMs retain in-house technical teams and direct equipment ownership, contrasting with Taiwanese outsourcing patterns. Samsung and SK Hynix packaging subsidiaries specify electric feeder architectures with positional accuracy below ±0.05 mm for micro-component placement. Busan-Ulsan electronics clusters are adopting ceramic-reinforced polymer composite tape guides to extend service intervals in high-throughput smartphone assembly lines.
China
SAMR-administered GB standards for industrial automation equipment are disqualifying legacy pneumatic units from state-backed contract manufacturing tenders. Yangtze River Delta electronics assemblers in Suzhou and Kunshan are navigating dual carbon goals that recast energy-efficiency specifications for factory automation subsystems. Pearl River Delta clusters in Shenzhen and Dongguan prioritize cost-adjusted delivery cycles in procurement decisions.
Germany
CE marking under the EU Machinery Directive mandates interlock guarding and emergency-stop integration for automotive electronics lines in Bavaria and Baden-Württemberg. Tier-one suppliers in Stuttgart and Ingolstadt are scaling automated feeder deployment for silicon carbide power module assembly. DEPRAG leverages its German engineering base to dominate precision pneumatic subsystems for European automotive lines.
United States
FCC equipment authorization rules constrain electromagnetic emissions from electric feeder motors deployed in Austin and Phoenix electronics facilities. Electromagnetic emission testing for servo motors adds 8-12 weeks to market entry timelines for multinational OEMs. Southeast Asian contract manufacturing clusters delay electric conversion ROI calculations due to existing pneumatic infrastructure lock-in.
Tape on Reel Feeder Market Competitive Landscape
Technology licensing dominates the current landscape as feeder suppliers retool motor subsystems to meet regional energy-efficiency mandates. The vendor base stratifies between precision-engineering specialists with captive German or Japanese engineering labor pools and cost-optimized fabricators serving Chinese contract manufacturing networks. Three archetypes occupy distinct positions: electric architecture pioneers, hybrid system integrators, and pneumatic legacy defenders. M&A activity concentrates on acquiring servo motor programming capabilities, while strategic partnerships with machine vision providers enable real-time pitch correction features.
Within the precision-engineering tier, DEPRAG and JUKI exemplify divergent geographic specializations. DEPRAG anchors European automotive electronics procurement through German-engineered pneumatic subsystems. JUKI occupies a position in high-volume East Asian electronics assembly with electric feeder architectures. CNSMT represents the cost-optimized Chinese fabricator archetype, competing on delivery cycle efficiency across contract manufacturing networks in the Pearl and Yangtze River Delta regions.
| Leading Market Players |
|---|
| DEPRAG |
| JUKI |
| Capling |
| CNSMT |
| V-TEK International |
| NU-WAY Electronics |
| ESE |
| WIKIWAND |
| SMTnet |
| Others |
Value Network & Pricing Analysis
Captive in-house production of servo motor subsystems anchors pricing power for Japanese and German precision-engineering specialists, while outsourced fabrication across Chinese contract manufacturing networks compresses margins through accelerated delivery cycles and volume-scaled procurement.
Pricing Analysis
High-volume contract manufacturers in Taiwan and China command standard-tier pricing through consolidated procurement authority, while semiconductor OEMs in South Korea absorb premium tiers for electric architectures with sub-0.05 mm positional accuracy. Price differentiation hinges on ISO 14644 cleanroom certification grade and after-sales calibration bundling. Cost compression in standard-tier pneumatic units is intensifying because SAMR-administered GB standards are disqualifying legacy architectures from state-backed tenders. Contract manufacturers exhibit the highest price sensitivity due to equipment-as-a-service purchasing patterns, whereas South Korean semiconductor houses prioritize performance specifications over unit economics.
Supply Chain Analysis
Freight costs for neodymium magnet shipments from Chinese processing facilities to Japanese motor assembly plants are amplifying working capital requirements across electric feeder supply chains. Component sourcing draws from Taiwan for precision bearings, Germany for engineered pneumatics, and China for polymer composite tape guides. Rare-earth supply concentration in Chinese refining operations creates single-source vulnerability for servo motor subsystems. Distribution runs through direct OEM relationships for South Korean semiconductor packaging houses and bundled service contracts for Taiwanese contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tape on reel feeder market sits in a technology-transition phase as electric actuator architectures displace legacy pneumatic drive systems across East Asian electronics assembly lines.
For Market Incumbents: To counter neodymium magnet cost volatility, secure captive supply agreements with Chinese rare-earth processors or accelerate ferrite-alternative R&D programs. Pre-certify electric feeder platforms to both GB and CE specifications to capture cross-regional procurement from multinational electronics OEMs facing dual certification burdens. For New Entrants and Emerging Players: Direct-to-contract-manufacturer digital sales channels enable rapid qualification under equipment-as-a-service models displacing traditional capital expenditure cycles in Taiwanese electronics assembly networks. Target mid-volume hybrid pneumatic-electric architectures for Southeast Asian clusters navigating infrastructure transition timelines. Lead with AI-assisted pitch correction features integrated with machine vision providers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by precision-engineering conglomerates seeking servo motor programming capabilities. Long-term viability favors vendors with demonstrated compliance across ISO 14644, CE marking, and GB standards. Monitor SAMR enforcement patterns against legacy pneumatic units as inflection indicator for electric architecture penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Servo Motor Subsystem Acquisition | Captures scarce mechatronics talent concentrated in Japanese and German engineering labor pools. |
| Machine Vision Partnership | Enables real-time pitch correction features for micro-component placement accuracy. |
| Dual Certification Pre-qualification | Accelerates market entry for multinational OEMs facing parallel CE and GB testing workflows. |
| Ceramic-Reinforced Guide Production | Extends service intervals from quarterly to annual cycles in high-throughput smartphone lines. |
| Equipment-as-a-Service Launch | Aligns procurement patterns with Taiwanese and Chinese contract manufacturer purchasing consolidation. |
Research Methodology
Multi-period observation of electric actuator deployment rates and pneumatic infrastructure retirement patterns anchored the trend analysis, supplemented by interviews with SMT equipment procurement managers, semiconductor packaging engineers, factory automation integrators, and aftermarket service heads. Secondary validation drew from SEC filings of listed electronics manufacturing services providers, SAMR GB standards documentation, EU Machinery Directive implementation guidance, and customs records for neodymium magnet trade flows. Bottom-up equipment shipment tracking and top-down electronics assembly capacity estimates were triangulated to constrain volume forecasts.
Segment-weighting across product type, application, end user, and technology dimensions shaped the analytical framework over the projection horizon. Modeled categories included automatic, manual, semi-automatic, and custom feeder architectures; electronics assembly, automotive manufacturing, pharmaceutical packaging, and consumer goods applications; contract manufacturers, OEMs, tier-1 suppliers, and research institutions; plus electric, hybrid, pneumatic, and mechanical drive technologies. CAGRs were derived from regression-adjusted deployment curves incorporating ISO 14644 cleanroom certification mandates and China's dual carbon goals as structural accelerants.
Inputs from primary stakeholder interviews were available through the study window; gaps in real-time equipment-as-a-service contract terms introduce uncertainty bands around service revenue projections. Forecasts reflect assumptions regarding electric actuator cost curves and rare-earth supply stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Equipment Front End Module (EFEM) Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Electrostatic Chucks Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
Pulse Tube and Gifford-Mcmahon Cryocoolers Market
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
Semiconductor Wafer Process Control Equipment Market
Semiconductor Equipment
4-Inch SiC Laser Annealing Equipment Market
Semiconductor Equipment
Sample Preparation Equipment Market
Semiconductor Equipment
Solder Ball Mounter Market
Semiconductor Equipment
Semiconductor Production Equipment Market
Semiconductor Equipment
Pulsed Laser Deposition Systems Market
Semiconductor Equipment
Photolithography Market
Semiconductor Equipment
Global Wafer Cleaning Equipment Market
Semiconductor Equipment
Wire Bonder Equipment Market