
 Multicore Cables Market | 2026-2036
Multicore Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Multicore Cables Market Foresight
Utility and data center buyer concentration is expanding as hyperscalers and national grid operators consolidate procurement into long-term framework agreements. Prysmian Group leverages its integrated submarine and land cable portfolio to anchor large-scale renewable interconnection projects. Nexans competes aggressively in European electrification tenders, while LS Cable & System sustains dominant manufacturing scale across Asia-Pacific markets.
Multicore cables bundle multiple insulated conductors within a single sheath, typically rated from 300V to 35kV depending on application, with copper or aluminum cores and XLPE or PVC insulation systems engineered for signal integrity and mechanical protection. Power cables dominate volume shipments due to grid expansion and renewable energy interconnection requirements, while data cables capture faster growth as fiber-composite hybrid constructions displace legacy copper backbones in telecommunications infrastructure. Control cables maintain stable margins in industrial automation, though instrumentation cables face pricing pressure from commoditized Asian supply.
IEC 60502, NFPA 70, and the EU Construction Products Regulation shape product design, fire-performance testing, and market access across major economies. The EU CPR mandates enhanced reaction-to-fire classifications for indoor installations, while NFPA 70 governs ampacity and conduit fill in North American commercial builds. Stakeholders must monitor evolving low-smoke zero-halogen specifications and regional content requirements that could disqualify non-compliant suppliers from publicly funded infrastructure programs.
Market Dynamics
Hyperscale data center operators and national grid utilities are consolidating procurement into multi-year framework agreements, compressing vendor margins while locking in volume commitments that reshape competitive positioning across copper and fiber-composite cable categories.
Growth Catalysts
- EU Construction Products Regulation:Enhanced reaction-to-fire classifications for indoor installations are forcing specification upgrades across German and French commercial builds, opening premium product lines for compliant suppliers.
- Data center power density:AI training clusters now demand 240kW+ per rack, requiring high-ampacity multicore feeder cables that bundle power and fiber monitoring in single-jacket constructions.
- China grid modernization:State Grid Corporation's ultra-high voltage transmission program sustains heavy-volume contracts for 110kV+ XLPE-insulated multicore systems through 2030.
Market Restraints
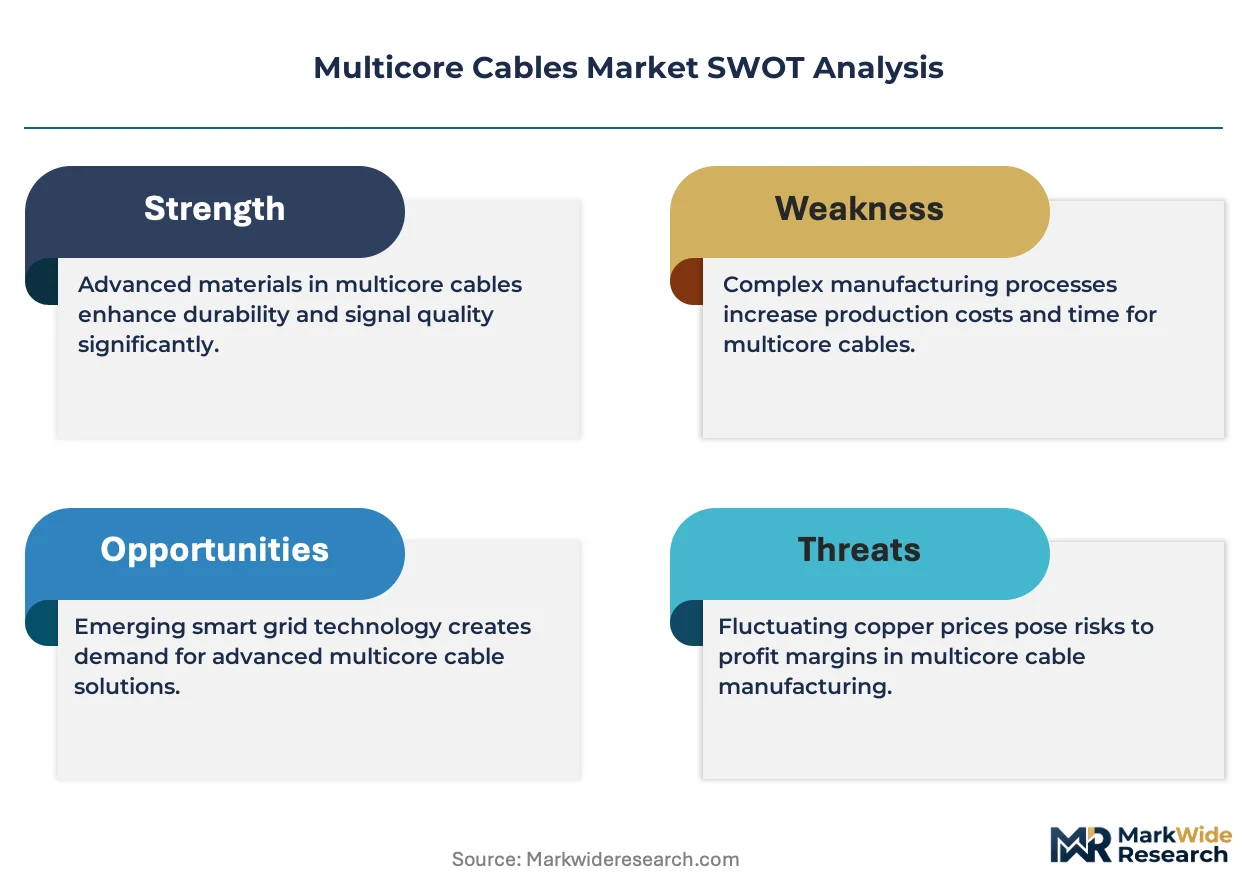
- Copper price volatility:LME copper futures above $9,000/tonne compress extrusion margins and trigger quarterly price renegotiation clauses in framework agreements.
- Regional supply concentration:Asia-Pacific manufacturers control 60%+ of global PVC compound capacity, creating single-source risk for European cable assemblers.
- Optical fiber substitution:All-dielectric self-supporting cables displace copper telecom backbones in greenfield 5G fronthaul, capping legacy copper demand growth.
Strategic Opportunities
- India transmission buildout:Power Grid Corporation's green energy corridors create demand for 66kV cross-linked polyethylene multicore systems in Rajasthan and Gujarat solar zones.
- US Inflation Reduction Act:Domestic content bonuses for federally funded infrastructure projects incentivize reshoring of cable extrusion and copper rod casting capacity.
- Fiber-copper hybrid convergence:Composite power-plus-communications cables enable single-pull installation in smart building retrofits, reducing labor hours by 40%.
Industry Challenges
- Low-smoke zero-halogen formulation expertise:Compound chemists capable of meeting CPR B2ca ratings without sacrificing mechanical flexibility command 35% salary premiums.
- Type approval timelines:IEC 60502-2 testing protocols require 18-24 months for new 20kV cable designs, delaying revenue recognition on R&D investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multicore Cables Market |
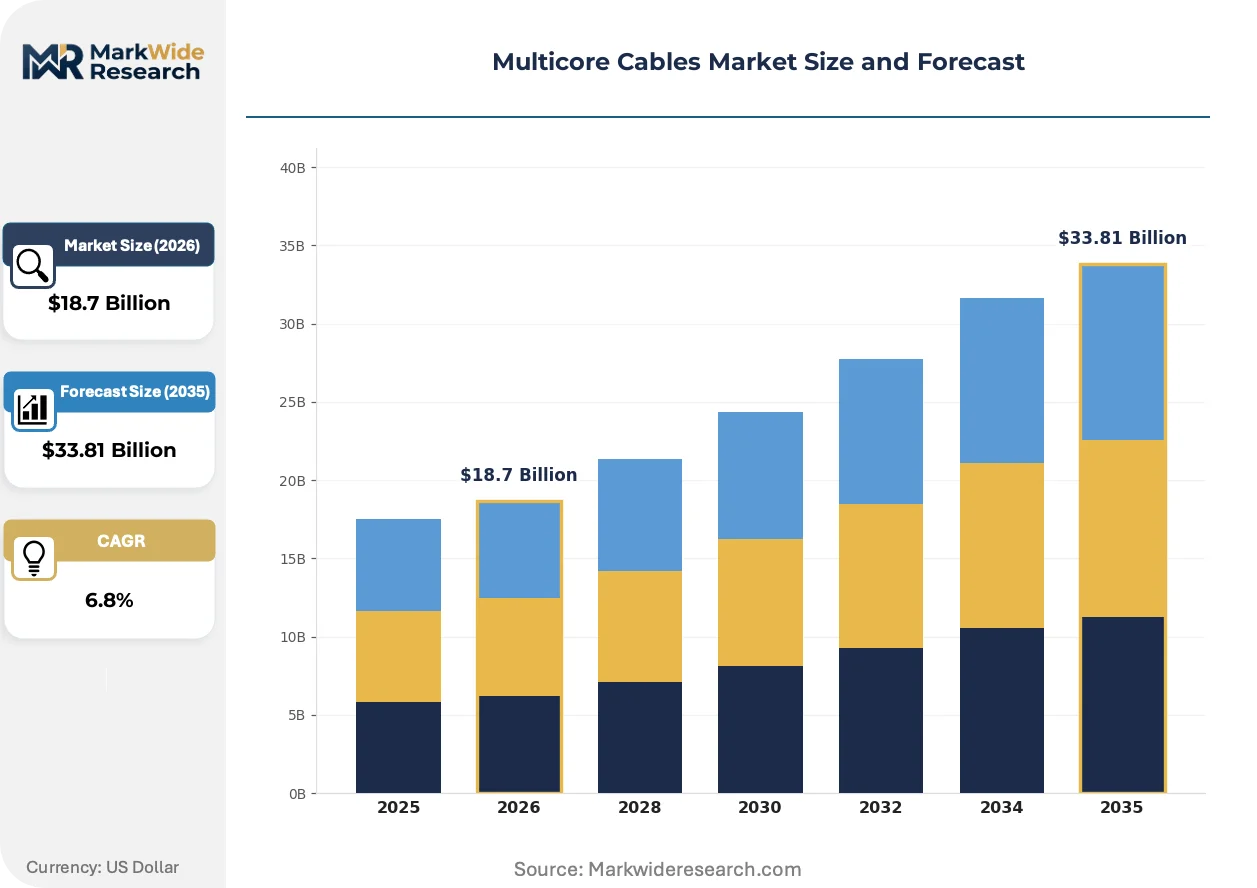
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cable Type: Power Cables, Data Cables, Control Cables, Instrumentation Cables Material: Copper, Aluminum, Fiber Optic, Composite End User: Telecommunications, Oil & Gas, Transportation, Renewable Energy Installation Type: Underground, Overhead, Indoor, Outdoor |
| Companies Covered | Prysmian Group, Nexans, LS Cable & System, Sumitomo Electric Industries, Southwire Company, Polycab, Centurion Power Cables Pvt. Ltd., KCL Cable Limited, Relemac Technologies Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multicore Cables Market Shifts & Advancements
Active unification of power and data transmission within single-jacket constructions is compressing installation labor and material counts across building infrastructure, while regulatory fire-performance mandates and procurement centralization reshape vendor economics.
Cross-linked polyethylene with triple-layer extrusion is unifying medium-voltage power and optical fiber sensing in one sheath. Offshore wind developers in the North Sea are specifying these hybrid cables for inter-array connections. This unification eliminates separate fiber pulls and enables real-time thermal monitoring of submarine circuits.
REACH restrictions on halogenated flame retardants are accelerating magnesium hydroxide adoption in European building cables. Compounders must reformulate without compromising CPR classification performance. German distributors now stock only B2ca-rated inventory, forcing rapid specification migration.
Long-term framework agreements with fixed-volume, variable-price mechanisms are displacing spot purchasing among Nordic utilities. Procurement teams negotiate 3-5 year supply contracts indexed to copper LME. This concentration favors cable producers with captive copper rod capacity and integrated logistics networks.
Multicore Cables Market Segmentation
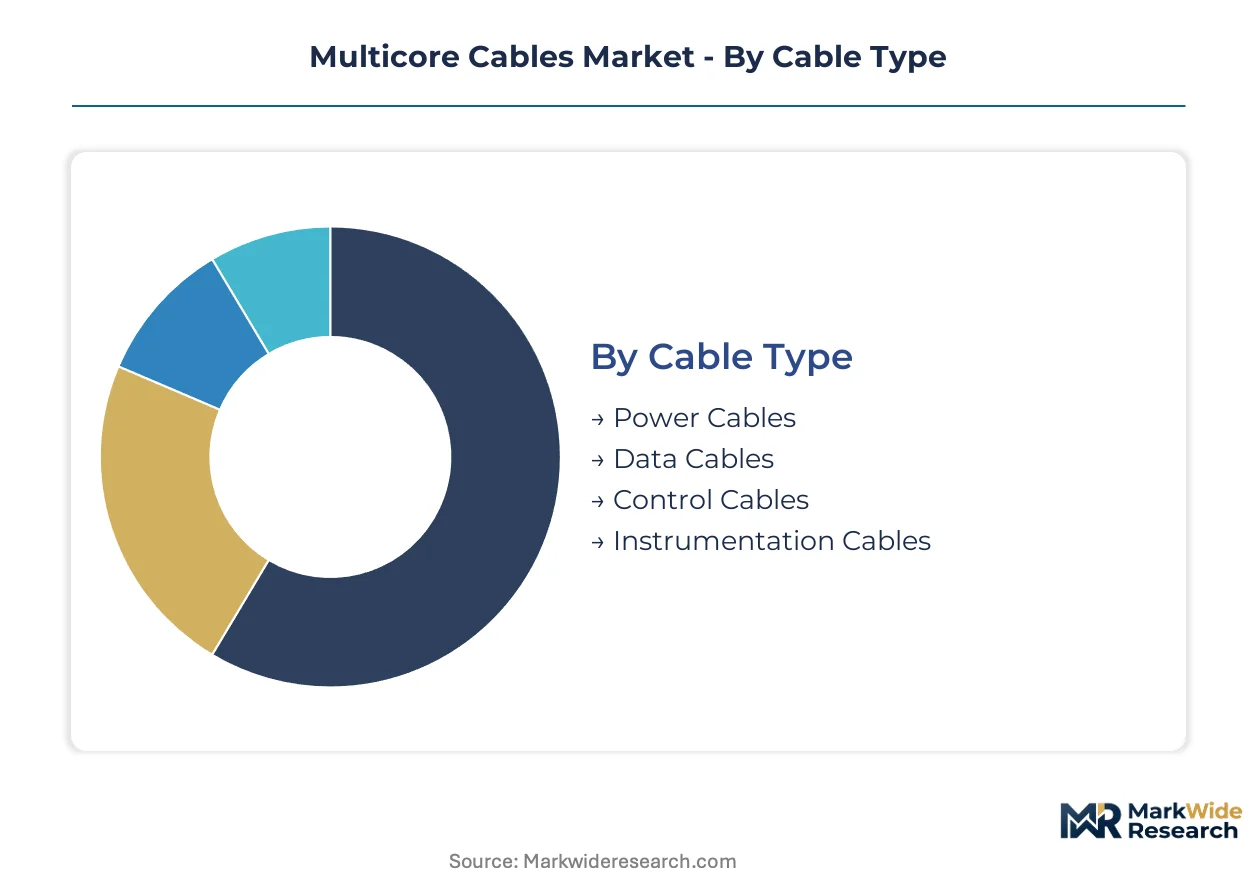
Multicore cable procurement divides sharply across voltage ratings, conductor materials, and fire-performance tiers. Specification mismatches between IEC 60502 utility standards and EU CPR indoor classifications create parallel supply chains that vendors must navigate simultaneously.
Cable Type:
IEC 60502-2 governs medium-voltage power cable designs, while TIA-568 and ISO/IEC 11801 shape data cable performance benchmarks. Control and instrumentation categories fall under IEC 60227 and IEC 60502-1 with varying flame-retardance requirements.
- Power Cables:XLPE-insulated copper or aluminum conductors rated 1kV to 35kV, engineered for grid interconnection and renewable energy export. State Grid Corporation's ultra-high voltage program in China sustains heavy-volume procurement of 110kV+ bundled systems. Stranded compact conductors with triple-layer extrusion dominate utility tenders where ampacity and thermal cycling resistance determine specification.
- Data Cables:Twisted-pair copper or fiber-composite constructions carrying Ethernet, fiber channel, or hybrid power-plus-communications protocols. Hyperscale data center operators in Ashburn, Frankfurt, and Singapore now specify 240kW+ rack densities requiring integrated fiber monitoring within single-jacket feeder cables. Category 8 copper and OM5 multimode fiber displace legacy backbone infrastructure in greenfield builds.
- Control Cables:Multi-conductor flexible designs with PVC or PUR sheathing for industrial automation signal transmission.
- Instrumentation Cables:Paired or triad constructions with individual and overall shields for process control accuracy in petrochemical environments.
Leading the category by volume: Power Cables. Growing fastest: Data Cables.
Material:
Raw material selection locks in conductivity, weight, and cost structures that ripple through procurement negotiations. LME copper pricing above $9,000/tonne compresses extrusion margins and triggers quarterly renegotiation clauses in framework agreements.
- Copper:Electrolytic tough pitch or oxygen-free high-conductivity grades delivering maximum ampacity in confined installations. European utilities specify copper for submarine interconnector projects where corrosion resistance and fatigue life outweigh aluminum's weight advantage. German and French distributors now stock only B2ca-rated copper building wire under EU CPR mandates.
- Aluminum:Alloy 1350 or 6201 conductors offering 50% weight reduction at 61% copper conductivity, specified for overhead transmission and long-span aerial installations. India's Power Grid Corporation deploys aluminum multicore systems across Rajasthan solar zones where conductor sag and tower loading drive material choice.
- Fiber Optic:All-dielectric self-supporting cables displacing copper telecom backbones in 5G fronthaul.
- Composite:Power-plus-fiber hybrid constructions enabling single-pull installation in smart building retrofits.
Copper commands premium pricing in fire-rated and submarine applications. Aluminum gains share fastest in overhead renewable interconnection.
End User:
Customer concentration shapes contract structures, with hyperscalers and national utilities consolidating procurement into multi-year framework agreements indexed to commodity inputs.
- Telecommunications:5G fronthaul and data center interconnect driving fiber-composite and high-pair-count copper demand. Nordic operators specify LSZH-sheathed cables for tunnel and metro installations under national fire-safety codes.
- Oil & Gas:Offshore platform and subsea production systems requiring mud-resistant, armored multicore control and power bundles. North Sea developers specify hybrid power-plus-sensing cables for inter-array wind connections with real-time thermal monitoring.
- Transportation:Rolling stock and infrastructure electrification with EN 50264 and NFPA 130 fire-performance requirements.
- Renewable Energy:Solar farm DC collection, wind turbine nacelle power, and export cable systems.
Telecommunications generates the highest specification velocity. Renewable Energy expands most quickly on capacity addition trajectories.
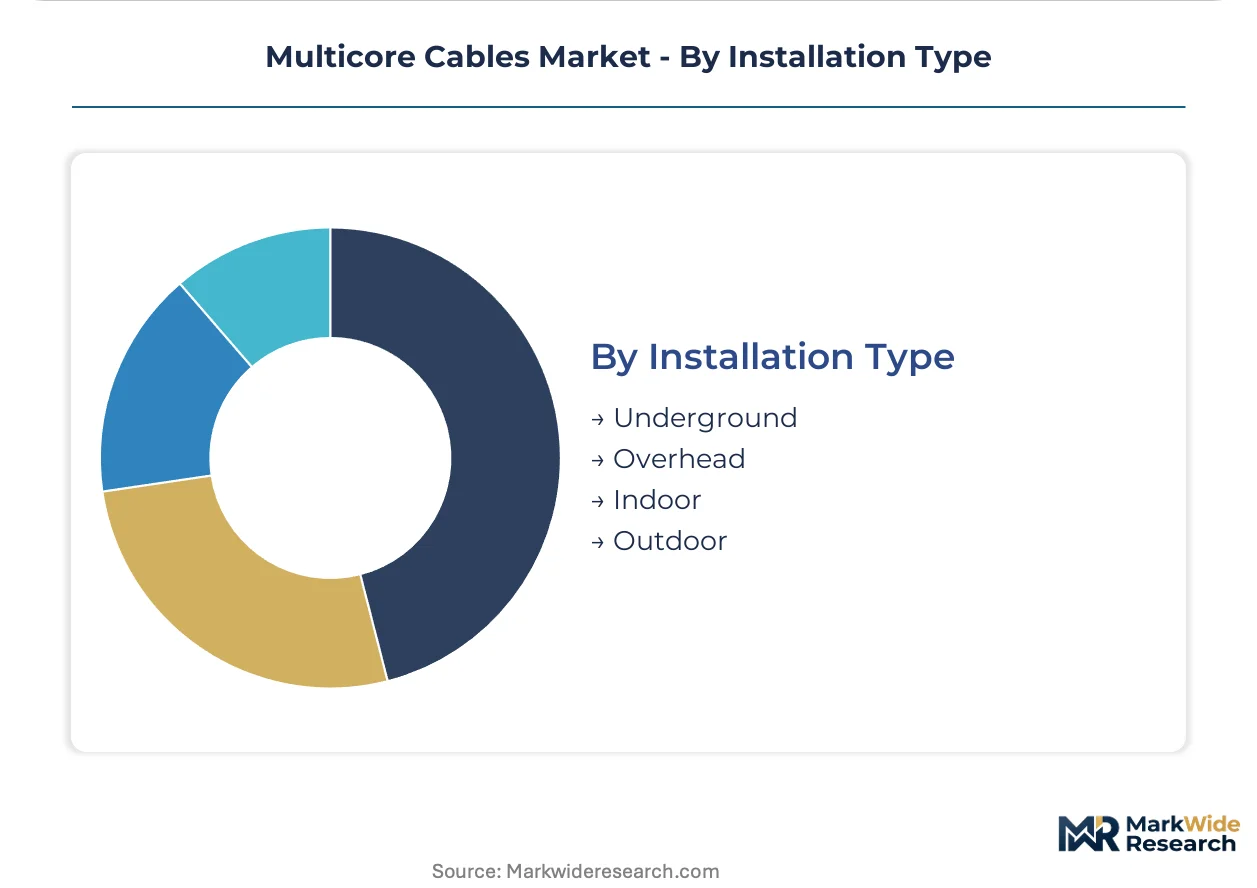
Installation Type:
Deployment environment dictates mechanical protection, moisture barriers, and fire-performance tiers that segment manufacturing lines and inventory positions.
- Underground:Direct-buried or duct-bank installations with water-blocking tapes, corrugated aluminum or steel armor, and HDPE or PVC jackets. Urban grid modernization in Shanghai and Mumbai prioritizes underground routing for reliability and right-of-way constraints.
- Overhead:Aerial self-supporting or messenger-supported designs with UV-stabilized jackets and tension members. Brazilian transmission buildouts favor overhead aluminum systems for cost and speed of deployment across remote terrain.
- Indoor:Plenum and riser-rated constructions governed by EU CPR reaction-to-fire classifications and NFPA 70 ampacity tables.
- Outdoor:Weather-resistant jackets with carbon black loading for UV stability in exposed industrial and renewable applications.
Underground claims the largest installed base. Indoor specifications are tightening fastest on regulatory fire-performance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper mining localities in Chile and Zambia anchor raw material flows for cable extrusion, while manufacturing clusters concentrate near major demand centers in Germany, China, and the United States where grid modernization and data center construction sustain procurement volumes.
China
State Grid Corporation's ultra-high voltage transmission program drives procurement of 110kV+ XLPE-insulated multicore systems through 2030. MIIT's dual carbon goals accelerate specification upgrades for renewable interconnection projects. Manufacturing concentrates in Jiangsu and Shandong provinces where integrated copper rod casting and cable extrusion facilities cluster near Shanghai port logistics.
Germany
Industrial automation and offshore wind interconnection sustain demand for medium-voltage power and hybrid sensing cables. ECHA's REACH restrictions on halogenated flame retardants force magnesium hydroxide reformulation in building wire compounds. The Rhine-Ruhr industrial corridor hosts concentrated cable assembly operations serving European electrification tenders.
United States
Hyperscale data center operators in Ashburn and Dallas-Fort Worth specify 240kW+ rack densities requiring high-ampacity feeder constructions. FERC interconnection standards and IRA domestic content bonuses incentivize reshoring of extrusion capacity. Southeast manufacturing corridors in Georgia and South Carolina expand copper rod casting to serve federally funded infrastructure programs.
India
Power Grid Corporation's green energy corridors create demand for 66kV cross-linked polyethylene systems across Rajasthan and Gujarat solar zones. CEA mandates on transmission reliability push specification upgrades in urban distribution networks. Cable manufacturing clusters in Maharashtra and Tamil Nadu scale production to meet state-backed renewable export requirements.
United Kingdom
North Sea offshore wind developers specify hybrid power-plus-fiber cables for inter-array connections with real-time thermal monitoring. BEIS building safety regulations align with EU CPR fire-performance classifications for commercial installations. Manufacturing activity concentrates in Yorkshire and the Midlands serving North Sea energy infrastructure and domestic grid reinforcement projects.
Multicore Cables Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue fiber-copper hybrid specializations and regional certification niches. The vendor base stratifies across integrated multinationals with captive copper capacity, mid-scale regional assemblers, and specialized compounders focused on low-smoke zero-halogen formulations. Dominant competitive moves include backward integration into copper rod casting and long-term framework agreements indexed to LME pricing.
Among Italian and French integrated cable producers, Prysmian Group and Nexans occupy positions representing the multinational archetype with submarine and land portfolio breadth. LS Cable & System exemplifies the Asia-Pacific scale-driven tier with manufacturing concentration serving regional utility procurement. These anchors illustrate how geographic production positioning and raw material integration separate competitive tiers in framework-driven procurement environments.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| LS Cable & System |
| Sumitomo Electric Industries |
| Southwire Company |
| Polycab |
| Centurion Power Cables Pvt. Ltd. |
| KCL Cable Limited |
| Relemac Technologies Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
Long-term framework agreements with hyperscale data center operators and national grid utilities are compressing vendor margins while locking in volume commitments, forcing cable producers to secure captive copper rod capacity and integrated logistics networks to maintain pricing power under LME-indexed contracts.
Pricing Analysis
Warranty and testing-service bundling now separates premium-tier suppliers from unbundled economy competitors in utility tenders. Three-tier pricing structure across CPR B2ca-certified premium, standard IEC 60502-compliant, and economy PVC grades reflects fire-performance certification and copper purity levels. Pricing pressure stems from quarterly renegotiation clauses triggered by LME volatility above $9,000 per tonne. Municipal utilities exhibit highest price sensitivity; submarine interconnector projects show lowest.
Supply Chain Analysis
Domestic content bonuses under the US Inflation Reduction Act and India's PLI scheme for manufacturing are reshaping sourcing patterns away from pure cost optimization toward regional qualification. Manufacturing concentrates in China, Germany, and the United States, drawing from Chilean and Zambian copper mining, South Korean XLPE compound supply, and German magnesium hydroxide flame retardants. Single-source risk sits with Asia-Pacific PVC compound capacity. Distribution runs through authorized distributor networks serving utility procurement desks and EPC contractor project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multicore cables market operates as a cost-of-compliance arena where EU CPR reaction-to-fire classifications and REACH halogen restrictions erect barrier-to-entry moats favoring compounders with certified low-smoke zero-halogen formulation expertise.
For Market Incumbents: Deploy captive copper rod casting capacity as the primary margin defense against LME volatility and quarterly renegotiation pressure. Prysmian Group and Nexans anchor positioning through backward integration into submarine cable manufacturing and long-term framework agreements with State Grid Corporation. Incumbents must accelerate magnesium hydroxide compound R&D to maintain CPR B2ca certification as REACH restrictions tighten. For New Entrants and Emerging Players: The 35-40% price-point gap between premium CPR B2ca-rated and economy PVC-sheathed cables creates entry space for mid-tier specialists. India's green energy corridors and US IRA-funded infrastructure projects represent the most penetrable geographies, with 66kV cross-linked polyethylene multicore systems for solar zones offering volume traction. A certification-first go-to-market angle—securing IEC 60502-2 type approval before commercial launch—builds utility credibility faster than price competition. For Investors and Strategic Acquirers: The window for entry favors compounders with proven LSZH formulation expertise and captive testing laboratory infrastructure. Long-term viability hinges on exposure to data center power-density upgrades and renewable interconnection cycles rather than commodity construction demand. Watch CPR classification migration timelines as the inflection signal—German distributors now stock only B2ca-rated inventory, forcing rapid specification lock-in across European markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Rod Casting | Captive smelting capacity insulates Prysmian and Nexans from LME volatility in framework negotiations. |
| CPR B2ca Certification Investment | German distributors' exclusive B2ca stocking mandates disqualify non-compliant suppliers from commercial projects. |
| Fiber-Copper Hybrid R&D Program | Power-plus-fiber convergence enables single-pull installation contracts with hyperscale Ashburn and Frankfurt operators. |
| Long-Term Framework Agreement Structuring | Fixed-volume, variable-price mechanisms with Nordic utilities lock out spot-market competitors. |
| Regional Extrusion Capacity Reshoring | IRA domestic content bonuses incentivize Georgia and South Carolina manufacturing for federally funded infrastructure. |
Research Methodology
Document review covered IEC 60502 and EU CPR regulatory filings, customs trade data for copper and cable exports, and hyperscaler capex disclosures, complemented by interviews with utility procurement managers, EPC contractor project directors, cable compound R&D leads, and distributor inventory planners. Secondary validation drew from FERC interconnection standards documentation, ECHA REACH restriction updates, and SEC filings of integrated cable producers. Bottom-up volume modeling and top-down value triangulation anchored segmentation outputs.
Installed base projections and revenue estimates across the analysis window reflect a structured analytical framework spanning voltage rating tiers, conductor material categories, fire-performance classifications, and end-user industry verticals. CAGRs were derived from segment-level growth rate reconciliation against macro infrastructure investment patterns. Forecast inputs incorporated State Grid Corporation ultra-high voltage procurement schedules and data center rack density specifications from Ashburn, Frankfurt, and Singapore operators.
Inputs from utility procurement managers and compound laboratory directors were available through the study window; gaps in real-time LME futures positioning and unannounced hyperscale facility expansions introduce uncertainty bands around near-term volume assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Insulated Wire and Cable Market
Cables
GCC Cable Accessories Market
Cables
Network Cable Tester Market
Cables
Europe HVAC Cables Market
Cables
Flexible Cables Market
Cables
North America HVAC Cables Market
Cables
Sensor Cable Market
Cables
Power and Signal Cables Market
Cables
Copper Stranded Wire Market
Cables
Cable Lugs Market
Cables
XLPE Cables Market
Cables
North America Coaxial Cable Market
Cables
Copper Cabling Systems Market
Cables
Downhole Cables Market
Cables
Sensing Cable Market
Cables
Cable Assembly Market