
 Cable Management System Market | 2026-2036
Cable Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Management System Market Intelligence
Project finance models for large-scale data center and utility grid upgrades are reconfiguring the competitive landscape for cable management suppliers. These long-term contracts favor suppliers with extensive manufacturing scale and global logistics networks. Schneider Electric SE leverages its broad portfolio to win integrated project bids. Meanwhile, Panduit Corp. specializes in high-performance solutions for enterprise and data center clients, securing its position through technical expertise.
A cable management system comprises engineered components designed to organize, route, and protect electrical and data cabling. These systems, including trays and conduits, must meet specific load-bearing capacities and fire-resistance ratings. In terms of product type, steel cable trays dominate industrial applications due to their strength and durability. However, PVC and fiberglass conduits represent the fastest-growing material segments, driven by their use in telecommunications and commercial construction where corrosion resistance is critical.
Product standards are heavily influenced by national and regional electrical codes, such as the National Electrical Code (NEC) in the United States. Concurrently, environmental regulations including the EU's RoHS directive restrict the use of hazardous substances in materials. These frameworks mandate specific performance and safety criteria for market access. Success will depend on suppliers' ability to innovate with materials that meet both evolving fire safety standards and sustainability goals.
Market Dynamics
The central tension in the cable management market is the collision between demand for industrial-grade durability and intensifying regulatory pressure for sustainable, low-hazard materials, particularly in fire safety applications.
Growth Catalysts
- Data Center Expansion:The proliferation of hyperscale and edge data centers creates concentrated demand for high-capacity cable trays and fiber raceways to support dense network architectures.
- Regulatory Mandates:The EU's Construction Products Regulation (CPR) compels the use of certified, fire-resistant materials for all permanently installed building products, including cable pathways.
- Grid Modernization:Upgrades to aging electrical grids in North America and Europe require robust conduits and trays to protect new high-voltage and communication lines from environmental hazards.
Market Restraints
- Input Cost Volatility:Fluctuations in the prices of steel, aluminum, and PVC resins directly impact manufacturer margins and create pricing instability for end-users.
- Divergent Electrical Codes:Discrepancies between standards, such as the National Electrical Code (NEC) in the United States and IEC standards, create compliance hurdles for global suppliers.
- Substitution from Wireless:In specific commercial and residential settings, the adoption of wireless power and data transmission technologies reduces the requirement for extensive physical cabling.
Strategic Opportunities
- EV Infrastructure:The global build-out of electric vehicle charging stations presents a new, large-scale application for durable, outdoor-rated conduits and cable protection systems.
- Smart Systems Integration:Incorporating sensors into cable trays for temperature and load monitoring opens service-based revenue models for predictive maintenance in critical facilities.
- Emerging Economies:Industrialization and infrastructure projects in regions like Southeast Asia represent underpenetrated markets for modern, code-compliant cable management solutions.
Industry Challenges
- Installer Skill Gaps:The increasing complexity of high-density fiber optic management systems requires specialized installation training that is not widely available, risking deployment errors.
- Material Certification Delays:The lengthy and expensive process of achieving fire safety and material compliance certifications for new products slows the market introduction of innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Management System Market |
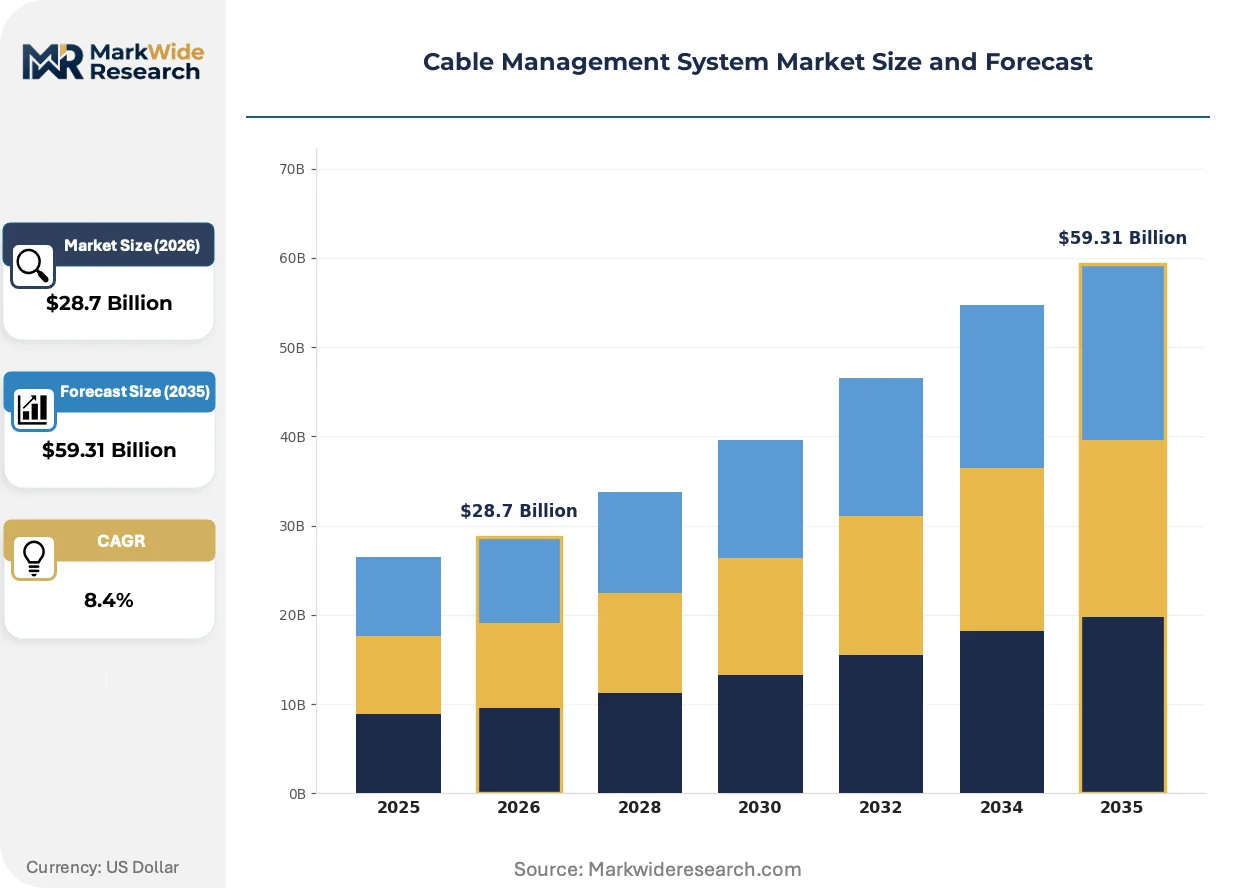
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cable Trays, Cable Troughs, Cable Conduits, Cable Ladders, Cable Ties Material: Steel, Aluminum, PVC, Fiberglass, Nylon Application: Data Centers, Telecommunications, Power Generation, Commercial Complexes, Transportation Infrastructure End User: Electrical Contractors, Facility Management, Network Operators, Utility Providers, Construction Firms |
| Companies Covered | Atkore International Group Inc., Eaton Corporation plc, Belden Incorporated, ABB Ltd., Hubbell Incorporated, Panduit Corp., Schneider Electric SE, TE Connectivity Ltd., Legrand S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Management System Market Strategic Shifts & Innovations
Material science innovation and software-driven design are converging to address dual market pressures. These forces are redefining product specifications and installation methodologies to meet demands for both enhanced safety and operational efficiency.
Building Information Modeling (BIM) and digital twin software allow for detailed pre-planning of cable routing and support structures. Engineering firms increasingly adopt this technology for complex projects like hospitals and industrial plants. This software-first approach is virtualizing the physical layout process, reducing on-site rework and material waste.
The European Union's RoHS directive continues to restrict the use of hazardous substances in electrical equipment. This regulation forces manufacturers to reformulate materials, especially PVC compounds and metal coatings, to eliminate substances like lead. The non-metallic conduit segment is most affected, accelerating R&D in halogen-free alternatives for public infrastructure projects.
A preference for pre-fabricated and modular cable management assemblies is growing among large project developers. This approach displaces traditional on-site, piece-by-piece installation with factory-built units that accelerate construction schedules. The shift is most visible in data center construction within the United States and Germany, where speed-to-market is a critical factor.
Cable Management System Market Segmentation
The cable management system market is fundamentally shaped by how various components are categorized, reflecting distinct performance requirements and installation environments. Understanding these segments allows for targeted product development and strategic market penetration across diverse infrastructure projects.
Product Type:
The cable management system market exhibits varying product lifecycle speeds, influencing material selection and installation methodologies.
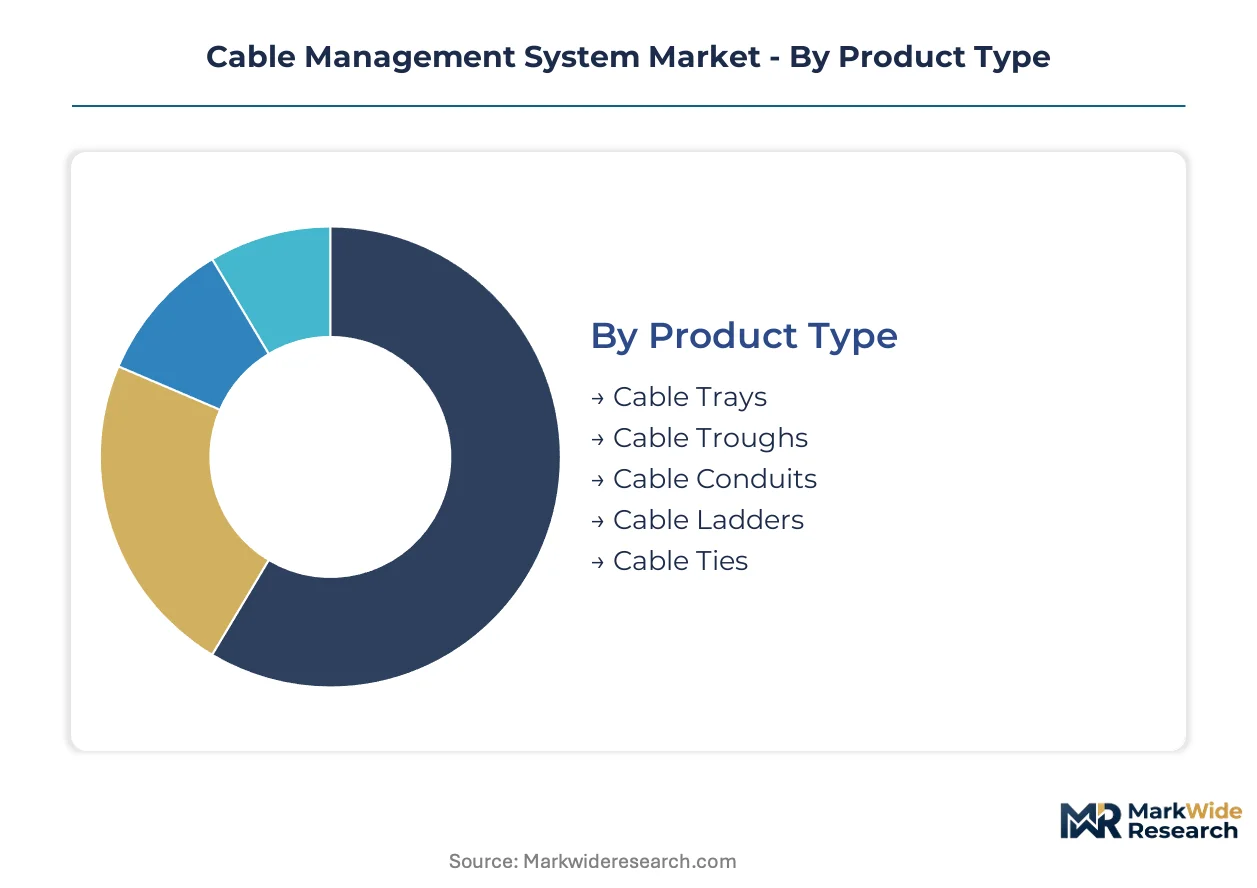
- Cable Trays:These open-structured supports facilitate easy access for cable additions, removals, and maintenance in industrial environments. Steel cable trays dominate heavy industrial applications due to their strength and load-bearing capacity in manufacturing plants and power stations.
- Cable Conduits:Enclosed tubes provide maximum protection for wiring against physical damage, moisture, and corrosive agents, critical for safety and longevity. Demand for PVC and fiberglass conduits is expanding most quickly in telecommunications networks and commercial building projects where chemical resistance is essential.
- Cable Troughs:These solid-bottom or ventilated channels offer continuous support for sensitive cables, preventing sagging and stress points.
- Cable Ladders:Designed with rungs, cable ladders provide robust support for heavy cable loads over long spans in outdoor utility installations.
- Cable Ties:Simple fastening devices secure bundles of cables, improving organization and airflow within equipment racks and control panels.
Cable Trays anchors the volume base while Cable Conduits gains share at the steepest rate.
Material:
Material choices for cable management systems often reflect a trade-off between initial cost and long-term performance requirements.
- Steel:Known for its high strength-to-weight ratio and durability, steel is a primary material for heavy-duty cable trays and conduits. Industrial facilities and data centers predominantly specify steel for its structural integrity and fire resistance.
- PVC:Polyvinyl chloride offers excellent corrosion resistance, electrical insulation, and flexibility, making it a cost-effective solution for many commercial and residential applications. The EU's RoHS directive influences PVC reformulation to eliminate hazardous substances for market access.
- Aluminum:Lighter than steel, aluminum provides good corrosion resistance and is often chosen for its aesthetic appeal in exposed commercial installations.
- Fiberglass:This composite material excels in highly corrosive environments and offers superior strength-to-weight characteristics, particularly in marine and wastewater treatment plants.
- Nylon:Flexible and impact-resistant, nylon is commonly used for cable ties and smaller conduit systems where chemical resistance is also a factor.
The shift towards Fiberglass reflects increasing demand for corrosion resistance in coastal infrastructure projects.
Application:
Specific end-use applications dictate the volume and complexity of cable management infrastructure required.
- Data Centers:Hyperscale and edge data centers require high-capacity cable trays and fiber raceways to manage dense network architectures and power distribution. The United States and Germany exhibit concentrated demand for advanced modular solutions.
- Telecommunications:This sector utilizes extensive conduit systems and fiber optic cable management solutions to protect communication lines from environmental hazards and physical damage. Grid modernization initiatives in North America drive demand for robust solutions.
- Power Generation:Power plants and substations demand heavy-duty, fire-resistant cable management systems to protect critical power and control cabling.
- Commercial Complexes:Office buildings, retail spaces, and hospitals require aesthetically pleasing and code-compliant cable pathways for power and data.
- Transportation Infrastructure:Airports, railways, and tunnels use specialized cable protection systems to withstand vibrations, weather, and heavy use.
Demand for Data Centers solutions is concentrated in the United States, driven by hyperscale cloud expansion.
End User:
The diverse procurement practices of end-user segments shape the customization and service requirements for cable management solutions.
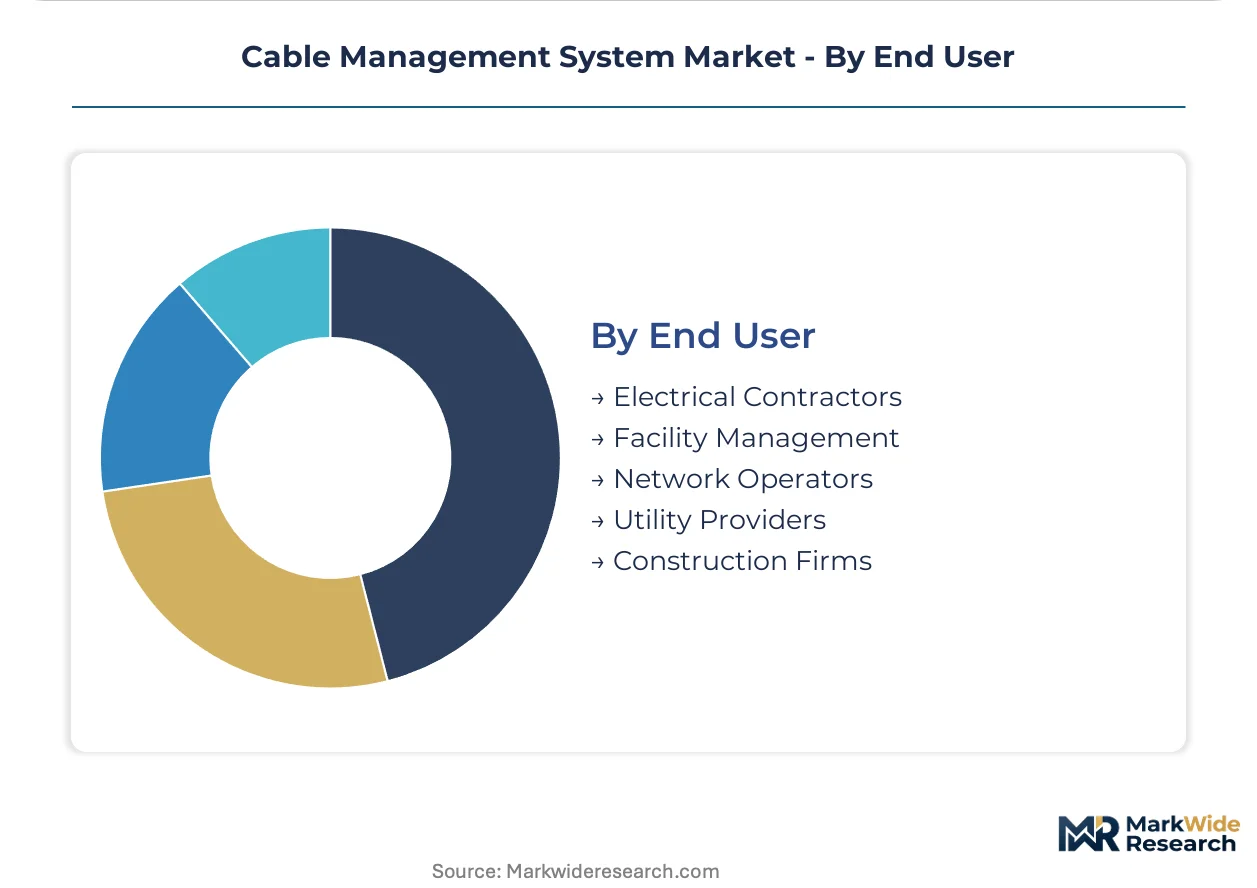
- Electrical Contractors:These professionals purchase and install cable management systems for various projects, requiring product availability and ease of installation. Skill gaps in specialized fiber optic management systems pose a challenge for complex deployments.
- Facility Management:Teams responsible for building operations specify systems that support long-term maintenance, future expansion, and regulatory compliance. Project finance models for large-scale upgrades influence procurement decisions.
- Network Operators:Telecommunications companies and internet service providers require high-performance, scalable solutions for their extensive network infrastructure.
- Utility Providers:Power companies and water utilities demand robust, outdoor-rated conduits and trays to protect critical infrastructure from environmental hazards. Grid modernization efforts in Europe drive significant investment.
- Construction Firms:General contractors integrate cable management into broader building projects, often preferring pre-fabricated and modular assemblies for accelerated construction schedules.
The procurement preferences of Utility Providers influence robust conduit selection across the market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global cable management system market exhibits varied import-export dynamics, with manufacturing hubs often supplying demand-intensive regions. Advanced infrastructure projects in developed economies drive significant imports of specialized components. Meanwhile, emerging markets are building domestic capacity to meet their rapidly expanding construction and industrial needs.
United States
Hyperscale data center expansion and extensive grid modernization efforts fuel demand for high-capacity cable trays and robust conduits. The National Electrical Code (NEC) mandates specific safety and performance standards for all electrical installations. Concentrated data center clusters in Virginia and Texas are rapidly deploying modular cable management solutions to accelerate deployment schedules.
Germany
Stringent regulatory mandates from the EU's Construction Products Regulation (CPR) compel the use of certified fire-resistant materials in commercial and public buildings. The country's strong industrial backbone and significant data center investments drive demand for durable steel cable trays and advanced fiber raceways. The Rhine-Main region, particularly around Frankfurt, sees extensive deployment for new digital infrastructure projects.
China
Rapid urbanization and extensive infrastructure projects, including new rail networks and smart city developments, create substantial demand for cable management systems. The dual carbon goals and GB standards influence the adoption of sustainable materials and energy-efficient designs for new construction. Industrial zones in the Yangtze River Delta are integrating advanced cable management for modern manufacturing facilities.
India
Significant investment in telecommunications infrastructure and renewable energy projects stimulates demand for corrosion-resistant conduits and trays across the country. The government's Smart Cities Mission and Production-Linked Incentive (PLI) schemes encourage local manufacturing and standardized product adoption. Major metropolitan areas like Bangalore and Delhi are experiencing a surge in commercial and data center construction.
United Kingdom
Aging utility grids undergoing modernization and new commercial construction projects require robust cable protection systems to ensure long-term reliability. Compliance with the EU's RoHS directive, even post-Brexit, remains a factor for material specifications in many applications. London's financial district and surrounding tech hubs consistently generate demand for high-density fiber management solutions.
Cable Management System Market Key Industry Players
On the supply side, the industry is characterized by a mix of large diversified conglomerates and specialized component manufacturers. The competitive landscape includes global players offering integrated solutions alongside regional firms focused on specific product types or niche applications. Strategic archetypes include broad-portfolio providers, high-performance solution specialists, and cost-efficient volume producers. Key competitive moves involve strategic partnerships for large infrastructure projects and continuous material innovation to meet evolving regulatory standards.
On the premium-tier vector, Schneider Electric SE, a European multinational corporation, represents broad portfolio integration for large-scale project bids, leveraging its extensive manufacturing scale and global logistics networks. Panduit Corp., a US-based company, exemplifies specialization in high-performance solutions for enterprise and data center clients, securing its position through technical expertise in complex environments. ABB Ltd., a global technology company with headquarters in Switzerland, anchors a position offering comprehensive electrical infrastructure, including cable management systems, across diverse industrial and utility applications worldwide. These entities demonstrate the varied approaches to market leadership, from integrated project delivery to specialized product excellence.
| Leading Market Players |
|---|
| Atkore International Group Inc. |
| Eaton Corporation plc |
| Belden Incorporated |
| ABB Ltd. |
| Hubbell Incorporated |
| Panduit Corp. |
| Schneider Electric SE |
| TE Connectivity Ltd. |
| Legrand S.A. |
| Others |
Cost & Logistics Intelligence
Concentrated demand from hyperscale data centers in the United States drives high-capacity utilization for specialized cable management suppliers, influencing both production scale and competitive pricing strategies.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing models for large-scale cable management systems. Price differentiation stems from the fire-resistance rating of materials and adherence to specific certifications like the EU's Construction Products Regulation. Pricing softness reflects input cost volatility in steel and PVC resins, impacting manufacturer margins. Electrical Contractors often exhibit higher price sensitivity compared to utility providers or facility management teams seeking long-term reliability.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the capital-intensive nature of large infrastructure projects. Geographic supply concentration for raw materials draws from China for steel and PVC, alongside specialized fiberglass production in the United States. Single-source vulnerability for advanced fire-resistant compounds presents a structural risk. Distribution runs through a hybrid model, combining direct sales to large project developers with established electrical distributors serving smaller contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cable management market represents a high-growth disruption driven by accelerating data center expansion and stringent fire safety regulations like the EU's CPR.
For Market Incumbents: Pre-empt competitive threats from specialized material science firms by investing in advanced R&D for halogen-free and sustainable compounds. Expand global logistics networks to serve rapidly growing data center clusters in the United States and Germany. Address installer skill gaps for complex fiber optic management systems through targeted training programs, enhancing customer loyalty and deployment efficiency.
For New Entrants and Emerging Players: Pursue strategic opportunities in the burgeoning EV infrastructure market, focusing on durable, outdoor-rated conduits and cable protection systems. Target underpenetrated emerging economies in Southeast Asia with modular, code-compliant solutions tailored for rapid industrialization projects. Offer integrated smart systems with embedded sensors for predictive maintenance, creating service-based revenue models.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists excelling in fire-resistant material innovation or software-driven design for complex cable routing. Long-term viability hinges on the continued global build-out of digital and energy infrastructure over the next decade. The signal to watch is the increasing regulatory harmonization of fire safety standards across key geographies, simplifying market access for certified products.
| Strategic Initiative | Industry Significance |
|---|---|
| Material Innovation for Halogen-Free Solutions | Ensures compliance with EU RoHS directive for public infrastructure projects. |
| Acquisition of Specialized Sensor Technology Firm | Integrates predictive maintenance capabilities for critical facilities. |
| Expansion of Modular Pre-fabrication Facilities | Accelerates construction timelines for data center developers in the United States. |
| Strategic Partnership with EV Charging Infrastructure Providers | Secures long-term contracts for outdoor-rated conduits. |
| Investment in Installer Training Programs | Addresses skill gaps for complex high-density fiber optic management systems. |
Research Approach
Initial hypotheses were tested against primary input from electrical contractors, facility managers, network operators, and construction firm executives. This qualitative data was then validated with secondary sources, including national electrical codes like the NEC, EU Construction Products Regulation documents, and industry association reports. A bottom-up and top-down triangulation approach ensured comprehensive market sizing and segmentation.
The demand-supply-balance framing guided the analytical framework across the projection horizon. Segmentation dimensions modeled included product type, material, application, end user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected market drivers, with key forecast inputs including data center infrastructure investment and electric vehicle charging station build-out.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new material science entrants or large infrastructure developers would shift outcomes. Forecasts reflect assumptions concerning current regulatory frameworks and technological trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Fault Locator Market
Cables
Middle East and Africa Submarine Cable System Market
Cables
India Optic Fiber Cable and Accessories Market
Cables
Nuclear Multi-Conductor Cables Market
Cables
Electric Vehicle Cables Market
Cables
Data Center Wire and Cable Market
Cables
Network Cable Tester Market
Cables
Low Voltage Cable Accessories Market
Cables
North America Copper Wire and Cable Market
Cables
Latin America Wire and Cable Market
Cables
Global Wires and Cables Market
Cables
Mineral Insulated (MI) Cable Market
Cables
US Cables Market
Cables
LED Cable Market
Cables
Single Core Cables Market
Cables
GCC Cable Accessories Market