
 Downhole Cables Market | 2026-2036
Downhole Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Downhole Cables Market Analysis
The gap between premium armored cables rated for HPHT wells and commodity-grade electrical conductors is realigning procurement patterns across the energy sector. Prysmian Group leverages its integrated optical-electrical manufacturing footprint to dominate subsea umbilical contracts. Schlumberger anchors its position through proprietary cable-telemetry bundles bundled with well intervention services. Halliburton differentiates via ruggedized downhole conductors engineered for extended-reach laterals.
Downhole cables are armored, insulated conductors—typically combining copper power cores with optical fiber elements in a steel-tube or polymer jacket—engineered to transmit power, data, and control signals across extreme pressure-temperature environments exceeding 200°C and 30,000 psi. Their primary purpose is enabling real-time reservoir monitoring, artificial lift control, and well integrity management in directional and horizontal completions. Fiber optic cables command the highest margin pools where distributed temperature and acoustic sensing justify premium pricing. Electrical cables occupy the largest volume position tied to ESP and submersible pump installations across mature basins. Hybrid cables represent the fastest-growing configuration as operators consolidate power, fiber, and hydraulic lines to reduce wellhead congestion.
API RP 19G and ISO 13628-5 govern subsea cable design verification, while BSEE well control regulations in the United States and Norway's PSA framework mandate redundant downhole communication pathways. These standards compel manufacturers to maintain dual-qualified production lines and third-party witnessed factory acceptance testing. Stakeholders must weigh capital allocation between incremental HPHT capability investments and modular cable architectures that accommodate retrofit sensing upgrades.
Market Dynamics
Intelligent well completion architectures are compressing cable procurement cycles as operators bundle power, fiber, and hydraulic functions into single umbilical runs, forcing manufacturers to requalify integrated designs under tighter API RP 19G timelines.
Growth Catalysts
- HPHT well proliferation:Reservoirs exceeding 200°C and 30,000 psi in the US Gulf Coast and Brazil's pre-salt basins require armored conductors with metallurgically sealed fiber cores, pulling demand for certified premium configurations.
- BSEE well control mandates:Redundant downhole communication pathways under US offshore regulations compel operators to install dual-qualified cable systems, expanding factory acceptance testing volumes and certification maintenance contracts.
- Electrical submersible pump retrofit cycles:Mature basins across the North Sea are replacing commodity copper conductors with sensor-integrated hybrid cables to enable real-time artificial lift optimization without well intervention.
Market Restraints
- Specialized alloy supply concentration:Super-duplex stainless steel and Inconel 625 for armored jackets concentrate among Nordic and Japanese metallurgical suppliers, exposing lead times to nickel price volatility and geopolitical trade friction.
- ISO 13628-5 qualification timelines:Third-party witnessed factory acceptance testing and subsea cable design verification protocols extend product development cycles by 18-24 months, freezing capital in work-in-progress inventory.
- Copper conductor substitution pressure:Aluminum power cores and wireless downhole telemetry systems are capturing share in shallow, low-temperature applications where signal latency tolerances permit simpler architectures.
Strategic Opportunities
- Retrofit sensing upgrades:Modular cable architectures with spare fiber count and hydraulic lumens enable brownfield installations to add distributed temperature and acoustic sensing without full umbilical replacement.
- Norway PSA framework expansion:Stricter well integrity documentation requirements under the Petroleum Safety Authority create captive demand for redundant fiber pathways in existing subsea tiebacks.
- Geothermal energy crossover:High-temperature cable qualifications developed for oil and gas HPHT wells transfer directly to enhanced geothermal systems in Nevada and Iceland, opening equipment reuse channels.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for fluoropolymer and PEEK insulation systems that survive sour gas environments is concentrated among retiring specialists in Houston and Aberdeen, constraining R&D throughput.
- Legacy wellhead congestion:Retrofitting intelligent completions into platforms designed for single-function conductors requires custom junction box engineering and subsea intervention vessel coordination, inflating installation risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Downhole Cables Market |
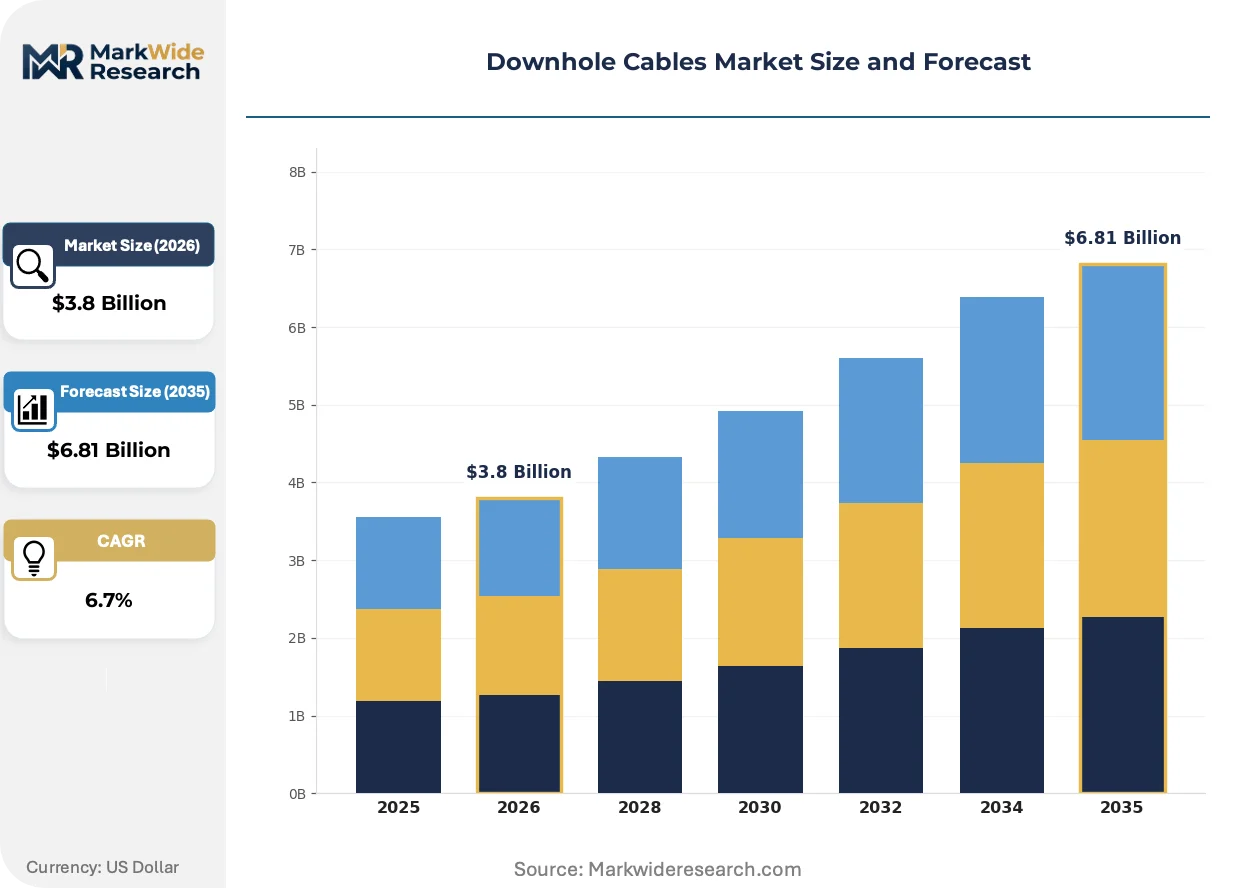
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electro-Optical Cables, Fiber Optic Cables, Electrical Cables, Hybrid Cables Technology: Single-Mode Fiber, Multi-Mode Fiber, Wireline, Wireless End User: Oil & Gas, Geothermal Energy, Mining Industry, Research Institutions Installation Method: Direct Burial, Surface Mounted, Suspended, Wellhead Installation |
| Companies Covered | Prysmian Group, Schlumberger, Halliburton, Baker Hughes, Nexans, Eland Cables, ABB, Fujikura Ltd, Galaxy Wire & Cable, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Downhole Cables Market Emerging Trajectories
Materials science breakthroughs and regulatory ratcheting are compressing product lifecycles while opening white space in integrated sensing architectures. Three developments dominate vendor roadmaps and operator procurement specifications.
Polymer-jacketed hybrid cables combining copper power cores, single-mode fiber, and stainless steel hydraulic tubes in a single extruded profile are overtaking traditional steel-tube armored configurations in deepwater pre-salt developments. Petrobras and Equinor are specifying these integrated bundles for new subsea tiebacks to reduce wellhead footprint and installation vessel time. The technology is overtaking discrete umbilical procurement by collapsing three separate supply contracts into one qualification pathway, compressing vendor margins on standalone electrical and fiber products.
Norway's PSA framework now mandates redundant downhole communication pathways with documented failure-mode analysis for all subsea production wells, extending ISO 13628-5 compliance requirements to existing installations. Operators must retrofit spare fiber capacity or install wireless backup telemetry before license renewal. North Sea brownfield projects are absorbing the bulk of cable engineering hours as vendors redesign junction boxes for legacy wellheads.
Integrated service contracting is consolidating cable procurement with installation and intervention services under single-vendor accountability. Major operators in the US Gulf Coast are abandoning component purchasing in favor of bundled umbilical-installation-commissioning packages where the cable supplier bears subsea connector reliability risk. This model is most visible in ultra-deepwater developments where installation vessel day rates exceed cable material costs, shifting commercial leverage toward vertically capable system integrators.
Downhole Cables Market Segmentation
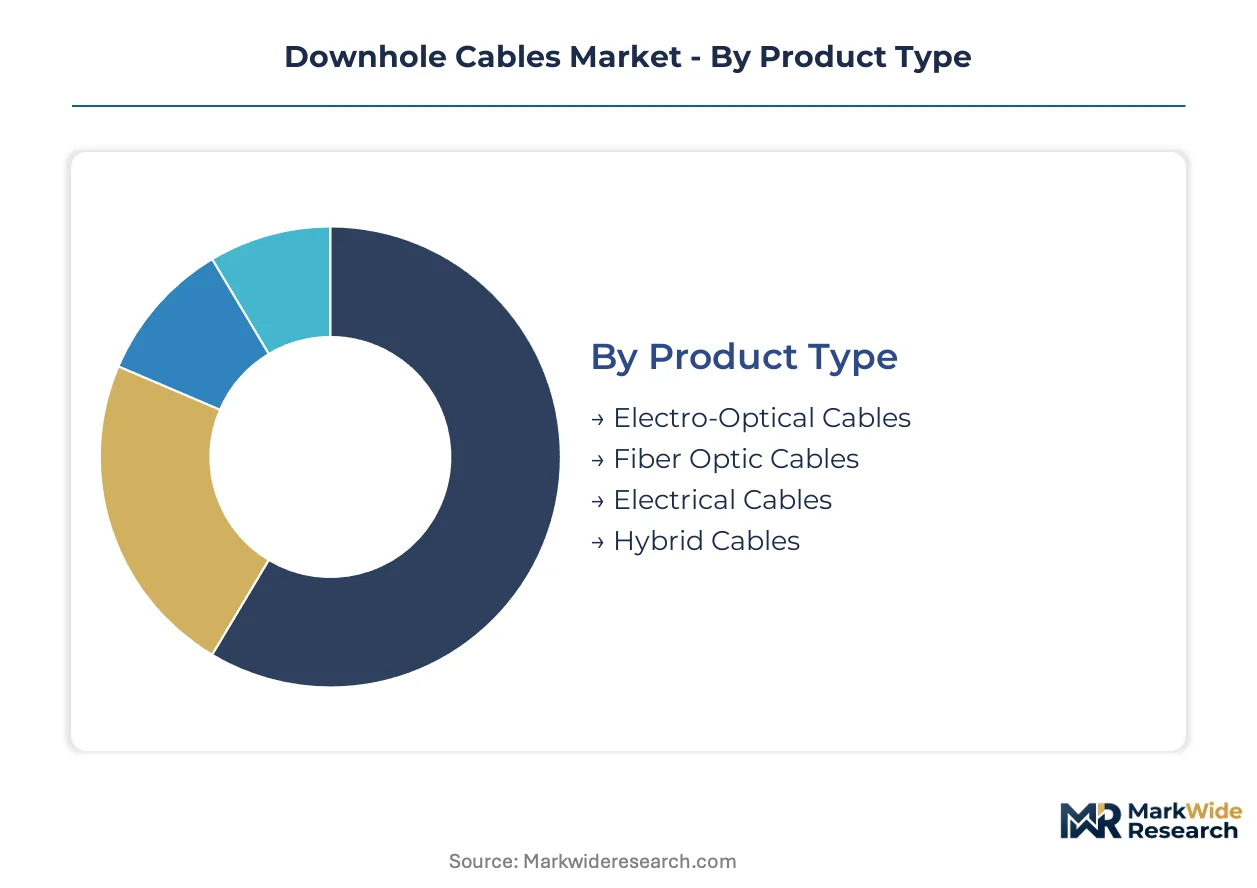
Downhole cable procurement patterns diverge sharply across product architectures, with integrated hybrid configurations displacing standalone electrical and fiber lines in deepwater budgets. Technology choices determine qualification timelines and factory acceptance testing burdens, while installation constraints in legacy wellheads reshape retrofit specifications.
Product Type:
Supply concentration tilts toward integrated configurations as operators consolidate procurement under single-vendor accountability models.
- Electro-Optical Cables:Combining copper power cores with optical fiber elements in a unified armored jacket, these cables serve intelligent well completions requiring simultaneous power delivery and distributed sensing. Demand concentrates in Brazil's pre-salt basins where Petrobras specifications mandate metallurgically sealed fiber cores rated for HPHT reservoirs exceeding 200°C.
- Hybrid Cables:These configurations integrate power, fiber, and hydraulic functions into single extruded profiles, collapsing three separate supply contracts into one qualification pathway. North Sea operators under Norway's PSA framework are specifying hybrid bundles for brownfield retrofits to reduce wellhead congestion without full umbilical replacement.
- Fiber Optic Cables:Pure optical configurations command premium pricing where distributed temperature and acoustic sensing justify standalone deployment.
- Electrical Cables:Copper conductor lines remain the volume workhorse for ESP installations across mature basins facing replacement cycles.
Today's leader: Hybrid Cables. Tomorrow's challenger: Electro-Optical Cables.
Technology:
Cost tier separation emerges between qualified fiber architectures and commodity wireline alternatives facing substitution pressure.
- Single-Mode Fiber:Long-haul optical transmission with minimal signal attenuation enables distributed acoustic sensing across extended-reach laterals. US Gulf Coast deepwater developments specify single-mode cores for redundant downhole communication pathways mandated under BSEE well control regulations.
- Multi-Mode Fiber:Shorter-distance optical transmission suits platform-to-wellhead links where signal latency tolerances permit simpler architectures. Mature North Sea installations favor multi-mode for retrofit sensing upgrades given existing junction box compatibility.
- Wireline:Conductor-based telemetry retains share in shallow, low-temperature applications where installation simplicity outweighs bandwidth requirements.
- Wireless:Radio-frequency and acoustic telemetry systems are capturing marginal share as backup communication pathways where cable installation proves impractical.
Volume concentrates in wireline today. Capability premiums accrue to single-mode fiber architectures.
End User:
Application-specific qualification requirements fragment vendor specialization across energy extraction verticals.
- Oil & Gas:Offshore and onshore hydrocarbon extraction drives the preponderance of HPHT cable demand, with API RP 19G and ISO 13628-5 compliance mandatory for subsea umbilical contracts. Brazil's pre-salt developments and US Gulf Coast ultra-deepwater projects anchor procurement volumes for armored electro-optical configurations.
- Geothermal Energy:Enhanced geothermal systems in Nevada and Iceland leverage existing oil and gas cable qualifications, opening equipment reuse channels for high-temperature ratings developed for HPHT wells.
- Mining Industry:Underground operations deploy ruggedized electrical conductors for pump control and monitoring in confined shaft environments.
- Research Institutions:Scientific drilling programs and subsurface characterization projects generate sporadic demand for specialized fiber deployments.
Revenue dominance rests with oil and gas. Steepest expansion trajectory belongs to geothermal energy crossover applications.
Installation Method:
Customer type stratification separates greenfield specification freedom from brownfield retrofit constraints.
- Wellhead Installation:Direct termination at subsea or surface wellheads requires custom junction box engineering to accommodate integrated power-fiber-hydraulic bundles. Norway's North Sea brownfield projects absorb disproportionate engineering hours as vendors redesign interfaces for legacy platforms.
- Direct Burial:Seabed trenching for subsea tiebacks demands armored jackets resistant to abrasion and hydrostatic pressure, with installation vessel day rates exceeding cable material costs in ultra-deepwater developments.
- Surface Mounted:Platform and rig-mounted cable runs prioritize flexibility and repair accessibility over extreme pressure ratings.
- Suspended:Riser and jumper configurations require dynamic bend radius management for floating production systems.
Wellhead installation commands premium engineering margins. Direct burial captures the largest project scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's pre-salt basins absorb more HPHT cable engineering hours than Norway's North Sea combined, yet the United States Gulf Coast maintains tighter regulatory compliance timelines that compress vendor qualification cycles.
United States
Ultra-deepwater developments in the Gulf of Mexico drive demand for redundant fiber pathways under BSEE well control mandates. The Bureau of Safety and Environmental Enforcement requires documented failure-mode analysis for all subsea production wells. Houston anchors the largest concentration of cable engineering and factory acceptance testing facilities serving domestic and export markets.
Brazil
Petrobras specifications for metallurgically sealed fiber cores dominate procurement patterns across pre-salt fields exceeding 200°C reservoir temperatures. The National Petroleum Agency enforces stringent well integrity documentation for subsea tiebacks. Rio de Janeiro hosts the primary engineering centers coordinating umbilical contracts for Santos Basin developments.
Norway
North Sea brownfield retrofits absorb disproportionate vendor engineering capacity under Petroleum Safety Authority framework expansions. PSA mandates now extend ISO 13628-5 compliance requirements to existing installations before license renewal. Stavanger and Bergen cluster the specialized junction box redesign capabilities serving legacy platform upgrades.
China
Domestic offshore developments in the South China Sea increasingly specify hybrid cable configurations for intelligent well completions. The Ministry of Emergency Management and national oil company procurement standards align with API RP 19G verification protocols. Tianjin and Qingdao manufacturing bases are expanding subsea umbilical production capacity for regional supply.
United Kingdom
Mature basin ESP replacement cycles in the central and northern North Sea favor sensor-integrated hybrid cables over commodity copper conductors. The Health and Safety Executive integrates PSA-aligned well integrity requirements through offshore safety case regulations. Aberdeen maintains specialized engineering services for subsea intervention vessel coordination and legacy wellhead retrofit planning.
Downhole Cables Market Vendor Landscape
Top-tier vendors anchor integrated system contracting, while mid-scale specialists concentrate on modular retrofit architectures. The market structure tilts toward consolidation as installation vessel day rates exceed material costs in ultra-deepwater developments. Three archetypes dominate: vertically integrated energy service conglomerates, dedicated cable and umbilical manufacturers, and regional engineering specialists. Competitive moves center on bundled service accountability models and backward integration into metallurgical supply chains.
Among Italy-based manufacturers, Prysmian Group exemplifies the integrated optical-electrical production archetype. Schlumberger and Halliburton occupy positions within the energy service conglomerate tier, anchoring cable-telemetry bundles within broader well intervention portfolios. These three entities represent the dominant competitive anchors shaping procurement specifications and vendor qualification protocols across deepwater developments.
| Leading Market Players |
|---|
| Prysmian Group |
| Schlumberger |
| Halliburton |
| Baker Hughes |
| Nexans |
| Eland Cables |
| ABB |
| Fujikura Ltd |
| Galaxy Wire & Cable |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between API RP 19G-qualified armored cables and unqualified commodity conductors manifests in divergent pricing power and procurement channel structures across the energy sector. Premium HPHT-rated configurations command sustained margins through Nordic and Japanese metallurgical supply chains, while standard electrical cables face cost compression from aluminum substitution and spot-market copper volatility.
Pricing Analysis
Capacity additions in China's Tianjin and Qingdao manufacturing bases are reshaping price floors for standard hybrid cable configurations, intensifying competition at the mid-tier. Three-tier pricing structure across premium HPHT armored, standard hybrid, and economy-grade electrical levels anchors the market, with differentiation resting on ISO 13628-5 certification status and factory acceptance testing documentation. Pricing pressure stems from integrated service contracting models where installation vessel day rates exceed material costs, forcing cable suppliers to absorb connector reliability risk. Independent operators and mature basin ESP retrofitters exhibit highest price sensitivity, while Petrobras and Equinor specifications demonstrate lowest elasticity due to non-negotiable HPHT ratings.
Supply Chain Analysis
Single-source vulnerability sits with Nordic super-duplex stainless steel suppliers and Japanese Inconel 625 metallurgical specialists for armored jacket materials. Manufacturing concentrates in Italy, the United States, and China, with raw material dependencies centering on nickel alloys, fluoropolymer insulation compounds, and single-mode fiber cores. Supply chain risk manifests in tariff exposure on specialty steel imports and nickel price volatility transmitted through long-lead alloy procurement. Distribution runs through integrated energy service conglomerates and dedicated umbilical manufacturers serving regional deepwater clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The downhole cables market functions as a stable compounder, with regulatory ratcheting on subsea well integrity mandating redundant communication pathways that sustain replacement demand regardless of oil price cycles.
For Market Incumbents: Lock in metallurgical supply partnerships with Nordic and Japanese alloy specialists to secure HPHT-rated jacket materials against nickel volatility and trade friction. Expand factory acceptance testing capacity to compress ISO 13628-5 qualification timelines and capture integrated umbilical-installation contracts where vessel day rates dominate project economics.
For New Entrants and Emerging Players: Enter via modular retrofit architectures targeting Norway's North Sea brownfield upgrades under PSA framework expansions, where legacy wellhead congestion demands custom junction box engineering absent from incumbent catalogs. Pursue geothermal energy crossover qualifications in Nevada and Iceland as the most penetrable application segment, leveraging existing oil and gas HPHT certifications for enhanced geothermal system deployments.
For Investors and Strategic Acquirers: Consolidation pressure builds where installation vessel scarcity and subsea connector reliability risks favor vertically capable system integrators over component specialists. Five-to-ten year viability rests on captive metallurgical supply and dual-qualified production lines. Target acquisition archetypes include regional engineering specialists with PSA-compliant junction box redesign capabilities. The signal to watch is BSEE mandate expansion to onshore unconventional wells, which would replicate redundant pathway requirements across the Permian and Bakken.
| Strategic Initiative | Industry Significance |
|---|---|
| Metallurgical Supply Partnership | Secures Inconel 625 and super-duplex stainless steel access against Nordic and Japanese export constraints. |
| Integrated Service Contracting | Consolidates cable procurement with installation and commissioning under single-vendor accountability for Gulf of Mexico ultra-deepwater. |
| PSA-Compliant Retrofit Engineering | Captures Norway North Sea brownfield demand for spare fiber capacity and redundant pathway documentation. |
| Geothermal Qualification Transfer | Repurposes HPHT oil and gas certifications for Nevada and Iceland enhanced geothermal system deployments. |
| Factory Acceptance Testing Expansion | Compresses ISO 13628-5 verification timelines to compete for Petrobras pre-salt umbilical contracts. |
Methodological Framework
Coverage spans the United States Gulf Coast, Brazil's pre-salt basins, Norway's North Sea, China's South China Sea, and the United Kingdom's central North Sea, with primary inputs from each region combining interviews with subsea project engineers, umbilical procurement managers, petroleum safety authority regulators, metallurgical supply specialists, and installation vessel operators. Secondary validation draws from BSEE well control filings, ANP well integrity documentation, PSA framework updates, API RP 19G revision records, and customs data on nickel alloy imports. Bottom-up project pipeline analysis and top-down energy service expenditure estimates were triangulated to establish market sizing.
Granularity-level modeling disaggregated volume and value across the analysis window by product architecture (electro-optical, hybrid, fiber optic, electrical), technology tier (single-mode fiber, multi-mode fiber, wireline, wireless), end-use vertical (oil and gas, geothermal, mining, research), and installation method (wellhead, direct burial, surface mounted, suspended). CAGRs were derived from regression analysis against subsea well completion counts, ESP replacement cycle timing, and regulatory mandate implementation schedules. Industry-specific forecast inputs included Petrobras pre-salt development timelines and BSEE redundant pathway compliance deadlines.
Inputs from API certification databases and national petroleum agency filings were available through the study window; gaps in proprietary well intervention cost data from integrated service contractors introduce uncertainty bands around bundled contract value estimates. Forecasts reflect assumptions on HPHT well proliferation rates, nickel alloy price trajectories, and regulatory enforcement consistency across jurisdictions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Fiber Optic Cable Accessories Market
Cables
Radio Frequency Cables Market
Cables
Middle East Cable Market
Cables
Underground Cable Market
Cables
Cable Organisers Market
Cables
Hybrid Cables Market
Cables
Type TC and Type TC-ER Cable (600 V) Market
Cables
Fiber Optical Cable and Cable Assembly Products Market
Cables
High-Speed Interconnects Market
Cables
XLPE Cables Market
Cables
Submarine Communication Cables Market
Cables
Cable Racks Market
Cables
Fiber Optic Cable Materials Market
Cables
Anti-Static Space Wires Market
Cables
Class 1E Electric Cables Market
Cables
Nuclear Multi-Conductor Cables Market