
 North America Gelatin Market | 2026-2036
North America Gelatin Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gelatin Market Intelligence
Pharmaceutical-grade gelatin sourcing is reconfiguring margin pools across the North American supply base. Darling Ingredients leverages vertical integration into rendering and collagen recovery to sustain cost leadership in type B gelatin. Gelita AG anchors its position through R&D intensity in hydrolyzed collagen peptides for nutraceutical applications. Nitta Gelatin competes via specialized film-forming grades that serve capsule manufacturers in the eastern United States.
Gelatin comprises partially hydrolyzed collagen extracted from animal connective tissues, with type A (acid-processed) and type B (alkali-processed) variants distinguished by pH treatment and isoelectric point near pH 9 for type B. Its primary commercial purpose centers on thermoreversible gel formation, film barrier properties, and emulsion stabilization across food, pharmaceutical, and photographic industries. Powder and granule formats dominate volume throughput due to handling efficiency in industrial batch processing, while capsule-grade gelatin commands premium positioning through endotoxin and microbial specification stringency. Pharmaceutical and confectionery applications split value generation, with drug delivery systems exhibiting faster structural expansion than mature candy segments where plant-based alternatives erode share.
FDA Current Good Manufacturing Practice regulations and USDA FSIS facility inspection protocols govern gelatin purity, traceability, and allergen control throughout North American production. The EPA monitors rendering facility emissions under Clean Air Act permits, adding compliance cost layers that favor scaled operators with environmental control investments. Stakeholders must monitor regulatory divergence between US FDA and Health Canada purity standards as cross-border ingredient sourcing decisions carry certification implications.
Market Dynamics
FDA Current Good Manufacturing Practice enforcement is tightening endotoxin specifications for pharmaceutical-grade gelatin, forcing capsule manufacturers to requalify suppliers and compressing the approved vendor base across North American production networks.
Growth Catalysts
- Updated FDA Dietary Supplement Labeling Requirements:New purity benchmarks are expanding demand for certified pharmaceutical-grade gelatin in nutraceutical encapsulation across the United States and Canada.
- Midwest Meat Processing Concentration:Dense rendering infrastructure in Iowa, Nebraska, and Kansas provides cost-advantaged type B gelatin feedstock supply chains.
- Softgel Drug Delivery Modernization:Modified-release and liquid-fill capsule technologies are pulling higher-specification gelatin grades into chronic disease therapeutic categories.
Market Restraints
- Bovine Raw Material Volatility:Cattle hide and bone prices fluctuate with livestock cycle conditions and rendering capacity utilization in the US Plains states.
- Plant-Based Encapsulation Substitution:Hydroxypropyl methylcellulose and pullulan capsules are capturing share in vegan-labeled dietary supplement segments.
- EPA Clean Air Act Compliance Burden:Rendering facility emission controls add fixed cost layers that disadvantage smaller gelatin producers without environmental capital investments.
Strategic Opportunities
- Underpenetrated Canadian Nutraceutical Manufacturing:Health Canada Natural Health Product regulations are creating certified-ingredient demand that domestic gelatin purification capacity has not yet matched.
- Hydrolyzed Collagen Peptide Functional Foods:Convergence of sports nutrition and senior wellness segments is opening beverage and bar applications beyond traditional gelatin gelling uses.
- Direct-to-Consumer Supplement Channels:E-commerce subscription models for personalized vitamin stacks are bypassing traditional pharmaceutical distribution and specifying capsule-grade gelatin directly.
Industry Challenges
- Cross-Border Certification Timeline Compression:Divergent FDA and Health Canada purity documentation requirements delay product launches for manufacturers serving both markets.
- Specialized Rendering Technician Shortage:Collagen extraction and hydrolysis process engineering expertise concentrates at a handful of legacy facilities with limited workforce pipeline.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gelatin Market |
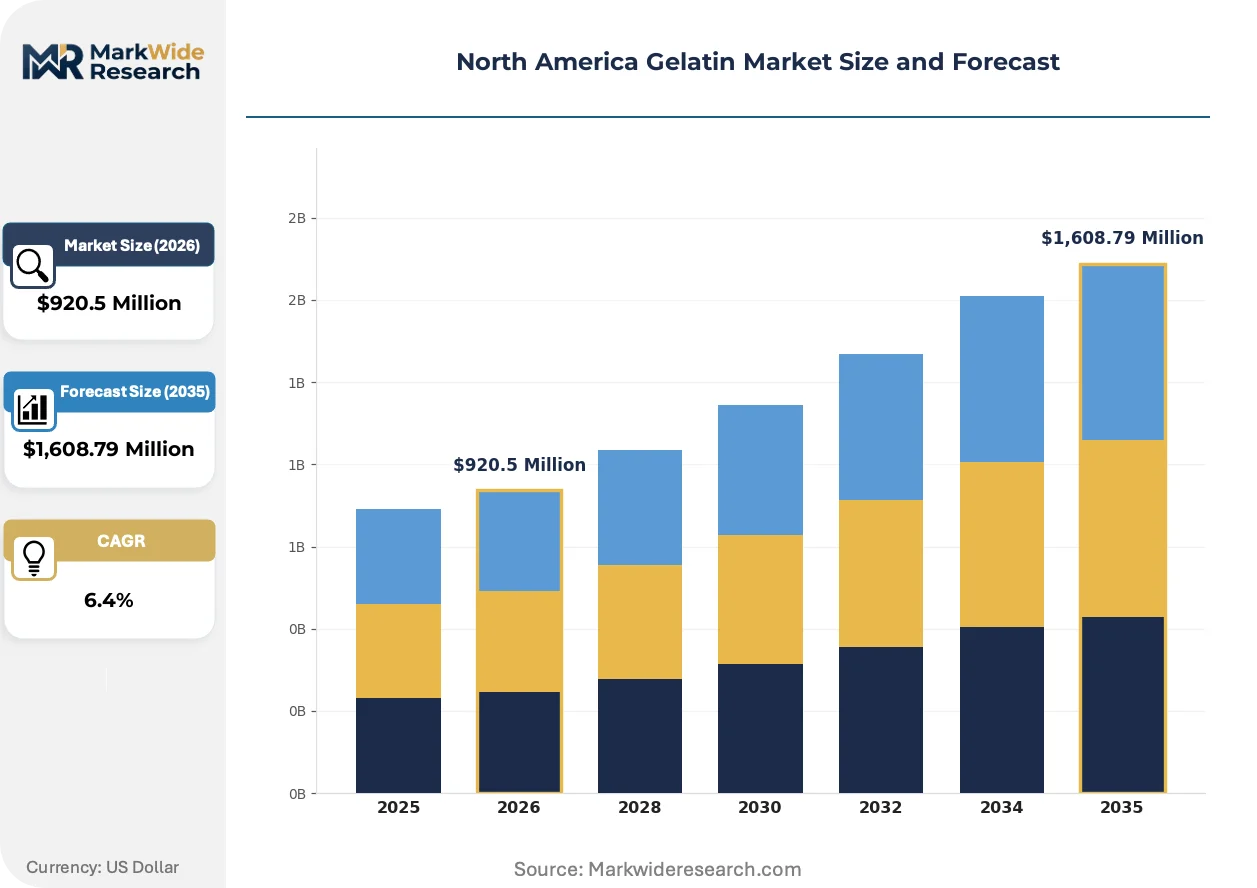
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,608.79 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Sheets, Capsules, Films Application: Pharmaceutical, Confectionery, Photography, Cosmetics, Pet Food End User: Food & Beverage Manufacturers, Cosmetic Brands, Pharmaceutical Companies, Pet Food Producers Distribution Channel: Direct Sales, Distributors, E-commerce, Retailers, Wholesalers |
| Companies Covered | Darling Ingredients, Gelita AG, Nitta Gelatin, PB Leiner, Tessenderlo Group, Rousselot, Weishardt, Ewald Gelatin, Italgelatine, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gelatin Market Strategic Shifts & Innovations
Pharmaceutical capsule manufacturing is undergoing specification stratification as endotoxin testing sensitivity advances and plant-based alternatives carve parallel supply channels. Three active developments are restructuring competitive positioning.
Enzymatic hydrolysis control technology is migrating from batch processing to continuous-flow reactor systems. Capsule manufacturers in the eastern United States are adopting real-time molecular weight monitoring to reduce gel strength variability. This precision is compressing rejected batch rates and enabling just-in-time raw material procurement.
Health Canada updated its Natural Health Product gelatin sourcing guidelines in parallel with FDA dietary supplement labeling revisions. Dual-jurisdiction manufacturers must maintain separate documentation streams for bovine spongiform encephalopathy traceability. The compliance burden falls heaviest on mid-tier contract manufacturers without dedicated regulatory affairs functions.
Direct material sourcing from rendering facilities is replacing distributor-mediated procurement for large capsule producers. Purchasing departments at pharmaceutical companies are establishing approved supplier lists that bypass traditional gelatin traders. This disintermediation is most advanced in the Midwest, where meat processing byproduct supply chains enable captive sourcing relationships.
North America Gelatin Market Segmentation
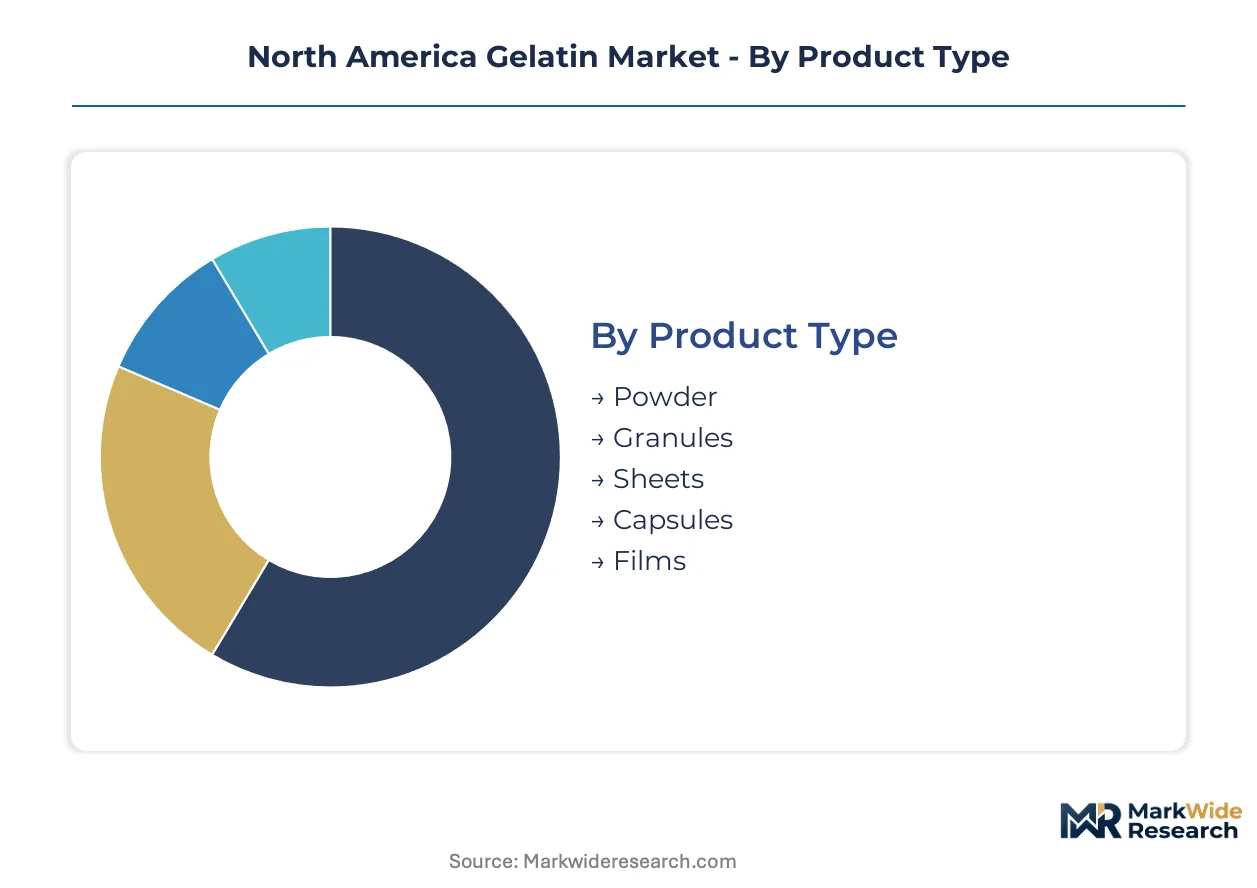
Segmentation in the North America Gelatin Market reveals how specification intensity and end-use certification requirements fragment supply relationships. Pharmaceutical-grade purity standards command premium positioning, while food-grade volumes anchor throughput economics.
Product Type:
Mature formats dominate industrial handling efficiency, while emerging formats serve precision applications.
- Powder:Fine-milled particles with standardized mesh sizes enable rapid dissolution in batch processing. Food & Beverage Manufacturers in the United States Midwest specify powder for gummy confectionery production where thermal processing demands consistent hydration kinetics.
- Capsules:Two-piece hard shells and softgel formulations require endotoxin-controlled gelatin meeting USP-NF monographs. Pharmaceutical Companies in New Jersey and Pennsylvania are expanding capsule-grade procurement as FDA dietary supplement labeling requirements tighten purity documentation.
- Granules:Intermediate particle size reduces dusting during pneumatic transfer systems. Pet Food Producers specify granules for coating applications on extruded kibble.
- Sheets:Standardized bloom-strength layers serve artisan confectionery and culinary applications. Specialty bakeries in Quebec and Ontario import sheet gelatin for mousse and aspic formulations.
- Films:Thin, transparent barriers function as edible packaging and capsule banding. Nutraceutical contract manufacturers in California are testing film-grade gelatin for single-dose strip packaging.
Powder retains volume leadership; Capsules holds the steepest expansion curve.
Application:
Cost tiers separate commodity-grade uses from certified pharmaceutical and specialty segments.
- Pharmaceutical:Encapsulation, tablet binding, and plasma expander applications require USP-grade material with documented BSE/TSE traceability. FDA Current Good Manufacturing Practice enforcement is compressing the approved supplier base for capsule manufacturers.
- Confectionery:Gummy candies, marshmallows, and aerated desserts exploit thermoreversible gelation. Hershey and Mars Wrigley facilities in Illinois and Pennsylvania source type A gelatin for consistent melt profiles.
- Photography:Silver halide emulsion binding represents a declining but specification-locked segment. Rochester-area coating operations maintain dedicated gelatin purification lines.
- Cosmetics:Collagen-derived peptides in topical formulations and hair care products. L'Oréal and Estée Lauder R&D centers in New Jersey specify hydrolyzed grades for skin penetration claims.
- Pet Food:Palatability enhancers and nutritional supplements for companion animals. Mars Petcare and Nestlé Purina operations in Kansas and Tennessee drive type B gelatin demand from regional rendering supply chains.
Confectionery retains volume leadership; Pharmaceutical holds the steepest expansion curve.
End User:
Customer type determines procurement scale and specification stringency, from bulk commodity tenders to validated supplier relationships.
- Pharmaceutical Companies:Multinational drug manufacturers and generic houses require audited supply chains with documented viral inactivation steps. Pfizer, Johnson & Johnson, and Teva facilities in Puerto Rico and the continental United States are consolidating approved vendor lists.
- Food & Beverage Manufacturers:Confectionery giants and private-label producers purchase high-volume, food-grade material. Mondelez and Ferrero operations in Chicago and Toronto specify bloom strength ranges for product texture consistency.
- Cosmetic Brands:Prestige and mass-market skincare formulators seek hydrolyzed collagen for anti-aging positioning. The Ordinary and Drunk Elephant parent companies in New York and Toronto are specifying marine and bovine peptide sources.
- Pet Food Producers:Premium and therapeutic pet nutrition manufacturers use gelatin for coating and binding. Champion Petfoods and Mars Petcare facilities in Alberta and Ohio source regionally rendered material.
Food & Beverage Manufacturers retain volume leadership; Pharmaceutical Companies holds the steepest expansion curve.
Distribution Channel:
Supply concentration favors direct relationships near rendering infrastructure, while fragmented channels serve smaller accounts.
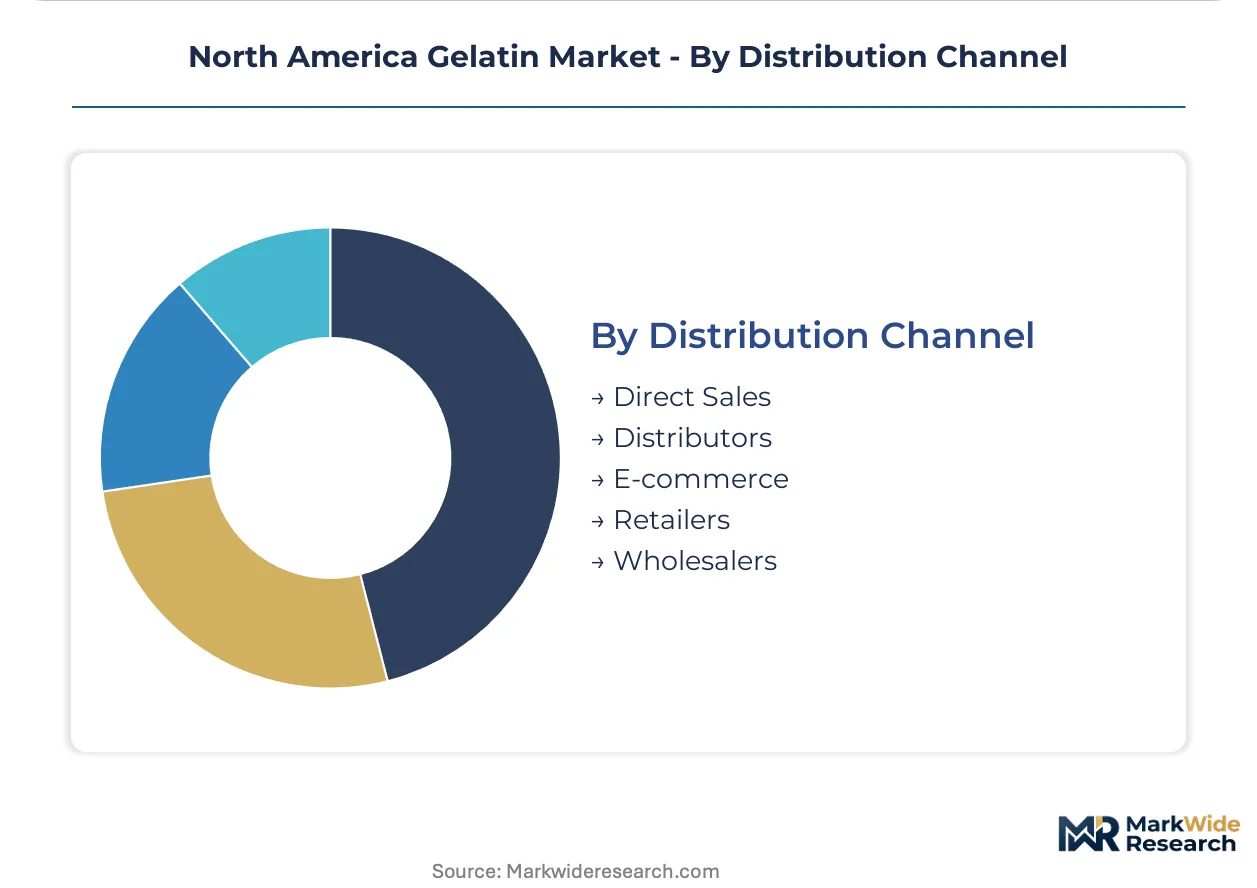
- Direct Sales:Large-volume pharmaceutical and food manufacturers contract directly with gelatin producers. Capsule manufacturers in New Jersey and Pennsylvania are bypassing distributors to secure type B supply from Midwest rendering operations.
- Distributors:Regional chemical and ingredient distributors serve mid-tier manufacturers without procurement scale. Univar Solutions and Brenntag operations in Texas and California stock food-grade gelatin for smaller confectionery accounts.
- E-commerce:Direct-to-consumer supplement brands and artisan food producers source small-lot specialty grades. Amazon Business and specialty ingredient platforms are gaining share among nutraceutical startups in Austin and Boulder.
- Retailers:Foodservice and craft supply channels for sheet and powder formats. Restaurant depot and bakery supply stores in Montreal and Vancouver serve culinary professionals.
- Wholesalers:Traditional bulk ingredient merchants serving regional food manufacturers. Remaining wholesale operations in the Great Lakes region consolidate smaller orders for independent candy producers.
Direct Sales retains volume leadership; E-commerce holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across North American gelatin demand. Pharmaceutical buyers absorb premium costs for endotoxin-certified grades, while confectionery manufacturers benchmark aggressively against plant-based alternatives. Regional supply clusters track meat processing infrastructure density.
United States
Midwest rendering operations in Iowa, Nebraska, and Kansas supply cost-advantaged type B gelatin feedstock. FDA Current Good Manufacturing Practice enforcement tightens endotoxin specifications for capsule manufacturers. New Jersey and Pennsylvania pharmaceutical clusters requalify supplier bases under updated purity documentation requirements.
Canada
Health Canada Natural Health Product regulations drive certified-ingredient demand that domestic purification capacity has not yet matched. Cross-border certification timelines compress as manufacturers serving both markets navigate divergent BSE/TSE traceability documentation. Ontario and Quebec nutraceutical contract manufacturers source increasingly from US Midwest rendering networks.
Mexico
Growing pet food manufacturing in Querétaro and Guanajuato pulls gelatin demand for palatability coatings. COFEPRIS pharmaceutical regulations align gradually with FDA standards, easing ingredient import pathways. Northern border states concentrate confectionery production serving US private-label accounts.
North America Gelatin Market Key Industry Players
Vertically integrated renderers and specialized gelatin pureurs split the North American market along feedstock control versus specification intensity lines. Darling Ingredients exemplifies the upstream-integrated archetype through captive rendering and collagen recovery infrastructure. Gelita AG and Nitta Gelatin occupy the technology-specialist tier, differentiating through hydrolyzed peptide R&D and film-forming grade precision. Competitive dynamics center on direct sourcing relationships displacing distributor channels, and enzymatic hydrolysis control investments reducing batch variability.
Within the integrated-processor tier, Darling Ingredients anchors cost leadership through backward integration into rendering operations. Gelita AG and Nitta Gelatin exemplify the specification-driven specialist archetype, occupying positions defined by pharmaceutical-grade certification depth rather than volume scale. These three companies represent the strategic poles—feedstock security versus purity premium—around which mid-tier competitors must position.
| Leading Market Players |
|---|
| Darling Ingredients |
| Gelita AG |
| Nitta Gelatin |
| PB Leiner |
| Tessenderlo Group |
| Rousselot |
| Weishardt |
| Ewald Gelatin |
| Italgelatine |
| Others |
Cost & Logistics Intelligence
Rendering capacity utilization in the US Plains states, particularly Iowa and Nebraska, sits above regional breakeven thresholds and is compressing spot pricing for type B gelatin feedstock while forcing smaller pureurs toward contract offtake commitments with meat processors.
Pricing Analysis
After-sales service contracts for endotoxin testing and batch certification now drive lifetime value for pharmaceutical-grade suppliers. Three-tier pricing structure across pharmaceutical, food-grade, and technical tiers separates certified capsule material from commodity confectionery gelatin. Pricing pressure stems from plant-based capsule substitution in vegan supplement segments. Confectionery manufacturers exhibit highest price sensitivity and benchmark aggressively against hydrocolloid alternatives, while pharmaceutical buyers absorb premiums for USP-grade certification.
Supply Chain Analysis
Cattle hide and bone supply from US Midwest rendering operations anchors North American type B gelatin production. Bovine raw material flows from Nebraska, Kansas, and Iowa feedstock networks; alkali processing chemicals and enzymatic hydrolysis reagents complete input dependencies. Single-source vulnerability concentrates in regional rendering facility consolidation. Distribution runs through direct procurement relationships for large capsule manufacturers, with chemical distributors serving mid-tier accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where direct-to-capsule-manufacturer sourcing platforms are disintermediating traditional gelatin traders, driven by real-time batch certification data interoperability between rendering facilities and pharmaceutical quality systems.
For Market Incumbents: Harden supplier lock-in through exclusive rendering agreements with Plains states meat processors facing EPA emission control upgrade costs. Deepen certification depth for dual FDA-Health Canada jurisdiction compliance as cross-border nutraceutical manufacturing expands. Defensive consolidation around enzymatic hydrolysis control technology reduces gel strength variability that triggers rejected batches.
For New Entrants and Emerging Players: Canadian nutraceutical contract manufacturing white-space represents the most penetrable entry point, as domestic purification capacity lags Health Canada Natural Health Product regulatory demand. Hydrolyzed collagen peptide functional food applications in sports nutrition and senior wellness segments offer second-mover positioning. Go-to-market through e-commerce subscription vitamin platforms that specify capsule-grade gelatin directly bypasses entrenched pharmaceutical distribution.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because rendering facility environmental compliance investments favor scaled operators with EPA Clean Air Act permit coverage. Acquisition targets include mid-tier pureurs with Health Canada certification gaps that US Midwest integrated processors can fill. Watch for FDA endotoxin specification tightening as inflection signal compressing approved vendor bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering | Darling Ingredients demonstrates how captive bovine feedstock supply secures cost leadership in type B gelatin. |
| Pharmaceutical-Grade Certification Investment | USP-NF monograph compliance and endotoxin testing capacity open capsule manufacturer procurement channels. |
| Hydrolyzed Collagen Peptide R&D | Gelita AG's nutraceutical applications expand addressable market beyond traditional thermoreversible gel uses. |
| Direct Sourcing Platform Development | Capsule manufacturers in New Jersey bypass distributors to secure Midwest rendering relationships. |
| Dual-Jurisdiction Regulatory Compliance | Parallel FDA and Health Canada documentation streams reduce cross-border product launch delays. |
Research Approach
Cross-validation between rendering facility production data and pharmaceutical capsule manufacturer procurement records anchors the qualitative findings. Primary interviews with meat processing operations managers, gelatin pureur technical directors, nutraceutical contract manufacturer quality leads, and FDA regulatory affairs consultants combined with secondary validation from USDA FSIS inspection reports, EPA Clean Air Act permit databases, Health Canada Natural Health Product guidance documents, and USP-NF monograph revisions. Bottom-up feedstock flow analysis and top-down pharmaceutical demand modeling complete triangulation.
Calibration against historical capacity utilization rates and price elasticity by grade tier shapes projection reliability. Segmentation dimensions span product type, application, end user, and distribution channel across the analysis window. CAGRs derive from fitted growth curves moderated by livestock cycle conditions and regulatory enforcement intensity. Forecast inputs include bovine raw material price volatility indices and plant-based encapsulation substitution rates.
Practitioners should monitor EPA enforcement actions on rendering facility emissions and Health Canada certification timeline changes for early signals requiring forecast revision. Cross-checking against USDA livestock inventory reports and FDA warning letter databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Casein Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Soybean Meal Market
Ingredients
Dried Distillers' Grains with Soluble Market
Ingredients
Dry Blended Products Market
Ingredients
Oyster Shell Powder Market
Ingredients
All Purpose Flour Market
Ingredients
Bouillon Cubes Market
Ingredients
North America Dairy Ingredients Market
Ingredients
Jasmine Extract Market
Ingredients
Virginiamycin Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
Pepsin Market
Ingredients
Rice Starch Market
Ingredients
North America Corn Starch Market
Ingredients
Organic Edible Oil Market