
 Soybean Meal Market | 2026-2036
Soybean Meal Market Size, Share, and Industry Trends Forecast 2026-2036
Soybean Meal Market Intelligence
The soybean meal trade is restructuring around a widening split between identity-preserved premium meal and undifferentiated commodity bulk. Cargill, Incorporated leverages its North American crush footprint to sustain premium protein consistency for branded feed customers. Bunge Global SA anchors South American origination through backward integration into Brazilian soy processing. Louis Dreyfus Company B.V. competes on ocean freight optimization and origination scale across multiple export corridors.
Soybean meal is the residual protein-rich product of solvent extraction or mechanical pressing of soybeans, typically containing 44-48% crude protein and used primarily as a livestock protein supplement in formulated feeds. Defatted soybean meal dominates volume throughput in modern crush facilities, while organic soybean meal commands margin premiums through certified supply chains and contracted offtake from specialty poultry integrators. Aquafeed application represents the fastest-expanding demand pool as salmon and shrimp producers substitute soy protein for finite fishmeal supplies.
The USDA enforces grain inspection and weighing standards that govern export quality certification, while the EU REACH framework and F-Gas Regulation constrain solvent use and emissions intensity in European crush operations. China's SAMR monitors imported soybean meal for mycotoxin thresholds and GMO traceability under national food safety protocols. Stakeholders must monitor evolving feed-to-food carbon accounting rules that threaten to reroute protein trade toward lower-emission crush origins.
Market Dynamics
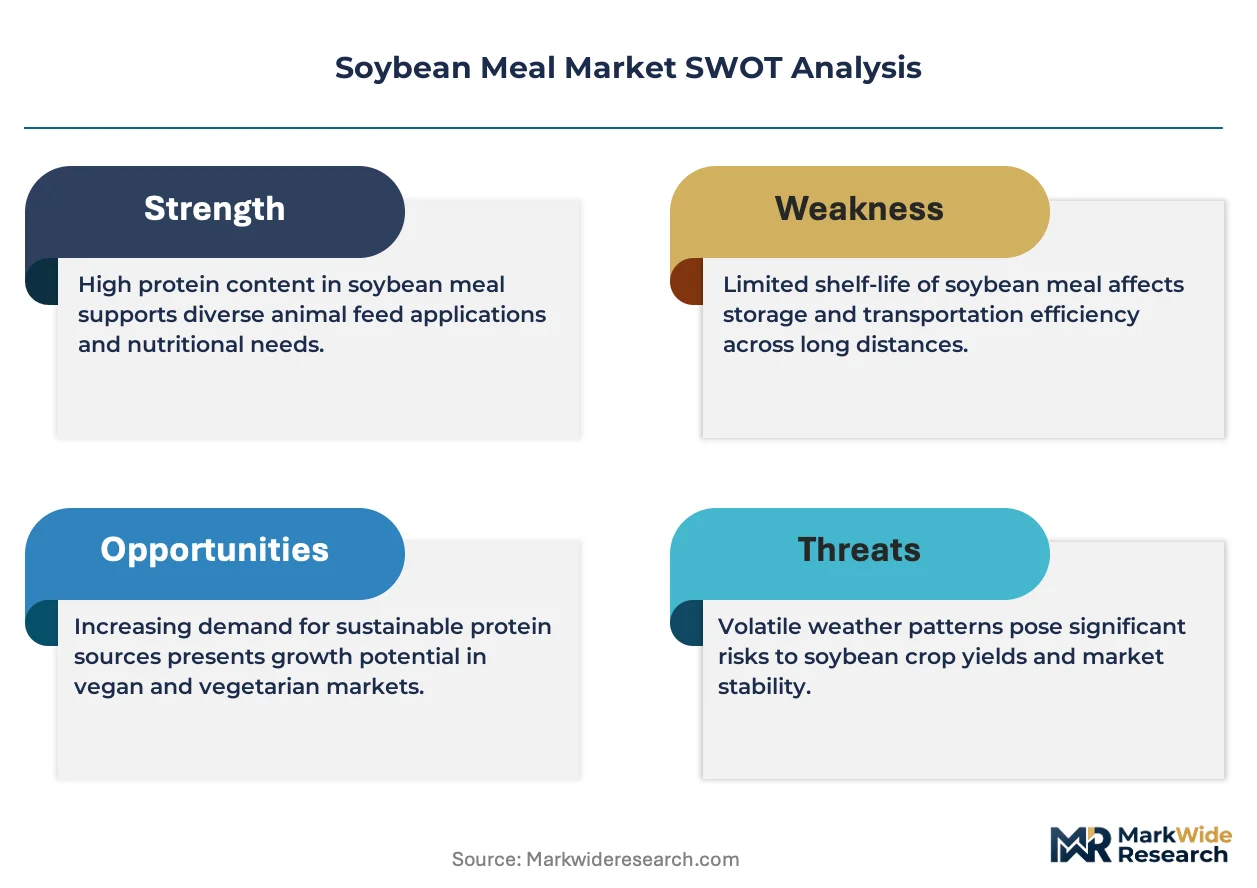
The soybean meal market is splitting into two parallel supply chains: identity-preserved premium meal for certified feed programs and undifferentiated bulk commodity flow. This bifurcation is compressing margins at the mid-tier while concentrating value capture among crush operators with verified origination control.
Growth Catalysts
- Aquaculture feed substitution:Salmon and shrimp producers in Norway and Chile are replacing finite fishmeal with soy protein concentrates. This dietary shift is pulling higher-protein meal grades into marine feed formulations.
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon solvents is forcing European crush facilities to adopt hexane recovery systems and alternative extraction methods. Compliance investment is filtering smaller processors from the supply base.
- Brazilian processing corridor expansion:Mato Grosso and Goiás states are adding solvent extraction capacity adjacent to soybean origination. Proximity crushing is reducing inland logistics costs and improving meal freshness metrics for export.
Market Restraints
- Soybean price volatility:Crush margins compress when Chicago Board of Trade soybean futures spike independently of meal demand. Feed compounders face formula cost instability that resists immediate pass-through.
- Chinese import phytosanitary barriers:SAMR mycotoxin thresholds and GMO traceability requirements create shipment rejection risk. Exporters must maintain dual-certified supply chains to access this demand pool.
- Single-cell protein substitution:Fermented microbial biomass from companies like Unibio and Calysta is displacing soy meal in premium aquafeed rations. Protein equivalence at lower carbon intensity threatens volume growth in coastal markets.
Strategic Opportunities
- Organic certification premiums:Specialty poultry integrators in the US Midwest and France are contracting dedicated organic meal supply. Price spreads between certified and conventional meal justify segregated handling infrastructure.
- Carbon-accounted crush origination:The EU Green Deal's feed-to-food carbon tracking is creating preference for Brazilian meal with verified deforestation-free sourcing. Early certifiers capture contract premiums from European compounders.
- Extruded full-fat soy expansion:On-farm extrusion systems in Vietnam and Indonesia are bypassing solvent extraction entirely. Localized processing is opening meal-equivalent markets without import tariff exposure.
Industry Challenges
- Hexane recovery engineering shortage:Solvent extraction facilities require process engineers familiar with closed-loop hexane systems. Talent scarcity in Argentina and Paraguay is delaying capacity expansion timelines.
- IP-protected enzyme pre-treatment:Novozymes and DSM patent portfolios cover cell-wall disruption technologies that improve protein extractability. Licensing complexity is fragmenting technology access among regional crush operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soybean Meal Market |
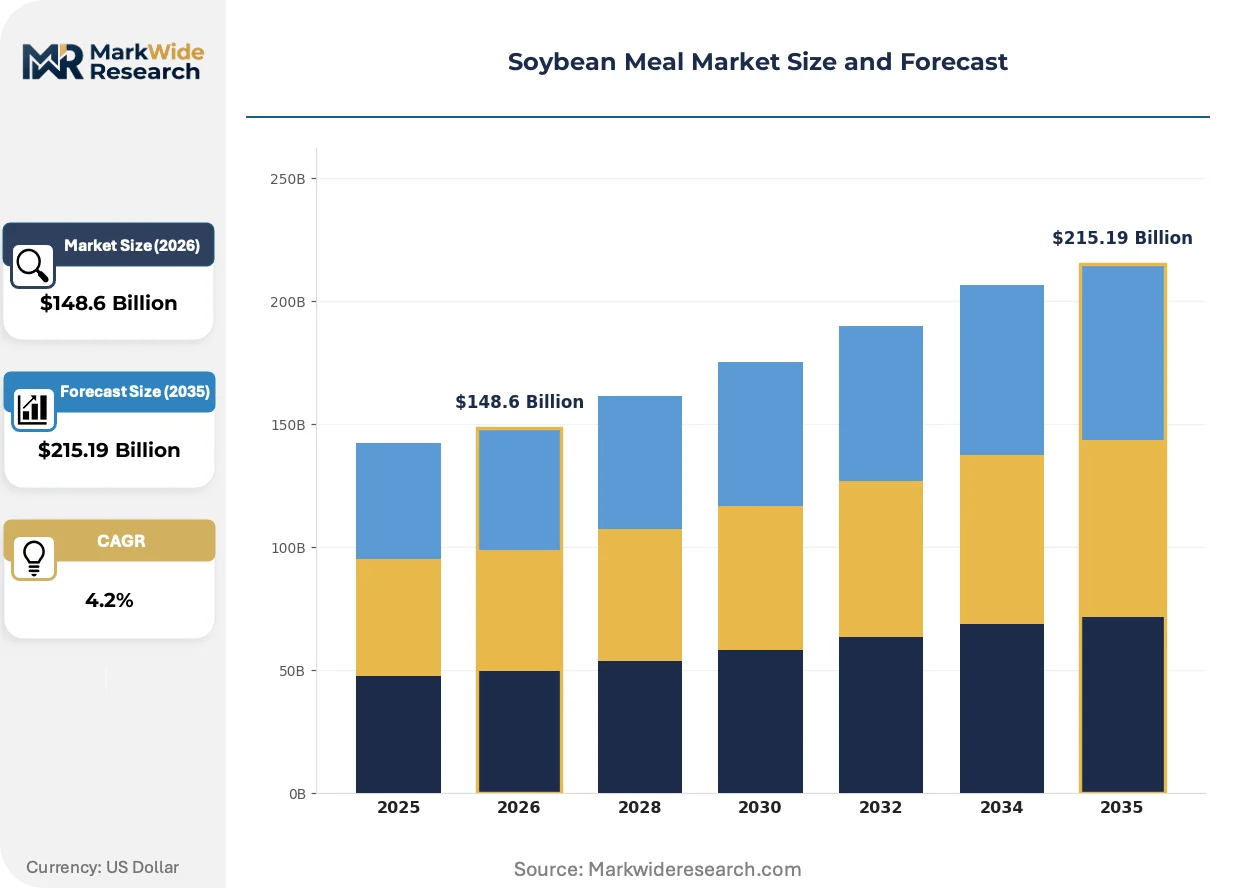
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $215.19 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Defatted Soybean Meal, Full-Fat Soybean Meal, Organic Soybean Meal, Textured Soybean Meal, Specialty Soybean Meal Application: Animal Feed, Aquafeed, Pet Food, Fertilizers, Industrial Uses End User: Poultry Farms, Swine Farms, Ruminant Feedlots, Aquaculture Farms, Pet Food Manufacturers Packaging Type: Bulk Bags, Sacks, Vacuum Packs, Paper Bags, Big Bags |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Bunge Global SA, Louis Dreyfus Company B.V., Wilmar International Limited, CHS Inc., COFCO Corporation, Ag Processing Inc, The Scoular Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soybean Meal Market Strategic Shifts & Innovations
Processing technology and regulatory carbon accounting are converging to reshape how soybean meal is extracted, certified, and traded across export corridors.
Expeller-pressed full-fat soy is unifying protein and oil retention in a single mechanical process. Southeast Asian swine producers are adopting this technology to reduce import dependency on solvent-extracted meal. The process is unifying on-farm feed milling with origination control, compressing the traditional three-stage supply chain into localized production.
REACH framework amendments are tightening solvent emission thresholds for European crush facilities. The regulation is accelerating capital deployment into hexane recovery upgrades and aqueous extraction pilots. German and Dutch processing plants are most affected, with several operators consolidating through shared infrastructure to spread compliance costs.
Compound feed manufacturers are consolidating procurement around long-term offtake contracts with named origination. This pattern is displacing spot-market purchasing in the EU and Japan. The shift is most visible among salmon feed producers in Norway, who now specify Brazilian state-level provenance in multi-year supply agreements.
Soybean Meal Market Segmentation
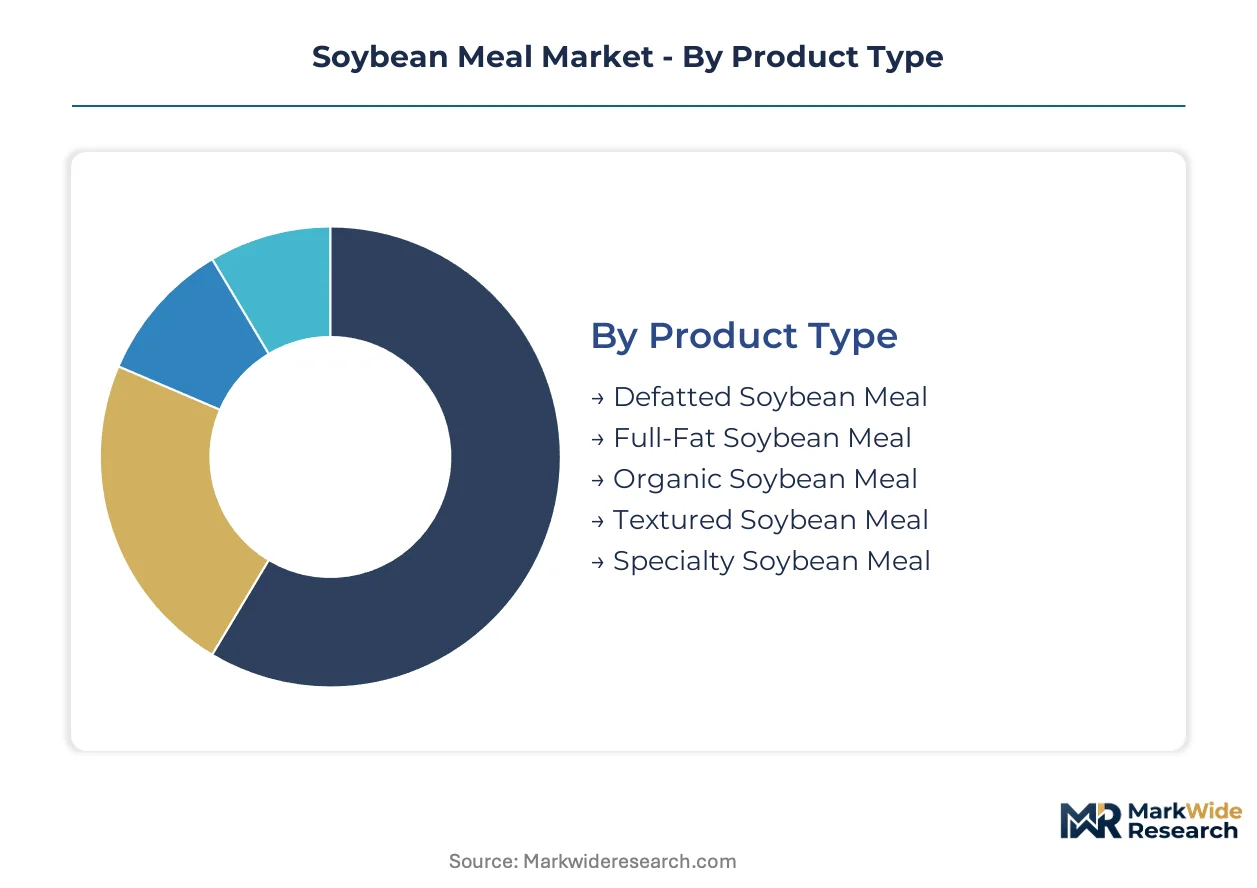
Soybean meal segmentation tracks how protein specification, feed formulation requirements, and handling economics split demand across distinct supply chains. Buyers select grades based on crude protein targets, certification needs, and integration with existing feed mill infrastructure.
Product Type:
Cost tier separates commodity processors from specialty operators in this category.
- Defatted Soybean Meal:Solvent-extracted meal containing 44-48% crude protein serves as the baseline livestock protein supplement. Volume concentrates in Brazilian export corridors supplying European and Southeast Asian compound feed mills facing formula cost pressures.
- Organic Soybean Meal:Certified non-GMO meal from segregated supply chains commands price premiums through contracted offtake. Demand clusters among specialty poultry integrators in France and the US Midwest seeking feed-to-food traceability compliance.
- Full-Fat Soybean Meal:Mechanical pressing retains oil content for energy-dense rations.
- Textured Soybean Meal:Extruded forms improve pellet durability in aquafeed applications.
- Specialty Soybean Meal:Custom protein profiles serve pharmaceutical and cosmetic extraction feedstocks.
Volume sits with defatted grades; growth tilts toward organic certification tiers.
Application:
Feed conversion efficiency and ingredient substitution economics determine adoption patterns here.
- Animal Feed:Standardized meal incorporation into poultry, swine, and ruminant rations dominates tonnage throughput. Procurement concentrates among integrated operations in Iowa, Netherlands, and Thailand where scale justifies dedicated crush supply contracts.
- Aquafeed:High-protein concentrates and enzyme-treated meals displace finite fishmeal in salmon and shrimp diets. Norwegian and Chilean marine feed producers specify Brazilian state-level provenance in multi-year sourcing agreements.
- Pet Food:Human-grade protein isolates enter premium kibble and wet food formulations.
- Fertilizers:Residual meal fractions supply organic nitrogen amendments for specialty crop operations.
- Industrial Uses:Protein hydrolysates serve adhesive and biodegradable polymer feedstocks.
Compound feed mills anchor volume; aquafeed applications climb the fastest.
End User:
Scale of operation and integration with origination shape procurement behavior across buyer types.
- Poultry Farms:Layer and broiler operations consume meal as the primary protein source in formulated feeds. Large integrators in Georgia, Arkansas, and São Paulo states backward-integrate into crush capacity to secure margin capture.
- Aquaculture Farms:Salmon, shrimp, and tilapia producers drive demand for dehulled, high-protein meal grades. Coastal operations in Vietnam and Indonesia increasingly adopt on-farm extrusion to bypass import tariffs.
- Swine Farms:Finishing operations in Iowa and Mato Grosso optimize amino acid profiles through precise meal inclusion rates.
- Ruminant Feedlots:Cattle finishing operations in Texas and Queensland incorporate meal as protein supplements in grain-based rations.
- Pet Food Manufacturers:Premium brands in Missouri and Ontario specify identity-preserved meal for label claims.
Poultry integration commands volume; aquaculture farms post the steepest expansion trajectory.
Packaging Type:
Logistics infrastructure and contamination risk tolerance differentiate handling requirements.
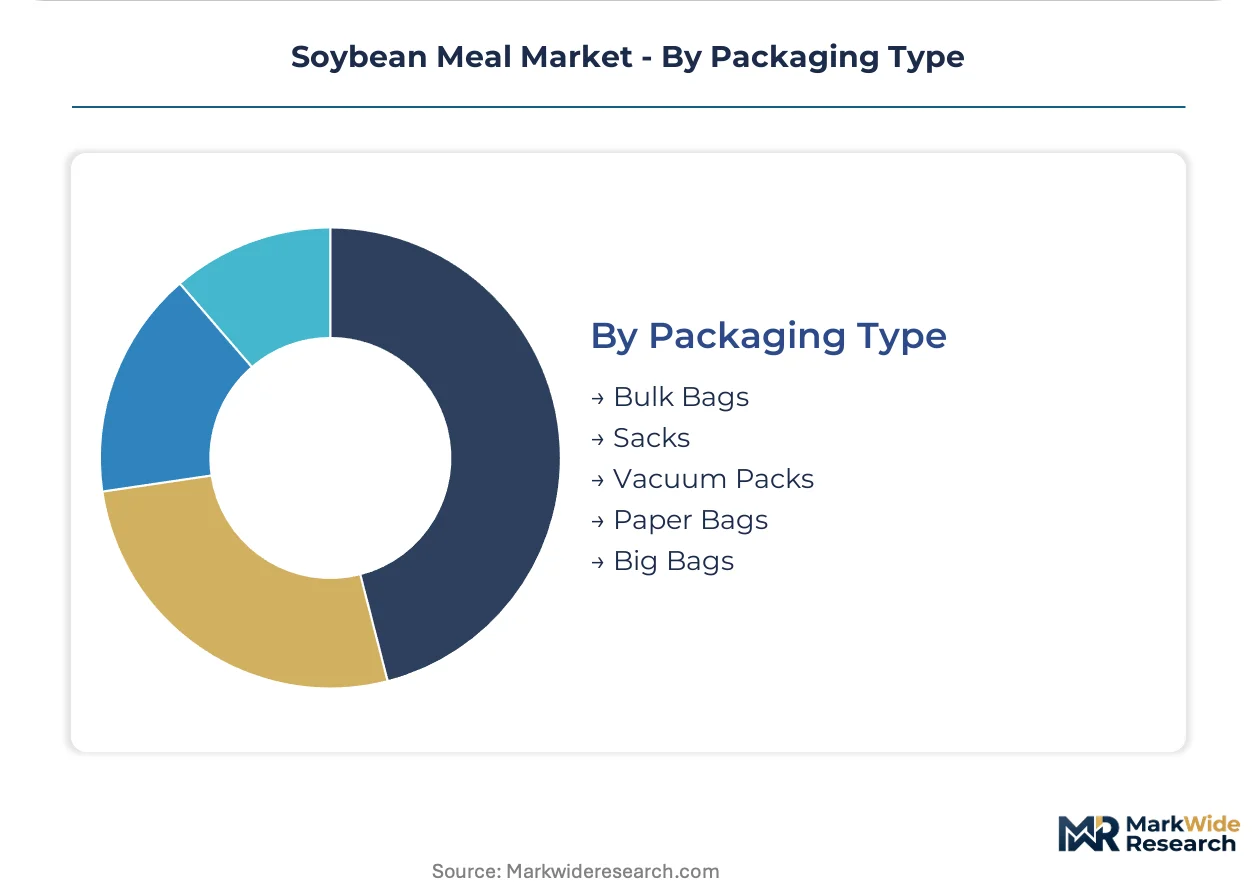
- Bulk Bags:One-ton flexible intermediate bulk containers serve integrated feed mills with pneumatic handling systems. Adoption concentrates among river-adjacent operations in Paraná state and Mississippi River terminals where vessel loading efficiency matters.
- Big Bags:Standardized two-ton units support automated batching in large compound feed facilities. European and Japanese port facilities specify these units for reduced handling labor and improved inventory tracking.
- Sacks:50-kilogram woven polypropylene bags serve smallholder distribution networks.
- Vacuum Packs:Oxygen-barrier packaging preserves amino acid stability for high-value aquafeed shipments.
- Paper Bags:Kraft multiwall constructions meet sustainability specifications in Nordic retail channels.
Flexible bulk formats capture volume; vacuum and paper alternatives gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mato Grosso's processing corridor anchors Brazilian crush capacity expansion, while demand pull concentrates in coastal aquaculture clusters and inland poultry integration belts across four additional countries.
Brazil
Aquafeed exporters in Norway and Chile source state-verified meal from Mato Grosso and Goiás crush facilities. ANVISA monitors mycotoxin thresholds under Mercosur sanitary protocols. The Barcarena port complex in Pará state is expanding dedicated meal loading terminals for Asian-bound shipments.
United States
Iowa and Illinois poultry integrators backward-integrate into crush capacity to capture margin from formula feed production. The USDA enforces grain inspection standards governing export quality certification. Mississippi River terminals at St. Louis and Memphis consolidate bulk handling for Gulf Coast vessel loading.
China
Compound feed mills in Guangdong and Shandong provinces drive import demand for high-protein meal grades. SAMR enforces GMO traceability and mycotoxin limits on inbound shipments. The Yangtze River Delta processing belt is expanding solvent extraction capacity adjacent to port infrastructure.
Argentina
European compounders source meal from Rosario corridor crush facilities facing hexane recovery engineering constraints. The national agricultural regulator oversees export phytosanitary certification under WTO sanitary agreements. Upstream Paraná River ports are deepening draft capacity for Panamax vessel loading.
Netherlands
German and French feed compounders procure through Rotterdam terminals subject to REACH solvent emission thresholds. ECHA compliance is filtering smaller crush operators from European supply chains. The Europoort industrial zone is consolidating shared hexane recovery infrastructure to spread compliance capital deployment.
Soybean Meal Market Key Industry Players
Premium-margin players sit above commodity-margin players across origination control and certification capability. The soybean meal market concentrates among multinational agricultural conglomerates with integrated crush-to-export infrastructure. Three archetypes dominate: North American integrators with premium protein consistency, South American originators with backward processing control, and Asian traders with ocean freight optimization. Competitive moves center on capacity expansion in Brazilian processing corridors and carbon-accounted supply chain certification for European offtake.
Within the multinational trading tier, Cargill, Incorporated and Bunge Global SA exemplify divergent geographic anchoring strategies, while Louis Dreyfus Company B.V. occupies a position emphasizing logistics-scale competitiveness across multiple export corridors. These three entities represent the dominant competitive archetypes: North American crush footprint leverage, South American origination integration, and freight-optimized trading scale respectively.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Bunge Global SA |
| Louis Dreyfus Company B.V. |
| Wilmar International Limited |
| CHS Inc. |
| COFCO Corporation |
| Ag Processing Inc |
| The Scoular Company |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's feed-to-food carbon tracking gates qualified supply access and premium-tier pricing for Brazilian crush operators with verified deforestation-free origination. Buyers without certified provenance face exclusion from European compounder procurement while certified suppliers capture contract premiums through segregated handling infrastructure.
Pricing Analysis
Value-based pricing anchored to feed conversion efficiency and amino acid digestibility separates premium meal grades from commodity bulk. Three-tier pricing structure across identity-preserved organic, certified deforestation-free, and undifferentiated commodity levels reflects certification investment and origination control. Cost compression in mid-tier conventional grades is intensifying as Brazilian processing corridor expansion adds solvent extraction capacity. Integrated poultry operations in Iowa and São Paulo states exhibit lowest price sensitivity due to backward integration into crush capacity, while independent feed compounders in Southeast Asia face formula cost instability that resists immediate pass-through.
Supply Chain Analysis
Hexane solvent recovery and aqueous extraction pilot returns reshape European crush facility economics under REACH emission thresholds. Geographic supply concentration centers on Brazil, the United States, and Argentina as dominant origination and processing hubs. Raw material flows draw from Mato Grosso soybean belts, Mississippi River grain corridors, and Paraná River port terminals. Single-source vulnerability runs through Brazilian inland logistics chokepoints during rainy season transport disruptions. Distribution runs through river-adjacent bulk terminals consolidating vessel loading for Asian and European bound shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where crush operators pursue upstream origination control to capture margin from formula feed production and secure carbon-accounted supply chain certification.
For Market Incumbents: Deploy state-level provenance verification systems to defend European offtake contracts against emerging Brazilian processing corridor entrants. Single-cell protein substitution from Unibio and Calysta threatens volume growth in premium aquafeed rations. Incumbents should consolidate hexane recovery engineering talent in Argentina and Paraguay where talent scarcity delays competitor expansion timelines. Certification investment in deforestation-free origination creates channel control over EU Green Deal compliant supply chains. For New Entrants and Emerging Players: Capture organic certification tier demand from specialty poultry integrators in France and the US Midwest where price spreads justify segregated handling infrastructure. White-space targets include on-farm extrusion system deployment in Vietnam and Indonesia bypassing import tariffs through localized full-fat soy processing. The most penetrable segment sits with aquaculture farms adopting extruded meal-equivalent production. Go-to-market positioning should emphasize carbon-accounted crush origination for European compounder procurement panels. For Investors and Strategic Acquirers: Brazilian state-level crush capacity announcements are the leading indicator that origination control premiums will compress toward logistics-scale competitiveness. Long-term viability favors operators with integrated crush-to-export infrastructure spanning multiple export corridors. Acquisition targets should screen for hexane recovery engineering capabilities and ANVISA or SAMR dual-certification infrastructure. Monitor EU F-Gas Regulation phasedown timelines for signals on European compliance capital deployment intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origination | Captures margin from formula feed production in Iowa and São Paulo integration belts. |
| Carbon-Accounted Certification Investment | Secures contract premiums from European compounders under EU Green Deal tracking rules. |
| Hexane Recovery System Deployment | Filters smaller processors from European supply chains under REACH emission thresholds. |
| State-Level Provenance Contracting | Norwegian salmon feed producers now specify Brazilian state-level sourcing in multi-year agreements. |
| Aqueous Extraction Pilot Scaling | Alternative processing methods reduce solvent dependency and F-Gas Regulation compliance burden. |
Research Approach
Independent corroboration across crush facility operations directors, compound feed procurement managers, and aquafeed formulation specialists underwrites the qualitative findings. Primary interviews with Brazilian processing corridor engineers, European REACH compliance officers, and Asian trading house logistics heads combined with secondary validation from customs trade data, ANVISA sanitary protocols, and SEC 10-K crush margin disclosures. Bottom-up capacity installation tracking and top-down trade flow analysis triangulate volume estimates across export corridors.
Comparable-period anchoring to historical crush margin cycles and protein substitution adoption curves shaped the forecast window construction. Segmentation modeling spans product type tiers, application feed conversion requirements, end-user integration scale, and regional regulatory framework clusters. CAGRs were derived from protein demand elasticity coefficients and capacity expansion timelines across the projection horizon. Industry-specific inputs include fishmeal substitution rates in Norwegian and Chilean aquafeed formulations and hexane recovery capital deployment schedules under EU F-Gas phasedown mandates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese SAMR phytosanitary barrier adjustments and single-cell protein cost parity achievements. Forecasts reflect documented assumptions on Brazilian inland logistics cost trajectories and EU carbon border adjustment implementation scope. Practitioners should monitor ANVISA mycotoxin threshold revisions and Paraná River draft deepening completion for early signals on South American export corridor competitiveness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Brazil Corn Syrup Market
Ingredients
Mustard Oil Market
Ingredients
Global Malt Extracts and Ingredients Market
Ingredients
Global Infant Nutrition Ingredients Market
Ingredients
Corn Peptide Market
Ingredients
Global Starch Derivatives Market
Ingredients
North America Cheese Powder Market
Ingredients
Amylase Market
Ingredients
Cocoa Derivatives Market
Ingredients
Casein Hydrolysate Market
Ingredients
Food Colors Market
Ingredients
Low Fat Cooking Oil Market
Ingredients
North America Carrageenan Market
Ingredients
Organic Edible Oil Market
Ingredients
Global Edible Oil Market
Ingredients
Fermented Ingredients Market