
 Casein Market | 2026-2036
Casein Market Size, Share, and Industry Trends Forecast 2026-2036
Casein Market Intelligence
Membrane filtration technology is reshaping casein extraction economics, cutting water use and improving protein recovery rates. Fonterra Co-operative Group Limited anchors Oceania supply through its farmer-owned cooperative structure. Kerry Group leverages its ingredient systems expertise to embed caseinates into functional beverage formulations. Glanbia plc specializes in sports nutrition channels, extending its reach through direct-to-consumer protein brands.
Casein denotes a family of phosphoproteins comprising approximately 80 percent of bovine milk protein, precipitated through acidification or enzymatic rennet action to yield functional isolates with emulsifying, gelling, and slow-digestion properties. Acid casein retains strong adhesive and paper-coating demand, though micellar casein captures expanding premium positioning in overnight recovery supplements. Bakery applications remain mature with thin margins, while nutraceutical companies drive value growth through clinical-grade micellar isolates.
EFSA governs nutrition and health claims on casein products across Europe, constraining label language and substantiation requirements. FDA GRAS status and USDA dairy grading standards shape US market access and quality benchmarks. Stakeholders must monitor evolving protein sustainability certifications and carbon accounting rules that will soon differentiate supplier eligibility in European procurement frameworks.
Market Dynamics
Membrane filtration upgrades are compressing extraction costs while EU Green Deal emissions standards force dairy processors into capital-intensive retrofits, restructuring competitive economics across the value chain.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down mandates are accelerating heat pump adoption in dairy processing plants, cutting energy intensity in German and French casein facilities.
- Sports nutrition manufacturers:Protein supplement brands are expanding casein procurement as overnight recovery formulations displace whey-dominant portfolios in North American and Asian markets.
- Micellar casein isolation:Advanced ceramic membrane systems are enabling 90%+ protein purity in single-pass operations, unlocking clinical-grade applications previously reserved for whey isolates.
Market Restraints
- Skim milk powder price volatility:Casein extraction economics remain tethered to commodity dairy cycles, with input cost swings compressing processor margins during trough periods.
- Oceania supply concentration:Farmer-owned cooperative structures in New Zealand and Australia create procurement bottlenecks for European and North American ingredient buyers seeking volume security.
- Plant protein substitution:Pea and fava protein isolates are capturing clean-label positioning in bakery and beverage applications, constraining acid casein volume growth in mature segments.
Strategic Opportunities
- German ingredient innovation clusters:Cologne and Hamburg R&D hubs are incubating enzymatic modification technologies for clean-label caseinate development targeting premium nutrition markets.
- Clinical nutrition applications:Micellar casein's slow-digestion kinetics are opening enteral and geriatric nutrition formulations, segments historically dominated by hydrolyzed proteins.
- Carbon accounting integration:EU CSRD disclosure requirements are creating first-mover advantage for processors with verified Scope 3 dairy sourcing, differentiating supplier eligibility in procurement frameworks.
Industry Challenges
- Membrane engineering talent scarcity:Dairy processors face recruitment gaps for ceramic filtration system operators and process optimization specialists, delaying technology rollout timelines.
- EFSA health claim substantiation:Clinical trial requirements for muscle protein synthesis claims extend product development cycles and elevate R&D expenditure thresholds for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Casein Market |
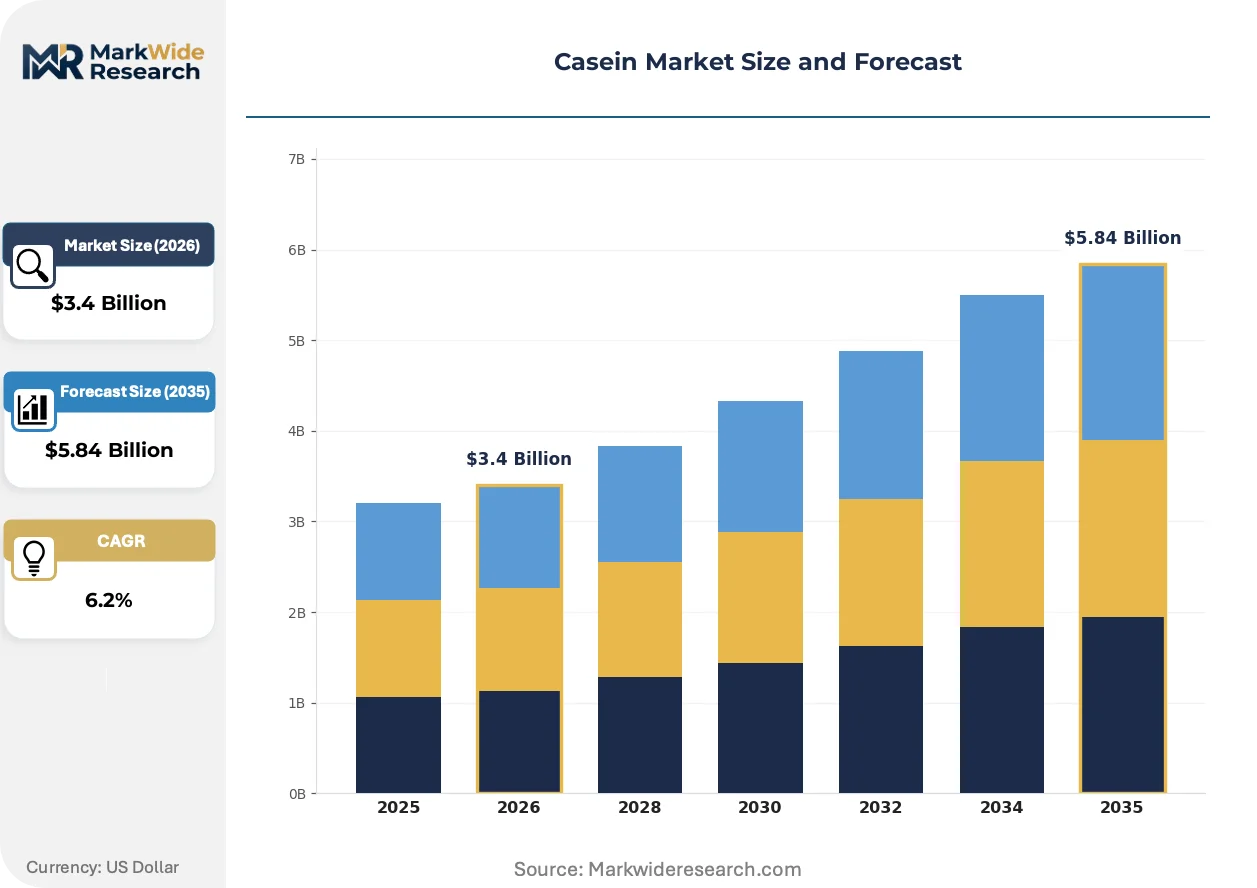
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micellar Casein, Caseinates, Acid Casein, Rennet Casein Application: Dairy Products, Protein Supplements, Bakery Products, Processed Foods Distribution Channel: Online Retail, Hypermarkets, Specialty Stores, Wholesalers Customer Type: Food Manufacturers, Fitness Enthusiasts, Nutraceutical Companies, Research Institutions |
| Companies Covered | Nestlé S.A., Kerry Group, Fonterra Co-operative Group Limited, Glanbia plc, FrieslandCampina Ingredients, Arla Foods Ingredients Group P/S, Danone S.A., Lactalis Ingredients, Saputo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Casein Market Strategic Shifts & Innovations
Digital twin modeling and enzymatic modification platforms are converging to compress formulation cycles, while regulatory carbon accounting is embedding sustainability metrics into procurement specifications.
Cross-flow ceramic membrane systems are virtualizing traditional acid precipitation workflows by enabling continuous micellar separation without chemical reagents. Sports nutrition contract manufacturers in the United States and Germany are adopting these systems at accelerated pace to meet clean-label demand. This virtualization is compressing capital recovery timelines while eliminating effluent treatment burdens associated with conventional acid casein production.
The EU F-Gas Regulation's hydrofluorocarbon phase-down is forcing dairy processors to retrofit refrigeration infrastructure with ammonia or CO2-based systems. Industrial consequence includes extended plant downtime and temporary supply constraints during conversion windows. German and Dutch casein facilities are responding by clustering retrofit investments with membrane filtration upgrades to minimize operational disruption.
Direct-to-consumer protein brands are consolidating procurement volumes through long-term offtake agreements with named processors, bypassing traditional ingredient distributor channels. This channel compression is most visible in North American sports nutrition, where vertically integrated brands are securing micellar casein supply through captive relationships rather than spot market purchases. The shift is elevating price transparency while compressing distributor margins in legacy supply chains.
Casein Market Segmentation
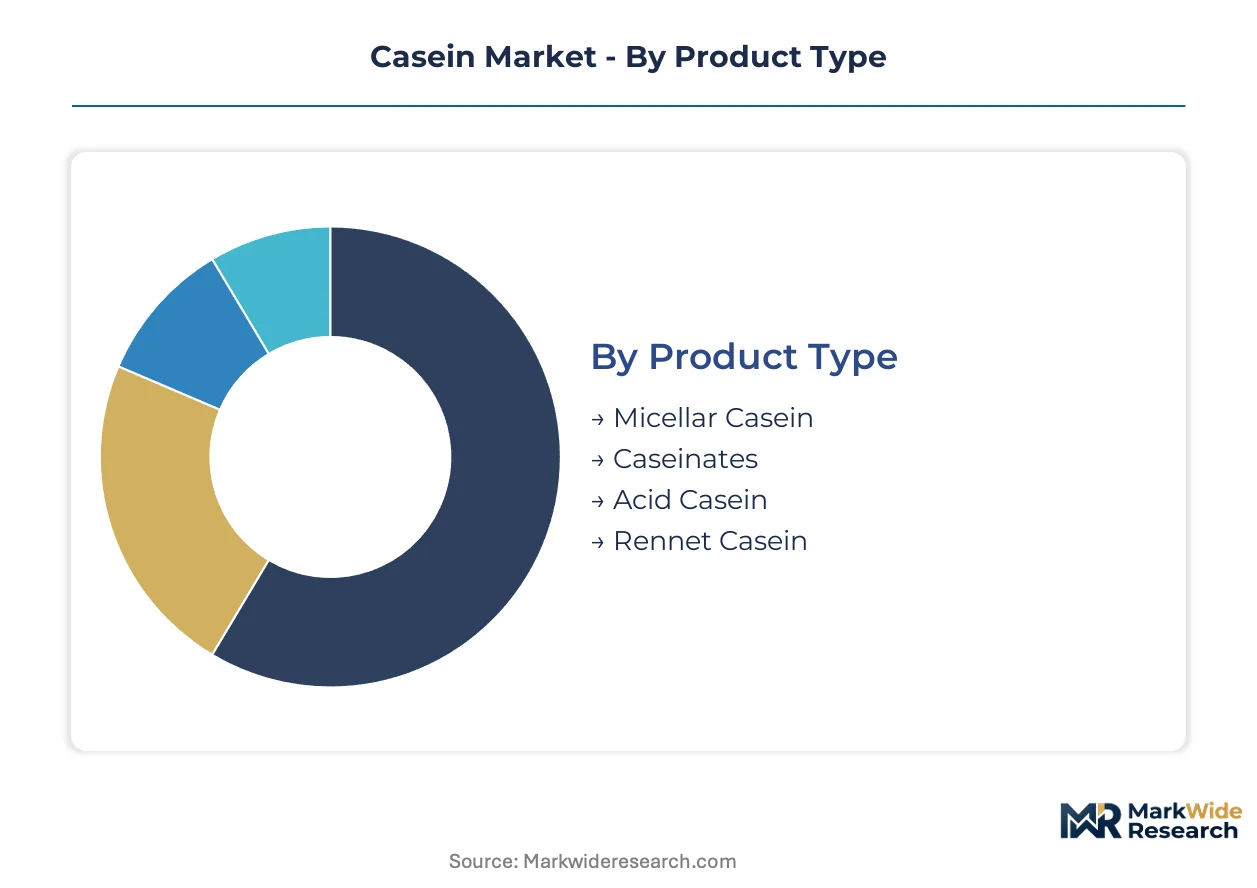
Casein segmentation reveals distinct profit pools across extraction chemistry and end-use application. Product type determines margin structure, while distribution channel shifts expose channel compression risks from direct procurement trends.
Product Type:
Mature acid and rennet grades anchor volume, while micellar isolates and functional caseinates command premium positioning through clinical-grade specifications.
- Micellar Casein:Native protein structure preserved through ceramic membrane filtration delivers 90%+ purity with intact micellar architecture. Overnight recovery supplements in North American sports nutrition concentrate procurement here, driven by slow-digestion kinetics that extend amino acid availability. This segment handles the majority of throughput; caseinates are the fastest mover on share.
- Caseinates:Soluble salts of acid casein (sodium, calcium, potassium) engineered for emulsification and water-binding in functional beverages. German ingredient clusters in Cologne and Hamburg drive enzymatic modification R&D targeting clean-label positioning.
- Acid Casein:Isoelectric precipitation at pH 4.6 yields adhesive-grade protein for paper coating and industrial binders. Pea protein substitution constrains volume expansion in mature bakery applications.
- Rennet Casein:Chymosin-coagulated curd with superior melting properties for processed cheese analogs. Italian and French dairy processors maintain specialized production lines for pizza cheese formulations.
Acid casein handles the majority of throughput; micellar casein is expanding most quickly on clinical nutrition demand.
Application:
Volume concentrates in traditional dairy, while value migrates toward performance nutrition and medical-grade formulations.
- Protein Supplements:Overnight recovery formulations displace whey-dominant portfolios through sustained-release amino acid kinetics. Direct-to-consumer brands secure captive supply via long-term offtake agreements, bypassing distributor channels.
- Dairy Products:Processed cheese, yogurt fortification, and ice cream stabilization consume standard-grade caseinates. EFSA nutrition claim constraints limit label differentiation in European retail.
- Bakery Products:Dough conditioning and shelf-life extension in bread and pastry applications. Thin margins and plant protein substitution pressure volume growth.
- Processed Foods:Meat analogs and convenience meal systems leverage casein emulsification for texture engineering. Asian processed food manufacturers expand procurement as Western formulation standards penetrate regional markets.
Dairy products handle the majority of throughput; protein supplements are climbing the fastest on sports nutrition premiumization.
Distribution Channel:
Channel structure reflects customer scale concentration, with volume buyers consolidating procurement away from fragmented retail pathways.
- Wholesalers:Bulk ingredient distributors serving mid-tier food manufacturers and regional bakery operations. Margin compression intensifies as large accounts defect to direct processor relationships.
- Online Retail:Direct-to-consumer protein brands and small-batch nutraceutical formulators purchase micellar isolates in configurable quantities. Amazon Business and specialized ingredient platforms expand geographic reach for specialty grades.
- Hypermarkets:Private-label sports nutrition and mass-market dairy fortification products. German REWE and French Carrefour chains dominate European retail caseinate movement.
- Specialty Stores:High-performance nutrition retailers and clinical supply distributors serving geriatric and enteral nutrition segments. Pharmacist-recommended positioning commands price premiums in Japanese and South Korean markets.
Wholesalers handle the majority of throughput; online retail is gaining share fastest on channel compression trends.
Customer Type:
Procurement sophistication varies sharply across customer scale, with institutional buyers driving specification standardization.
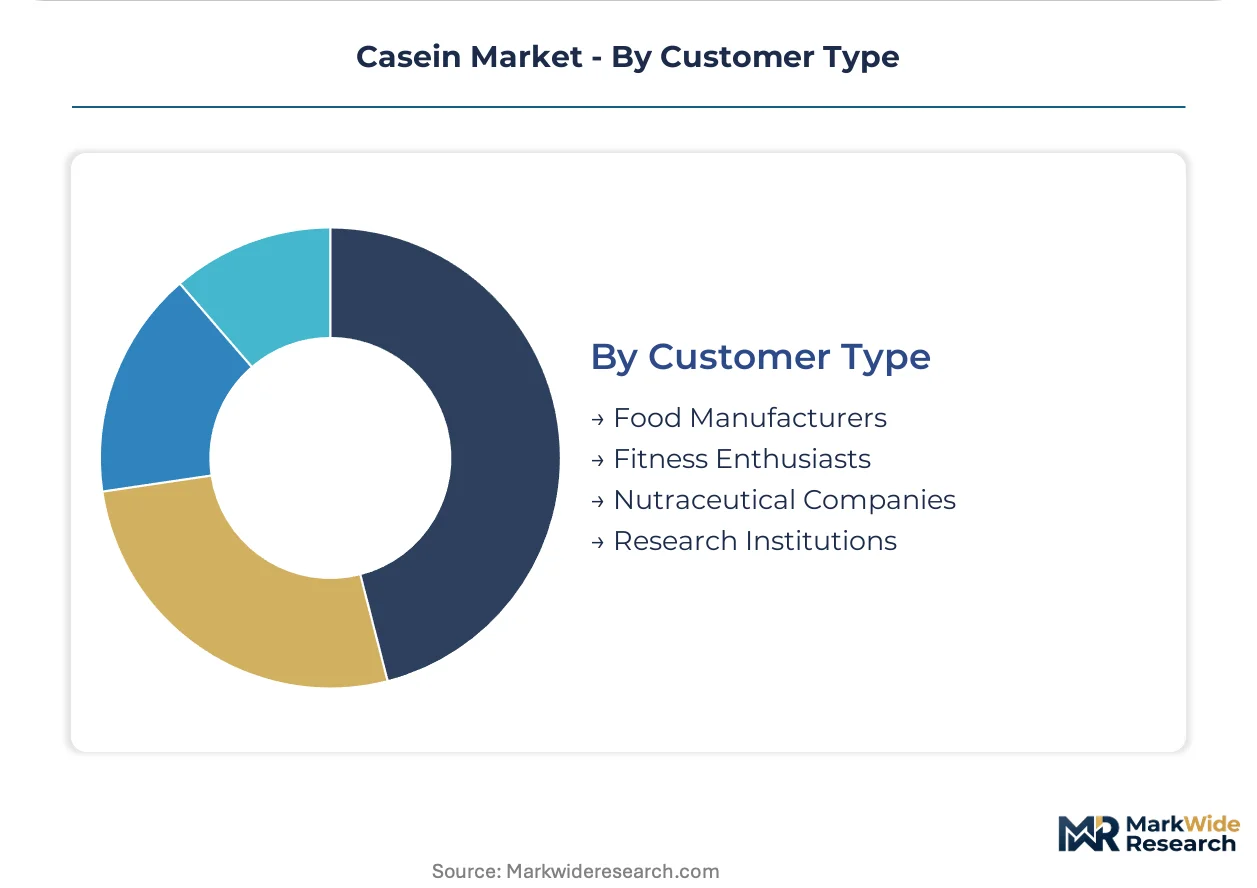
- Food Manufacturers:Multinational dairy and processed food corporations impose carbon accounting and Scope 3 verification requirements through EU CSRD-aligned procurement frameworks. Volume concentration enables formula customization and dedicated production runs.
- Nutraceutical Companies:Clinical-grade micellar casein purchasers for medical nutrition and geriatric care formulations. FDA GRAS substantiation and EFSA health claim dossiers extend product development cycles.
- Fitness Enthusiasts:Individual and small-gym procurement through direct-to-consumer channels. Price transparency from brand vertical integration erodes traditional retail markups.
- Research Institutions:Academic and contract research organizations sourcing reference-grade proteins for metabolic studies and formulation science. Small batch requirements limit supplier interest outside specialized distributors.
Food manufacturers handle the majority of throughput; nutraceutical companies are expanding most quickly on clinical nutrition applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient procurement by sports nutrition manufacturers and clinical nutrition formulators concentrates demand in Germany, the United States, New Zealand, and China. These markets anchor membrane filtration capacity and clean-label caseinate development.
United States
Direct-to-consumer protein brands consolidate micellar casein procurement through long-term offtake agreements with named processors. FDA GRAS status shapes quality benchmarks for clinical-grade isolates. California and Texas host contract manufacturing clusters adopting ceramic membrane systems for overnight recovery formulations.
Germany
Clean-label caseinate innovation drives procurement from Cologne and Hamburg R&D hubs serving premium nutrition markets. EU F-Gas Regulation mandates hydrofluorocarbon phase-downs, forcing dairy processors into ammonia-based refrigeration retrofits. Bavarian processing facilities cluster membrane filtration upgrades with emissions compliance investments.
New Zealand
Farmer-owned cooperative structures concentrate Oceania casein supply, creating procurement bottlenecks for European and North American buyers seeking volume security. Fonterra anchors export capacity through its cooperative governance model. Canterbury dairy processing zones supply clinical-grade micellar isolates to Asian nutraceutical manufacturers.
China
Processed food manufacturers expand casein procurement as Western formulation standards penetrate regional meat analog and convenience meal markets. SAMR dairy safety regulations impose traceability requirements on imported protein isolates. Yangtze River Delta ingredient distributors consolidate volumes for bakery and beverage applications.
Netherlands
Carbon accounting integration through EU CSRD disclosure requirements creates first-mover advantage for processors with verified Scope 3 dairy sourcing. FrieslandCampina and specialized ingredient traders operate from Randstad logistics corridors. North Brabant dairy facilities retrofit membrane systems alongside F-Gas Regulation compliance timelines.
Casein Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Farmer-owned cooperatives and multinational ingredient houses dominate volume procurement, while enzymatic modification specialists capture premium positioning in clean-label segments. Two strategic archetypes prevail: membrane technology-integrated processors and direct-to-consumer brand owners securing captive supply. Competitive moves concentrate on long-term offtake agreements and backward integration into dairy sourcing.
Within the cooperative archetype, Fonterra Co-operative Group Limited represents farmer-governed supply concentration, while Kerry Group exemplifies ingredient systems integration. Glanbia plc occupies a position bridging sports nutrition channels with direct-to-consumer brand ownership. These three anchors illustrate divergent pathways: cooperative supply security, formulation expertise embedding, and vertical brand control.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Kerry Group |
| Fonterra Co-operative Group Limited |
| Glanbia plc |
| FrieslandCampina Ingredients |
| Arla Foods Ingredients Group P/S |
| Danone S.A. |
| Lactalis Ingredients |
| Saputo Inc. |
| Others |
Cost & Logistics Intelligence
Skim milk powder price volatility determines both pricing tier spreads and supply chain shape, compressing processor margins during trough periods while forcing buyers toward long-term offtake agreements to secure volume certainty.
Pricing Analysis
Cost-plus contracts indexed to GDT (Global Dairy Trade) auction prices dominate micellar casein procurement, with premium-mid-economy pricing differentiation separating clinical-grade isolates from standard caseinates. Ceramic membrane filtration investment elevates purity-tier premiums, while food manufacturers impose carbon accounting verification as a price threshold for supplier eligibility. Pricing pressure stems from plant protein substitution in bakery applications, with fitness enthusiasts and direct-to-consumer brands showing highest price sensitivity compared to institutional nutraceutical buyers.
Supply Chain Analysis
Tariff exposure between New Zealand and China dominates supply chain risk architecture for Oceania-origin casein. Production concentrates in New Zealand, Germany, and the Netherlands, with raw material flows drawing from farmer-owned cooperative structures, membrane filtration equipment suppliers, and F-Gas Regulation-compliant refrigeration retrofits. Single-source vulnerability persists in ceramic membrane engineering talent, constraining technology rollout timelines. Distribution runs through bulk ingredient wholesalers, direct processor relationships, and online retail platforms serving contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating as direct-to-consumer protein brands and multinational food manufacturers bypass traditional distributor channels, fragmenting legacy wholesale margins while concentrating procurement leverage among volume accounts.
For Market Incumbents: Harden supply security through backward integration into named-processor captive relationships, securing micellar casein volumes against Oceania cooperative bottlenecks. Invest in enzymatic modification R&D at German innovation clusters to defend clean-label positioning against pea protein substitution. Prioritize EU CSRD-aligned carbon accounting verification to maintain procurement eligibility with institutional buyers. For New Entrants and Emerging Players: Clinical nutrition applications in geriatric and enteral care represent the most penetrable entry point, with micellar casein's slow-digestion kinetics displacing hydrolyzed proteins in segments historically closed to dairy suppliers. Target specialty store distribution in Japanese and South Korean pharmacist-recommended channels. Pursue white-label formulation partnerships with sports nutrition contract manufacturers as the go-to-market angle. For Investors and Strategic Acquirers: The market sits at a technology-adoption phase that favors membrane filtration-integrated processors with verified Scope 3 sourcing. Long-term viability hinges on clinical-grade certification pipelines and direct-to-consumer brand ownership. Acquire targets with ceramic membrane capacity and named-processor offtake relationships. Watch EFSA health claim substantiation timelines as the inflection signal for premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Ceramic system adoption cuts water use and unlocks clinical-grade purity tiers for nutraceutical buyers. |
| Backward Integration into Dairy Sourcing | Named-processor captive supply secures volume certainty against Fonterra cooperative concentration risk. |
| Enzymatic Modification R&D Investment | Cologne and Hamburg clusters incubate clean-label caseinates for premium sports nutrition positioning. |
| Carbon Accounting Verification Program | EU CSRD-aligned Scope 3 disclosure differentiates supplier eligibility in institutional procurement frameworks. |
| Direct-to-Consumer Channel Launch | Vertical brand control bypasses distributor compression while capturing overnight recovery supplement premiums. |
Research Approach
A standing panel of dairy processing plant managers, sports nutrition procurement leads, membrane filtration system operators, and EFSA regulatory affairs specialists provided ongoing calibration. Primary interviews combined with secondary validation from customs trade data, Fonterra cooperative governance disclosures, EU F-Gas Regulation implementation tracking, and SEC filings from listed ingredient houses. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Scenario-bracketing around regulatory compliance timelines and commodity dairy cycle positions shaped the projection methodology across the analysis window. Segmentation dimensions included product type, application, distribution channel, and customer procurement sophistication. CAGRs derived from protein supplement demand elasticity, clinical nutrition penetration rates, and membrane technology adoption curves.
Macroeconomic conditions sit as an overlay; deviation in skim milk powder auction prices, EU emissions retrofit investment cycles, or plant protein substitution velocity would shift the trajectory. Forecasts reflect assumptions on regulatory stability and technology diffusion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Organic Pastry Flour Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Vital Wheat Gluten Market
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
North America Plant Protein Ingredients Market
Ingredients
United Kingdom Protein Market
Ingredients
China Soy Protein Market
Ingredients
Non-PHO Ingredients Market
Ingredients
India Starch and Starch Derivative Market
Ingredients
Organic Virgin Coconut Oil Market
Ingredients
Modified Flour Market
Ingredients
Olive Leaf Extract Market
Ingredients
Starch Market
Ingredients
Konjac Root Fiber Market
Ingredients
Pomace Olive Oil Market
Ingredients
Africa Soy Protein Ingredients Market