
 Vegan Marshmallows Market | 2026-2036
Vegan Marshmallows Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Marshmallows Market Analysis
Market Context
Plant-based confectionery formulation expertise is bifurcating the competitive landscape between artisan specialists and scaled manufacturers. Dandies leverages its dedicated vegan production infrastructure to sustain premium positioning across North American natural retail channels. Chicago Vegan Foods anchors its growth through deep control of aquafaba supply chains and in-house whipping technology. Ananda Foods competes on heritage vegan credentials and specialized distribution through UK health food shops.
Technical Definition and Segments
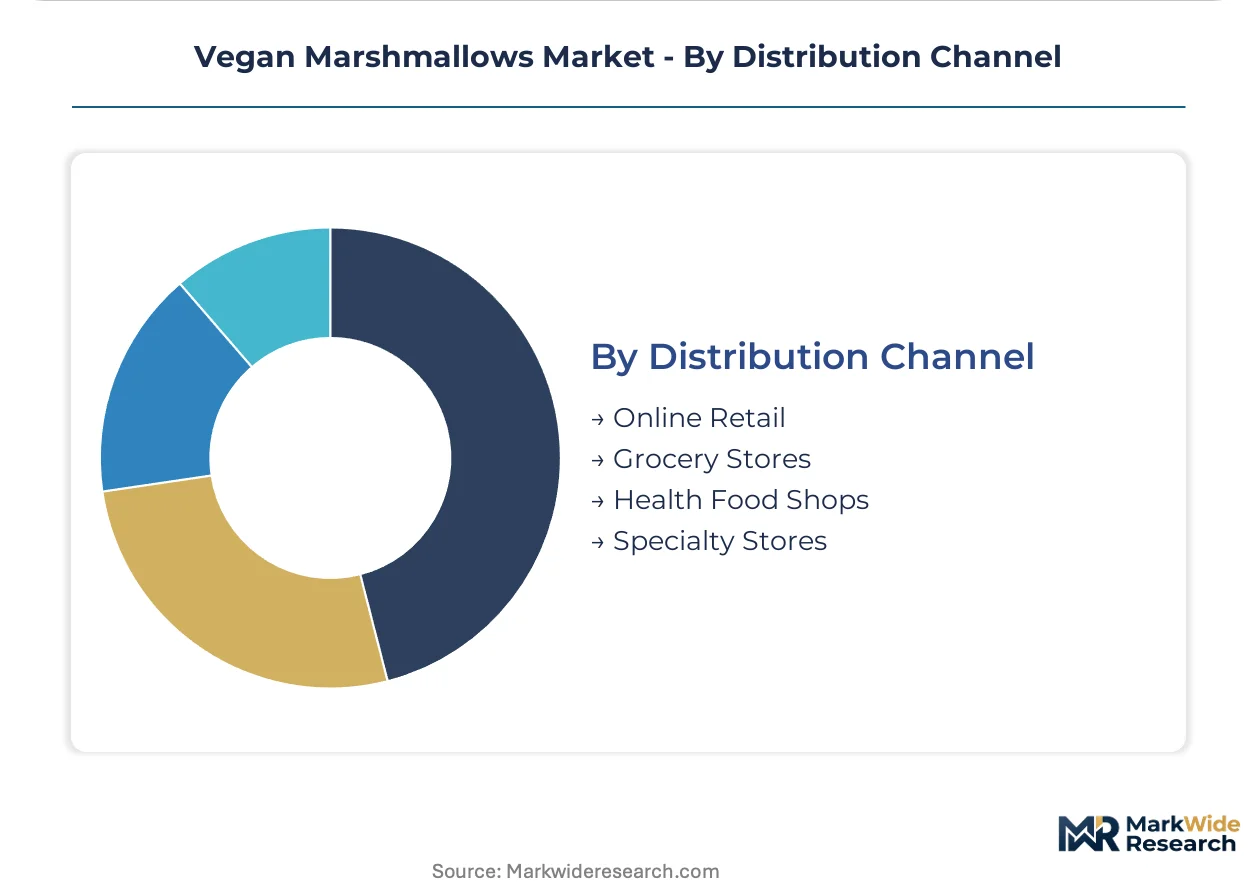
Vegan marshmallows are aerated confectionery products utilizing plant-derived hydrocolloids such as carrageenan, agar-agar, or aquafaba to replicate the elastic texture and stable foam structure traditionally achieved with porcine or bovine gelatin, primarily serving retail baking, hot beverage topping, and direct consumption markets. The product type dimension shows mini marshmallows occupying the volume-leading position for baking applications while marshmallow fluff captures expanding foodservice demand for spreadable formats. Within distribution channels, online retail represents the fastest-growing pathway as direct-to-consumer subscription models reduce shelf-space dependency, whereas health food shops retain the highest margin pool due to certified organic and allergen-free positioning.
Regulatory Outlook
The US FDA maintains strict gelatin labeling requirements that indirectly advantage vegan alternatives through transparent ingredient disclosure, while EFSA and EMA frameworks across Europe enforce novel food assessments for emerging plant proteins used in confectionery applications. USDA organic certification and EU organic regulations create tiered market access where certified products command shelf placement in premium channels. Stakeholders must monitor evolving definitions of clean-label claims as regulators scrutinize plant-based terminology and carbon footprint disclosures across multiple jurisdictions.
Market Dynamics
Plant-based gelling agent innovation is restructuring competitive advantage around proprietary hydrocolloid processing capabilities and captive supply chain control rather than brand equity alone.
Growth Catalysts
- Clean-label mandates:EFSA novel food assessments and FDA gelatin disclosure rules accelerate retailer preference for transparent ingredient decks in Germany, the United Kingdom, and the United States.
- Aquafaba processing advances:In-house whipping technology development enables consistent foam stability without porcine or bovine gelatin, opening foodservice channels previously closed to vegan confectionery.
- Specialty bakery demand:Allergen-free positioning in certified organic retail channels pulls volume for mini marshmallow formats used in premium baking applications.
Market Restraints
- Input cost volatility:Carrageenan and agar-agar harvest sensitivity to marine ecosystem conditions creates margin pressure unavailable to gelatin-based competitors.
- Supply concentration risk:Aquafaba sourcing depends on chickpea processing byproduct availability concentrated in specific agricultural regions with limited alternative streams.
- Technical limitation:Plant-derived hydrocolloids struggle to replicate the exact melt profile and elastic recovery of mammalian gelatin in high-temperature baking applications.
Strategic Opportunities
- Direct-to-consumer subscription:Online retail channel development reduces shelf-space dependency and captures recurring revenue through certified organic and allergen-free positioning.
- EU organic regulation tailwind:Tiered market access rules create premium placement incentives for USDA organic and EU organic certified products in health food shops.
- Marshmallow fluff format expansion:Spreadable product development targets underpenetrated foodservice demand for hot beverage topping and dessert applications.
Industry Challenges
- Formulation talent scarcity:Plant-based aeration science expertise sits concentrated with artisan specialists, constraining scaled manufacturer capability building.
- Certification timeline friction:USDA organic and novel food assessment procedures create multi-quarter approval delays for new hydrocolloid introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Marshmallows Market |
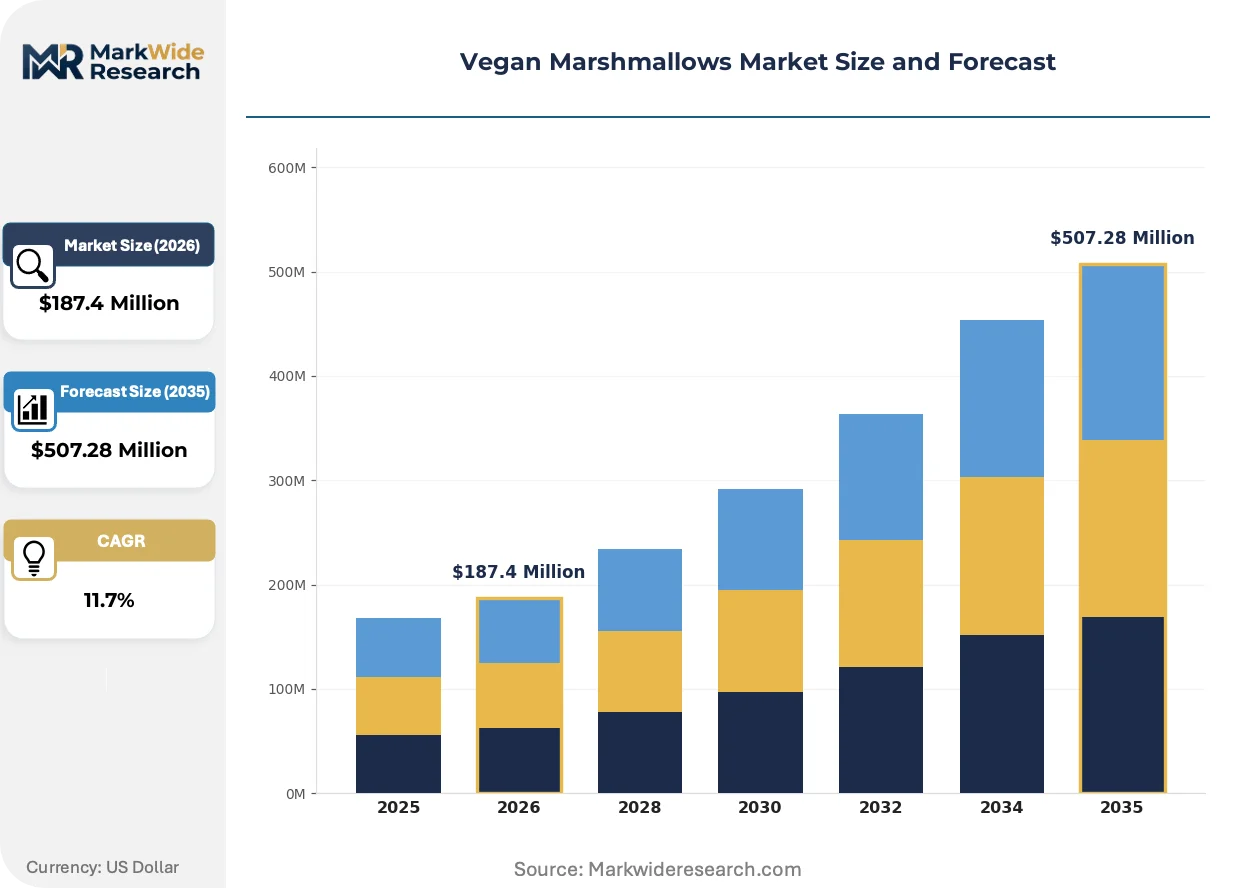
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Marshmallows, Marshmallow Fluff, Sticks, Jumbo Marshmallows Sweetener Type: Agave Syrup, Coconut Sugar, Maple Syrup, Raw Cane Sugar Packaging Type: Pouches, Jars, Boxes, Bulk Packages Distribution Channel: Online Retail, Grocery Stores, Health Food Shops, Specialty Stores |
| Companies Covered | Dandies, Chicago Vegan Foods, Ananda Foods, Freedom Mallows, The Naked Marshmallow Co., Freedom Confectionery, Yummallo, Holland & Barrett Retail Limited, Mr. Mallo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Marshmallows Market Emerging Trajectories
Processing technology convergence and regulatory transparency requirements are compressing the traditional advantage window of incumbent gelatin suppliers while elevating specialized plant-based formulation capabilities.
Aquafaba-derived aeration systems are displacing legacy carrageenan-dominant formulations in premium confectionery applications. Specialty bakeries and natural retail channels in Germany and the United Kingdom adopt these systems fastest, seeking cleaner label declarations. The shift is compressing R&D cycles as manufacturers race to patent proprietary whipping processes before commodity hydrocolloid suppliers catch up.
EU Green Deal carbon footprint disclosure frameworks are forcing ingredient provenance documentation throughout confectionery supply chains. Industrial consequence includes mandatory supplier auditing for marine-derived hydrocolloids like agar-agar. Certified organic marshmallow producers face the steepest compliance burden but secure preferential shelf placement in Western European health food channels as a direct result.
Buyer concentration in foodservice procurement is consolidating vendor relationships around full-format suppliers capable of delivering both mini marshmallows and spreadable fluff. Independent bakery chains and café groups in the United States increasingly bypass traditional distribution intermediaries, negotiating directly with manufacturers who control in-house aquafaba processing. This disintermediation is most visible in metropolitan clusters where vegan lifestyle penetration drives menu innovation pressure.
Vegan Marshmallows Market Segmentation
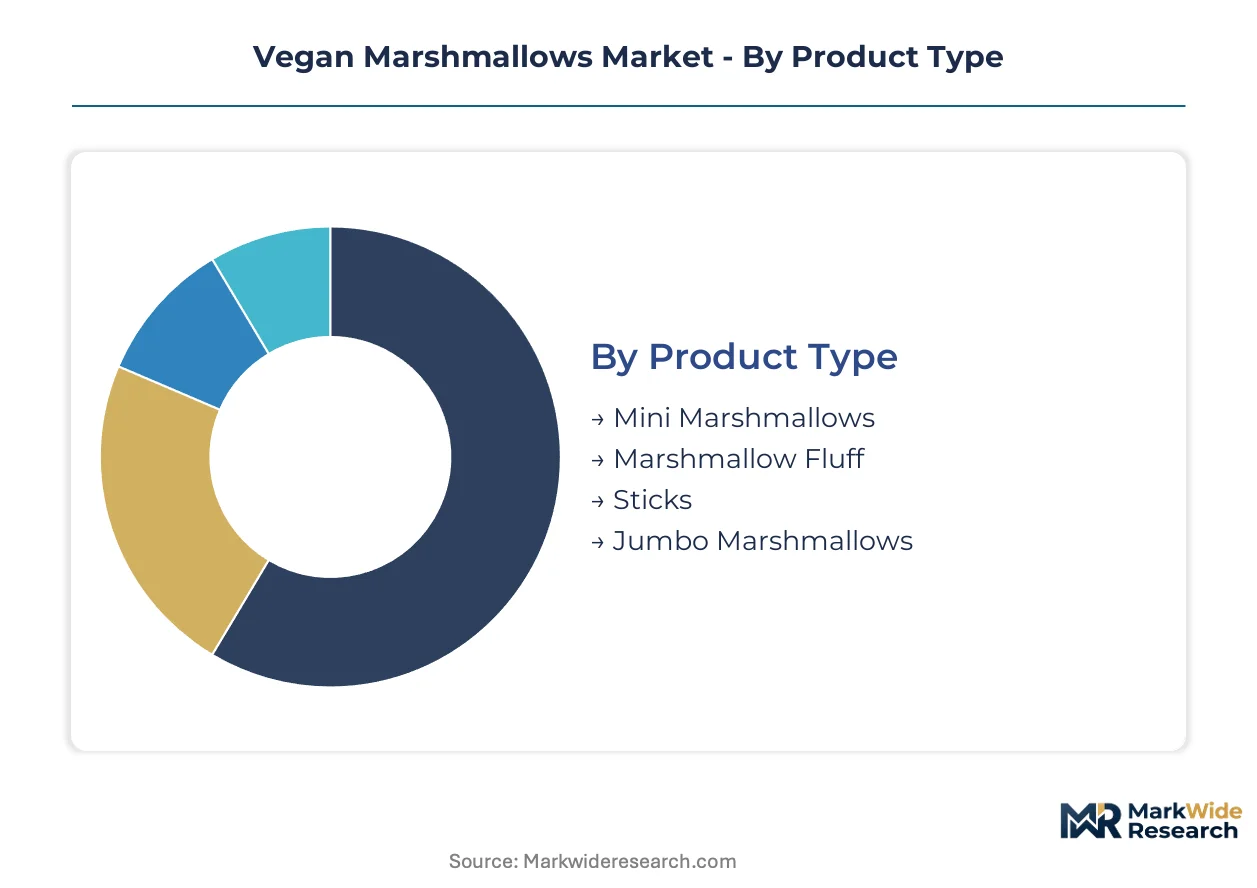
Vegan marshmallow segmentation reveals distinct channel affinities that shape manufacturer go-to-market priorities. Each dimension carries implications for formulation, certification requirements, and margin capture that diverge sharply from conventional gelatin-based confectionery.
Product Type:
Mini marshmallows flow predominantly through grocery and health food retail for home baking applications, while fluff formats concentrate in foodservice procurement channels seeking spreadable dessert components.
- Mini Marshmallows:Small-format aerated cylinders utilizing carrageenan or aquafaba gelling systems for hot beverage suspension and baking incorporation. Demand concentrates in Germany and the United Kingdom where clean-label home baking trends drive certified organic purchases through health food shops.
- Marshmallow Fluff:Spreadable whipped confectionery with reduced density and extended shelf stability through modified plant hydrocolloid ratios. United States café chains and specialty bakeries represent the steepest expansion trajectory for direct foodservice procurement bypassing traditional distribution.
- Sticks:Elongated formats for roasting applications requiring enhanced heat resistance through agar-agar stabilization.
- Jumbo Marshmallows:Oversized campfire and confectionery decoration formats with specialized packaging requirements for structural integrity.
Mini marshmallows dominate installed base across retail channels. Marshmallow fluff is where expansion concentrates as foodservice menu innovation accelerates.
Sweetener Type:
Cost tier stratification separates premium positioning from mass-market accessibility, with certification grade determining shelf placement in tiered retail environments.
- Agave Syrup:Low-glycemic sweetening from blue agave nectar processing, commanding premium placement in diabetic-friendly and keto-adjacent product lines.
- Coconut Sugar:Unrefined palm sap-derived sweetener with mineral content retention and caramel notes, prevalent in USDA organic and EU organic certified SKUs.
- Maple Syrup:Grade A or processing-grade maple sap concentrate, concentrated in North American artisan production with regional provenance marketing.
- Raw Cane Sugar:Minimally processed sucrose retaining molasses content, anchoring mass-market price positioning through supply scale and formulation familiarity.
Raw cane sugar anchors volume production economics. Maple syrup and agave variants are climbing the fastest as premium positioning intensifies.
Packaging Type:
Volume scale and margin capture diverge sharply between single-serve convenience formats and bulk procurement systems serving commercial baking operations.
- Pouches:Flexible film barriers with reseal features for moisture protection, dominating impulse purchase and trial-size distribution in grocery checkout placement.
- Jars:Rigid container systems for fluff and spreadable formats requiring scoop access and extended refrigerator stability after opening.
- Boxes:Structural cartons for gift and seasonal merchandising with premium unboxing experience in specialty retail.
- Bulk Packages:Foodservice-scale poly-lined containers for commercial bakery and confectionery manufacturing ingredient supply.
Pouches command the highest unit velocity in retail. Bulk packages are gaining share fastest as commercial bakery outsourcing accelerates.
Distribution Channel:
Customer type and purchase occasion determine margin structure, with subscription recurrence and certification requirements creating distinct operational demands.
- Online Retail:Direct-to-consumer and marketplace platforms enabling subscription models and allergen-filtered search discovery, expanding most quickly as shelf-space dependency diminishes.
- Grocery Stores:Conventional and natural supermarket chains with planogram placement battles and promotional calendar dependence for seasonal volume spikes.
- Health Food Shops:Independent and chain natural retailers with certified organic and allergen-free positioning commanding premium price realization.
- Specialty Stores:Confectionery boutiques, baking supply retailers, and gift merchants with curated assortment and experiential merchandising.
Grocery stores maintain the broadest installed base. Online retail is where expansion concentrates as direct manufacturer relationships bypass traditional wholesale markup.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA gelatin disclosure requirements in the United States create indirect tailwinds for plant-based alternatives through transparent ingredient mandates. Germany, the United Kingdom, and the United States concentrate the steepest vegan lifestyle penetration in foodservice procurement. EFSA novel food assessments and EU Green Deal carbon disclosure frameworks reshape competitive access across Western European health food retail.
United States
Specialty bakery chains and café groups in metropolitan clusters drive direct-to-manufacturer procurement bypassing traditional distribution intermediaries. FDA maintains strict gelatin labeling requirements that advantage vegan alternatives through ingredient transparency mandates. Chicago anchors significant aquafaba processing infrastructure development for consistent foam stability in foodservice applications.
Germany
Clean-label home baking trends pull certified organic mini marshmallow volume through independent health food shops. EFSA novel food assessments enforce rigorous evaluation for emerging plant proteins in confectionery applications. Berlin and Munich concentrate artisan vegan confectionery specialists with proprietary hydrocolloid processing capabilities.
United Kingdom
Heritage vegan credentials and specialized distribution networks sustain premium positioning in natural retail channels. EU organic regulations create tiered market access where certified products command preferential shelf placement. London and Southeast England clusters host established plant-based aeration science expertise concentrated with artisan specialists.
Canada
Health Canada and PMRA frameworks govern novel ingredient introductions in plant-based confectionery with alignment to international standards. USDA organic certification equivalency agreements facilitate cross-border premium product flow into natural retail channels. Toronto and Vancouver metropolitan areas concentrate vegan foodservice menu innovation driving spreadable fluff format demand.
France
ANSM and CNIL oversight extends to clean-label claim scrutiny affecting plant-based terminology in confectionery marketing. EU Green Deal carbon footprint disclosure requirements mandate supplier auditing throughout marine-derived hydrocolloid supply chains. Paris and Île-de-France host luxury confectionery boutiques curating certified organic vegan marshmallow assortments for gift merchandising.
Vegan Marshmallows Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in plant-based confectionery formulation. The competitive landscape bifurcates between scaled manufacturers with captive aquafaba supply chains and artisan specialists concentrated in regional health food distribution. Three archetypes dominate: integrated hydrocolloid processors controlling in-house whipping technology, heritage vegan confectioners with deep retail relationships, and diversified natural food companies leveraging existing brand equity. Competitive moves concentrate on strategic partnerships for raw material security and portfolio diversification into spreadable fluff formats.
Within the heritage vegan specialist tier, Dandies and Ananda Foods exemplify archetypes anchored in dedicated production infrastructure and regional distribution depth. Chicago Vegan Foods occupies a position representing integrated aquafaba supply chain control with proprietary processing capabilities. These three entities collectively illustrate the competitive tension between scaled manufacturing efficiency and artisan formulation expertise that defines current market structure.
| Leading Market Players |
|---|
| Dandies |
| Chicago Vegan Foods |
| Ananda Foods |
| Freedom Mallows |
| The Naked Marshmallow Co. |
| Freedom Confectionery |
| Yummallo |
| Holland & Barrett Retail Limited |
| Mr. Mallo Group |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between aquafaba processors and specialty confectionery manufacturers lock in both supply access and price visibility, insulating premium tier producers from chickpea harvest volatility while exposing spot-market buyers to margin compression during seasonal supply crunches.
Pricing Analysis
Contract-based long-term offtake dominates procurement between scaled manufacturers and aquafaba suppliers, with price differentiation anchored in certification grade and volume scale. USDA organic and EU organic tiers command shelf placement premiums in health food shops, while raw cane sugar formulations anchor mass-market accessibility. Cost compression in premium tiers is intensifying because marine hydrocolloid harvest sensitivity creates input volatility unavailable to gelatin-based competitors. Foodservice buyers exhibit highest price sensitivity due to menu cost pressures, whereas health food shop consumers demonstrate lowest sensitivity when allergen-free positioning is certified.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for agar-agar and carrageenan shipments originating from Indonesia and the Philippines. Raw material sourcing draws from chickpea processing byproduct streams concentrated in India and the United States, with marine hydrocolloid extraction tethered to Southeast Asian coastal ecosystems. Single-source vulnerability in aquafaba supply creates structural risk as alternative plant protein streams remain underdeveloped. Distribution runs through health food shops and direct-to-consumer subscription platforms, with foodservice procurement increasingly bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proprietary aquafaba whipping technology and plant-based aeration science expertise sit concentrated with a narrow specialist tier, constraining scaled manufacturer capability building and creating acquisition premiums for targets with captive formulation talent.
For Market Incumbents: Secure captive aquafaba supply through backward integration into chickpea processing or exclusive offtake partnerships with regional processors, insulating margin structure from harvest volatility. Invest in novel food assessment pre-submission with EFSA to compress certification timelines for next-generation hydrocolloid introductions, defending position against artisan specialists with established regulatory navigation capabilities. For New Entrants and Emerging Players: USDA organic certification fast-track through accredited third-party reviewers opens shelf placement in premium health food channels where incumbent concentration remains lowest. Target marshmallow fluff format expansion in United States metropolitan café clusters, where foodservice procurement bypasses traditional distribution and rewards direct manufacturer relationships with volume commitments. For Investors and Strategic Acquirers: Capital is best deployed toward integrated hydrocolloid processors with in-house whipping technology and established direct-to-consumer subscription infrastructure. Over the projection horizon, viability hinges on proprietary formulation capabilities rather than brand equity alone. The signal to watch is aquafaba supply chain consolidation announcements, indicating margin compression risk for non-integrated competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Aquafaba Supply Integration | Captive chickpea byproduct sourcing locks in foam stability consistency for foodservice channel expansion. |
| Novel Food Assessment Pre-Submission | Early EFSA engagement compresses multi-quarter approval delays for carrageenan alternative hydrocolloids. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models reduce shelf-space dependency and capture allergen-filtered search discovery. |
| Marshmallow Fluff Format Development | Spreadable product expansion targets underpenetrated United States café and specialty bakery procurement. |
| EU Organic Certification Investment | Tiered market access rules secure preferential placement in Western European health food retail channels. |
Methodological Framework
Initial hypotheses were tested against primary input from plant-based confectionery R&D directors, health food shop category buyers, foodservice procurement managers, and aquafaba processing facility operators, and refined through secondary validation against FDA gelatin labeling guidance documents, EFSA novel food assessment registers, USDA organic certification databases, and EU Green Deal carbon disclosure frameworks. Bottom-up volume modeling from individual SKU velocity data was triangulated against top-down market sizing from trade flow analysis.
Variance decomposition across product type, sweetener tier, packaging format, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation with macroeconomic drivers. Industry-specific forecast inputs incorporated marine hydrocolloid harvest yield variability and clean-label regulatory adoption curves across Germany, the United Kingdom, and the United States.
Underlying assumptions cover sustained vegan lifestyle penetration in foodservice procurement and stable chickpea processing byproduct availability, with deviation risk concentrated in marine ecosystem disruption affecting carrageenan and agar-agar supply. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Extruded Soy Products Market
Plant Based Food
Plant-Based Bacon Market
Plant Based Food
United States Plant Protein Market
Plant Based Food
Organic Pea Protein Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
India Pea Protein Market
Plant Based Food
Plant Based Protein Market
Plant Based Food
Europe Plant-Based Food Market
Plant Based Food
Plant Based Meal Kit Market
Plant Based Food
Plant Based Food Colors Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
Plant Based Cheese Market
Plant Based Food
Brazil Soy Beverages Market
Plant Based Food
South America Rice Protein Market
Plant Based Food
Germany Soy Protein Market