
 Global Protein Hydrolysate Ingredients Market | 2026-2036
Global Protein Hydrolysate Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Protein Hydrolysate Ingredients Market Foresight
Buyer concentration among sports nutrition brands is expanding as specialized athletic supplement companies consolidate purchasing power while functional food startups fragment demand across niche channels. Kerry Group plc leverages its flavor-masked hydrolysate technology to secure long-term supply contracts with endurance nutrition brands. Fonterra Co-operative Group Limited anchors Oceania's whey hydrolysate output through integrated dairy processing networks. Glanbia plc differentiates via direct-to-brand partnerships that bypass traditional ingredient distributors.
Protein hydrolysate ingredients are proteins enzymatically cleaved into peptide fractions and free amino acids, typically achieving 50-90% degree of hydrolysis with molecular weights below 10 kDa to accelerate gastric emptying and plasma amino acid appearance. Their primary commercial purpose centers on delivering rapid nitrogen assimilation for post-exercise recovery, medical nutrition, and low-allergen infant feeding applications. Whey hydrolysate occupies the premium tier in sports nutrition due to superior leucine bioavailability, while collagen hydrolysate extends into functional foods and nutricosmetics as consumers prioritize joint and dermal health. Powder dominates manufacturing economics due to stability and bulk handling efficiency, though liquid concentrates gain traction in ready-to-drink clinical nutrition formats.
The FDA exercises oversight through Current Good Manufacturing Practice regulations for dietary supplements, while EFSA sets novel food safety benchmarks that govern collagen and pea hydrolysate approvals across EU member states. China's NMPA and SAMR enforce infant formula registration requirements that mandate clinical validation for hydrolysate-based hypoallergenic products. Stakeholders must monitor evolving peptide-specific health claim pathways in major jurisdictions to anticipate which hydrolysate categories will unlock premium positioning versus commodity protein substitution.
Market Dynamics
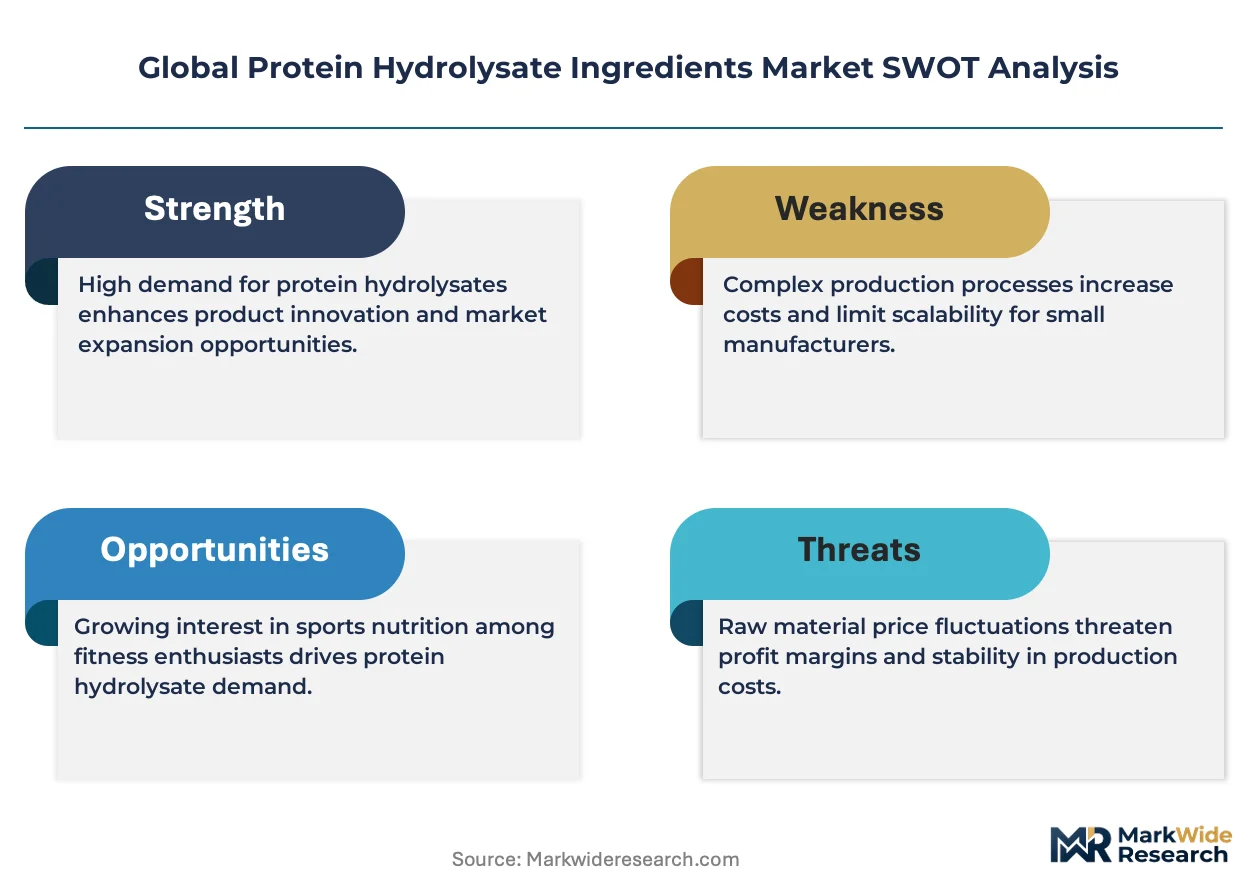
Sports nutrition brands are consolidating purchasing power around rapid-absorption protein formats, forcing ingredient suppliers to invest in flavor-masked hydrolysate technologies and bypass traditional distribution channels through direct-to-brand partnerships.
Growth Catalysts
- Endurance athlete demand:Marathon runners and triathletes prioritize whey hydrolysates for accelerated plasma amino acid appearance during recovery windows.
- EFSA novel food pathways:Pea and collagen hydrolysate approvals across EU member states unlock premium positioning in clinical nutrition applications.
- Enzymatic hydrolysis advances:Controlled peptide cleavage achieving 50-90% degree of hydrolysis with molecular weights below 10 kDa improves gastric emptying rates.
Market Restraints
- Dairy input cost volatility:Whey hydrolysate production remains tethered to fluid milk and cheese manufacturing economics, exposing margins to commodity dairy cycles.
- Supply concentration in Oceania:Integrated dairy processing networks in New Zealand and Australia dominate premium whey hydrolysate feedstock availability.
- Allergen disclosure complexity:FDA dietary supplement labeling requirements mandate extensive peptide fraction documentation, extending compliance timelines for new entrants.
Strategic Opportunities
- Brazil nutricosmetics channel:Collagen hydrolysate penetration into functional foods and dermal health supplements lags behind sports nutrition, creating whitespace for joint-care positioning.
- China infant formula registration:NMPA and SAMR clinical validation mandates for hypoallergenic hydrolysate products favor suppliers with established pediatric nutrition partnerships.
- Ready-to-drink liquid concentrates:Clinical nutrition manufacturers are shifting from powder to liquid hydrolysate formats for hospital and eldercare feeding applications.
Industry Challenges
- Peptide-specific health claim substantiation:EFSA and FDA divergent evidentiary standards for bioactive peptide efficacy claims fragment R&D investment priorities.
- Flavor masking capex intensity:Bitter peptide fraction suppression requires proprietary encapsulation infrastructure that mid-scale hydrolysate producers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Protein Hydrolysate Ingredients Market |
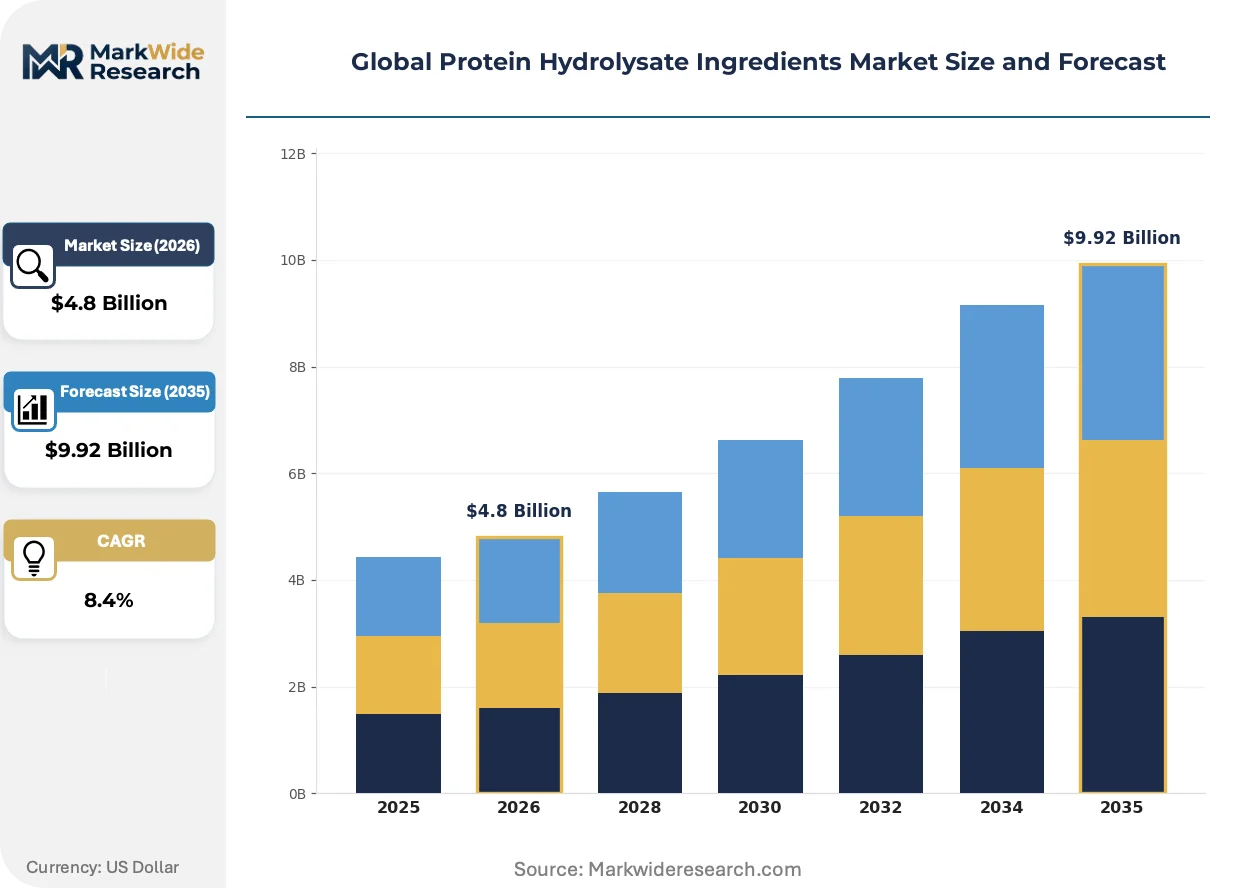
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Hydrolysate, Casein Hydrolysate, Soy Protein Hydrolysate, Collagen Hydrolysate, Pea Protein Hydrolysate Application: Sports Nutrition, Infant Formula, Functional Foods, Dietary Supplements, Clinical Nutrition Form: Powder, Liquid Concentrate, Granules, Tablets, Capsules End User: Manufacturers, Nutraceutical Companies, Food & Beverage Producers, Pharmaceutical Firms, Research Institutions |
| Companies Covered | Arla Foods Ingredients, Kerry Group plc, Fonterra Co-operative Group Limited, Cargill, Incorporated, Glanbia plc, Abbott Laboratories, Archer Daniels Midland Company, Royal FrieslandCampina, Agropur, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Protein Hydrolysate Ingredients Market Shifts & Advancements
Enzymatic processing advances and regulatory divergence around bioactive peptide claims are fragmenting competitive positioning between premium sports nutrition suppliers and commodity protein substitute manufacturers.
Membrane filtration technology is decentralizing hydrolysate production economics by enabling smaller-scale manufacturers to achieve peptide fraction separation previously requiring capital-intensive spray-drying infrastructure. Regional dairy cooperatives in Germany and the Netherlands are adopting ceramic membrane systems to capture whey hydrolysate value from local cheese processing waste. This capability diffusion compresses minimum efficient scale thresholds and erodes historical volume advantages held by integrated multinationals.
China's SAMR has tightened infant formula registration requirements through clinical validation mandates for hydrolysate-based hypoallergenic products. Domestic manufacturers must submit peptide safety and efficacy data to NMPA review panels before marketing claims approval. European suppliers with established pediatric nutrition dossiers are accelerating partnership negotiations with Chinese brand owners to preempt local capacity buildouts.
Direct-to-brand ingredient partnerships are displacing traditional distributor intermediaries in sports nutrition procurement. Endurance nutrition companies now negotiate multi-year hydrolysate supply contracts with peptide fraction specifications and exclusive flavor masking technologies. This channel compression concentrates technical dialogue between R&D functions and compresses price transparency for spot-market buyers in North American and Western European markets.
Global Protein Hydrolysate Ingredients Market Segmentation
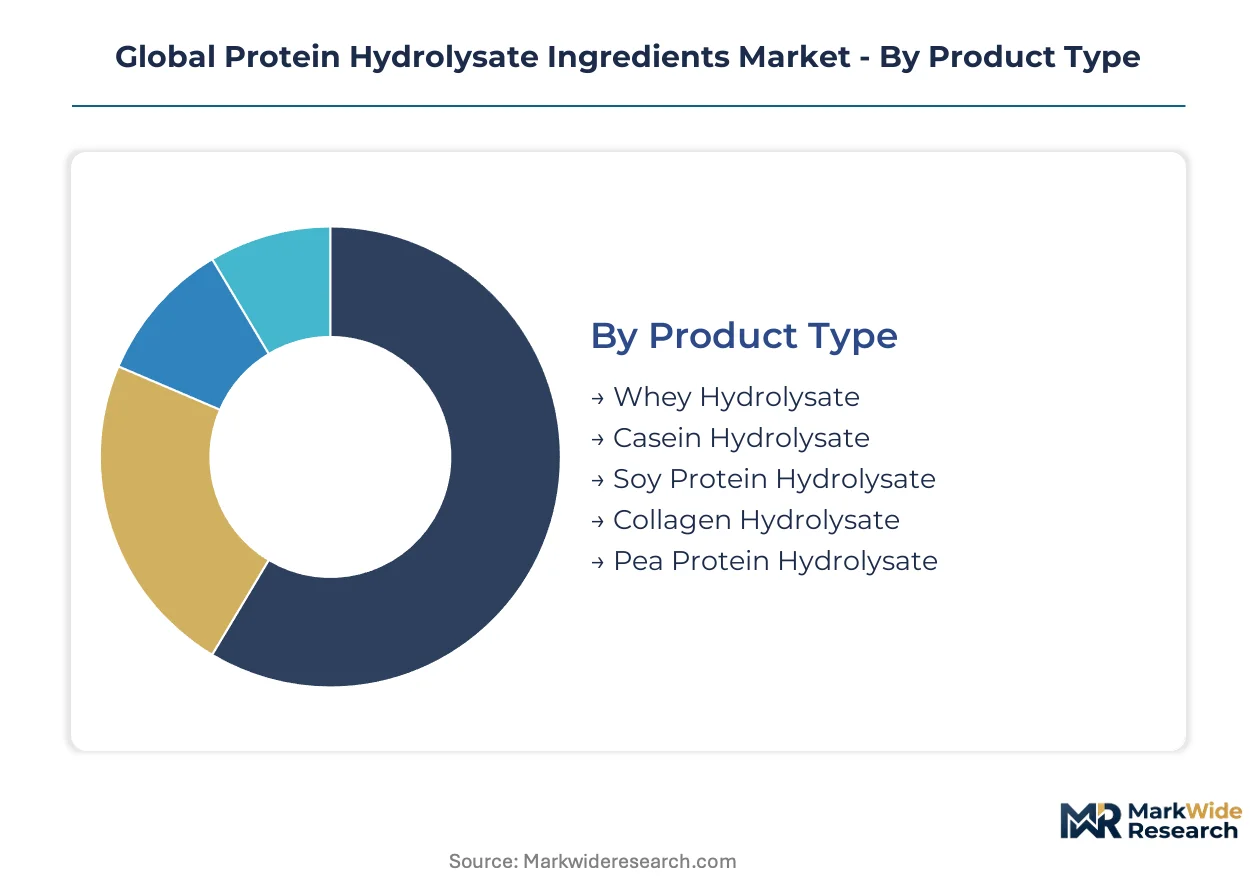
Peptide fraction specifications and enzymatic processing parameters dictate commercial positioning across hydrolysate categories. Formulation requirements vary sharply between rapid-absorption sports applications and hypoallergenic infant nutrition, fragmenting supplier capabilities along technical rather than purely geographic lines.
Product Type:
Degree of hydrolysis and molecular weight distribution separate commodity protein substitutes from premium peptide formulations.
- Whey Hydrolysate:Achieves 50-90% hydrolysis with molecular weights below 10 kDa for accelerated gastric emptying. Sports nutrition brands in the United States and Germany concentrate procurement around leucine-rich fractions for post-exercise recovery protocols.
- Collagen Hydrolysate:Delivers bioactive peptides supporting joint and dermal matrix synthesis. Brazil and China are expanding nutricosmetics applications as consumers prioritize functional foods over traditional supplements.
- Casein Hydrolysate:Sustained-release peptide kinetics suit overnight recovery and clinical nutrition applications.
- Soy Protein Hydrolysate:Plant-derived hypoallergenic positioning serves vegetarian and allergen-restricted formulations.
- Pea Protein Hydrolysate:EFSA novel food approvals unlock EU clinical nutrition positioning for sustainable protein sourcing.
Whey hydrolysate leads on scale; pea protein hydrolysate leads on momentum.
Application:
Regulatory validation requirements and reimbursement pathways fragment demand concentration across end-use sectors.
- Sports Nutrition:Endurance athletes and resistance training populations drive rapid-absorption format adoption. Direct-to-brand procurement contracts in North America and Western Europe specify peptide fraction profiles and flavor masking performance.
- Infant Formula:China's NMPA and SAMR enforce clinical validation mandates for hypoallergenic hydrolysate products. European suppliers with pediatric nutrition dossiers accelerate partnership negotiations with domestic brand owners.
- Functional Foods:Collagen-fortified beverages and bars penetrate Brazil and South Korea through joint-care and skin-health positioning.
- Dietary Supplements:Capsule and tablet formats serve aging populations in Japan and Germany seeking convenient protein supplementation.
- Clinical Nutrition:Hospital and eldercare feeding applications in the United States and Netherlands shift toward liquid concentrate formats for tube feeding compliance.
Sports nutrition commands volume concentration; infant formula climbs the fastest on regulatory tailwinds.
Form:
Manufacturing economics and stability requirements determine format selection across distribution channels.
- Powder:Dominates bulk handling efficiency and shelf stability for sports nutrition and infant formula manufacturing. Spray-dried hydrolysates from New Zealand and Australian dairy networks supply global brand owners.
- Liquid Concentrate:Gains traction in ready-to-drink clinical nutrition and hospital feeding applications where reconstitution steps create compliance barriers.
- Granules:Intermediate dissolution properties serve functional food integration where powder dispersibility limits processing.
- Tablets:Compressed formats target dietary supplement retail channels in Germany and Japan with dose-precision requirements.
- Capsules:Encapsulation protects bitter peptide fractions for direct-to-consumer nutraceutical positioning.
Powder leads on scale; liquid concentrate leads on momentum.
End User:
Technical dialogue depth and procurement centralization separate integrated manufacturers from distributed ingredient purchasers.
- Manufacturers:Sports nutrition and infant formula producers negotiate multi-year hydrolysate supply contracts with peptide fraction specifications. Kerry Group and Glanbia anchor direct partnerships bypassing traditional distributors.
- Nutraceutical Companies:Fragmented demand across specialty channels prioritizes capsule and tablet format flexibility over volume scale.
- Food & Beverage Producers:Functional food integration in Brazil and China requires flavor-masked collagen hydrolysates for clean-label positioning.
- Pharmaceutical Firms:Clinical nutrition and medical food applications demand batch documentation exceeding dietary supplement standards.
- Research Institutions:Peptide bioactivity studies drive small-volume procurement of defined molecular weight fractions.
Manufacturers lead on scale; food and beverage producers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologists and dairy protein scientists concentrate in New Zealand's Waikato region, Germany's Bavaria, and China's coastal provinces, anchoring hydrolysate innovation clusters that supply formulation expertise to global brand owners.
United States
Endurance nutrition brands in Colorado and Utah consolidate procurement around leucine-rich whey fractions for post-exercise recovery protocols. FDA dietary supplement labeling requirements mandate extensive peptide fraction documentation, extending compliance timelines for new entrants. Greater Denver hosts specialized sports nutrition manufacturers negotiating direct-to-brand hydrolysate contracts with molecular weight specifications below 10 kDa.
Germany
Clinical nutrition manufacturers in Bavaria and North Rhine-Westphalia drive demand for casein hydrolysates with sustained-release kinetics. EFSA novel food safety benchmarks govern collagen and pea hydrolysate approvals across EU member states, unlocking premium positioning in medical nutrition applications. Munich anchors pediatric nutrition R&D partnerships targeting China infant formula registration pathways.
China
Domestic infant formula producers in Heilongjiang and Inner Mongolia scale hypoallergenic hydrolysate capacity to meet NMPA clinical validation mandates. SAMR enforcement of peptide safety dossier requirements favors European suppliers with established pediatric nutrition partnerships. Yangtze River Delta dairy processors invest in enzymatic hydrolysis infrastructure to capture value from local cheese manufacturing waste streams.
Brazil
Functional food startups in São Paulo and Minas Gerais penetrate nutricosmetics channels with collagen hydrolysates positioned for joint-care and dermal health applications. ANVISA regulatory frameworks for novel food ingredients shape import approval timelines for hydrolyzed protein concentrates. São Paulo's ingredient distribution hubs fragment demand across specialty retail and direct-to-consumer supplement channels.
New Zealand
Integrated dairy cooperatives in Waikato and Canterbury dominate premium whey hydrolysate feedstock supply through captive cheese processing networks. Fonterra's flavor-masked hydrolysate technology secures long-term contracts with endurance nutrition brands in North America and Western Europe. Christchurch membrane filtration specialists enable regional processors to achieve peptide fraction separation without capital-intensive spray-drying infrastructure.
Global Protein Hydrolysate Ingredients Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers in the protein hydrolysate ingredients sector. Dairy-derived ingredient divisions of multinational food groups anchor volume supply through integrated processing networks, while independent hydrolysate specialists differentiate via proprietary enzymatic cleavage technologies and direct-to-brand partnership models. Three archetypes dominate: integrated dairy processors controlling upstream milk supply, ingredient technology specialists with flavor-masking IP, and clinical nutrition formulators with regulatory dossier expertise. Competitive moves concentrate on capacity expansion in enzymatic hydrolysis infrastructure and strategic partnerships bypassing traditional distribution intermediaries.
Among Irish-based ingredient technology groups, Kerry Group plc exemplifies the flavor-masking specialist archetype through its proprietary encapsulation capabilities that suppress bitter peptide fractions. New Zealand's Fonterra Co-operative Group Limited anchors the integrated dairy processor tier with captive whey hydrolysate output from cheese manufacturing networks. Glanbia plc occupies a position within the direct-to-brand partnership model, representing suppliers that negotiate multi-year supply contracts specifying molecular weight distributions and exclusive technical specifications.
| Leading Market Players |
|---|
| Arla Foods Ingredients |
| Kerry Group plc |
| Fonterra Co-operative Group Limited |
| Cargill, Incorporated |
| Glanbia plc |
| Abbott Laboratories |
| Archer Daniels Midland Company |
| Royal FrieslandCampina |
| Agropur |
| Others |
Supply & Pricing Matrix
Captive integration into New Zealand's dairy processing networks anchors premium whey hydrolysate positioning, concentrating pricing power among cooperatives that control both milk supply and enzymatic hydrolysis infrastructure. This upstream control insulates volume leaders from commodity dairy volatility while forcing spot-market buyers into price-taker roles.
Pricing Analysis
Capacity additions in Germany and the Netherlands are reshaping price floors for mid-tier hydrolysate grades, compressing margins for non-integrated producers. Three-tier pricing structure across premium, standard, and economy levels separates leucine-specified sports nutrition fractions from clinical-grade hypoallergenic products and commodity protein substitutes. Cost compression in standard tiers is intensifying because membrane filtration technology diffuses peptide separation capabilities to smaller regional processors. Sports nutrition brands exhibit lowest price sensitivity due to direct-to-brand contract structures, while functional food startups in Brazil face acute budget constraints.
Supply Chain Analysis
Freight cost differentials between Oceania and European markets fragment procurement economics for North American buyers, tilting sourcing decisions toward contract stability over spot-price optimization. Supply concentrates in New Zealand, Australia, and Germany, with enzymatic processing feedstock drawing from local cheese manufacturing waste streams. Raw material dependencies rest on fluid milk availability, specialized protease enzymes, and ceramic membrane filtration systems. Single-source vulnerability runs through Fonterra's dominance of premium whey hydrolysate feedstock. Distribution runs through direct-to-brand partnerships that displace traditional ingredient distributors in sports nutrition channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in protein hydrolysate ingredients rests on enzymatic efficiency gains and premium-tier consolidation around peptide-specific health claims, rewarding suppliers with validated clinical dossiers.
For Market Incumbents: To counter membrane filtration technology diffusion eroding scale advantages, anchor market position through backward integration into proprietary flavor-masking encapsulation infrastructure and exclusive multi-year supply contracts specifying molecular weight distributions below 10 kDa with endurance nutrition brands in the United States and Germany. For New Entrants and Emerging Players: Capture whitespace in Brazil's nutricosmetics channel where collagen hydrolysate penetration lags behind sports nutrition, leveraging joint-care positioning in functional foods and direct-to-consumer supplement formats to bypass established distributor relationships that incumbent suppliers dominate. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale enzymatic processing specialists because EFSA and FDA divergent peptide claim standards fragment R&D investment priorities, creating acquisition opportunities for platforms that aggregate regulatory dossier capabilities across multiple jurisdictions. The inflection signal to monitor is NMPA infant formula registration approval velocity for European suppliers with pediatric nutrition partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Capacity Expansion | Captures value from cheese processing waste streams in Germany and Netherlands dairy networks. |
| Direct-to-Brand Partnership Structuring | Bypasses traditional distributors to concentrate technical dialogue with Kerry Group and Glanbia procurement functions. |
| Flavor-Masking Technology Licensing | Enables clean-label positioning in Brazil functional foods and China nutricosmetics applications. |
| Pediatric Nutrition Dossier Acquisition | Accelerates NMPA registration pathways for hypoallergenic infant formula market entry. |
| Membrane Filtration Infrastructure Deployment | Decentralizes production economics for regional dairy cooperatives competing with Oceania supply concentration. |
Research Methodology
Coverage spans North America, Western Europe, Asia-Pacific, and Latin America, with primary inputs from each region combining interviews with sports nutrition procurement directors, infant formula regulatory affairs leads, dairy cooperative technical managers, and clinical nutrition formulators. Secondary validation draws from FDA dietary supplement filings, EFSA novel food opinions, NMPA infant formula registration databases, and customs trade data for hydrolyzed protein concentrates. Bottom-up volume estimates triangulate against top-down industry association benchmarks.
Granularity extends to product type, application, form, and end user dimensions, with peptide fraction specifications and degree of hydrolysis parameters modeled at the sub-segment level across the projection horizon. CAGRs derive from regression analysis against dairy input cost indices and regulatory approval timelines. Forecast inputs incorporate enzymatic processing capacity buildouts and direct-to-brand contract penetration rates.
Underlying measurement precision varies by segment; sports nutrition procurement data carries tighter precision than fragmented nutraceutical channel estimates. Forecasts reflect assumptions about EFSA peptide claim pathways and NMPA registration velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Casein Hydrolysate Market
Ingredients
Global Cocoa Ingredients Market
Ingredients
Cooking Coconut Milk Market
Ingredients
Bouillon Cubes Market
Ingredients
Soybean Meal Market
Ingredients
Potato Starch Market
Ingredients
Sunflower Oil Market
Ingredients
Potato Fiber Market
Ingredients
Murumuru Butter Market
Ingredients
Asia-Pacific Fats and Oil Market
Ingredients
Arachidonic Acid Market
Ingredients
Food Amino Acids Market
Ingredients
Europe Potato Protein Market
Ingredients
Global Apricot Oil Market
Ingredients
Europe Feed Yeast Market
Ingredients
Global Yeast Market