
 Pepsin Market | 2026-2036
Pepsin Market Size, Share, and Industry Trends Forecast 2026-2036
Pepsin Market Analysis
Aftermarket technical service revenue is narrowing toward suppliers that bundle analytical validation with bulk enzyme supply. Sichuan Deebio Pharmaceutical leverages its integrated porcine sourcing and extraction facilities to control cost volatility. BIOFAC anchors European demand through GMP-certified fermentation and isolation capabilities. Amano Enzyme differentiates via recombinant enzyme platforms that reduce batch-to-batch variability in high-purity grades.
Pepsin is a proteolytic enzyme extracted primarily from porcine gastric mucosa, functioning optimally at pH 1.5–2.5 with a molecular weight near 34.6 kDa; it cleaves peptide bonds adjacent to aromatic amino acids, serving as a critical digestive aid and bioprocessing catalyst. Pharmaceutical pepsin commands premium positioning due to USP-grade certification requirements for tablet and capsule formulations, while food-grade pepsin competes on volume in cheese manufacturing and protein hydrolysate production. Enzymatic pepsin occupies a specialized niche in laboratory reagents and cell culture applications where defined activity units are mandatory.
The US FDA and China's NMPA enforce divergent purity monographs for pepsin used in drug applications, forcing dual-track quality systems at multinational suppliers. REACH registration in Europe constrains porcine-derived imports unless full toxicological dossiers are filed, advantaging regional producers like BIOFAC. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP standards, as alignment would reshape competitive access across the three largest demand zones.
Market Dynamics
Pharmacopeial harmonization pressure between USP, EP, and ChP standards is forcing multinational suppliers to maintain parallel quality systems, reshaping competitive access across the three largest demand zones.
Growth Catalysts
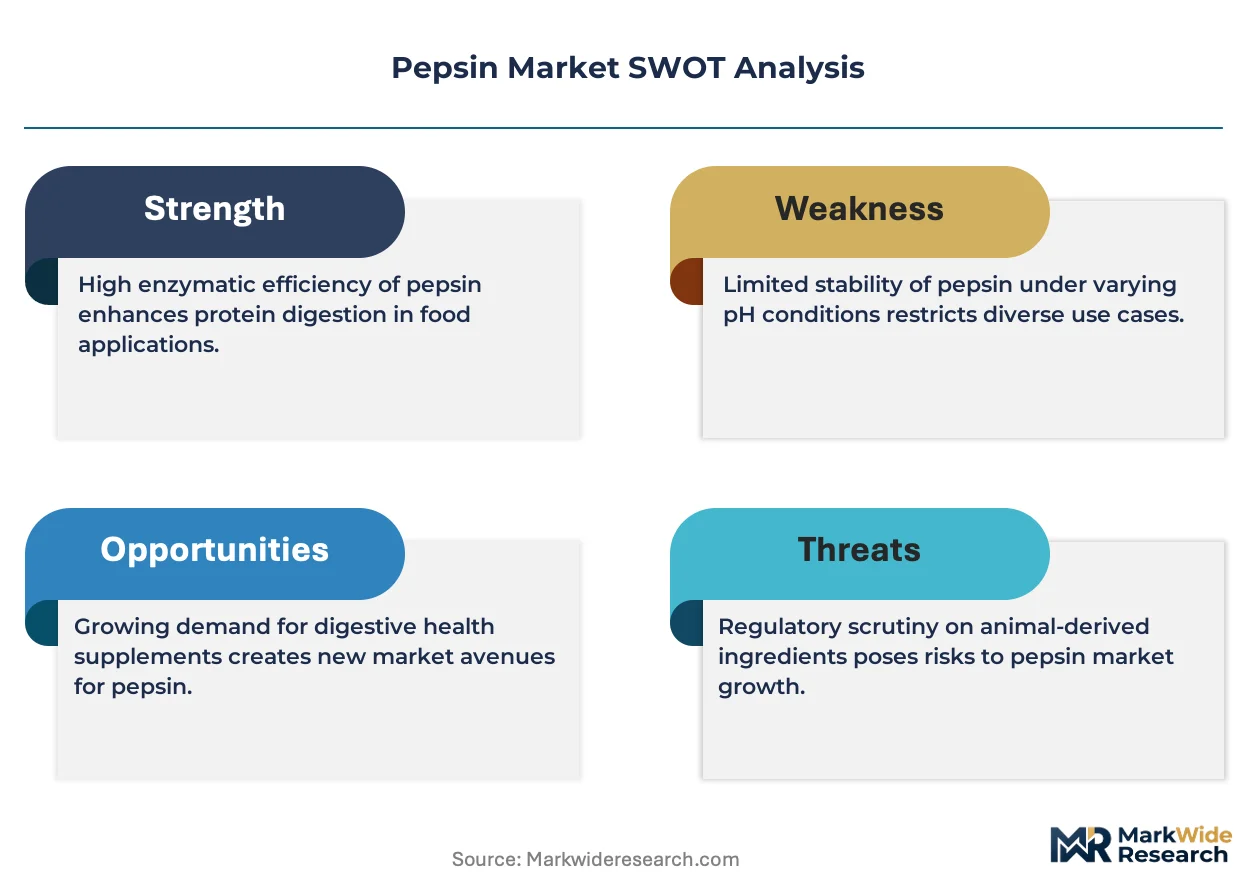
- Nutraceutical formulation demand:Digestive enzyme therapies are gaining traction among supplement manufacturers seeking clinically validated actives for gut health positioning.
- REACH registration in Europe:The toxicological dossier requirement constrains porcine-derived imports, advantaging regional producers with established compliance infrastructure.
- China's Sichuan and Henan extraction clusters:These provinces serve both domestic drugmakers and export markets, concentrating technical expertise and raw material access.
Market Restraints
- Porcine gastric mucosa supply volatility:Swine disease outbreaks and slaughterhouse capacity fluctuations create input cost instability for extraction-based producers.
- Divergent FDA-NMPA purity monographs:The US and Chinese regulators enforce non-aligned specifications, forcing dual-track manufacturing and testing protocols.
- Recombinant protease substitution:Engineered alternatives with reduced batch variability threaten traditional pepsin in laboratory reagent applications.
Strategic Opportunities
- Cell culture reagent expansion:Defined-activity enzymatic pepsin for bioprocessing applications commands premium positioning in regenerative medicine workflows.
- India's PLI scheme for active pharmaceutical ingredients:Domestic enzyme manufacturing incentives could redirect procurement from Chinese suppliers.
- Cheese manufacturing automation:Protein hydrolysate producers in dairy processing are standardizing on food-grade pepsin for consistent curd formation.
Industry Challenges
- ISO 13485 certification timelines:Medical device-grade pepsin requires extended quality system audits, delaying market entry for new suppliers.
- Analytical validation skill scarcity:The shortage of chromatography specialists capable of USP-compliant activity assays limits technical service bundling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pepsin Market |
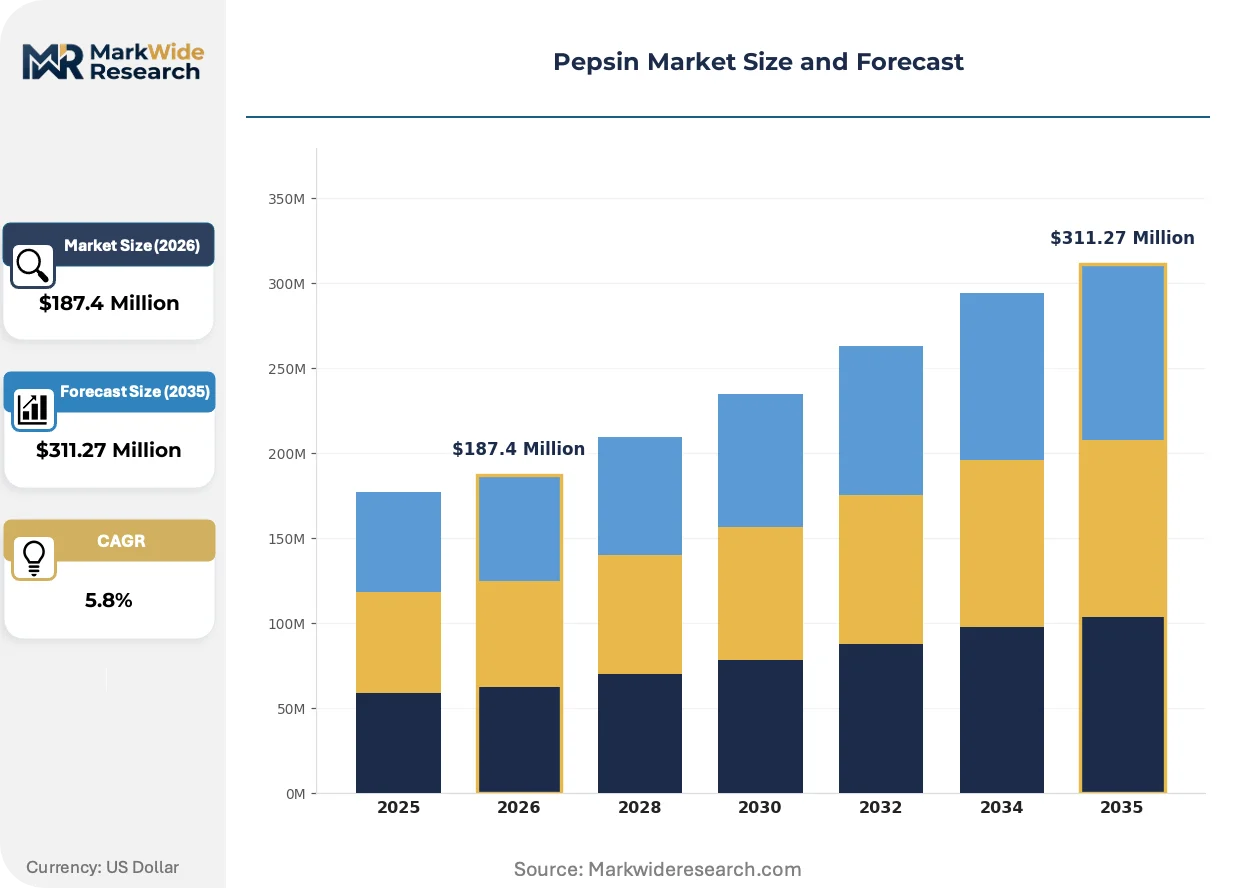
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymatic Pepsin, Pharmaceutical Pepsin, Food-Grade Pepsin, Industrial Pepsin Application: Food Processing, Pharmaceutical Formulation, Dietary Supplements, Animal Feed Additives End User: Food & Beverage Industry, Healthcare Providers, Nutraceutical Companies, Animal Nutrition Form: Powdered Form, Liquid Form, Tablet Form, Capsule Form |
| Companies Covered | Sichuan Deebio Pharmaceutical, Biolaxi, BIOFAC, Feideli Pharmaceutical, Vivatis Pharma, A. Constantino, Mitushi Pharma, Linzhang Hengyi, Amano Enzyme, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pepsin Market Emerging Trajectories
Process analytical technology is compressing batch release cycles. Suppliers now compete on real-time purity verification rather than post-hoc certificate analysis.
Recombinant enzyme expression platforms are digitizing quality assurance workflows. Biopharmaceutical contract manufacturers are adopting these systems for cell culture media preparation. The technology is digitizing documentation trails that previously required manual chromatographic validation, reducing release timelines from weeks to days.
China's NMPA tightened impurity profiling requirements for enzyme-derived actives in 2024. Domestic suppliers must now submit full peptide mapping data with each drug master file. Pharmaceutical-grade pepsin imports face extended technical review periods, redirecting procurement toward NMPA-registered domestic producers.
Aftermarket service unbundling is fragmenting buyer-supplier relationships. Large nutraceutical formulators now separate bulk enzyme procurement from analytical validation contracts. This pattern is most visible in North American and European markets where qualified third-party testing laboratories have proliferated.
Pepsin Market Segmentation
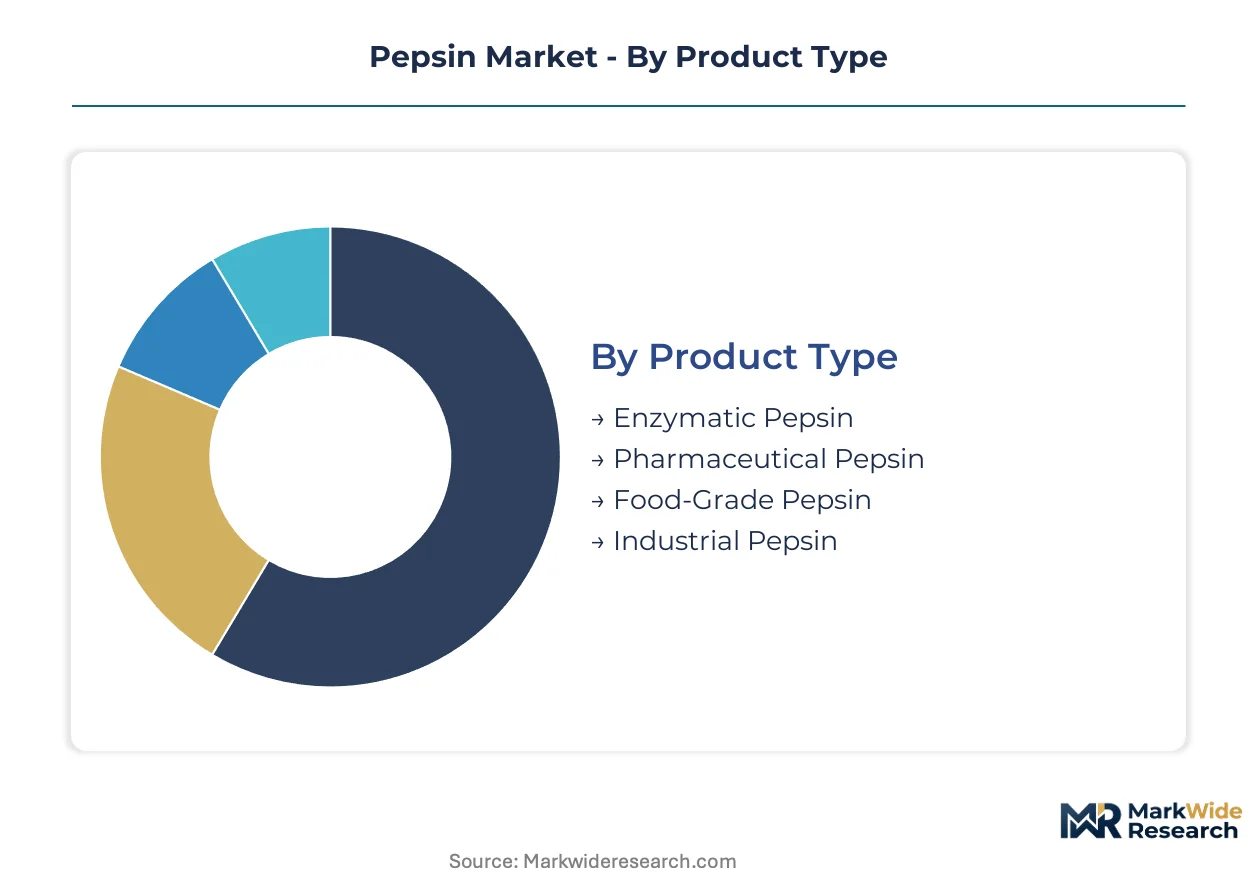
Pepsin procurement patterns diverge sharply across certification grades and delivery formats. Pharmaceutical buyers prioritize USP-grade documentation and batch-to-batch consistency, while food processors optimize for enzymatic activity per unit cost.
Product Type:
Pharmaceutical pepsin cycles through quality review in 4-6 weeks, while industrial grades move on spot pricing with 72-hour turnaround.
- Pharmaceutical Pepsin:USP-grade certification mandates peptide mapping and endotoxin testing for tablet and capsule formulations. Demand concentrates among CDSCO-registered Indian drugmakers and China's NMPA-compliant domestic producers seeking import substitution.
- Enzymatic Pepsin:Defined-activity units for cell culture and laboratory reagents, typically 1:10,000 to 1:15,000 activity specifications. Bioprocessing contract manufacturers in Germany and Switzerland drive procurement for regenerative medicine workflows.
- Food-Grade Pepsin:Standardized activity for cheese manufacturing and protein hydrolysate production.
- Industrial Pepsin:Bulk volume applications in leather processing and waste treatment with minimal purity requirements.
Pharmaceutical pepsin anchors the volume base while enzymatic pepsin gains share at the steepest rate.
Application:
Cost tier separation is pronounced: pharmaceutical formulation commands 8-12x pricing multiples over animal feed applications.
- Pharmaceutical Formulation:Digestive enzyme therapies for gastroparesis and hypochlorhydria, requiring FDA or EMA drug master file compliance. Sichuan and Henan extraction clusters supply domestic Chinese drugmakers alongside export-oriented European GMP facilities.
- Dietary Supplements:Capsule and tablet formats for gut health positioning in nutraceutical channels. North American contract manufacturers bundle analytical validation with bulk procurement to accelerate speed-to-shelf.
- Food Processing:Cheese curd formation and protein hydrolysis in dairy and savory flavor production.
- Animal Feed Additives:Digestive aid for swine and poultry nutrition with minimal regulatory oversight.
Dietary supplements deliver the highest margin contribution while pharmaceutical formulation maintains the most stable offtake commitments.
End User:
Customer type determines specification stringency: healthcare providers demand certificate of analysis per lot, while animal nutrition buyers accept certificate of conformance.
- Nutraceutical Companies:Clinically validated enzyme blends for digestive health SKUs, requiring 24-month stability data and accelerated aging protocols. These buyers separate bulk enzyme procurement from third-party analytical validation contracts.
- Healthcare Providers:Hospital formulary procurement of single-entity pepsin for rare digestive disorders, governed by pharmacopeial monograph compliance.
- Food & Beverage Industry:Standardized enzymatic activity for manufacturing process consistency.
- Animal Nutrition:Cost-optimized procurement for feed formulation with basic activity guarantees.
Food and beverage channels move the highest tonnage while nutraceutical companies are expanding their specification requirements most aggressively.
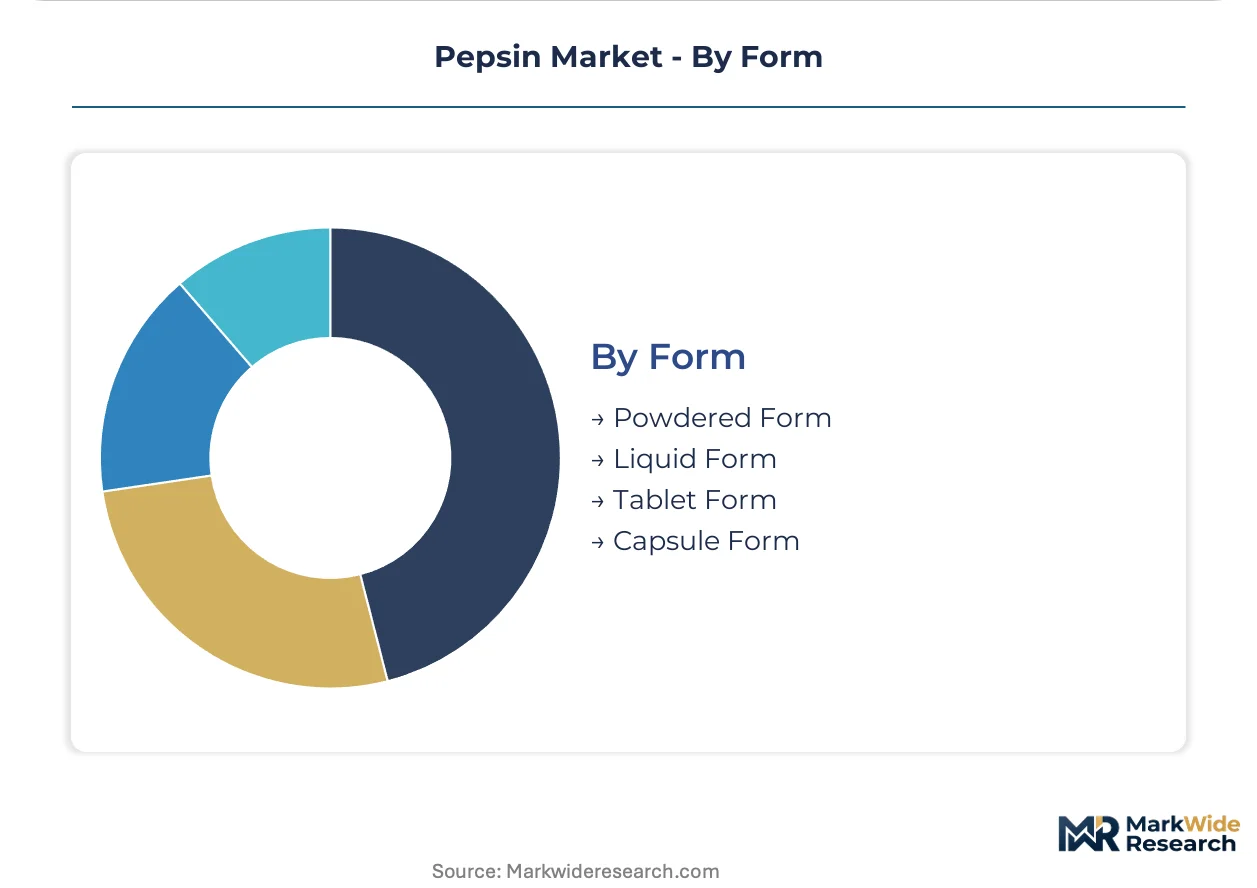
Form:
Supply concentration favors powder processing: Sichuan extraction facilities output 70%+ of global bulk powder before downstream formulation.
- Powdered Form:Bulk intermediate for tablet compression, capsule filling, and food processing integration. Chinese extraction clusters dominate upstream supply, with downstream formulation split between domestic Chinese drugmakers and European GMP finishers.
- Capsule Form:Enteric-coated and immediate-release configurations for nutraceutical and pharmaceutical channels. North American and European contract manufacturers specialize in finished dosage form production from imported powder.
- Liquid Form:Laboratory reagents and specialized digestive aids with defined pH stability windows.
- Tablet Form:Direct compression formats with excipient compatibility requirements.
Powdered form underpins upstream supply concentration while capsule form captures the most value-added margin in finished goods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extraction infrastructure clusters in China's interior provinces, while GMP-certified finishing capacity concentrates in Western Europe and North America. Regulatory divergence between FDA and NMPA purity standards forces multinational suppliers to maintain parallel quality systems. Each major demand zone exhibits distinct procurement patterns shaped by local pharmacopeial requirements and industrial specialization.
China
Sichuan and Henan provinces host the dominant pepsin extraction clusters, serving domestic drugmakers and export markets simultaneously. NMPA tightened impurity profiling requirements in 2024, mandating full peptide mapping data with each drug master file. Domestic suppliers in Chengdu and Zhengzhou are redirecting procurement toward NMPA-registered producers as import reviews extend.
United States
Nutraceutical formulators in North American markets drive demand for USP-grade pepsin with bundled analytical validation services. FDA enforces divergent purity monographs from Chinese standards, requiring separate manufacturing protocols for export-bound versus domestic production. Contract manufacturers in New Jersey and California specialize in finished dosage forms from imported powder intermediates.
Germany
Bioprocessing contract manufacturers in Germany and Switzerland anchor European demand for defined-activity enzymatic pepsin. REACH registration constrains porcine-derived imports without full toxicological dossiers, advantaging regional producers with established compliance infrastructure. BIOFAC operates GMP-certified fermentation and isolation capabilities serving regenerative medicine workflows.
India
CDSCO-registered drugmakers source pharmaceutical-grade pepsin for digestive enzyme therapies targeting gastroparesis and hypochlorhydria. The PLI scheme for active pharmaceutical ingredients incentivizes domestic enzyme manufacturing, potentially redirecting procurement from Chinese suppliers. Maharashtra and Gujarat formulation hubs are expanding technical capabilities for peptide-based drug production.
Japan
PMDA-compliant manufacturers prioritize batch-to-batch consistency in high-purity enzymatic grades for cell culture applications. Amano Enzyme leverages recombinant expression platforms to reduce variability in laboratory reagent specifications. Tokyo and Osaka biopharmaceutical clusters are digitizing quality assurance workflows for media preparation in regenerative medicine.
Pepsin Market Vendor Landscape
Vertically integrated extractors and specialized enzyme houses split the market into distinct capability tiers. Consolidation pressure favors suppliers that control porcine sourcing through captive slaughterhouse relationships or fermentation-based alternatives. Three archetypes dominate: upstream-integrated Chinese extractors with provincial cluster advantages, European GMP-certified finishers with regulatory compliance depth, and Japanese recombinant specialists with platform technology differentiation. Capacity expansion in India's PLI zones and strategic partnerships for analytical validation bundling represent the dominant competitive vectors.
Among Chinese extractors, Sichuan Deebio Pharmaceutical and Linzhang Hengyi occupy positions reflecting upstream integration into porcine sourcing infrastructure. European compliance-focused supply is anchored by BIOFAC, which exemplifies the GMP-certified archetype with established REACH dossiers. Amano Enzyme represents the recombinant platform specialist tier, reducing batch variability through engineered expression systems rather than animal-derived extraction.
| Leading Market Players |
|---|
| Sichuan Deebio Pharmaceutical |
| Biolaxi |
| BIOFAC |
| Feideli Pharmaceutical |
| Vivatis Pharma |
| A. Constantino |
| Mitushi Pharma |
| Linzhang Hengyi |
| Amano Enzyme |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Sichuan extraction facilities is compressing spot pricing for food-grade powder while extending pharmaceutical-grade contract lead times, forcing buyers to pre-commit volume through annual offtake agreements.
Pricing Analysis
Aftermarket analytical validation services now drive lifetime value more than bulk enzyme sales, with Sichuan Deebio and BIOFAC bundling peptide mapping and endotoxin testing into multi-year supply contracts. Pricing stratifies across USP-grade certification, food-grade standardization, and industrial-grade spot markets, with pharmaceutical buyers absorbing premiums for dual FDA-NMPA compliance documentation. Cost compression in food-grade tiers is intensifying as Henan extraction clusters expand capacity, while enzymatic pepsin for cell culture maintains pricing power through recombinant platform scarcity. Nutraceutical contract manufacturers exhibit highest price sensitivity, demanding unbundled procurement and third-party testing alternatives.
Supply Chain Analysis
Tariff exposure between Chinese extraction clusters and European REACH-registered finishers dominates supply chain risk planning, with porcine-derived intermediates facing extended customs clearance for toxicological dossier verification. Raw material supply draws from Sichuan and Henan slaughterhouse networks, German GMP-certified isolation facilities, and Japanese recombinant fermentation platforms. Single-source vulnerability concentrates in porcine gastric mucosa procurement, where African swine fever outbreaks in 2019-2020 demonstrated input cost volatility. Distribution runs through bulk powder intermediates to regional formulation hubs in New Jersey, Mumbai, and Basel for finished dosage conversion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as recombinant expression systems digitize quality assurance workflows, with Amano Enzyme's engineered proteases establishing interoperability standards that traditional extractors must adopt or exit high-purity segments.
For Market Incumbents: Entrench GMP-certified capacity through captive porcine sourcing agreements in Sichuan and Henan provinces, while accelerating ISO 13485 certification for medical device-grade pepsin to defend against recombinant substitution in cell culture applications. Backward integration into slaughterhouse infrastructure anchors cost position against African swine fever recurrence. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-incentivized API manufacturing zones, where domestic enzyme production incentives create procurement redirection opportunities from Chinese suppliers. Target CDSCO-registered drugmakers in Maharashtra and Gujarat with bundled analytical validation services, leveraging third-party chromatography specialists to circumvent skill scarcity barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across recombinant enzyme platforms, as digitized quality systems and peptide mapping infrastructure replace manual validation workflows. Acquisition targets should exhibit dual FDA-NMPA drug master file compliance or captive REACH dossier completion, with signal-to-watch being pharmacopeial harmonization announcements between USP, EP, and ChP standards that would reshape competitive access economics.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Completion | European market access for porcine-derived pepsin rests on ECHA toxicological registration, advantaging BIOFAC's established compliance infrastructure. |
| NMPA Drug Master File Registration | Domestic Chinese suppliers with full peptide mapping data capture procurement redirected from import-dependent drugmakers. |
| Recombinant Platform Investment | Engineered expression systems reduce batch-to-batch variability for PMDA-compliant manufacturers in regenerative medicine workflows. |
| Captive Slaughterhouse Integration | Upstream control over porcine gastric mucosa insulates Sichuan extractors from African swine fever input volatility. |
| ISO 13485 Certification Pathway | Medical device-grade pepsin qualification opens hospital formulary procurement for rare digestive disorder therapies. |
Methodological Framework
A spread of perspectives from extraction facility operators, GMP-certified finishers, nutraceutical procurement directors, CDSCO regulatory affairs leads, and bioprocessing contract manufacturers converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation against FDA drug master file submissions, NMPA registration databases, EMA quality documentation, and REACH registration records. Bottom-up volume estimates from Sichuan and Henan production clusters were triangulated against top-down pharmaceutical formulation demand from Indian and European drugmakers.
Demand-supply balance modeling across the analysis window incorporated product type segmentation by certification grade, application tier from pharmaceutical formulation to animal feed, end-user specification stringency, and powdered versus finished dosage form. CAGRs were derived from growth driver elasticity estimates applied to baseline extraction capacity and pharmacopeial harmonization scenarios. Forecast inputs included PLI scheme implementation timelines in India, NMPA impurity profiling enforcement intensity, and recombinant protease substitution rates in laboratory reagent channels.
Sensitivities concentrate around African swine fever recurrence patterns, pharmacopeial standard alignment negotiations, and REACH dossier approval delays for porcine-derived imports. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Non-GMO Oil Market
Ingredients
Commercial Amino Acids Market
Ingredients
Glucomannan Market
Ingredients
Asia-Pacific Dairy Ingredients Market
Ingredients
Yeast Derivatives Market
Ingredients
Pulses Ingredients Market
Ingredients
North America Gums Market
Ingredients
Asia-Pacific Lipids Market
Ingredients
Spray-Dried Isolate Market
Ingredients
Gum Arabic Market
Ingredients
India Gelatin Market
Ingredients
Sugared Egg Yolk Market
Ingredients
Australia Soy Protein Market
Ingredients
Tryptose Market
Ingredients
Sunflower Protein Market
Ingredients
Camelina Oil Market