
 Virginiamycin Market | 2026-2036
Virginiamycin Market Size, Share, and Industry Trends Forecast 2026-2036
Virginiamycin Market Analytics
Feed-milling conglomerates is bifurcating demand away from small independent livestock producers across the virginiamycin value chain. Phibro Animal Health Corporation leverages captive fermentation capacity to secure raw material continuity for its virginiamycin complexes. Zoetis anchors North American distribution through veterinary clinic partnerships and direct-to-feed-mill logistics networks. Merck Animal Health competes on regulatory dossier breadth, maintaining approvals across multiple species and geographies.
Virginiamycin comprises a streptogramin antibiotic complex produced via submerged fermentation of Streptomyces virginiae, yielding primarily virginiamycin M1 and S1 factors effective against Gram-positive pathogens and used for growth promotion and disease prevention in food animal production. Powder formulations dominate commercial volumes due to blending compatibility with mash and pelleted feeds, though oral suspensions capture margin in therapeutic veterinary channels where precision dosing commands premium positioning. The livestock end-user segment sustains baseline demand through cattle feedlot applications, while poultry operations represent the fastest-expanding consumption pool as integrators standardize on virginiamycin-salinomycin rotation programs.
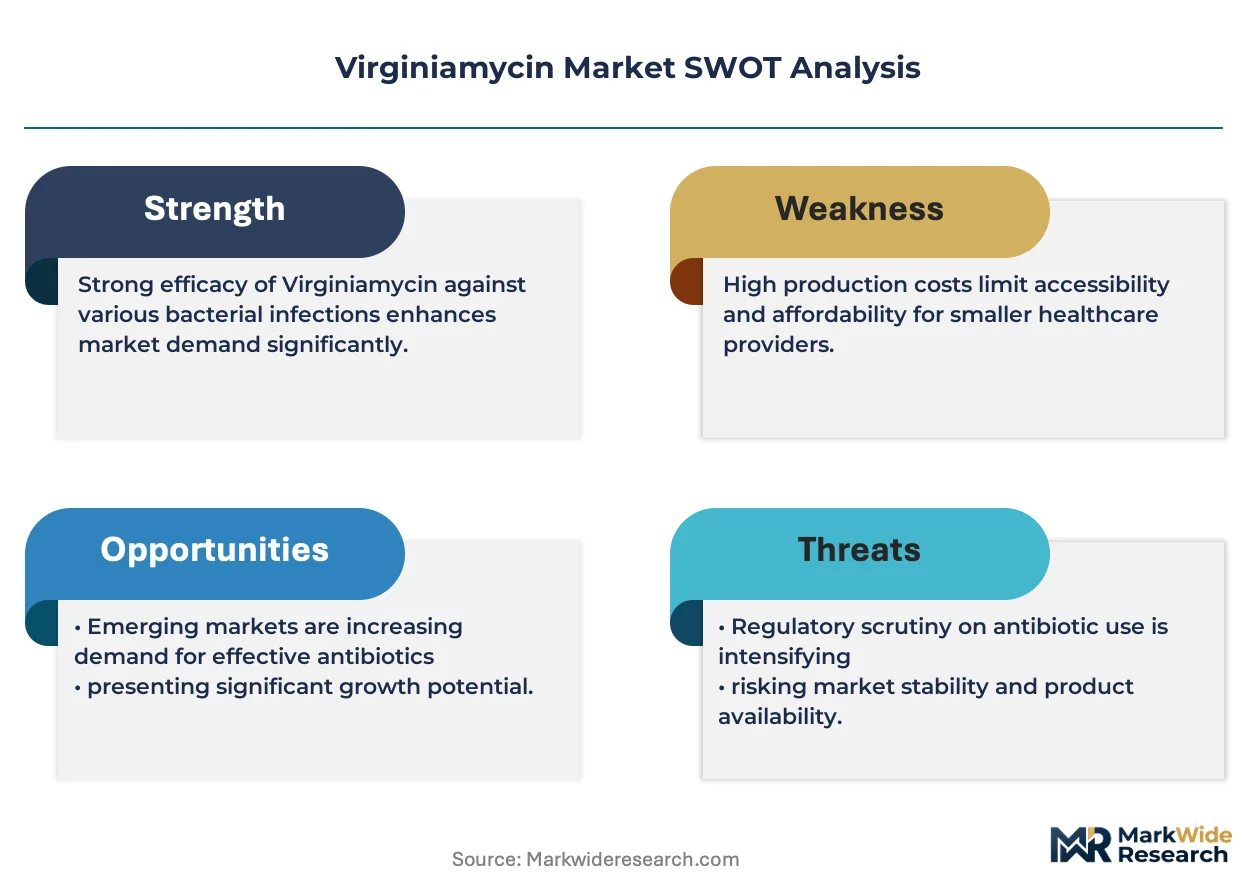
The FDA's Veterinary Feed Directive mandates veterinary oversight for all medically important antibiotics in feed, compelling distributors to maintain prescription verification infrastructure and reshaping channel economics for virginiamycin sales. Brazil's MAPA and the EU's EMA operate divergent residue monitoring frameworks, creating compliance complexity for manufacturers serving multiple export markets. Stakeholders must monitor evolving regulatory science on antimicrobial resistance linkages to streptogramin use, as future class restrictions would force rapid reformulation investment across installed feed additive portfolios.
Market Dynamics
The FDA's Veterinary Feed Directive has restructured channel economics by mandating veterinary oversight for all medically important antibiotics in feed, forcing distributors to build prescription verification infrastructure and reshaping how virginiamycin reaches end-users.
Growth Catalysts
- Poultry Integrator Consolidation:Vertically integrated broiler operations in Brazil are standardizing on virginiamycin-salinomycin rotation programs, creating volume pull through multi-year supply contracts.
- EMA Residue Monitoring Harmonization:Streamlined veterinary medicinal product frameworks across EU member states are reducing regulatory friction for feed-grade antibiotic approvals.
- Fermentation Yield Improvements:Bioprocess optimization in submerged Streptomyces virginiae cultivation is lowering unit production costs for M1 and S1 factor complexes.
Market Restraints
- Streptogramin Cross-Resistance Linkages:EMA and FDA regulatory science reviews on antimicrobial resistance are creating uncertainty about future class restrictions for human-relevant antibiotic classes.
- Feed-Grade API Supply Concentration:Captive fermentation capacity is concentrated among three manufacturers, creating raw material continuity risks for non-integrated formulators.
- Salinomycin Substitution Pressure:Ionophore coccidiostats are capturing rotation program share in poultry operations seeking non-antibiotic alternatives for export markets.
Strategic Opportunities
- Vietnamese Aquaculture Penetration:Shrimp and catfish producers are adopting virginiamycin for bacterial disease prevention in intensive pond systems, opening species expansion beyond terrestrial livestock.
- Precision Dosing Formulation:Micro-encapsulation technology is enabling water-soluble presentations for therapeutic veterinary channels where oral suspensions command premium positioning.
- USDA Organic Transition Incentives:Livestock operations pursuing organic certification are creating demand for withdrawal-compliant antibiotic programs that virginiamycin supports.
Industry Challenges
- Veterinary Prescription Infrastructure:Feed mills must integrate electronic prescription verification systems to comply with FDA documentation standards, requiring IT investment and staff training.
- Multi-Jurisdiction Dossier Maintenance:Manufacturers face divergent residue monitoring frameworks across Brazil's MAPA, the EU's EMA, and the FDA, multiplying compliance costs for export-oriented production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virginiamycin Market |
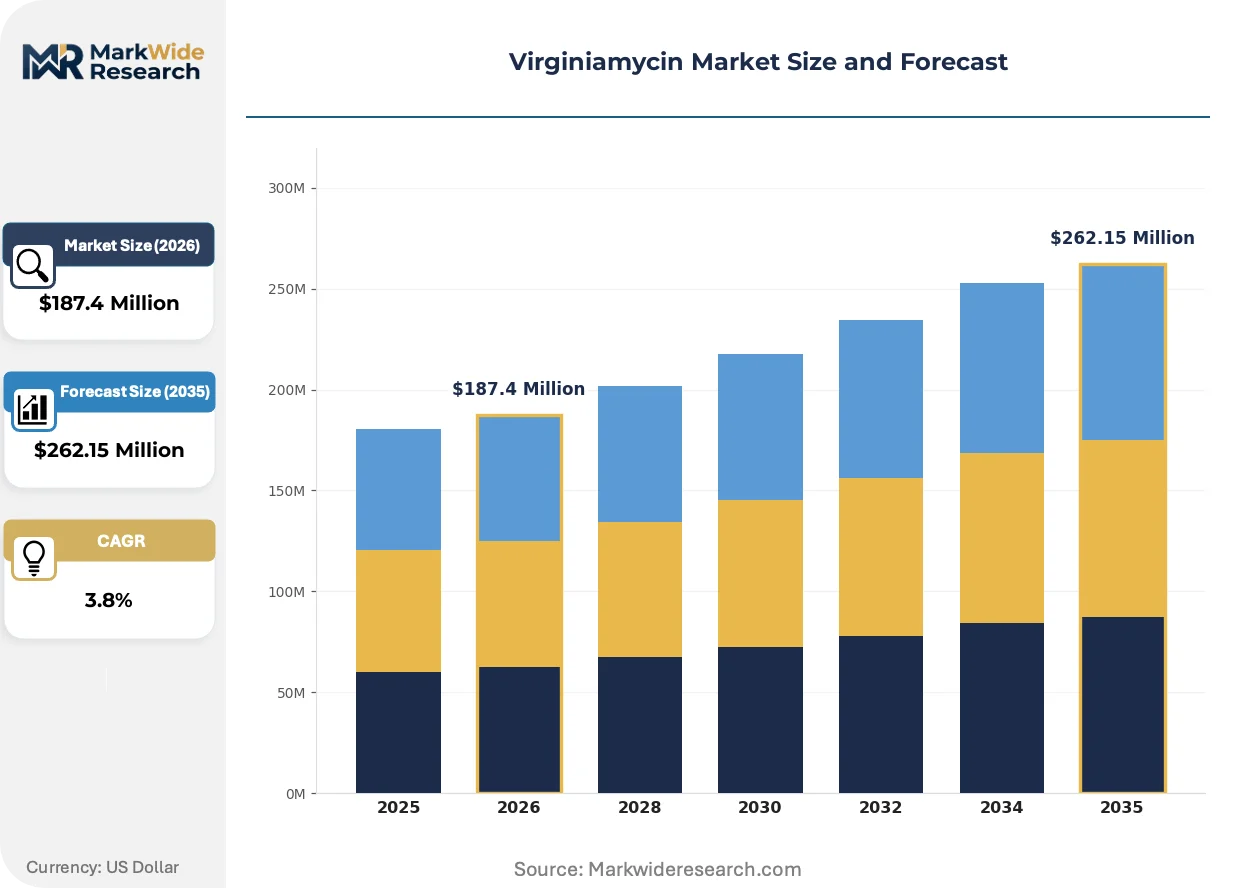
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral, Suspension, Powder Application: Animal Feed, Therapeutic Use, Veterinary Medicine, Feed Additive End User: Livestock, Poultry, Aquaculture, Companion Animals Distribution Channel: Online Sales, Retail Pharmacies, Veterinary Clinics, Distributors |
| Companies Covered | Merck Animal Health, Bayer Animal Health, Zoetis, Ceva, Virbac, Phibro Animal Health Corporation, DSM, Boehringer Ingelheim, Elanco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virginiamycin Market Evolving Landscape
Formulation science and regulatory compliance infrastructure are converging to reshape how virginiamycin moves from fermentation tanks to feed mills, with technology investments concentrating on precision delivery and documentation automation.
Micro-encapsulation of virginiamycin complexes is miniaturizing particle size distribution to enable uniform blending in pelleted feeds and controlled release in rumen environments. Large-scale feed manufacturers in the US Midwest are adopting these engineered particles to meet FDA blending homogeneity requirements. The technology is miniaturizing the effective dose window while reducing feed matrix interactions that previously degraded potency.
REACH authorization timelines for veterinary feed additives are compressing market entry pathways for novel formulations in EU member states. Manufacturers are pre-submission consulting with EMA scientific committees to align residue depletion studies with MRL harmonization protocols. Poultry export operations in Poland and Hungary are most affected, accelerating investment in analytical testing infrastructure to verify compliance.
Direct-to-feed-mill logistics networks are displacing traditional veterinary clinic distribution for volume virginiamycin premix contracts. Large integrators in Brazil's southern poultry belt are negotiating annual procurement agreements that bypass distributor markups. This channel restructuring is most visible in Santa Catarina and Paraná, where vertically coordinated production systems dominate broiler output.
Virginiamycin Market Segmentation
Virginiamycin flows through distinct channel configurations depending on formulation physics and end-use scale. Understanding these pathways clarifies where margin pools concentrate and where regulatory friction reshapes access economics.
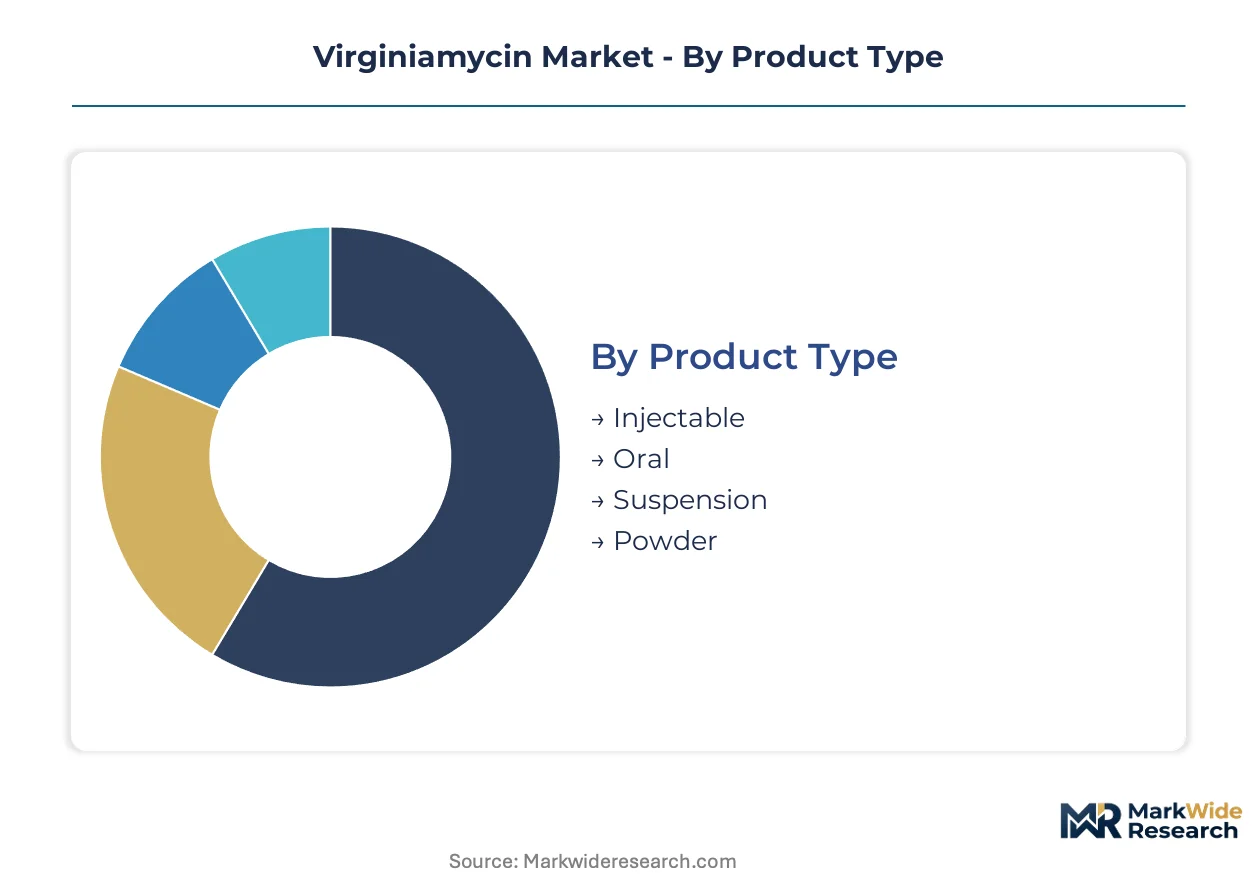
Product Type:
Channel economics diverge sharply between feed-grade bulk formulations and precision-dosed therapeutic presentations, with powder dominating volume contracts and oral suspensions capturing veterinary clinic premiums.
- Powder:Dry virginiamycin complexes blend uniformly into mash and pelleted feeds, serving feed-mill procurement at scale. Brazilian poultry integrators in Santa Catarina and Paraná negotiate annual volume contracts that bypass distributor markups entirely.
- Oral:Liquid presentations enable therapeutic administration in cattle feedlots where individual animal dosing replaces mass medication protocols. Demand clusters in US Midwest feedlot operations subject to FDA Veterinary Feed Directive prescription verification requirements.
- Suspension:Water-soluble micro-encapsulated variants penetrate Vietnamese aquaculture systems for shrimp and catfish bacterial disease prevention.
- Injectable:Parenteral formulations serve companion animal veterinary channels where precision therapy commands premium positioning against systemic Gram-positive infections.
Powder dominates installed base. Oral is where expansion concentrates.
Application:
Regulatory jurisdiction determines formulation requirements, with feed-grade applications facing veterinary oversight mandates that therapeutic channels have long absorbed.
- Animal Feed:Growth promotion and coccidiosis prevention in broiler operations drive baseline consumption. Brazil's vertically integrated processors standardize on virginiamycin-salinomycin rotation programs through multi-year supply agreements.
- Feed Additive:Premix formulations integrate into compound feed manufacturing, requiring homogeneity verification under FDA blending standards. US feed manufacturers invest in analytical testing infrastructure to verify compliance.
- Therapeutic Use:Targeted bacterial disease treatment in intensive livestock systems operates under stricter prescription protocols, concentrating demand in veterinary-supervised channels.
- Veterinary Medicine:Clinical diagnosis and treatment applications serve smaller-scale producers outside integrated supply chains, relying on retail pharmacy and clinic distribution.
Animal Feed anchors volume consumption. Feed Additive is climbing the fastest as direct-to-mill procurement displaces traditional distribution.
End User:
Species-specific pharmacokinetics and residue monitoring frameworks create divergent compliance burdens across livestock categories.
- Poultry:Broiler integrators in Brazil's southern belt drive the steepest demand trajectory, with rotation programs replacing single-agent coccidiostat protocols. MAPA residue monitoring frameworks govern export-oriented production.
- Livestock:Cattle feedlot applications sustain baseline demand through growth promotion and liver abscess prevention, particularly in North American operations.
- Aquaculture:Intensive shrimp and catfish pond systems in Vietnam adopt virginiamycin for bacterial disease prevention, opening species expansion beyond terrestrial production.
- Companion Animals:Small-animal veterinary channels represent marginal volume but premium pricing for therapeutic formulations.
Livestock maintains the broadest installed base. Poultry is gaining share fastest through integrator consolidation.
Distribution Channel:
Channel restructuring accelerates as volume buyers bypass intermediary markups and regulatory documentation requirements reshape logistics economics.
- Distributors:Traditional wholesale networks retain relevance for mid-scale feed manufacturers lacking direct manufacturer relationships, though margin compression intensifies.
- Veterinary Clinics:Prescription verification infrastructure under FDA Veterinary Feed Directive consolidates therapeutic channel control, with Zoetis anchoring North American clinic partnerships.
- Online Sales:Digital procurement platforms emerge for smaller producers seeking compliance documentation and competitive pricing transparency.
- Retail Pharmacies:Community veterinary supply points serve companion animal and small-livestock producers outside integrated systems.
Distributors retain the deepest installed relationships. Direct-to-feed-mill logistics are displacing traditional intermediaries fastest in high-volume poultry markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos in São Paulo State anchors South American virginiamycin trade flows, handling bulk fermentation-derived antibiotics for redistribution across Mercosur feed markets. Brazil's southern poultry belt and Vietnam's Mekong Delta aquaculture corridors concentrate demand for streptogramin-based disease prevention programs.
Brazil
Vertically integrated broiler processors in Santa Catarina and Paraná standardize on virginiamycin-salinomycin rotation protocols through multi-year supply contracts. MAPA residue monitoring frameworks govern export-oriented production destined for EU and Middle Eastern markets. Direct-to-feed-mill procurement in Chapecó and Cascavel bypasses traditional distributor markups entirely.
United States
Midwest cattle feedlot operations sustain baseline consumption through liver abscess prevention programs in Nebraska and Kansas finishing yards. FDA Veterinary Feed Directive mandates electronic prescription verification infrastructure, reshaping channel economics for medicated feed distribution. Iowa and Illinois feed manufacturers invest in analytical testing capacity to verify blending homogeneity compliance.
Vietnam
Intensive shrimp and catfish pond systems in the Mekong Delta adopt virginiamycin for bacterial disease prevention in Bac Lieu and Ca Mau provinces. The country's national veterinary regulator maintains residue surveillance protocols aligned with EU import requirements. Can Tho-based aquafeed mills negotiate direct procurement agreements with fermentation suppliers.
Germany
Compound feed manufacturers in Lower Saxony and North Rhine-Westphalia integrate virginiamycin premixes for export-oriented pork production. EMA veterinary medicinal product frameworks streamline approval pathways across EU member states. Münsterland feed clusters invest in micro-encapsulation technology to meet precision dosing specifications.
China
Integrated livestock operations in Shandong and Henan provinces drive formulation demand for swine and poultry disease prevention. NMPA veterinary drug registration protocols govern import substitution strategies for domestic fermentation capacity. Qingdao feed industry zones concentrate blending infrastructure for regional distribution networks.
Virginiamycin Market Competitive Landscape
Concentration sits with captive fermentation specialists who control submerged Streptomyces virginiae cultivation capacity. Three manufacturers dominate raw material supply for virginiamycin M1 and S1 factor complexes, creating continuity dependencies for non-integrated formulators. Strategic archetypes split between fermentation-integrated API producers and formulation-specialized distributors. Competitive moves center on backward integration into fermentation assets and geographic expansion through direct-to-mill logistics networks.
Among North American animal health corporations, Merck Animal Health, Zoetis, and Phibro Animal Health Corporation occupy positions across the value chain. Merck Animal Health exemplifies the regulatory dossier breadth archetype, maintaining multi-species approvals across divergent geographies. Zoetis anchors distribution infrastructure through veterinary clinic partnerships and feed-mill direct logistics. Phibro Animal Health Corporation represents captive fermentation integration, securing upstream control over raw material continuity for antibiotic complexes.
| Leading Market Players |
|---|
| Merck Animal Health |
| Bayer Animal Health |
| Zoetis |
| Ceva |
| Virbac |
| Phibro Animal Health Corporation |
| DSM |
| Boehringer Ingelheim |
| Elanco |
| Others |
Value Network & Pricing Analysis
Multi-year offtake agreements between Brazilian poultry integrators and fermentation suppliers lock in both virginiamycin supply access and price visibility across volatile raw material cycles. These contracts insulate volume buyers from spot market fluctuations in Streptomyces virginiae feedstocks while committing suppliers to dedicated M1 and S1 factor production capacity.
Pricing Analysis
Volume-discount tiering structures separate annual contract purchasers from spot-market buyers across the virginiamycin value chain. Pricing stratifies across feed-grade bulk, micro-encapsulated premium, and therapeutic oral suspension tiers based on formulation complexity and regulatory documentation depth. Cost compression in standard powder grades is intensifying as Brazilian integrators consolidate procurement leverage through direct-to-mill negotiations. Small independent feed manufacturers exhibit the highest price sensitivity, lacking scale to bypass distributor markups or qualify for tier-one contract thresholds.
Supply Chain Analysis
Port congestion at Santos and container availability constraints on Asia-Pacific trade lanes intermittently disrupt virginiamycin premix shipments to Vietnamese aquafeed mills. Fermentation capacity concentrates in the United States, Brazil, and China, with captive Streptomyces virginiae cultivation facilities anchoring upstream supply. Raw material dependencies include pharmaceutical-grade substrate media, specialized fermentation vessel alloys, and purified water systems. Single-source vulnerability pervades non-integrated formulators lacking backward integration into API production. Distribution runs through direct-to-feed-mill logistics networks for high-volume poultry contracts, while veterinary clinic channels serve therapeutic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The virginiamycin market is entering a cyclical recovery phase as Brazilian broiler production cycles rebound from avian influenza disruptions and feed additive restocking accelerates.
For Market Incumbents: Consolidate fermentation capacity utilization through multi-year supply agreements with MAPA-certified Brazilian exporters facing EMA residue scrutiny. Deepen backward integration into Streptomyces virginiae strain optimization to defend margins against salinomycin substitution pressure in rotation programs. Channel control through veterinary clinic partnerships remains critical for therapeutic-tier pricing power. For New Entrants and Emerging Players: Precision-dosing formulation gaps in Vietnamese aquaculture channels present accessible white-space where incumbent fermentation specialists under-serve shrimp and catfish producers. Target Bac Lieu and Ca Mau provinces with water-soluble micro-encapsulated variants through direct technical sales to Can Tho-based feed mills. Partner with regional distributors possessing existing MAPA documentation infrastructure to accelerate market entry. For Investors and Strategic Acquirers: Capital is best deployed toward fermentation-integrated API producers with captive Streptomyces virginiae capacity and multi-jurisdiction regulatory dossiers. Long-term viability hinges on antimicrobial resistance policy durability across the five-to-ten-year window. Monitor EMA and FDA regulatory science reviews on streptogramin cross-resistance linkages as the primary inflection signal for class-wide restriction risk.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fermentation Capacity Expansion | Secures upstream control over virginiamycin M1 and S1 factor raw material continuity for integrated formulators. |
| Micro-Encapsulation Technology Licensing | Enables precision dosing formulations for Vietnamese aquaculture channels commanding premium positioning. |
| Direct-to-Feed-Mill Logistics Network | Bypasses distributor markups in Brazil's Santa Catarina and Paraná poultry belts where integrator consolidation concentrates. |
| EMA Multi-Species Dossier Expansion | Streamlines approval pathways across EU member states for export-oriented Brazilian premix manufacturers. |
| Prescription Verification Infrastructure | Complies with FDA Veterinary Feed Directive mandates for electronic documentation in US medicated feed distribution. |
Research Methodology
Operator-level perspectives from fermentation plant managers, poultry integrator procurement directors, feed mill quality control leads, and veterinary regulatory affairs specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FDA Veterinary Feed Directive guidance documents, EMA veterinary medicinal product frameworks, MAPA residue monitoring protocols, and Brazilian agricultural trade statistics. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Sensitivity analysis tested forecast robustness against regulatory restriction scenarios and raw material supply disruptions. Segmentation dimensions modeled include formulation type, application channel, end-user species, and distribution configuration alongside regional regulatory cluster variations. CAGRs were derived from production capacity expansion timelines and integrator procurement contract visibility. Forecast inputs incorporated fermentation yield improvement trajectories and veterinary prescription infrastructure penetration rates.
Material uncertainties — antimicrobial resistance policy shifts, streptogramin class restriction decisions, and feed-grade API supply concentration events — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory continuity and production technology diffusion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Isoamyl Laurate Market
Ingredients
Wheat Malt Market
Ingredients
Wheat Starch Market
Ingredients
Mineral Premix Market
Ingredients
Omega Ingredients Market
Ingredients
Shortening Fats Market
Ingredients
Sweet Almond Oil Market
Ingredients
Organic Pastry Flour Market
Ingredients
Bovine Gelatin Market
Ingredients
China Soy Protein Market
Ingredients
Specialty Malt Market
Ingredients
Asia-Pacific Yeast and Yeast Extract Market
Ingredients
Starches/Glucose Market
Ingredients
Egg Membrane Powder Market
Ingredients
US Choline Bitartrate Market
Ingredients
Olive Leaf Extract Market