
 Rice Starch Market | 2026-2036
Rice Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Rice Starch Market Outlook
Software-defined ingredient customization is consolidating how rice starch suppliers package value around their base commodities. Ingredion leverages formulation partnerships with multinational food manufacturers to sustain premium positioning in modified starch applications. Roquette anchors European supply through its plant-based ingredient expertise, while BENEO competes on prebiotic rice starch derivatives for digestive health positioning.
Rice starch consists of amylose and amylopectin polysaccharides extracted from milled rice, typically containing 15-30% amylose depending on cultivar, and functions as a gelling agent, texturizer, and fat replacer across food and industrial applications. Native starch occupies the volume base for cost-sensitive food manufacturing, while modified starch commands margin pools where thermal stability and acid resistance prove critical for processed sauces and convenience meals. Pre-gelatinized starch is accelerating in instant food applications where cold-water solubility eliminates cooking steps for ready-to-eat formulations.
FDA food additive regulations and GRAS self-affirmation pathways shape U.S. market access timelines for novel rice starch modifications, while REACH registration requirements in Europe govern chemical safety profiles for modified grades. The EU Green Deal sustainability benchmarks are pressuring suppliers to document carbon intensity across paddy-to-powder supply chains. Stakeholders must monitor evolving clean-label certification schemes and regional carbon border adjustments to preserve competitive positioning without explicit regulatory harmonization.
Market Dynamics
Clean-label substitution pressure from food manufacturers is compressing synthetic thickener demand while concentrating procurement around certified rice starch suppliers with documented paddy-to-powder traceability.
Growth Catalysts
- EU Green Deal sustainability mandates:Carbon intensity documentation requirements are accelerating supplier certification investments across European food manufacturing supply chains.
- Instant food formulation demand:Pre-gelatinized rice starch eliminates cooking steps for ready-to-eat meals, pulling volume from conventional native starch applications.
- Southeast Asian paddy concentration:Thailand and Vietnam dominate raw material sourcing, creating procurement efficiency for regional processing infrastructure.
Market Restraints
- Input cost volatility:Paddy rice prices fluctuate with monsoon patterns and irrigation constraints across Mekong Delta cultivation zones.
- Supply concentration risk:Modified starch technical expertise clusters among European and North American processors, creating geographic dependency for premium grades.
- REACH registration friction:ECHA chemical safety documentation requirements extend market access timelines for novel rice starch modifications entering European food applications.
Strategic Opportunities
- Prebiotic positioning:Resistant starch derivatives targeting digestive health applications command margin premiums in functional food and nutraceutical channels.
- Carbon border adjustment readiness:Early compliance with EU Green Deal benchmarks creates competitive insulation against 2026-2035 phased tariff implementations.
- Cold-water solubility innovation:Instant beverage and bakery premix applications represent underpenetrated demand pools for pre-gelatinized formulations.
Industry Challenges
- Clean-label certification complexity:Multiple non-harmonized schemes across organic, non-GMO, and carbon-neutral standards fragment compliance resource allocation.
- Modified starch R&D capex intensity:Thermal stability and acid resistance property development requires pilot-scale extrusion and testing infrastructure.
- GRAS self-affirmation expertise scarcity:FDA food additive pathway navigation demands specialized regulatory affairs capacity that mid-tier suppliers struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rice Starch Market |
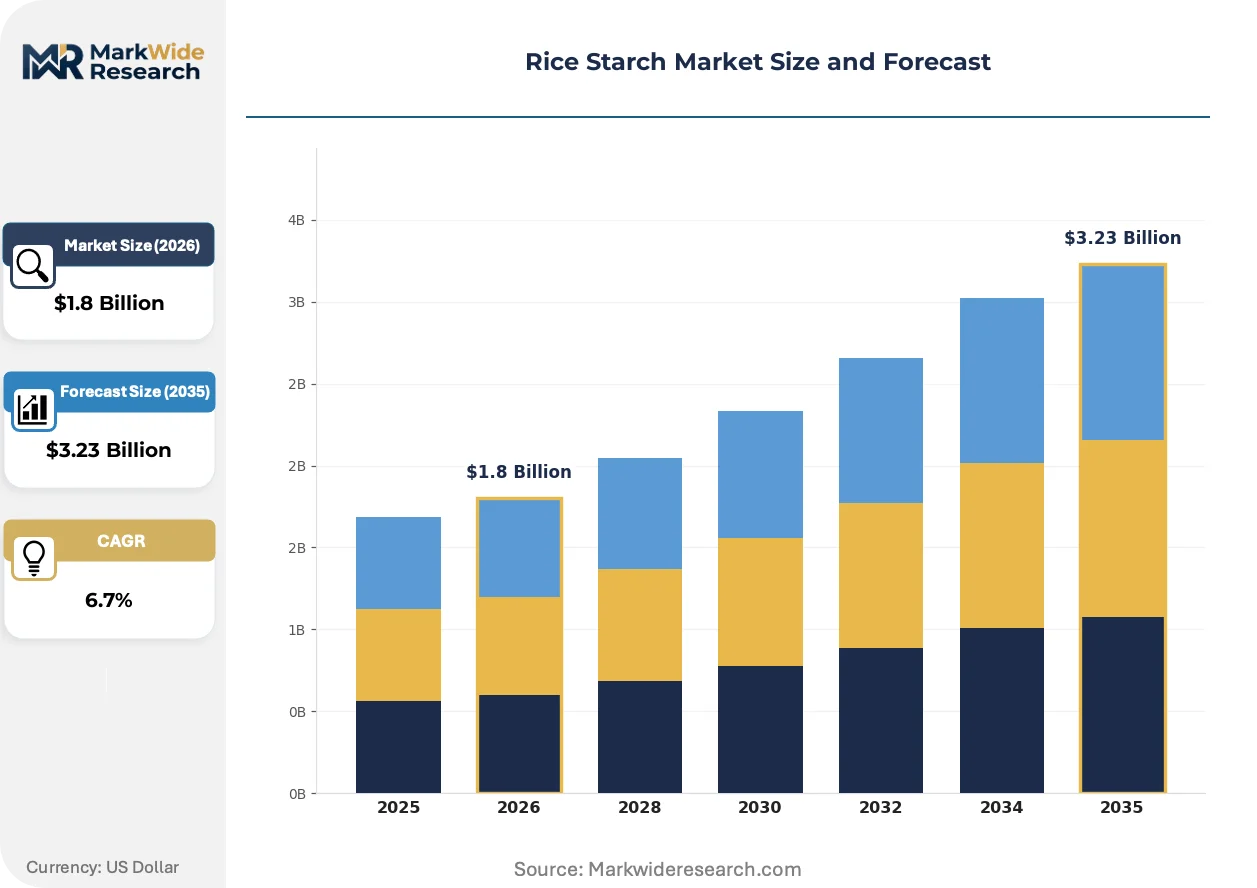
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Modified Starch, Pre-gelatinized Starch, Instant Starch Application: Food & Beverage, Pharmaceuticals, Cosmetics, Paper Coating End User: Food Manufacturers, Personal Care Brands, Pharmaceutical Companies, Paper Mills Distribution Channel: Online Stores, Distributors, Wholesalers, Direct Sales |
| Companies Covered | AGRANA, Thai Flour Industry, BENEO, Thai Wah, Roquette, Ingredion, Bangkok Starch, WFM Wholesome Foods, Ebro Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rice Starch Market Strategic Shifts
Formulation science is converging with sustainability verification to reshape how rice starch suppliers package value, moving beyond commodity pricing toward certified ingredient systems with embedded technical service.
Enzymatic modification technologies are expanding into precision texturization applications where controlled molecular weight reduction enables fat-mimetic mouthfeel in plant-based meat and dairy alternatives. European sauce manufacturers are adopting these systems at pilot scale. The technology is expanding into premium positioning that separates technical-grade suppliers from commodity native starch traders.
REACH registration requirements for modified starch grades are tightening chemical safety documentation standards across European food additive supply chains. ECHA substance evaluation protocols now demand extended toxicity datasets for novel cross-linked derivatives. Processed sauce and convenience meal manufacturers are consolidating supplier relationships around established registrants with complete dossiers.
Buyer concentration among multinational food manufacturers is compressing formulation partnership timelines and unbundling traditional distributor relationships. Technical service and co-development agreements are displacing spot procurement for modified starch applications. This pattern is most visible in North American and European processed food sectors where procurement teams consolidate approved supplier lists.
Rice Starch Market Segmentation
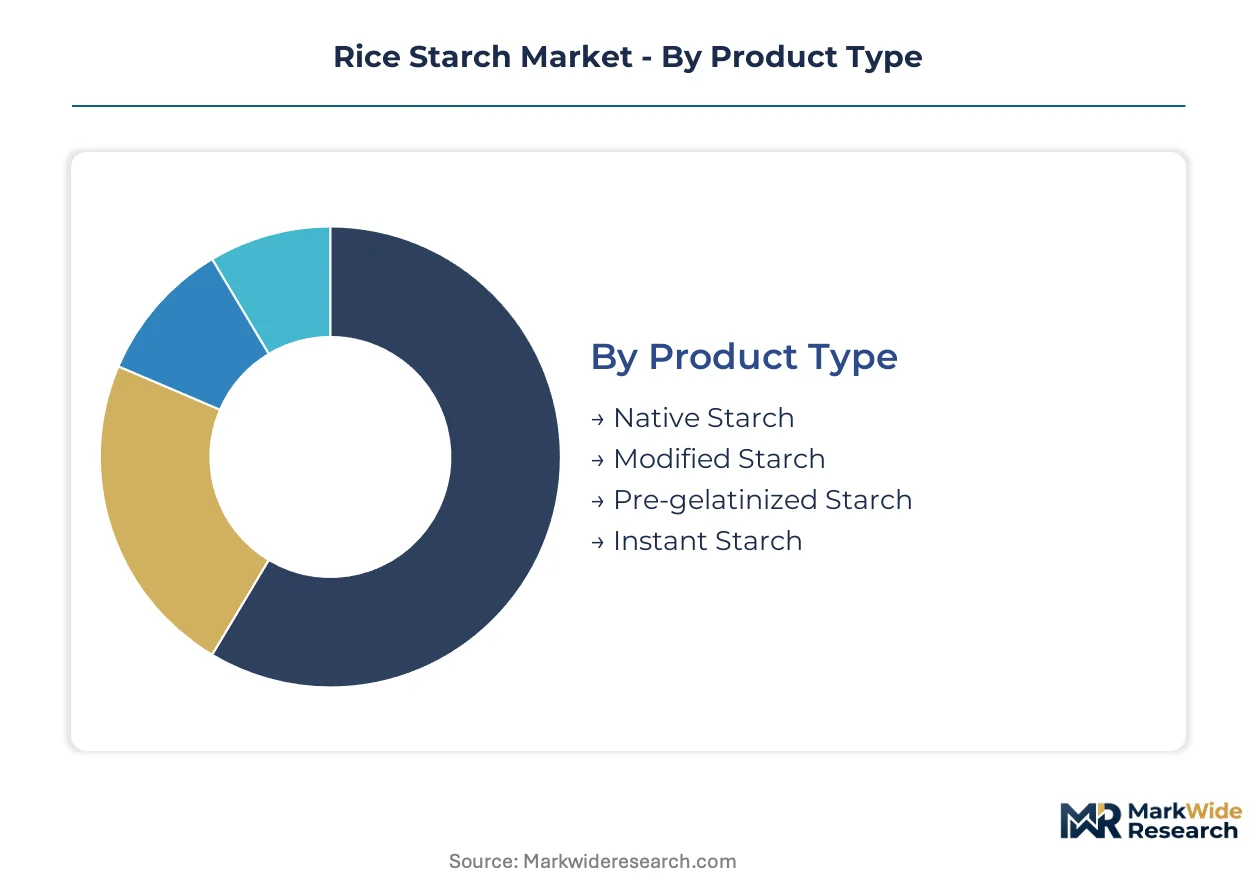
Rice starch segmentation reflects divergent paths between commodity volume plays and premium functional positioning. Suppliers configure production assets around either cost-efficient native extraction or capital-intensive modification capabilities.
Product Type:
The customization-vs-standardization spectrum spans unmodified commodity grades through precision-engineered derivatives with tailored rheological profiles.
- Native Starch:Extracted through wet-milling without chemical or enzymatic alteration, retaining natural amylose-amylopectin ratios. Food manufacturers in Thailand and Vietnam source this grade for cost-sensitive noodle and snack applications where basic thickening suffices. Paddy price volatility directly compresses margins here.
- Modified Starch:Cross-linked, acetylated, or oxidized variants deliver thermal stability and acid resistance for retort-processed sauces. European sauce manufacturers consolidate procurement around established REACH registrants with complete ECHA dossiers.
- Pre-gelatinized Starch:Cold-water soluble grades eliminate cooking steps for instant food premixes.
- Instant Starch:Agglomerated particles engineered for rapid dispersion in beverage applications.
Leading the category by volume: Native Starch. Growing fastest: Modified Starch.
Application:
End-use concentration tracks regulatory intensity, with food-grade certification requirements creating tiered entry barriers across segments.
- Food & Beverage:Gelling, texturizing, and fat-replacing functions across sauces, bakery, and confectionery. Clean-label substitution pressure from synthetic thickeners concentrates procurement around certified suppliers with documented paddy-to-powder traceability.
- Pharmaceuticals:Excipient applications for tablet binding and controlled-release formulations. FDA GRAS self-affirmation pathways and EMA excipient master file requirements extend supplier qualification timelines.
- Cosmetics:Powder base and absorbent applications in personal care formulations.
- Paper Coating:Surface sizing and binding for specialty paper grades.
Food & Beverage commands the revenue base. Pharmaceuticals offers the steepest expansion trajectory.
End User:
Buyer scale determines service model, with multinational food manufacturers demanding co-development partnerships while regional mills accept spot procurement.
- Food Manufacturers:Multinational processed food companies drive modified starch specifications through technical service agreements. Procurement teams consolidate approved supplier lists around formulation partnership capabilities.
- Personal Care Brands:Cosmetic formulators seek prebiotic rice starch derivatives for digestive health positioning in nutricosmetic applications.
- Pharmaceutical Companies:Generic drug manufacturers and contract development organizations source excipient-grade material.
- Paper Mills:Specialty paper producers in Japan and Germany specify coating starches for printability enhancement.
Food Manufacturers dominate procurement volume. Personal Care Brands are expanding most quickly.
Distribution Channel:
Channel selection reflects order scale and technical service requirements, with direct relationships displacing traditional intermediaries for modified grades.
- Direct Sales:Technical-grade modified starches move through supplier-direct relationships with multinational food manufacturers. Co-development agreements and formulation partnerships unbundle traditional distributor roles.
- Distributors:Regional ingredient distributors aggregate native starch volumes for mid-tier food processors lacking direct supplier relationships.
- Wholesalers:Commodity-grade material for small-scale paper mills and regional cosmetic manufacturers.
- Online Stores:Sample quantities and specialty grades for research institutions and artisan food producers.
Direct Sales leads by margin contribution. Online Stores are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand and Vietnam dominate raw material supply, while European and North American processors control premium modification technologies. This geographic split between paddy cultivation and value-added processing shapes procurement strategies across the analysis window.
Thailand
Thai Flour Industry and Bangkok Starch anchor Southeast Asian supply chains through integrated paddy-to-powder operations. The country's Board of Investment promotes food ingredient exports through tax incentives and processing zone development. Pathum Thani and Ayutthaya provinces concentrate wet-milling infrastructure serving instant noodle and snack manufacturers across Asia.
Vietnam
Mekong Delta cultivation zones supply high-amylose cultivars preferred by European modified starch processors. Ministry of Agriculture and Rural Development irrigation projects aim to stabilize monsoon-dependent yields. Can Tho and An Giang provinces host expanding extraction capacity targeting clean-label export certification.
Germany
Roquette operates modified starch R&D and production serving EU sauce and convenience meal manufacturers. REACH registration requirements through ECHA govern chemical safety documentation for cross-linked derivatives. Frankfurt-Rhine-Main logistics clusters facilitate distribution to processed food producers in France and Benelux markets.
United States
Ingredion leverages formulation partnerships with multinational food manufacturers for modified starch applications. FDA GRAS self-affirmation pathways shape market access timelines for novel rice starch modifications. Chicago and Midwest agricultural processing corridors concentrate technical service capabilities for North American customers.
Belgium
BENEO develops prebiotic rice starch derivatives targeting digestive health positioning in functional foods. EU Green Deal sustainability benchmarks pressure documentation of carbon intensity across supply chains. Tienen facility operations exemplify European plant-based ingredient expertise consolidation.
Rice Starch Market Competitive Environment
Capital-heavy wet-milling operators compete with asset-light specialty ingredient designers across divergent margin pools. The supplier base organizes into three tiers: integrated Southeast Asian processors controlling raw material access, European and North American modification specialists commanding premium technical grades, and regional distributors aggregating commodity volumes. Strategic moves concentrate on backward integration into paddy sourcing and forward integration into formulation partnerships with multinational food manufacturers.
Within the integrated processing tier, Thai Flour Industry and Bangkok Starch exemplify Southeast Asian operators with captive supply chain control over Mekong Delta cultivation zones. Roquette occupies a position representing European modification expertise anchored in REACH-compliant chemical safety dossiers. BENEO sits within the functional positioning vector, developing prebiotic derivatives that separate technical-grade suppliers from commodity native starch traders.
| Leading Market Players |
|---|
| AGRANA |
| Thai Flour Industry |
| BENEO |
| Thai Wah |
| Roquette |
| Ingredion |
| Bangkok Starch |
| WFM Wholesome Foods |
| Ebro Foods |
| Others |
Value Chain & Pricing Dynamics
Multinational food manufacturers concentrate procurement decisions, forcing rice starch suppliers toward contract-based long-term offtake agreements with embedded technical service rather than spot commodity trading. This buyer concentration compresses margin pools for native starch traders while rewarding REACH-registered modification specialists with pricing power anchored in formulation partnerships.
Pricing Analysis
Margin tightening in native starch reflects paddy price volatility across Mekong Delta cultivation zones and irrigation-constrained harvests. Three-tier pricing structure across premium modified, standard native, and economy ungraded levels separates suppliers by certification tier and thermal stability performance. Cost-down pressure on commodity grades accelerates because Thai and Vietnamese mills compete for volume export contracts. Regional noodle manufacturers exhibit highest price sensitivity, while European sauce producers prioritize acid-resistant modified grades with complete ECHA dossiers.
Supply Chain Analysis
Reverse-logistics flows for rice starch remain minimal given food-grade contamination protocols, though pharmaceutical excipient returns feed into lower-grade paper coating applications. Supply concentrates in Thailand, Vietnam, and Germany, with raw material sourcing drawing from Mekong Delta paddy cultivation and European modification processing. The chain rests on high-amylose cultivar availability, wet-milling capacity, and REACH-compliant chemical inputs. Single-source vulnerability concentrates in Southeast Asian paddy supply, where monsoon dependency creates harvest volatility. Distribution runs through direct supplier relationships for modified grades and regional distributors for native starch volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rice starch markets sit in a formulation-science transition, with enzymatic modification technologies displacing conventional chemical cross-linking for precision texturization in plant-based meat alternatives.
For Market Incumbents:Cement formulation partnership exclusivity with multinational food manufacturers to lock out commodity traders from premium modified starch applications. Prioritize backward integration into Mekong Delta paddy sourcing to insulate margin pools from irrigation-constrained harvest volatility. Invest in pilot-scale extrusion infrastructure for thermal stability R&D before REACH registration timelines extend further.
For New Entrants and Emerging Players:Capture prebiotic rice starch derivative white space in functional food and nutraceutical channels where digestive health positioning commands margin premiums. Target instant beverage premix applications for cold-water solubility grades that remain underpenetrated by established suppliers. Enter through clean-label certification specialization, building paddy-to-powder traceability documentation that satisfies EU Green Deal benchmarks ahead of phased tariff implementations.
For Investors and Strategic Acquirers:The window for entry favors integrated Southeast Asian processors with captive paddy supply and European REACH registration expertise. Long-term viability hinges on carbon intensity documentation capabilities across supply chains as border adjustments phase in. Monitor ECHA substance evaluation protocol expansions for novel cross-linked derivatives as the signal for consolidation pressure on mid-tier suppliers lacking complete dossiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Paddy Sourcing | Captive Mekong Delta supply insulates margin pools from monsoon-dependent harvest volatility. |
| REACH Registration Completion | Full ECHA dossiers unlock European sauce manufacturer procurement consolidation around approved suppliers. |
| Prebiotic Derivative Development | Resistant starch positioning accesses functional food margin premiums in nutraceutical channels. |
| Carbon Intensity Documentation | EU Green Deal compliance creates competitive insulation against phased border adjustment tariffs. |
| Formulation Partnership Expansion | Technical service agreements with multinational food manufacturers displace spot procurement relationships. |
Study Parameters
Trade databases, ECHA registration filings, and food ingredient customs records formed the secondary backbone for supply chain mapping and competitive positioning analysis. Primary interviews with wet-milling plant managers, procurement leads at European sauce manufacturers, distribution channel partners, and technical R&D directors at modification specialists validated extraction cost structures and formulation partnership terms. Bottom-up and top-down triangulation cross-checked paddy-to-powder volume flows against end-use demand segmentation.
Bottom-up modeling aggregated country-level production capacity, cultivation yields, and processing utilization rates across Thailand and Vietnam, while top-down analysis calibrated aggregate market expansion against clean-label substitution trends in synthetic thickener displacement. Segmentation dimensions included product type tiers, application intensity across food and pharmaceutical channels, end-user scale categories, and distribution channel structures. CAGRs derived from regression against historical paddy price cycles and REACH registration timeline impacts. Forecast inputs incorporated monsoon pattern variability and EU Green Deal implementation pacing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to irrigation infrastructure investment delays and ECHA protocol expansions for novel modifications. Forecasts reflect documented assumptions around paddy yield stability and certification scheme harmonization progress. Practitioners should monitor Mekong Delta water management project milestones and EMA excipient master file requirement updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Australia Sodium Reduction Ingredients Market
Ingredients
Dairy Ingredients Market
Ingredients
Sunflower Meal Market
Ingredients
Salt Content Reduction Ingredients Market
Ingredients
Protein Extracts from Single Cell Protein and Other Conventional Sources Market
Ingredients
Egg White Powder Market
Ingredients
Industrial and Bar-B-Que Charcoal Market
Ingredients
India Gelatin Market
Ingredients
Global Infant Nutrition Ingredients Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
Philippines Edible Oils & Fats Market
Ingredients
Microencapsulated Oil Market
Ingredients
Germany Gelatin Market
Ingredients
Vitamin B Complex Ingredients Market
Ingredients
Potato Starch Market
Ingredients
Citrus Fiber Market