
 Bouillon Cubes Market | 2026-2036
Bouillon Cubes Market Size, Share, and Industry Trends Forecast 2026-2036
Bouillon Cubes Market Analytics
The EU Green Deal is realigning formulation priorities across European bouillon producers, pushing sodium reduction and cleaner-label ingredient decks. Unilever leverages its Knorr brand's global manufacturing footprint to sustain cost advantages in emerging markets. Nestle S.A. anchors its Maggi portfolio through deep distribution networks in Africa and South Asia. Ajinomoto Co. differentiates via umami science expertise and specialized yeast-extract technologies.
Bouillon cubes are compressed seasonings composed of dehydrated stock, vegetables, seasonings, salt, and hydrogenated fat, formed under high pressure into dissolvable cubes for rapid flavor delivery in cooking. The organic and low-sodium product types command premium shelf positioning as health-conscious buyers trade up from traditional variants. Chicken and beef flavor profiles dominate household purchases, while vegetable and seafood variants capture growth in vegetarian-forward restaurants and institutional catering. Supermarkets and online retail channels together account for the bulk of volume flow, though specialty stores retain margin-rich positioning for gluten-free and certified-organic lines.
FDA sodium-labeling rules and EFSA clean-label guidance together tighten compositional standards for manufacturers selling into North America and Europe. India's FSSAI fortification mandates and China's SAMR food-safety audits add compliance layers for entrants targeting those volume markets. Stakeholders must monitor evolving sodium thresholds and front-of-pack labeling requirements across multiple jurisdictions to preserve market access and brand positioning.
Market Dynamics
The EU Green Deal's clean-label mandates are compressing formulation timelines across the bouillon sector, forcing simultaneous sodium reduction and ingredient transparency upgrades before enforcement deadlines.
Growth Catalysts
- Urban Convenience Demand:Indian metropolitan households are adopting bouillon cubes as core pantry staples, replacing time-intensive traditional stock preparation in dual-income families.
- EFSA Clean-Label Guidance:European manufacturers are reformulating to eliminate artificial additives and hydrogenated fats, creating premium positioning for compliant product lines.
- Yeast-Extract Umami Technology:Specialized fermentation processes are enabling deeper flavor profiles at reduced sodium levels, satisfying health-conscious institutional buyers.
Market Restraints
- Palm Oil Input Volatility:Hydrogenated fat costs fluctuate with Malaysian and Indonesian export policies, squeezing margin stability for mass-market producers.
- Sodium Threshold Compression:FDA labeling rules and WHO intake guidelines are narrowing the acceptable formulation window for traditional high-salt variants.
- Fresh Broth Substitution:Refrigerated and frozen stock alternatives in developed markets capture health-premium segments resistant to dehydrated formats.
Strategic Opportunities
- FSSAI Fortification Mandates:India's micronutrient enrichment requirements for staple foods create entry pathways for iodine and iron-fortified bouillon variants.
- Direct-to-Consumer Channels:Subscription-based online platforms are bypassing traditional retail markups for organic and specialty product lines.
- Plant-Based Protein Convergence:Pea and mushroom extract technologies are enabling clean-label vegetable bouillon with meat-comparable savory depth.
Industry Challenges
- Flavor Chemist Talent Scarcity:The intersection of food science and clean-label formulation requires specialized expertise that outpaces current training pipeline output.
- Dual Certification Timelines:Simultaneous organic and halal certification processes extend product launch cycles by eight to fourteen months in key markets.
- Legacy Equipment Retrofit Costs:Sodium-reduction production lines require pressure and temperature modifications incompatible with existing cube compression infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bouillon Cubes Market |
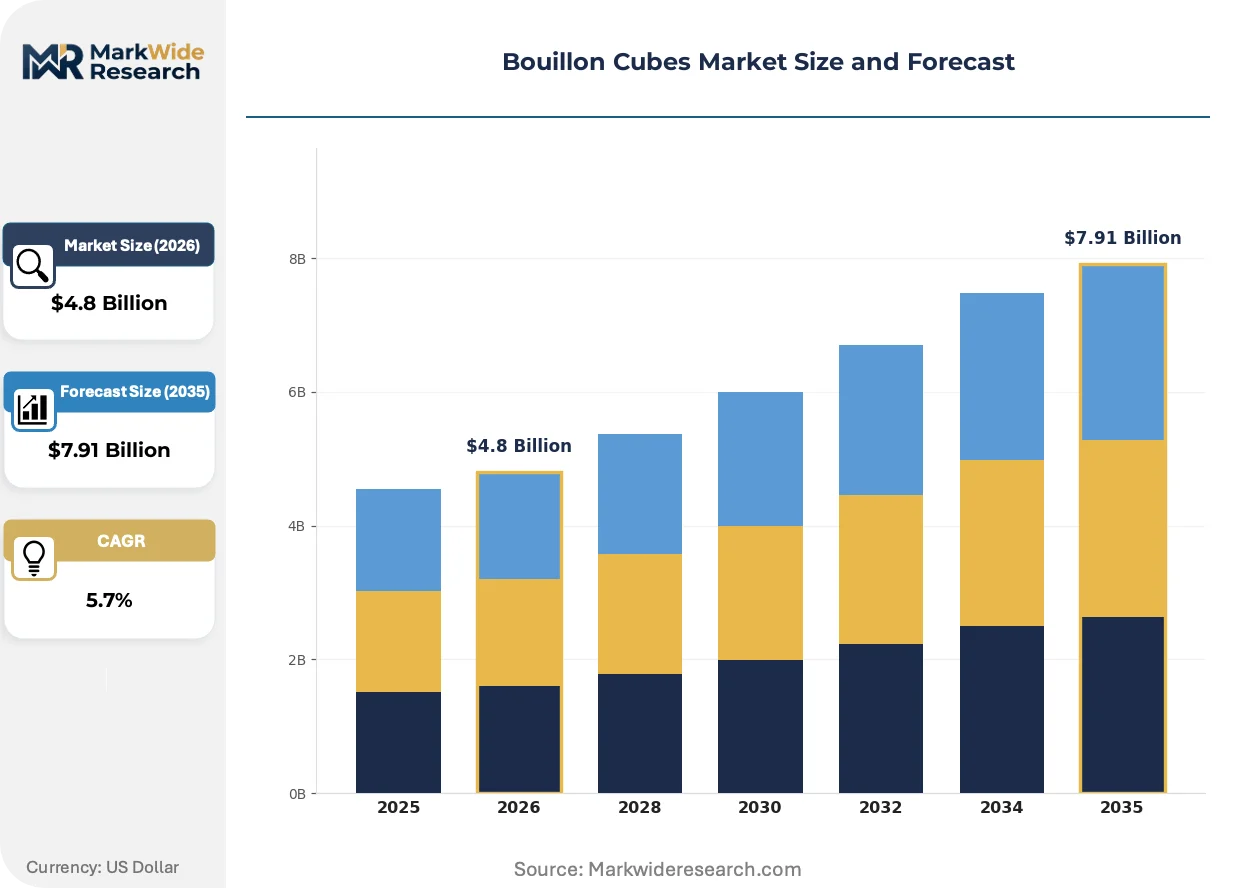
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Low-Sodium, Traditional, Gluten-Free Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores End User: Households, Restaurants, Catering Services, Food Manufacturers Flavor Profile: Chicken, Beef, Vegetable, Seafood |
| Companies Covered | Unilever (Knorr), Nestle S.A. (Maggi), Hormel Foods Corporation, Kraft Heinz Company, Ajinomoto Co., Campbell Soup Company, Bou Brands LLC, Goya Foods, McCormick & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bouillon Cubes Market Evolving Landscape
Clean-label pressure is fragmenting the competitive landscape into sodium-reduction specialists, organic certifiers, and traditional cost leaders, with technology choices determining which tier manufacturers can occupy.
Spray-dried vegetable powder technology is absorbing moisture-control functions previously handled by chemical preservatives, enabling shorter ingredient decks. European and North American premium brands are adopting this at scale, while Asian manufacturers trial hybrid formats. The shift is compressing shelf-life extension costs and forcing reformulation of legacy hydrogenated-fat binders.
REACH chemical safety registrations are tightening scrutiny of flavoring substances and processing aids in European bouillon production. Manufacturers must document full supply chain substance flows or face market withdrawal. Small and mid-sized producers in Eastern Europe are consolidating to share compliance costs, while multinationals accelerate in-house extraction capabilities.
Institutional procurement teams are unbundling flavor-base contracts from broadline foodservice agreements, creating direct supplier relationships previously intermediated by distributors. Hotel and restaurant chains in the Middle East and Southeast Asia are leading this separation, negotiating volume commitments for customized sodium specifications. The pattern is visible most acutely in UAE and Saudi Arabia, where hospitality groups centralize kitchen standardization across property portfolios.
Bouillon Cubes Market Segmentation
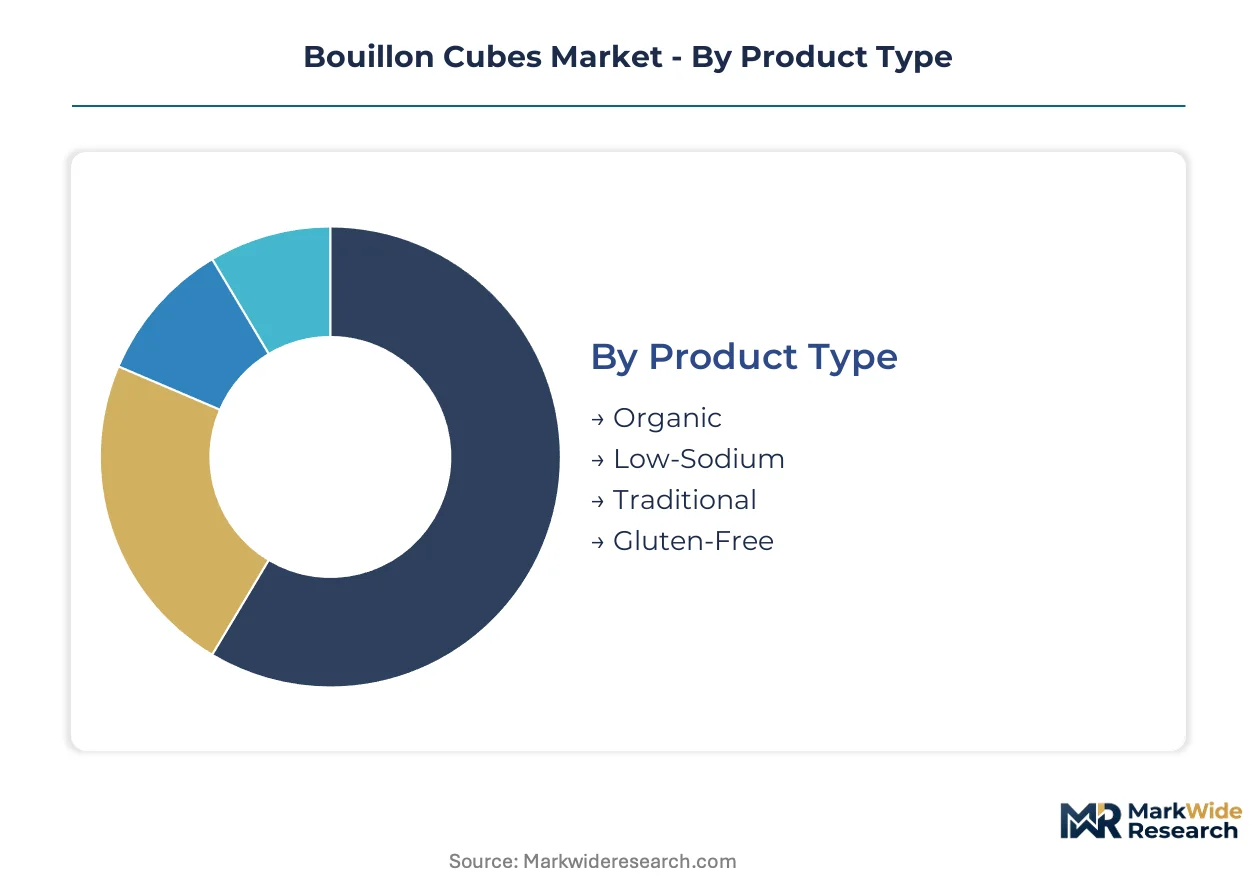
Bouillon cube manufacturers calibrate formulation, packaging, and channel strategy against divergent buyer priorities across health-conscious households, cost-driven foodservice operators, and industrial-scale food processors. Segment-level targeting determines margin capture, with organic and low-sodium variants commanding shelf-position premiums while traditional formats defend volume in emerging markets.
Product Type:
Purchase decisions here pivot on health-positioning trade-offs between clean-label credentials and unit economics, with dual-income urban households driving premium tier expansion.
- Organic:Certified-ingredient decks exclude synthetic pesticides and GMO inputs, requiring segregated supply chains and third-party audit documentation. Demand clusters in German and French metropolitan retail, where EU Green Deal labeling transparency mandates accelerate shelf-space reallocation toward certified lines.
- Low-Sodium:Yeast-extract and potassium-chloride formulations reduce sodium density while preserving umami impact through fermentation-derived nucleotides. Institutional buyers in UAE hospitality chains specify these variants for kitchen standardization across property portfolios, balancing regulatory anticipation with flavor consistency.
- Traditional:Hydrogenated-fat binders and salt-dominant profiles maintain cost leadership for price-sensitive emerging-market penetration.
- Gluten-Free:Modified starch and rice-flour bases replace wheat-derived fillers, capturing celiac-sensitive and free-from positioning in North American specialty retail.
Volume sits with Traditional; growth tilts toward Low-Sodium.
Distribution Channel:
Channel selection determines margin structure and buyer-relationship depth, with direct-to-consumer platforms eroding traditional retail markups in premium segments.
- Supermarkets:Mass-market volume flows through hypermarket and supermarket chains, where slotting fees and promotional calendars dictate brand visibility. Indian urban retail expansion concentrates household purchases in modern trade formats replacing kirana-store sourcing.
- Online Retail:Subscription platforms and marketplace storefronts bypass distributor layers, enabling specialty and organic lines to reach dispersed health-conscious buyers. Direct fulfillment from regional warehouses compresses working capital requirements for mid-tier brands.
- Specialty Stores:Health-food and ethnic grocers command margin-rich positioning for certified-organic, halal, and kosher variants with localized community penetration.
- Convenience Stores:Single-serve and impulse formats target urban commuter traffic with immediate-consumption packaging and localized flavor profiles.
Supermarkets anchor current volume; Online Retail climbs the fastest.
End User:
End-use segmentation separates flavor-base procurement into household pantry replenishment, commercial kitchen standardization, and industrial ingredient integration.
- Households:Dual-income families in Indian and Brazilian metropolitan areas adopt bouillon cubes as time-saving substitutes for traditional stock preparation, with chicken and beef profiles dominating repeat purchases.
- Restaurants:Independent and chain operators across Southeast Asia and the Middle East specify customized sodium levels and cube sizes for menu consistency, unbundling flavor-base contracts from broadline distributors.
- Catering Services:Volume foodservice operations prioritize cost-per-serving efficiency and extended holding stability in buffet and banquet applications.
- Food Manufacturers:Processed soup, sauce, and ready-meal producers integrate bouillon-derived flavor bases as standardized inputs, demanding batch-to-batch consistency and documentation for clean-label claims.
Households retain the largest share; Restaurants gain share fastest.
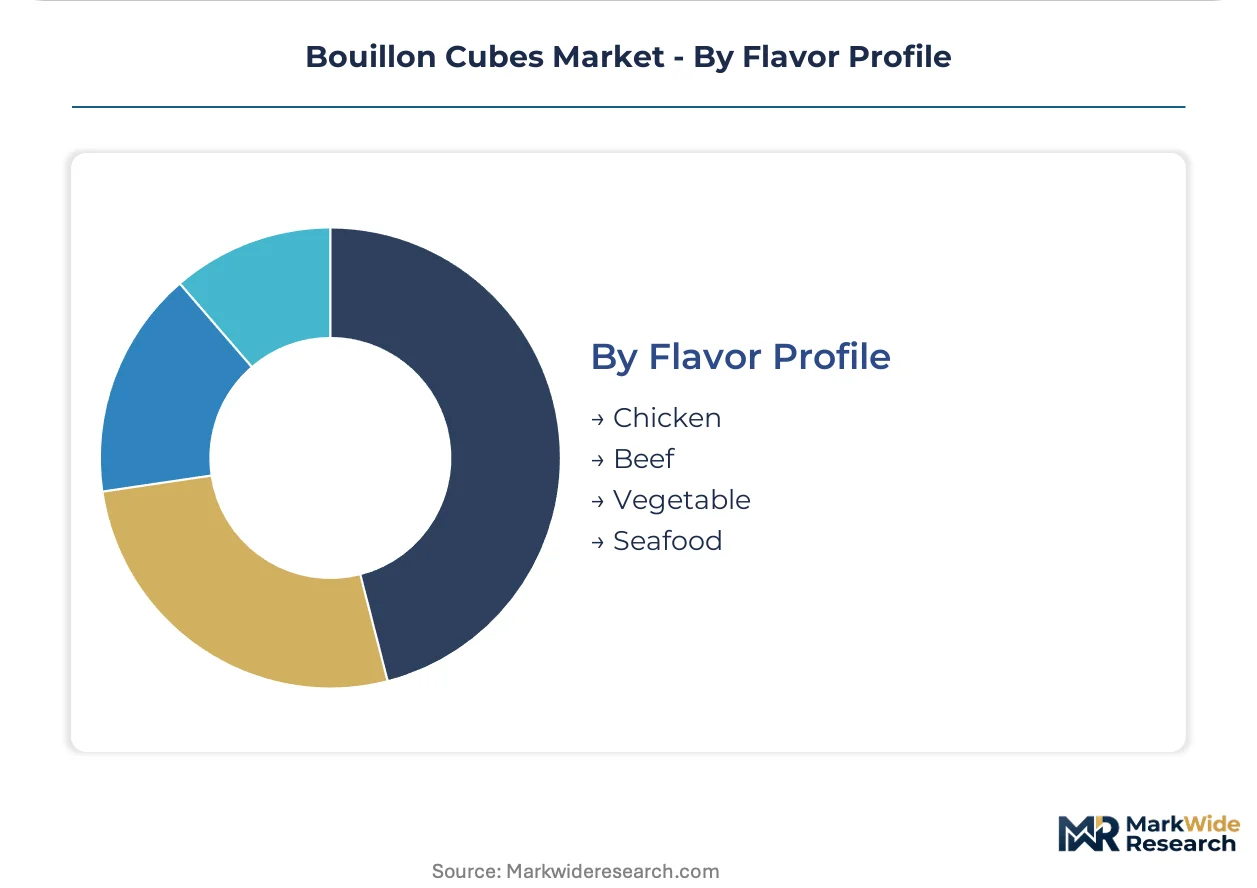
Flavor Profile:
Flavor selection reflects protein-consumption patterns, vegetarian dietary shifts, and regional culinary tradition.
- Chicken:Poultry-derived bases dominate global household penetration, with yeast-extract and hydrolyzed-protein technologies enabling cost-competitive formulation across price tiers.
- Beef:Red-meat profiles anchor Latin American and Middle Eastern foodservice demand, where traditional cooking methods emphasize rich, dark stock foundations.
- Vegetable:Mushroom, tomato, and herb-derived formulations capture vegetarian-forward restaurant menus and institutional catering in European urban centers, with pea and extract technologies deepening savory complexity.
- Seafood:Fish and shellfish bases serve coastal Asian cuisines and specialized food manufacturing, with narrower geographic concentration than land-protein variants.
Chicken and Beef concentrate volume; Vegetable shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and China concentrate bouillon cube consumption through urban household expansion, while European production facilities pivot toward clean-label export formats. Manufacturing clusters in Southeast Asia supply cost-optimized variants for institutional buyers across the Middle East and Africa.
India
Metropolitan households in Mumbai and Delhi-NCR are replacing traditional stock preparation with bouillon cubes as dual-income families prioritize cooking convenience. FSSAI fortification mandates for staple foods create regulatory pathways for iodine-enriched variants. Gujarat and Maharashtra host the primary manufacturing corridors supplying domestic modern retail chains.
China
Urban consumers in Shanghai and Beijing are shifting toward reduced-sodium flavor bases amid SAMR food-safety audit intensification. The country's dual carbon goals are pressuring hydrogenated-fat suppliers toward cleaner processing methods. Guangdong Province concentrates flavor-extraction technology development for yeast-derived umami applications.
Germany
EU Green Deal labeling transparency mandates are accelerating shelf-space reallocation toward certified organic lines in Berlin and Hamburg retail networks. REACH chemical safety registrations tighten scrutiny of flavoring substances across Rhineland manufacturing sites. Bavaria-based producers are consolidating to share compliance infrastructure costs.
United States
FDA sodium-labeling rules are narrowing formulation windows for traditional high-salt variants in California and New York Metro markets. The Pacific Northwest hosts specialty retail concentration for gluten-free and certified-organic bouillon lines. Midwest food manufacturers integrate bouillon-derived flavor bases into processed soup and ready-meal production.
Brazil
São Paulo and Rio de Janeiro metropolitan areas anchor Latin American demand for beef and chicken flavor profiles aligned with traditional cooking methods. ANVISA food-safety protocols govern imported additive specifications for multinational brands. Minas Gerais agricultural processing clusters supply dehydrated vegetable inputs for regional formulation.
Bouillon Cubes Market Competitive Landscape
The competitive structure tilts toward multinational conglomerates with deep distribution infrastructure and brand heritage spanning multiple continents. Tiered positioning separates sodium-reduction specialists, organic certifiers, and traditional cost leaders based on technology choices and regulatory compliance depth. Dominant competitive moves include geographic expansion through localized flavor portfolio diversification and strategic partnerships with institutional procurement teams unbundling flavor-base contracts from broadline distributors.
Among diversified consumer goods conglomerates, Unilever plc and Nestle S.A. occupy positions representing global manufacturing footprint advantages and deep emerging-market penetration. Ajinomoto Co. sits within a specialized tier exemplifying umami science expertise and fermentation technology differentiation. These three anchors demonstrate how scale, distribution density, and technical specialization define competitive positioning across price tiers and regulatory environments.
| Leading Market Players |
|---|
| Unilever (Knorr) |
| Nestle S.A. (Maggi) |
| Hormel Foods Corporation |
| Kraft Heinz Company |
| Ajinomoto Co. |
| Campbell Soup Company |
| Bou Brands LLC |
| Goya Foods |
| McCormick & Company |
| Others |
Value Network & Pricing Analysis
Sodium-reduction retrofitting across European production lines is compressing unit economics while concentrating supply leverage among multinationals with captive yeast-extract capabilities. This technological transition simultaneously elevates fixed-cost barriers for mid-tier producers and reshapes procurement power toward integrated flavor-science specialists.
Pricing Analysis
Margin tightening in traditional high-sodium tiers reflects palm oil input volatility and compressed formulation windows under FDA labeling rules. Three-tier pricing structure across premium, standard, and economy levels separates certified-organic lines from clean-label mid-tier variants and hydrogenated-fat-based economy formats. Price differentiation hinges on certification grade and volume scale, with institutional buyers in UAE hospitality chains negotiating customized sodium specifications at scale. Cost-down pressure on economy tiers accelerates because Malaysian export policy fluctuations destabilize hydrogenated fat costs. Food manufacturers demonstrate highest price sensitivity due to batch-to-batch consistency requirements, while specialty retail buyers absorb premiums for gluten-free positioning.
Supply Chain Analysis
Yeast-extract supply rests on fermentation technology clusters in Japan and specialized European producers, with vegetable powder inputs drawing from Indian and Chinese dehydration facilities. Palm oil dependency anchors formulation costs to Indonesian and Malaysian export flows, while potassium chloride for sodium reduction sources from Canadian and Belarusian mining operations. Single-source vulnerability concentrates in proprietary umami nucleotide extraction, where Ajinomoto and select European specialists control specialized fermentation IP. Distribution runs through broadline foodservice distributors in emerging markets, bypassed by direct procurement relationships in Middle Eastern hospitality consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as manufacturers pursue captive yeast-extract production to secure sodium-reduction formulation autonomy and escape input cost volatility.
For Market Incumbents: Deepen backward integration into yeast-extract fermentation to secure sodium-reduction input stability against palm oil volatility. Expand clean-label certification infrastructure across Rhineland and Bavaria production clusters to preempt REACH documentation requirements. Anchor distribution control through direct institutional procurement relationships in UAE and Saudi Arabia hospitality consolidation. For New Entrants and Emerging Players: FSSAI fortification mandates in India open a window for iodine-enriched bouillon variants targeting metropolitan household pantry adoption. White-space concentration sits with subscription-based organic lines bypassing traditional retail markups. Entry angle should leverage direct-to-consumer fulfillment from regional warehouses serving dispersed health-conscious buyers in North American specialty segments. For Investors and Strategic Acquirers: Re-rating potential sits with sodium-reduction specialists given EU Green Deal enforcement acceleration and FDA labeling rule tightening. Acquisition targets should demonstrate captive umami-science capabilities or established clean-label certification infrastructure. Signal to watch is institutional procurement unbundling velocity in Middle East hospitality consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yeast-Extract Production | Captive fermentation capacity insulates margin stability against specialized input supply constraints. |
| Clean-Label Certification Investment | REACH documentation and organic audit infrastructure preserves European market access under EU Green Deal mandates. |
| Direct-to-Consumer Channel Launch | Subscription platforms bypass distributor markups for premium organic and gluten-free product lines. |
| Institutional Procurement Partnership | Direct relationships with UAE hospitality chains capture volume commitments for customized sodium specifications. |
| FSSAI Fortification Compliance | Micronutrient enrichment pathways unlock Indian metropolitan household penetration in modern retail formats. |
Research Methodology
Document review covered FSSAI fortification guidelines, FDA sodium-labeling rules, EU Green Deal implementation documents, and EFSA clean-label guidance, complemented by interviews with flavor-science R&D directors, foodservice procurement managers at Middle Eastern hospitality groups, category buyers at Indian modern retail chains, and supply planners at European manufacturing facilities. Secondary validation drew from customs records tracking palm oil and yeast-extract trade flows, SEC filings of diversified consumer goods conglomerates, and REACH chemical safety registration databases. Bottom-up volume modeling across product type, distribution channel, end user, and flavor profile segments was cross-referenced against top-down macroeconomic indicators.
Historical consumption patterns were cross-referenced against panel input from institutional procurement teams and retail category managers across the analysis window. Segmentation dimensions modeled include health-positioning tier, channel structure, end-use application, and regional regulatory cluster. CAGRs were derived through trend extrapolation adjusted for enforcement timelines of sodium-threshold regulations and urbanization trajectories in emerging markets. Forecast inputs incorporated yeast-extract technology adoption curves and palm oil price volatility assumptions.
Caveats apply where enforcement delays in FDA labeling rules or EU Green Deal implementation could materially shift the outlook for clean-label reformulation investment. Forecasts reflect assumptions regarding urban household adoption rates in India and institutional procurement unbundling velocity in the Middle East. A small set of named triggers—palm oil export policy shifts, sodium-threshold regulatory revisions, and yeast-extract supply disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Peanut Ingredients Market
Ingredients
Bean Pasta Market
Ingredients
Europe Malt Extract Market
Ingredients
APAC Savoury Ingredients Market
Ingredients
Hen Egg White Protein Market
Ingredients
Baking Ingredients Market
Ingredients
Botanical Ingredients Market
Ingredients
Siraitia Grosvenorii Extract Market
Ingredients
Africa Sodium Reduction Ingredients Market
Ingredients
Cholesterol API Market
Ingredients
Oat Fiber Market
Ingredients
Mallow Glycolic Extract Market
Ingredients
Vegetable Glycerin Market
Ingredients
Potato & Yam Derivatives Market
Ingredients
Date Syrup Market
Ingredients
Sesame Seed Extract Market