
 Africa Nutraceutical Market | 2026-2036
Africa Nutraceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Nutraceutical Market Outlook
The African Union's Malabo Declaration on nutrition security is realigning government procurement priorities for fortified foods across member states. Danone S.A. leverages its dairy-based probiotic infrastructure to anchor distribution in North African markets. Nestlé SA competes through micronutrient fortification programs targeting maternal health segments. Herbalife Nutrition differentiates via direct-selling networks that penetrate secondary cities beyond traditional retail footprints.
Nutraceuticals comprise bioactive compounds, vitamins, minerals, herbal extracts, and probiotic cultures formulated for physiological benefit beyond basic nutrition, typically standardized to defined potency thresholds and manufactured through controlled fermentation, extraction, or synthesis processes. These products serve preventive health, performance optimization, and clinical nutrition applications across consumer and institutional channels. Probiotics and herbal supplements capture expanding margin pools as African consumers shift from reactive treatment to preventive wellness protocols. The pills and powders form categories dominate manufacturing scale, while gummies gain traction among pediatric and younger adult demographics through pharmacy and supermarket channels. Healthcare institutions represent the most concentrated end-user segment for clinical-grade formulations, though general consumers drive volume through online retail expansion.
South Africa's Department of Health enforces Complementary Medicines Regulations under the Medicines and Related Substances Act, while Nigeria's National Agency for Food and Drug Administration and Control (NAFDAC) mandates product registration and label verification for imported supplements. Kenya's Pharmacy and Poisons Board adds layer of quality control for pharmacy-distributed items. These frameworks elevate compliance costs for new entrants but simultaneously build consumer trust in certified products. Stakeholders must monitor harmonization efforts across the African Continental Free Trade Area for mutual recognition of supplement standards and registration protocols.
Market Dynamics
The Malabo Declaration on nutrition security is restructuring government procurement across African Union member states, redirecting institutional demand toward fortified foods and clinical-grade formulations while tightening compliance requirements for suppliers.
Growth Catalysts
- Fortification mandates:The Malabo Declaration compels member states to prioritize micronutrient-enriched foods in public health programs, creating institutional demand channels for domestic manufacturers.
- E-commerce platform expansion:Online retail networks are penetrating secondary cities in Nigeria and Kenya, reducing distribution friction for probiotic and herbal supplement brands.
- Athlete and fitness segments:Functional food adoption is accelerating among sports communities across South Africa, Ghana, and Egypt, driving premium product development.
Market Restraints
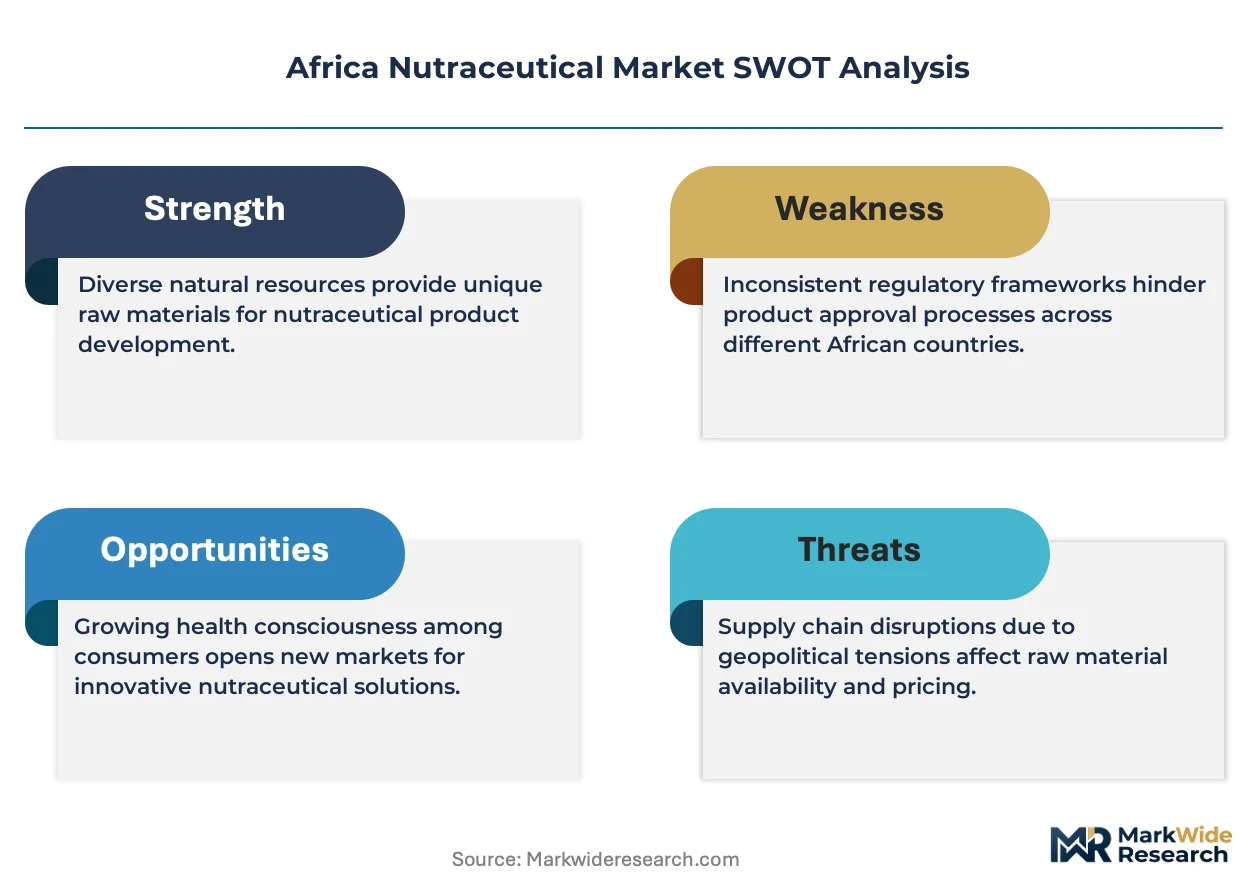
- Import dependency for active ingredients:Probiotic cultures and standardized herbal extracts concentrate in European and Asian supplier bases, exposing African formulators to currency volatility and shipping disruptions.
- Multi-layer registration costs:South Africa's Complementary Medicines Regulations, Nigeria's NAFDAC protocols, and Kenya's Pharmacy and Poisons Board requirements create cumulative compliance burdens that deter new entrants.
- Substitution by traditional medicine:Informal herbal preparations and unregulated traditional practitioners capture price-sensitive consumers in rural zones, limiting addressable market expansion.
Strategic Opportunities
- Underpenetrated East African corridor:Ethiopia and Tanzania present white-space demand for pharmacy-distributed vitamins, with urbanization rates outstripping formal retail coverage.
- Direct-selling network expansion:Secondary cities beyond Lagos, Nairobi, and Johannesburg remain underserved by traditional retail, creating channel innovation potential for personalized nutrition consultative models.
- Harmonized AfCFTA standards:Mutual recognition protocols under the African Continental Free Trade Area promise to collapse redundant registration requirements across member states.
Industry Challenges
- Phytochemical standardization expertise:Local laboratories lack capacity for potency verification and contaminant screening of herbal raw materials, forcing reliance on costly third-party testing.
- Cold chain infrastructure gaps:Probiotic viability requires temperature-controlled logistics that remain inconsistent across the Lagos-Abuja and Nairobi-Mombasa distribution corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Nutraceutical Market |
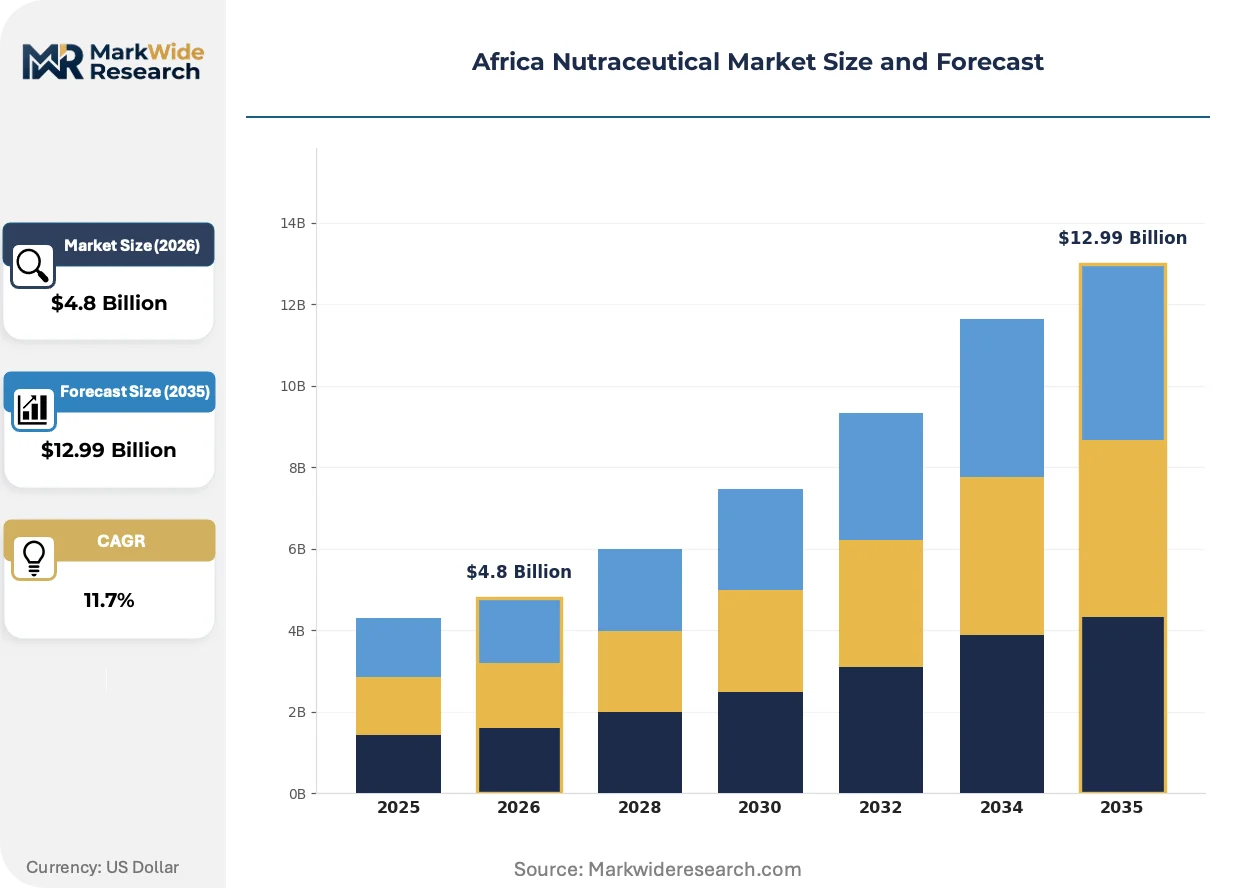
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Supplements, Vitamins, Minerals, Probiotics End User: Healthcare Institutions, Athletes, General Consumers, Nutritional Centers Distribution Channel: Online Retail, Pharmacies, Health Food Stores, Supermarkets Form: Pills, Powders, Liquids, Gummies |
| Companies Covered | Danone S.A., The Kellogg Company, Nestlé SA, GlaxoSmithKline PLC, Herbalife Nutrition, Arla Foods, Red Bull Corporation, The Coca-Cola Company, Amway Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Nutraceutical Market Strategic Shifts
Digital health integration and localized production technologies are compressing the distance between formulation science and consumer access across African markets. These shifts are reconfiguring competitive advantage toward supply chain responsiveness and regulatory agility.
Mobile-enabled diagnostic platforms are decentralizing personalized nutrition recommendations. Fitness applications and telehealth services in South Africa and Nigeria now integrate biomarker data to suggest specific supplement protocols. Younger demographics adopt these tools fastest, bypassing traditional pharmacy consultations and compressing the path from symptom recognition to product purchase.
South Africa's updated health claims framework under the Medicines and Related Substances Act is tightening evidentiary standards for probiotic and herbal marketing. Manufacturers must now submit clinical trial data or systematic reviews to support physiological benefit statements. Premium brands with existing research portfolios gain positioning advantage, while smaller competitors face reformulation or label restriction.
Pharmacy chains in Nigeria's urban centers and Kenya's Nairobi-Mombasa corridor are unbundling after-sales consultation from product sales. Consumers increasingly self-diagnose via online health content, then purchase vitamins and minerals through supermarket and e-commerce channels. This behavior shift pressures traditional pharmacy margins while expanding volume through mass-market retail formats.
Africa Nutraceutical Market Segmentation
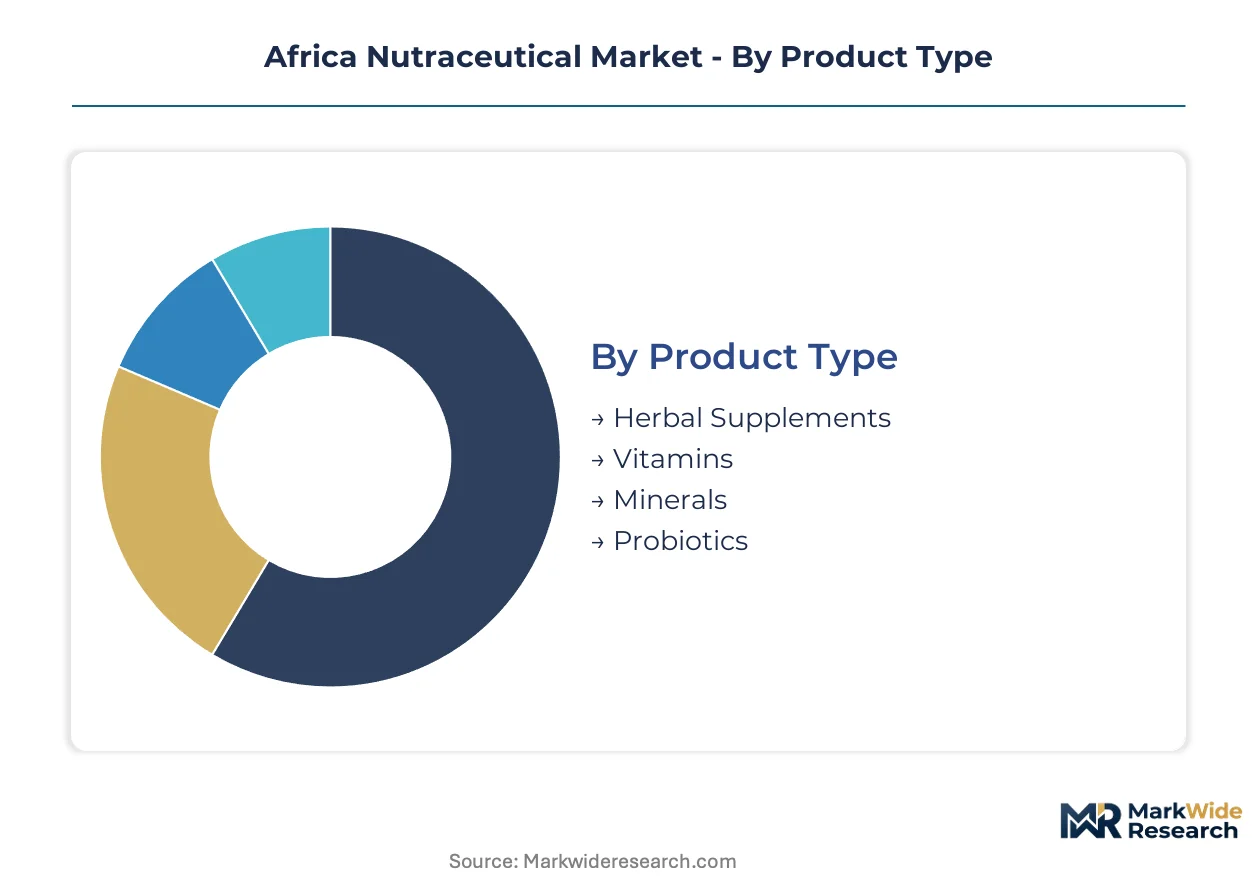
Segmentation in African nutraceuticals reveals divergent margin structures and channel requirements. Product form and distribution pathway determine cold chain investment, while end-user concentration shapes regulatory compliance intensity across the continent.
Product Type:
Volume concentrates in mass-market formulations, while premium margin pools accrue to clinically validated segments with potency standardization.
- Probiotics:Live microbial cultures requiring controlled fermentation and cold chain integrity. Demand clusters among urban professionals in South Africa's Gauteng province and Nigeria's Lagos corridor, where pharmacy chains now stock refrigerated displays. Viability loss during transport remains the critical constraint.
- Herbal Supplements:Standardized phytochemical extracts from indigenous and imported botanical sources. Kenya's Nairobi-Mombasa corridor shows fastest adoption as consumers bridge traditional medicine familiarity with formal product assurance. Phytochemical verification capacity gaps force reliance on European testing laboratories.
- Vitamins:Synthetic and nature-identical micronutrient formulations dominating manufacturing scale. Nigeria's NAFDAC registration requirements elevate compliance costs for importers.
- Minerals:Chelated and inorganic elemental supplements, frequently co-formulated with vitamins. South Africa's Complementary Medicines Regulations mandate heavy metal screening for all mineral products.
Today's leader: Probiotics. Tomorrow's challenger: Herbal Supplements.
End User:
Institutional procurement channels demand clinical-grade documentation, while direct-to-consumer segments prioritize convenience and taste masking.
- General Consumers:Self-directed purchasers driving volume through supermarket and e-commerce channels. South Africa's updated health claims framework is tightening evidentiary standards for marketing to this segment.
- Healthcare Institutions:Hospitals and clinics requiring batch consistency documentation and therapeutic dosing protocols. The Malabo Declaration is restructuring government procurement priorities toward fortified clinical nutrition across African Union member states.
- Athletes:Performance-optimization seekers adopting functional foods and targeted supplementation. Ghana and Egypt show emerging demand concentration alongside established South African sports nutrition markets.
- Nutritional Centers:Specialized clinics and wellness facilities offering personalized protocol design. Ethiopia and Tanzania present white-space expansion potential as urbanization outstrips formal retail coverage.
Institutional channels anchor revenue stability. General consumers are gaining share fastest.
Distribution Channel:
Physical retail retains trust advantage for first-time purchasers, while digital platforms capture repeat-buyer convenience and subscription retention.
- Pharmacies:Professional consultation settings with regulatory oversight from Kenya's Pharmacy and Poisons Board and South Africa's Department of Health. Urban centers in Nigeria and Kenya are expanding pharmacy chain footprints.
- Online Retail:Platform-based sales penetrating secondary cities beyond traditional retail reach. Nigeria's e-commerce networks are reducing distribution friction for probiotic and herbal brands.
- Supermarkets:Mass-market volume channels where consumers self-select vitamins and minerals after online health content research.
- Health Food Stores:Specialty retailers catering to fitness-conscious and preventive wellness demographics. South Africa's major metropolitan areas maintain the densest store networks.
Pharmacies hold certification credibility. Online retail climbs the fastest.
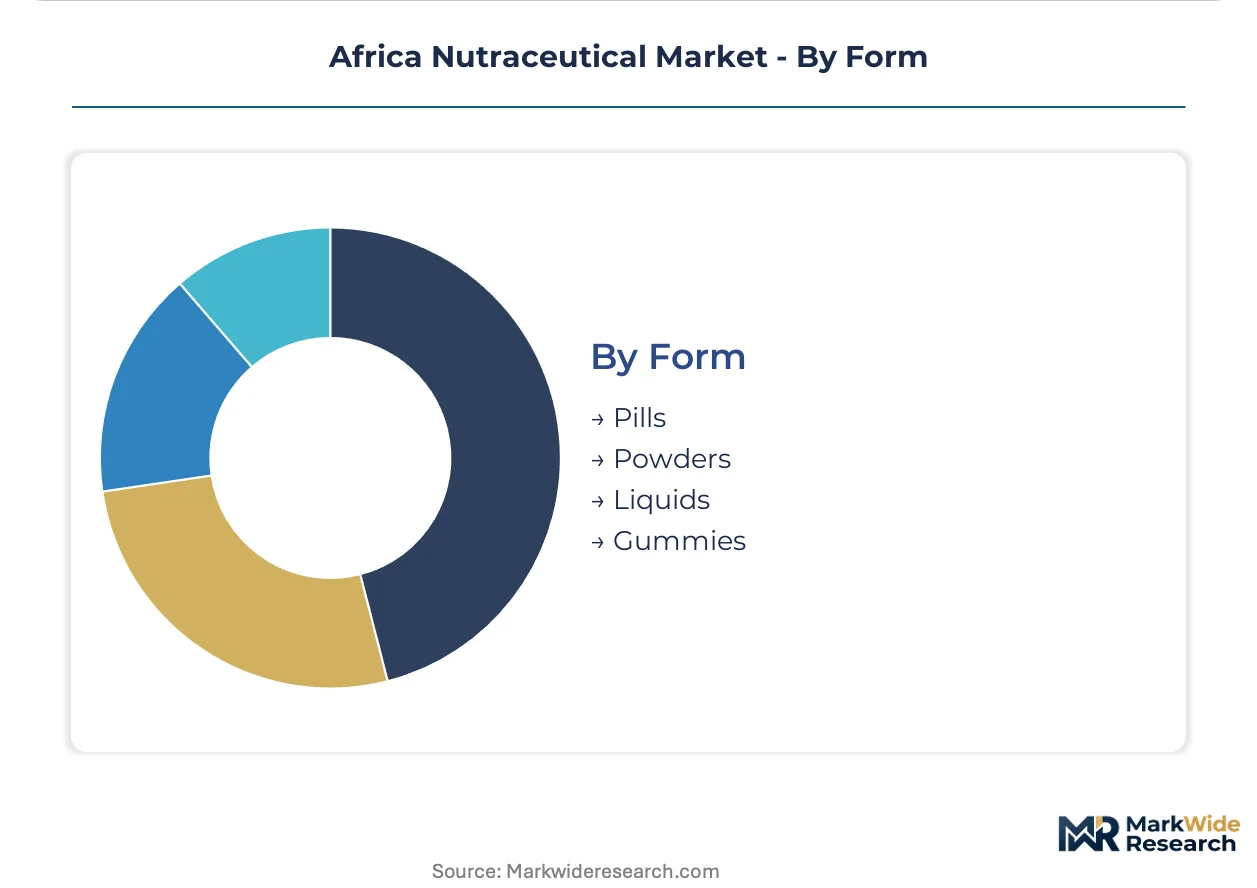
Form:
Manufacturing scale favors compressed and loose-dose formats, while palatability-driven forms command pediatric and younger adult premiums.
- Pills:Compressed tablets and capsules dominating production economics and shelf stability. Healthcare institutions specify this format for compliance and dosing accuracy.
- Powders:Bulk active ingredients and finished formulations offering dose flexibility. Athletes and nutritional centers prefer this format for customizable protocols.
- Gummies:Gelatin and pectin-based delivery systems gaining traction among pediatric demographics and younger adults. Pharmacy and supermarket channels in South Africa and Nigeria are expanding gummy assortments.
- Liquids:Suspensions and solutions for populations with swallowing difficulties or rapid absorption requirements. Cold chain requirements limit distribution reach.
Pills and powders anchor manufacturing scale. Gummies represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scientific talent clusters in South Africa's pharmaceutical corridor anchor the continent's nutraceutical formulation capabilities, while distribution networks concentrate in Nigeria's commercial hubs and Kenya's logistics corridors.
South Africa
Pharmacy chain expansion in Gauteng province and Cape Town drives probiotic refrigerated display penetration. The Department of Health enforces Complementary Medicines Regulations under the Medicines and Related Substances Act. Cape Town's biotechnology cluster hosts potency verification laboratories serving regional herbal extract standardization.
Nigeria
Urban professional demand concentrates in Lagos and Abuja for vitamin and mineral formulations. The National Agency for Food and Drug Administration and Control mandates product registration and label verification for imported supplements. The Lagos-Ibadan corridor anchors e-commerce distribution networks reducing last-mile friction for direct-to-consumer brands.
Kenya
The Nairobi-Mombasa corridor shows fastest herbal supplement adoption bridging traditional medicine familiarity with formal product assurance. The Pharmacy and Poisons Board adds quality control layers for pharmacy-distributed items. Nairobi's emerging pharmaceutical manufacturing zone attracts regional distribution headquarters for East African market access.
Egypt
Sports nutrition demand accelerates among Cairo and Alexandria fitness communities seeking performance optimization formulations. The country's national pharmaceutical regulator maintains import licensing requirements for bioactive compounds. The Suez Canal logistics zone facilitates cold chain transit for European-sourced probiotic cultures.
Ghana
Athlete segment expansion in Accra drives functional food trial among competitive sports communities. The country's food and drug authority enforces registration protocols for fortified food imports. The Tema industrial zone concentrates secondary packaging and labeling operations for regional re-export.
Africa Nutraceutical Market Competitive Environment
Capital-heavy producers compete with asset-light designers across Africa's nutraceutical value chain. Dairy-based multinationals with captive fermentation infrastructure hold manufacturing scale advantages. Direct-selling networks and pharmacy-centric distributors represent distinct strategic archetypes. Competitive moves concentrate on cold chain partnerships and regulatory compliance certification stacking.
Among diversified nutrition conglomerates, Danone S.A. and Nestlé SA occupy positions leveraging dairy processing infrastructure for probiotic culture propagation. Herbalife Nutrition exemplifies the direct-selling archetype penetrating secondary cities beyond traditional retail footprints. These players anchor competitive intensity around distribution reach and formulation standardization capabilities.
| Leading Market Players |
|---|
| Danone S.A. |
| The Kellogg Company |
| Nestlé SA |
| GlaxoSmithKline PLC |
| Herbalife Nutrition |
| Arla Foods |
| Red Bull Corporation |
| The Coca-Cola Company |
| Amway Corporation |
| Others |
Value Chain & Pricing Dynamics
Cold chain infrastructure deployment across the Lagos-Abuja and Nairobi-Mombasa corridors is compressing probiotic viability losses while simultaneously concentrating manufacturing scale among capital-heavy players with captive fermentation assets. This technology transition rewards integrated dairy processors and penalizes asset-light formulators dependent on third-party logistics, reshaping margin distribution across the value chain.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade formulations with batch documentation from mass-market vitamins and unbranded herbal powders. Certification tier under South Africa's Complementary Medicines Regulations and Nigeria's NAFDAC protocols commands substantial premiums, while volume scale in supermarket channels drives aggressive cost compression at the economy level. Price differentiation hinges on cold chain integrity guarantees and phytochemical verification capacity. Institutional buyers in healthcare settings exhibit lowest price sensitivity due to procurement mandates under the Malabo Declaration, whereas rural consumers substitute toward informal traditional medicine at the slightest premium escalation.
Supply Chain Analysis
Certification gating through South Africa's Department of Health, Nigeria's NAFDAC, and Kenya's Pharmacy and Poisons Board fragments supplier bases and elevates compliance costs for cross-border trade. Active ingredient concentration rests on European probiotic culture suppliers and Asian standardized extract providers, exposing African formulators to currency volatility and shipping disruptions. Raw material dependencies span live microbial cultures, chelated mineral precursors, and phytochemical reference standards. Single-source vulnerability in cold chain logistics across the continent's distribution corridors presents structural risk. Distribution runs through pharmacy chain networks in urban centers, with e-commerce platforms penetrating secondary cities beyond traditional retail footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa nutraceutical market functions as a stable compounder anchored by the Malabo Declaration's institutional procurement mandates, which generate predictable demand streams for fortified foods and clinical-grade formulations across African Union member states.
For Market Incumbents: Hedge against substitution by informal traditional medicine through backward integration into indigenous botanical cultivation and captive probiotic fermentation capacity. Deepen vertical control over phytochemical standardization by acquiring Cape Town-based potency verification laboratories. Channel control through exclusive pharmacy chain partnerships in Nigeria's urban centers and Kenya's Nairobi-Mombasa corridor defends margin position against direct-selling network encroachment.
For New Entrants and Emerging Players: AfCFTA harmonization protocols under the African Continental Free Trade Area open a window for regulatory arbitrage by enabling single-registration market access across multiple member states. Target Ethiopia and Tanzania's white-space pharmacy corridors where urbanization outstrips formal retail coverage. Pursue direct-selling network models penetrating secondary cities beyond Lagos, Nairobi, and Johannesburg, leveraging personalized nutrition consultations to bypass entrenched pharmacy distribution.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap herbal extract standardizers lacking in-house phytochemical verification capacity. Long-term viability over the extended horizon centers on regulatory compliance certification stacking and cold chain partnership depth. Acquisition target archetype: regional distributors with established Pharmacy and Poisons Board relationships in East Africa. Monitor AfCFTA mutual recognition protocol implementation as the inflection signal for cross-border margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Partnership Expansion | Probiotic viability guarantees differentiate premium brands in South Africa's pharmacy chains. |
| Indigenous Botanical Cultivation | Backward integration into Kenyan and Nigerian herbal sourcing reduces third-party testing dependency. |
| Direct-Selling Network Buildout | Personalized consultation models capture secondary cities beyond traditional retail footprints. |
| Regulatory Certification Stacking | NAFDAC plus Complementary Medicines Registration enables premium pricing in institutional channels. |
| Phytochemical Verification Acquisition | Cape Town laboratory assets anchor regional standardization capabilities for herbal supplements. |
Study Parameters
Multiple input streams — primary interviews with regulatory affairs leads at African national pharmaceutical agencies, brand managers at multinational nutrition conglomerates, and pharmacy chain procurement directors — were reconciled against secondary validation from African Union nutrition security databases, NAFDAC registration filings, and South African Department of Health regulatory gazettes. Bottom-up demand modeling across product type, end user, distribution channel, and form segments was triangulated with top-down macroeconomic projections for urbanization and healthcare expenditure.
Data-stream reconciliation anchored volume and value outputs across the analysis window through segmented growth rate derivation. Modeled dimensions encompassed product type tiering, end-user concentration, distribution pathway, and regional regulatory cluster. CAGRs were computed from historical trajectory analysis and forward-looking demand elasticity assessment. Forecast inputs incorporated Malabo Declaration procurement timelines, e-commerce penetration curves in Nigerian secondary cities, and cold chain infrastructure deployment schedules along East African logistics corridors.
Revisions become necessary when AfCFTA harmonization protocols stall, currency volatility disrupts active ingredient import economics, or traditional medicine substitution accelerates beyond modeled parameters. Forecasts reflect assumptions around regulatory enforcement consistency and institutional procurement continuity. A model refresh is warranted upon material change in cold chain infrastructure investment commitments or Malabo Declaration implementation pace across African Union member states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
Europe Amino Acid in Dietary Supplements Market
Nutritional Supplements
Lithium Orotate Supplement Market
Nutritional Supplements
North America Bovine Lactoferrin Market
Nutritional Supplements
Heart Health Supplement Market
Nutritional Supplements
Omega-3 Fish Oils Market
Nutritional Supplements
Dextrose Monohydrate Market
Nutritional Supplements
Garlic Supplements Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Global Nutraceutical Market
Nutritional Supplements
North America Vegan Supplements Market
Nutritional Supplements
Green Food Supplements Market
Nutritional Supplements
Botanical Supplements Market
Nutritional Supplements
Asia-Pacific Dietary Supplement Market
Nutritional Supplements
Maternity Vitamins and Supplements Market
Nutritional Supplements
South America Nutraceuticals Market