
 Organic Edible Oil Market | 2026-2036
Organic Edible Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Edible Oil Market Analysis
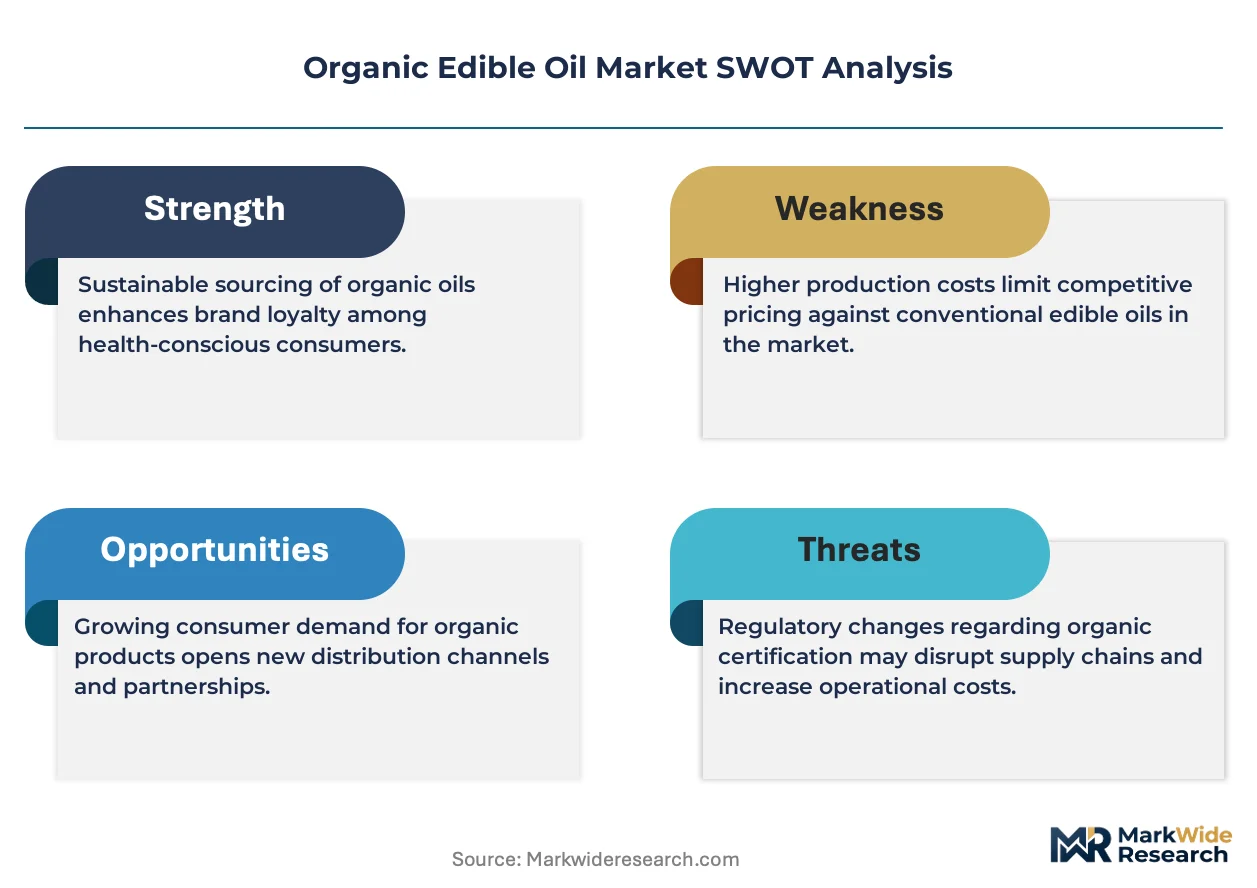
European organic oilseed acreage is rebalancing after weather-driven shortfalls in the Black Sea region. Cargill Inc. leverages its crush facility network across the Netherlands and Germany to secure organic soybean and rapeseed supply. EFKO sustains a dominant position in Eastern European organic sunflower oil through backward integration into Ukrainian farming cooperatives. Nutiva Inc. differentiates via specialization in virgin coconut oil sourced from certified farms in Sri Lanka and the Philippines.
Organic edible oil denotes lipid extracts obtained from plants cultivated without synthetic pesticides, genetically modified organisms, or petroleum-based fertilizers, typically cold-pressed or expeller-pressed below 50 degrees Celsius to preserve tocopherols and phenolic compounds. The substance serves commercial food manufacturing, retail cooking, and cosmetic formulation where clean-label positioning commands price premiums. Olive oil occupies the largest revenue pool among product types due to entrenched Mediterranean diet associations and established EU organic certification infrastructure. Avocado oil represents the fastest-expanding category as North American households and restaurants adopt high-smoke-point alternatives to conventional vegetable oils. Bulk containers capture disproportionate margin contribution from food manufacturers seeking to reduce per-unit packaging costs in high-volume frying and baking applications.
USDA organic standards in the United States and EU organic regulations enforced by EFSA and national competent authorities mandate strict traceability from farm to bottle, creating compliance barriers for uncertified imports. REACH and emerging CSRD disclosure requirements in Europe are pressuring processors to document carbon intensity across oilseed cultivation, crushing, and refining stages. Stakeholders must monitor how divergent national interpretations of organic integrity rules affect cross-border bulk shipment eligibility and retail label claims.
Market Dynamics
EU Green Deal farm-to-fork mandates are compressing chemical-free sourcing timelines for food manufacturers, forcing rapid reconfiguration of oilseed procurement networks across crushing and refining stages.
Growth Catalysts
- REACH and CSRD disclosure rules:European processors face mandatory carbon intensity documentation across cultivation and refining stages, accelerating certified organic capacity investments.
- Avocado oil adoption:North American restaurants and households are replacing conventional vegetable oils with high-smoke-point alternatives for frying applications.
- German retail expansion:Conventional supermarket chains have expanded certified organic cooking oil shelf space, concentrating demand in this single market.
Market Restraints
- Input cost volatility:Organic oilseed premiums over conventional feedstock fluctuate with weather-driven shortfalls in Black Sea and Ukrainian growing regions.
- Supply concentration risk:Eastern European organic sunflower oil production depends heavily on backward-integrated Ukrainian farming cooperatives.
- Regulatory friction:Divergent national interpretations of organic integrity rules between USDA and EU organic standards create cross-border bulk shipment eligibility barriers.
Strategic Opportunities
- Argentina cold-press upgrades:Export-grade organic sunflower oil yield quality improvements position South American suppliers for European procurement expansion.
- Sri Lankan and Philippine coconut specialization:Virgin coconut oil from certified tropical farms offers clean-label differentiation for cosmetic and premium food formulations.
- EU Green Deal tightening:Progressive chemical-free sourcing requirements through 2030 create guaranteed offtake pathways for certified organic crush capacity.
Industry Challenges
- Traceability system complexity:Farm-to-bottle documentation mandated by EFSA and national competent authorities strains legacy ERP infrastructure at mid-scale processors.
- Certification timeline compression:Three-year organic conversion periods for conventional oilseed acreage lag behind manufacturer procurement deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Edible Oil Market |
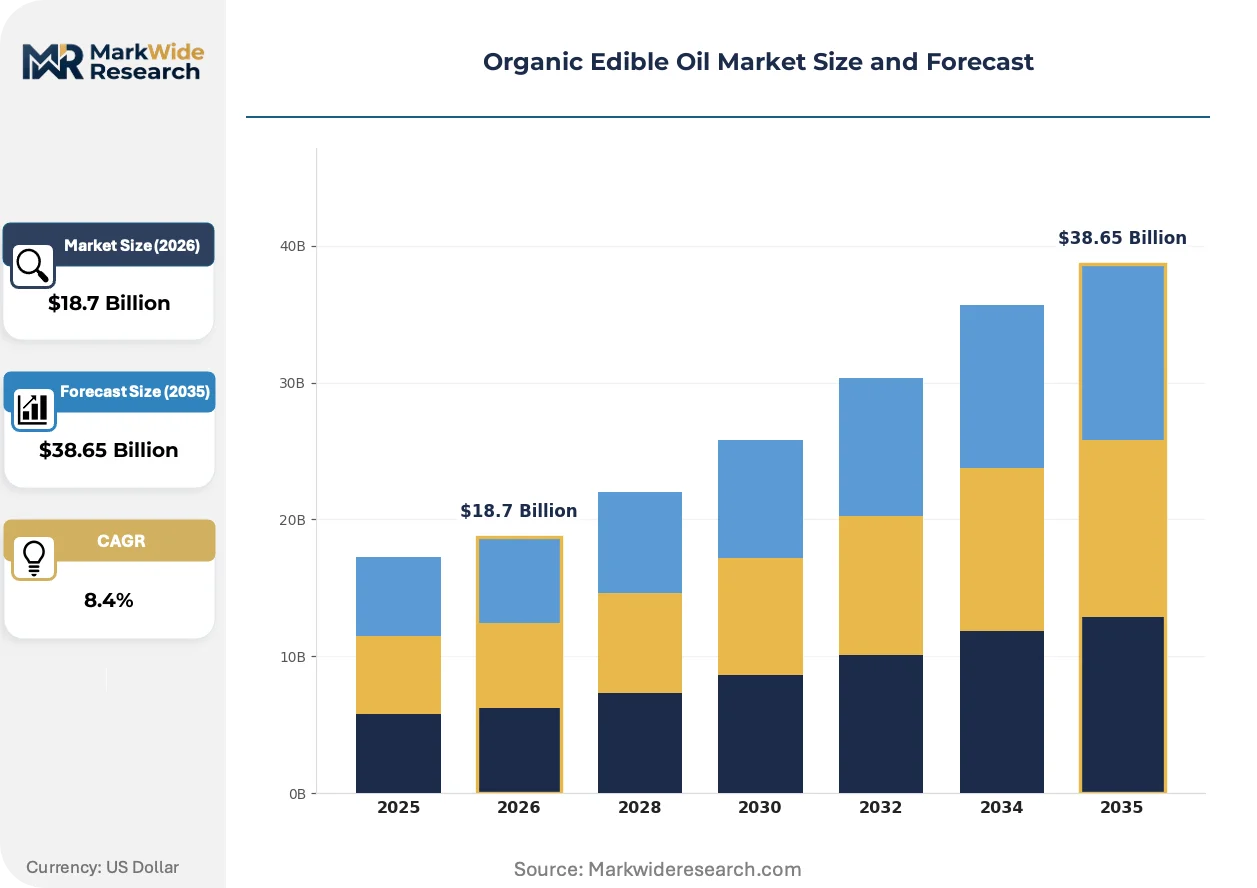
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Olive Oil, Coconut Oil, Sunflower Oil, Avocado Oil Packaging Type: Bottles, Tetra Packs, Bulk Containers, Cans End User: Households, Restaurants, Food Manufacturers, Retailers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Aryan International, EFKO, Adams Group, NOW Health Group Inc., Clearspring Ltd., Cargill Inc., Catania Spagna, Eden Foods Inc., Nutiva Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Edible Oil Market Emerging Trajectories
Extraction technology and regulatory disclosure frameworks are simultaneously reshaping how organic edible oil moves from field to formulation, with cold-press methods and carbon accounting now central to competitive positioning.
Supercritical CO2 extraction is expanding into organic edible oil processing, replacing solvent-based refining for high-value specialty oils. Premium cosmetic and nutraceutical manufacturers in Germany and the Netherlands are adopting this method at accelerated rates. The technology is expanding into mid-tier food applications as equipment costs decline and clean-label positioning commands wider price premiums.
CSRD mandates in Europe now require documented carbon intensity across oilseed cultivation, crushing, and refining stages. Processors must install monitoring systems or risk exclusion from institutional food manufacturing contracts. Organic olive oil suppliers in Spain and Italy face the steepest compliance curves due to fragmented smallholder supply bases.
Restaurant procurement departments now specify certified organic oils in fryer oil contracts, displacing conventional bulk purchasing patterns. Food service distributors in North America are restructuring inventory toward single-origin and cold-pressed SKUs. This specification cascade is most visible in California and New York metropolitan restaurant clusters where health-forward positioning drives menu engineering decisions.
Organic Edible Oil Market Segmentation
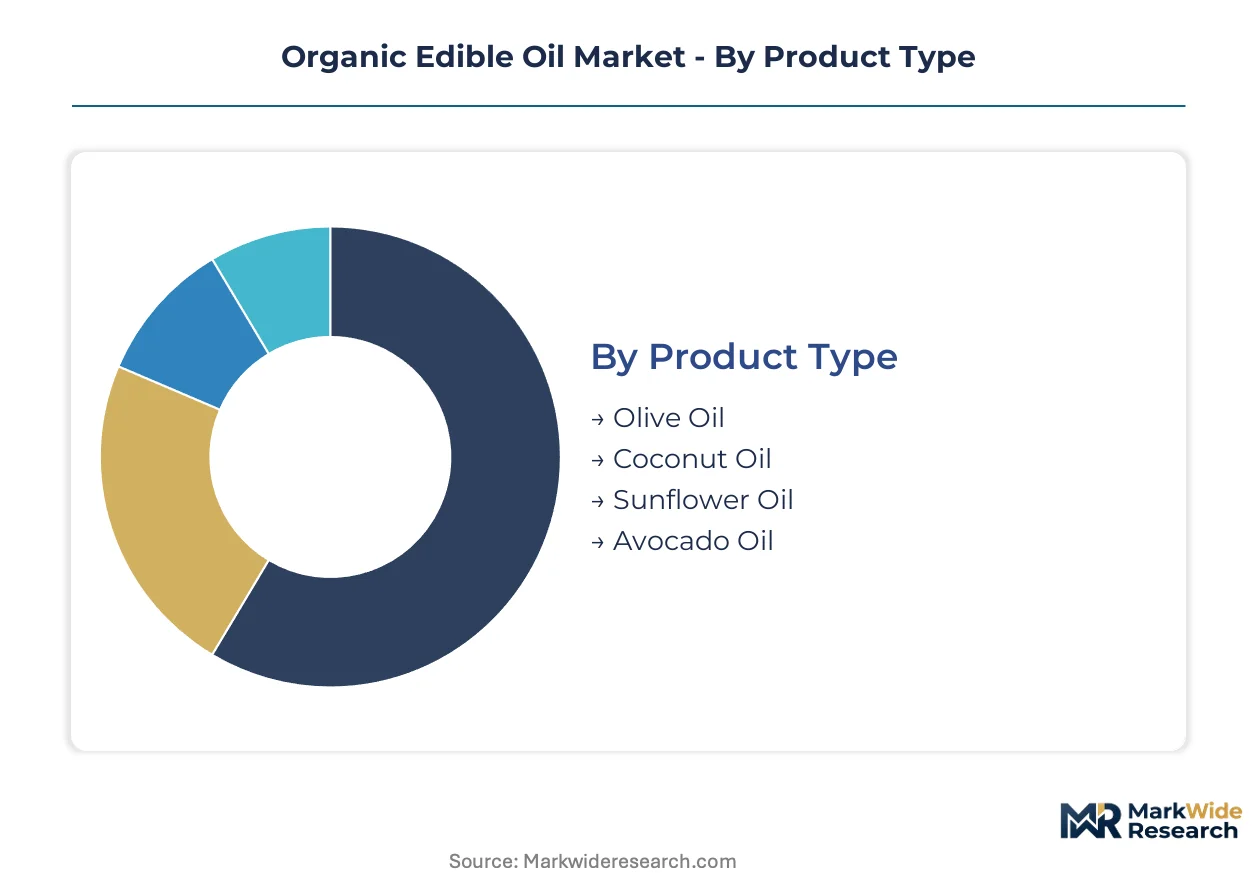
Organic edible oil procurement patterns diverge sharply across extraction methods, container formats, and buyer sophistication. Specification requirements from EFSA-registered food manufacturers differ fundamentally from household purchasing criteria tracked through German supermarket loyalty data.
Product Type:
Cold-press extraction temperature thresholds and fatty acid profiles determine suitability across frying, dressing, and cosmetic applications.
- Olive Oil:Extra-virgin grades pressed below 27 degrees Celsius retain polyphenol concentrations that command premium positioning in Mediterranean diet formulations. German and Italian retail chains allocate disproportionate shelf space to DOP-certified organic variants as EU Green Deal traceability requirements tighten.
- Avocado Oil:High smoke points above 270 degrees Celsius position this segment for restaurant fryer oil contracts displacing conventional vegetable alternatives. North American procurement departments in California and New York metropolitan clusters now specify certified organic grades for health-forward menu engineering.
- Sunflower Oil:Ukrainian farming cooperatives supply high-oleic organic varieties through backward-integrated Eastern European crush networks.
- Coconut Oil:Virgin grades from Sri Lankan and Philippine certified farms serve cosmetic clean-label formulations requiring lauric acid consistency.
Olive oil leads on scale; avocado oil leads on momentum.
Packaging Type:
Container selection correlates directly with buyer volume thresholds and oxidation risk tolerance across distribution distances.
- Bulk Containers:Food manufacturers operating high-volume frying and baking lines specify tote and drum formats to minimize per-unit packaging costs. REACH documentation requirements for German processors favor reusable intermediate bulk containers with embedded lot tracking.
- Bottles:Glass and PET formats dominate household retail in German conventional supermarket chains where organic shelf space expansion concentrates demand. UV-blocking amber glass commands premium positioning for cold-pressed specialty oils with tocopherol preservation claims.
- Tetra Packs:Aseptic cartons extend shelf life for coconut and sunflower oils in ambient distribution channels.
- Cans:Metal packaging serves food service distributors in North America seeking stackable formats for restaurant back-of-house storage.
Bulk containers dominate manufacturing procurement; bottles lead household velocity.
End User:
Buyer technical sophistication determines specification stringency from farm-to-bottle traceability through smoke point certification.
- Food Manufacturers:EFSA-registered processors mandate three-year organic conversion documentation and carbon intensity disclosures under CSRD rules. German bakery and snack producers now require cold-pressed sunflower and rapeseed oils with certified tocopherol retention above 90 percent.
- Restaurants:Fryer oil contracts in California and New York metropolitan clusters increasingly specify certified organic grades with single-origin provenance. Procurement departments track oxidation stability metrics for high-heat applications.
- Households:German consumers concentrate demand through conventional supermarket chains where organic cooking oil shelf space has expanded significantly.
- Retailers:Private label programs require processors to maintain dual USDA and EU organic certifications for cross-border bulk shipment eligibility.
Food manufacturers lead on specification density; restaurants lead on adoption velocity.
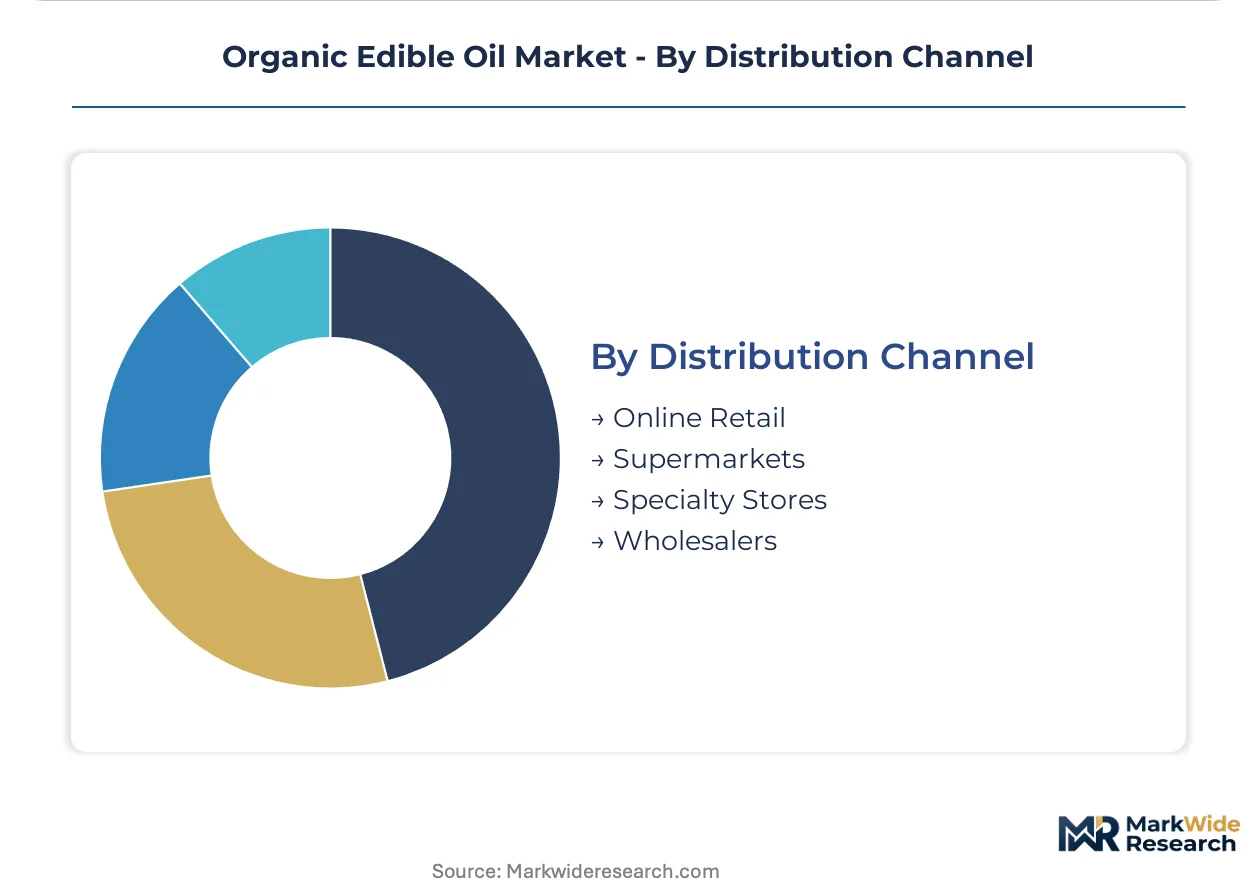
Distribution Channel:
Channel selection reflects buyer urgency, lot size requirements, and certification verification needs.
- Supermarkets:German conventional chains have expanded certified organic cooking oil shelf space faster than specialty formats, concentrating demand in this single market. REWE and EDEKA loyalty data tracks household migration from conventional to organic vegetable oils.
- Online Retail:Direct-to-consumer platforms serve North American households seeking single-origin avocado and coconut oils with embedded QR traceability. Subscription models lock in recurring revenue for Sri Lankan and Philippine virgin coconut oil suppliers.
- Specialty Stores:Organic food retailers in the Netherlands and Germany curate cold-pressed olive oil assortments with DOP and PGI documentation.
- Wholesalers:Food service distributors in North America restructure inventory toward certified organic fryer oils for restaurant contract fulfillment.
Supermarkets lead on volume concentration; online retail leads on growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting organic oilseed crush capacity toward jurisdictions with streamlined certification reciprocity between USDA and EU organic standards. Argentina's cold-press upgrade investments and Germany's retail shelf-space expansion illustrate how compliance cost differentials reshape sourcing geography.
Germany
Conventional supermarket chains REWE and EDEKA have expanded certified organic cooking oil shelf space faster than specialty retailers, concentrating household demand in this single market. EU Green Deal farm-to-fork mandates enforced by EFSA and national competent authorities compress chemical-free sourcing timelines for domestic food manufacturers. The Rhine-Ruhr industrial corridor hosts processing facilities documenting carbon intensity under CSRD disclosure rules.
United States
North American restaurants in California and New York metropolitan clusters now specify certified organic fryer oils with single-origin provenance for health-forward menu engineering. USDA organic standards mandate strict farm-to-bottle traceability that creates compliance barriers for uncertified imports. Food service distributors restructure inventory toward cold-pressed avocado and sunflower oil SKUs.
Argentina
Cold-press extraction technology upgrades are improving export-grade organic sunflower oil yield quality for European procurement expansion. The country's national agricultural regulator oversees organic conversion documentation that lags three years behind manufacturer procurement deadlines. Pampas region farming cooperatives supply high-oleic varieties through backward-integrated crush networks.
Ukraine
Eastern European organic sunflower oil production depends heavily on farming cooperatives integrated into crush networks serving EFKO and other processors. Weather-driven shortfalls in Black Sea growing regions create input cost volatility that fluctuates organic oilseed premiums over conventional feedstock. Odessa corridor facilities face traceability system complexity from EFSA farm-to-bottle documentation mandates.
Sri Lanka
Virgin coconut oil from certified tropical farms serves cosmetic clean-label formulations requiring lauric acid consistency for German and Dutch premium manufacturers. The country's national food safety authority enforces organic integrity rules that diverge from EU interpretations, creating cross-border bulk shipment eligibility barriers. Colombo processing clusters specialize in cold-pressed grades with tocopherol preservation claims.
Organic Edible Oil Market Vendor Landscape
European producers anchor one tier through backward-integrated crush networks; tropical-origin specialists hold differentiated positioning in virgin coconut and specialty oils. The vendor base stratifies across scale-driven commodity processors, geographic niche players, and certification-heavy branded suppliers. Three archetypes dominate: EU-integrated oilseed crushers with carbon disclosure compliance, tropical-origin single-source specialists, and North American distribution-heavy brands. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure organic conversion acreage ahead of procurement deadlines.
Among EU-integrated processors, Cargill Inc. and EFKO exemplify the scale-driven archetype through crush facility networks spanning the Netherlands, Germany, and Eastern European farming cooperatives. Nutiva Inc. occupies a position within the tropical-origin specialist tier, representing clean-label differentiation through certified farm relationships in Sri Lanka and the Philippines. These three companies illustrate how competitive positioning depends on upstream control over organic oilseed supply and downstream compliance with divergent USDA and EU organic standards.
| Leading Market Players |
|---|
| Aryan International |
| EFKO |
| Adams Group |
| NOW Health Group Inc. |
| Clearspring Ltd. |
| Cargill Inc. |
| Catania Spagna |
| Eden Foods Inc. |
| Nutiva Inc. |
| Others |
Supply Flow & Price Mechanics
Organic oilseed premiums over conventional feedstock cascade through crush margins to retail shelf price tiers, with weather-driven shortfalls in Ukrainian growing regions compressing processor margins before REACH documentation costs layer onto German food manufacturer procurement.
Pricing Analysis
Distributor markups on bulk organic sunflower oil shipments from Argentina to Rotterdam compress as European processors consolidate procurement volumes under CSRD-mandated carbon disclosure contracts. Price differentiation stratifies across EU organic certification grade, cold-press temperature threshold documentation, and tocopherol retention percentage. Pricing pressure stems from three-year organic conversion timelines lagging manufacturer procurement deadlines. Food manufacturers exhibit highest price sensitivity due to bulk volume scale, while cosmetic formulators absorb premiums for virgin coconut oil lauric acid consistency.
Supply Chain Analysis
Container freight rates from Colombo to Hamburg directly affect Sri Lankan virgin coconut oil competitiveness in German cosmetic formulations. Supply concentrates in Ukraine for high-oleic sunflower varieties, Argentina for export-grade crush capacity, and Sri Lanka for lauric acid-rich coconut grades. Crush networks draw from organic farming cooperatives, cold-press equipment, and EFSA-traceable documentation systems. Single-source vulnerability runs through Odessa corridor facilities facing Black Sea logistics disruption. Distribution runs through REWE and EDEKA supermarket chains for household velocity, with food service wholesalers serving North American restaurant procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EU Green Deal farm-to-fork mandates force specification upgrades toward certified organic cold-pressed grades with embedded carbon intensity documentation.
For Market Incumbents: To counter input cost volatility from Black Sea weather-driven shortfalls, Cargill-class processors should deepen backward integration into Pampas region farming cooperatives and install supercritical CO2 extraction capacity for premium cosmetic contract capture. EFKO-similar players must secure dual USDA-EU organic certification reciprocity ahead of retailer private label deadline compression.
For New Entrants and Emerging Players: CSRD disclosure rules in Germany open a window for carbon-accounting-specialized crush facilities serving Rhine-Ruhr bakery and snack producers. White-space targets include aseptic Tetra Pack coconut oil for ambient distribution channels and single-origin avocado oil subscription models for North American direct-to-consumer platforms. The most penetrable entry point runs through online retail traceability-embedded SKUs bypassing conventional supermarket slotting fees.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale processors lack ERP infrastructure for EFSA farm-to-bottle documentation mandates. Long-term viability favors acquirers of tropical-origin single-source specialists with certified acreage locked through multi-year grower contracts. The inflection signal to watch is German supermarket chain private label program specification cascades requiring dual certification for cross-border bulk eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farming Cooperatives | Captive organic oilseed supply secures margin against Black Sea input cost volatility. |
| Supercritical CO2 Extraction Installation | Clean-label positioning commands premium from German cosmetic and nutraceutical manufacturers. |
| Dual Certification Investment | USDA-EU organic reciprocity unlocks REWE and EDEKA private label program participation. |
| Carbon Intensity Monitoring Systems | CSRD compliance maintains institutional food manufacturing contract eligibility across Europe. |
| Single-Origin Provenance Branding | QR-traceable SKUs penetrate North American online retail subscription models. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with organic oilseed procurement managers at EFSA-registered food manufacturers, crush facility operations directors in Argentina and Germany, and coconut oil processing executives in Sri Lanka with secondary validation from EU organic certification databases, customs trade flow records, and CSRD implementation guidance documents. Bottom-up volume modeling and top-down value triangulation anchored market size estimates.
Historical reference periods established baseline organic oilseed acreage conversion rates, cold-press capacity utilization, and retail shelf space allocation trends that informed projection assumptions across the modeling period. Segmentation dimensions included extraction method temperature thresholds, container format volume tiers, end-user specification stringency levels, and distribution channel certification verification requirements. CAGRs derived from regression analysis against EU Green Deal implementation timelines and North American restaurant procurement specification cascades, with organic conversion lag times and supercritical equipment cost curves as key forecast inputs.
Revisions become necessary when EFSA organic integrity rule interpretations diverge across member states, Black Sea logistics corridors face sustained disruption, or CSRD carbon accounting methodologies shift materially. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Boysenberry Extract Market
Ingredients
Safflower Oil Market
Ingredients
Fish Gelatin Market
Ingredients
Precision Fermentation Ingredient Supplier Market
Ingredients
Plant Based Thickener Market
Ingredients
China Gelatin Market
Ingredients
Medium-Chain Triglyceride (MCT) Fat Market
Ingredients
Eucalyptus Oil Market
Ingredients
Global Personal Care Active Ingredients Market
Ingredients
Homecare Ingredients Market
Ingredients
Blue Light Protection Ingredients Market
Ingredients
India Protein Market
Ingredients
Green Gram Powder Market
Ingredients
Fermentation Ingredient Market
Ingredients
Virgin Coconut Oil Market
Ingredients
Sugared Egg Yolk Market