
 North America Corn Starch Market | 2026-2036
North America Corn Starch Market Size, Share, and Industry Trends Forecast 2026-2036
North America Corn Starch Market Intelligence
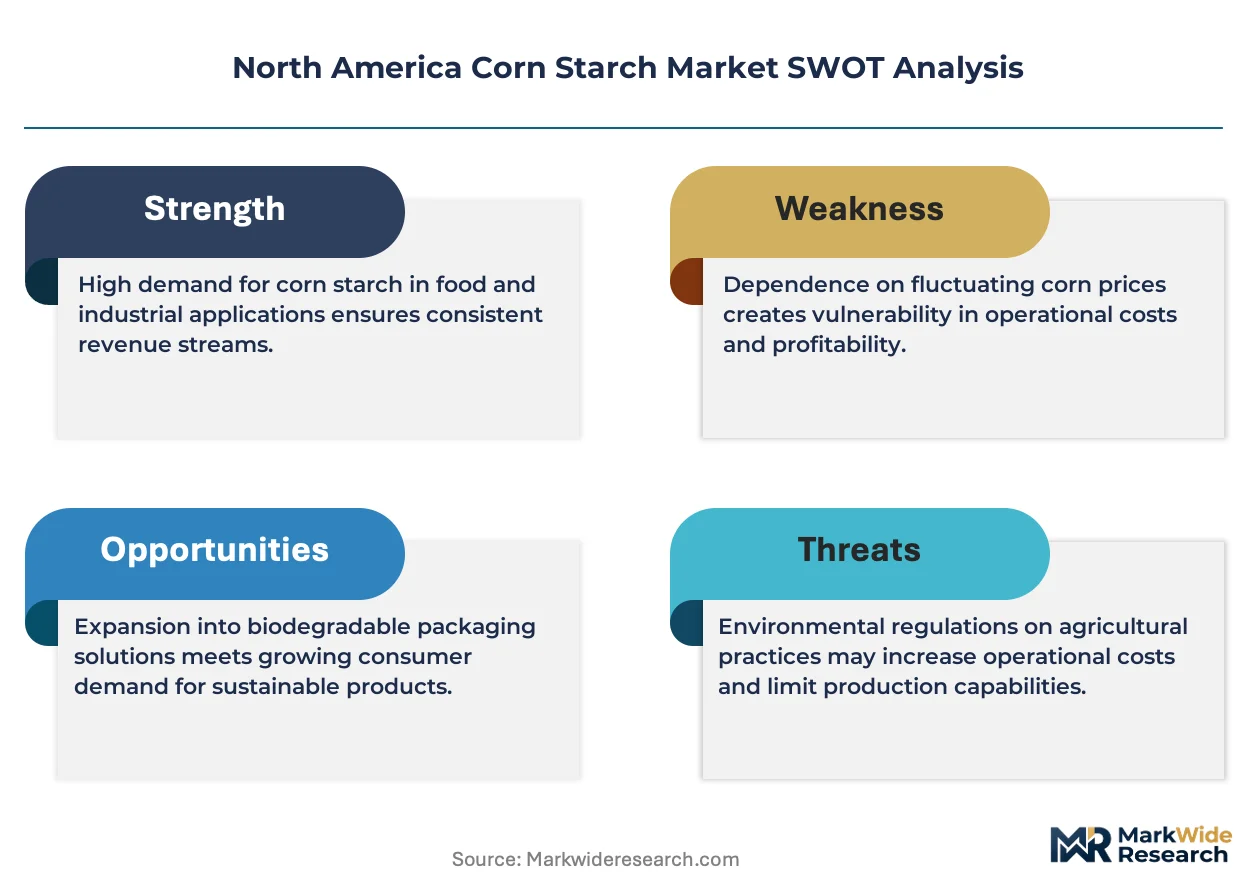
EPA biofuel blending mandates is shifting capital allocation across corn wet-milling operations, raising compliance thresholds for new entrants. Cargill Incorporated leverages its captive corn supply and river logistics network to sustain margin advantages in bulk native starch. Ingredion Incorporated anchors its position through modified starch R&D pipelines serving pharmaceutical binding applications. Archer Daniels Midland Company competes on fermentation-grade starch output tied to bioplastics feedstock demand.
North America corn starch comprises carbohydrate polymers extracted from maize endosperm through wet-milling or dry-milling, typically containing 27% amylose and 73% amylopectin by weight, functioning as a thickening, gelling, and stabilizing agent across industrial and consumer applications. Modified starch commands the dominant value share due to cross-linked and oxidized variants replacing synthetic additives in food and beverage formulations. Specialty starch represents the fastest-expanding product category as pharmaceutical-grade purity grades gain traction in excipient applications. The food and beverage application segment occupies the deepest margin pool, though personal care absorbency applications in dry shampoo and powder formulations are gaining formulation share.
The U.S. Food and Drug Administration oversees GRAS self-affirmation pathways for food-grade corn starch, while EPA Renewable Fuel Standard obligations cascade into starch allocation decisions between food and ethanol channels. Health Canada and PMRA coordinate cross-border pesticide residue tolerances affecting corn sourcing standards for starch destined for pharmaceutical excipient use. Stakeholders must monitor how evolving biofuel policy intersects with food-security priorities to anticipate starch supply availability and pricing volatility.
Market Dynamics
The EPA Renewable Fuel Standard is redirecting corn wet-milling capacity toward ethanol channels, tightening food-grade starch availability and amplifying price volatility across formulation-dependent industries.
Growth Catalysts
- Clean-label mandates:Food and beverage formulators are replacing synthetic thickeners with native and modified corn starch variants to meet retailer clean-label requirements.
- Bioplastics feedstock pull:Fermentation-grade starch demand from polylactic acid manufacturers in the U.S. Midwest is absorbing surplus wet-milling output.
- Pharmaceutical excipient upgrading:Modified starch with enhanced binding properties is displacing microcrystalline cellulose in tablet formulations across North American contract manufacturing organizations.
Market Restraints
- Input cost volatility:Fertilizer and natural gas price swings directly compress wet-milling margins, with natural gas accounting for substantial energy input in drying and dewatering stages.
- Supply concentration risk:Wet-milling infrastructure clusters in Illinois, Iowa, and Indiana, creating geographic vulnerability to drought-induced yield shocks.
- Substitution threat:Tapioca and potato starch variants are gaining formulation share in gluten-free baked goods where neutral flavor profiles outweigh cost considerations.
Strategic Opportunities
- Underpenetrated pharmaceutical grades:High-purity excipient certification for parenteral applications remains limited in Canada, creating first-mover potential for GMP-compliant producers.
- Regulatory tailwind:Health Canada's updated Food and Drug Regulations for novel food ingredients are streamlining modified starch approval pathways.
- Technology convergence:Enzymatic conversion processes combined with membrane filtration are enabling specialty starch fractions previously unattainable through conventional wet-milling.
Industry Challenges
- Process engineering talent scarcity:Wet-milling operations face recruitment gaps for operators skilled in continuous fermentation monitoring and enzyme dosing optimization.
- GRAS notification timelines:FDA self-affirmation pathways for new modified starch variants require 18-24 month documentation cycles, delaying product commercialization.
- Legacy equipment retrofit costs:Existing dry-milling facilities require substantial capital outlay to achieve pharmaceutical-grade air classification and metal detection standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Corn Starch Market |
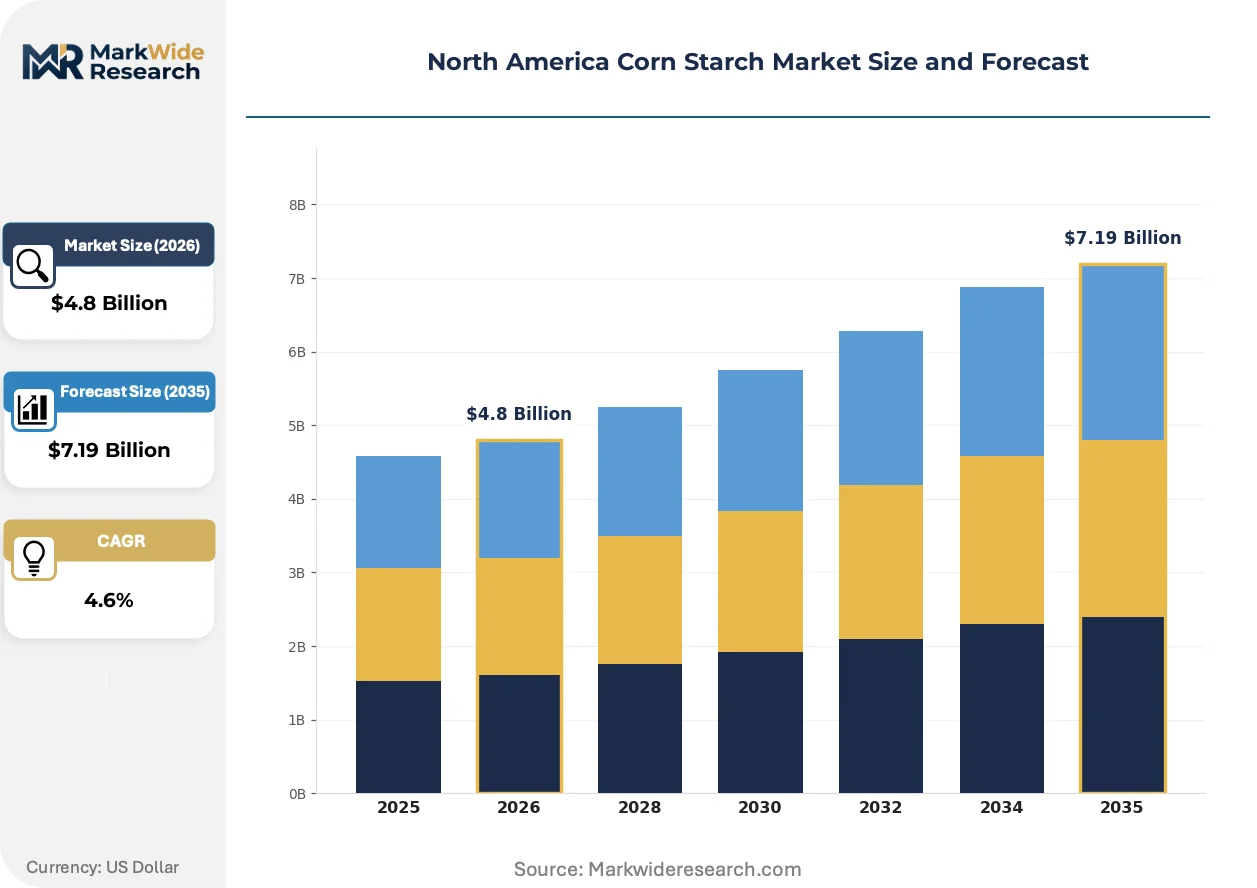
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Modified Starch, Instant Starch, Specialty Starch Application: Food & Beverage, Personal Care, Pharmaceuticals, Paper End User: Agriculture, Food Industry, Chemical Sector, Textile Packaging Type: Bulk Bags, Bags, Drums, Pails |
| Companies Covered | Tate & Lyle PLC, Grain Processing Corporation, Cargill Incorporated, Emsland Group, AGRANA Beteiligungs AG, Archer Daniels Midland Company, Roquette Frères, American Key Food Products, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Corn Starch Market Strategic Shifts & Innovations
Enzymatic modification and precision fermentation are rewriting the technical boundaries of starch functionality, while regulatory pressure on synthetic additives accelerates natural polymer substitution across formulated products.
Cross-linked and oxidized starch variants produced through controlled enzymatic treatment are rewriting the performance benchmarks for high-shear food processing. Sauce and dressing manufacturers in the U.S. Southeast are adopting these grades at accelerating rates. This enzymatic approach is rewriting the cost structure for clean-label thickeners by reducing additive loadings without viscosity loss.
The FDA's updated GRAS notification protocols for food-grade starches are tightening documentation requirements for novel modification chemistries. Wet-milling operators must now submit expanded toxicology data for cross-linked variants intended for infant nutrition applications. Pharmaceutical excipient producers serving the U.S. market are responding by segregating production lines to isolate food-grade and pharma-grade certification pathways.
Direct sourcing contracts between food manufacturers and wet-milling cooperatives are displacing traditional distributor intermediaries in bulk native starch procurement. Large bakery and snack producers in the U.S. Midwest are negotiating multi-year supply agreements with fixed-price escalators tied to corn futures. This consolidation of buying power is most visible in Illinois and Iowa, where captive supply relationships now govern over half of industrial starch movements.
North America Corn Starch Market Segmentation
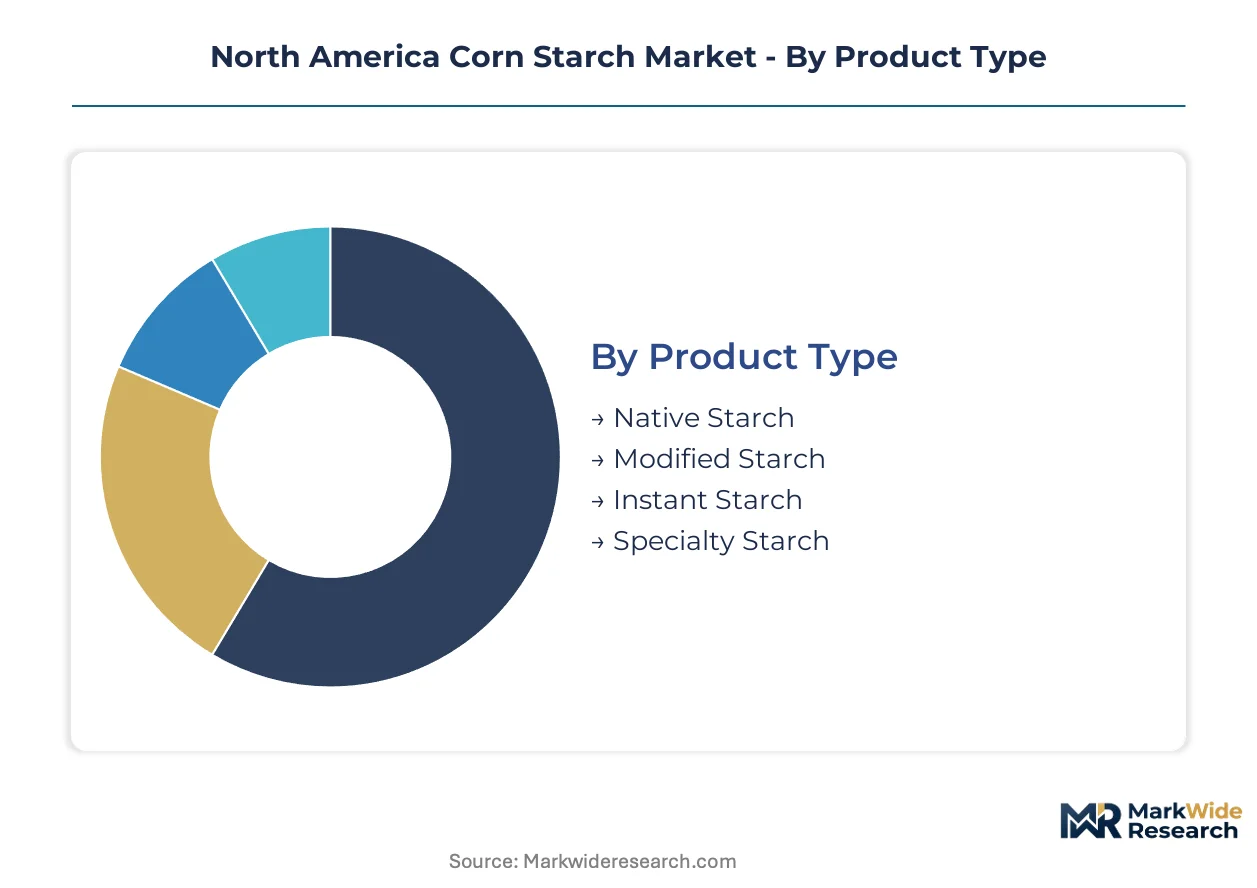
Segmentation in the North America corn starch market reveals how wet-milling output splits across functional grades, end-use specifications, and logistics configurations. Buyers prioritize different starch properties depending on whether their formulations demand viscosity stability, instant solubility, or pharmaceutical-grade purity.
Product Type:
Buyers in this category differentiate primarily by modification depth and performance under process stress.
- Modified Starch:Cross-linked and oxidized variants deliver shear-thinning resistance and acid stability for high-temperature food processing. Sauce manufacturers in the U.S. Southeast are absorbing expanded wet-milling capacity as FDA GRAS documentation requirements tighten for novel chemistries.
- Specialty Starch:High-amylose and waxy variants achieve pharmaceutical-grade purity through membrane filtration and enzymatic fractionation. Canadian parenteral excipient producers are pursuing GMP certification for sterile-grade material amid Health Canada regulatory streamlining.
- Native Starch:Unmodified carbohydrate polymers from standard wet-milling serve cost-sensitive thickening applications.
- Instant Starch:Pre-gelatinized grades hydrate without heat for cold-process beverage and dessert formulations.
Volume sits with Modified Starch; growth tilts toward Specialty Starch.
Application:
Margin capture in this category diverges sharply between formulation complexity and regulatory burden.
- Food & Beverage:Clean-label mandates from U.S. retail chains are displacing synthetic hydrocolloids with native and modified corn starch in dressings, soups, and bakery fillings. Wet-milling operators in Illinois and Iowa are dedicating separate production lines to achieve organic certification for this channel.
- Pharmaceuticals:Modified starch with enhanced binding properties is displacing microcrystalline cellulose in tablet formulations across North American contract manufacturing organizations. FDA oversight of GRAS self-affirmation pathways extends documentation cycles for excipient-grade material.
- Personal Care:Absorbency applications in dry shampoo and powder formulations are gaining formulation share as talc replacement accelerates.
- Paper:Surface sizing and coating applications consume oxidized starch grades for printability enhancement.
Revenue concentrates in Food & Beverage; steepest expansion trajectory belongs to Pharmaceuticals.
End User:
Procurement scale and technical specification intensity separate buyers in this category.
- Food Industry:Large bakery and snack producers in the U.S. Midwest negotiate multi-year supply agreements with fixed-price escalators tied to corn futures. Direct sourcing contracts with wet-milling cooperatives are displacing traditional distributor intermediaries for bulk native starch.
- Chemical Sector:Fermentation-grade starch demand from polylactic acid manufacturers in the U.S. Midwest absorbs surplus wet-milling output as EPA biofuel blending mandates redirect capacity decisions.
- Agriculture:Seed coating and dusting applications consume lower-purity starch fractions.
- Textile:Warp sizing applications favor oxidized starch for yarn strength during weaving.
Contract value peaks with Food Industry; volume growth favors Chemical Sector.
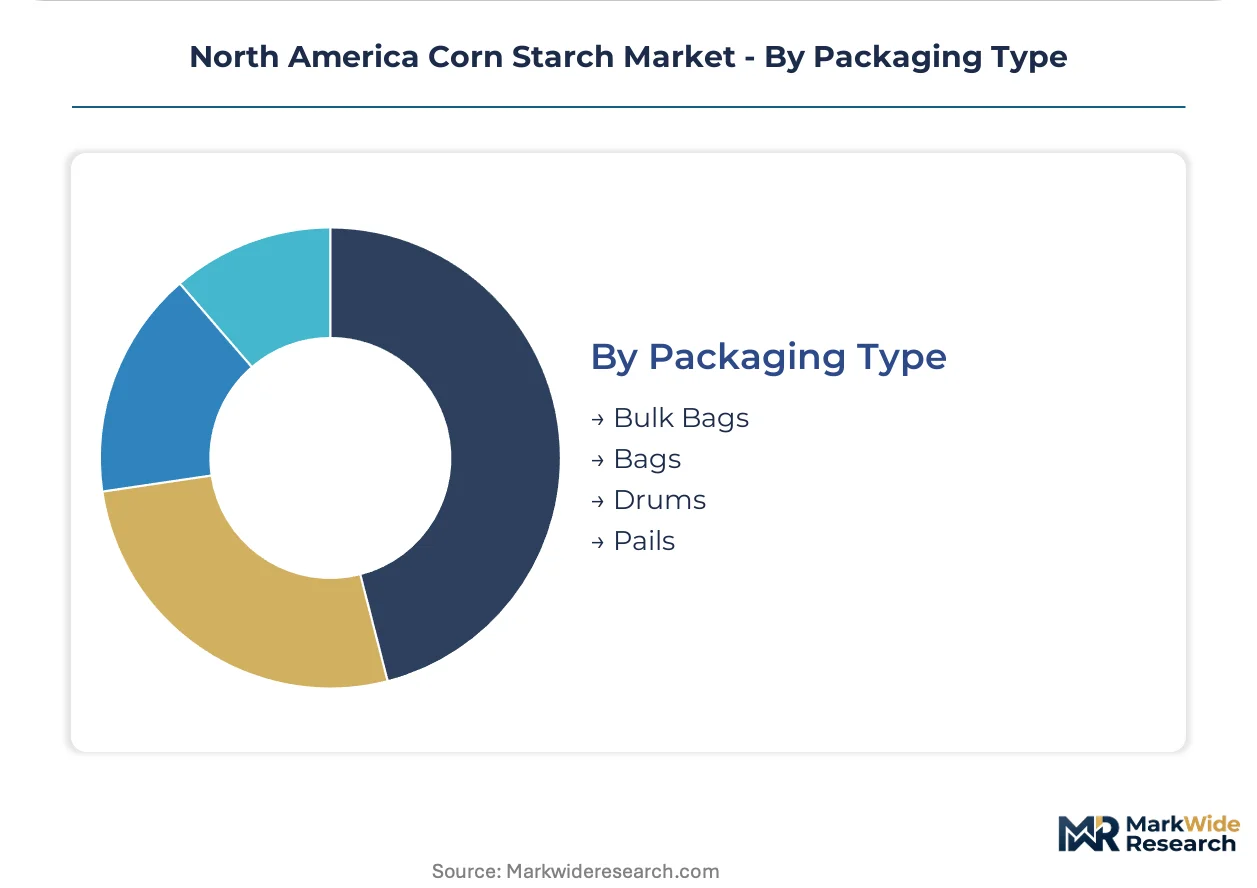
Packaging Type:
Logistics economics and contamination risk thresholds determine buyer preferences here.
- Bulk Bags:One-ton flexible intermediate bulk containers dominate industrial movements between wet-milling facilities and large food manufacturers. River barge and railcar integration from Illinois and Iowa corn belt clusters minimizes per-unit freight cost.
- Drums:Fiber or steel drums with liner bags protect pharmaceutical-grade starch from moisture and foreign particulate contamination. GMP-compliant producers serving Health Canada-regulated markets maintain segregated drum-filling lines.
- Bags:Multi-wall paper sacks serve mid-scale food processors with moderate throughput requirements.
- Pails:Small-format plastic containers address laboratory and pilot-scale pharmaceutical formulation needs.
Shipment volume concentrates in Bulk Bags; specification intensity peaks with Drums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food and beverage manufacturers cluster procurement decisions around wet-milling infrastructure, with corn belt proximity dictating supply reliability and freight economics across North American formulation operations.
United States
Illinois, Iowa, and Indiana host the densest wet-milling infrastructure, where Cargill Incorporated and Archer Daniels Midland Company operate integrated river-logistics networks. The EPA Renewable Fuel Standard redirects corn allocation toward ethanol channels, tightening food-grade starch availability. Chicago and Decatur processing clusters now dedicate separate production lines to achieve organic certification for clean-label supply chains.
Canada
Pharmaceutical-grade starch demand from Toronto and Montreal contract manufacturing organizations is accelerating Health Canada regulatory streamlining for novel excipient approvals. The PMRA coordinates cross-border pesticide residue tolerances with FDA standards. Prairie province corn sourcing increasingly feeds specialized modified starch fractions for parenteral applications where GMP compliance creates first-mover premiums.
Mexico
Bakery and snack producers in Mexico City and Guadalajara negotiate direct sourcing contracts with U.S. wet-milling cooperatives, bypassing traditional distributor intermediaries. The Secretariat of Economy's food safety modernization aligns ingredient certification with FDA GRAS pathways. Northern border states concentrate toll-processing arrangements for instant starch hydration grades serving beverage formulation.
North America Corn Starch Market Key Industry Players
U.S. Midwest producers anchor the bulk native starch tier; European and Canadian specialists hold modified and pharmaceutical-grade positions. Market structure consolidates around three integrated agribusiness conglomerates controlling captive corn supply and river logistics, while mid-cap fractionation specialists compete on enzymatic modification depth. Strategic archetypes separate into upstream-integrated commodity suppliers, R&D-driven specialty formulators, and toll-processing regional operators. Competitive moves center on backward integration into seed genetics and multi-year direct sourcing contracts with fixed-price escalators.
Within the integrated commodity tier, Cargill Incorporated and Archer Daniels Midland Company exemplify upstream control over captive corn supply and fermentation-grade output allocation. Ingredion Incorporated occupies the specialty modification archetype, anchoring pharmaceutical binding applications through modified starch R&D pipelines. Tate & Lyle PLC represents the transatlantic specialist position, bridging North American formulation demand with European enzymatic modification expertise.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Grain Processing Corporation |
| Cargill Incorporated |
| Emsland Group |
| AGRANA Beteiligungs AG |
| Archer Daniels Midland Company |
| Roquette Frères |
| American Key Food Products |
| Ingredion Incorporated |
| Others |
Cost & Logistics Intelligence
Corn futures prices on the Chicago Board of Trade cascade through wet-milling economics into three distinct pricing tiers across North American starch markets. Food-grade native starch absorbs the tightest margin compression when energy and fertilizer costs spike, while pharmaceutical-grade specialty fractions command substantial premiums through GMP certification barriers.
Pricing Analysis
Volume concentrates in commodity native starch sold through annual contracts with fixed-price escalators tied to CBOT corn futures, while margin pools deepest in pharmaceutical excipient grades certified for parenteral applications. Price differentiation hinges on certification tier—FDA GRAS self-affirmation versus Health Canada GMP compliance—and volume scale, with bulk railcar shipments achieving substantial discounts against drum-packaged pharma material. Pricing pressure stems from EPA biofuel mandates redirecting wet-milling capacity toward ethanol channels, tightening food-grade availability. Small-scale bakery and snack producers exhibit highest price sensitivity, while contract manufacturing organizations absorb premium pricing for excipient-grade supply security.
Supply Chain Analysis
Single-source vulnerability sits with Illinois, Iowa, and Indiana, where over seventy percent of North American wet-milling capacity clusters within drought-exposed corn belt geography. Raw material flows draw from captive corn supply agreements with Midwest grain elevators, while natural gas feeds drying and dewatering operations and enzyme inputs enable specialty fractionation. Supply chain risk centers on river logistics chokepoints—Mississippi barge disruptions cascade into railcar shortages and inventory accumulation at Decatur and Chicago processing hubs. Distribution runs through integrated river-rail networks for bulk industrial buyers, with drum-filling lines serving pharmaceutical channels through temperature-controlled trucking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American corn starch markets operate under sustained supply constraint as EPA biofuel mandates permanently redirect wet-milling capacity, propping pricing power for food-grade material. Capacity additions lag demand growth across pharmaceutical excipient and bioplastics feedstock channels.
For Market Incumbents: Acquire enzymatic modification technology platforms to defend margin position against tapioca and potato starch substitution in clean-label formulations. Secure captive corn supply through multi-year origination contracts with Iowa and Illinois grain elevators. Expand GMP-certified production lines for Health Canada-regulated parenteral excipient markets before regulatory streamlining attracts European competitors. For New Entrants and Emerging Players: Precision fermentation-based starch functionality platforms offer technology-first entry into high-margin pharmaceutical binding applications where modified starch displaces microcrystalline cellulose. Target Canadian parenteral excipient production where GMP certification gaps create first-mover premiums. Pursue toll-processing arrangements with underutilized Prairie province dry-milling facilities to bypass capital-intensive wet-milling infrastructure. For Investors and Strategic Acquirers: The window for entry favors mid-cap fractionation specialists with existing Health Canada relationships and enzymatic R&D pipelines. Long-term viability hinges on backward integration into seed genetics and membrane filtration capabilities. Watch EPA Renewable Fuel Standard allocation decisions as the inflection signal—sustained ethanol channel priority would amplify food-grade starch scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Genetics | Captive high-amylose corn supply secures specialty starch feedstock for pharmaceutical excipient lines. |
| GMP Certification Investment | Health Canada streamlining creates first-mover premiums for sterile-grade parenteral starch producers. |
| Enzymatic Modification Scale-Up | Cross-linked variants meet FDA GRAS documentation requirements for infant nutrition applications. |
| Direct Sourcing Contract Expansion | Multi-year agreements with Midwest bakery producers displace distributor intermediaries in bulk native starch. |
| Membrane Filtration Technology Deployment | Specialty fractionation enables waxy and high-amylose grades previously unattainable through conventional wet-milling. |
Research Approach
USDA crop production reports, EPA Renewable Fuel Standard compliance filings, and Health Canada regulatory guidance documents formed the secondary backbone for supply and policy analysis. Primary interviews with wet-milling plant managers, procurement leads at Midwest food manufacturers, pharmaceutical excipient quality directors, and grain elevator operators validated capacity utilization and pricing dynamics. Bottom-up triangulation across facility-level production data and top-down demand modeling across food, pharmaceutical, and chemical end-uses anchored volume and value estimates.
Bottom-up modeling built forecasts from individual wet-milling facility capacities, corn origination costs, and product mix allocations across native, modified, and specialty starch grades. Top-down validation cross-referenced against EPA ethanol blending mandates, FDA GRAS notification trends, and pharmaceutical excipient import data. Segmentation dimensions included product type, application intensity, end-user procurement scale, and packaging logistics configuration. CAGRs derived from capacity expansion pipelines, regulatory timeline assumptions, and substitution elasticity across tapioca and potato starch alternatives.
Several conditions sit outside the modeled scope, including extreme drought-induced yield shocks beyond historical variance, abrupt EPA biofuel mandate suspension, and breakthrough precision fermentation technologies eliminating wet-milling entirely. Forecasts reflect documented assumptions about regulatory continuity and energy input cost trajectories. Deviation in EPA Renewable Fuel Standard allocation thresholds or Health Canada excipient approval timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Gelatin Market
Ingredients
Biotech Ingredients Market
Ingredients
Edible Halal Gelatin Market
Ingredients
South America Phytosterols Market
Ingredients
Marine Collagen Ingredients Market
Ingredients
Safflower Oil Market
Ingredients
Global Dairy Protein Ingredients Market
Ingredients
Casein Market
Ingredients
Egg Phosphatidylcholine Market
Ingredients
Industrial Starch Market
Ingredients
Trait Enhanced Oils Market
Ingredients
Germany Protein Market
Ingredients
North America Potato Starch Market
Ingredients
Hydrolyzed Vegetable Protein Market
Ingredients
Specialty Feed Additives Market
Ingredients
African Brewing Enzymes Market