
 Seafood Flavors Market | 2026-2036
Seafood Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Seafood Flavors Market Analytics
Multi-source procurement of marine raw materials is hardening as a baseline industry practice. Givaudan leverages its captive supply networks across multiple coastal zones to secure consistent biomass streams. Firmenich sustains R&D intensity in enzymatic extraction protocols that yield cleaner taste profiles. Nikken Foods Co. Ltd. anchors its position through deep specialization in Asian shellfish and crustacean flavor precursors.
Seafood flavors encompass concentrated taste-active compounds derived from fish, shellfish, and marine extracts, typically manufactured through enzymatic hydrolysis, Maillard reaction, or controlled thermal processing to achieve specific flavor intensity measured in parts per million equivalence. These inputs serve primarily to replicate or amplify marine taste notes in processed foods where whole seafood inclusion proves economically or logistically impractical. Natural type variants command premium positioning due to clean-label alignment, while amplified formats capture volume in cost-sensitive sauce and dressing applications. Liquid form dominates foodservice channels for dosing flexibility, though powder formats gain traction in retail seasoning blends where shelf stability and transport efficiency matter.
FDA seafood HACCP protocols and EU REACH frameworks govern contaminant thresholds and extraction solvent approvals, directly shaping which marine sources qualify for commercial flavor production. EFSA evaluations of novel marine peptides further constrain ingredient innovation timelines for European suppliers. Stakeholders must monitor evolving biogenic amine limits under Codex Alimentarius discussions, as these standards will determine which processing geographies retain market access.
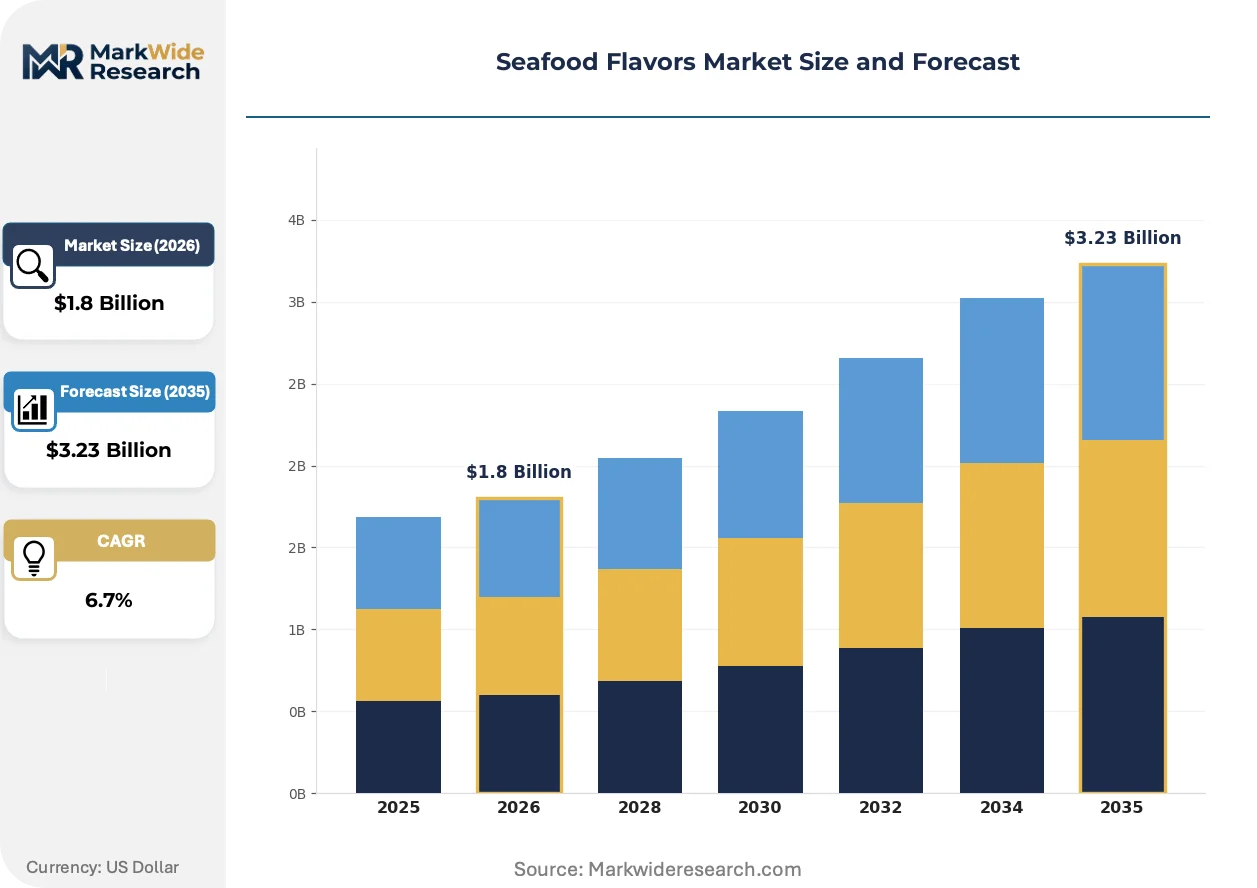
Market Dynamics
Enzymatic extraction technology is compressing production timelines for marine-derived taste compounds while EU F-Gas Regulation and biogenic amine thresholds under Codex Alimentarius discussions force simultaneous compliance investments across processing clusters.
Growth Catalysts
- Clean-label reformulation mandates:Ready-to-eat meal manufacturers in North America and Europe are stripping artificial additives from portfolios, creating direct pull for natural-type seafood flavor variants that replicate marine taste without whole-fish inclusion.
- Aquaculture byproduct valorization:Vietnamese and Thai processing clusters are converting shrimp heads, fish frames, and shellfish waste into flavor precursors through controlled enzymatic hydrolysis, lowering raw material costs for regional flavor houses.
- Maillard reaction optimization:Advanced thermal processing protocols now achieve specific flavor intensity measured in parts per million equivalence with greater batch consistency, reducing rework rates for sauce and dressing applications.
Market Restraints
- Marine biomass supply volatility:Wild-catch fluctuations and seasonal aquaculture cycles in Southeast Asian coastal zones create input cost instability for hydrolyzed fish and shellfish extract producers.
- Extraction solvent approval constraints:EU REACH frameworks limit approved solvents for commercial flavor production, disqualifying several lower-cost processing methods used in non-European geographies.
- Plant-based seafood mimicry:Algae-derived and fermented yeast alternatives are capturing share in cost-sensitive dressing applications where marine authenticity carries lower buyer priority.
Strategic Opportunities
- Underpenetrated African markets:Nigeria and South Africa present white space for shelf-stable seasoning blends as urbanization accelerates processed food consumption and retail infrastructure expands.
- EU Green Deal alignment:Carbon-neutral processing certifications are unlocking premium positioning in European retail channels where sustainability claims command shelf placement advantages.
- Direct-to-foodservice distribution:Liquid format producers are bypassing traditional ingredient distributors to establish captive supply relationships with quick-service chains requiring precise dosing flexibility.
Industry Challenges
- Enzymologist talent scarcity:Specialized biochemists capable of optimizing protease selection for specific seafood substrates command premium compensation, constraining R&D expansion for mid-tier flavor houses.
- HACCP protocol complexity:FDA seafood safety requirements demand continuous monitoring infrastructure that smaller Vietnamese and Thai processors struggle to fund without external capital.
- Novel peptide approval timelines:EFSA evaluation periods for innovative marine-derived taste-active compounds extend commercialization cycles by 18-36 months, freezing innovation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seafood Flavors Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Natural, Artificial, Organic, Amplified Application: Sandwiches, Sauces, Dressings, Seasonings Form: Liquid, Powder, Granular, Paste Market Channel: Retail, Foodservice, Online, Distribution |
| Companies Covered | Adare Food Ingredients Pvt Ltd., FLAVORCAN INTERNATIONAL INC., Givaudan, Kanegrade Ltd., Nikken Foods Co. Ltd., Firmenich, NorthTaste Flavourings Ltd., Seafood Flavours A/S, Innova Flavors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seafood Flavors Market Evolving Landscape
Process intensification and regulatory compression are forcing simultaneous technology adoption and compliance architecture rebuilds across marine flavor extraction operations.
Continuous-flow enzymatic reactors are replacing batch processing tanks in industrial-scale facilities. Ready-to-eat meal manufacturers and sauce compounders are adopting these systems at accelerated pace to secure supply commitments. This hardware transition is modularizing production footprints, allowing flavor houses to deploy smaller, distributed units closer to raw material sources rather than consolidating in single mega-facilities.
REACH authorization requirements for extraction solvents are tightening contaminant thresholds for marine-derived inputs entering European supply chains. Industrial consequence includes forced equipment replacement for processors relying on legacy solvent systems. Powder format suppliers serving retail seasoning blends are most affected, responding by relocating finishing stages to REACH-compliant tolling partners in Germany and the Netherlands.
Buyer concentration among multinational ready-to-eat meal manufacturers is compressing supplier qualification timelines. Direct sourcing teams at these food companies are displacing traditional ingredient distributors for liquid format procurement. This pattern is most visible in North American foodservice channels where chains now mandate quarterly supplier audits that smaller Vietnamese flavor houses cannot resource without consortium arrangements.
Seafood Flavors Market Segmentation
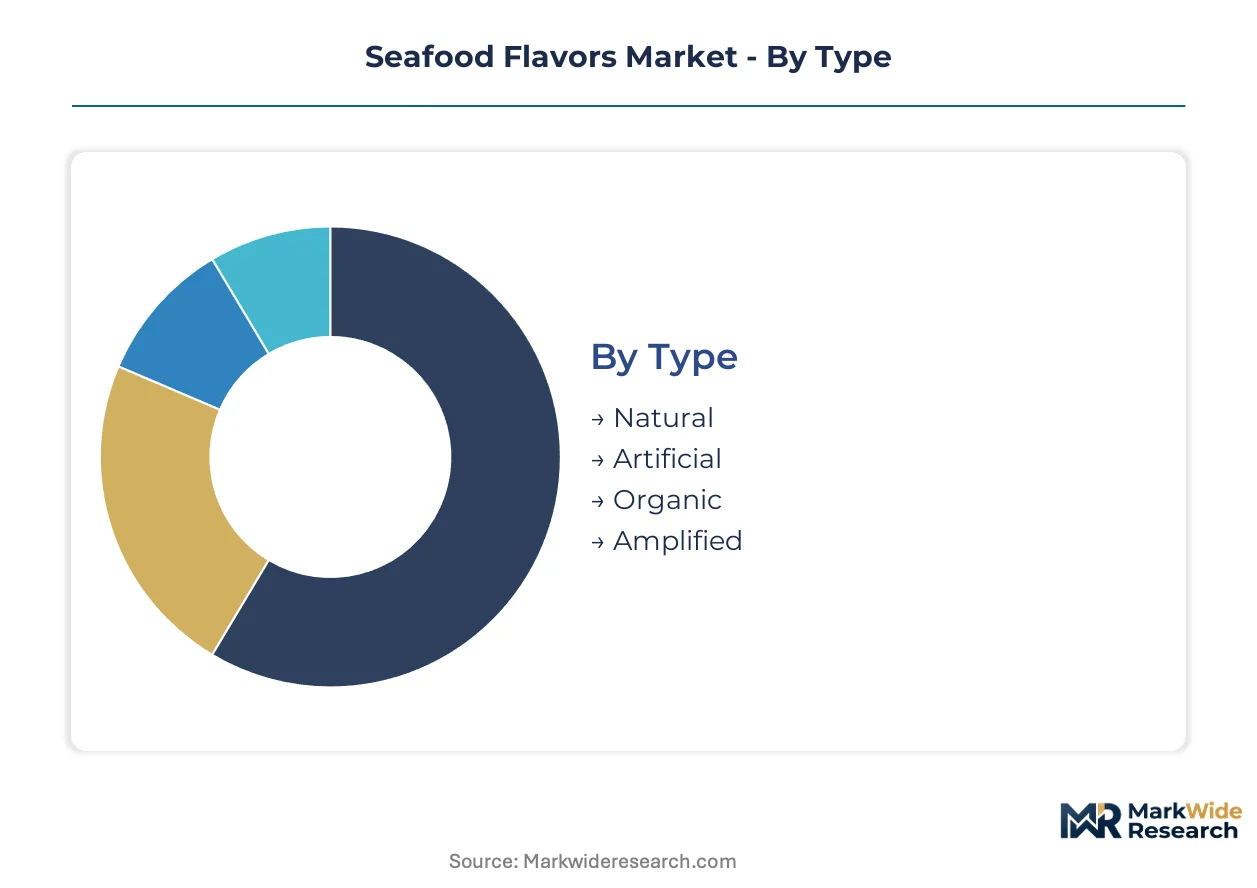
Seafood flavor procurement strategies diverge sharply across type, application, and form dimensions. Buyers prioritize clean-label alignment in premium retail channels while cost-sensitive foodservice operators optimize for dosing precision and shelf stability.
Type:
Supply concentration for marine-derived precursors favors natural extraction facilities clustered along Vietnamese and Thai coastlines.
- Natural:Enzymatic hydrolysis of fish frames and shellfish waste yields taste-active peptides with ppm-equivalent intensity. Ready-to-eat meal manufacturers in the United States and Germany are stripping artificial additives, pulling volume toward these variants despite 15-30% cost premiums over synthetic alternatives.
- Artificial:Chemically synthesized esters and aldehydes replicate crustacean and finfish notes at lower unit cost. Demand concentrates in Southeast Asian sauce compounders serving domestic markets where clean-label pressure remains weaker than in Western retail.
- Organic:Certified marine biomass from controlled aquaculture operations meets EU organic processing standards. Supply bottlenecks at EFSA-accredited extraction facilities limit commercial scale.
- Amplified:High-potency concentrates achieve target flavor impact at reduced inclusion rates. Powder seasoning blenders in Nigeria and South Africa are adopting these formats to reduce freight costs.
Natural variants absorb the bulk of installed capacity; amplified formats are expanding most quickly in emerging market retail channels.
Application:
End-use cost tiers separate premium reformulation projects from commodity sauce production.
- Sauces:Liquid seafood extracts integrate into emulsion-based formulations requiring heat stability through retort processing. North American quick-service chains are qualifying direct-supply relationships with enzymatic extraction specialists to secure consistent dosing.
- Dressings:Cold-process mayonnaise and vinaigrette applications demand lipid-compatible flavor systems with oxidative stability. Algae-derived alternatives are capturing share in cost-sensitive European private-label programs.
- Sandwiches:Pre-made fillings and spreads require shelf-stable marine notes without moisture migration. Thai processors dominate supply to Japanese convenience retail networks.
- Seasonings:Dry blends for retail and foodservice rely on powder and granular formats with 18-month stability windows. South African urban retail expansion is accelerating demand for shelf-stable sachet formats.
Sauce applications command the highest absolute volume; dressing reformulation is climbing the fastest as plant-based seafood mimicry intensifies competitive pressure.
Form:
Customer type determines format selection between precision-dosing foodservice operators and stability-focused retail manufacturers.
- Liquid:Pumpable concentrates enable gram-scale accuracy in automated sauce production lines. Direct-to-foodservice distribution models are bypassing traditional ingredient distributors in the United States and Canada.
- Powder:Spray-dried extracts with maltodextrin carriers optimize transport efficiency and warehouse storage density. REACH-compliant tolling partners in Germany and the Netherlands are absorbing finishing-stage relocation from Asian processors.
- Granular:Agglomerated particles reduce dusting and improve flow characteristics in high-speed seasoning blend operations.
- Paste:High-viscosity formats suit artisanal sauce production and small-batch foodservice preparation.
Liquid formats dominate foodservice procurement; powder output is gaining share fastest as retail seasoning blenders consolidate supply bases.
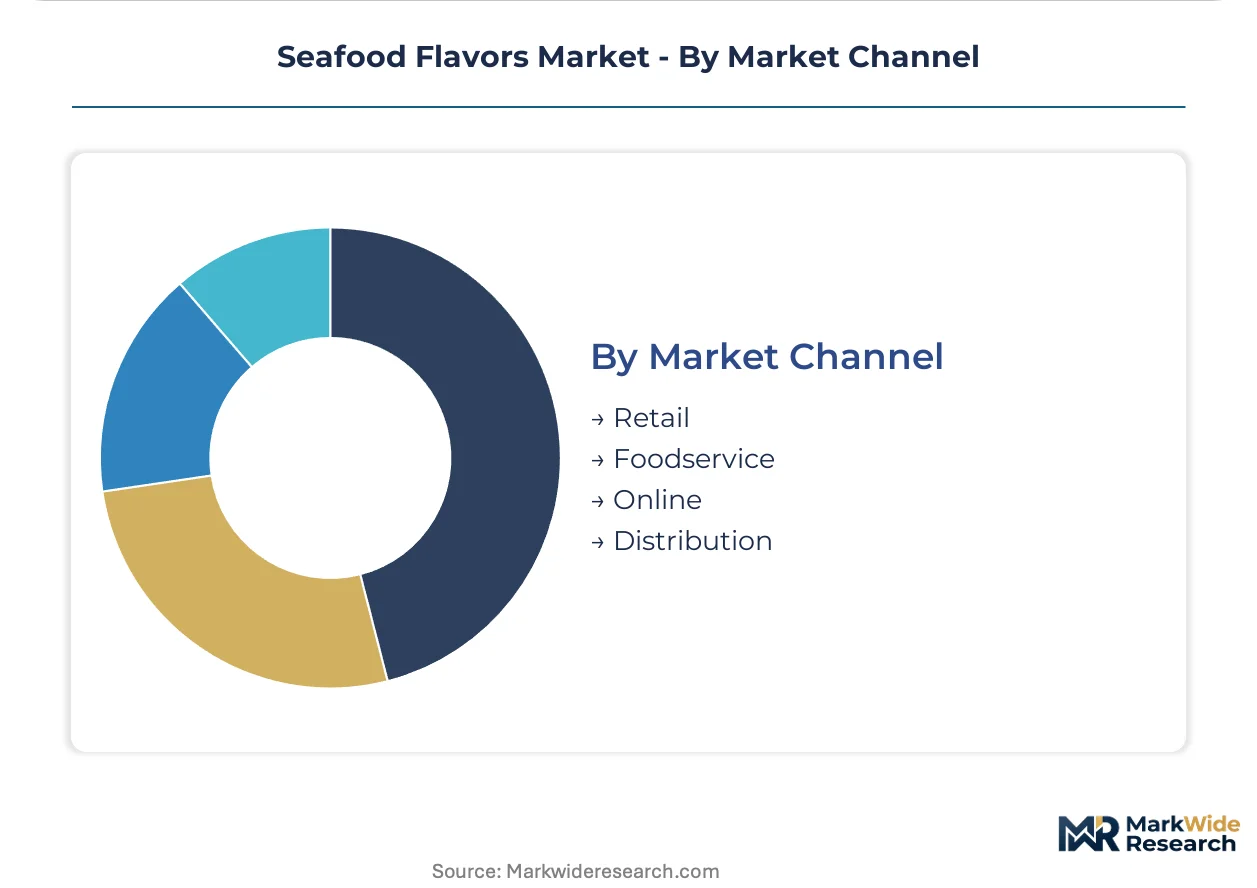
Market Channel:
Volume concentration varies between consolidated multinational buyers and fragmented regional distributors.
- Foodservice:Chain procurement teams impose quarterly supplier audits and HACCP documentation requirements. Vietnamese mid-tier flavor houses are forming consortium arrangements to meet North American audit standards.
- Retail:Supermarket and hypermarket buyers prioritize carbon-neutral processing certifications aligned with EU Green Deal requirements. Premium shelf placement accrues to REACH-compliant suppliers.
- Distribution:Traditional ingredient distributors retain relevance in fragmented African and Latin American markets where direct supplier relationships prove uneconomical.
- Online:E-commerce platforms serve small-scale food manufacturers and artisanal producers with minimum order quantities below distributor thresholds.
Foodservice channels absorb the majority of liquid format output; online distribution is expanding most quickly among specialty and craft food producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam and Thailand concentrate the fastest-expanding buyer demand for seafood flavors as their aquaculture processing clusters convert byproduct waste into flavor precursors. Ready-to-eat meal manufacturers in the United States and Germany are pulling volume toward natural extraction variants. Regulatory divergence between EU REACH frameworks and FDA seafood HACCP protocols is fragmenting compliance requirements across supply geographies.
United States
North American quick-service chains are qualifying direct-supply relationships with enzymatic extraction specialists to secure consistent liquid format dosing. FDA seafood HACCP protocols demand continuous monitoring infrastructure that favors larger processors with capital reserves. Chicago and Dallas foodservice distribution hubs are absorbing captive supply arrangements that bypass traditional ingredient distributors.
Germany
EU Green Deal carbon-neutral processing certifications are unlocking premium retail shelf placement for REACH-compliant suppliers. EFSA evaluation timelines for novel marine peptides extend commercialization cycles, freezing innovation pipelines for domestic flavor houses. Hamburg and Rotterdam tolling partners are absorbing powder format finishing stages relocated from Asian processors.
Vietnam
Shrimp head and fish frame valorization through controlled enzymatic hydrolysis is lowering raw material costs for regional flavor houses. The country's national food safety regulator enforces evolving biogenic amine limits that determine export market access. Ho Chi Minh City processing clusters are forming consortium arrangements to meet North American quarterly supplier audit standards.
Thailand
Shelf-stable marine notes for Japanese convenience retail networks dominate export demand from Thai processors. F-Gas Regulation alignment pressures are forcing equipment replacement for facilities relying on legacy solvent systems. Bangkok-area flavor houses are deepening specialization in crustacean flavor precursors to differentiate from Vietnamese competitors.
South Africa
Urban retail expansion is accelerating demand for shelf-stable seasoning sachet formats in Nigerian and domestic markets. The country's national standards body is harmonizing with Codex Alimentarius discussions on biogenic amine thresholds. Johannesburg distribution infrastructure is consolidating procurement for pan-African seasoning blenders seeking amplified format concentrates.
Seafood Flavors Market Competitive Landscape
Capacity expansion dominates the current landscape as extraction facilities modularize toward distributed units closer to raw material sources. The vendor base concentrates around three tiers: multinational flavor houses with captive coastal supply networks, mid-tier Asian specialists in shellfish and crustacean precursors, and regional tolling operators serving REACH compliance finishing. Strategic archetypes include vertically integrated biomass controllers, enzymatic protocol licensors, and carbon-neutral certification specialists. M&A activity and direct-to-foodservice distribution partnerships represent the dominant competitive vectors reshaping supplier-buyer relationships.
Within the multinational tier, Givaudan and Firmenich exemplify divergent strategic positions—one leveraging multi-zone coastal biomass security, the other sustaining R&D intensity in taste profile refinement. Nikken Foods Co. Ltd. occupies a specialist position anchored in Asian shellfish and crustacean flavor precursors. These three entities represent the competitive spectrum from global scale to deep geographic specialization.
| Leading Market Players |
|---|
| Adare Food Ingredients Pvt Ltd. |
| FLAVORCAN INTERNATIONAL INC. |
| Givaudan |
| Kanegrade Ltd. |
| Nikken Foods Co. Ltd. |
| Firmenich |
| NorthTaste Flavourings Ltd. |
| Seafood Flavours A/S |
| Innova Flavors |
| Others |
Value Network & Pricing Analysis
Clean-label reformulation mandates from North American and German ready-to-eat meal manufacturers are compressing supplier margins while forcing extraction facilities to absorb REACH compliance costs for European market access. This demand-side specification shift rewards processors with captive biomass networks and carbon-neutral certifications, widening spreads between compliant and non-compliant supply tiers.
Pricing Analysis
Volume concentration in Southeast Asian enzymatic extraction clusters runs against margin capture by REACH-accredited European tolling partners. Three-tier pricing structure across natural, amplified, and artificial variants reflects certification grade and biogenic amine testing protocols. Pricing pressure stems from plant-based seafood mimicry in European dressing applications, where algae-derived alternatives undercut marine extracts on unit cost. Cost-sensitive African seasoning blenders exhibit highest price sensitivity; North American quick-service chains prioritize dosing precision over per-kilogram rates.
Supply Chain Analysis
Freight cost optimization is driving powder format finishing-stage relocation from Vietnamese and Thai processors to German and Dutch tolling partners. Raw material supply draws from shrimp aquaculture byproduct streams in Vietnam, fish frame hydrolysis operations in Thailand, and controlled crustacean harvesting in Japanese coastal zones. Single-source vulnerability concentrates in Southeast Asian enzymologist talent pools, where specialized biochemist scarcity constrains R&D expansion. Distribution runs through direct-to-foodservice channels for liquid formats and consolidated distributor networks for African retail seasoning sachets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA-accredited extraction capacity bottlenecks are propping pricing premiums for REACH-compliant suppliers, creating durable margin pools for processors with pre-qualified novel peptide pipelines.
For Market Incumbents: Anticipate regulatory compression by securing captive biomass networks across multiple coastal zones and pre-funding EFSA evaluation timelines for innovative marine peptides. Algae-derived seafood mimicry threatens cost-sensitive dressing segments; defend position through carbon-neutral certification investments that unlock European retail shelf placement advantages. For New Entrants and Emerging Players: Enter via enzymatic protocol licensing to mid-tier Vietnamese processors lacking in-house R&D capabilities, or through direct-to-foodservice distribution partnerships with North American quick-service chains requiring precise liquid format dosing. South African urban retail expansion offers the most penetrable geography for amplified powder seasoning formats. For Investors and Strategic Acquirers: Re-rating potential sits with enzymatic extraction specialists holding EFSA pre-approval for novel marine peptides given accelerating clean-label reformulation timelines. Long-term viability favors processors with backward integration into aquaculture byproduct supply. Watch EFSA evaluation period compression as the signal indicating innovation pipeline thaw and multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aquaculture Byproduct Supply | Vietnamese processors secure shrimp head and fish frame streams at below-spot rates. |
| REACH-Compliant Tolling Partnership | German and Dutch facilities absorb powder finishing stages from Asian processors. |
| Direct-to-Foodservice Distribution | Liquid format producers bypass distributors to serve North American quick-service chains. |
| Carbon-Neutral Processing Certification | EU Green Deal alignment unlocks premium retail shelf placement in European channels. |
| Enzymatic Protocol Licensing | Technology licensors capture margin from mid-tier Vietnamese flavor houses lacking R&D scale. |
Research Methodology
Independent corroboration across primary interviews with enzymatic extraction specialists, regulatory affairs leads at flavor houses, procurement directors at ready-to-eat meal manufacturers, and aquaculture processing operators underwrites the qualitative findings. Secondary validation draws from EU REACH authorization databases, EFSA novel food evaluations, FDA seafood HACCP guidance documents, and Vietnamese national food safety regulator biogenic amine limit proposals. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Comparable-period anchoring to historical extraction facility throughput and clean-label reformulation adoption curves structures the projection framework across the analysis window. Segmentation modeling covers type tier, application end-use, physical form, and regional regulatory cluster dimensions. CAGRs derive from capacity expansion timelines, buyer concentration patterns, and compliance cost pass-through elasticity. Forecast inputs include enzymologist wage inflation trajectories and EFSA evaluation queue depths.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt Codex Alimentarius biogenic amine limit revisions or F-Gas Regulation enforcement acceleration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish Protein Concentrate Market
Seafood
Seafood Powders Market
Seafood
Dried Scallop Market
Seafood
Mackerel Market
Seafood
Organic Shrimp Market
Seafood
Fresh Fish Market
Seafood
Fish Protein Market
Seafood
South America Canned Seafood Market
Seafood
Frozen Seafood Market
Seafood
Latin America Salmon Market
Seafood
Sardine and Anchovy Umami Concentrate Systems Market
Seafood
Global Frozen and Canned Seafood Market
Seafood
Fish Oil Market
Seafood
Vietnam Pangasius (Basa) Market
Seafood
US Crustacean Market
Seafood
Global Smoked Fish Market