
 Tuna Market | 2026-2036
Tuna Market Size, Share, and Industry Trends Forecast 2026-2036
Tuna Market Intelligence
Food service procurement is consolidating around high-volume, traceable supply contracts as restaurants and institutional cafeterias prioritize provenance documentation. Thai Union Group leverages its integrated cold-chain infrastructure to secure long-term contracts with European retail banners. Dongwon Industries anchors its position through deepwater fleet ownership and Korean coastal processing dominance. Maruha Nichiro competes via precision freezing technology that extends sashimi-grade shelf life for Japanese domestic distribution.
Tuna comprises large pelagic fish from the Scombridae family, primarily Thunnus species, processed through blast freezing, canning in vegetable oil or brine, or dry-curing for shelf-stable protein delivery with omega-3 fatty acid content exceeding 20% in select cuts. Canned tuna sustains the largest revenue pool due to pantry-stocking behavior and extended shelf stability, though margin compression from commodity skipjack pricing limits upside. Frozen tuna occupies the fastest-growing structural position as sushi-grade logistics improve and direct-to-restaurant channels bypass traditional wholesale layers. Vacuum-sealed packaging within the packaging-type dimension commands premium placement in supermarket chilled sections, reflecting consumer preference for visible product integrity.
The EU IUU Regulation and CITES Appendix I listings for bluefin tuna shape fleet licensing, catch documentation, and market access for Atlantic and Mediterranean suppliers. NOAA Fisheries and the Western and Central Pacific Fisheries Commission enforce quota frameworks that constrain supply elasticity and elevate compliance costs for distant-water fleets. Stakeholders must monitor stock-assessment revisions and regional fisheries management organization negotiations to anticipate quota reallocation and species-specific trade restrictions.
Market Dynamics
Fleet operators face mounting pressure from the EU IUU Regulation's traceability mandates, which are consolidating purchasing power among buyers capable of documenting provenance from catch to retail shelf.
Growth Catalysts
- Ready-to-eat protein demand:Fitness-oriented households in Japan and South Korea are consolidating weekly purchasing around sashimi-grade and premium canned formats, compressing traditional wholesale layers.
- EU IUU Regulation compliance:Mandatory catch documentation schemes are filtering out non-compliant suppliers, creating market access premiums for verified fleet operators.
- Precision freezing technology:Advanced blast-freezing protocols are extending sashimi-grade shelf life, enabling direct-to-restaurant distribution that bypasses traditional auction intermediaries.
Market Restraints
- Skipjack commodity pricing volatility:Input cost swings for raw material compress margins across canned tuna production, limiting reinvestment capacity.
- Quota-constrained supply elasticity:Western and Central Pacific Fisheries Commission enforcement frameworks restrict catch volumes, elevating compliance costs for distant-water fleets.
- Bluefin CITES Appendix I listing:Trade restrictions on Atlantic and Mediterranean stocks create supply bottlenecks for premium sashimi channels.
Strategic Opportunities
- Vietnam processing expansion:Underdeveloped cold-chain infrastructure in central coastal provinces offers first-mover positioning for integrated operators.
- Vacuum-sealed retail formats:Supermarket chilled sections are allocating expanded shelf space to visible-integrity packaging, displacing traditional can formats.
- Direct-to-restaurant logistics:Bypassing wholesale auction layers through captive cold-chain networks captures margin previously distributed across intermediary handlers.
Industry Challenges
- Electronic monitoring system integration:Fleet operators must retrofit vessels with satellite-linked catch verification hardware, straining capital deployment timelines.
- Stock assessment revision cycles:Regional fisheries management organization quota negotiations create planning uncertainty across multi-year vessel deployment schedules.
- Cross-jurisdictional documentation harmonization:Reconciling EU, NOAA, and WCPFC reporting standards fragments compliance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tuna Market |
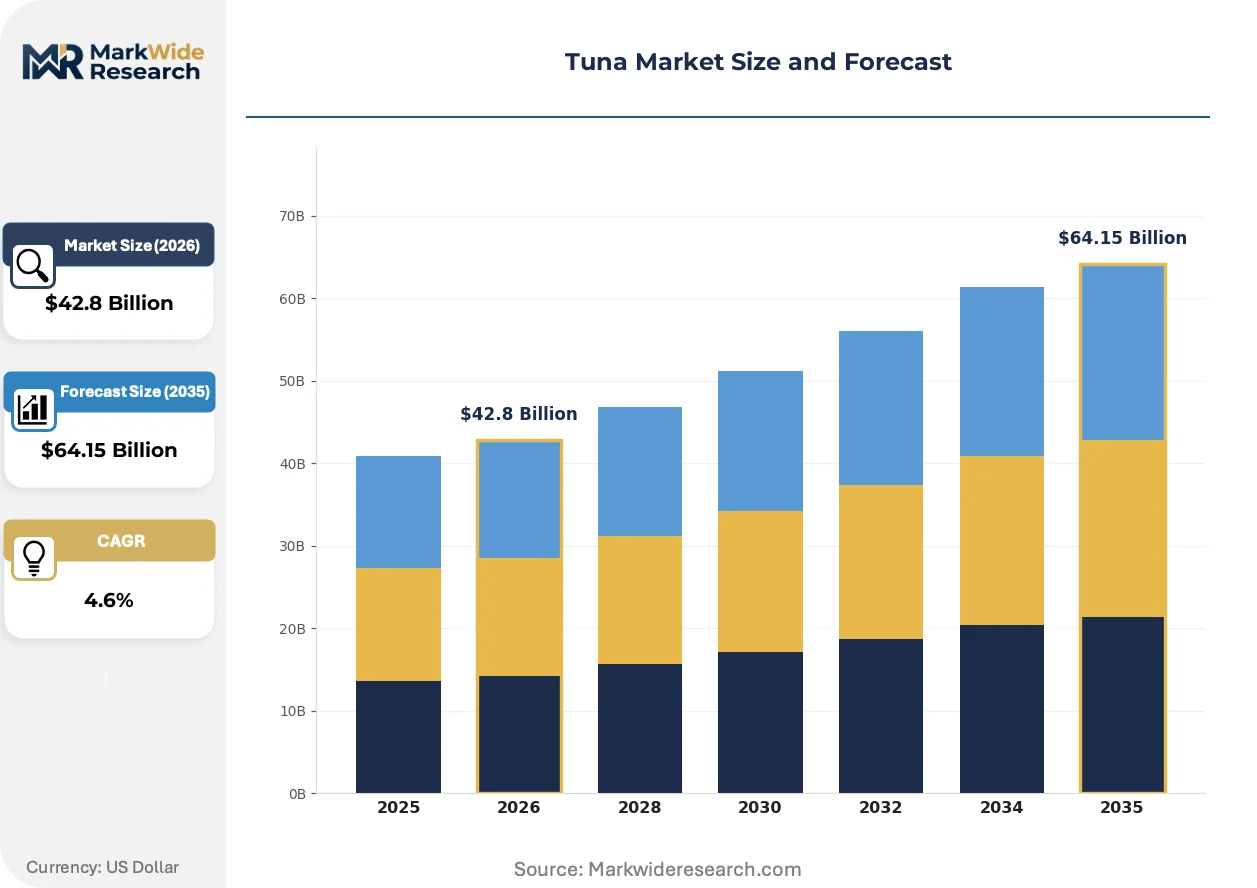
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $64.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Tuna, Canned Tuna, Frozen Tuna, Smoked Tuna Distribution Channel: Online Retailers, Supermarkets, Fish Markets, Restaurants End User: Households, Food Service Providers, Retail Chains, Exporters Packaging Type: Vacuum Sealed, Canned, Bulk Packaging, Modified Atmosphere |
| Companies Covered | Centerga, Mowgli Holdings, Thai Union Group, Grupo Calvo, Calvo Group, Dongwon Industries, Bolton Group, StarKist, Maruha Nichiro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tuna Market Strategic Shifts & Innovations
Processing technology and regulatory digitization are compressing traditional supply chain layers while reshaping how provenance is verified and monetized across retail and food service channels.
Blockchain-enabled traceability platforms are rewriting how catch documentation flows from vessel to point-of-sale. European retail banners and Japanese supermarket chains are mandating platform adoption for contract eligibility. This technology is compressing verification timelines from weeks to hours, eliminating documentation gaps that previously delayed customs clearance.
NOAA Fisheries electronic monitoring mandates are forcing fleet-wide hardware retrofits that transmit real-time catch data to regional enforcement databases. Vessel operators face capital outlays for camera systems and satellite uplinks. Atlantic and Pacific distant-water fleets are absorbing these costs to maintain market access, while smaller operators are exiting licensed fisheries.
Consumer preference for visible product integrity is rotating demand toward vacuum-sealed chilled formats and away from opaque can packaging. Japanese and South Korean retail banners are expanding dedicated chilled sections for sashimi-grade cuts. This channel shift is compressing shelf-stable volume growth while elevating per-unit margins for logistics-capable suppliers.
Tuna Market Segmentation
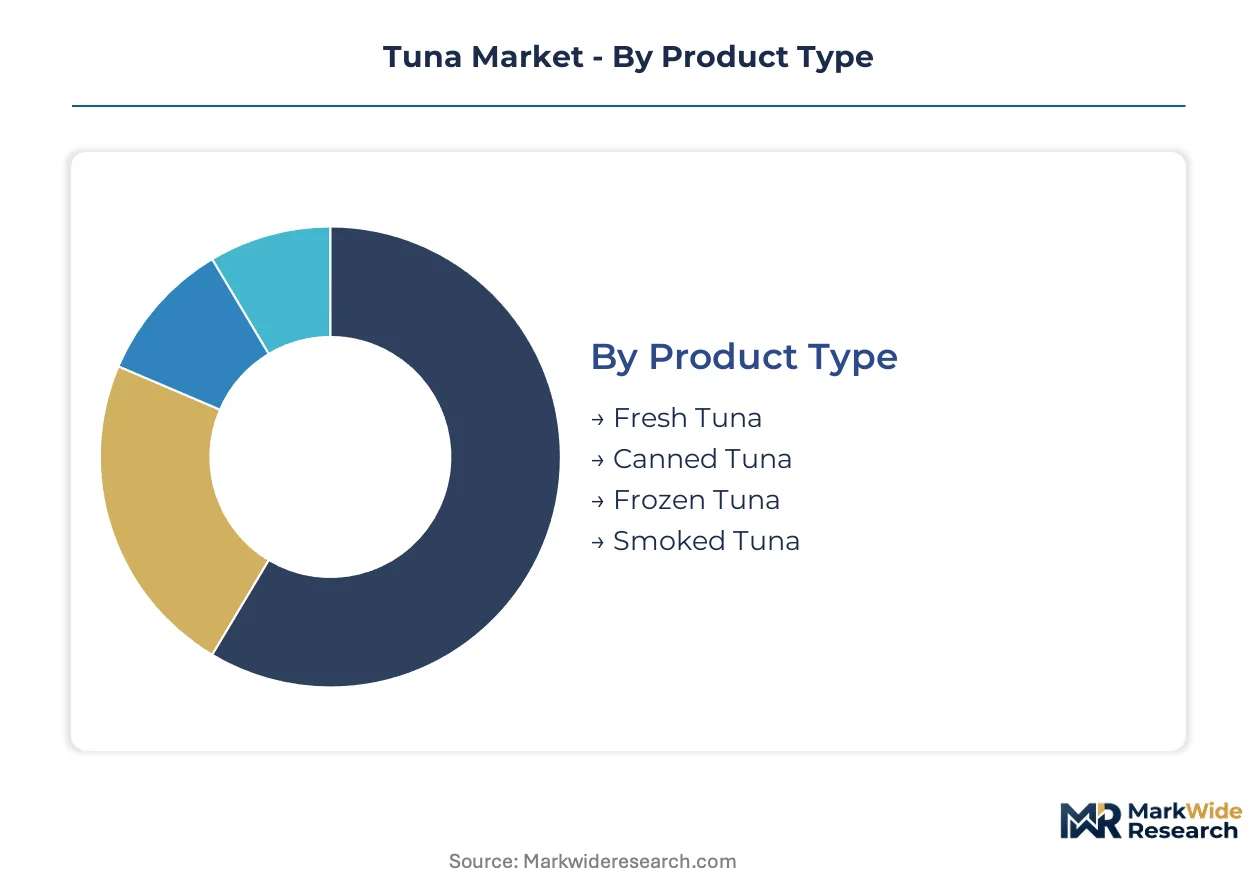
Tuna market segmentation reflects divergent capital requirements across processing technologies and distribution infrastructures. Processing format and cold-chain investment intensity determine competitive positioning and margin capture for fleet operators and downstream handlers.
Product Type:
Capital intensity peaks with blast-freezing infrastructure and canning line automation, while fresh distribution demands rapid-turn logistics networks rather than fixed asset deployment.
- Fresh Tuna:Sashimi-grade product requires temperature-controlled logistics from vessel to point-of-sale within 72 hours. Japanese auction houses and direct-to-restaurant channels in Tokyo and Osaka concentrate premium procurement, with EU IUU Regulation documentation adding compliance overhead for Atlantic suppliers.
- Frozen Tuna:Ultra-low temperature blast freezing at minus 60 degrees Celsius preserves cellular structure for extended sashimi-grade shelf life. South Korean and Vietnamese processors are expanding capacity to serve direct-to-restaurant channels that bypass traditional wholesale layers.
- Canned Tuna:Automated retort lines and vegetable oil filling systems represent moderate capital intensity with high throughput economics. Thai and Philippine canneries dominate volume production for European and North American retail banners.
- Smoked Tuna:Wood-fired kilns and brine curing vats require specialized equipment with limited scale economies. Nordic and Pacific Northwest artisanal processors serve premium deli and specialty retail channels.
Most installed capacity flows through Canned Tuna. Expansion is steepest in Frozen Tuna.
Distribution Channel:
Channel selection determines working capital cycles, with direct-to-restaurant formats compressing payment terms versus supermarket banner negotiations.
- Restaurants:Direct procurement contracts with sashimi-grade specifications command premium pricing and loyalty-based volume commitments. Japanese izakaya chains and Korean hwe establishments consolidate purchasing around verified provenance documentation.
- Supermarkets:Chilled section placement for vacuum-sealed formats requires slotting fees and promotional support investment. European retail banners are mandating blockchain traceability platform adoption for contract eligibility.
- Fish Markets:Auction-based price discovery in Tokyo's Toyosu Market and Busan's Jagalchi Market sets regional benchmark pricing for fresh product grades.
- Online Retailers:E-commerce penetration for frozen and shelf-stable formats is expanding in urban Japan and South Korea, with subscription models capturing fitness-oriented household purchasing consolidation.
Volume concentrates in Supermarkets. Margin expansion is most pronounced in Restaurants.
End User:
End-user segmentation maps to procurement sophistication, with food service operators demanding technical specification compliance and households prioritizing convenience and price accessibility.
- Food Service Providers:Institutional cafeterias and restaurant groups consolidate purchasing around long-term supply contracts with traceability mandates. Japanese corporate dining operators and European contract caterers lead specification stringency.
- Households:Pantry-stocking behavior sustains canned tuna volume, with fitness-oriented segments in Seoul and Tokyo rotating toward premium chilled formats. Weekly purchasing consolidation is compressing traditional wholesale intermediation.
- Retail Chains:Banner-specific private label development requires dedicated supply contracts with packaging customization and promotional calendar alignment.
- Exporters:Re-export handlers in Singapore and Rotterdam coordinate cross-regional arbitrage between Pacific catch zones and Mediterranean processing demand.
Procurement scale peaks with Food Service Providers. Specification complexity is expanding fastest among Retail Chains.
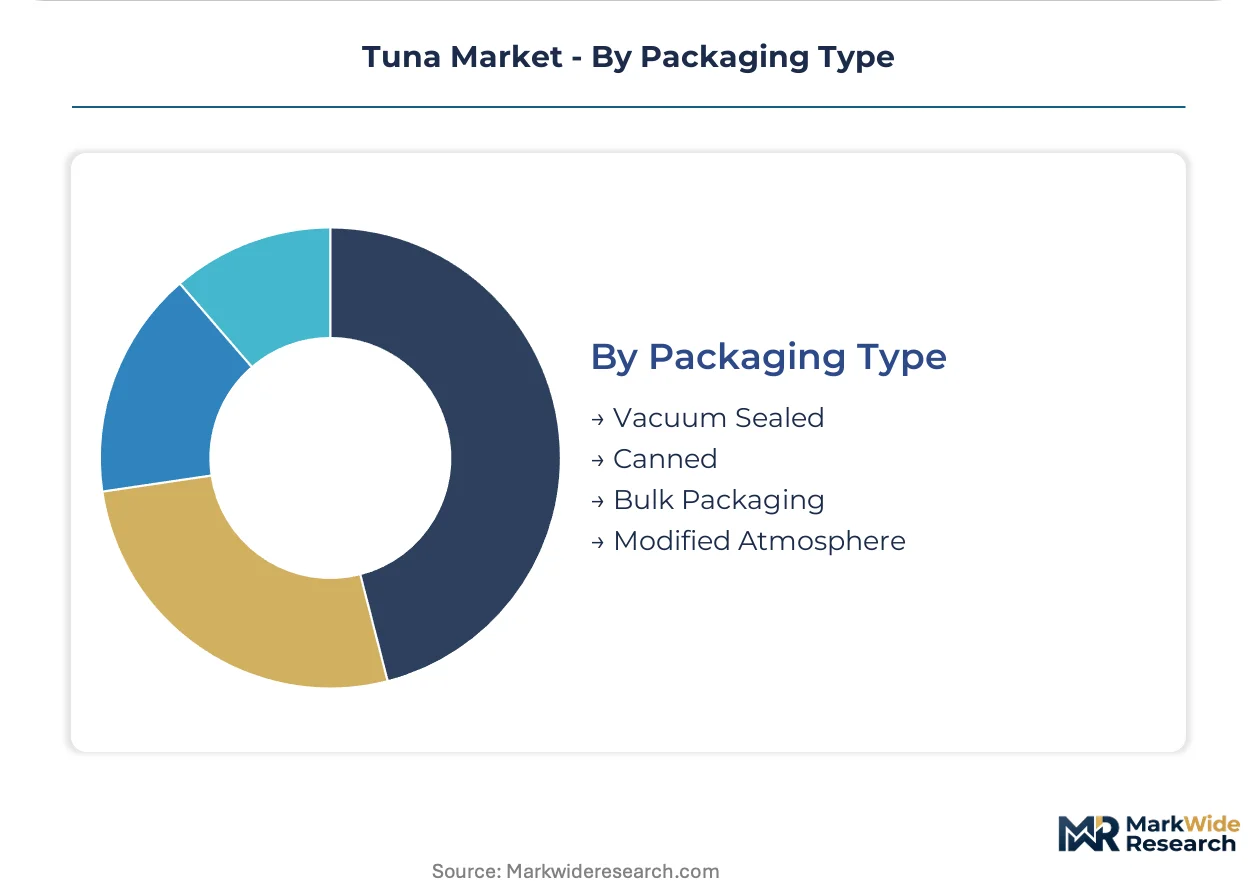
Packaging Type:
Packaging technology investment separates premium positioning from commodity competition, with visible-integrity formats commanding shelf space allocation and margin premiums.
- Vacuum Sealed:Multi-layer barrier films with oxygen scavenging technology extend chilled shelf life while enabling product visibility. Japanese and South Korean supermarket banners are expanding dedicated chilled section allocation for this format.
- Canned:Double-seamed steel containers with vegetable oil or brine filling provide extended ambient stability at moderate unit cost. Retort processing infrastructure requires significant thermal energy investment.
- Modified Atmosphere:Gas-flushed trays with high-barrier lidding films balance visibility with shelf life extension for fresh retail presentation. European chilled seafood counters are adopting this format for premium positioning.
- Bulk Packaging:Insulated containers with gel packs serve food service and processing facility procurement with minimal retail-facing branding investment.
Volume throughput concentrates in Canned. Premium shelf space capture is accelerating fastest in Vacuum Sealed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's Toyosu Market anchors global price discovery for sashimi-grade product, with procurement patterns radiating across Pacific Rim consumption clusters. Fleet operators and processors calibrate supply contracts against Japanese auction benchmarks while navigating divergent regulatory frameworks.
Japan
Izakaya chains and corporate dining operators in Tokyo and Osaka consolidate weekly purchasing around bluefin and bigeye grades. The Fisheries Agency enforces strict catch documentation under domestic implementation of international conservation measures. Kansai's Osaka port cluster processes frozen imports for direct-to-restaurant distribution bypassing wholesale layers.
United States
NOAA Fisheries electronic monitoring mandates reshape distant-water fleet compliance costs for Pacific and Atlantic operators. The Magnuson-Stevens Act conservation provisions constrain Atlantic bluefin quota allocations seasonally. San Diego and Honolulu harbor infrastructure supports re-export handlers coordinating Pacific catch with mainland processing demand.
Thailand
European retail banners source canned skipjack through Bangkok-based procurement offices demanding EU IUU Regulation traceability compliance. The Department of Fisheries implements vessel monitoring system mandates for distant-water fleet licensing. Samut Sakhon processing zones concentrate retort line capacity serving private-label contracts.
South Korea
Hwe establishments in Seoul and Busan rotate procurement toward frozen sashimi-grade product as domestic coastal catch declines. The Ministry of Oceans and Fisheries enforces strict import documentation aligning with regional fisheries management organization protocols. Busan's Jagalchi Market anchors price discovery for Russian and Pacific-origin frozen grades.
Spain
Mediterranean purse-seine operators face CITES Appendix I constraints on Atlantic bluefin landings for domestic cannery supply. The Ministry of Agriculture, Fisheries and Food implements EU catch certification schemes for export eligibility. Vigo and Marin processing clusters specialize in ventresca and premium canned formats for European retail placement.
Tuna Market Key Industry Players
Capacity expansion dominates the current landscape as operators retrofit vessels with electronic monitoring hardware and extend blast-freezing infrastructure. The vendor base organizes around three tiers: integrated fleet-and-processing conglomerates, specialized cannery operators, and regional cold-chain logistics providers. Consolidation pressures favor entities with captive supply chains and provenance documentation capabilities. Technology licensing agreements and backward integration into vessel ownership represent the two dominant competitive vectors reshaping procurement relationships.
Among Asia-Pacific integrated operators, Thai Union Group and Maruha Nichiro exemplify the fleet-owning conglomerate archetype, while Dongwon Industries anchors the Korean coastal processing tier. These entities occupy positions defined by cold-chain control and direct-to-restaurant channel access rather than commodity volume throughput. European cannery specialists including Grupo Calvo and Bolton Group represent the brand-centric tier competing through private-label development and retail banner relationships. StarKist occupies a distinct position within the North American shelf-stable segment.
| Leading Market Players |
|---|
| Centerga |
| Mowgli Holdings |
| Thai Union Group |
| Grupo Calvo |
| Calvo Group |
| Dongwon Industries |
| Bolton Group |
| StarKist |
| Maruha Nichiro |
| Others |
Cost & Logistics Intelligence
Deepwater vessel crew concentrations in the Philippines and Indonesia compress labor-cost differentials between premium sashimi-grade and commodity canned tiers, widening pricing spreads as EU IUU Regulation compliance overhead elevates documentation costs for Atlantic suppliers.
Pricing Analysis
Input-cost pass-through from skipjack commodity volatility drives contract-based long-term offtake structures for canned production, while spot-market dynamics govern fresh sashimi-grade transactions at Japanese auction houses. Price differentiation hinges on catch certification grade under CITES Appendix I and EU catch documentation schemes, alongside cold-chain integrity verification. Pricing pressure intensifies in commodity skipjack tiers as Thai and Philippine canneries absorb margin compression from raw material swings. Food service procurement groups exhibit lowest price sensitivity due to provenance mandates, while mass-market retail banners negotiate aggressively on volume commitments.
Supply Chain Analysis
Regional distribution centers in Bangkok, Busan, and Rotterdam coordinate hub-and-spoke patterns that aggregate Pacific catch for European and North American downstream channels. Supply concentrates in Thailand, the Philippines, and Vietnam for processing infrastructure, with Japan and South Korea anchoring premium consumption endpoints. Raw material dependencies center on skipjack, yellowfin, and bigeye tuna stocks governed by WCPFC and ICCAT quota frameworks. Single-source vulnerability from distant-water fleet licensing restrictions in the Western and Central Pacific elevates supply chain risk. Distribution runs through integrated cold-chain networks controlled by fleet-owning conglomerates that bypass traditional wholesale auction layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Vietnam's underdeveloped central coastal provinces and Thailand's saturated processing corridors rewards first-movers capturing labor-cost advantages before cold-chain infrastructure maturation eliminates spreads.
For Market Incumbents: Deepen backward integration into vessel ownership to secure captive supply against quota reallocation uncertainty from WCPFC stock assessment revisions. Expand blast-freezing capacity in Vietnamese coastal zones to capture margin from direct-to-restaurant channels. Electronic monitoring system mandates from NOAA Fisheries and the EU strain smaller competitors' capital deployment timelines, creating consolidation opportunities for fleet-owning conglomerates with compliant infrastructure already deployed. For New Entrants and Emerging Players: Fitness-oriented household segments in Seoul and Tokyo present underserved buyer archetypes seeking subscription-model premium chilled formats with visible product integrity packaging. Bypass established wholesale auction layers through captive cold-chain partnerships with Busan and Jagalchi Market handlers. Target vacuum-sealed retail placement in South Korean supermarket banners expanding dedicated chilled sections, leveraging blockchain traceability platform adoption as contract eligibility threshold. For Investors and Strategic Acquirers: Integrated food conglomerates with existing protein portfolios are the most active acquirer in this space, seeking provenance-documentation capabilities to satisfy EU retail banner mandates. Acquisition target archetypes include regional cold-chain logistics providers with WCPFC-compliant vessel relationships and Vietnamese processors with underutilized blast-freezing capacity. Signal to watch: ICCAT quota reallocation announcements that would elevate scarcity premiums for Atlantic bluefin-dependent operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vessel Ownership | Captive supply secures quota access against WCPFC reallocation uncertainty. |
| Blast-Freezing Infrastructure Expansion | Minus 60-degree Celsius protocols extend sashimi-grade shelf life for restaurant channels. |
| Blockchain Traceability Platform Adoption | European retail banners mandate platform compliance for contract eligibility. |
| Vacuum-Sealed Packaging Line Investment | Multi-layer barrier films capture premium shelf space in Korean chilled sections. |
| Direct-to-Restaurant Logistics Network Buildout | Bypassing Toyosu auction intermediaries captures margin across Tokyo izakaya chains. |
Research Approach
Coverage spans East Asia, Southeast Asia, and Europe, with primary inputs from each region combining executive interviews with fleet operators, processing facility managers, and retail category buyers alongside secondary validation. Secondary sources include WCPFC and ICCAT quota documentation, EU IUU Regulation compliance filings, Japanese Fisheries Agency catch statistics, and Thai Department of Fisheries licensing records. Bottom-up vessel capacity and processing throughput estimates triangulate against top-down consumption surveys and import-export customs data.
Rate-of-change decomposition separates volume growth from price-level effects across the projection horizon, with segmentation dimensions encompassing product type, distribution channel, end user, and packaging format. CAGRs derive from trend-line extrapolation of historical quota allocations, stock assessment trajectories, and regulatory enforcement intensity. Industry-specific forecast inputs include electronic monitoring system adoption curves and vacuum-sealed packaging penetration rates in Japanese and South Korean retail banners.
Inputs from WCPFC stock assessment cycles and ICCAT quota negotiation timelines were available through the study window; gaps in real-time catch verification data from non-compliant fleet operators introduce uncertainty bands around Pacific supply elasticity assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and conservation measure adherence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish Protein Hydrolysate Market
Seafood
Halibut Market
Seafood
Vietnam Pangasius (Basa) Market
Seafood
Europe Shrimp Market
Seafood
Carp Market
Seafood
Alaskan Salmon Market
Seafood
North America Frozen and Canned Seafood Market
Seafood
Food Clamshells Market
Seafood
Edible Seaweed Market
Seafood
United States Salmon Market
Seafood
Fish Protein Market
Seafood
United Arab Emirates Seafood Market
Seafood
Tinned Fish Market
Seafood
Seafood Extracts Market
Seafood
Molluscs Market
Seafood
Crayfish Market