
 Oyster Market | 2026-2036
Oyster Market Size, Share, and Industry Trends Forecast 2026-2036
Oyster Market Intelligence
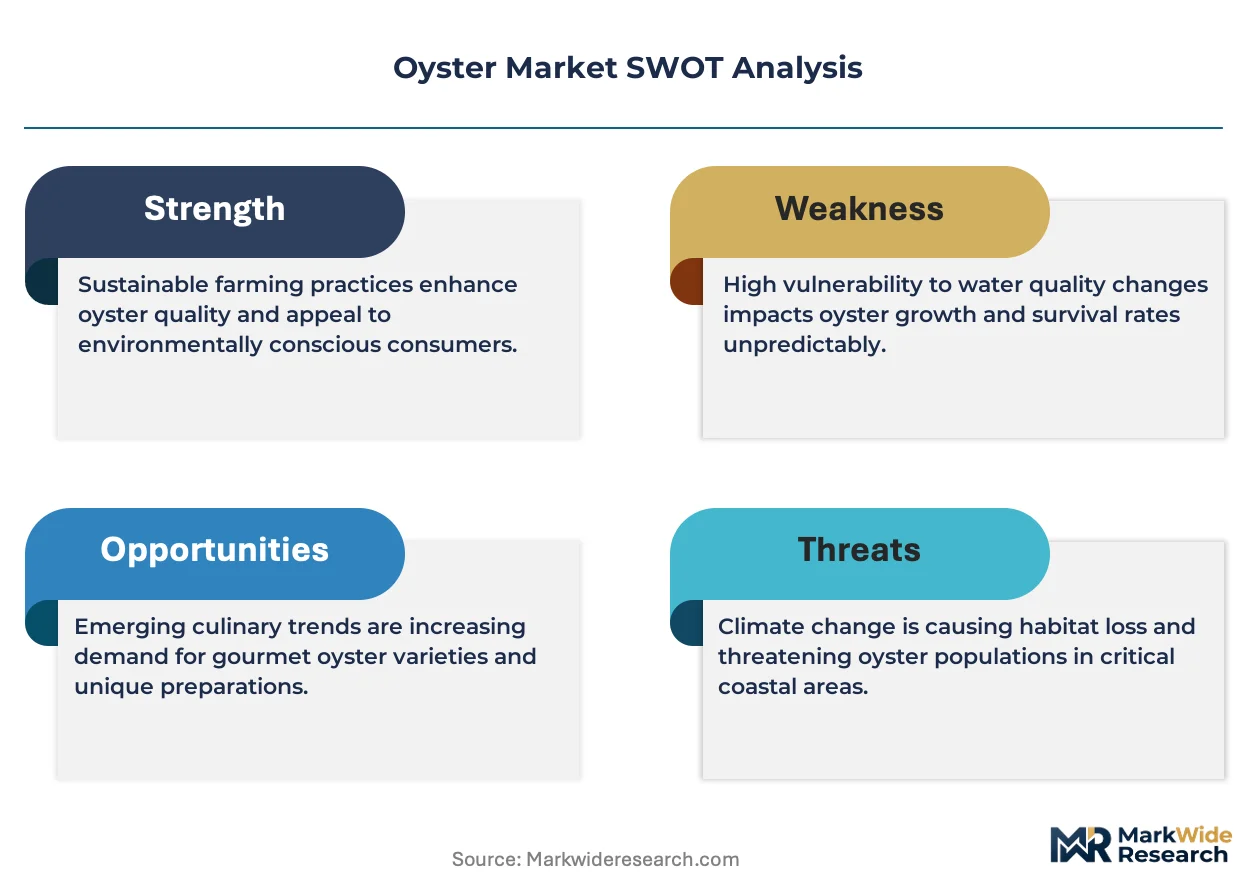
Pre-portioned half-shell retail packs is decoupling bulk wholesale purchasing from individual consumer decision-making. France Naissain leverages its hatchery-to-table integration to dominate European seed supply. Hog Island Oyster Company anchors its position through direct-to-restaurant distribution along the US West Coast. Fujian Jiatian Agricultural Development Co. competes on frozen oyster export volume into Southeast Asian markets.
An oyster is a bivalve mollusk of the family Ostreidae, harvested wild or cultivated via rack-and-bag, longline, or bottom-culture systems, with meat moisture content typically ranging from 75% to 85% and shell calcium carbonate exceeding 90% by dry weight; it serves as a protein source, ecosystem engineer in coastal restoration, and premium culinary ingredient. Live oysters command the highest margin pool in product type segmentation due to perishability premiums and traceability requirements, while canned oysters sustain volume leadership through shelf-stable convenience for retail channel distribution. Online sales within distribution channel segmentation is expanding fastest as direct-ship cold-chain logistics mature.
EFSA and REACH in Europe govern food safety and chemical residue limits for imported shellfish, while China's SAMR enforces GB standards for aquatic product labeling and cold-chain documentation. These frameworks shape demand by elevating compliance costs for smaller harvesters and favoring vertically integrated operators with in-house laboratory certification. Stakeholders must monitor evolving traceability mandates and cold-chain infrastructure investments as regulatory stringency diverges across major producing zones.
Market Dynamics
Live oyster perishability premiums are compressing traditional wholesale margins as direct-to-restaurant cold-chain logistics mature, forcing processors to choose between traceability infrastructure investment or exit from premium live segments.
Growth Catalysts
- EFSA traceability mandates:European Union food safety frameworks now require end-to-end documentation for shellfish imports, creating compliance barriers that favor established vertically integrated operators with captive laboratory certification.
- Coastal restoration demand:Oyster reef deployment for shoreline stabilization and nitrogen sequestration is generating public procurement contracts for seed supply in the United States and France.
- Half-shell retail formats:Pre-portioned live packs are decoupling bulk purchasing from individual consumer decision-making, expanding addressable demand through supermarket and e-commerce channels.
Market Restraints
- Seed supply concentration:European hatchery capacity clusters in France and Ireland, creating geographic chokepoints that amplify climate-related mortality risks across continental production.
- Calcium carbonate input volatility:Shell substrate costs for bottom-culture systems fluctuate with industrial lime demand, compressing margins for rack-and-bag operators dependent on purchased cultch.
- Wild harvest substitution:Canned Pacific oyster imports from China undercut fresh live pricing in Southeast Asian markets, limiting premium segment expansion.
Strategic Opportunities
- Direct-ship e-commerce channels:Cold-chain logistics maturation enables live oyster delivery to inland consumers in Germany and Poland, bypassing traditional wholesale layers.
- Carbon credit stacking:Oyster reef restoration projects qualify for blue carbon offsets under emerging voluntary standards, creating ancillary revenue streams for coastal leaseholders.
- REACH-compliant packaging innovation:Biodegradable insulated shippers meeting EU chemical safety frameworks open premium positioning for export-oriented processors.
Industry Challenges
- Hatchery technician scarcity:Broodstock management and algal culture expertise concentrates in aging workforces along France's Atlantic coast, constraining expansion timelines for new entrants.
- Depuration certification delays:EU-approved purification facility accreditation timelines stretch 18-24 months, blocking market access for harvesters lacking existing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oyster Market |
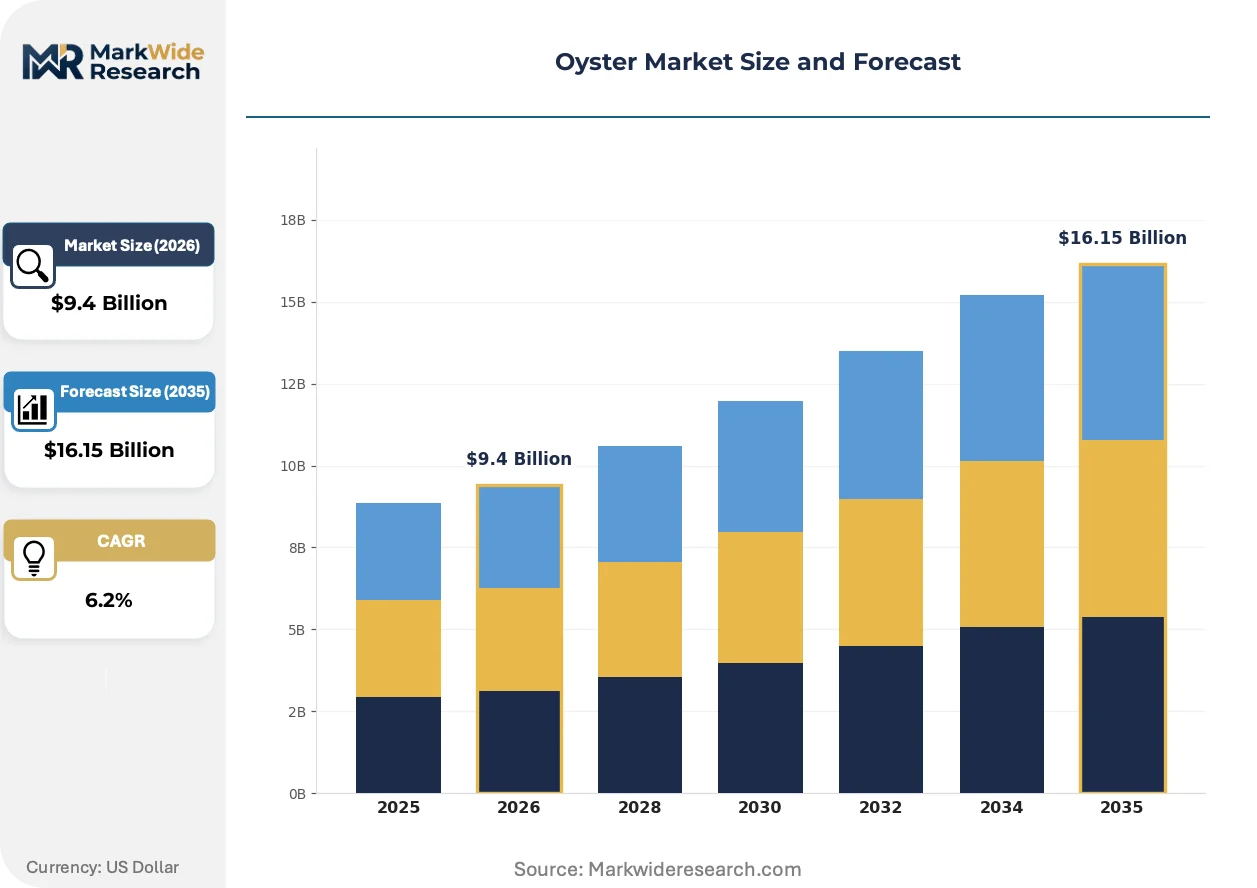
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.15 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Oysters, Canned Oysters, Frozen Oysters, Smoked Oysters Distribution Channel: Retail Stores, Restaurants, Seafood Markets, Online Sales End User: Consumers, Food Service Providers, Exporters, Manufacturers Packaging Type: Bulk Packaging, Retail Packaging, Eco-friendly Packaging, Styrofoam Containers |
| Companies Covered | France Naissain, Fujian Jiatian Agricultural Development Co., Chatham Shellfish Company, Huitres Favier Earl, Hoopers Island Oyster Company, JM Clayton Seafood Company, Hog Island Oyster Company, Huîtres Hélie, Weifang-based Green Life Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oyster Market Strategic Shifts & Innovations
Automation of grading and packing operations is compressing labor-dependent processing economics, while regulatory digitization and channel disintermediation reshape competitive positioning across live and value-added segments.
Computer vision systems with spectral imaging are automating live oyster grading by meat fill ratio and shell integrity. Mid-scale processors in Normandy and Washington State are adopting these units to reduce sorting labor by two-thirds. The technology is automating quality consistency that previously required experienced manual graders, enabling throughput scaling without proportional headcount expansion.
REACH framework amendments are tightening chemical residue documentation for imported shellfish entering European processing facilities. Harvesters in third-party countries must now submit batch-level laboratory certification through centralized ECHA portals. Vietnamese and Korean exporters are responding by establishing EU-accredited testing partnerships to maintain market access.
Restaurant procurement is consolidating around direct relationships with branded growers, displacing traditional seafood distributors in premium live segments. Chefs in Copenhagen and San Francisco now specify hatchery-origin traceability as a contract condition. This pattern is most visible in Michelin-tier dining where provenance documentation commands menu price premiums.
Oyster Market Segmentation
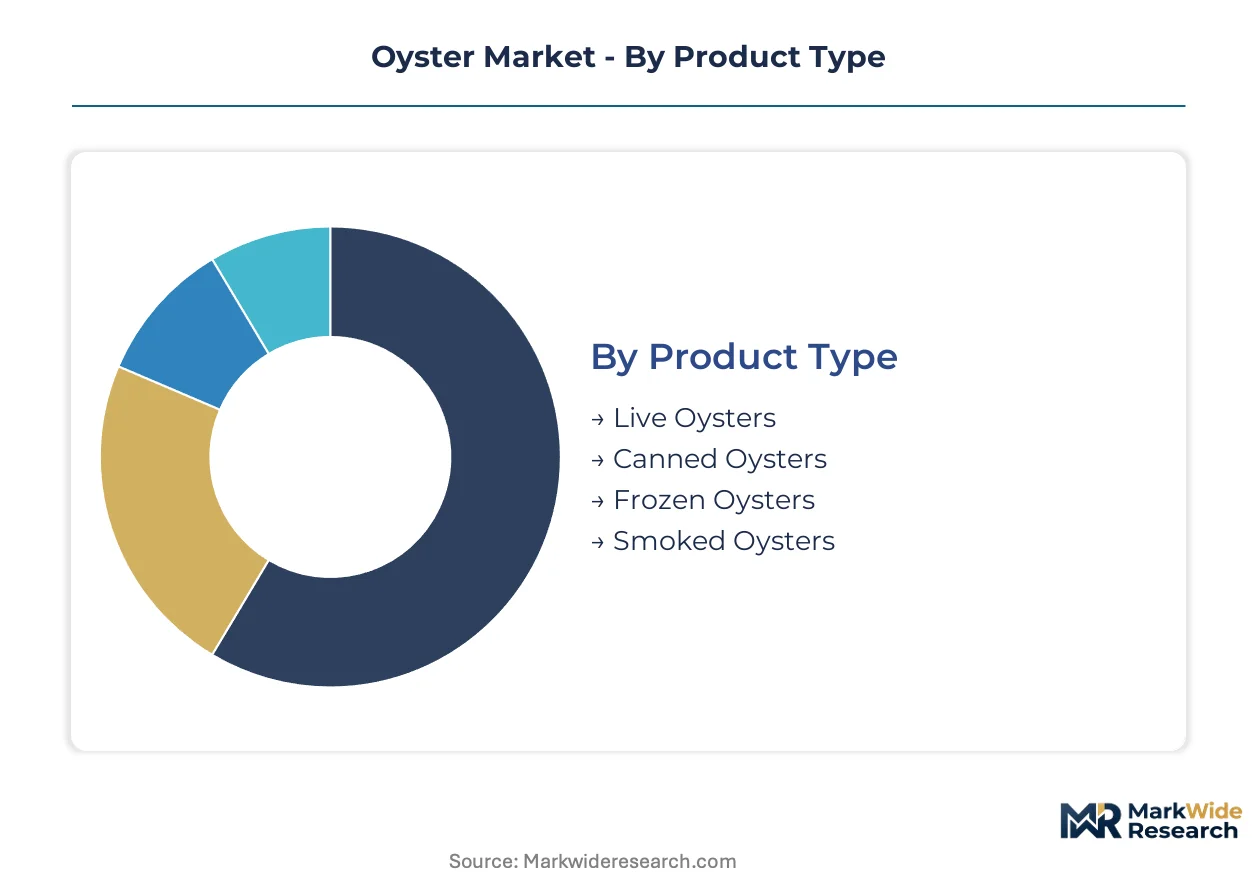
Oyster segmentation reflects divergent buyer priorities across freshness tolerance, traceability requirements, and channel economics. Each category maps distinct value pools to operational capabilities required for compliance and margin capture.
Product Type:
Buyers in this category separate by perishability tolerance and price sensitivity toward live delivery premiums versus shelf-stable convenience.
- Live Oysters:These specimens maintain 75-85% meat moisture content and command traceability premiums due to EFSA documentation mandates. Demand concentrates in French Michelin-tier restaurants where hatchery-origin certification justifies menu pricing. Cold-chain logistics maturity is compressing wholesale margins and accelerating direct-to-restaurant procurement.
- Canned Oysters:Heat-sterilized meat in brine or oil delivers shelf-stable protein with calcium carbonate content exceeding 90% by dry shell weight. Volume leadership persists in Southeast Asian retail channels where Chinese Pacific oyster imports undercut fresh live alternatives. Convenience positioning sustains penetration in inland markets lacking cold-chain infrastructure.
- Frozen Oysters:Individual quick-freezing preserves texture for food service manufacturing applications. Fujian Jiatian Agricultural Development Co. dominates export volume into Southeast Asian processor networks.
- Smoked Oysters:Wood-smoked variants target premium snack and appetizer segments with extended ambient stability. Specialty retailers in Germany and Poland stock these for inland consumers seeking oyster experience without live handling complexity.
Live oysters lead volumes today; online sales of pre-portioned half-shell packs are gaining share fastest.
Distribution Channel:
Channel selection in this category tracks buyer proximity to harvesting regions and willingness to absorb cold-chain cost premiums.
- Retail Stores:Supermarket distribution of pre-portioned half-shell packs is decoupling bulk wholesale purchasing from individual consumer decision-making. France's Marennes-Oléron cluster supplies premium live inventory to Carrefour and E.Leclerc networks. REACH-compliant biodegradable insulated shippers are opening premium positioning for export-oriented processors.
- Restaurants:Direct relationships with branded growers now displace traditional seafood distributors in premium live segments. Copenhagen and San Francisco chefs specify hatchery-origin traceability as contract conditions. Hog Island Oyster Company anchors West Coast supply through dedicated restaurant logistics.
- Seafood Markets:Traditional wet markets persist in Vietnam and Korea where EU-accredited testing partnerships maintain export pathway access. Depuration certification delays of 18-24 months block new entrant access to this channel.
- Online Sales:Direct-ship cold-chain logistics maturation enables live delivery to inland German and Polish consumers. France Naissain leverages hatchery-to-table integration for seed supply transparency in e-commerce positioning.
Restaurants command margin premiums today; online sales are expanding most quickly as logistics infrastructure matures.
End User:
End-user differentiation in this category centers on volume scale, processing sophistication, and export certification requirements.
- Food Service Providers:Restaurant procurement consolidation around direct grower relationships is reshaping distributor economics. Coastal restoration demand for shoreline stabilization and nitrogen sequestration generates public procurement contracts for seed supply in the United States and France.
- Exporters:Batch-level laboratory certification through centralized ECHA portals is now mandatory for third-country harvesters. Vietnamese and Korean operators are establishing EU-accredited testing partnerships to maintain market access.
- Consumers:Individual buyers purchasing through retail and online channels drive pre-portioned format innovation. Half-shell retail packs reduce handling complexity for home preparation.
- Manufacturers:Processors of value-added products require consistent frozen supply for battering and breading operations. Frozen oyster specifications prioritize meat yield over shell integrity.
Food service providers dominate value capture today; exporters face the steepest compliance cost escalation.
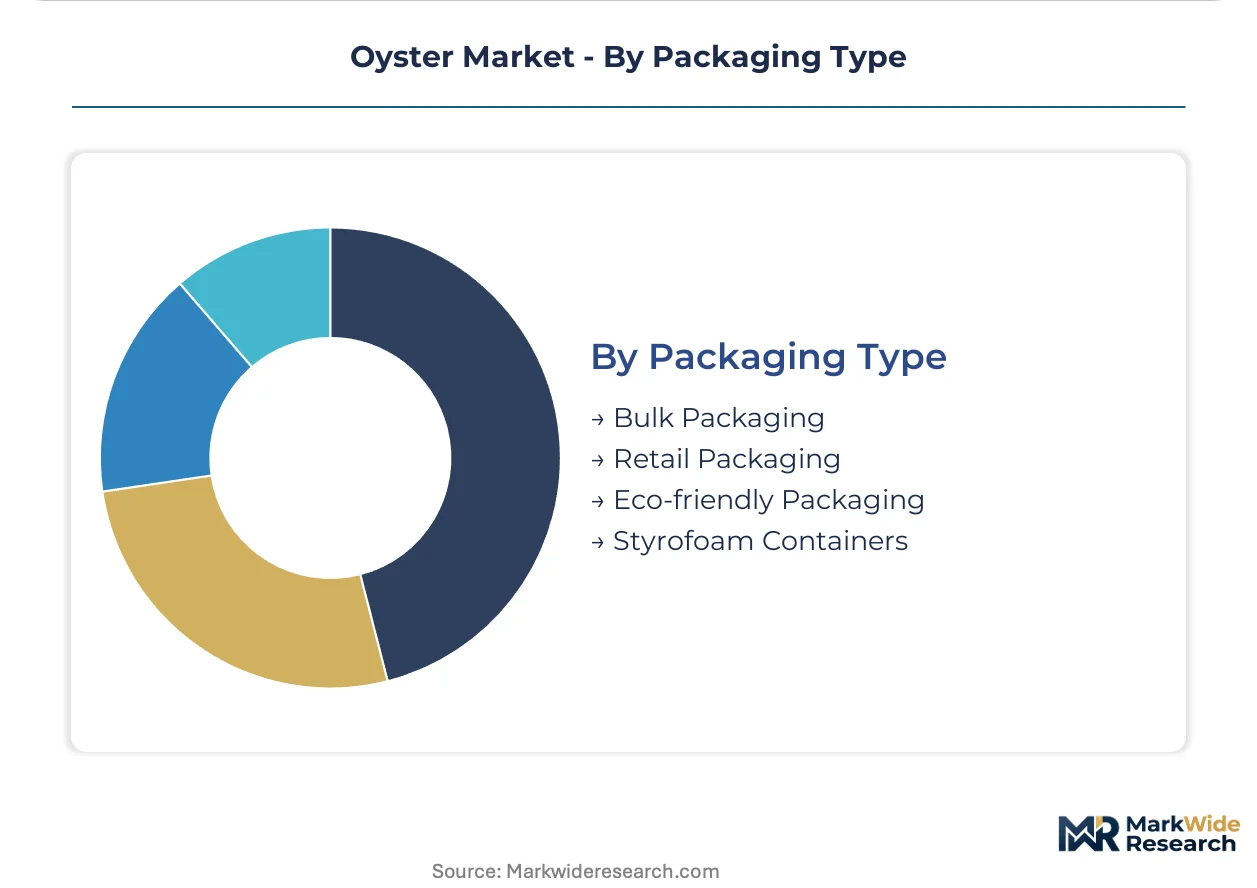
Packaging Type:
Packaging selection in this category balances insulation performance, regulatory compliance, and waste reduction mandates.
- Eco-friendly Packaging:Biodegradable insulated shippers meeting REACH chemical safety frameworks open premium export positioning. EU Green Deal packaging waste directives are accelerating material transition timelines.
- Retail Packaging:Pre-portioned half-shell configurations with individual labeling enable traceability documentation for supermarket distribution. France Naissain's hatchery-to-table integration supports retail pack provenance claims.
- Bulk Packaging:Live oyster shipments in standard containers serve restaurant and seafood market wholesale layers. Calcium carbonate substrate costs for bottom-culture systems fluctuate with industrial lime demand.
- Styrofoam Containers:Expanded polystyrene persists in cost-sensitive export corridors despite regulatory pressure. France and Ireland's hatchery capacity concentration creates geographic chokepoints amplifying climate-related mortality risks across continental production.
Bulk packaging leads shipment volumes today; eco-friendly alternatives are climbing the fastest on regulatory mandate acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oyster aquaculture originated in ancient Rome and matured into industrial scale along France's Atlantic coastline during the nineteenth century. Modern production geography traces this lineage through specialized hatchery clusters and processing infrastructure that persist in historically established zones.
France
Marennes-Oléron and Normandy processing clusters supply premium live oysters across continental Europe. EFSA traceability mandates require end-to-end documentation for shellfish imports, elevating compliance costs that favor established vertically integrated operators. France Naissain leverages hatchery-to-table integration to dominate European seed supply from its Atlantic coast facilities.
United States
Coastal restoration demand generates public procurement contracts for seed supply in Chesapeake Bay and Gulf Coast regions. FDA and state-level shellfish sanitation programs govern depuration certification timelines that stretch 18-24 months for new market entrants. Hog Island Oyster Company anchors West Coast supply through direct-to-restaurant distribution along California and Oregon.
China
Frozen oyster export volume into Southeast Asian markets concentrates in Fujian province processing facilities. SAMR enforces GB standards for aquatic product labeling and cold-chain documentation that shape export compliance requirements. Weifang-based Green Life Foods competes on frozen oyster volume from Shandong Peninsula production bases.
Ireland
Seed supply concentration creates geographic chokepoints that amplify climate-related mortality risks across continental European production. National shellfish monitoring programs align with EU hygiene regulations for classified harvesting areas. Galway Bay and Donegal Bay clusters specialize in Pacific oyster spat supply to French and British growers.
Vietnam
EU-accredited testing partnerships maintain export pathway access for processed oyster products entering European processing facilities. Batch-level laboratory certification through centralized ECHA portals is now mandatory for third-country harvesters. Mekong Delta processing zones are establishing laboratory partnerships to satisfy REACH framework chemical residue documentation.
Oyster Market Key Industry Players
The competitive structure tilts toward vertically integrated hatchery-to-table specialists with captive laboratory certification. Mid-scale processors face compression between traceability infrastructure investment requirements and wholesale margin erosion from direct-ship logistics maturation. Two strategic archetypes dominate: hatchery-integrated seed suppliers controlling upstream genetics, and branded growers capturing restaurant procurement through provenance documentation. Competitive moves concentrate on cold-chain infrastructure expansion and EU-accredited testing partnership establishment.
Among French hatchery-integrated operators, France Naissain exemplifies the seed supply control archetype through Atlantic coast broodstock management. Fujian Jiatian Agricultural Development Co. occupies a position within the frozen export volume tier serving Southeast Asian processor networks. Hog Island Oyster Company represents the direct-to-restaurant branded grower model with West Coast logistics infrastructure. These three anchors illustrate the geographic and operational specialization that fragments competitive positioning across live, frozen, and seed supply segments.
| Leading Market Players |
|---|
| France Naissain |
| Fujian Jiatian Agricultural Development Co. |
| Chatham Shellfish Company |
| Huitres Favier Earl |
| Hoopers Island Oyster Company |
| JM Clayton Seafood Company |
| Hog Island Oyster Company |
| Huîtres Hélie |
| Weifang-based Green Life Foods |
| Others |
Cost & Logistics Intelligence
Restaurant procurement consolidation around direct grower relationships anchors pricing power in live oyster segments, compressing wholesale intermediaries into transactional commodity roles. Three-tier pricing structure across premium live, standard frozen, and economy canned levels stratifies margins by perishability tolerance and traceability documentation burden.
Pricing Analysis
Premium-mid-economy pricing differentiation separates hatchery-certified live specimens from mass-market frozen exports and shelf-stable canned alternatives. Price differentiation hinges on EFSA traceability documentation and cold-chain delivery guarantees versus shelf-stable convenience. Pricing pressure stems from Chinese Pacific oyster imports undercutting fresh live alternatives in Southeast Asian retail channels. Food service providers exhibit lowest price sensitivity due to provenance documentation requirements, while inland consumers through online channels show highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from EU-registered depuration facilities mandate multi-supplier qualification for restaurant procurement contracts. Supply concentrates in France, Ireland, and China, with hatchery broodstock and algal culture inputs drawing from specialized Atlantic coast facilities. Single-source vulnerability runs through French seed supply concentration amplifying climate-related mortality risks. Distribution runs through direct-to-restaurant cold-chain logistics bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in hatchery-to-table integration and carbon credit stacking for coastal leaseholders, as automation compresses labor-dependent processing economics.
For Market Incumbents: Lock in hatchery-origin traceability certification to defend against Vietnamese and Korean exporters establishing EU-accredited testing partnerships. Prioritize captive laboratory investment over wholesale margin capture, as direct-ship logistics maturity erodes traditional distributor economics. Secure coastal restoration procurement contracts for seed supply in Chesapeake Bay and Gulf Coast regions. For New Entrants and Emerging Players: Enter via inland European e-commerce corridors in Germany and Poland where cold-chain infrastructure gaps persist. Target smoked oyster specialty retail positioning for consumers seeking oyster experience without live handling complexity. Establish biodegradable insulated shipper partnerships meeting REACH chemical safety frameworks as go-to-market differentiator. For Investors and Strategic Acquirers: Food service distributors with captive hatchery assets are the most active acquirer in this space, consolidating backward into seed supply control. Long-term viability favors operators with demonstrated EFSA compliance infrastructure and coastal leasehold carbon credit eligibility. Monitor EU Green Deal packaging waste directive acceleration as inflection indicator for material transition investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Hatchery-to-Table Integration | France Naissain's broodstock control eliminates seed supply chokepoint vulnerability for integrated operators. |
| EU-Accredited Testing Partnership | Vietnamese processors establishing ECHA portal certification maintain market access against compliance barriers. |
| Carbon Credit Stacking | Oyster reef restoration projects qualify for blue carbon offsets under emerging voluntary standards. |
| Direct-Ship E-Commerce Launch | Cold-chain logistics maturation enables live delivery penetration into inland German and Polish markets. |
| Biodegradable Packaging Transition | REACH-compliant insulated shippers open premium export positioning under EU Green Deal directives. |
Research Approach
Bottom-up food service procurement modeling reconciled against top-down hatchery capacity tracking forms the analytical core. Primary interviews with oyster farm operators, restaurant procurement managers, seafood distributors, and regulatory compliance officers combined with secondary validation from EFSA shellfish safety directives, SAMR aquatic product standards, and customs trade databases. Triangulation across bottom-up volume builds and top-down production capacity assessments ensures consistency.
Historical trendline analysis of live versus processed oyster trade flows informs projection frameworks across product type, distribution channel, and end-user segmentation dimensions. CAGRs derive from regression analysis of perishability premium compression and cold-chain logistics penetration rates. Hatchery mortality data and depuration facility accreditation timelines feed industry-specific forecast inputs.
Inputs from EU shellfish monitoring programs and FDA state-level sanitation databases were available through the study window; gaps in private hatchery broodstock genetics data introduce uncertainty bands. Forecasts reflect assumptions around EFSA traceability mandate enforcement consistency and REACH packaging amendment implementation timelines. Deviation in climate-related hatchery mortality events would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Dry-Packaged Scallops Market
Seafood
Fish Protein Market
Seafood
Europe Salmon Market
Seafood
Tinned Fish Market
Seafood
Seafood Takeout Market
Seafood
Frozen Seafood Market
Seafood
Japan Lobster Market
Seafood
Mussels Market
Seafood
Salmon Market
Seafood
Tuna Fish Market
Seafood
Caviar Market
Seafood
Fish Meal Market
Seafood
Seafood Processing Market
Seafood
Europe Lobster Market
Seafood
United States Lobster Market
Seafood
North America Tuna Market