
 Middle East and Africa Canned Seafood Market | 2026-2036
Middle East and Africa Canned Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Canned Seafood Market Foresight
Fishery processing labor shortages across North African coastal zones is redrawing competitive positioning among manufacturers with established African operations. Thai Union Group PCL anchors its regional supply network through integrated tuna sourcing and Moroccan canning partnerships. Oceana Group Limited leverages its Namibian hake access and Walvis Bay processing assets to sustain volume leadership in Southern African retail channels. Bolton Group B.V. competes through diversified species portfolios spanning sardine and mackerel lines tailored to Middle Eastern consumer preferences.
Canned seafood comprises thermally stabilized fish products sealed in hermetic containers after pre-cooking, typically achieving commercial sterility through retort processing at temperatures exceeding 116 degrees Celsius for shelf lives extending 24 to 60 months. The category serves retail, food service, and industrial buyers requiring protein stability without refrigerated distribution infrastructure. Tuna dominates value contribution across Middle East and Africa channels due to established consumer recognition and premium positioning in Gulf retail environments. Flexible pouches represent the fastest-expanding packaging format as younger consumers in South Africa and Kenya prioritize portability and reduced metal waste. Supermarkets and hypermarkets control the primary distribution margin pool, though online channels are gaining traction in UAE and Saudi Arabian urban centers.
South Africa's Department of Health enforces strict labeling and additive standards for canned fish imports, while Saudi Arabia's SFDA mandates halal certification and shelf-life documentation for all processed seafood entering the Kingdom. These frameworks elevate compliance costs for smaller exporters but create structured market access for certified producers with established regulatory affairs capabilities. Stakeholders must monitor evolving food safety harmonization efforts between Gulf standards bodies and African trade blocs to anticipate certificate reciprocity shifts that could reroute competitive supply flows.
Market Dynamics
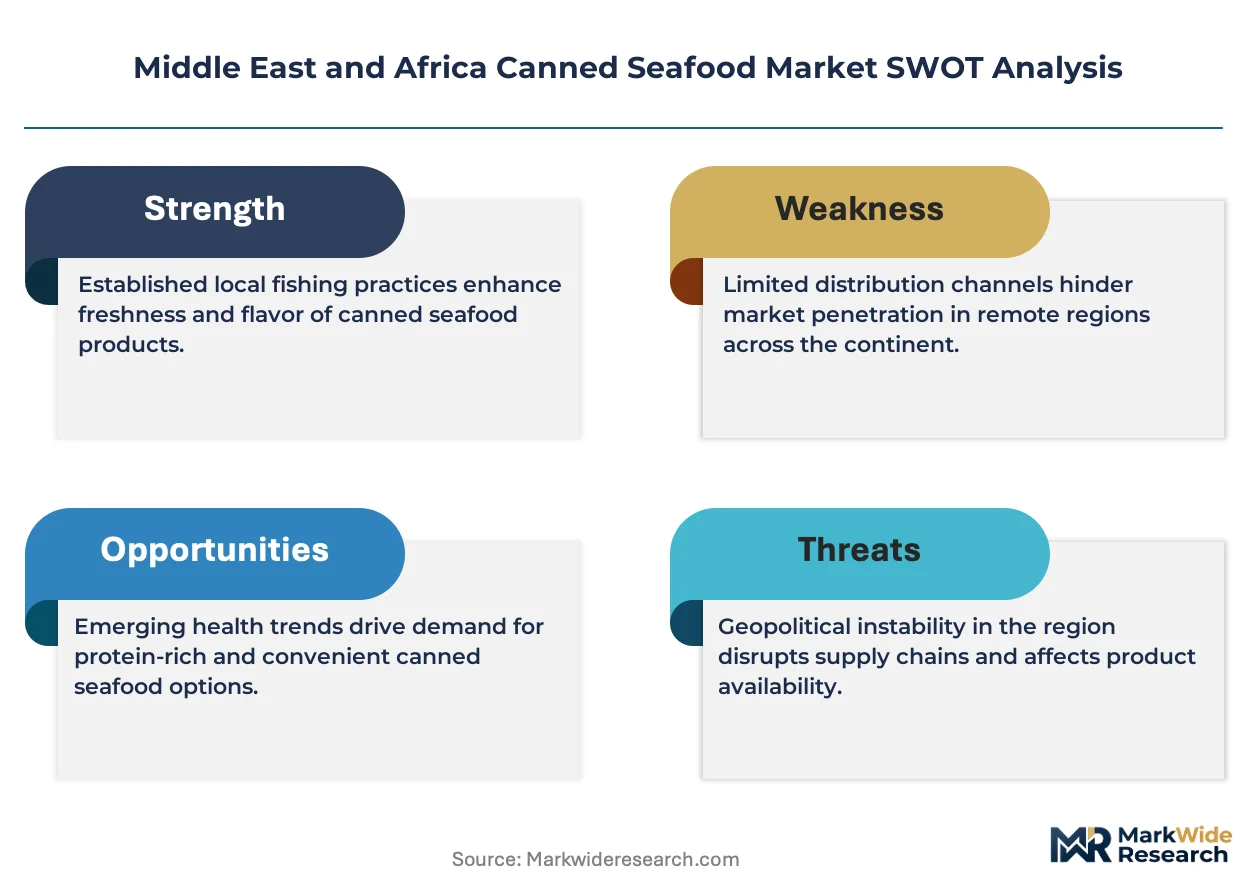
Food service operators across Gulf Cooperation Council states are expanding shelf-stable protein procurement as tourism and hospitality capacity rises, while South Africa's updated food safety labeling requirements under the Department of Health tighten import documentation and accelerate local certification investments.
Growth Catalysts
- Tourism Infrastructure Buildout:Hospitality capacity expansion across Dubai, Riyadh, and Doha is driving institutional procurement of canned tuna and sardine for hotel banquet operations and airline catering contracts.
- SFDA Halal Certification Mandate:Saudi Arabia's food and drug authority requires comprehensive shelf-life documentation and halal processing verification, creating structured demand for certified suppliers with established regulatory affairs capabilities.
- Retort Processing Advancements:Automated sterilization systems achieving temperatures exceeding 116 degrees Celsius are extending product shelf lives to 60 months, reducing spoilage risk in Nigeria's cold-chain-limited distribution corridors.
Market Restraints
- Skipjack Tuna Price Volatility:Raw material costs fluctuate with Indian Ocean purse seine catch volumes, compressing margins for Moroccan and Namibian canners dependent on distant-water fleet supply.
- North African Labor Scarcity:Fishery processing worker shortages across Moroccan and Tunisian coastal zones constrain output expansion despite rising order volumes from Middle Eastern buyers.
- Flexible Pouch Substitution:Younger consumers in South Africa and Kenya increasingly favor portable pouch formats over traditional metal cans, threatening legacy packaging line investments.
Strategic Opportunities
- Nigerian Urban Retail Penetration:Supermarket expansion in Lagos and Abuja corridors, combined with persistent cold-chain limitations, positions canned fish as a practical protein staple for middle-income households.
- E-Channel Development:Online grocery platforms in UAE and Saudi Arabian urban centers are gaining traction as fulfillment infrastructure matures, opening direct-to-consumer pathways bypassing traditional hypermarket gatekeepers.
- EU-GCC Standards Harmonization:Emerging certificate reciprocity discussions between Gulf standards bodies and African trade blocs could reroute competitive supply flows toward pre-certified regional producers.
Industry Challenges
- Retort Engineering Talent Gap:Specialized thermal processing technicians capable of maintaining commercial sterility protocols are scarce across North African manufacturing zones, limiting quality consistency at scale.
- Label Compliance Timeline Compression:South Africa's Department of Health enforcement of additive disclosure standards demands rapid reformulation and artwork revision cycles for import-dependent distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Canned Seafood Market |
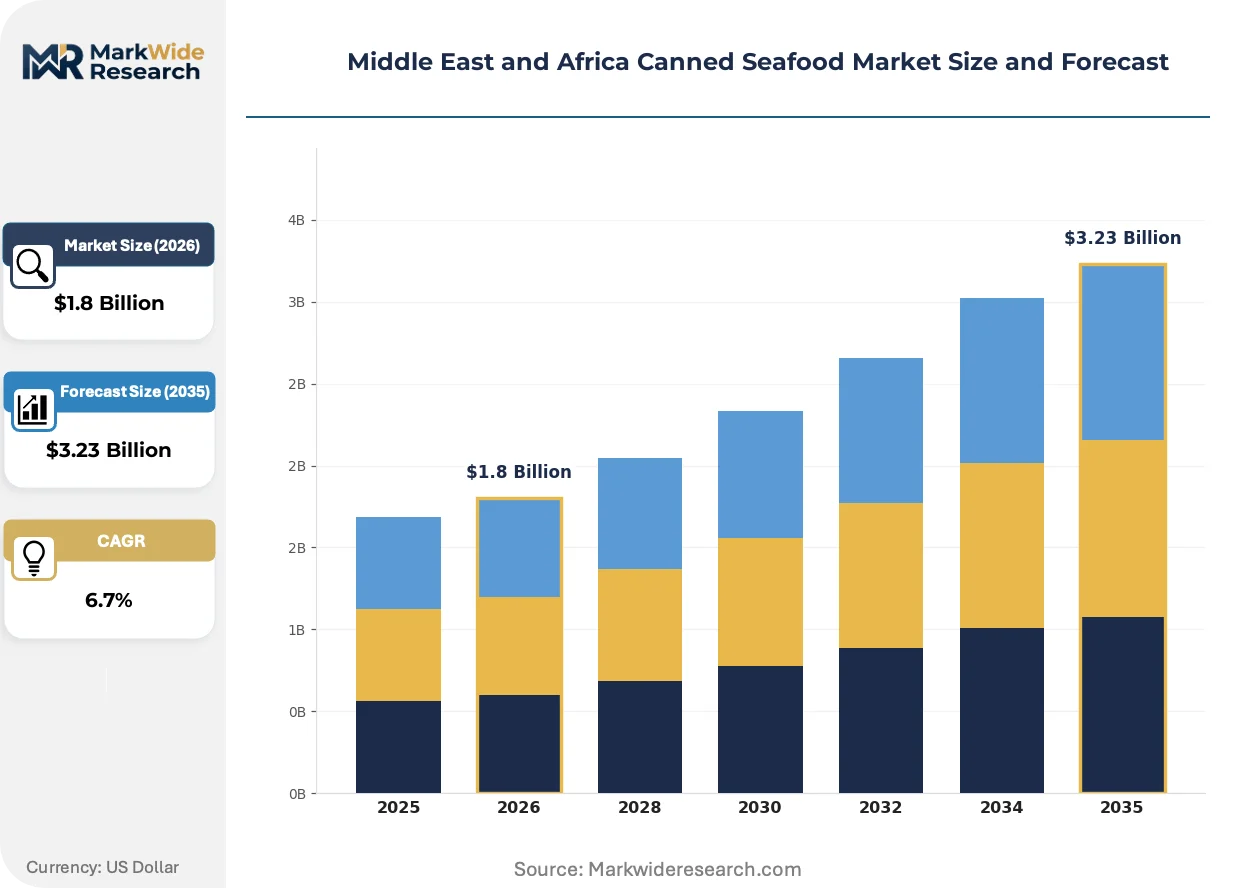
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tuna, Sardines, Mackerel, Salmon Packaging Type: Flexible Pouches, Cans, Glass Jars, Tetra Packs End User: Food Service, Retail, Households, Industrial Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesalers |
| Companies Covered | Thai Union Group PCL, Oceana Group Limited, Bolton Group B.V., Terrasan Group of Companies, Trident Seafoods Corporation, American Tuna Inc, Al-Alali, Century Pacific Food, Bidvest Namibia Fisheries Holdings, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Canned Seafood Market Shifts & Advancements
Packaging format evolution and regulatory harmonization efforts are actively restructuring competitive positioning across Middle East and Africa distribution channels. Three developments warrant particular attention.
Retortable flexible pouches are displacing traditional three-piece metal cans in Southern African retail channels. Younger consumers in Johannesburg and Cape Town prioritize portability and reduced metal waste, compelling manufacturers to reconfigure filling lines. The shift is compressing capital recovery timelines for legacy canning assets while rewarding suppliers with pouch conversion capabilities.
Saudi Arabia's SFDA has tightened halal certification and shelf-life documentation requirements for all processed seafood entering the Kingdom. Industrial consequence includes elevated compliance costs for smaller exporters without established regulatory affairs functions. Gulf retail chains are responding by consolidating supplier bases toward certified producers with integrated traceability systems.
Urban households in Nigeria's Lagos-Abuja corridor are rotating protein procurement toward shelf-stable options as supermarket penetration deepens. Traditional wet-market fish vendors face displacement from organized retail formats where canned products offer consistent pricing and safety assurance. The behavioral shift is most visible among dual-income families with limited cold storage capacity at point of consumption.
Middle East and Africa Canned Seafood Market Segmentation
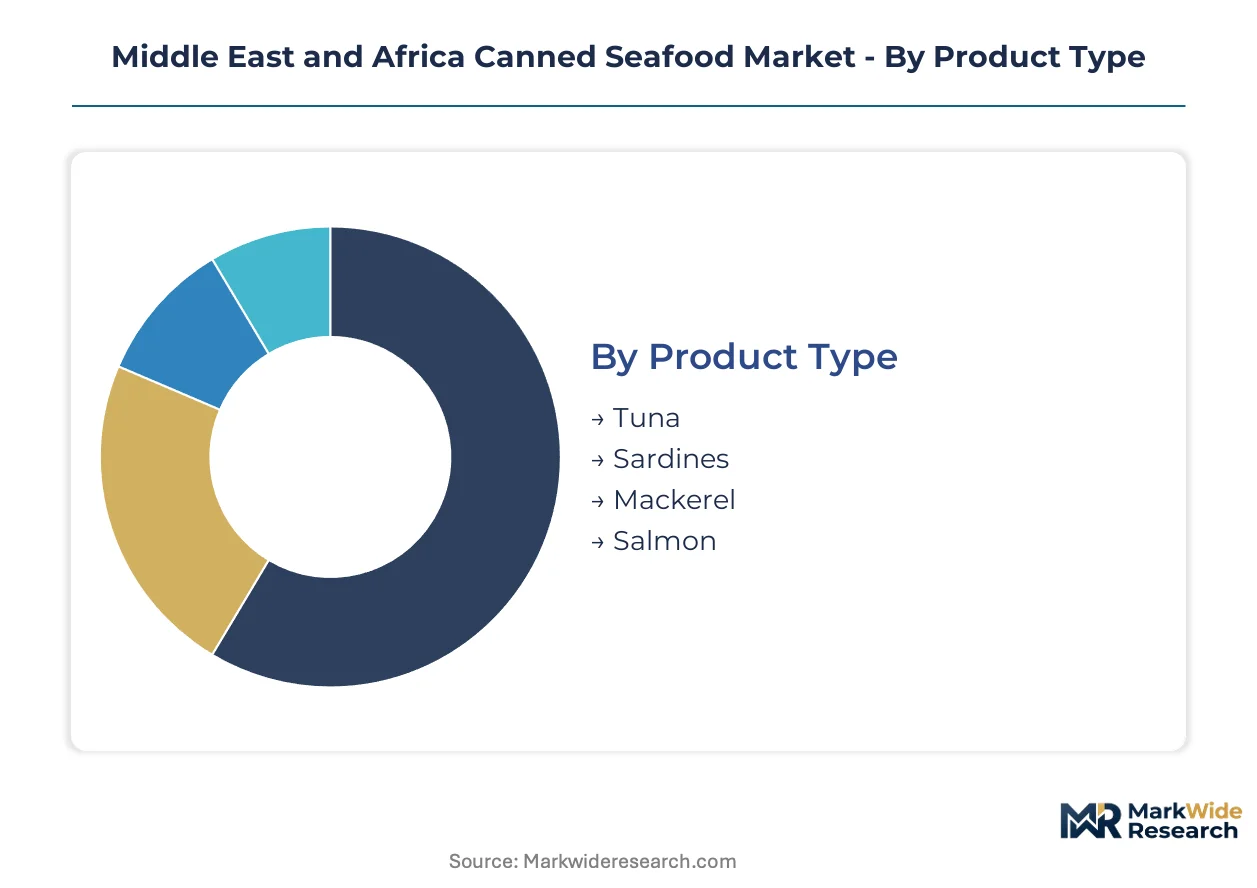
Channel configuration across Middle East and Africa varies sharply by segment. Gulf retail chains favor premium tuna in metal cans, while Nigerian urban corridors drive pouch format adoption where cold-chain gaps persist.
Product Type:
Tuna and sardines flow predominantly through supermarket and food service channels in Saudi Arabia and UAE, with mackerel and salmon carving distinct paths in North African retail and industrial procurement.
- Tuna:Skipjack and yellowfin species dominate thermal processing volumes across Moroccan canneries. Gulf Cooperation Council hospitality operators anchor demand through hotel banquet and airline catering contracts, with halal certification requirements from Saudi Arabia's SFDA filtering supplier eligibility.
- Sardines:Small pelagic fish processed in tomato sauce or vegetable oil constitute the volume staple in Egyptian and Tunisian retail. Lagos supermarket penetration and Abuja household cold-storage limitations position this segment as the practical protein default for Nigerian middle-income families.
- Mackerel:Atlantic and chub species serve price-sensitive segments across North African coastal markets.
- Salmon:Premium positioning in UAE and Saudi Arabian hypermarkets targets expatriate demographics with established canned salmon consumption habits.
Tuna dominates installed base. Sardines are where expansion concentrates.
Packaging Type:
Cost tier stratification separates premium-positioned formats from economy staples, with capital recovery timelines driving manufacturer commitment decisions.
- Flexible Pouches:Retortable multilayer films achieve commercial sterility while reducing metal waste and transport weight. Johannesburg and Cape Town younger consumers prioritize portability, compelling South African manufacturers to reconfigure filling lines and compress legacy asset recovery schedules.
- Cans:Three-piece metal containers retain institutional preference across Gulf food service procurement for structural integrity and shelf visibility. Moroccan and Namibian canneries maintain volume leadership through established steel and aluminum sourcing relationships.
- Glass Jars:Premium presentation formats serve gift-oriented retail in UAE urban centers.
- Tetra Packs:Aseptic carton systems occupy niche positions in Kenyan and Ethiopian retail channels with developing cold-chain infrastructure.
Cans dominate installed base. Flexible pouches are climbing the fastest.
End User:
Application urgency varies by thermal stability requirements and procurement scale, with food service operators demanding batch consistency and households prioritizing unit economics.
- Food Service:Hotel chains across Dubai, Riyadh, and Doha require pallet-scale procurement with documented halal processing verification. Saudi Arabia's SFDA mandates comprehensive shelf-life documentation, elevating compliance costs and consolidating supplier bases toward certified producers with integrated traceability.
- Retail:Supermarket and hypermarket channels control primary margin pools across Middle East and Africa, with private-label expansion in South Africa's Shoprite and Pick n Pay networks pressuring branded pricing architecture.
- Households:Dual-income families in Nigeria's Lagos-Abuja corridor rotate protein procurement toward shelf-stable options as organized retail displaces traditional wet-market vendors.
- Industrial:Food manufacturers source bulk tuna and sardine for further processing into ready-meal and sandwich fillings.
Retail dominates installed base. Food service is gaining share fastest.
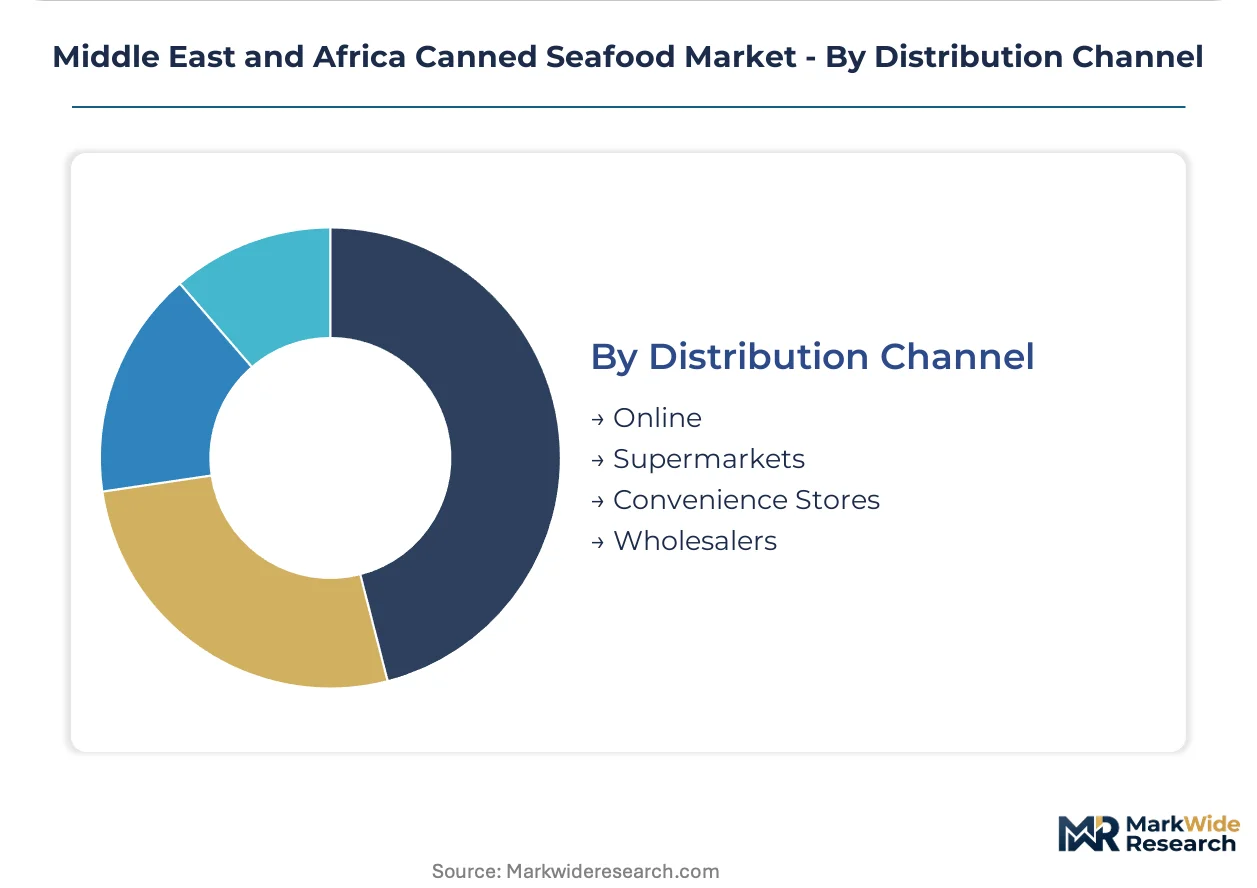
Distribution Channel:
Customer type fragmentation separates institutional procurement from individual consumption, with fulfillment infrastructure maturity determining channel viability.
- Supermarkets:Hypermarket and supermarket chains across Saudi Arabia, UAE, and South Africa concentrate volume throughput and category management influence. Carrefour, Lulu, and Shoprite networks dictate shelf placement fees and promotional calendar alignment.
- Online:E-grocery platforms in UAE and Saudi Arabian urban centers mature fulfillment infrastructure, opening direct-to-consumer pathways that bypass traditional hypermarket gatekeepers. Jumia and Noon operations in Nigeria face last-mile constraints in Lagos peripheral zones.
- Convenience Stores:Small-format retail in Egyptian and Moroccan urban cores serves immediate consumption needs with limited SKU breadth.
- Wholesalers:Cash-and-carry operators supply independent retailers and food service accounts across North African markets with weaker organized retail penetration.
Supermarkets dominate installed base. Online is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the Middle East and Africa canned seafood market tilts heavily toward Gulf Cooperation Council importers, while North African processing hubs absorb raw material volatility without commensurate margin recovery.
Saudi Arabia
SFDA halal certification mandates and shelf-life documentation requirements filter supplier eligibility for institutional procurement. Riyadh-based hospitality operators drive pallet-scale demand for verified tuna and sardine products. Jeddah port infrastructure channels re-exports toward Red Sea corridor markets.
United Arab Emirates
Dubai's tourism infrastructure buildout anchors food service procurement for hotel banquet and airline catering contracts. MOHAP food safety standards align with Gulf harmonization frameworks. Abu Dhabi retail networks concentrate hypermarket category management influence for premium-positioned formats.
South Africa
Updated Department of Health labeling requirements compress compliance timelines for import-dependent distributors. Cape Town and Johannesburg younger consumers accelerate flexible pouch adoption. Walvis Bay processing assets sustain volume leadership in Southern African retail channels.
Nigeria
Supermarket penetration in Lagos and Abuja corridors positions canned fish as a practical protein staple for middle-income households with limited cold storage. The country's national food safety regulator enforces additive disclosure standards for imported products. Lagos port clearance bottlenecks favor shelf-stable alternatives to fresh supply.
Morocco
Agadir and Casablanca canneries face fishery processing labor shortages despite rising order volumes from Middle Eastern buyers. The country's national fisheries authority coordinates distant-water fleet supply agreements for skipjack tuna. Tangier Med port infrastructure supports re-export positioning toward European markets.
Middle East and Africa Canned Seafood Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa canned seafood market. Gulf retail chains consolidate supplier bases toward certified producers with integrated traceability systems, while North African canneries compete on volume throughput. Three archetypes dominate: integrated multinational processors with African coastal assets, regional specialists leveraging species-specific access, and Gulf-based distributors with regulatory affairs capabilities. Competitive moves center on halal certification investments and pouch format line conversions.
Among integrated processors with established African operations, Thai Union Group PCL and Oceana Group Limited exemplify the scale-driven archetype, while Bolton Group B.V. occupies a position within the diversified species portfolio tier. These entities anchor supply network configurations through Moroccan canning partnerships and Namibian hake access respectively.
| Leading Market Players |
|---|
| Thai Union Group PCL |
| Oceana Group Limited |
| Bolton Group B.V. |
| Terrasan Group of Companies |
| Trident Seafoods Corporation |
| American Tuna Inc |
| Al-Alali |
| Century Pacific Food |
| Bidvest Namibia Fisheries Holdings |
| Others |
Supply & Pricing Matrix
Moroccan and Namibian cannery capacity utilization above 85 percent anchors regional supply concentration and sets price floors for Gulf import markets. Scale economies at Thai Union's Agadir partnerships and Oceana's Walvis Bay assets compress unit costs while distant-water skipjack procurement volatility transmits margin pressure downstream.
Pricing Analysis
The customization-premium spread separates halal-certified SFDA-compliant SKUs from standard retail offerings. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale. Pricing pressure stems from Indian Ocean skipjack volatility compressing margins at Moroccan processors. Food service buyers in Dubai and Riyadh exhibit lowest price sensitivity due to halal verification requirements, while Nigerian retail channels face acute cost consciousness.
Supply Chain Analysis
Inventory lead times stretch 45-90 days for Gulf-bound shipments transiting Tangier Med and Jeddah. Supply concentrates in Morocco, Namibia, and Thailand for raw material processing, with finished goods distribution running through Saudi Arabia and UAE hypermarket networks. The chain rests on distant-water tuna fleet access, retort equipment spare parts, and multilayer pouch films. Single-source vulnerability sits with Indian Ocean purse seine operators. Downstream distribution feeds through Carrefour, Lulu, and Shoprite centralized procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa canned seafood market represents high-growth disruption as retortable flexible pouches displace metal cans and SFDA halal mandates restructure supplier eligibility.
For Market Incumbents: Secure halal certification reciprocity across Gulf standards bodies before certificate harmonization locks in competitor positioning. Deepen backward integration into Namibian hake supply and Moroccan sardine fisheries to offset distant-water tuna price volatility. Channel control through direct e-grocery partnerships in UAE and Saudi Arabia defends against private-label compression.
For New Entrants and Emerging Players: Lead with pouch-format SKUs targeting Johannesburg and Cape Town younger consumers where legacy canners face asset-stranding risk. Nigerian supermarket expansion in Lagos peripheral zones offers the most penetrable geography given cold-chain gaps and wet-market displacement. Go-to-market through Jumia and Noon fulfillment partnerships bypasses hypermarket slotting fee barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated processors with captive Namibian or Moroccan coastal assets and established SFDA regulatory affairs functions. Five-to-ten year viability favors canneries with pouch line conversion capability and Gulf retail chain direct supply relationships. The signal to watch is EU-GCC standards harmonization progress as certificate reciprocity would reroute competitive supply flows toward pre-certified regional producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Investment | SFDA compliance unlocks Saudi institutional procurement and airline catering contracts. |
| Flexible Pouch Line Conversion | Retortable film capacity captures Johannesburg and Cape Town younger consumer rotation. |
| Backward Integration into Fisheries | Captive Namibian hake supply insulates Oceana from distant-water tuna volatility. |
| E-Channel Direct Partnership | Noon and Jumia fulfillment bypasses Carrefour and Lulu slotting fee structures. |
| Regulatory Affairs Capability Build | Integrated traceability systems meet South Africa Department of Health additive disclosure demands. |
Research Methodology
Cross-validation between primary interviews with cannery operations directors, Gulf retail category buyers, and Namibian fisheries regulators anchors the qualitative findings against secondary validation. Primary fieldwork engaged Moroccan processing plant managers, UAE food service procurement leads, and South African supermarket private-label directors. Secondary sources comprised Saudi SFDA import filings, South Africa Department of Health labeling guidance, customs trade data through Tangier Med and Jeddah ports, and SEC disclosures from listed processors. Bottom-up volume builds and top-down macroeconomic triangulation converged on segment-level estimates.
Sensitivity analysis tested forecast outputs against skipjack price volatility bands and Gulf tourism growth scenarios across the analysis window. The analytical framework modeled product type, packaging format, end user, and distribution channel dimensions alongside halal certification tier as an industry-specific stratifier. CAGRs derived from segment-level growth rate synthesis and macroeconomic driver elasticity. Industry-specific inputs included Indian Ocean tuna catch projections and Gulf hospitality capacity expansion pipelines.
The analysis sits within stated boundaries; outcomes outside sustained Gulf tourism growth, stable distant-water fleet supply, or current SFDA regulatory stringency would require recalibration. Forecasts reflect documented assumptions on consumer format preferences and certificate reciprocity timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Japan Frozen Seafood Market
Seafood
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market
Seafood
Sea Biscuits Market
Seafood
Wild Pollock Market
Seafood
Crustacean Market
Seafood
Salmon Fish Market
Seafood
Crayfish Market
Seafood
Europe Salmon Market
Seafood
Canned Tuna Market
Seafood
Tuna and Algae Omega-3 Market
Seafood
Edible Seaweed Market
Seafood
North America Salmon Market
Seafood
Canned Seafood Market
Seafood
Krill Meal Market
Seafood
Alaskan Salmon Market
Seafood
Fish Hydrolysate Market