
 North America Salmon Market | 2026-2036
North America Salmon Market Size, Share, and Industry Trends Forecast 2026-2036
North America Salmon Market Intelligence
Fresh fillet grade specification is collapsing the gap between farmed Atlantic and premium wild-caught positioning across North American retail counters. Mowi ASA leverages its integrated feed-to-fork model to sustain volume leadership in the United States fresh salmon segment. Cooke Aquaculture anchors Canadian supply through its vertically owned hatchery and sea-site network in Atlantic Canada. Bakkafrost differentiates via its Scottish-origin genetics program, which competes directly with domestic farmed supply on color and fat-line metrics.
North America salmon encompasses farmed Atlantic salmon (Salmo salar) and wild Pacific species including Chinook, Coho, and Sockeye, distinguished by flesh color, fat content, and omega-3 fatty acid profiles measured in grams per serving. Fresh salmon commands the dominant value share in retail and foodservice channels, while smoked salmon generates concentrated margin pools through premium gifting and deli-counter positioning. The foodservice end-user segment shows the fastest structural expansion, driven by sushi-format adoption and raw-prep certification requirements across restaurant chains.
NOAA Fisheries and the Canadian Food Inspection Agency enforce harvest quotas and HACCP compliance that shape wild-catch availability and processing standards. The FDA's Seafood Hazard Analysis Critical Control Point framework governs import inspection frequency and farmed salmon antibiotic residue thresholds. State-level water quality regulators in Maine and Washington issue discharge permits that determine land-based and net-pen expansion timelines. Stakeholders must monitor recirculating aquaculture system permitting precedents and traceability mandate harmonization between U.S. and Canadian federal agencies.
Market Dynamics
Land-based recirculating aquaculture systems are forcing a capital reallocation across North American salmon production, as Maine and Washington state regulators issue discharge permits that favor closed-containment models over traditional net-pen operations.
Growth Catalysts
- Foodservice raw-prep certification:Sushi-format adoption across United States restaurant chains is expanding Atlantic salmon procurement for premium menu positioning. Chains now require HACCP-compliant suppliers for raw service.
- State-level RAS permitting:Washington and Maine water quality regulators are granting discharge permits to land-based recirculating aquaculture systems faster than federal net-pen renewal timelines.
- Pacific Northwest cold-chain clustering:Processing infrastructure concentration near Seattle and Vancouver population centers is reducing logistics costs for fresh fillet distribution.
Market Restraints
- Fishmeal input cost volatility:Atlantic salmon feed formulations depend on Peruvian anchovy harvest quotas, which NOAA Fisheries tracks for omega-3 oil availability.
- Canadian supply concentration:New Brunswick and British Columbia sea-site networks control the majority of North American farmed volume, creating geographic single-point risk.
- Wild-catch quota rigidity:Alaska Department of Fish and Game harvest limits cap Sockeye and Coho availability regardless of retail price signals.
Strategic Opportunities
- Underpenetrated U.S. inland markets:Dallas-Fort Worth and Chicago metropolitan areas lack dedicated salmon processing infrastructure despite rising foodservice demand.
- Integrated feed-to-fork traceability:FDA Seafood HACCP framework harmonization with Canadian Food Inspection Agency standards could unlock cross-border premium labeling.
- Smoked salmon gifting channels:Direct-to-consumer subscription models are bypassing traditional deli-counter distribution for premium holiday positioning.
Industry Challenges
- RAS engineering talent scarcity:Land-based recirculating aquaculture systems require water chemists and biofilter specialists that existing aquaculture programs do not produce.
- Antibiotic residue testing timelines:FDA import inspection frequency creates inventory hold periods that compress fresh fillet shelf life.
- Wild-catch seasonality integration:Foodservice operators struggle to balance fixed menu commitments against Alaska salmon run timing variability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Salmon Market |
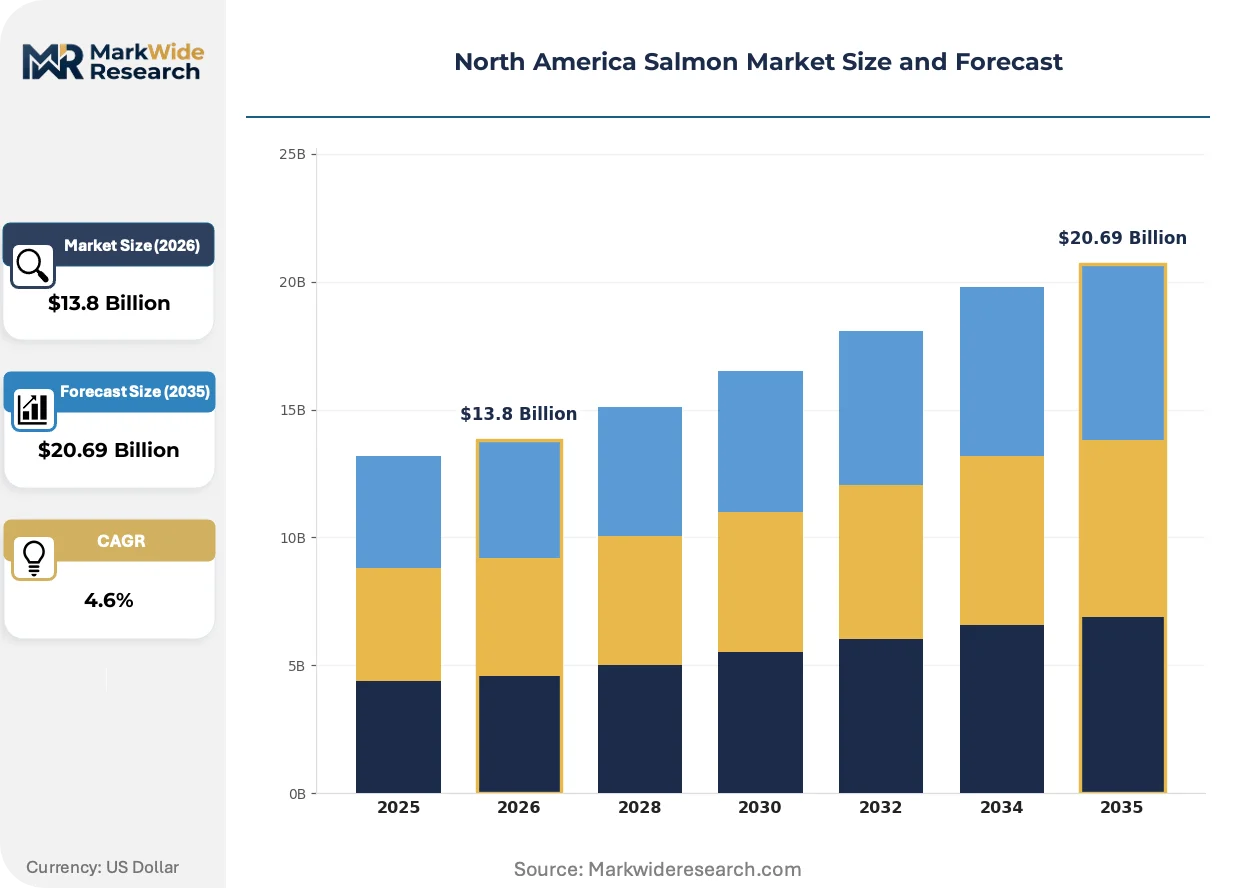
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $20.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Salmon, Frozen Salmon, Smoked Salmon, Canned Salmon Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Foodservice End User: Households, Restaurants, Hotels, Catering Services Packaging Type: Bulk Packaging, Retail Packaging, Vacuum Sealed, Tray Packs |
| Companies Covered | Atlantic Sapphire, SalMar ASA, Mowi ASA, Bakkafrost, Lerøy Seafood Group, Cermaq Group, Empresas AquaChile, Grieg Seafood, Cooke Aquaculture, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Salmon Market Strategic Shifts & Innovations
Production technology is splitting the North American salmon supply base into two distinct operational models, each demanding different capital structures and regulatory relationships.
Recirculating aquaculture systems are bifurcating the farmed salmon supply base between land-based closed containment and marine net-pen operations. Premium retailers and sushi-grade distributors are prioritizing RAS-origin Atlantic salmon for consistent pathogen-free certification. This technology split is compressing net-pen expansion timelines in Washington state while accelerating Maine land-based project financing.
NOAA Fisheries harvest quota frameworks are tightening wild Pacific salmon availability through species-specific escapement requirements. The industrial consequence is premium pricing concentration for Chinook and Sockeye in retail channels. Alaska processors are responding by diverting more volume to frozen H&G formats rather than fresh fillet production.
Foodservice procurement is consolidating around certified raw-prep suppliers as sushi-format menu penetration expands beyond coastal metropolitan areas. Regional distributors are displacing traditional broadline seafood houses with specialized cold-chain operators holding FDA Seafood HACCP and state-level raw fish certifications. This channel restructuring is most visible in Texas and Illinois markets where sushi chain expansion outpaces local supplier qualification.
North America Salmon Market Segmentation
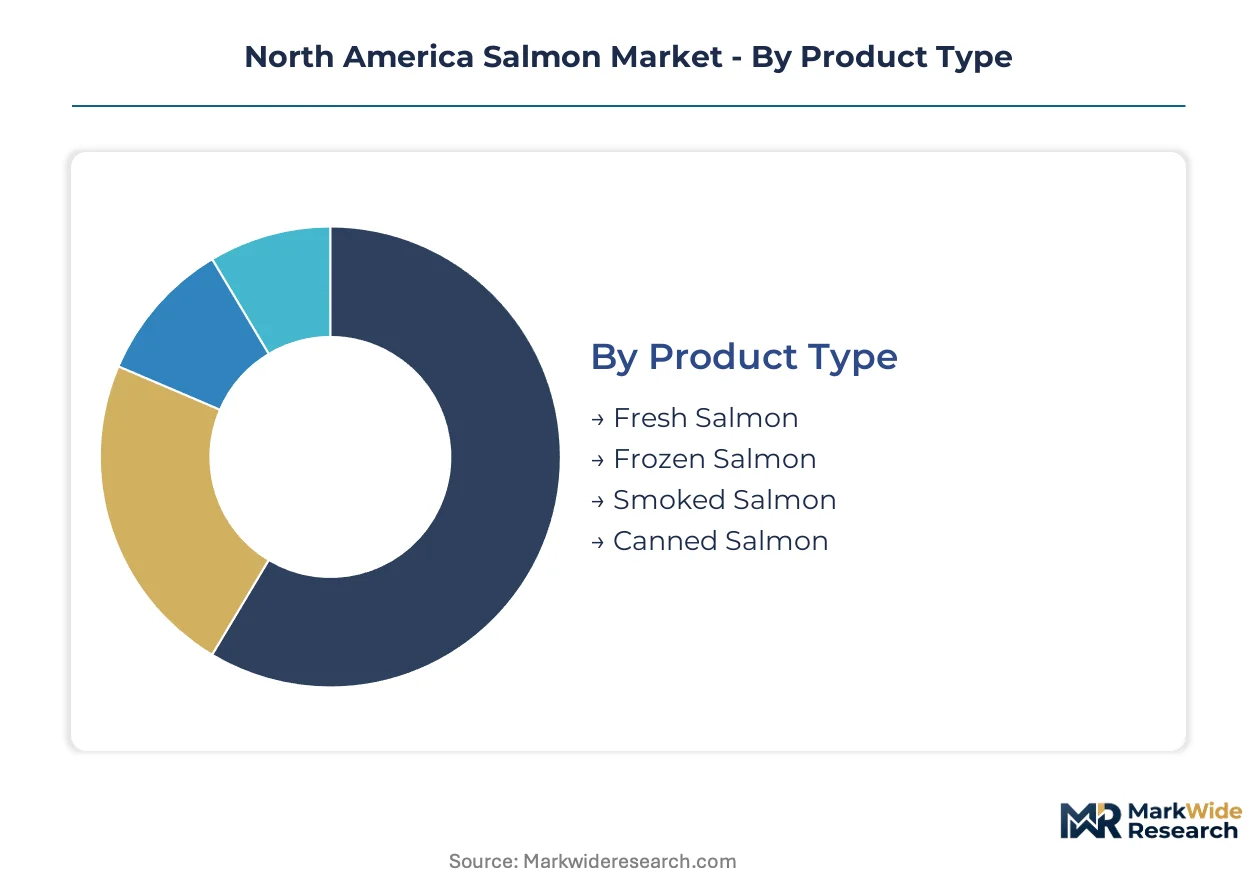
Channel-specific requirements reshape product specifications across North American salmon flows. Retail, foodservice, and direct-to-consumer channels each demand distinct packaging, certification, and cold-chain configurations that segment the market structurally.
Product Type:
Channel mix determines which product formats capture margin pools versus volume scale across retail and foodservice procurement.
- Fresh Salmon:Fillets and whole fish maintained at 0-2°C through HACCP-certified cold chains. Foodservice operators in Seattle, Vancouver, and New York metropolitan areas concentrate procurement here for raw-prep certification requirements.
- Frozen Salmon:Blast-frozen H&G and portion-controlled fillets stored at -18°C. Alaska processors divert increasing Sockeye and Coho volume to frozen formats as wild-catch quotas tighten and fresh shelf life compresses.
- Smoked Salmon:Cold-smoked and hot-smoked varieties for deli counters and direct-to-consumer subscription channels.
- Canned Salmon:Shelf-stable pink and sockeye products for retail pantry stocking and emergency food programs.
Fresh salmon dominates installed foodservice base. Smoked salmon is where premium margin expansion concentrates.
Distribution Channel:
Cost tier stratification separates mass-market volume from specialty premium positioning across the four channel structures.
- Supermarkets:High-volume fresh fillet counters and frozen seafood aisles serving household meal preparation. Chains in the Pacific Northwest leverage proximity to Seattle and Vancouver processing clusters to reduce logistics costs and extend shelf life.
- Foodservice:Specialized distributors holding FDA Seafood HACCP and state-level raw fish certifications for sushi-format restaurant chains. Texas and Illinois markets show steepest expansion trajectory as inland sushi penetration outpaces local supplier qualification.
- Online Retail:Direct-to-consumer frozen and smoked salmon subscription models bypassing traditional deli-counter distribution.
- Specialty Stores:Premium wild-caught and RAS-origin Atlantic salmon for certified organic and sustainable seafood positioning.
Supermarkets dominate household volume. Foodservice is where certification requirements and margin expansion concentrate.
End User:
Application-specific preparation requirements segment demand by cooking method, certification needs, and procurement scale.
- Restaurants:Sushi-format and raw-prep certified Atlantic salmon procurement expanding across United States chain operations. HACCP compliance and state-level raw fish permits determine supplier eligibility.
- Households:Retail fresh fillet and frozen portion purchases for home meal preparation, concentrated in coastal metropolitan areas with established cold-chain infrastructure.
- Hotels:Breakfast buffet smoked salmon and banquet fresh fillet requirements for hospitality foodservice operations.
- Catering Services:Bulk fresh and frozen procurement for event-based meal service with variable portion scaling.
Restaurants dominate certified raw-prep demand. Households represent the broadest geographic penetration base.
Packaging Type:
Supply concentration in Pacific Northwest processing clusters shapes packaging configuration and shelf-life extension strategies.
- Vacuum Sealed:Oxygen-barrier film packaging extending fresh fillet shelf life from 7 to 21 days for retail and foodservice distribution. Washington and British Columbia processors favor this format for cross-continental shipment to underpenetrated inland markets.
- Retail Packaging:Pre-portioned tray packs with absorbent pads and gas-flushed atmospheres for supermarket fresh counters. Maine and Atlantic Canada land-based RAS operations prioritize this format for consistent pathogen-free certification labeling.
- Bulk Packaging:Whole fish and H&G formats for foodservice processors and secondary filleting operations.
- Tray Packs:Modified atmosphere packaging for fresh fillet display cases in specialty and supermarket channels.
Vacuum sealed dominates shelf-life extension investment. Retail packaging is where premium labeling and traceability integration concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a structural salmon trade deficit, importing farmed Atlantic fillets while exporting limited wild Pacific volumes to Asian markets. Canadian processors bridge this gap through cross-border cold-chain integration. Mexican demand remains import-dependent with minimal domestic production infrastructure.
United States
Foodservice operators in Texas and Illinois metropolitan areas are expanding sushi-format procurement faster than local supplier qualification permits. The FDA's Seafood HACCP framework governs raw-prep certification requirements for restaurant chains. Seattle anchors Pacific Northwest processing infrastructure, with cold-chain clusters reducing logistics costs for fresh fillet distribution to inland markets.
Canada
New Brunswick and British Columbia sea-site networks control the majority of North American farmed Atlantic salmon volume. Health Canada and the Canadian Food Inspection Agency enforce harvest quotas and processing standards that shape wild-catch availability. Vancouver processing clusters concentrate vacuum-sealing and modified atmosphere packaging capacity for cross-border retail distribution.
Mexico
Restaurant chains in Mexico City and Monterrey are adopting raw-prep salmon formats without domestic RAS or net-pen production capacity. The country's national food safety regulator applies import inspection protocols for farmed Atlantic salmon from Canadian and U.S. sources. Baja California lacks processing infrastructure despite proximity to Pacific wild-catch zones, forcing reliance on imported fresh and frozen fillets.
North America Salmon Market Key Industry Players
Listed leaders compete with private specialists across capital access and operational flexibility dimensions. The market structure tilts toward consolidation among integrated feed-to-fork operators, with tiered competition between scale-driven multinationals and regional specialists. Three archetypes dominate: vertically integrated Atlantic producers, wild-catch processors with quota access, and land-based RAS technology developers. Capacity expansion and geographic diversification represent the dominant competitive moves, as players secure discharge permits and processing licenses ahead of demand growth.
Among Norway-based listed producers, Mowi ASA and SalMar ASA exemplify scale-driven integration archetypes with feed production and distribution network control. Cooke Aquaculture anchors the private specialist tier as a Canada-based family-owned operator with hatchery and sea-site ownership across Atlantic Canada and Maine. Atlantic Sapphire represents the land-based RAS technology vector, with Florida-based closed-containment production targeting pathogen-free certification premiums.
| Leading Market Players |
|---|
| Atlantic Sapphire |
| SalMar ASA |
| Mowi ASA |
| Bakkafrost |
| Lerøy Seafood Group |
| Cermaq Group |
| Empresas AquaChile |
| Grieg Seafood |
| Cooke Aquaculture |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Atlantic salmon producers and foodservice distributors lock in volume commitments while capping price volatility exposure for sushi-format restaurant chains across Texas and Illinois metropolitan areas.
Pricing Analysis
Foodservice operators anchor contract-based pricing structures that stratify across sushi-grade certification tiers, with raw-prep HACCP compliance commanding premium positioning over standard fresh fillet grades. Price differentiation hinges on pathogen-free RAS origin versus conventional net-pen supply, plus cold-chain integrity guarantees. Cost compression in standard-grade Atlantic fillets is intensifying because Peruvian anchovy quota volatility feeds into omega-3 oil input costs. Mass-market retail buyers show highest price sensitivity, while certified raw-prep foodservice chains absorb premiums for supply security.
Supply Chain Analysis
Just-in-time fresh fillet delivery dominates foodservice procurement, though Alaska processors increasingly favor strategic frozen stockpiles as Sockeye and Coho quotas tighten. Supply concentrates in Norway, Canada, and Scotland for farmed Atlantic volume, with wild Pacific sourcing anchored in Alaska and British Columbia. Feed formulations draw from Peruvian fishmeal, Canadian wheat, and Scandinavian fish oil. Single-source vulnerability runs through New Brunswick and British Columbia sea-site networks that control majority North American farmed output. Distribution runs through Seattle and Vancouver cold-chain clusters for fresh fillet penetration into inland U.S. markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America salmon market rewards operators who control scarce RAS engineering talent and state-level discharge permitting relationships ahead of competitor expansion timelines.
For Market Incumbents: Secure RAS engineering teams through targeted recruitment from water chemistry and biofilter specialist programs before land-based project financing accelerates. Lock in multi-year state discharge permits in Maine and Washington ahead of regulatory queue congestion. Deepen backward integration into hatchery genetics to differentiate color and fat-line metrics against Scottish-origin imports. For New Entrants and Emerging Players: Anchor in Dallas-Fort Worth and Chicago metropolitan areas where sushi-format demand outpaces local supplier qualification. Target certified raw-prep foodservice distributors lacking HACCP-compliant cold-chain partners. Lead with direct-to-consumer smoked salmon subscription models that bypass traditional deli-counter margin compression. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated Atlantic producers with captive hatchery networks and established FDA Seafood HACCP compliance frameworks across the 5-10 year viability window. Monitor recirculating aquaculture system permitting precedents as the inflection signal for land-based production cost parity against net-pen supply.| Strategic Initiative | Industry Significance |
|---|---|
| RAS Discharge Permit Acquisition | Maine and Washington state water quality regulators favor closed-containment over net-pen renewal timelines. |
| Raw-Prep Certification Investment | FDA Seafood HACCP compliance unlocks sushi-format procurement from expanding inland restaurant chains. |
| Feed-to-Fork Traceability Integration | Harmonization with Canadian Food Inspection Agency standards enables cross-border premium labeling. |
| Pacific Northwest Cold-Chain Expansion | Seattle and Vancouver processing clusters reduce logistics costs for fresh fillet inland distribution. |
| Direct-to-Consumer Channel Development | Smoked salmon subscription models capture holiday gifting margin pools outside traditional retail. |
Research Approach
Operator-level perspectives from foodservice procurement directors, RAS facility engineers, cold-chain logistics managers, and Alaska wild-catch processors anchored the qualitative base. Secondary validation drew from NOAA Fisheries harvest quota publications, FDA Seafood HACCP guidance documents, state environmental discharge permit records, and Canadian Food Inspection Agency processing standards. Bottom-up volume modeling triangulated against top-down trade flow analysis across farmed Atlantic and wild Pacific supply streams.
Sensitivity analysis tested input assumptions across the projection horizon, with segmentation dimensions spanning product type, distribution channel, end-user application, and packaging configuration alongside RAS versus net-pen production origin. CAGRs emerged from fitted growth curves applied to baseline volume and value estimates. Industry-specific forecast inputs incorporated Peruvian anchovy quota trajectories and state-level permitting velocity differentials.
Material uncertainties — regulatory harmonization delays, fishmeal input cost spikes, and RAS engineering talent scarcity — sit outside the modeled envelope. Forecasts reflect documented assumptions about discharge permit issuance rates and foodservice certification adoption curves. Revision becomes warranted when land-based production cost parity against conventional net-pen supply crosses threshold viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish Meal and Fish Oil Market
Seafood
Carp Market
Seafood
Trout Market
Seafood
Global Smoked Fish Market
Seafood
Dried Scallop Market
Seafood
Smoked Whiting Market
Seafood
Mackerel Market
Seafood
Mussel Oil Market
Seafood
Alaskan Salmon Market
Seafood
Haddock Market
Seafood
Japan Lobster Market
Seafood
Seafood Processing Market
Seafood
Surimi by-Product Market
Seafood
Salmon Fish Market
Seafood
Fish Hydrolysate Market
Seafood
Tuna and Algae Omega-3 Market