
 Global White Shrimp Market | 2026-2036
Global White Shrimp Market Size, Share, and Industry Trends Forecast 2026-2036
Global White Shrimp Market Outlook
Aquaculture Stewardship Council certification is unwinding competitive access across the Global White Shrimp Market, disqualifying uncertified producers from premium retail and foodservice contracts. Charoen Pokphand Foods PCL leverages integrated feed-to-table operations across Thailand and Vietnam. Thai Union Group PCL sustains volume leadership through frozen value-added product lines sold into European and North American retail channels. Clearwater Seafoods differentiates via wild-caught positioning and traceability systems that command shelf-space in Canadian and US supermarkets.
White shrimp (Litopenaeus vannamei) denotes a fast-growing penaeid species farmed in brackish water ponds, typically harvested at 15-20 grams within 90-120 days for protein-dense meat with mild flavor profile. Frozen products dominate trade flows due to extended shelf stability and suitability for cross-border logistics, while cooked segments capture margin pools through ready-to-eat convenience positioning. E-commerce channels are expanding fastest among distribution pathways, though wholesale remains the volume anchor for restaurant and food processing buyers.
US FDA Hazard Analysis Critical Control Point rules, EU Regulation 853/2004 on food of animal origin, and Ecuador's national aquaculture biosafety protocols collectively shape import eligibility and farm-level operational standards. These frameworks elevate compliance costs but also consolidate market access for certified operators with documented chain-of-custody systems. Stakeholders must monitor evolving antibiotic residue testing protocols and carbon footprint disclosure requirements as purchasing criteria harden across major import jurisdictions.
Market Dynamics
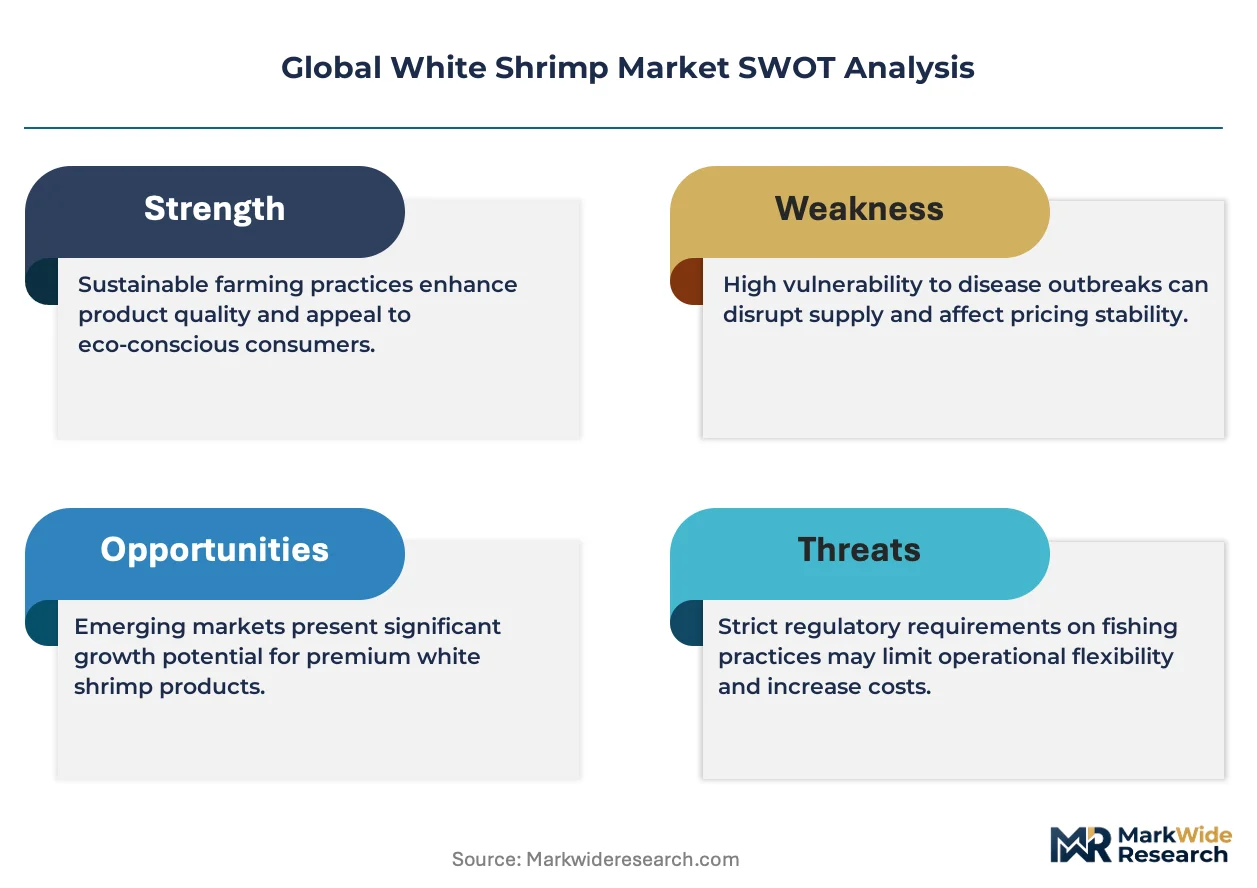
Aquaculture Stewardship Council certification requirements are compressing farm-gate margins while simultaneously erecting entry barriers that favor capital-intensive operators with documented chain-of-custody systems across Ecuador, Vietnam, and Indonesia.
Growth Catalysts
- Intensive Pond Systems:Ecuadorian producers are expanding 40-hectare intensive ponds with automated aeration and sensor-based water quality monitoring, lifting yields per hectare while reducing labor intensity.
- EU Regulation 853/2004:Harmonized food safety standards for products of animal origin are streamlining cross-border trade within the European Union, reducing duplicate testing for certified exporters.
- Value-Added Processing:Southeast Asian food processing industries are scaling procurement of cooked, breaded, and marinated shrimp products, capturing higher unit economics than raw frozen commodity trade.
Market Restraints
- Feed Cost Volatility:Fishmeal and soybean meal prices swing with South American crop cycles and Peruvian anchovy quotas, compressing margins for non-integrated farms without captive feed mills.
- Antibiotic Residue Testing:US FDA Hazard Analysis Critical Control Point rules and EU maximum residue limits are disqualifying shipments from regions with inconsistent veterinary oversight, forcing costly pre-export laboratory screening.
- Climate Vulnerability:Brackish water pond operations in coastal Vietnam and Bangladesh face salinity intrusion and extreme weather events that disrupt stocking cycles and destroy infrastructure.
Strategic Opportunities
- Carbon Footprint Disclosure:EU Green Deal supply chain due diligence requirements are creating first-mover advantage for operators with verified lifecycle assessments and Scope 3 traceability systems.
- E-Commerce Direct-to-Consumer:Frozen seafood platforms in China and South Korea are bypassing traditional wholesale layers, enabling branded shrimp producers to capture retail margin pools previously lost to intermediaries.
- Recirculating Aquaculture Systems:Land-based closed-loop production is penetrating premium retail channels in Japan and Germany with antibiotic-free claims and year-round supply consistency.
Industry Challenges
- Aquaculture Veterinarian Shortage:Farm biosecurity management and disease diagnostics depend on specialized veterinary expertise that concentrates in Thailand and Ecuador, leaving Indonesian and Indian operations understaffed.
- ASC Certification Timelines:The 12-18 month audit and remediation cycle delays market access for new entrants, locking in incumbents who achieved certification during earlier, less stringent protocol versions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global White Shrimp Market |
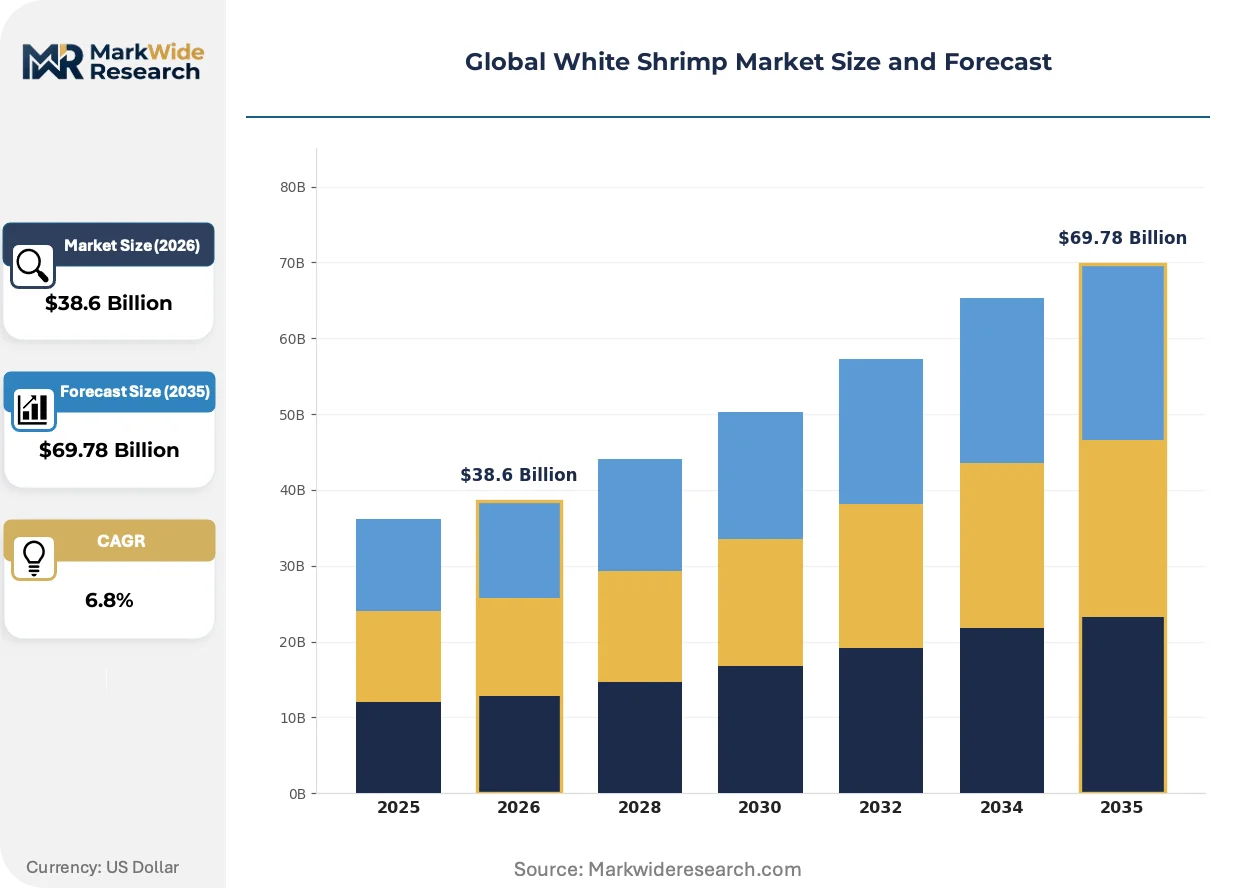
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Frozen, Cooked, Dried Distribution Channel: Retail, Wholesale, Direct Sales, E-commerce End User: Household, Restaurants, Food Processing, Exporters Harvest Method: Aquaculture, Wild-caught, Coastal Farming, Integrated Farming |
| Companies Covered | Thai Union Group PCL, Charoen Pokphand Foods PCL, Avanti Feeds Limited, Aqua Star, Clearwater Seafoods, High Liner Foods, Nordic Seafood A/S, Apex Frozen Foods Ltd, Grupo Ibérica Congelados S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global White Shrimp Market Strategic Shifts
Automation and biological intensification are restructuring production economics while regulatory disclosure mandates and channel fragmentation are rewriting how value is captured and distributed across the value chain.
Automated feeding systems with acoustic sensors that detect shrimp appetite in real-time are supplanting manual tray feeding protocols in Vietnamese and Ecuadorian intensive ponds. Mid-scale operators with 20-50 hectare footprints are deploying these systems fastest, cutting feed conversion ratios by fifteen to twenty percent and compressing the competitive position of labor-dependent semi-intensive farms.
EU Corporate Sustainability Reporting Directive disclosure requirements are mandating supply chain due diligence for large food retailers and foodservice groups sourcing white shrimp. Importers must now document environmental and social metrics from hatchery through processing, with enforcement beginning for fiscal years 2024-2025, pushing procurement departments to pre-qualify only ASC-certified suppliers with third-party verified data.
Foodservice distributors in North America are unbundling frozen shrimp specifications from traditional broadline contracts, creating standalone protein sourcing categories with dedicated quality assurance teams. This disintermediation of procurement authority from generalist buyers to specialist seafood merchandisers is most visible in US regional restaurant chains with 50-200 unit footprints, which now negotiate directly with Ecuadorian and Indian processors rather than relying on national distributor programs.
Global White Shrimp Market Segmentation
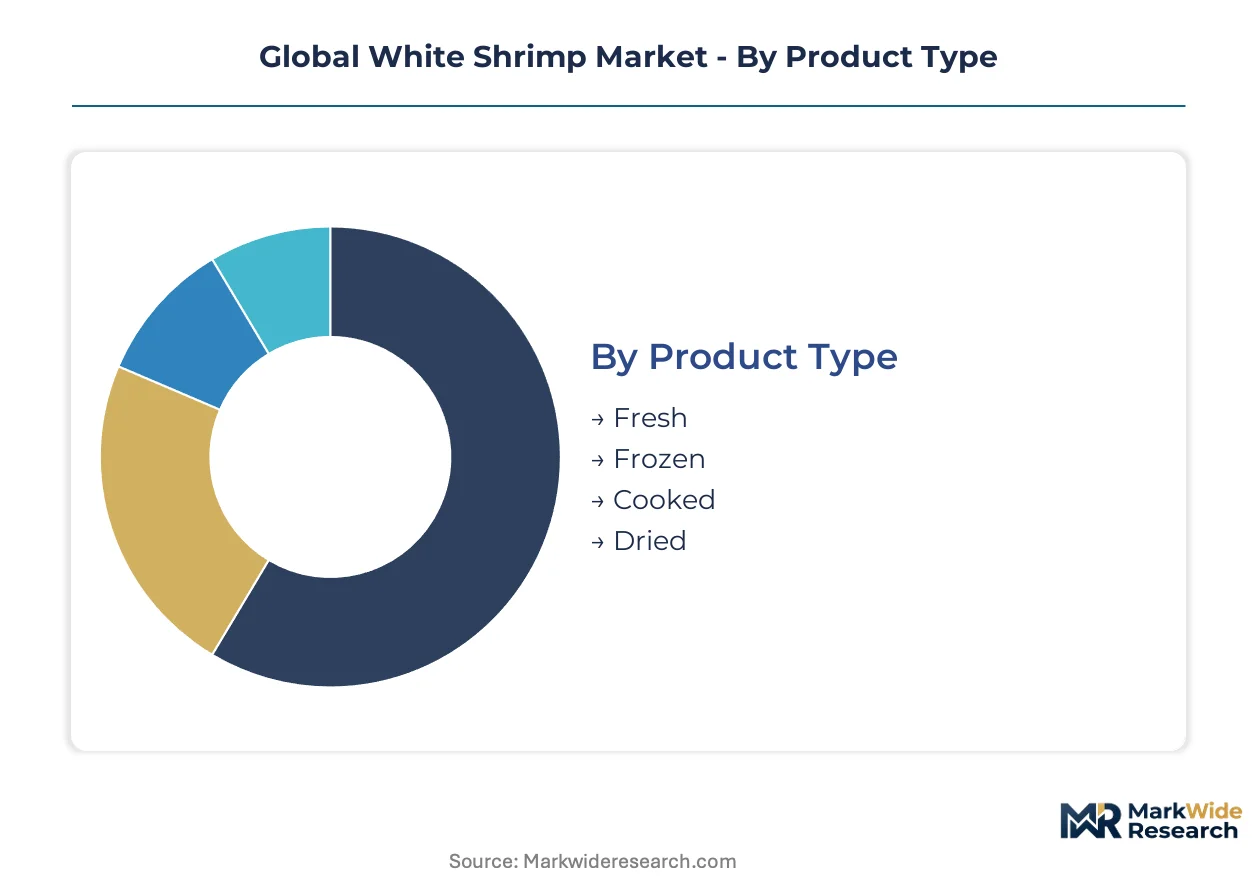
Segmentation in the Global White Shrimp Market determines pricing power, logistics requirements, and regulatory exposure across distinct value chains. Product form and distribution channel selection directly shape margin capture for producers in Ecuador, Vietnam, and Indonesia.
Product Type:
Premium margin pools concentrate in value-added processing tiers where labor input and certification compliance create defendable price positions.
- Frozen:Individually quick-frozen blocks and retail bags dominate cross-border trade flows due to shelf stability and suitability for containerized logistics. Demand concentrates in North American retail and European foodservice channels where EU Regulation 853/2004 traceability requirements favor suppliers with documented cold chain custody. Frozen commands the largest revenue share but faces compression from private-label commoditization.
- Cooked:Pre-cooked and value-added products including breaded, marinated, and ready-to-eat formats capture higher unit economics through convenience positioning. Southeast Asian food processing industries in Vietnam and Thailand are scaling procurement of cooked segments for supermarket deli counters and quick-service restaurant supply chains. Cooked is rotating up the share rankings.
- Fresh:Chilled whole shrimp with limited shelf life serves premium restaurant and retail segments in proximate markets. Fresh holds installed capacity concentrated in coastal distribution zones within 48 hours of harvest.
- Dried:Traditional preservation for ethnic food markets and ingredient applications in East Asian cuisine. Dried maintains niche positioning with stable but limited expansion trajectory.
Frozen holds installed capacity. Cooked is rotating up the share rankings.
Distribution Channel:
Channel selection determines working capital intensity and brand control, with direct routes capturing margin previously lost to intermediary layers.
- E-commerce:Frozen seafood platforms in China and South Korea are bypassing traditional wholesale tiers, enabling branded producers to access retail margin pools. Direct-to-consumer fulfillment requires cold chain infrastructure investment but reduces dependency on distributor pricing power. E-commerce is climbing the fastest among channel categories.
- Wholesale:Traditional distributor networks remain the volume anchor for restaurant chains and food processing buyers requiring consistent large-lot supply. Wholesale relationships in North America and Europe depend on ASC certification and HACCP documentation for market access.
- Retail:Supermarket and hypermarket chains in Germany, Japan, and the United States specify product origin, traceability, and sustainability credentials as shelf-space conditions. Retail procurement teams are unbundling shrimp from broadline contracts into standalone protein categories.
- Direct Sales:Processor-to-buyer relationships for institutional foodservice and export trading houses. Direct sales concentrate in Ecuadorian and Indian operations with established quality assurance protocols.
Wholesale maintains the broadest installed capacity. E-commerce is climbing the fastest.
End User:
Customer type dictates specification complexity, with food processing demanding consistent sizing and households prioritizing convenience formats.
- Food Processing:Industrial buyers in Southeast Asia require standardized count-per-kilogram specifications for breaded, battered, and further-processed product lines. Food processing contracts typically run 12-24 months with penalty clauses for antibiotic residue violations.
- Restaurants:Foodservice distributors in North American regional chains now negotiate directly with Ecuadorian and Indian processors rather than relying on national broadline programs. Restaurant procurement prioritizes tail-on, peeled, and deveined formats for kitchen labor reduction.
- Household:Retail consumers in urban China and South Korea drive demand for convenience-oriented frozen and pre-cooked portions. Household purchasing responds to e-commerce promotional cycles and sustainability labeling claims.
- Exporters:Trading houses and re-export operations in Vietnam and Thailand consolidate volumes for redistribution to secondary markets. Exporters depend on EU and US FDA import eligibility certifications.
Food Processing holds installed capacity. Restaurants are rotating up the share rankings.
Harvest Method:
Production system selection determines biosecurity risk, capital intensity, and certification timeline exposure for farm operators.
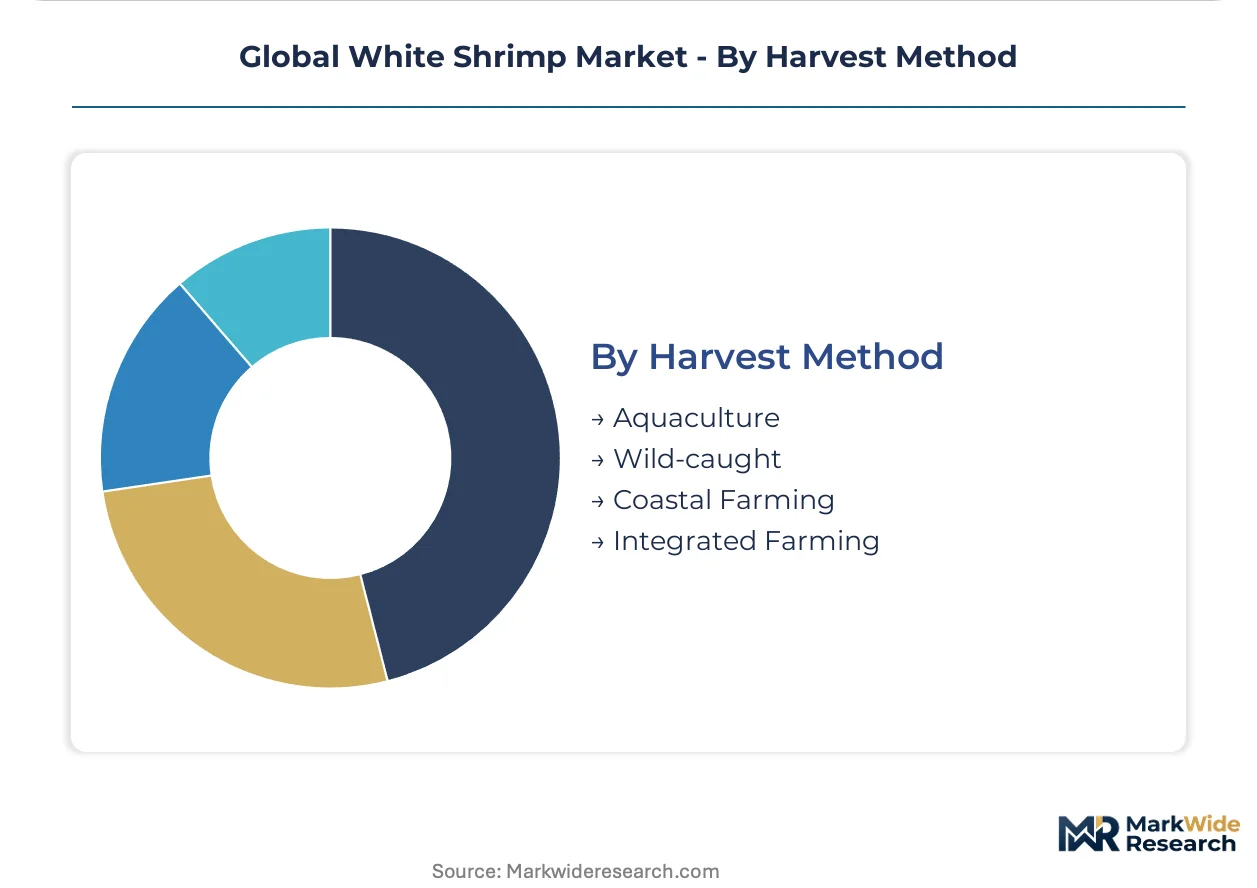
- Aquaculture:Intensive pond-based systems in Ecuador and Vietnam deploy automated aeration and sensor-based water quality monitoring to lift yields per hectare. Aquaculture dominates volume supply but faces ASC certification compliance costs and feed price volatility.
- Wild-caught:Ocean harvest operations in the Gulf of Mexico and Pacific coasts of Mexico supply differentiated traceability claims for premium retail positioning. Wild-caught maintains limited global volume share due to quota constraints and seasonal availability.
- Coastal Farming:Semi-intensive brackish water ponds in Bangladesh and coastal Vietnam face salinity intrusion and extreme weather vulnerability. Coastal farming operations concentrate in regions with limited veterinary infrastructure.
- Integrated Farming:Rice-shrimp rotational systems and mangrove-associated production in Indonesia and Thailand offer lower intensity with reduced environmental compliance burdens. Integrated farming serves sustainability-conscious European buyers.
Aquaculture holds installed capacity. Integrated Farming is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal supply chain due diligence requirements are redirecting procurement flows toward certified producers in Ecuador, Vietnam, and Indonesia. National biosafety protocols in major producing countries are tightening veterinary oversight and documentation standards. Processing capacity is clustering near coastal farming zones with cold chain infrastructure to serve European and North American import channels.
Ecuador
Intensive pond expansion in Guayas and El Oro provinces is lifting yields through automated aeration systems. The national aquaculture biosafety protocol mandates farm-level disease surveillance and antibiotic-free certification for export eligibility. Processing clusters in Guayaquil and Manta are integrating direct-to-retail contracts with US and EU buyers.
Vietnam
Southeast Asian food processing industries are scaling cooked and value-added shrimp procurement for supermarket deli and quick-service channels. EU Regulation 853/2004 traceability requirements are streamlining cross-border trade for certified exporters with documented cold chain custody. Mekong Delta operations in Bạc Liêu and Cà Mau face salinity intrusion risks while adopting sensor-based water quality monitoring.
Indonesia
Rice-shrimp rotational systems in Sulawesi and Java are serving sustainability-conscious European buyers with lower environmental compliance burdens. The country's national food safety authority enforces HACCP documentation for export processing establishments. Integrated farming clusters in South Sulawesi are expanding ASC-certified pond area to meet EU Green Deal disclosure timelines.
United States
Regional restaurant chains with 50-200 unit footprints are unbundling shrimp procurement from broadline distributor contracts. FDA Hazard Analysis Critical Control Point rules disqualify shipments with antibiotic residue violations, forcing pre-export laboratory screening. Gulf Coast wild-caught operations in Louisiana and Texas supply differentiated traceability claims for premium retail positioning.
Thailand
Integrated feed-to-table operations leverage captive supply chains across coastal farming zones and processing facilities. The national fisheries department enforces aquaculture veterinarian licensing for farm biosecurity management. Bangkok-based processing clusters are scaling value-added product lines for European retail channels under ASC certification protocols.
Global White Shrimp Market Competitive Environment
Listed leaders compete with private specialists across certification tiers and channel access. The vendor base concentrates around integrated feed-to-table operators, frozen commodity traders, and wild-caught differentiators. Three archetypes dominate: capital-intensive certifiers with documented chain-of-custody systems, volume processors serving private-label retail, and premium-positioned wild-caught specialists. Competitive moves center on ASC certification acceleration and direct procurement relationships with regional restaurant chains.
Within the integrated operator tier, Charoen Pokphand Foods PCL and Thai Union Group PCL exemplify feed-to-table control spanning hatchery through retail shelf placement. Clearwater Seafoods occupies a position as the wild-caught traceability anchor for North American premium retail channels. These three entities represent the strategic poles—captive supply integration, frozen value-added scale, and differentiated sourcing claims—around which procurement departments structure supplier qualification.
| Leading Market Players |
|---|
| Thai Union Group PCL |
| Charoen Pokphand Foods PCL |
| Avanti Feeds Limited |
| Aqua Star |
| Clearwater Seafoods |
| High Liner Foods |
| Nordic Seafood A/S |
| Apex Frozen Foods Ltd |
| Grupo Ibérica Congelados S.A. |
| Others |
Value Chain & Pricing Dynamics
Ninety-to-one-hundred-twenty-day harvest cycles in Ecuadorian and Vietnamese intensive ponds compress working capital turns while concentrating pricing power among ASC-certified operators with documented cold chain custody. This lead-time band feeds directly into contract structures where certification status commands shelf-space premiums in EU and North American retail channels.
Pricing Analysis
Certification level (ASC/FDA-grade) creates the primary spread between farm-gate and retail price tiers, with antibiotic-free and carbon-disclosed product lines capturing margin pools above commodity frozen blocks. Contract-based long-term offtake dominates institutional procurement, while spot-market transactions concentrate in secondary trading hubs. Price differentiation hinges on traceability documentation and EU Green Deal compliance readiness, with feed cost volatility intensifying pressure on non-integrated operators. Food processing buyers exhibit highest price sensitivity due to standardized count-per-kilogram specifications, while premium retail channels absorb certification premiums with limited volume elasticity.
Supply Chain Analysis
Panama Canal transit and refrigerated container availability at Guayaquil and Ho Chi Minh City ports underwrite cross-border delivery reliability for frozen product flows. Geographic supply concentrates in Ecuador, Vietnam, and Indonesia, with processing capacity clustering near coastal farming zones in Guayas, Bạc Liêu, and South Sulawesi. Raw material dependencies center on Peruvian fishmeal, Brazilian soybean meal, and hatchery-specific broodstock lines. Single-source vulnerability in veterinary diagnostics equipment feeds from concentrated supplier bases in Thailand. Distribution runs through wholesale networks anchored in European foodservice and North American retail procurement, with e-commerce platforms in China and South Korea emerging as direct-to-consumer alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
White shrimp aquaculture sits in early-cycle expansion as EU Corporate Sustainability Reporting Directive disclosure timelines force procurement departments toward pre-qualified ASC-certified suppliers with verified lifecycle assessments.
For Market Incumbents: Compound certification acceleration by compressing audit remediation cycles below twelve-month benchmarks while deepening backward integration into captive feed mill operations. Disease surveillance protocols and antibiotic-free positioning defend against emerging recirculating aquaculture system competitors in Japan and Germany. Channel control through direct processor-to-restaurant contracts with North American regional chains locks out distributor intermediaries. For New Entrants and Emerging Players: Anchor in integrated farming segments serving sustainability-conscious European buyers, where rice-shrimp rotational systems in Indonesian Sulawesi face lower ASC compliance burdens than intensive pond conversions. Carbon footprint disclosure readiness represents the most penetrable white-space target as EU Green Deal enforcement accelerates. E-commerce direct-to-consumer fulfillment in South Korean frozen seafood platforms offers a defensible go-to-market angle bypassing wholesale margin capture. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agribusiness parents with under-monetized aquaculture divisions lacking ASC certification infrastructure. Long-term viability frames around five-to-ten-year windows where regulatory disclosure mandates consolidate procurement toward documented chain-of-custody operators. Mid-scale Vietnamese and Ecuadorian operators with twenty-to-fifty-hectare intensive pond footprints and automated feeding deployment represent the priority acquisition archetype. The signal to watch is EU import rejection rates for antibiotic residue violations, which indicate enforcement intensity and certification premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| ASC Certification Acceleration | Twelve-to-eighteen-month audit cycles lock in market access before EU Green Deal enforcement tightens procurement eligibility. |
| Backward Integration into Feed Production | Captive fishmeal and soybean meal sourcing insulates margins from Peruvian anchovy quota volatility and South American crop cycles. |
| Direct Processor-to-Restaurant Contracts | Unbundling from broadline distributors captures margin pools previously lost to intermediary pricing power in North American foodservice. |
| Carbon Footprint Disclosure Systems | Verified lifecycle assessments create first-mover advantage under EU Corporate Sustainability Reporting Directive supply chain due diligence. |
| Automated Feeding System Deployment | Acoustic sensor-based appetite detection in Vietnamese and Ecuadorian ponds compresses feed conversion ratios by fifteen-to-twenty percent. |
Study Parameters
The analysis maps frozen, cooked, fresh, and dried product segments, each validated through hatchery operators, feed mill procurement managers, processing plant quality assurance heads, and EU retail category buyers. Primary interviews with aquaculture veterinarians and cold chain logistics providers combined with secondary validation against customs trade records, ASC certification databases, FDA import refusal logs, and EU Rapid Alert System for Food and Feed notifications. Bottom-up farm-level production estimates triangulated against top-down import volume data from North American and European customs authorities.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled product form, distribution channel, end-user category, and harvest method dimensions alongside regional regulatory cluster variations. CAGRs derived from historical trajectory analysis and adoption curve positioning for automated aeration and sensor-based monitoring technologies. Industry-specific forecast inputs incorporated fishmeal price volatility indices and EU Green Deal implementation timelines.
Material uncertainties — disease outbreak severity, climate-driven salinity intrusion in Mekong Delta operations, and feed input cost spikes — sit outside the modeled envelope. Forecasts reflect assumptions about certification penetration rates and enforcement consistency for antibiotic residue testing. Practitioners should keep alternative scenarios live as EU supply chain due diligence requirements and carbon disclosure mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Striped Bass Market
Seafood
Alaskan Salmon Market
Seafood
Fish Oil Market
Seafood
Haddock Market
Seafood
Crustacean Market
Seafood
Fish Protein Concentrate Market
Seafood
Dried Scallop Market
Seafood
Processed Seafood and Seafood Processing Equipment Market
Seafood
Canned Tuna Market
Seafood
Seafood Powders Market
Seafood
European Frozen Seafood Market
Seafood
Saudi Arabia Seafood Market
Seafood
Herring Market
Seafood
Lobster Market
Seafood
Wild Pollock Market
Seafood
COD Market