
 North America Frozen and Canned Seafood Market | 2026-2036
North America Frozen and Canned Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
North America Frozen and Canned Seafood Market Analytics
The gap between premium line-caught offerings and mass-market commodity packs is broadening across North American retail shelves. High Liner Foods leverages its integrated North Atlantic supply chain to dominate the frozen whitefish category. Trident Seafoods sustains its Alaska-based harvesting and processing network to anchor the premium wild-caught salmon segment. StarKist competes aggressively on price in canned tuna, occupying the value tier through high-volume production.
North America frozen and canned seafood comprises finfish, crustaceans, and mollusks preserved through blast freezing at minus 40 degrees Celsius or thermal processing in hermetically sealed containers, primarily serving shelf-stable protein distribution and year-round species availability. Frozen shrimp leads volume growth among product types due to its centrality in food service menus and home meal preparation. Canned tuna remains the mature profit pool, with margin concentration in branded retail packs rather than private-label bulk formats. Supermarkets and wholesale channels together control the majority of distribution throughput, though online retail is gaining traction in direct-to-consumer frozen shipments.
FDA HACCP regulations and NOAA fisheries management standards govern harvest quotas, processing sanitation, and species labeling across U.S. operations, while CFIA enforces parallel safety protocols in Canada. These frameworks elevate compliance costs for smaller processors but also create barriers that reinforce established supply networks. Stakeholders must monitor quota allocations under the Magnuson-Stevens Act and emerging traceability mandates that will reshape sourcing verification requirements.
Market Dynamics
Frozen shrimp procurement volumes from quick-service chains are compressing margins across the Gulf Coast processing corridor, forcing operators to automate filleting lines and consolidate cold-chain assets.
Growth Catalysts
- Food service procurement concentration:Quick-service chains in the U.S. are locking in multi-year frozen shrimp contracts, guaranteeing throughput for Louisiana and Texas processors.
- FDA HACCP enforcement:Pathogen control mandates at processing facilities are accelerating capital deployment into blast freezing infrastructure.
- Blast freezing at minus 40 degrees Celsius:This preservation technology is extending shelf life for finfish exports from the Gulf Coast to inland distribution hubs.
Market Restraints
- Fuel cost volatility:Diesel price swings directly impact refrigerated trucking rates between Gulf Coast processing plants and Midwest retail distribution centers.
- Harvest quota concentration:Magnuson-Stevens Act allocations concentrate pollock and cod access among Alaska-based catcher-processor fleets.
- Wild stock variability:Pacific salmon run fluctuations create supply uncertainty for premium canned and frozen product lines.
Strategic Opportunities
- Direct-to-consumer frozen shipments:Insulated packaging innovations are opening e-commerce channels previously blocked by cold-chain reliability concerns.
- CFIA-parallel safety protocols:Canadian import alignment with FDA standards creates cross-border sourcing flexibility for U.S. distributors.
- Traceability mandate preparation:Early compliance with emerging NOAA sourcing verification requirements will secure preferential retail placement.
Industry Challenges
- HACCP certification timelines:New processing facilities face extended FDA approval periods before commercial operations can commence.
- Automated filleting integration:Legacy gutting and heading lines require substantial retrofit capital to achieve labor cost targets.
- Skilled refrigeration technician scarcity:Ammonia-based blast freezing systems demand specialized maintenance talent concentrated in port cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Frozen and Canned Seafood Market |
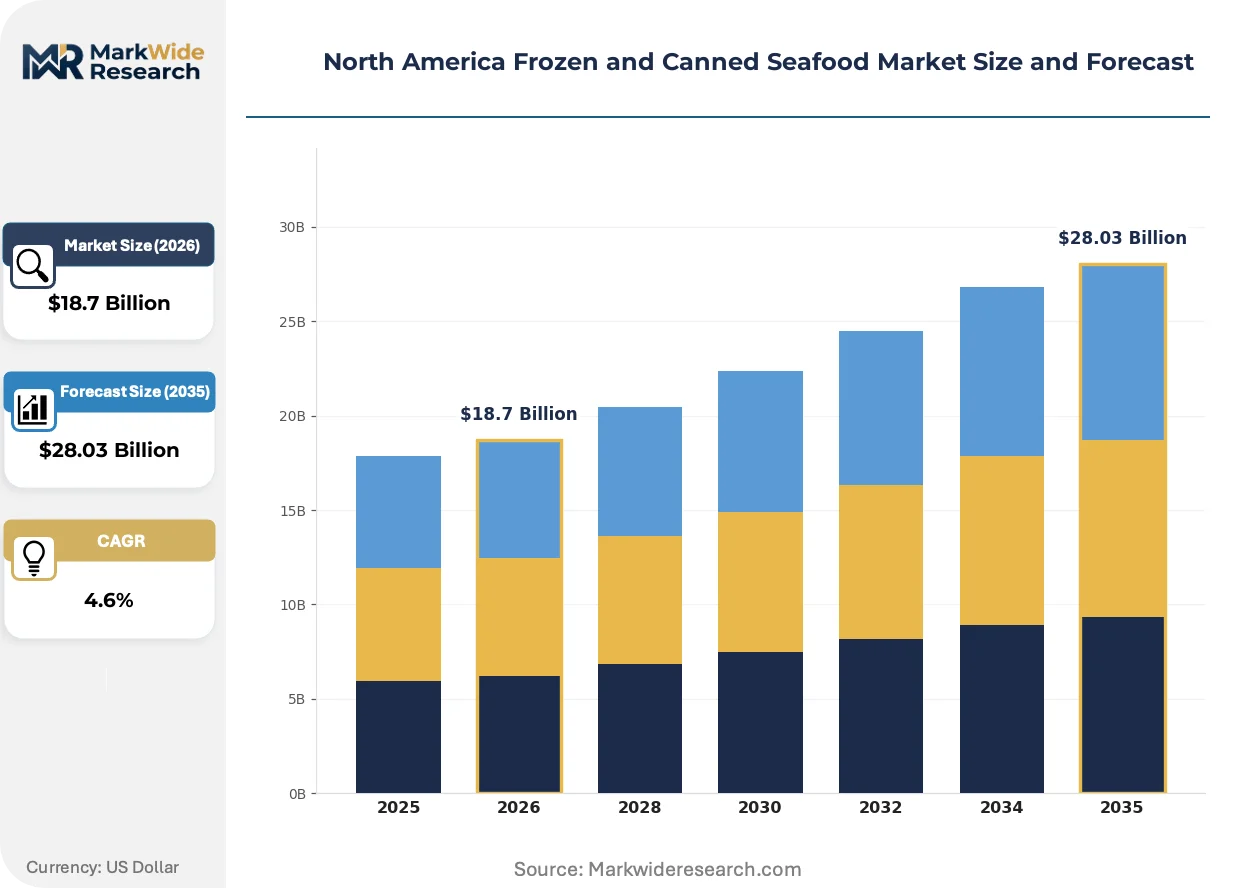
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Fish, Canned Tuna, Canned Salmon, Frozen Shrimp Packaging Type: Bulk, Retail Packs, Vacuum Sealed, Cans Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale End User: Restaurants, Households, Food Service, Catering |
| Companies Covered | High Liner Foods Inc., Trident Seafoods Corporation, Thai Union Group PCL, Mowi ASA, Bolton Group SRL, Bumble Bee Seafoods, Gorton's, StarKist Co., SeaPak, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Frozen and Canned Seafood Market Evolving Landscape
Processing automation and regulatory traceability mandates are restructuring competitive advantage around capital intensity and supply-chain transparency rather than raw harvest access alone.
Individual quick freezing technology is electrifying whitefish processing economics. Mid-scale Gulf Coast operators are adopting IQF tunnel systems to replace block freezing lines. This equipment transition is electrifying margin recovery on lower-grade fillets previously diverted to commodity channels.
The FDA's emerging traceability rule under the Food Safety Modernization Act is mandating electronic record-keeping from harvest through retail. Processing facilities must upgrade data infrastructure to capture lot codes and temperature logs. Smaller canneries in the Pacific Northwest are consolidating to shared compliance platforms rather than bearing individual system costs.
Meal-kit subscription services are pulling frozen seafood into portion-controlled, recipe-ready formats. These channels bypass traditional wholesale distribution through direct fulfillment centers in Dallas and Chicago. The shift is most visible among dual-income households in Texas and Illinois seeking convenience without restaurant price points.
North America Frozen and Canned Seafood Market Segmentation
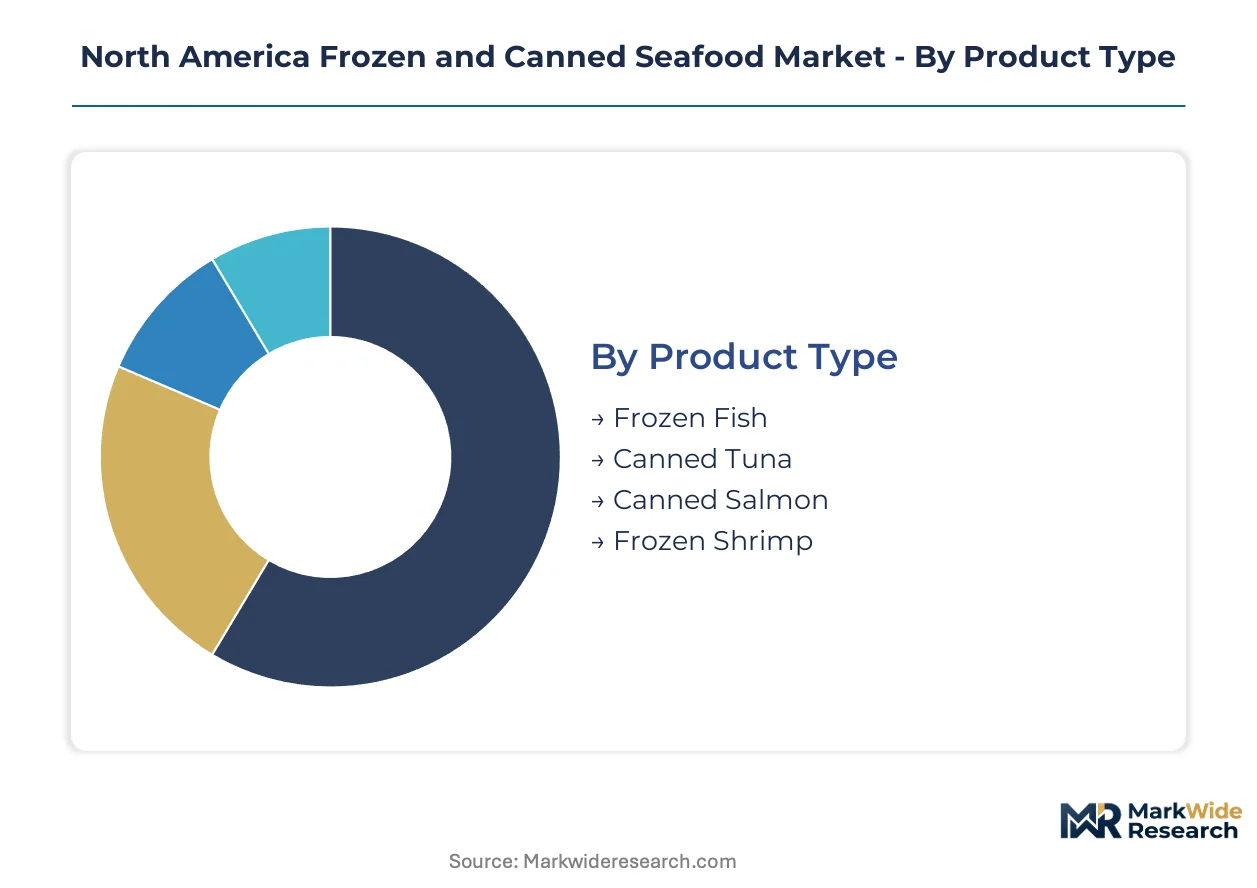
Capital allocation across segments in the North America frozen and canned seafood market follows divergent equipment and compliance requirements. Processing infrastructure for blast freezing demands substantially different investment profiles than thermal canning lines, shaping where private equity and strategic buyers deploy capital.
Product Type:
Frozen shrimp and canned tuna command the heaviest upfront capital outlays due to specialized blast freezing tunnels and retort sterilization systems respectively.
- Frozen Fish:Whitefish varieties including pollock, cod, and haddock undergo blast freezing at minus 40 degrees Celsius immediately after filleting. Gulf Coast processors from Louisiana through Texas concentrate capacity here to serve quick-service chain procurement contracts.
- Canned Tuna:Skipjack and albacore species are precooked, cleaned, and thermally processed in hermetically sealed containers under FDA HACCP protocols. Branded retail packs capture margin concentration while private-label bulk formats compete on volume.
- Canned Salmon:Wild-caught Pacific species are processed in Alaska-based facilities with seasonal harvesting windows limiting annual throughput. Shelf-stable protein distribution relies on this segment for year-round species availability.
- Frozen Shrimp:IQF tunnel systems are electrifying processing economics for mid-scale Gulf Coast operators replacing block freezing lines. Food service procurement concentration is compressing margins and accelerating automation adoption.
Frozen shrimp absorbs the bulk of installed capacity; frozen fish is expanding most quickly through IQF technology deployment.
Packaging Type:
Packaging selection tracks directly through distribution channel economics and cold-chain reliability requirements.
- Bulk:Institutional formats serve food service and catering channels with 10-20 pound cases minimizing per-unit handling costs. Wholesale distributors control throughput for this segment.
- Retail Packs:Consumer-facing units ranging from 8-16 ounces dominate supermarket shelf space. Canned tuna margin concentration resides here rather than in private-label alternatives.
- Vacuum Sealed:Modified atmosphere packaging extends shelf life for premium finfish cuts. Direct-to-consumer frozen shipments increasingly rely on this format for e-commerce fulfillment.
- Cans:Hermetically sealed containers remain the mature profit pool for shelf-stable protein distribution. Retort infrastructure requirements create barriers for new entrants.
Retail packs command the highest per-unit margins; vacuum sealed formats are climbing the fastest as online retail penetration deepens.
Distribution Channel:
Channel selection determines cold-chain investment intensity and regulatory compliance scope.
- Supermarkets:Traditional retail anchors frozen seafood volume through dedicated freezer cases and promotional cycling. High Liner Foods and Trident Seafoods maintain preferred supplier status with major chains.
- Online Retail:Insulated packaging innovations are opening e-commerce channels previously blocked by cold-chain reliability concerns. Dallas and Chicago fulfillment centers bypass traditional wholesale distribution.
- Convenience Stores:Limited freezer space restricts assortment to high-velocity canned tuna and single-serve frozen items. StarKist competes aggressively on price for shelf-stable placement.
- Wholesale:Club and cash-and-carry formats aggregate volume for restaurants and catering operations. Refrigerated trucking rates between Gulf Coast processing plants and Midwest distribution centers directly impact channel economics.
Supermarkets retain the largest throughput share; online retail is gaining the fastest traction in direct-to-consumer frozen shipments.
End User:
End-user segmentation separates volume-scale procurement from premium positioning strategies.
- Restaurants:Quick-service chains lock in multi-year frozen shrimp contracts guaranteeing throughput for Louisiana and Texas processors. Menu standardization drives species consistency requirements.
- Households:Dual-income households in Texas and Illinois seek convenience without restaurant price points. Meal-kit subscription services are pulling frozen seafood into portion-controlled formats.
- Food Service:Institutional operators including schools, hospitals, and corporate cafeterias prioritize cost predictability and supply security. HACCP certification timelines create vendor stickiness.
- Catering:Event-based demand concentrates in bulk formats with seasonal peaks around holidays and summer wedding seasons. Smaller canneries in the Pacific Northwest serve this channel through shared compliance platforms.
Restaurants absorb the bulk of procurement volume; households are expanding most quickly through meal-kit and direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast processing corridor from Louisiana through Texas anchors North American frozen seafood activity, with Houston and New Orleans serving as the primary logistics hubs for shrimp and finfish distribution into Midwest retail networks.
United States
Quick-service chains lock in multi-year frozen shrimp contracts that guarantee throughput for Gulf Coast processors. FDA HACCP enforcement mandates pathogen controls at processing facilities, accelerating capital deployment into blast freezing infrastructure. The Louisiana-Texas corridor concentrates automated filleting capacity to serve food service procurement volumes.
Canada
Atlantic provinces supply premium wild-caught species to U.S. retail and food service channels. CFIA enforces parallel safety protocols with FDA standards, creating cross-border sourcing flexibility for distributors. Vancouver and Halifax maintain cold-chain export capacity for Pacific and Atlantic harvests respectively.
Mexico
Pacific coast shrimp farms supply raw material to U.S. processing facilities across the border. Mexican fisheries regulators coordinate harvest quotas with NOAA management standards for species consistency. Guaymas and Mazatlán serve as primary consolidation points for farmed shrimp exports.
North America Frozen and Canned Seafood Market Competitive Landscape
Capital-heavy producers compete with asset-light brand licensors across tiered competitive positions. Integrated harvesters with captive fishing fleets and shore-based processing plants occupy the premium wild-caught segment. Contract processors relying on third-party raw material supply compete on volume throughput for food service accounts. Brand licensors without production assets capture retail margin through marketing investment and distribution relationships. Consolidation pressure favors players with HACCP-certified infrastructure and established retail placement.
Within the integrated harvester tier, Trident Seafoods Corporation and High Liner Foods Inc. exemplify contrasting geographic strategies—Alaska-based wild-caught specialization versus North Atlantic whitefish integration. StarKist Co. occupies the value-tier branded position through high-volume canned tuna production. These three entities represent the dominant archetypes: wild-catch integration, supply-chain control, and price-competitive branding.
| Leading Market Players |
|---|
| High Liner Foods Inc. |
| Trident Seafoods Corporation |
| Thai Union Group PCL |
| Mowi ASA |
| Bolton Group SRL |
| Bumble Bee Seafoods |
| Gorton's |
| StarKist Co. |
| SeaPak |
| Others |
Value Network & Pricing Analysis
The premium-wild-caught versus commodity-farmed divergence separates pricing power from volume throughput across North American seafood channels. FDA HACCP certification tiers anchor value-based premiums for Alaska salmon and Gulf shrimp, while unbranded block-frozen imports compete on spot-market thinness.
Pricing Analysis
Value-based pricing tied to harvest method and traceability documentation anchors the premium tier. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and brand equity, with Trident Seafoods and High Liner Foods commanding shelf-space premiums. Cost compression in food service-contracted frozen shrimp is intensifying because quick-service chains leverage procurement concentration for volume discounts. Private-label canned tuna buyers exhibit highest price sensitivity; wild-caught certification holders show lowest.
Supply Chain Analysis
Domestic-content rules under the Magnuson-Stevens Act and Buy American provisions for institutional procurement are reshaping sourcing toward U.S. Gulf Coast and Alaska operations. Supply concentrates in the United States, Canada, and Mexico, with Pacific coast shrimp farms feeding cross-border processing. Raw material dependencies include wild Pacific salmon runs, farmed shrimp larvae, and fuel for refrigerated trucking fleets. Single-source vulnerability from Pacific salmon stock fluctuations threatens premium canned product lines. Distribution runs through Houston and New Orleans cold-chain hubs into Midwest retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure favors HACCP-certified operators with established retail placement, as compliance capital requirements force smaller canneries toward shared platforms or exit.
For Market Incumbents: To counter margin compression from food service procurement concentration, automate filleting lines in Louisiana-Texas corridor facilities and deepen backward integration into Alaska catcher-processor fleets. Certification investment in early FDA traceability rule compliance secures preferential retail placement against delayed rivals. For New Entrants and Emerging Players: Direct-to-consumer frozen shipments through Dallas and Chicago fulfillment centers offer the most penetrable route, bypassing wholesale distributor control. Target vacuum-sealed premium finfish for dual-income households in Texas and Illinois seeking convenience without restaurant price points. White space exists in meal-kit subscription recipe-ready formats. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale Gulf Coast processors given IQF automation catalysts and multi-year quick-service contract visibility. Long-term viability over a five-to-ten year window favors operators with integrated North Atlantic or Alaska supply chains. Watch NOAA traceability mandate implementation timelines as inflection indicator for compliance-cost winners.| Strategic Initiative | Industry Significance |
|---|---|
| IQF Technology Deployment | Individual quick freezing electrifies margin recovery on lower-grade Gulf Coast fillets. |
| HACCP Infrastructure Investment | Blast freezing and pathogen controls satisfy FDA enforcement and create competitive moats. |
| Direct-to-Consumer Channel Launch | Insulated packaging innovations open e-commerce previously blocked by cold-chain reliability. |
| Traceability Compliance Platform | Electronic record-keeping from harvest through retail secures preferential placement under emerging rules. |
| Alaska Catcher-Processor Integration | Captive wild-caught salmon supply anchors premium positioning against commodity competitors. |
Research Methodology
Multi-period observation of frozen shrimp contract volumes, canned tuna retail pricing spreads, and HACCP certification timelines anchored the trend analysis, supplemented by interviews with Gulf Coast processing plant managers, quick-service chain procurement directors, FDA compliance officers, supermarket category buyers, and Alaska-based fleet operators. Secondary validation drew from NOAA fisheries landings data, FDA inspection records, CFIA import statistics, and SEC filings of publicly traded seafood processors. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates.
Segment-weighting across product type, packaging format, distribution channel, and end-user category shaped the analytical framework throughout the projection horizon. CAGRs derived from trend extrapolation of food service procurement growth, automation adoption curves, and regulatory implementation schedules. Forecast inputs included Magnuson-Stevens quota allocations, diesel price volatility assumptions for refrigerated trucking, and e-commerce penetration rates for frozen shipments.
The model holds under stable FDA enforcement intensity and intact Gulf Coast processing capacity; deviation in Pacific salmon run collapse or fuel price spikes would shift volume and value trajectories. Forecasts reflect documented assumptions about quick-service contract renewal rates and traceability rule phase-in timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Cod Fish Market
Seafood
Tinned Fish Market
Seafood
Oyster Meal Market
Seafood
Fresh Fish Market
Seafood
Rainbow Trout Market
Seafood
GCC Seafood Market
Seafood
Europe Lobster Market
Seafood
Mackerel Market
Seafood
Organic Salmon Market
Seafood
Fish Processing Market
Seafood
Canned Seafood Market
Seafood
European Frozen Seafood Market
Seafood
United States Frozen and Canned Seafood Market
Seafood
Fish Hydrolysate Market
Seafood
Fish Protein Hydrolysate Market
Seafood
Sea Bass Market