
 Fish Processing Market | 2026-2036
Fish Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Processing Market Analysis
Market Context
The capability gap between fully integrated processors and commodity-dependent operators is collapsing as automation costs fall and cold-chain logistics standardize. Mowi ASA leverages its hatchery-to-harvest control to sustain margin capture across Atlantic salmon value chains. Thai Union Group anchors its position through diversified species sourcing and retail-ready product development across European and Asian markets. Trident Seafoods competes from Alaska with shore-based processing dominance and direct fleet ownership.
Technical Definition and Structural Segments
Fish processing encompasses the transformation of whole or gutted fish into consumer-ready or industrial-input products through mechanical filleting, thermal smoking, salt curing, acid marination, or blast freezing to temperatures below minus 18 degrees Celsius, yielding shelf-stable or chilled outputs for human consumption and further food manufacturing. Frozen fish leads volume throughput due to extended distribution reach and foodservice dependency, while surimi commands premium positioning as a functional protein substrate for analog seafood manufacturing. Canned fish retains mature, price-sensitive demand concentrated in Southern European and Latin American retail channels, whereas dried fish occupies niche ethnic-market positions with limited scalability.
Regulatory Frame and Outlook
The EU's IUU Regulation, EFSA contaminant thresholds, and FDA Seafood HACCP requirements collectively elevate compliance costs and exclude non-certified suppliers from premium market access. Japan's Food Sanitation Act and METI labeling standards further constrain entry for exporters lacking documented cold-chain integrity and species verification. Stakeholders must monitor evolving traceability mandates and certification harmonization between major import jurisdictions to preserve market participation.
Market Dynamics
Automation in filleting and pin-boning lines is collapsing labor-cost differentials between high-wage and low-wage processing jurisdictions, forcing commodity operators to consolidate or exit as integrated players capture margin through yield optimization and traceability premiums.
Growth Catalysts
- EU IUU Regulation traceability mandates:The Illegal, Unreported and Unregulated Fishing Regulation now requires catch documentation at every supply chain node, creating competitive advantage for processors with verified chain-of-custody systems and excluding non-compliant suppliers from premium European retail channels.
- Surimi-based analog seafood:Plant-forward formulations using refined surimi as a functional protein substrate are penetrating foodservice and retail freezer cases, opening new volume outlets for Alaskan pollock and Pacific whiting processors with surimi-grade production lines.
- Norwegian aquaculture corridor concentration:Vertical integration from hatchery through primary processing in the Bergen-Stavanger axis is standardizing quality benchmarks and export logistics, pulling investment toward controlled-environment Atlantic salmon value chains.
Market Restraints
- Wild-catch input volatility:Quota fluctuations for key whitefish species in the Barents Sea and North Pacific create raw material cost instability that commodity processors cannot hedge effectively against contract pricing commitments.
- Energy-intensive cold-chain requirements:Blast freezing to minus 18 degrees Celsius and continuous cold storage impose electricity cost structures that disadvantage processors in jurisdictions without hydroelectric or nuclear baseload generation.
- Substitute protein competition:Cultivated meat and precision-fermented seafood proteins are attracting venture capital and pilot-scale production capacity, threatening long-term demand for conventional processed fish in premium consumer segments.
Strategic Opportunities
- Indian domestic retail modernization:Cold-chain infrastructure expansion in Maharashtra and Tamil Nadu is creating first-mover advantage for frozen and value-added fish product entrants as organized retail displaces traditional wet-market distribution.
- Blockchain-IoT traceability convergence:Integration of distributed ledger verification with temperature-logging sensors enables real-time quality attestation, unlocking price premiums in Japanese sashimi-grade and European organic-certified segments.
- US Inflation Reduction Act clean energy incentives:Tax credits for industrial electrification and renewable energy adoption reduce operating cost burdens for processors retrofitting freezing and refrigeration systems with heat pump and solar thermal technologies.
Industry Challenges
- Skilled filleting technician scarcity:Automation reduces but does not eliminate demand for hand-finishing expertise in high-value species, and training pipelines lag retirement outflows in traditional fishing communities along the North Sea and Gulf of Alaska.
- Multi-jurisdiction certification complexity:Simultaneous compliance with FDA Seafood HACCP, EFSA contaminant thresholds, and METI labeling standards extends product launch timelines and strains quality assurance staffing for exporters serving multiple premium markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Processing Market |
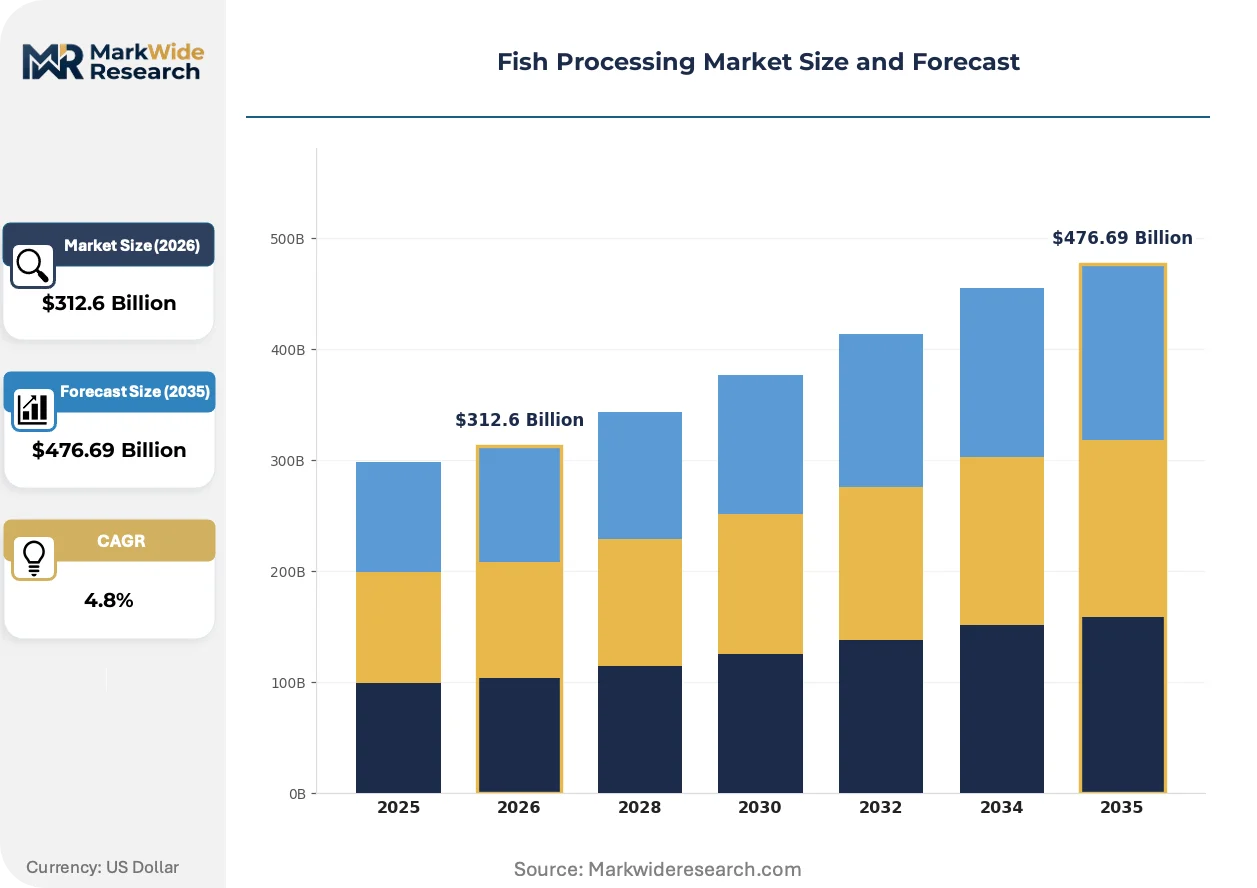
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $476.69 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Fish, Canned Fish, Dried Fish, Surimi Processing Method: Filleting, Smoking, Curing, Marinating End User: Restaurants, Retail Chains, Foodservice, Households Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales |
| Companies Covered | Maruha Nichiro Corporation, Thai Union Group, Mowi ASA, Nippon Suisan Kaisha, Charoen Pokphand Foods PCL, Lerøy Seafood Group, Trident Seafoods, Royal Greenland A/S, Austevoll Seafood ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Processing Market Emerging Trajectories
Processing technology and supply chain verification systems are restructuring competitive advantage around yield precision and provenance transparency rather than scale alone. Three developments are compressing legacy operating models.
Hyperspectral imaging systems for real-time flesh-quality assessment are supplanting manual grading and destructive sampling in primary processing lines. Nordic and Japanese salmon processors are deploying these systems at line speeds exceeding 50 fillets per minute. The technology is compressing quality variation and reducing giveaway in portion-cutting operations.
REACH chemical authorization requirements and the EU Green Deal's carbon-border adjustment mechanism are elevating documentation burdens for processors using conventional refrigerants and fossil thermal energy. Operators in Poland and Spain are retrofitting ammonia-based refrigeration and biomass boilers to preserve market access. Smaller Mediterranean canneries lacking capital for compliance face exclusion from core export channels.
Direct-procurement relationships between retail chains and vessel operators are disintermediating traditional auction and broker channels in whitefish supply. British and German supermarket groups now contract frozen-at-sea trawlers for exclusive species-volume commitments. The shift is most visible in North Atlantic cod and haddock flows, where price discovery is migrating from commodity exchanges to bilateral negotiation.
Fish Processing Market Segmentation
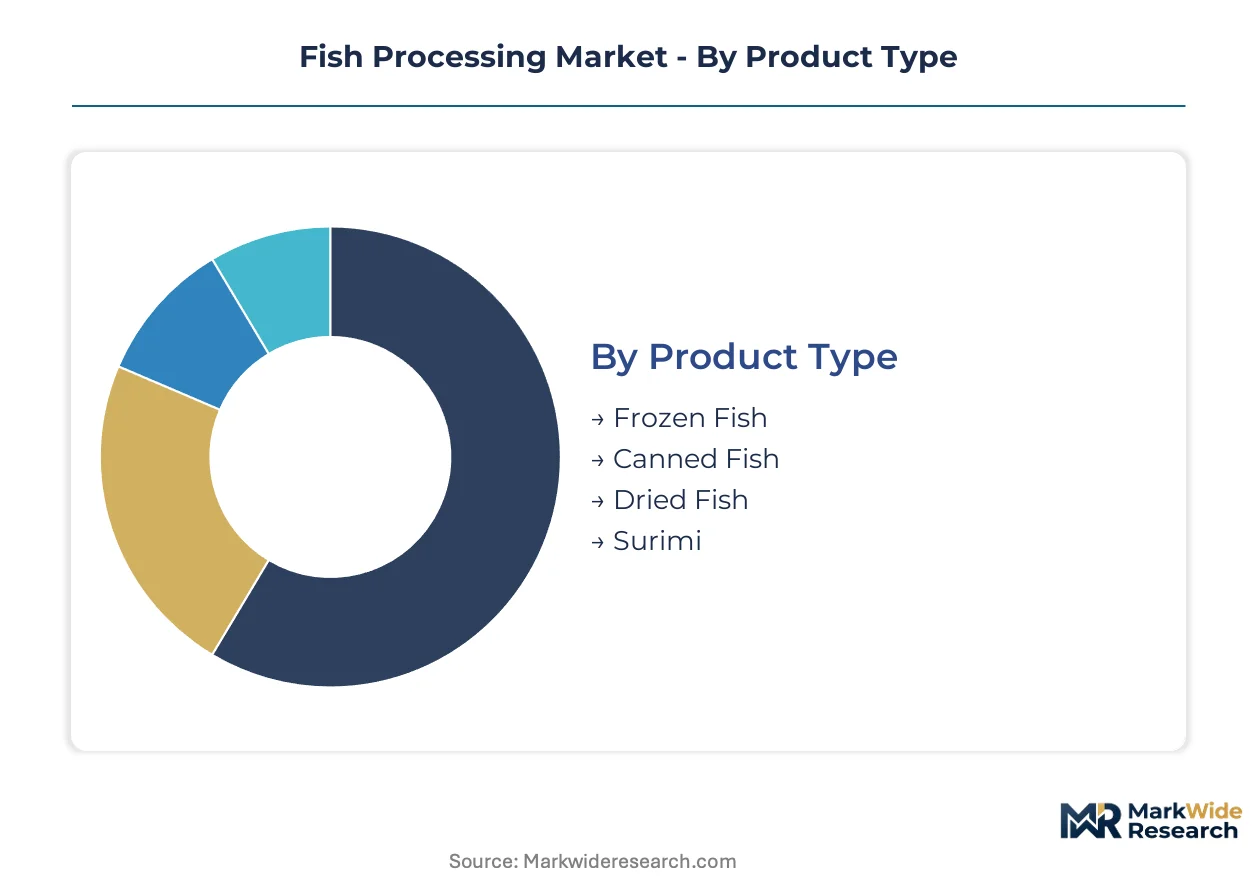
Segmentation in fish processing reveals how product form, processing intensity, and channel access determine margin capture and geographic reach. Each dimension exposes different competitive dynamics between commodity throughput and premium positioning.
Product Type:
Domestic consumption concentrates in chilled and short-shelf-life formats, while export flows dominate frozen and surimi categories due to cold-chain infrastructure requirements.
- Frozen Fish:Blast-frozen fillets and whole fish at minus 18 degrees Celsius enable transoceanic distribution and foodservice procurement at scale. Norwegian and Alaskan processors anchor supply into European and Asian retail chains where extended shelf life reduces inventory risk.
- Surimi:Refined, washed fish protein paste serves as the functional substrate for crab analogs and value-added seafood products. Japanese and South Korean food manufacturers drive demand for high-grade Alaska pollock surimi, with pricing tied to gel-strength specifications and color grade.
- Canned Fish:Thermal sterilization in hermetic containers yields shelf-stable products for price-sensitive Southern European and Latin American retail channels.
- Dried Fish:Salt-cured and dehydrated products occupy ethnic-market niches with limited scalability beyond West African and Southeast Asian diaspora communities.
Frozen fish commands the established base. The steepest expansion runs through surimi as plant-forward analog formulations penetrate mainstream retail freezer cases.
Processing Method:
Capital intensity and labor skill requirements create tiered margin structures, with automated mechanical operations scaling faster than craft-dependent traditional methods.
- Filleting:Mechanical pin-boning and portion-cutting lines achieve line speeds exceeding 50 fillets per minute with hyperspectral quality grading. Scottish and Chilean salmon processors deploy this automation to reduce labor dependency and standardize yield recovery rates.
- Smoking:Thermal smoking with controlled humidity and wood-species selection produces ready-to-eat delicatessen products. Baltic and Scottish smokehouses command price premiums in German and French retail through Protected Geographical Indication status and traditional production claims.
- Curing:Salt and acid preservation methods concentrate in Mediterranean basin operations serving Southern European ethnic markets.
- Marinating:Acid-based protein denaturation for ready-to-eat applications remains geographically concentrated in Scandinavian and Japanese specialty production.
Filleting dominates volume throughput. Smoking delivers the highest margin expansion trajectory through premium retail positioning and origin-based certification.
End User:
Contract stability and specification tolerance separate institutional buyers from fragmented household demand, with foodservice operators driving standardization in portion sizing and packaging formats.
- Restaurants:Full-service and casual dining operators demand consistent portion weights and species verification for menu transparency. North American and European chain operators now require blockchain-traceable documentation for whitefish and salmon procurement.
- Retail Chains:Supermarket private-label programs specify frozen and surimi products with exclusive volume commitments and direct-vessel contracting. British and German retailers disintermediate traditional auction channels for North Atlantic cod and haddock supply.
- Foodservice:Institutional catering and contract feeding operations prioritize frozen bulk formats with extended shelf stability and simplified preparation protocols.
- Households:Traditional wet-market purchasing persists in India and Southeast Asia, though cold-chain expansion in Maharashtra and Tamil Nadu is shifting volume toward organized retail frozen formats.
Retail chains anchor volume concentration. Restaurants are gaining share fastest through traceability premiums and species-verification requirements.
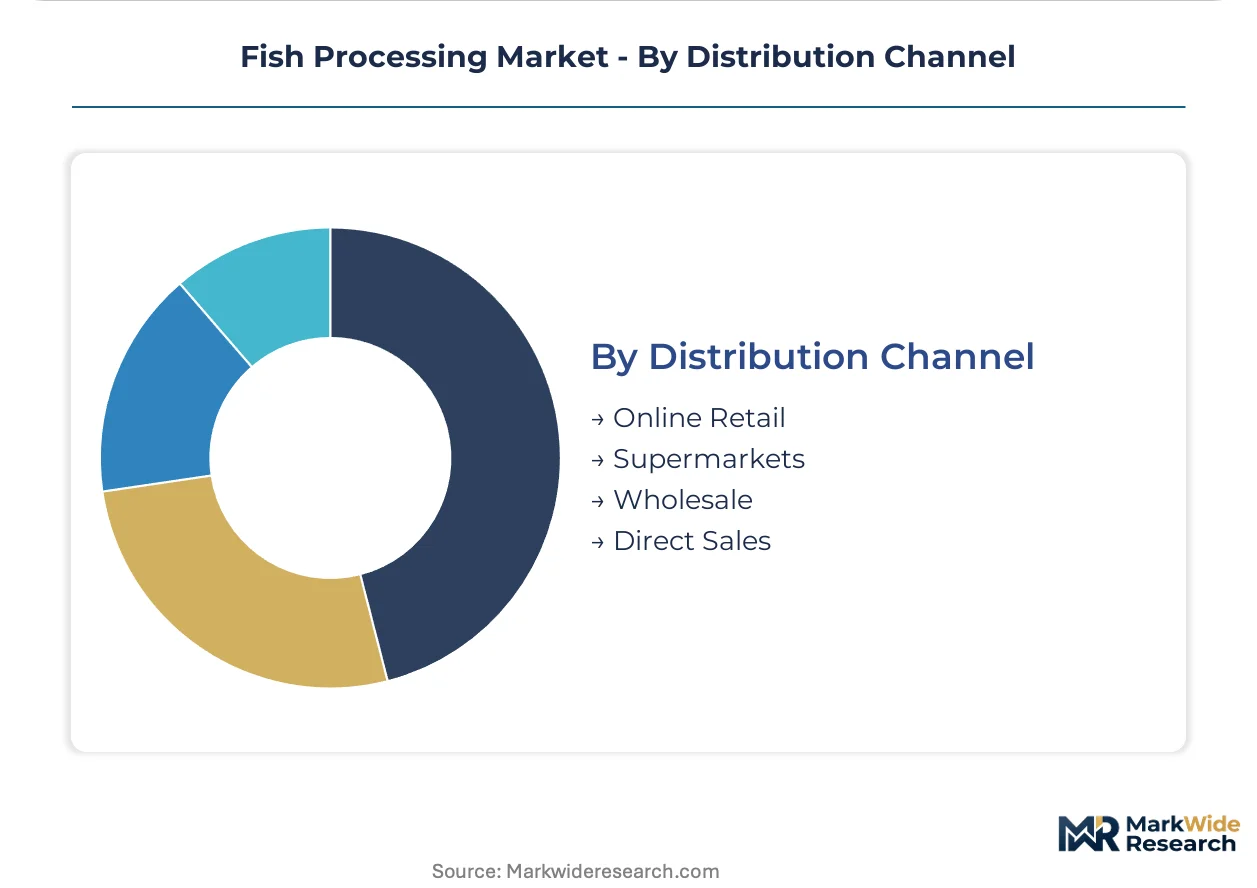
Distribution Channel:
Channel selection determines cold-chain integrity investment and working capital intensity, with direct procurement relationships restructuring traditional broker-mediated flows.
- Supermarkets:Multi-temperature logistics networks and private-label development programs create captive demand for processors with certified chain-of-custody systems. EU IUU Regulation compliance is now mandatory for shelf access in premium European retail.
- Wholesale:Traditional auction and broker channels persist for commodity whitefish, though price discovery is migrating toward bilateral negotiation as retail groups consolidate procurement.
- Online Retail:Direct-to-consumer frozen delivery requires last-mile cold-chain investment that favors processors with integrated logistics or third-party cold-storage partnerships.
- Direct Sales:Vessel-to-processor contracting eliminates intermediary margins for large-scale frozen-at-sea operators with dedicated fleet ownership.
Supermarkets control the established volume base. Online retail is climbing the fastest as urban household penetration of organized frozen food purchasing accelerates in Indian and Southeast Asian metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across consuming regions. Southern European retail channels absorb commodity canned fish with minimal substitution response, while Japanese and North American buyers demand verified provenance and pay substantial premiums for documented chain-of-custody.
Norway
Atlantic salmon aquaculture drives processing investment along the Bergen-Stavanger corridor. EU IUU Regulation traceability mandates favor Norwegian exporters with integrated hatchery-to-fillet control and blockchain-verified documentation. Vertical consolidation from farm to primary processing concentrates export-quality output in Rogaland and Hordaland counties.
United States
Alaska pollock and Pacific cod sustain frozen-at-sea operations serving foodservice and surimi manufacturers. FDA Seafood HACCP compliance costs exclude smaller shore-based processors from premium retail channels. Seattle-based fleet operators and Dutch Harbor processing hubs anchor North Pacific whitefish flows into Asian and European markets.
Japan
Sashimi-grade tuna and salmon consumption maintains exacting quality specifications for raw consumption. METI labeling standards and Food Sanitation Act requirements constrain entry to exporters with documented cold-chain integrity. Tokyo's Tsukiji successor market and Osaka distribution clusters set price benchmarks for premium chilled imports.
Thailand
Tuna canning and value-added seafood manufacturing serve European and North American private-label programs. EU tariff preferences under the Everything But Arms arrangement support export competitiveness for certified processors. Samut Sakhon and Songkhla industrial zones concentrate labor-intensive secondary processing for global retail chains.
Spain
Traditional canneries in Galicia and the Basque Country face REACH chemical authorization and EU Green Deal carbon-border pressures. Smaller Mediterranean operators lacking capital for ammonia refrigeration retrofits risk exclusion from core export channels. Vigo and Marin processing clusters pivot toward certified sustainable sourcing to preserve supermarket shelf access.
Fish Processing Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale and traceability systems determining margin capture. The upper tier controls hatchery, harvesting, and primary processing assets that command price premiums in verified-origin segments. Below them, species-specific specialists and regional canners compete on throughput efficiency and contract manufacturing relationships. Consolidation pressures favor operators with captive raw material supply and certified cold-chain documentation. Strategic moves concentrate on fleet and processing facility acquisitions, plus direct retail procurement relationships that disintermediate traditional broker channels.
Among integrated aquaculture operators, Mowi ASA and Lerøy Seafood Group exemplify the controlled-supply archetype with hatchery-to-export integration. Thai Union Group anchors the diversified-species tier, spanning tuna sourcing and value-added manufacturing across multiple geographies. At the wild-catch end, Trident Seafoods represents fleet-based processing dominance with shore-based capacity in Alaska.
| Leading Market Players |
|---|
| Maruha Nichiro Corporation |
| Thai Union Group |
| Mowi ASA |
| Nippon Suisan Kaisha |
| Charoen Pokphand Foods PCL |
| Lerøy Seafood Group |
| Trident Seafoods |
| Royal Greenland A/S |
| Austevoll Seafood ASA |
| Others |
Supply Flow & Price Mechanics
Blast-freezing capacity utilization above 85 percent in Norwegian and Alaskan processing corridors establishes price floors that smaller shore-based operators cannot match, compressing margins for commodity-dependent processors while integrated players capture premiums through verified chain-of-custody documentation.
Pricing Analysis
After-sales service contracts for cold-chain maintenance and traceability system updates generate recurring revenue that exceeds initial equipment sales for automation vendors serving filleting lines. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-verified sashimi-grade salmon from commodity frozen fillets and canned tuna. Pricing pressure stems from energy cost volatility in jurisdictions without hydroelectric baseload, squeezing operators reliant on fossil thermal inputs. Retail chains exhibit lowest price sensitivity for verified-origin products, while foodservice distributors remain most responsive to per-kilogram differentials.
Supply Chain Analysis
Inventory cycles stretching 90-120 days for frozen-at-sea whitefish create working capital intensity that favors fleet owners with integrated shore processing over broker-dependent traders. Raw material supply concentrates in Norway, Alaska, and Thailand, with Norwegian aquaculture corridors, Alaskan pollock grounds, and Thai tuna canning zones anchoring global throughput. Processor dependence on wild-catch quotas, aquaculture feed inputs, and refrigerated logistics capacity creates exposure to regulatory and climatic disruptions. Distribution runs through supermarket private-label programs and direct vessel contracting, displacing traditional auction channels for premium species.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as British and German retail chains consolidate procurement through direct vessel contracting, fragmenting traditional broker intermediation and shifting price discovery toward bilateral negotiation.
For Market Incumbents: Compound traceability advantages by integrating blockchain-IoT verification systems across hatchery-to-fillet operations, defending against cultivated protein substitutes through origin-certification premiums. Deepen backward integration into feed production and genetics to secure raw material cost stability against quota volatility. Prioritize ammonia refrigeration retrofits and biomass thermal systems to preserve EU market access under Green Deal carbon-border mechanisms. For New Entrants and Emerging Players: Anchor in Indian domestic retail modernization, where cold-chain infrastructure expansion in Maharashtra and Tamil Nadu creates first-mover opportunity for frozen and value-added formats displacing wet-market distribution. Target surimi-based analog seafood manufacturing partnerships with plant-forward foodservice distributors seeking functional protein substrates. Pursue direct procurement relationships with regional supermarket chains bypassing traditional auction layers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processors with captive fleet or aquaculture assets and certified cold-chain documentation over commodity traders lacking provenance systems. Long-term viability hinges on regulatory compliance infrastructure rather than scale alone. Monitor EU IUU Regulation enforcement intensity and Japanese METI labeling standard harmonization as inflection indicators for premium market access barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed and Genetics | Captive supply of Atlantic salmon smolts secures margin capture against volatile spot markets for eggs. |
| Blockchain-IoT Traceability Deployment | Real-time temperature logging unlocks Japanese sashimi-grade premiums and EU organic certification access. |
| Ammonia Refrigeration Retrofit | REACH chemical compliance and F-Gas Regulation alignment preserve supermarket shelf access in core export channels. |
| Direct Vessel Contracting with Retail Chains | Bilateral price negotiation with British and German supermarkets displaces broker margins in North Atlantic cod flows. |
| Surimi-Grade Production Line Expansion | Alaska pollock and Pacific whiting processing capacity serves plant-forward analog seafood manufacturing demand. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with processing plant managers, fleet operations directors, retail category buyers, cold-chain logistics specialists, and regulatory compliance officers; and secondary validation through customs trade databases, FDA Seafood HACCP inspection records, EU IUU Regulation enforcement reports, and FAO fisheries statistics. Bottom-up volume modeling triangulated against top-down value estimates derived from processor revenue disclosures and trade flow analysis.
Across the analysis window, projections integrated product type segmentation by frozen, surimi, canned, and dried categories; processing method tiers from automated filleting to craft smoking; and end-user channels spanning restaurants, retail chains, foodservice, and household distribution. CAGRs were derived from historical volume trajectories adjusted for regulatory enforcement intensity, cold-chain infrastructure buildout rates, and substitute protein venture funding flows as leading indicators.
Decision-makers should treat outputs as directional under assumptions of continued EU IUU Regulation enforcement, stable aquaculture feed cost structures, and no breakthrough commercialization of cultivated seafood; material deviation in wild-catch quota allocations or carbon-border implementation timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Processed Seafood Market
Seafood
Fish Protein Market
Seafood
Edible Seaweed Market
Seafood
Middle East Seafood Market
Seafood
Fish Maw Market
Seafood
Asia Pacific Canned Seafood Market
Seafood
Seafood Extracts Market
Seafood
United States Plant-Based Seafood Market
Seafood
Molluscs Market
Seafood
Fish Nutrition Market
Seafood
Asia-Pacific Seafood Market
Seafood
North America Frozen Seafood Market
Seafood
Europe Seafood Market
Seafood
Europe Shrimp Market
Seafood
Global Seafood Market
Seafood
United States Salmon Market