
 Lobster Market | 2026-2036
Lobster Market Size, Share, and Industry Trends Forecast 2026-2036
Lobster Market Intelligence
Direct-to-restaurant distribution is reshaping how premium lobster reaches end plates, bypassing traditional auction houses and shortening catch-to-kitchen cycles. Clearwater Seafoods leverages integrated cold-chain logistics to sustain year-round supply from Atlantic Canadian waters. Tangier Lobster Company anchors its position through specialized live-holding facilities that extend product viability across transcontinental routes. Thai Union Group competes via diversified processing scale, converting seasonal gluts into frozen and value-added formats for Asian retail channels.
Lobster denotes large marine crustaceans of the family Nephropidae, commercially harvested for their muscular abdomen and claws; specimens typically weigh 0.5–2 kilograms at market readiness, with shell hardness and meat yield determining grade classification. The primary commercial purpose centers on premium protein supply for foodservice and retail consumption, where live product commands substantial price premiums over processed alternatives. Live lobster leads volume among product types due to ritualized dining demand and perceived freshness signaling, while frozen lobster tails concentrate margin pools in export-oriented processing. Food service providers represent the fastest-growing end-user channel as institutional buyers adopt sous-vide and blast-frozen formats to reduce labor and waste.
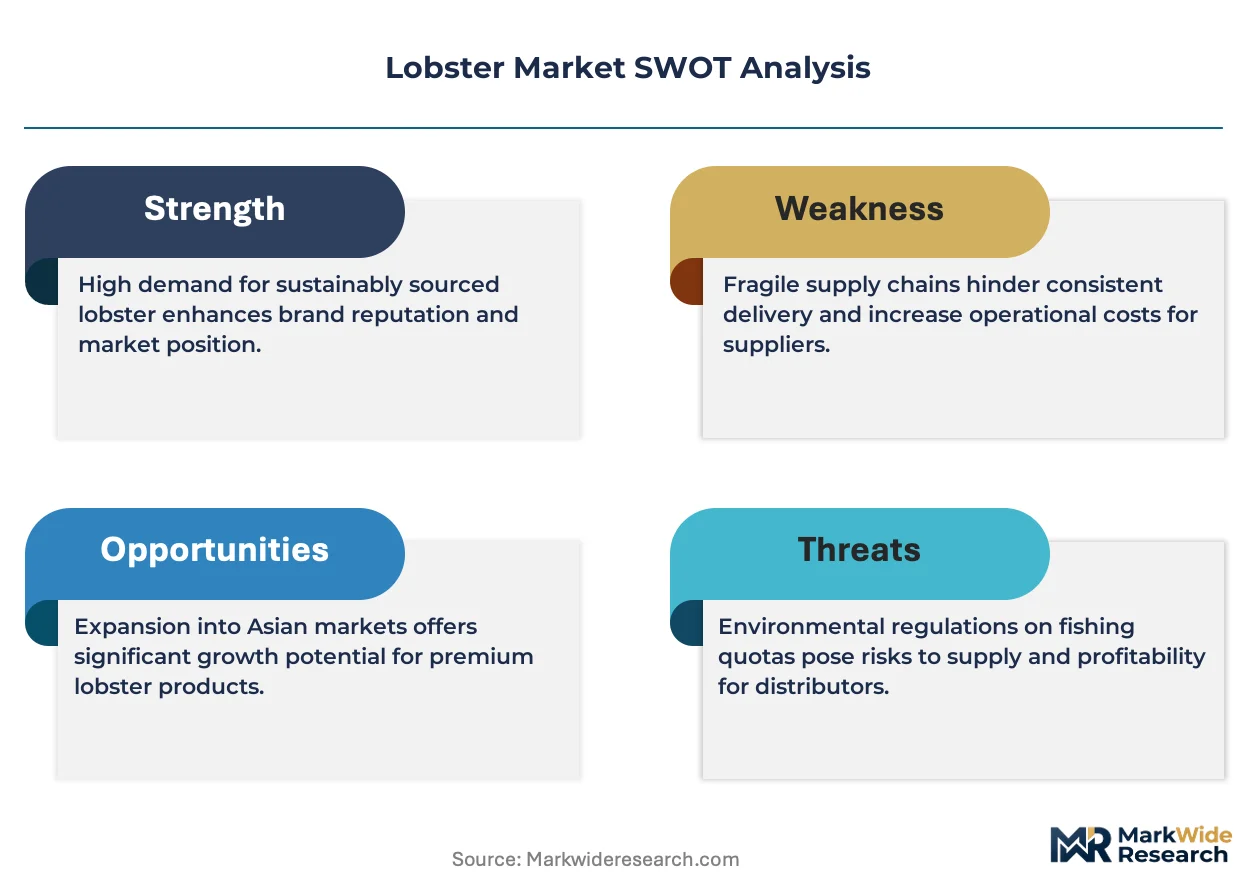
NOAA Fisheries administers the Atlantic Coastal Fisheries Cooperative Management Act alongside Canada's Department of Fisheries and Oceans seasonal trap restrictions, jointly governing catch quotas that constrain supply elasticity. The Marine Stewardship Council certification framework shapes market access for export-oriented processors, with EU import standards under EFSA and the EU Green Deal's traceability mandates filtering non-compliant product from European retail shelves. Stakeholders must monitor shifting minimum legal size thresholds and emerging carbon-footprint labeling requirements that will redefine competitive positioning in premium segments.
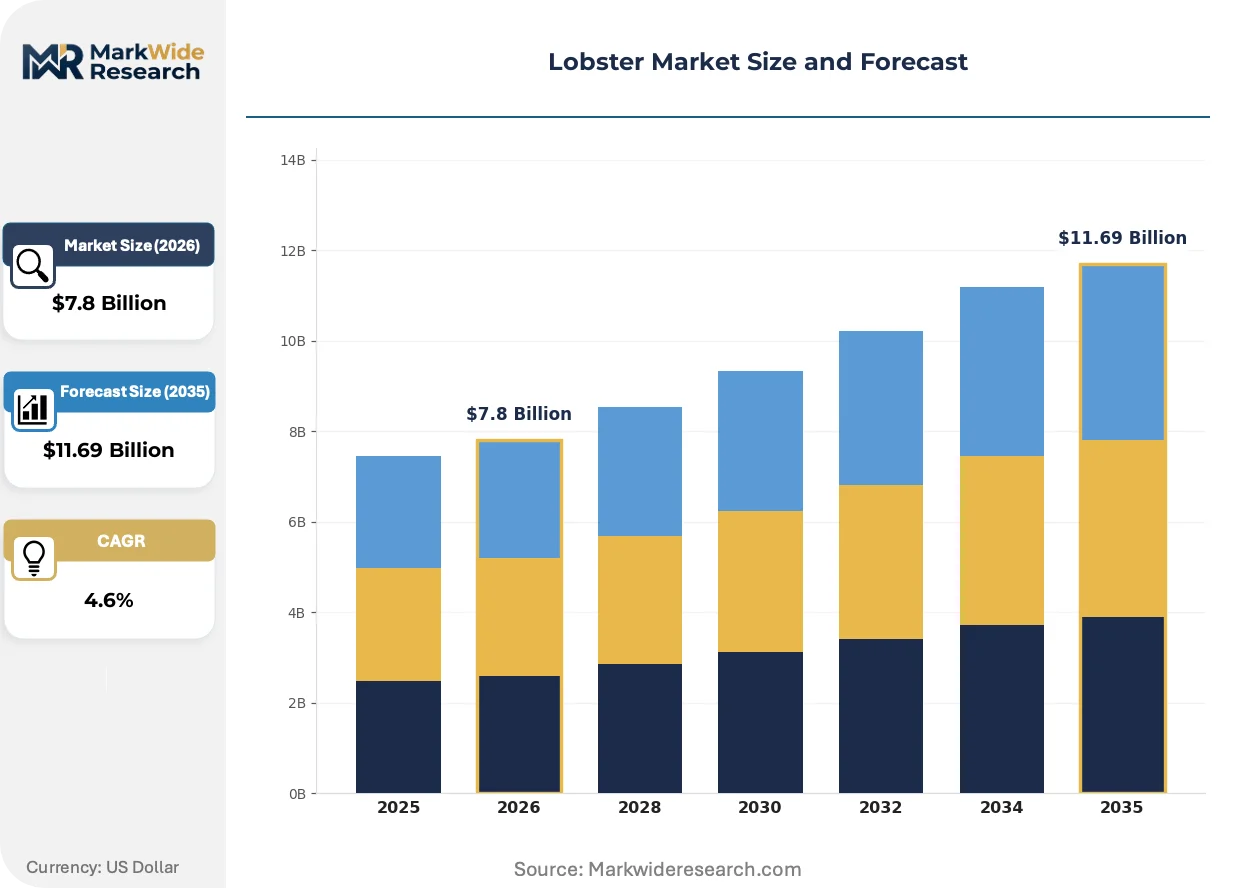
Market Dynamics
Canada's Department of Fisheries and Oceans trap limit reductions and Maine's seasonal closure expansions are constraining supply elasticity while live-holding technology investments by distributors compress catch-to-kitchen cycles.
Growth Catalysts
- Traceability mandates:The EU Green Deal's carbon-footprint labeling requirements filter non-compliant product from European retail shelves, creating competitive advantage for certified Atlantic Canadian exporters.
- Foodservice automation:Institutional buyers adopt sous-vide and blast-frozen formats to reduce labor and waste, expanding addressable demand for processed lobster products.
- Coastal cluster concentration:Premium foodservice buyers in Boston, Portland, and Halifax expand procurement of traceable live product, reinforcing brand premiums for cold-water yields.
Market Restraints
- Bait cost volatility:Herring and mackerel supply fluctuations drive input cost uncertainty for trap-based harvesters in the Gulf of Maine.
- Single-region supply risk:Cold-water lobster biomass concentrates in the Northwest Atlantic, exposing buyers to climate-driven stock migration.
- Shell disease proliferation:Epizootic shell disease in southern New England waters degrades meat yield and grade classification, reducing harvestable inventory.
Strategic Opportunities
- Asian retail penetration:Thai Union Group's frozen and value-added formats demonstrate viable pathways for converting seasonal gluts into shelf-stable products for Chinese and Japanese retail channels.
- Integrated cold-chain expansion:Specialized live-holding facilities enable transcontinental distribution with extended product viability, opening inland North American markets previously unreachable.
- Marine Stewardship Council tailwinds:MSC certification framework shapes market access for export-oriented processors, with EU import standards under EFSA creating compliance-based competitive moats.
Industry Challenges
- Live-handling expertise scarcity:Extended product viability across transcontinental routes demands specialized aquaculture technicians, creating talent pipeline constraints.
- Multi-jurisdictional compliance complexity:NOAA Fisheries' Atlantic Coastal Fisheries Cooperative Management Act and Canada's seasonal trap restrictions require simultaneous adherence to divergent quota systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lobster Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Lobster, Frozen Lobster, Cooked Lobster, Lobster Tails End User: Restaurants, Retail Stores, Seafood Markets, Food Service Providers Distribution Channel: Direct Sales, Wholesale, E-commerce, Export Packaging Type: Tray Packs, Vacuum Sealed, Bulk Packaging, Sustainable Packaging |
| Companies Covered | High Liner Foods, Tangier Lobster Company, Clearwater Seafoods, Supreme Lobster, Geraldton Fishermen's Co-operative, Boston Lobster Company, Red Lobster, Thai Union Group, East Coast Seafood Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lobster Market Strategic Shifts & Innovations
Technology-enabled supply chain compression and regulatory-driven traceability mandates are restructuring how premium lobster reaches end plates, with three forces dominating competitive adaptation.
Automated grading systems using machine vision and spectral analysis are collapsing traditional manual inspection bottlenecks at processing facilities. Mid-scale processors in Atlantic Canada deploy these systems to sort by shell hardness and meat yield with throughput rates impossible under human inspection. The technology is collapsing price discovery delays between harvesters and buyers, enabling real-time auction mechanisms that shorten cash conversion cycles.
The EU Green Deal's traceability mandates and EFSA import standards are filtering non-compliant product from European retail shelves. Processors must now document carbon footprint and chain of custody from trap to terminal market, raising compliance costs for smaller operators. Export-oriented facilities in Nova Scotia and New Brunswick are responding by investing in blockchain-enabled tracking systems that satisfy EU documentation requirements.
Direct-to-restaurant distribution models are displacing traditional auction house intermediation in premium segments. Foodservice buyers in coastal cities now contract directly with harvester cooperatives, securing traceable live product with verified catch dates. This pattern concentrates in Maine's lobstering communities and adjacent Canadian Maritime provinces where cold-water yields sustain brand premiums through shortened catch-to-kitchen cycles.
Lobster Market Segmentation
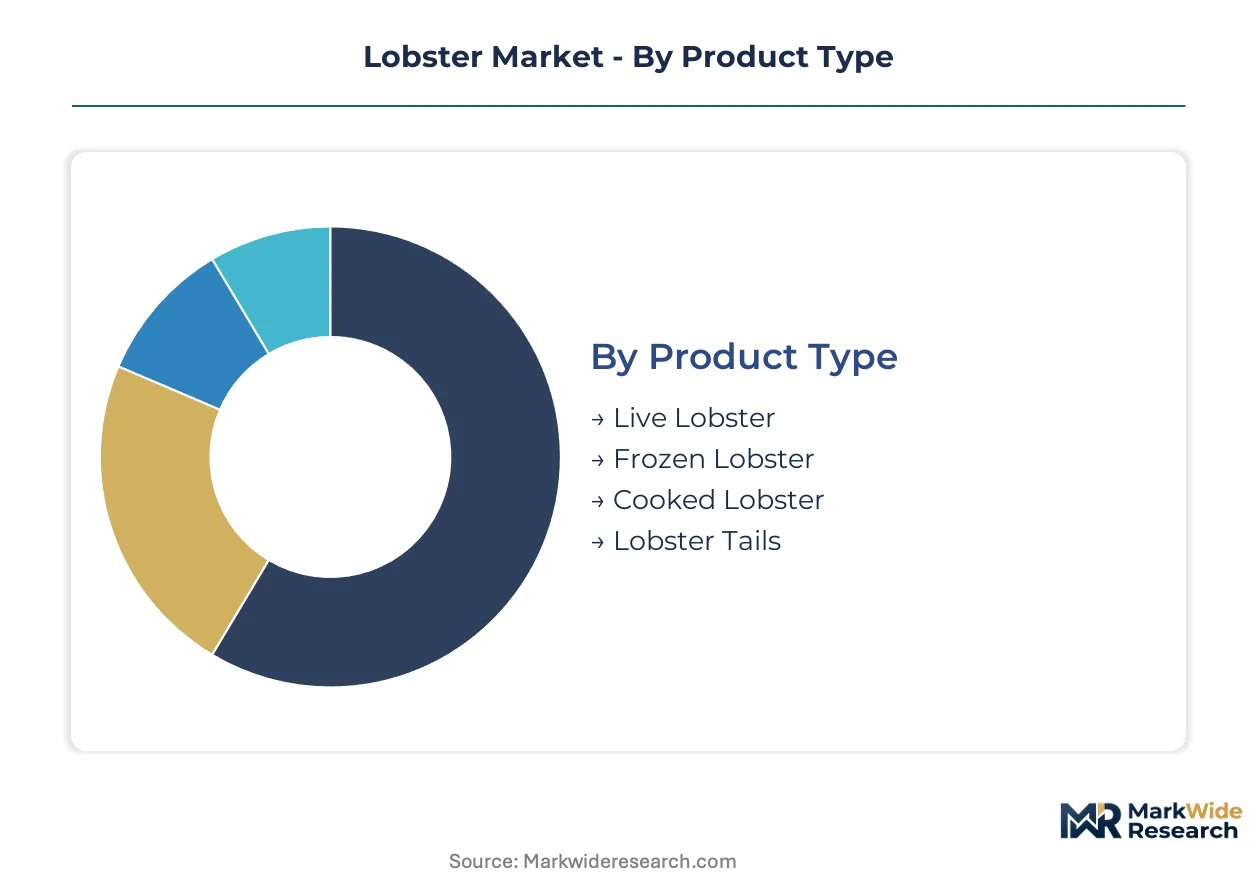
Product form and distribution pathway determine margin capture in the lobster trade, with live product commanding premiums through ritualized freshness signaling while processed formats unlock volume in distant markets. End-user concentration in coastal foodservice clusters and the emergence of direct procurement channels reshape how harvesters monetize catch quality across grade tiers.
Product Type:
Use-case spectrum spans ceremonial dining occasions demanding live product through institutional procurement favoring labor-reducing processed formats.
- Live Lobster:Whole specimens maintained in circulating seawater systems from harvest through terminal sale; shell hardness and limb integrity determine grade classification. Coastal foodservice buyers in Boston and Halifax contract directly with harvester cooperatives, securing verified catch dates that command substantial premiums at white-tablecloth establishments.
- Frozen Lobster:Blast-frozen whole specimens or sections preserved at -18°C for extended shelf stability; glaze percentage and thaw-loss rates define quality tiers. Thai Union Group and comparable processors convert seasonal supply gluts into inventory for Asian retail channels where cold-chain infrastructure constraints favor stable-frozen over live logistics.
- Cooked Lobster:Steam-cooked and chilled product ready for immediate consumption or recipe integration.
- Lobster Tails:Abdominal sections separated and graded by meat fill ratio; vacuum-sealed tails concentrate margin pools in export-oriented processing.
The dominant share belongs to Live Lobster, while Frozen Lobster is closing the gap fastest.
End User:
Customer type stratification reflects divergent procurement capabilities, from direct dockside relationships through centralized institutional purchasing.
- Restaurants:Independent and chain operators sourcing through auction houses or direct harvester contracts; menu positioning as center-of-plate protein or ingredient component drives specification requirements. Maine's coastal dining establishments anchor regional demand through summer tourism peaks.
- Food Service Providers:Institutional caterers, hospitality groups, and contract feeding operations adopting sous-vide and blast-frozen formats to reduce kitchen labor and plate waste. This channel is expanding most quickly as standardized portioning and extended holding tolerance address operator cost pressures.
- Retail Stores:Supermarket chains and specialty grocers merchandising live tanks or frozen sections.
- Seafood Markets:Traditional mongers and ethnic market operators serving consumer pick-and-choose preferences.
Restaurants retain volume leadership, though Food Service Providers demonstrate the steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin retention and traceability documentation burden, with direct models compressing intermediation costs.
- Direct Sales:Harvester-to-restaurant contracts bypassing auction infrastructure; blockchain-enabled catch documentation satisfies EU Green Deal traceability mandates for export-oriented Nova Scotia facilities.
- Wholesale:Traditional auction houses and distributor intermediaries aggregating supply from multiple harvesters.
- E-commerce:Platform-based sales enabling consumer direct ordering with overnight cold-chain fulfillment.
- Export:Containerized shipment to Asian and European markets requiring MSC certification and EFSA-compliant documentation.
Wholesale channels handle the greatest volume, while Direct Sales gain share fastest among premium segments.
Packaging Type:
Packaging investment correlates with shelf-life extension requirements and sustainability positioning in regulatory-filtered markets.
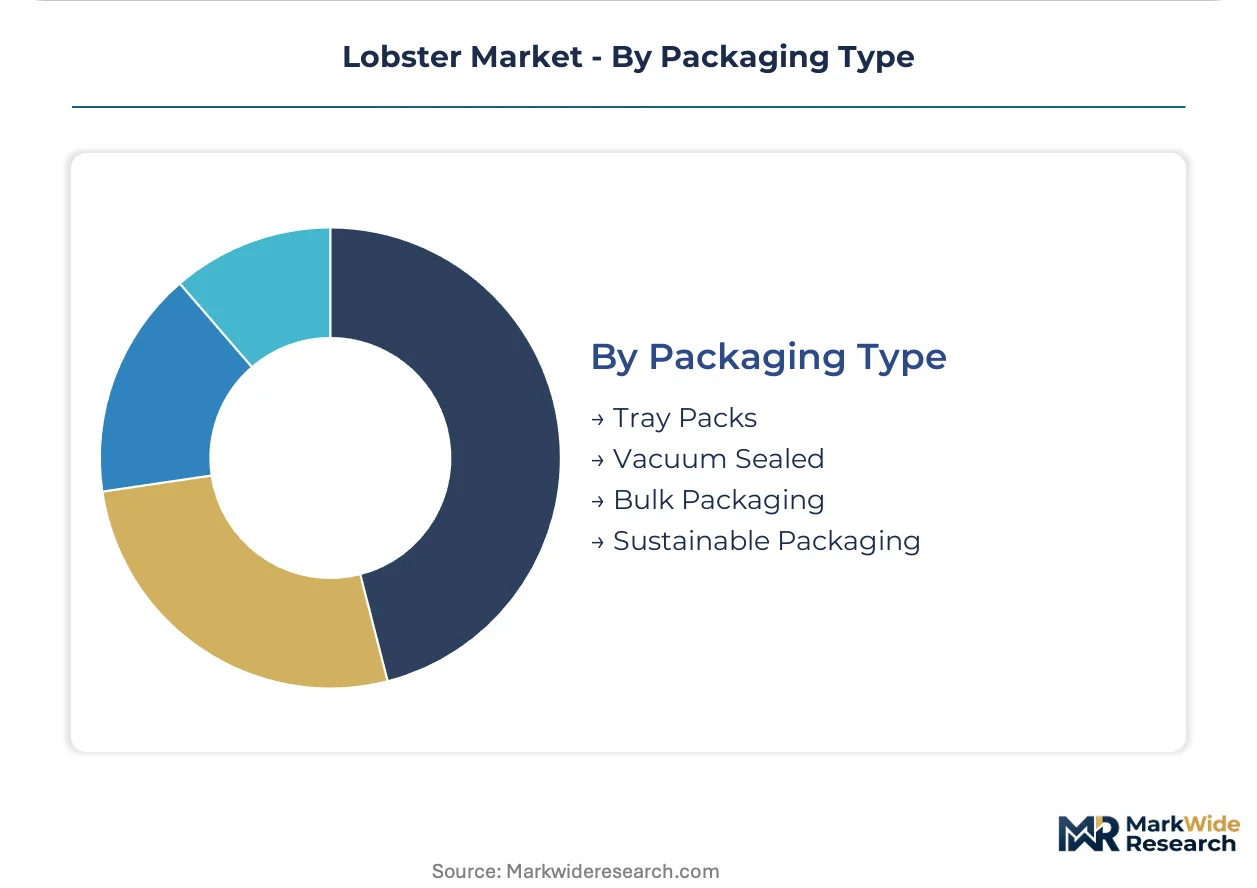
- Vacuum Sealed:Modified-atmosphere packaging removing oxygen to inhibit enzymatic degradation; processors targeting EU retail shelves invest in recyclable film substrates to meet emerging carbon-footprint labeling requirements.
- Sustainable Packaging:Compostable trays, seaweed-based films, and reusable container systems; Clearwater Seafoods and comparable exporters deploy these formats to defend market access under tightening European environmental standards.
- Tray Packs:Polystyrene or pulp-based containers for retail merchandising display.
- Bulk Packaging:Master cartons and totes for foodservice and processing throughput.
Vacuum Sealed formats dominate processed product distribution, while Sustainable Packaging climbs fastest on regulatory compliance tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Portland International Marine Terminal's refrigerated cargo infrastructure underwrites Maine's position as the primary North American live lobster export gateway, handling containerized shipments to Asian and European markets.
United States
Summer tourism peaks in coastal Maine drive seasonal demand surges for live product at dockside restaurants and Boston's white-tablecloth establishments. NOAA Fisheries administers the Atlantic Coastal Fisheries Cooperative Management Act alongside seasonal trap restrictions that constrain harvest volumes. Portland's direct-to-restaurant distribution networks now bypass traditional auction houses, compressing catch-to-kitchen cycles for traceable product.
Canada
The Department of Fisheries and Oceans tightened trap limits and seasonal closures to protect breeding stocks in Atlantic Canadian waters. Health Canada enforces seafood safety standards under the Safe Food for Canadians Regulations, with Marine Stewardship Council certification shaping EU market access. Nova Scotia and New Brunswick processing facilities invest in blockchain-enabled tracking systems to satisfy EU Green Deal documentation requirements.
China
Shanghai and Beijing's luxury dining sector sustains demand for live Atlantic lobster despite cold-chain infrastructure constraints that favor frozen alternatives. The General Administration of Customs China enforces strict import documentation and cold-chain verification protocols. Dalian and Qingdao ports serve as primary entry points for North American live shipments, with specialized live-holding facilities extending product viability.
Japan
Tokyo's high-end ryotei restaurants and Osaka's hotel banquet operations maintain ceremonial demand for live product with verified catch dates. The Ministry of Health, Labour and Welfare administers food safety standards under the Food Sanitation Act, with METI overseeing import quota allocations. Tsukiji Outer Market distributors specialize in same-day air freight from Atlantic Canadian sources.
United Kingdom
London's fine-dining establishments and Edinburgh's seafood restaurants source live lobster through direct contracts with Maritime Canadian harvester cooperatives. The Food Standards Agency enforces EU-retained import standards including EFSA traceability mandates and emerging carbon-footprint labeling requirements. Billingsgate Market intermediaries now favor MSC-certified suppliers to defend retail shelf positioning.
Lobster Market Key Industry Players
On the supply side, the industry is consolidating around integrated cold-chain operators capable of sustaining live product viability across transcontinental routes. Harvester cooperatives and specialized distributors coexist with diversified seafood conglomerates, creating a tiered competitive structure. Two strategic archetypes dominate: vertically integrated Atlantic Canadian exporters controlling trap-to-terminal logistics, and Asian-scale processors converting seasonal gluts into frozen inventory. Dominant competitive moves include specialized live-holding facility investments and MSC certification acquisition for EU market defense.
Among North American specialists, Tangier Lobster Company and Clearwater Seafoods exemplify the integrated cold-chain archetype, while Thai Union Group represents the scale-driven processing model converting regional supply into Asian retail distribution. These three anchors illustrate how geographic positioning and infrastructure investment separate premium live-product handlers from commodity-oriented processors.
| Leading Market Players |
|---|
| High Liner Foods |
| Tangier Lobster Company |
| Clearwater Seafoods |
| Supreme Lobster |
| Geraldton Fishermen's Co-operative |
| Boston Lobster Company |
| Red Lobster |
| Thai Union Group |
| East Coast Seafood Group |
| Others |
Cost & Logistics Intelligence
The Portland-Halifax refrigerated cargo corridor anchors cost dynamics for live lobster distribution, where freight rates from Maine's export terminals to Asian markets compress margins for non-integrated harvesters while reinforcing price premiums for cold-water yields with verified catch documentation. Supply concentration in Atlantic Canadian waters and the Gulf of Maine funnels pricing power toward distributors controlling specialized live-holding infrastructure, creating sharp differentiation between dockside auction prices and direct-to-restaurant contract rates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by shell hardness, meat yield ratios, and MSC certification status. Price differentiation centers on live-holding duration capabilities and EU Green Deal traceability compliance, with certified Atlantic Canadian exporters commanding substantial premiums over commodity auction lots. Cost compression in the frozen segment is intensifying because Thai Union Group and comparable processors convert seasonal gluts into inventory for price-sensitive Asian retail channels. Foodservice providers demonstrate the highest price sensitivity due to standardized portioning requirements, while white-tablecloth establishments in Boston and Tokyo absorb premiums for verified live product with documented catch dates.
Supply Chain Analysis
Specialized live-holding facility operators Tangier Lobster Company and Clearwater Seafoods control transcontinental distribution capacity, with captive infrastructure investments determining market access for harvester cooperatives. Supply concentrates in Canada, the United States, and emerging secondary processing hubs in Vietnam for value-added conversion. Herring and mackerel bait supplies, circulating seawater systems, and blast-freezing equipment constitute critical input dependencies. Single-region supply risk from climate-driven stock migration in the Northwest Atlantic exposes buyers to inventory disruption. Distribution runs through direct harvester-to-restaurant contracts for premium live product, while wholesale auction houses and containerized export channels handle volume frozen shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Live-handling expertise scarcity constrains expansion for distributors attempting transcontinental routes, with specialized aquaculture technician pipelines representing the critical capability gap separating integrated operators from commodity processors. The market rewards backward control over cold-chain infrastructure and MSC certification assets.
For Market Incumbents: Insulate margin pools by acquiring specialized live-holding facilities in Nova Scotia and New Brunswick to extend product viability across Asian routes, while investing in blockchain-enabled tracking systems to satisfy tightening EU EFSA documentation requirements. Defend against Thai Union Group's frozen-format scale advantage by deepening direct restaurant relationships in Boston, Portland, and Halifax that bypass auction intermediation. For New Entrants and Emerging Players: Pursue underdeveloped inland North American markets previously unreachable due to live-holding constraints, where foodservice providers adopting sous-vide formats present lower barrier-to-entry demand. Target institutional catering operations seeking blast-frozen portion control with standardized specifications. Establish go-to-market presence through e-commerce platforms offering overnight cold-chain fulfillment to coastal-adjacent metropolitan areas. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified seafood conglomerates with underutilized Atlantic Canadian processing assets and dormant MSC certification pathways. Long-term viability hinges on regulatory compliance infrastructure rather than commodity harvest access. Monitor EU carbon-footprint labeling implementation as the inflection signal separating compliant exporters from filtered market participants.| Strategic Initiative | Industry Significance |
|---|---|
| Live-Holding Facility Expansion | Specialized infrastructure in Nova Scotia extends product viability for transcontinental routes to Shanghai and Tokyo. |
| MSC Certification Acquisition | EU EFSA import standards under the Green Deal filter non-compliant product from European retail shelves. |
| Blockchain Traceability Implementation | Chain-of-custody documentation satisfies emerging carbon-footprint labeling requirements for Atlantic Canadian exporters. |
| Direct-to-Restaurant Distribution | Harvester cooperative contracts in Maine bypass auction houses and compress catch-to-kitchen cycles. |
| Frozen Format Scale-Up | Blast-freezing investment converts seasonal Gulf of Maine gluts into shelf-stable inventory for Asian retail channels. |
Research Approach
Findings reconcile primary fieldwork against secondary review of NOAA Fisheries harvest data, Canada Department of Fisheries and Oceans trap limit records, EU EFSA import compliance databases, and Marine Stewardship Council certification registries. Primary interviews incorporated harvester cooperative representatives, live-holding facility operations managers, foodservice procurement directors at Boston and Halifax restaurant groups, and cold-chain logistics specialists. Bottom-up volume modeling from trap-level harvest data triangulates against top-down trade flow analysis for export-oriented processing volumes.
Forecast inputs include regulatory quota trajectories under the Atlantic Coastal Fisheries Cooperative Management Act, live-holding technology adoption curves, and EU Green Deal traceability implementation timelines. Segmentation dimensions span product form, end-user channel, distribution pathway, and regional cold-chain infrastructure maturity. CAGRs derive from supply-constrained harvest projections intersecting with demand elasticity estimates across foodservice automation adoption and Asian retail penetration scenarios. Bait cost volatility and shell disease prevalence in southern New England waters inform scenario-weighted outcomes.
Macroeconomic conditions sit as an overlay; deviation in freight rates, currency exchange levels, or luxury dining discretionary spending would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory quota stability and certification framework continuity. Quarterly review of EU carbon-footprint labeling enforcement, NOAA seasonal closure expansions, and Asian port cold-chain verification protocols is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
North America Tuna Market
Seafood
Mackerel Market
Seafood
Mussels Market
Seafood
South America Canned Seafood Market
Seafood
Asian Sea Bass Market
Seafood
Edible Seaweed Market
Seafood
Trout Market
Seafood
Processed Seafood Market
Seafood
United States Salmon Market
Seafood
Canned Salmon Market
Seafood
Canned Sardines Market
Seafood
Organic Salmon Market
Seafood
Haddock Market
Seafood
North America Salmon Market
Seafood
Global Frozen and Canned Seafood Market
Seafood
Salmon Fish Market