
 Caviar Market | 2026-2036
Caviar Market Size, Share, and Industry Trends Forecast 2026-2036
Caviar Market Analysis
Aquaculture producers in China and Italy are repositioning global caviar supply chains toward farmed output. Kaluga Queen leverages its Hangzhou Bay sturgeon farms to dominate domestic Chinese distribution. Petrossian Inc. sustains century-old brand equity through direct retail control in Paris and New York. Agroittica Lombarda anchors European supply with its Calvisano aquaculture complex, the world's largest sturgeon farm.
Caviar consists of salt-cured roe from Acipenseridae sturgeon species, graded by egg size, color, and texture with malossol processing using under 3.5% salt to preserve delicate flavor. Its primary commercial purpose centers on luxury gastronomy and ceremonial gifting across hospitality and private consumption channels. Osetra and farmed grade categories capture expanding volume as wild-origin Beluga faces persistent CITES trade restrictions. Food service and gourmet shop distribution channels concentrate margin pools, while online retail extends geographic reach to emerging affluent consumers.
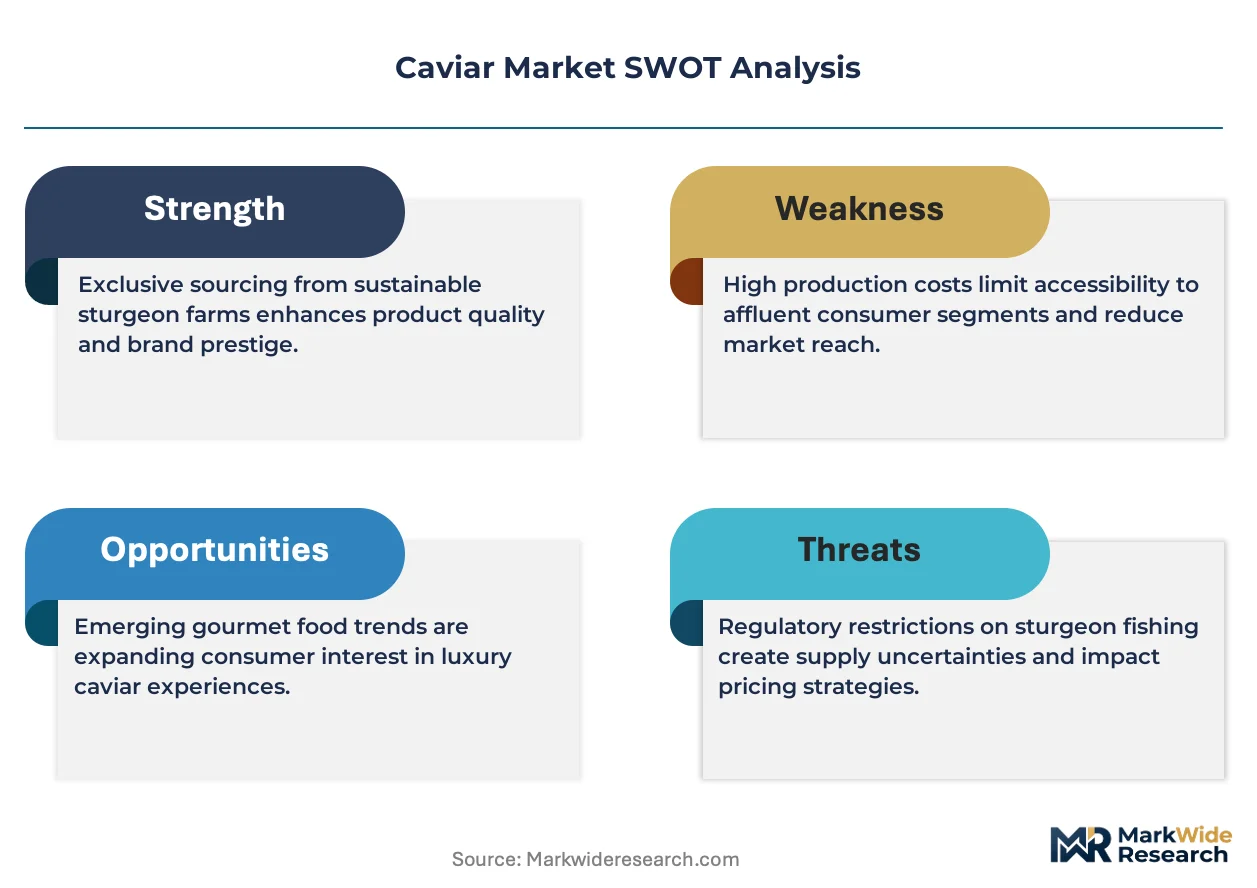
CITES appendices regulate international sturgeon trade, compelling producers toward certified aquaculture documentation. The EU's F-Gas Regulation and national veterinary standards in France and Italy enforce processing facility compliance that shapes market access for European exporters. China's SAMR and GB food safety standards govern import clearance and domestic farmed caviar labeling requirements. Stakeholders must monitor evolving traceability mandates and aquaculture certification schemes as regulatory stringency tightens across major producing and consuming jurisdictions.
Market Dynamics
The global caviar market pivots on a singular structural force: CITES enforcement has permanently severed wild sturgeon supply chains, forcing producers to rebuild around aquaculture certification and traceable farm-to-table documentation systems.
Growth Catalysts
- UAE Luxury Hospitality Expansion:Dubai and Abu Dhabi hotel chains are institutionalizing caviar service programs across fine-dining outlets and in-room amenities, creating sustained institutional demand.
- China's SAMR Labeling Standards:Clear domestic farmed caviar classification rules have reduced consumer confusion and accelerated retail penetration in tier-one cities.
- Recirculating Aquaculture Systems:RAS technology deployment at Italian and Chinese farms is compressing sturgeon maturation timelines and improving roe yield consistency.
Market Restraints
- Input Cost Volatility:Sturgeon feed formulations depend on fishmeal and fish oil prices, which fluctuate with Peruvian anchovy harvest cycles and El Niño disruptions.
- Supply Concentration Risk:Over half of farmed caviar processing capacity sits in Italy's Lombardy region, exposing buyers to localized climate or veterinary events.
- Regulatory Friction:The EU's F-Gas Regulation imposes refrigeration compliance costs on aging European processing facilities without grandfathering provisions.
Strategic Opportunities
- Saudi Arabia's Giga-Project Hospitality:NEOM and Red Sea tourism developments are specifying caviar for VIP catering contracts ahead of 2030 visitor targets.
- Direct-to-Consumer Subscription Channels:E-commerce platforms bypass traditional importer markups and build recurring revenue among affluent households.
- Carbon-Neutral Certification:Producers achieving ISO 14064 verification can access premium pricing in environmentally conscious Nordic and German retail.
Industry Challenges
- Veterinary Specialist Scarcity:Sturgeon pathology expertise concentrates at Italian and French research institutes, limiting farm expansion in newer producing regions.
- Multi-Year Capital Lockup:Female sturgeon require 7-10 years to reach first harvest, demanding patient financing structures unavailable to most agricultural lenders.
- CITES Documentation Complexity:Each international shipment requires species-specific permits with non-standardized formatting across customs jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caviar Market |
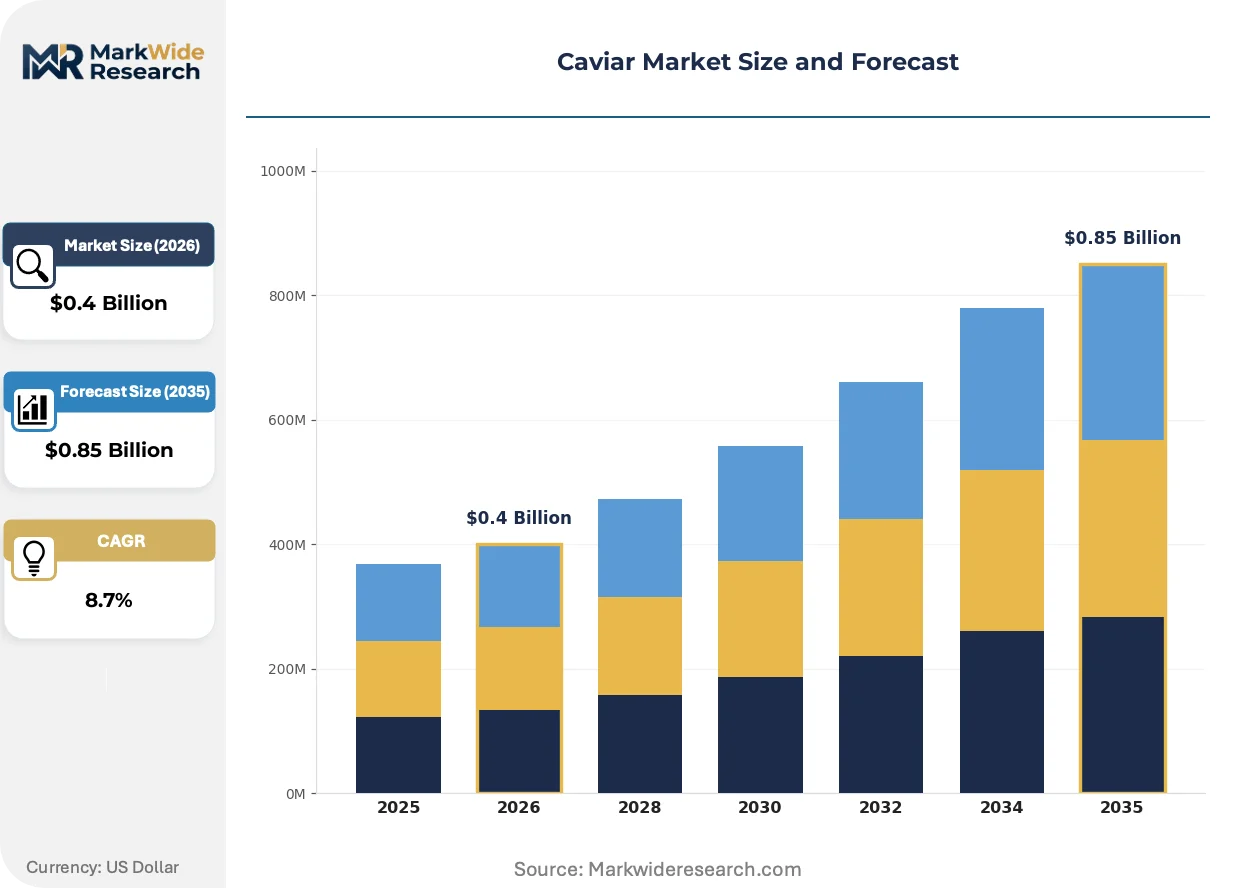
| Market Size in 2026 | $0.4 Billion |
| Market Size in 2035 | $0.85 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beluga, Osetra, Sevruga, Paddlefish Grade: Black Caviar, Malossol, Pasteurized, Farmed Packaging Type: Tins, Glass Jars, Vacuum Packs, Plastic Containers Distribution Channel: Online, Retail, Gourmet Shops, Food Service |
| Companies Covered | Petrossian Inc., The Caviar Co., Kaluga Queen, Black River Caviar, Caviar House & Prunier, Agroittica Lombarda, Tsar Nicoulai Caviar, Sasanian Caviar Inc., Labeyrie Fine Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caviar Market Emerging Trajectories
Digital traceability platforms and alternative roe processing methods are restructuring how caviar moves from farm to final consumption, with implications for pricing power and brand differentiation.
Blockchain-enabled provenance tracking is rewriting competitive advantage in the premium segment. Michelin-starred restaurants in Paris and New York now require batch-level origin verification before contract renewal. This technology is compressing information asymmetry between producers and end-buyers, eliminating opaque intermediary layers.
REACH-compliant non-toxic tinning alloys are replacing traditional lead-soldered caviar tins across EU export channels. The substitution eliminates food-contact contamination risks but requires retooling at Italian and French canneries. Smaller processors in Eastern Europe lack capital for equipment conversion, consolidating EU supply among compliant facilities.
Private-label caviar programs are displacing heritage brand dominance in Asian duty-free retail. Airport operators in Singapore and Hong Kong now specify house-branded farmed varieties for lounge and retail concessions. This pattern is most visible in China, where domestic travelers demonstrate weaker brand loyalty than European or American counterparts.
Caviar Market Segmentation
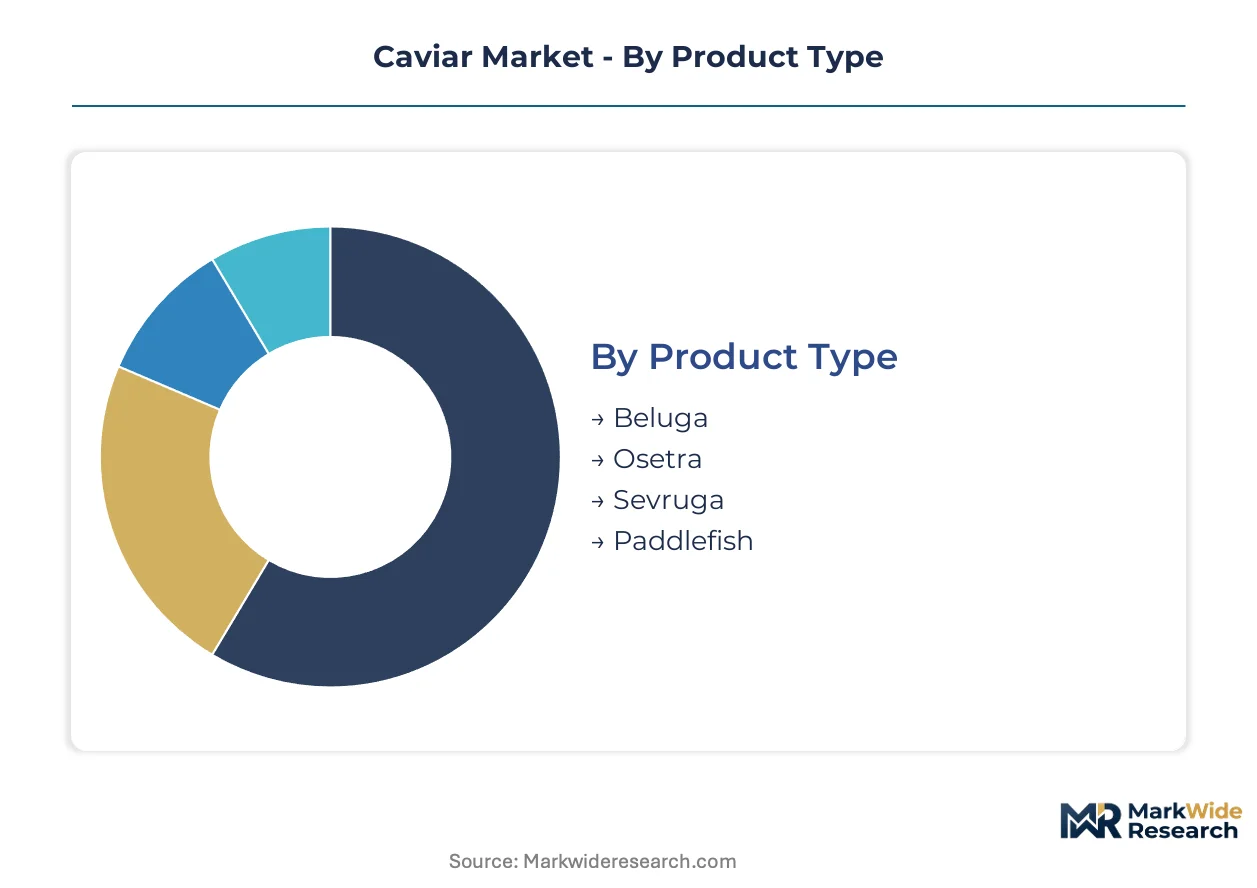
Caviar segmentation reflects divergent supply realities under CITES enforcement and diverging buyer sophistication across hospitality and retail channels. Grade and provenance certifications now override species origin as the primary sorting mechanism for commercial transactions.
Product Type:
Species differentiation maps directly onto regulatory accessibility and maturation economics.
- Beluga:Huso huso roe commands the highest price tier but faces strict CITES Appendix II trade restrictions. Wild-origin Beluga remains commercially unavailable; farmed variants from CITES-registered aquaculture operations supply Dubai hotel contracts and Moscow private dining clubs.
- Osetra:Acipenser gueldenstaedtii and related species dominate commercial volume. Chinese farms at Hangzhou Bay and Italian Calvisano operations prioritize Osetra for its 6-8 year maturation timeline and consistent egg quality. Michelin-starred restaurants in Paris specify Osetra for tasting menu applications.
- Sevruga:Acipenser stellatus offers smaller egg diameter and more intense flavor profile. Russian and Iranian heritage brands maintain Sevruga distribution through European gourmet shops despite limited new farmed supply.
- Paddlefish:Polyodon spathula roe from North American aquaculture serves as a legal substitute where sturgeon trade faces documentation friction. Midwestern US farms supply domestic food service channels.
Mature deployment sits with Osetra. Newer deployment is concentrated in farmed Beluga from certified aquaculture.
Grade:
Processing method and origin documentation now determine price positioning more than species alone.
- Black Caviar:Traditional salt-cured roe without malossol processing carries extended shelf life but firmer texture. Russian and Iranian export houses maintain Black Caviar production for Middle Eastern retail distribution.
- Malossol:Under 3.5% salt content preserves delicate membrane structure and fresh flavor. Premium hospitality procurement in New York and London requires malossol certification for white-tablecloth service. This grade is expanding most quickly among farmed Osetra output.
- Pasteurized:Heat-treated roe extends ambient distribution reach to airport retail and cruise ship catering. Shelf-stable properties attract Asian duty-free operators.
- Farmed:Aquaculture-origin classification with CITES documentation and traceability verification. Chinese domestic consumption and European export compliance both pivot on explicit farmed labeling under national regulator standards.
Heritage procurement centers on malossol. Volume scaling depends on farmed grade penetration.
Packaging Type:
Packaging selection balances oxidation protection with presentation requirements across channel contexts.
- Tins:Traditional lead-free soldered or REACH-compliant alloy containers remain standard for restaurant service and gifting. Italian canneries at Agroittica Lombarda specialize in tin packaging for European export.
- Glass Jars:Visual transparency supports retail merchandising in gourmet shops. French and Swiss retailers specify jar presentation for counter display.
- Vacuum Packs:Modified atmosphere packaging extends refrigerated shelf life for e-commerce fulfillment. Chinese online retailers deploy vacuum packs for tier-one city delivery.
- Plastic Containers:Cost-optimized format for food service portion control and airline catering. UAE hospitality procurement uses plastic for in-room amenity programs.
Prestige positioning attaches to tins. Logistics efficiency favors vacuum packs.
Distribution Channel:
Channel selection determines margin capture and brand control intensity.
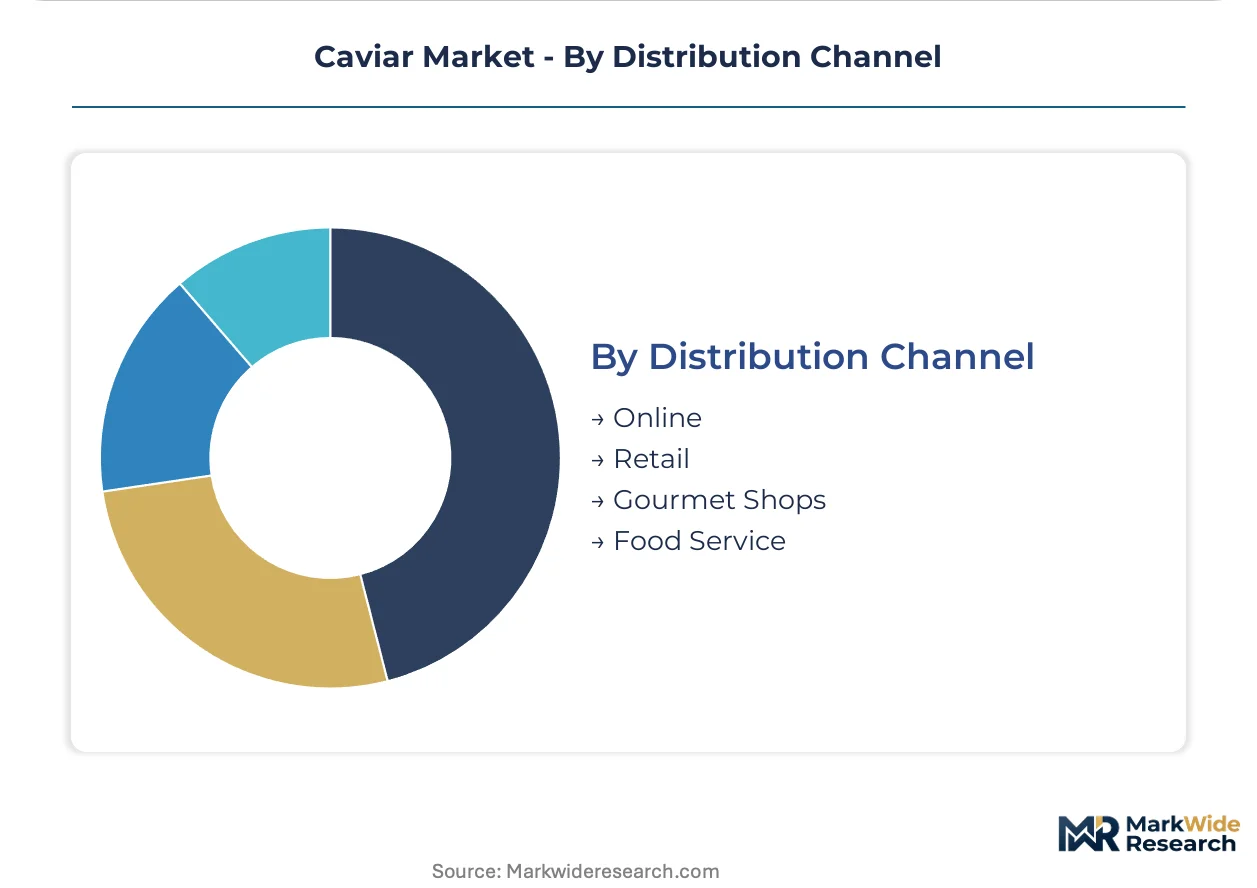
- Online:Direct-to-consumer platforms bypass importer markups and enable subscription revenue. Chinese e-commerce operators leverage SAMR-compliant labeling for domestic farmed caviar penetration.
- Retail:Supermarket and department store counters require packaged formats with extended shelf life. European retail chains specify farmed origin for sustainability messaging.
- Gourmet Shops:Heritage brands maintain flagship presence in Paris, New York, and London for experiential purchasing and gifting occasions. Petrossian and comparable houses control this channel directly.
- Food Service:Hotels and restaurants generate sustained institutional demand with specification contracts. Dubai and Abu Dhabi luxury hospitality chains are expanding caviar service programs across fine-dining outlets.
Margin concentration rests with gourmet shops. Geographic expansion runs through online channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sturgeon aquaculture operations cluster along specific waterways that provide temperature-stable conditions for long maturation cycles. China, Italy, the United Arab Emirates, France, and the United States each host distinct production and consumption ecosystems shaped by local regulatory frameworks.
China
Hangzhou Bay sturgeon farms supply rising domestic consumption among affluent urban consumers in Shanghai and Beijing. SAMR labeling standards for farmed caviar have reduced retail confusion and accelerated tier-one city penetration. Kaluga Queen anchors production at Qiandao Lake facilities, dominating domestic distribution channels.
Italy
The Calvisano aquaculture complex in Lombardy processes the majority of European farmed caviar output for export to Paris and New York gourmet shops. EU F-Gas Regulation imposes refrigeration compliance costs on aging canneries without grandfathering provisions. Brescia province concentrates veterinary expertise and tinning alloy conversion investments.
United Arab Emirates
Dubai and Abu Dhabi luxury hotel chains are institutionalizing caviar service programs across fine-dining outlets and in-room amenities. MOHAP food safety standards govern import clearance for hospitality procurement. Jumeirah Beach and Downtown Dubai clusters generate sustained institutional demand from Gulf state visitors.
France
Paris maintains century-old heritage brand presence through direct retail control in Place de la Madeleine flagship locations. ANSM veterinary standards enforce processing facility compliance that shapes market access for European exporters. Aquitaine region farms supply domestic malossol-grade output to Michelin-starred restaurants.
United States
Midwestern paddlefish aquaculture serves domestic food service channels where sturgeon trade faces documentation friction. FDA seafood HACCP regulations govern processing facility inspections. California and New York metropolitan areas concentrate gourmet shop and direct-to-consumer subscription demand.
Caviar Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription channels and carbon-neutral certification programs. The market structures around heritage houses with century-old brand equity, integrated aquaculture-to-retail operators, and specialized regional processors. Three archetypes dominate: vertically integrated farm-to-table specialists, heritage brand custodians with flagship retail control, and scale-driven aquaculture exporters. Competitive intensity centers on CITES documentation capabilities and RAS technology deployment rather than price alone.
Within the heritage brand tier, Petrossian Inc. and Caviar House & Prunier exemplify century-old Paris-based houses that maintain direct retail control in flagship locations. Agroittica Lombarda occupies a position as the scale-driven Italian integrated producer. Kaluga Queen represents the Chinese farm-to-table specialist archetype with domestic distribution dominance. These three anchors illustrate how geographic concentration of sturgeon aquaculture and regulatory compliance capabilities determine competitive positioning.
| Leading Market Players |
|---|
| Petrossian Inc. |
| The Caviar Co. |
| Kaluga Queen |
| Black River Caviar |
| Caviar House & Prunier |
| Agroittica Lombarda |
| Tsar Nicoulai Caviar |
| Sasanian Caviar Inc. |
| Labeyrie Fine Foods |
| Others |
Supply Flow & Price Mechanics
Malossol-grade farmed Osetra commands a three-to-fourfold premium over pasteurized alternatives, with that divergence manifesting in divergent supply chain configurations: premium tiers route through Italian canneries with CITES-certified cold chain documentation, while economy segments source from Chinese vacuum-pack processors serving e-commerce fulfillment.
Pricing Analysis
Traceability-bundling separates premium hospitality procurement from unbundled retail formats. Three-tier pricing structure across malossol, pasteurized, and farmed-economy levels anchors the market, with differentiation driven by CITES certification depth and cold-chain integrity guarantees. Cost compression in pasteurized tiers intensifies because Chinese processors are scaling vacuum-pack output for domestic e-commerce. Food service buyers in Dubai luxury hotels demonstrate the least price sensitivity, while Asian duty-free operators exhibit acute elasticity to per-gram rates.
Supply Chain Analysis
Fishmeal feed formulations rest on Peruvian anchovy harvest cycles and El Niño disruptions, with sturgeon farms drawing from volatile commodity inputs. Geographic supply concentrates in Italy, China, and France, where aquaculture operations cluster around temperature-stable waterways. Single-source vulnerability sits with Lombardy processing capacity, where over half of European farmed caviar undergoes tinning and certification. Distribution runs through heritage brand flagships in Paris and New York, direct-to-consumer platforms in Chinese tier-one cities, and hospitality procurement offices in Dubai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CITES documentation complexity is forcing consolidation among smaller processors lacking dedicated compliance staff, eliminating marginal players from export channels.
For Market Incumbents: Lock in RAS technology deployment at Italian and Chinese facilities to compress the 7-10 year sturgeon maturation timeline, while securing exclusive veterinary pathology partnerships at Brescia research institutes to block competitor expansion. Heritage houses must defend against private-label displacement in Asian duty-free by enforcing batch-level blockchain provenance as a contract-renewal condition. For New Entrants and Emerging Players: China's SAMR labeling standards for farmed caviar open a window for domestic brand-building among affluent Shanghai and Beijing consumers confused by import-origin claims. Target carbon-neutral certification as the most penetrable positioning lever, with ISO 14064 verification enabling premium access to Nordic retail. A direct-to-consumer subscription angle bypasses importer markups and builds recurring revenue visibility. For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated farm-to-table specialists with captive RAS infrastructure and CITES registration depth. The 5-10 year viability window favors producers with patient capital structures already deployed across sturgeon maturation cycles. Watch RAS yield consistency improvements as the inflection signal separating scalable operations from capital-trapped competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Implementation | Michelin-starred restaurants in Paris now require batch-level origin verification before contract renewal. |
| RAS Technology Deployment | Italian and Chinese farms compress sturgeon maturation timelines while improving roe yield consistency. |
| Carbon-Neutral Certification | ISO 14064 verification unlocks premium pricing in environmentally conscious Nordic and German retail channels. |
| Direct-to-Consumer Subscription Launch | E-commerce platforms bypass traditional importer markups and build recurring revenue among affluent households. |
| CITES Compliance Infrastructure Investment | Species-specific permit capabilities determine market access across non-standardized customs jurisdictions. |
Methodological Framework
Multi-period observation of sturgeon farm output volumes, CITES permit issuance patterns, and hospitality procurement contract terms anchored the trend analysis, supplemented by interviews with aquaculture operations managers, Italian cannery technical directors, Dubai hotel F&B procurement heads, Paris heritage brand retail directors, and Chinese e-commerce category managers. Secondary validation drew from customs trade databases, EU F-Gas Regulation implementation records, SAMR food safety filings, and SEC disclosures from listed luxury goods conglomerates. Bottom-up farm capacity modeling and top-down hospitality demand estimation provided triangulation checks.
Segment-weighting applied species-grade matrices, packaging format distribution shares, and channel penetration rates across the projection horizon. The analytical framework modeled product type, grade certification tier, packaging format, and distribution channel dimensions. CAGRs were derived from supply-constrained demand elasticity curves and aquaculture capacity expansion schedules. Key inputs included sturgeon female maturation timelines, RAS technology adoption curves, and CITES enforcement intensity indices.
The model assumes a particular technology adoption path for recirculating aquaculture systems; alternative pathways for open-pond sturgeon farming with shorter payback periods would alter the capacity expansion outlook. Forecasts reflect documented assumptions about CITES regulatory continuity and feed input cost stabilization. A small set of named triggers—El Niño severity, EU F-Gas grandfathering reversals, and Chinese domestic consumption tax shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Middle East Seafood Market
Seafood
Carp Market
Seafood
US Crustacean Market
Seafood
Global Seafood Market
Seafood
Rainbow Trout Market
Seafood
Haddock Market
Seafood
Frozen Seafood Market
Seafood
COD Market
Seafood
Lobster Market
Seafood
Organic Seafood Market
Seafood
Fish Maw Market
Seafood
Smoked Whiting Market
Seafood
Sardine and Anchovy Umami Concentrate Systems Market
Seafood
Processed Seafood and Seafood Processing Equipment Market
Seafood
Oyster Market
Seafood
GCC Seafood Market