
 North America Seafood Market | 2026-2036
North America Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
North America Seafood Market Analytics
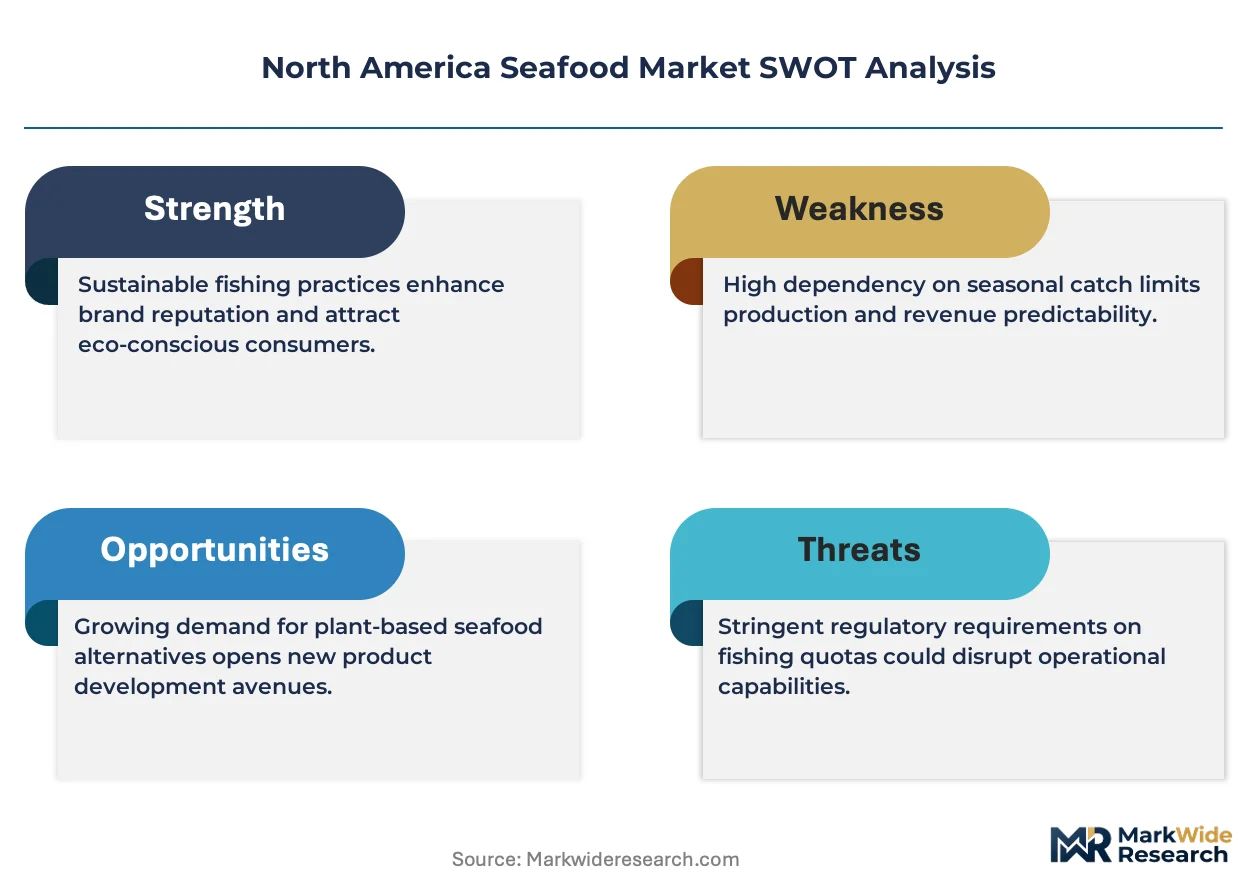
Plant-based protein alternatives is hardening competition for whitefish categories, pressuring conventional processors to defend margin pools. Trident Seafoods Corporation leverages its Alaska vertical integration to control pollock and salmon supply from harvest through retail. Pacific Seafood Group anchors its position with coastwide distribution infrastructure spanning Oregon, Washington, and California. High Liner Foods specializes in value-added frozen seafood for North American food service accounts, competing on recipe-ready formats.
North America seafood encompasses finfish, shellfish, and mollusks harvested from wild fisheries or aquaculture operations, typically processed through filleting, freezing, canning, or drying to extend shelf life and preserve nutritional density. The category serves protein procurement for retail grocery, food service preparation, and industrial ingredient applications. Frozen fish commands the largest volume position due to extended distribution reach and year-round availability, while vacuum packaging is displacing conventional formats as retailers prioritize shelf-life extension and visual product integrity. Canned seafood retains stable demand among household pantry segments, though growth velocity lags behind fresh and chilled alternatives in coastal metropolitan markets.
The U.S. Food and Drug Administration enforces Hazard Analysis Critical Control Point protocols across seafood processing facilities, elevating compliance costs for smaller operators while advantaging scaled participants with dedicated quality systems. NOAA Fisheries administers Magnuson-Stevens Act provisions that govern catch limits and seasonal area closures, directly constraining wild harvest volumes and redirecting investment toward aquaculture expansion. Health Canada and the Canadian Food Inspection Agency maintain parallel import inspection regimes that shape cross-border product flows. Stakeholders must weigh capital allocation between wild-catch efficiency improvements and land-based or offshore aquaculture development as regulatory pressure on ocean harvests intensifies.
Market Dynamics
The North America seafood sector is experiencing acute pressure from the FDA's updated seafood import monitoring program, which tightens traceability mandates and forces processors to rebuild supplier verification systems or exit import-reliant product lines entirely.
Growth Catalysts
- Species diversification:Food service operators from quick-service chains to fine-dining groups are expanding menus beyond traditional whitefish, creating pull-through demand for underutilized wild stocks and aquaculture alternatives.
- Cold-chain infrastructure:Concentrated investment along the U.S. Pacific Coast in port modernization and refrigerated logistics is enabling volume throughput previously constrained by seasonal distribution bottlenecks.
- Health Canada alignment:Parallel import inspection protocols between Canadian and U.S. agencies are reducing cross-border friction, accelerating product velocity for integrated North American supply chains.
Market Restraints
- Magnuson-Stevens Act constraints:NOAA Fisheries catch limits and seasonal area closures directly cap wild harvest volumes, redirecting capital toward aquaculture but delaying near-term supply expansion.
- Alaska supply concentration:Pollock and salmon dependency on single-state harvest geography creates weather and quota volatility that processors cannot hedge through geographic diversification.
- Plant-based substitution:Accelerating formulation improvements in alternative protein categories are compressing price elasticity for conventional whitefish in retail and food service channels.
Strategic Opportunities
- Vacuum packaging displacement:Retailers prioritizing shelf-life extension and visual product integrity are phasing conventional formats, creating upgrade revenue for packaging technology adopters.
- Land-based aquaculture:Regulatory pressure on ocean harvests is concentrating investment incentives in recirculating aquaculture systems, particularly in inland U.S. states with water access and permissive zoning.
- Recipe-ready formats:Food service labor constraints are elevating demand for value-added frozen products that reduce kitchen preparation time and skill requirements.
Industry Challenges
- HACCP compliance burden:FDA enforcement of Hazard Analysis Critical Control Point protocols elevates fixed costs for quality systems, disadvantaging smaller operators without dedicated technical staff.
- Traceability system integration:Foreign supplier verification demands under the updated import monitoring program require processor investment in digital chain-of-custody infrastructure with uncertain payback timelines.
- Aquaculture permitting velocity:Federal and state jurisdictional overlap in offshore lease approvals is delaying project commissioning despite available capital and proven technology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Seafood Market |
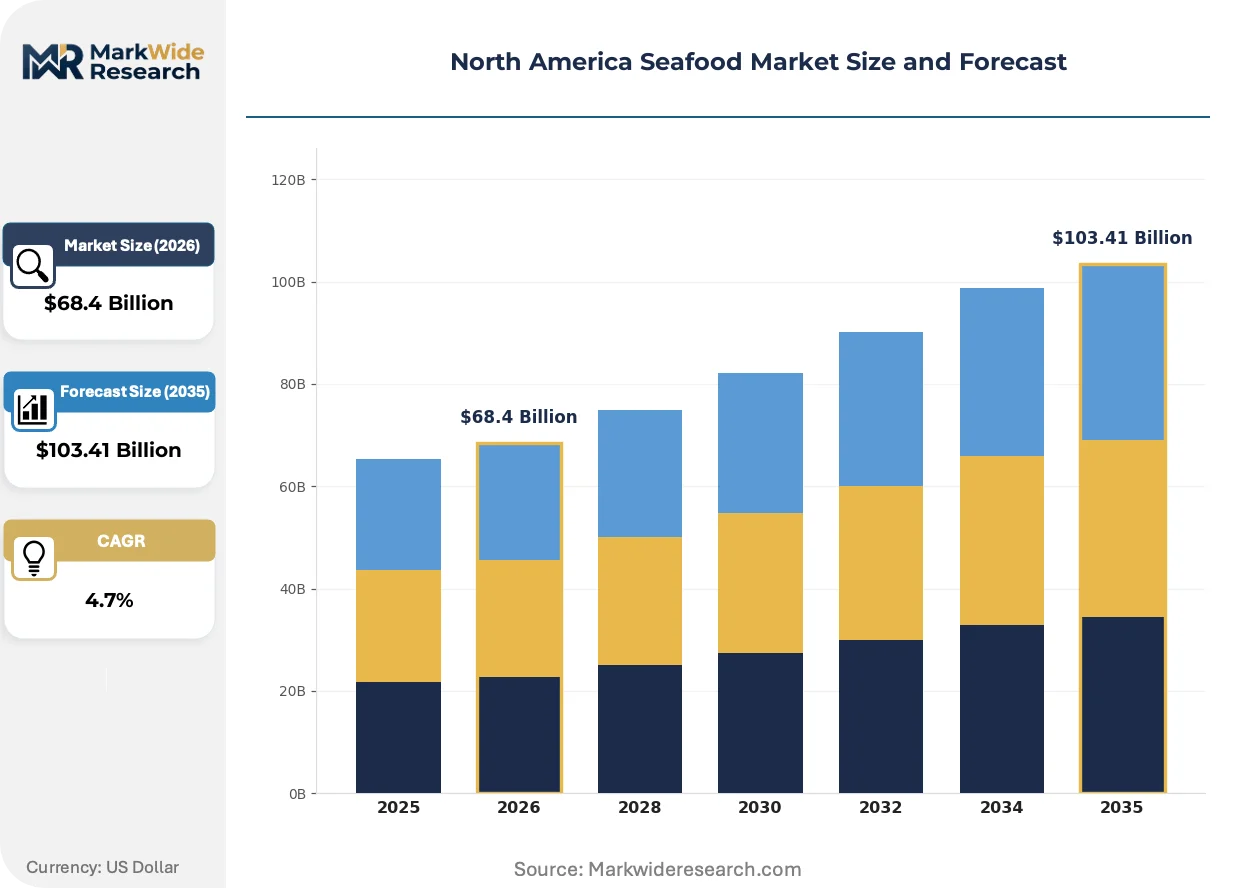
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Fish, Frozen Fish, Canned Seafood, Dried Seafood Distribution Channel: Supermarkets, Online Retail, Fish Markets, Restaurants End User: Households, Food Service, Retailers, Industrial Users Packaging Type: Vacuum Packaging, Modified Atmosphere Packaging, Cans, Bags |
| Companies Covered | Trident Seafoods Corporation, Pacific Seafood Group, High Liner Foods, Clearwater Seafoods, Mowi ASA, Thai Union Group, Beaver Street Fisheries, Inland Seafood, Red Chamber Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Seafood Market Evolving Landscape
Technology adoption across harvesting, processing, and distribution layers is compressing traditional competitive advantages built on geographic proximity to wild stocks.
Blockchain-enabled traceability platforms are consolidating supplier verification workflows into unified digital ledgers. Major retail grocery and food service buyers are mandating participation as a procurement precondition. This consolidation is compressing margins for processors unable to absorb platform integration costs.
Health Canada's updated import inspection regime is synchronizing documentation requirements with FDA protocols, reducing dual-compliance overhead for cross-border operators. The industrial consequence is accelerated consolidation of processing capacity in border-adjacent facilities. Pacific Northwest operators are responding by expanding dual-certified production lines.
Food service procurement is consolidating volume commitments through direct contracts with vertically integrated harvesters, bypassing traditional wholesale distributors. This channel compression is most visible in quick-service chain supply chains, where specification consistency and cost predictability outweigh assortment breadth. Alaska-based operators with captive processing assets are capturing share from broker-reliant competitors.
North America Seafood Market Segmentation
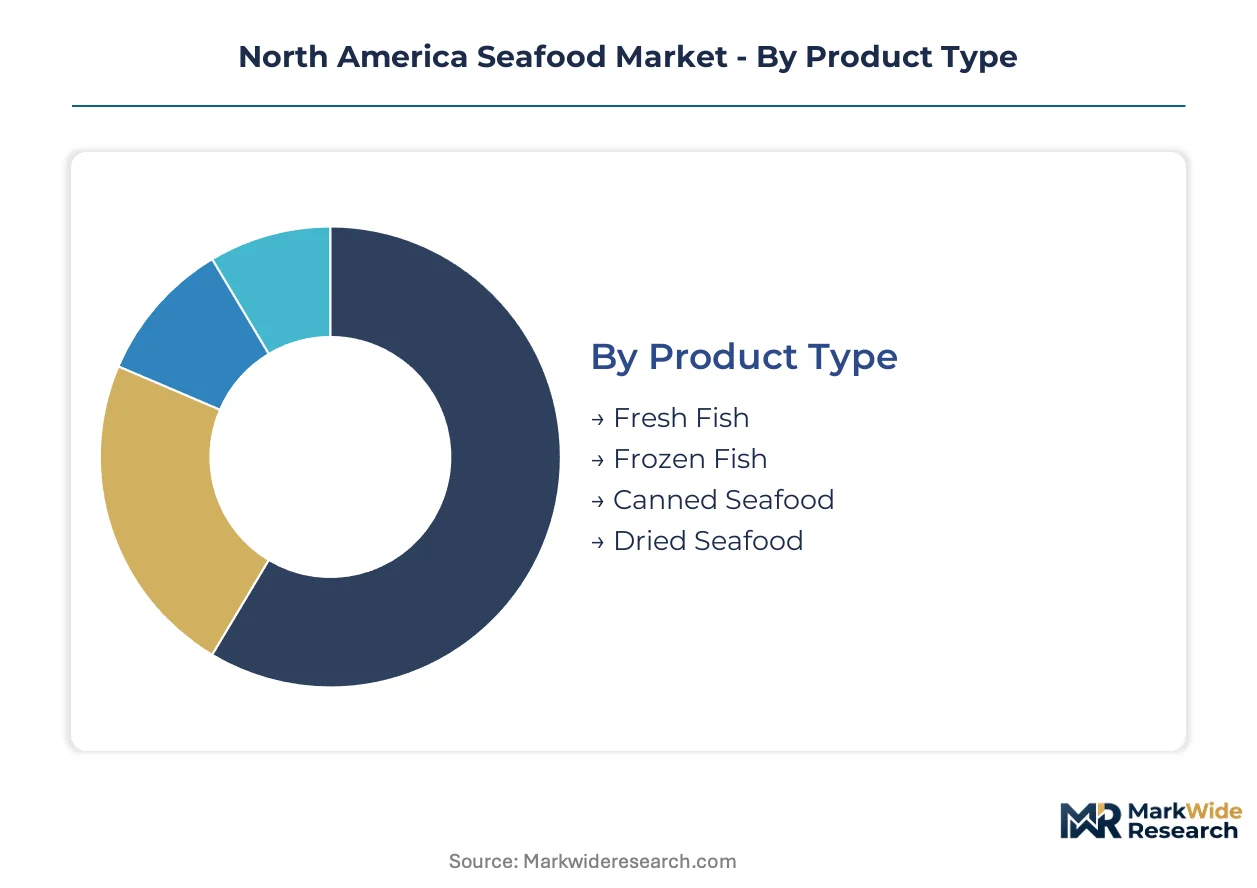
Segmentation in the North America seafood market reveals how supply chain configuration shapes competitive positioning. Product format, channel access, and packaging technology each concentrate margin capture among operators with aligned infrastructure investments.
Product Type:
Supply concentration in Alaska pollock and Pacific salmon harvest geography directly advantages processors with captive cold-chain assets from dock to distribution center.
- Frozen Fish:Blast-frozen at sea or shore plants to lock protein integrity, this format commands volume leadership through year-round distribution reach independent of seasonal harvest windows. Demand concentrates in Midwest and Mountain state retail markets where fresh supply remains logistically constrained. Cold-chain infrastructure investments along the U.S. Pacific Coast are extending frozen product velocity into previously underserved interior markets.
- Fresh Fish:Air-freighted or trucked within 48-72 hours of harvest, fresh product retains premium price positioning in coastal metropolitan markets from Seattle to Boston. The segment depends on direct airport-to-retailer logistics partnerships that smaller operators cannot replicate. FDA HACCP compliance costs disproportionately burden fresh-focused processors without dedicated quality systems.
- Canned Seafood:Thermal-processed in hermetically sealed containers for ambient shelf stability, this format serves pantry-stocking households and emergency food programs with minimal cold-chain dependency. Alaskan salmon and Pacific tuna dominate raw material sourcing.
- Dried Seafood:Moisture-reduced through controlled dehydration or traditional air-drying methods, this category serves ethnic food retail and industrial ingredient applications with concentrated flavor profiles and extended storage life.
Today's leader: Frozen Fish. Tomorrow's challenger: Fresh Fish.
Distribution Channel:
Channel cost structures stratify sharply between capital-intensive retail infrastructure and asset-light digital intermediation.
- Supermarkets:Multi-department retailers with dedicated seafood cases and trained counter staff dominate volume throughput in suburban and exurban geographies. The channel requires slotting fee negotiations and promotional calendar alignment that favors scaled suppliers with marketing budgets. Pacific Northwest chains are expanding private-label seafood programs to capture margin from branded alternatives.
- Restaurants:Food service operators from quick-service chains to independent fine-dining establishments purchase through broadline distributors or direct contracts with vertically integrated harvesters. Labor constraints are elevating demand for portion-controlled, recipe-ready formats that reduce kitchen preparation time.
- Online Retail:Direct-to-consumer platforms and grocery delivery intermediaries are gaining traction in dense urban markets with same-day cold-chain fulfillment capabilities. Customer acquisition costs remain elevated relative to repeat purchase rates.
- Fish Markets:Independent specialty retailers and municipal pier operations serve ethnic communities and quality-focused consumers with whole-fish processing and custom fabrication services. Geographic concentration in coastal Northeast and Pacific cities limits national scale.
Supermarkets currently anchor volume. Restaurants represent the steepest expansion trajectory as food service menu diversification accelerates.
End User:
Procurement sophistication varies dramatically across user categories, from price-sensitive household purchasing to specification-driven industrial ingredient sourcing.
- Food Service:Restaurants, institutional cafeterias, and catering operations purchase on contract terms emphasizing specification consistency and cost predictability. Direct sourcing from Alaska-based vertically integrated operators is compressing traditional wholesale distributor margins. Labor shortages are accelerating demand for value-added products requiring minimal kitchen skill.
- Households:Retail consumers select across fresh, frozen, and shelf-stable formats based on preparation confidence, price point, and meal occasion. Health and wellness positioning drives premium acceptance for omega-3 fortified and sustainably certified products.
- Retailers:Grocery chains and club stores negotiate volume commitments with processors, increasingly mandating blockchain-enabled traceability as a procurement precondition. Private-label expansion is redirecting margin from national brands.
- Industrial Users:Food manufacturers and nutraceutical extractors purchase commodity-grade fish meal, oil, and protein isolates for ingredient applications. Price volatility in wild harvest inputs is redirecting formulation toward aquaculture-derived alternatives.
Food Service leads commercial value capture. Industrial Users are gaining share fastest as alternative protein and supplement markets expand.
Packaging Type:
Packaging technology investment separates operators capable of shelf-life extension and visual integrity from commodity competitors.
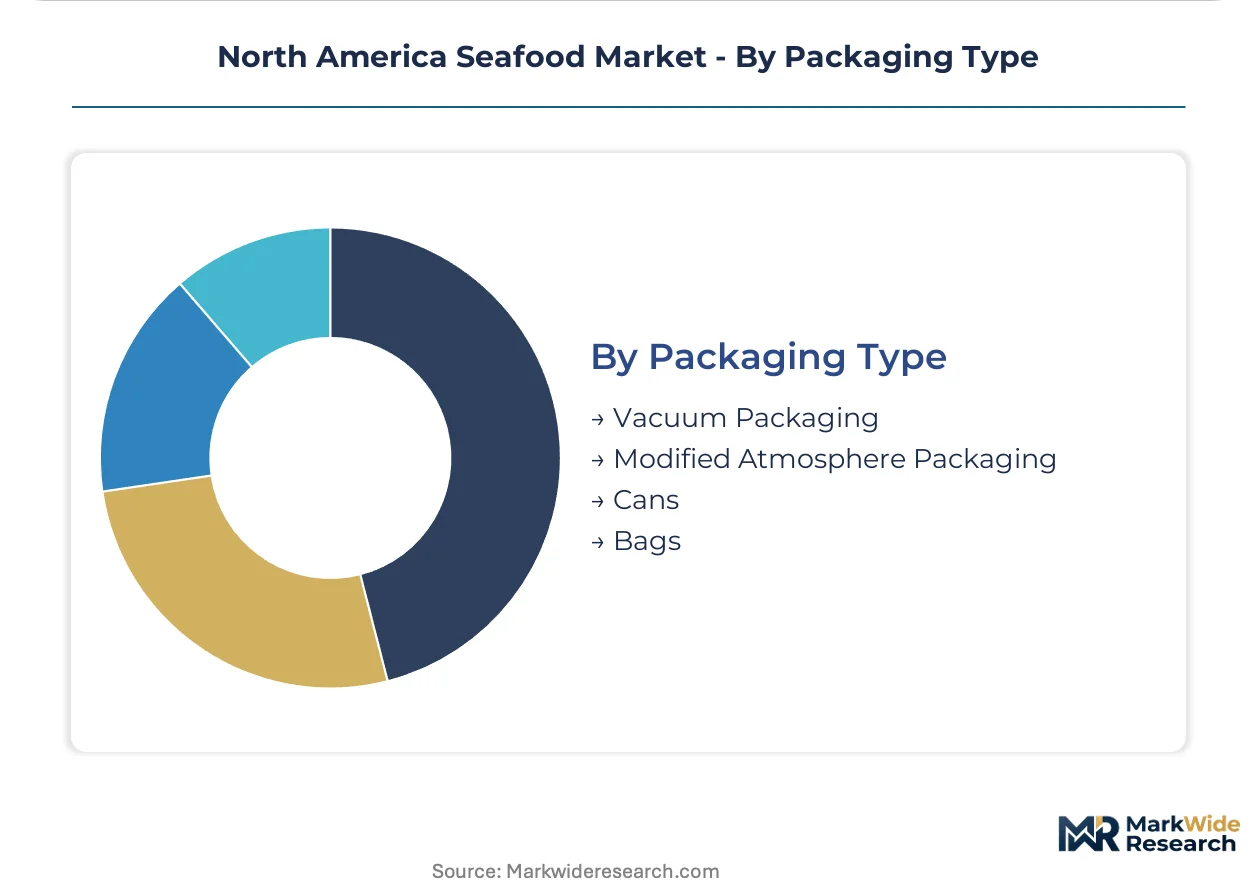
- Vacuum Packaging:Oxygen-evacuated barrier films eliminate oxidative degradation and extend refrigerated shelf life while maintaining product visibility. Retailers are phasing conventional overwrap formats in favor of this technology. Equipment capital requirements favor processors with dedicated packaging lines over mixed-format operations.
- Modified Atmosphere Packaging:Controlled gas mixtures within high-barrier containers retard microbial growth and preserve color in fresh retail presentations. The technology commands premium positioning in upscale grocery channels.
- Cans:Metal containers with double-seamed closures provide hermetic integrity for thermally processed products, enabling ambient distribution without cold-chain dependency.
- Bags:Flexible pouches and laminated films serve frozen product protection and bulk industrial shipping with lower material cost and cube efficiency than rigid alternatives.
Vacuum Packaging dominates new retail specification. Modified Atmosphere Packaging is climbing the fastest as fresh case-ready demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific Northwest processing corridor from Seattle to Anchorage anchors North American seafood throughput, with cold-chain infrastructure investments extending distribution reach into interior markets previously constrained by seasonal logistics.
United States
Alaska pollock and Pacific salmon harvests drive volume, with food service operators diversifying menus beyond traditional whitefish categories. The FDA's updated seafood import monitoring program tightens traceability mandates for foreign suppliers, forcing processor investment in digital verification systems. Seattle-based operators expand dual-certified production lines to capture cross-border retail demand.
Canada
Atlantic lobster and Pacific salmon aquaculture sustain export-oriented production, with Health Canada aligning import inspection protocols with FDA documentation requirements. The Canadian Food Inspection Agency enforces parallel HACCP standards across processing facilities. Vancouver and Halifax anchor coastwise distribution networks serving integrated North American supply chains.
Mexico
Tuna canning and shrimp aquaculture concentrate in Sinaloa and Sonora, supplying North American retail and food service channels with cost-competitive alternatives to domestic harvests. Federal fisheries regulators administer seasonal area closures that redirect investment toward land-based recirculating systems. Mazatlán processing clusters upgrade cold-chain capacity to maintain product integrity on extended distribution routes.
North America Seafood Market Competitive Landscape
Global majors compete with regional champions across supply chain control and distribution infrastructure, producing a tiered structure where scale advantages concentrate among vertically integrated harvesters while mid-cap processors defend niche positioning through species specialization. Three archetypes dominate: Alaska-based integrated operators controlling pollock and salmon from harvest through retail; coastwise distributors leveraging Pacific Northwest port infrastructure for volume throughput; and value-added frozen specialists competing on recipe-ready formats for food service accounts. Competitive moves center on backward integration into captive supply and packaging technology upgrades that extend shelf-life and secure retail specification.
Within the integrated harvester tier, Trident Seafoods Corporation exemplifies the Alaska-based archetype with vertical control over wild-catch supply chains. Pacific Seafood Group anchors coastwise distribution positioning across Oregon, Washington, and California port infrastructure. High Liner Foods occupies the value-added specialist position, competing on frozen format innovation for North American food service accounts.
| Leading Market Players |
|---|
| Trident Seafoods Corporation |
| Pacific Seafood Group |
| High Liner Foods |
| Clearwater Seafoods |
| Mowi ASA |
| Thai Union Group |
| Beaver Street Fisheries |
| Inland Seafood |
| Red Chamber Group |
| Others |
Value Network & Pricing Analysis
Alaska pollock and Pacific salmon price benchmarks cascade through North American seafood supply chains into three-tier pricing structures across premium, standard, and economy levels. FDA import monitoring compliance costs and cold-chain logistics differentials stratify final pricing by buyer archetype and geographic delivery point.
Pricing Analysis
Input-cost pass-through from wild harvest quota volatility and fuel-intensive vessel operations compresses margins for processors without captive supply. Pricing stratifies across premium, standard, and economy tiers based on catch method certification and cold-chain integrity documentation. Cost compression in economy-tier frozen whitefish intensifies because plant-based alternatives erode price elasticity. Quick-service chains exhibit highest price sensitivity while fine-dining groups absorb premiums for traceability-verified species.
Supply Chain Analysis
Regional distribution centers in Seattle, Anchorage, and Los Angeles anchor hub-and-spoke patterns extending frozen product reach into interior U.S. markets. Supply concentrates in Alaska pollock fisheries, British Columbia salmon aquaculture, and Atlantic Canada lobster grounds. Raw material flows hinge on seasonal harvest windows, fuel costs, and quota allocations under Magnuson-Stevens Act provisions. Single-source vulnerability from Alaska weather disruptions threatens volume continuity. Distribution runs through coastwise cold-chain networks with port-adjacent blast-freezing capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American seafood functions as a geographic-arbitrage play between U.S. regulatory compliance costs and Mexican cost-competitive aquaculture, with FDA traceability mandates widening the cost differential.
For Market Incumbents: Cement control over captive supply through backward integration into Alaska shore-based processing or land-based recirculating aquaculture systems in permissive zoning jurisdictions. Defend margin pools against plant-based substitution by investing in vacuum packaging technology that extends retail shelf-life and commands specification premiums.
For New Entrants and Emerging Players: Health Canada's alignment with FDA import inspection protocols in cross-border seafood trade opens a window for dual-certified production facilities in Vancouver and Halifax serving integrated North American supply chains. Target underpenetrated land-based aquaculture in inland U.S. states with water access. Lead with blockchain-enabled traceability as a procurement precondition for retail grocery accounts.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated mid-cap processors controlling species-specialized harvest assets from dock through distribution. Long-term viability centers on aquaculture expansion as wild harvest constraints tighten under NOAA Fisheries seasonal closures. Watch permitting velocity for offshore lease approvals as the inflection signal for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Supply | Alaska-based harvest control insulates processors from quota volatility and foreign supplier verification costs. |
| Land-Based Recirculating Aquaculture Systems | Inland U.S. deployment bypasses Magnuson-Stevens Act constraints and seasonal harvest bottlenecks. |
| Vacuum Packaging Technology Upgrade | Oxygen-evacuated barrier films secure retail specification by extending shelf-life and preserving visual integrity. |
| Blockchain-Enabled Traceability Platform | Digital chain-of-custody infrastructure satisfies FDA import monitoring mandates and buyer procurement preconditions. |
| Dual-Certified Cross-Border Production | Health Canada-FDA protocol alignment reduces compliance overhead for integrated North American supply chains. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national regulatory cluster and processing corridor. The approach combines primary interviews with seafood processing executives, cold-chain logistics operators, food service procurement directors, and retail grocery category buyers with secondary validation from FDA import monitoring filings, NOAA Fisheries harvest data, Health Canada inspection protocols, and customs trade records. Bottom-up volume modeling and top-down value triangulation anchor the analytical framework.
Granularity extends to product format, distribution channel, packaging technology, and end-user category across the projection horizon. CAGRs derive from modeled annual growth trajectories in each segment, with cross-validation against vessel deployment schedules, aquaculture permitting pipelines, and cold-chain infrastructure investment disclosures. Forecast inputs incorporate seasonal harvest variation, regulatory compliance cost inflation, and alternative protein substitution elasticity.
Revisions become necessary when Magnuson-Stevens Act amendments, FDA traceability rule expansions, or abrupt climate disruptions to Alaska fisheries materialize. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Europe Salmon Market
Seafood
Edible Seaweed Market
Seafood
Fish Powder Market
Seafood
Canned Seafood Market
Seafood
North America Frozen and Canned Seafood Market
Seafood
Japan Lobster Market
Seafood
Rainbow Trout Market
Seafood
Salmon Fish Market
Seafood
Shellfish Market
Seafood
Seafood Extracts Market
Seafood
Food Clamshells Market
Seafood
Fin Fish Market
Seafood
Octopus Market
Seafood
Europe Lobster Market
Seafood
Smoked Whiting Market
Seafood
Organic Salmon Market