
 Alaskan Salmon Market | 2026-2036
Alaskan Salmon Market Size, Share, and Industry Trends Forecast 2026-2036
Alaskan Salmon Market Analytics
Capital-intensity divergence between large-scale processors and artisanal operators is rotating competitive advantage toward integrated supply chains. Trident Seafoods Corporation leverages vertical integration from harvest to retail, sustaining cold-chain integrity across Alaska's remote waters. Ocean Beauty Seafoods anchors its position through dominant foodservice distribution networks, while Peter Pan Seafoods Inc. specializes in value-added fillet and portion products for premium retail channels.
Alaskan salmon comprises five Pacific species—chinook, sockeye, coho, pink, and chum—harvested under strict biological escapement mandates with flesh oil content ranging from 4% to 15% depending on species and run timing. Frozen fillets occupy the largest volume position due to extended shelf stability and export logistics efficiency. Smoked products command the strongest margin pool as craft processing techniques differentiate artisanal offerings, while whole fish distribution to Asian markets leads growth velocity among form categories.
NOAA Fisheries, the Alaska Department of Fish and Game, and the Marine Stewardship Council collectively govern catch limits, escapement thresholds, and eco-label eligibility. These frameworks restrict total allowable harvest and mandate seasonal closures that directly constrain supply availability and shape inventory planning cycles. Stakeholders must monitor escapement performance data and certification renewal timelines to anticipate quota adjustments and secure preferred processor allocation slots.
Market Dynamics
NOAA's annual escapement-based quota system creates supply volatility that processors must hedge through multi-year cold storage contracts and forward purchase agreements with catcher-processor fleets.
Growth Catalysts
- MSC Certification Premiums:Marine Stewardship Council eco-labels unlock preferential shelf placement in Whole Foods, Costco, and regional co-op chains across the Pacific Northwest.
- Direct-to-Consumer Freezer Programs:Subscription box operators like Sitka Salmon Shares bypass traditional wholesale tiers, capturing margin that previously flowed to foodservice distributors.
- Chinook Run Rebuilding:Alaska Department of Fish and Game hatchery supplementation programs in Prince William Sound are expanding sockeye and coho terminal harvest availability.
Market Restraints
- Fuel Cost Volatility:Diesel price swings directly compress catcher-vessel operating margins, forcing seasonal fleet reductions in the Bering Sea pollock-salmon overlap fisheries.
- Processing Labor Scarcity:H-2B visa caps constrain workforce availability at remote Bristol Bay and Kodiak plants during peak July-August run timing.
- Farmed Atlantic Substitution:Norwegian and Chilean aquaculture operations deliver year-round supply stability that wild-catch seasonalities cannot match.
Strategic Opportunities
- Smoked Salmon Craft Segment:Small-batch alder and fruitwood smoking techniques command 40-60% price premiums over industrial hot-smoke products in specialty retail.
- Nutraceutical Oil Extraction:Omega-3 concentrate recovery from processing waste streams opens pharmaceutical and dietary supplement channel diversification.
- Carbon-Labeling Alignment:Pending SEC climate disclosure rules position wild Alaskan salmon favorably against feed-intensive farmed alternatives in ESG-scored procurement.
Industry Challenges
- Quality Grader Certification Bottlenecks:NOAA Seafood Inspection Program examiner availability limits throughput at peak season, forcing processors to hold inventory in expensive blast-freeze queues.
- Intermodal Cold Chain Handoffs:Temperature excursions during Anchorage-Seattle air cargo transfers trigger insurance claims and retailer rejection penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alaskan Salmon Market |
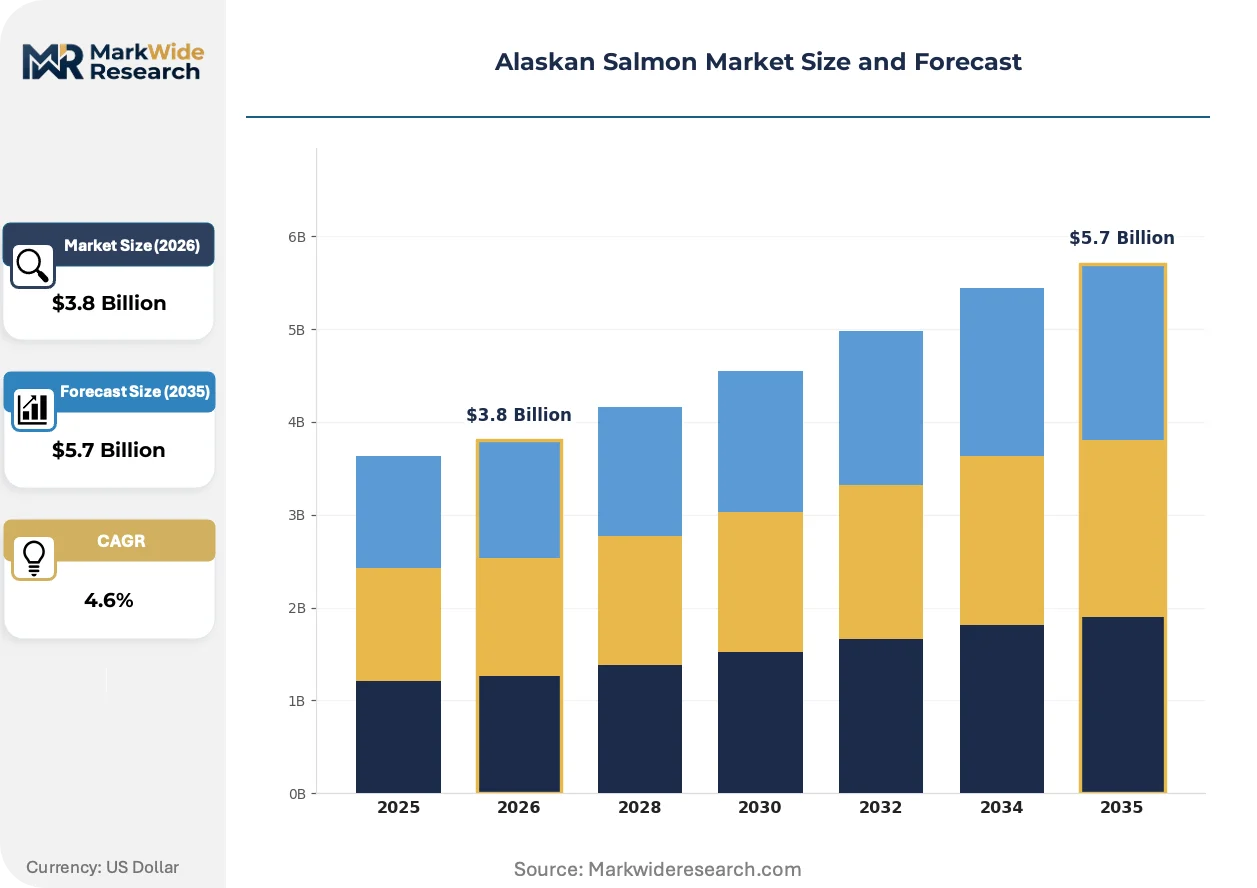
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Frozen, Smoked, Canned Distribution Channel: Retail, Wholesale, Online, Food Service End User: Households, Restaurants, Retailers, Food Manufacturers Form: Whole Fish, Fillets, Steaks, Portions |
| Companies Covered | Trident Seafoods Corporation, Ocean Beauty Seafoods, Peter Pan Seafoods Inc., Icicle Seafoods, Silver Bay Seafoods, Copper River Seafoods, Wild Alaskan Company, Great Alaska Seafood, Iliamna Fish Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alaskan Salmon Market Evolving Landscape
Digital traceability platforms and precision harvesting technologies are compressing information asymmetries between remote fishing grounds and downstream buyers, reshaping how quality premiums are captured and authenticated.
Blockchain-based lot tracking is decomposing the opaque broker layers that historically obscured origin and handling history from end buyers. Regional grocery cooperatives and independent fishmongers in Seattle and Portland are piloting QR-code verification at point-of-sale. This transparency compression is forcing commodity wholesalers to document chain-of-custody or surrender margin to verified-source competitors.
NOAA Fisheries' electronic monitoring mandate for catcher-processor vessels is replacing human observer coverage with camera-and-sensor systems. The regulation reduces per-trip compliance costs while expanding data resolution for escapement modeling. Small-boat operators in Southeast Alaska are retrofitting decks with EM-compliant housing, though upfront capital requirements favor larger fleet consolidations.
Restaurant procurement teams are shortening supplier rotation cycles from annual to quarterly reviews, prioritizing flexibility over volume commitments. This contract compression disadvantages processors with rigid forward-sales structures. The shift is most pronounced in San Francisco and Los Angeles fine-dining channels, where menu volatility and ingredient storytelling override traditional long-term sourcing relationships.
Alaskan Salmon Market Segmentation
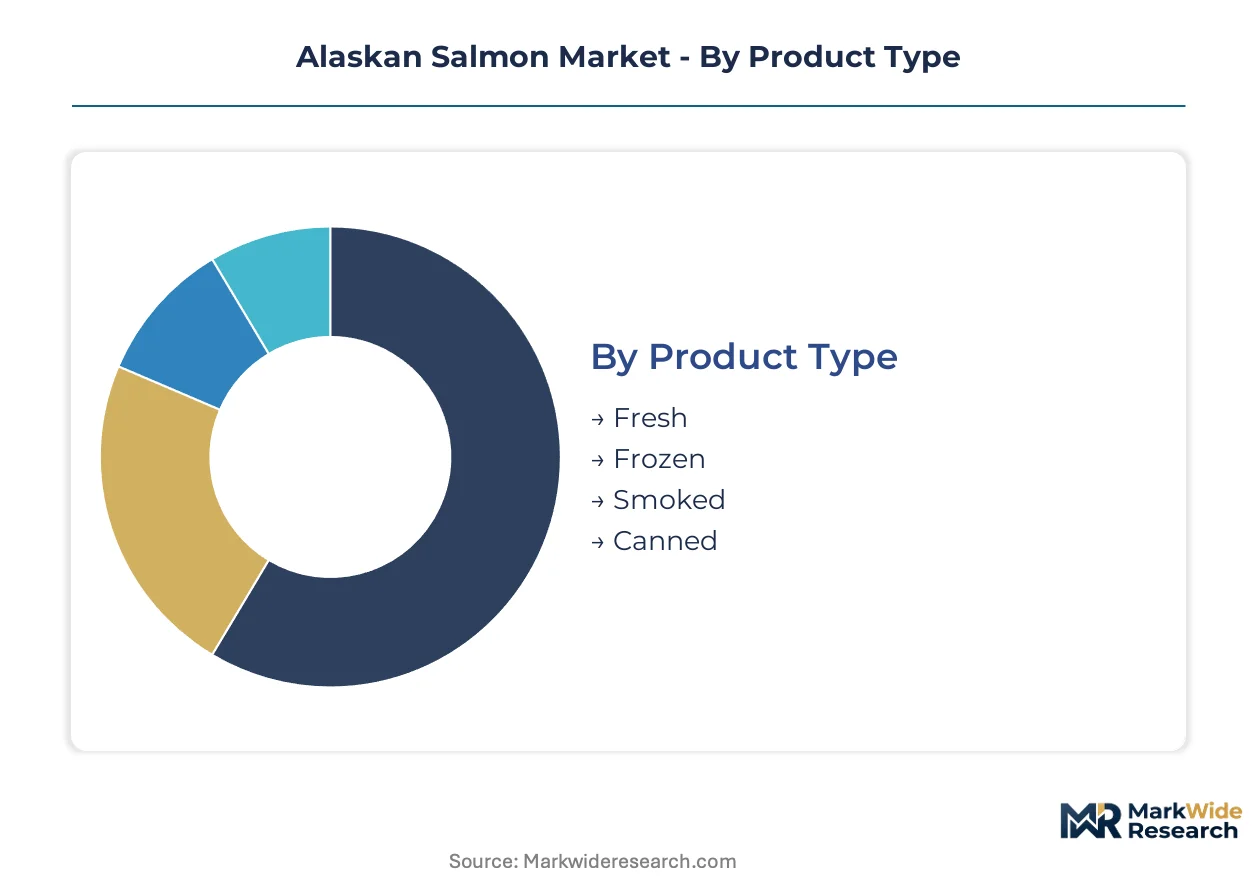
Segmentation in the Alaskan salmon market determines margin capture and channel access. Species-run timing, processing form, and distribution pathway each create distinct price tiers and customer loyalty patterns that processors must align against fleet allocation decisions.
Product Type:
Channel-mix dynamics vary sharply across product types, with fresh commanding premium retail placement while frozen and smoked absorb volume through divergent wholesale pathways.
- Fresh:Air-freighted salmon within 48-72 hours of harvest maintains cellular integrity for sushi-grade applications. Seattle and Los Angeles wholesale terminals absorb the majority of fresh volume, where Japanese-imported handling protocols justify 40-60% price premiums over frozen alternatives.
- Frozen:Blast-frozen at sea or shore plants within six hours of bleeding extends shelf stability to 18-24 months. Bulk export to Asian reprocessing hubs and US foodservice distributors dominates volume flows, with H&G (headed and gutted) forms optimizing container cube utilization.
- Smoked:Alder, applewood, and hickory cold-smoke techniques differentiate Pacific Northwest artisanal processors. Retail delis and direct-to-consumer subscription channels absorb craft production, while industrial hot-smoke feeds mass-market grocery private label programs.
- Canned:Pink and chum species dominate shelf-stable production for food pantry and emergency relief distribution. Alaska's remote processing infrastructure and long shelf life make canned forms critical for rural Alaskan food security programs.
By volume, frozen leads. By growth pace, smoked is ahead.
Distribution Channel:
Cost-to-serve economics separate channel profitability, with direct-to-consumer models capturing margin previously surrendered to wholesale intermediaries.
- Retail:Grocery chains and independent fishmongers in Portland, Seattle, and San Francisco prioritize MSC-certified sourcing for shelf placement. Costco and Whole Foods procurement teams audit chain-of-custody documentation quarterly, rejecting lots with temperature excursion gaps.
- Wholesale:Terminal markets and broadline distributors like Sysco and US Foods aggregate volume for redistribution to smaller retailers and institutions. Consolidation among foodservice distributors has reduced independent processor access, favoring vertically integrated operators with dedicated sales forces.
- Online:Subscription box operators and e-commerce platforms bypass traditional tiered markups. Direct fulfillment from Alaska-based blast-freeze inventory enables harvest-to-door timelines competitive with fresh retail.
- Food Service:White-tablecloth restaurants and institutional cafeterias demand consistent portion sizing and documented origin for menu storytelling. Contract compression from annual to quarterly terms is forcing processors toward flexible inventory positioning.
Food service generates the highest revenue per pound. Online channels are climbing the fastest.
End User:
Application requirements dictate specification rigidity, with restaurants demanding flexibility while manufacturers prioritize contract stability.
- Households:Direct-to-consumer freezer programs and retail purchase decisions increasingly hinge on traceability verification. QR-code lot tracking enables origin confirmation that supports premium willingness-to-pay in Pacific Northwest metro markets.
- Restaurants:Menu volatility and ingredient storytelling requirements drive preference for smaller, frequent deliveries over volume commitments. San Francisco and Los Angeles fine-dining channels rotate suppliers quarterly, prioritizing narrative flexibility.
- Retailers:Private label development and shelf-space negotiations favor processors with year-round supply consistency. Regional grocery cooperatives pilot blockchain verification to differentiate against commodity competitors.
- Food Manufacturers:Pet food, nutraceutical, and ready-meal producers purchase trim and mechanically separated meat under long-term contracts. Omega-3 extraction from processing waste streams creates secondary revenue for integrated processors.
Food manufacturers absorb the highest volume share. Restaurants are expanding most quickly.
Form:
Processing depth determines value recovery from raw material, with whole fish optimizing export logistics and portions capturing retail premium.
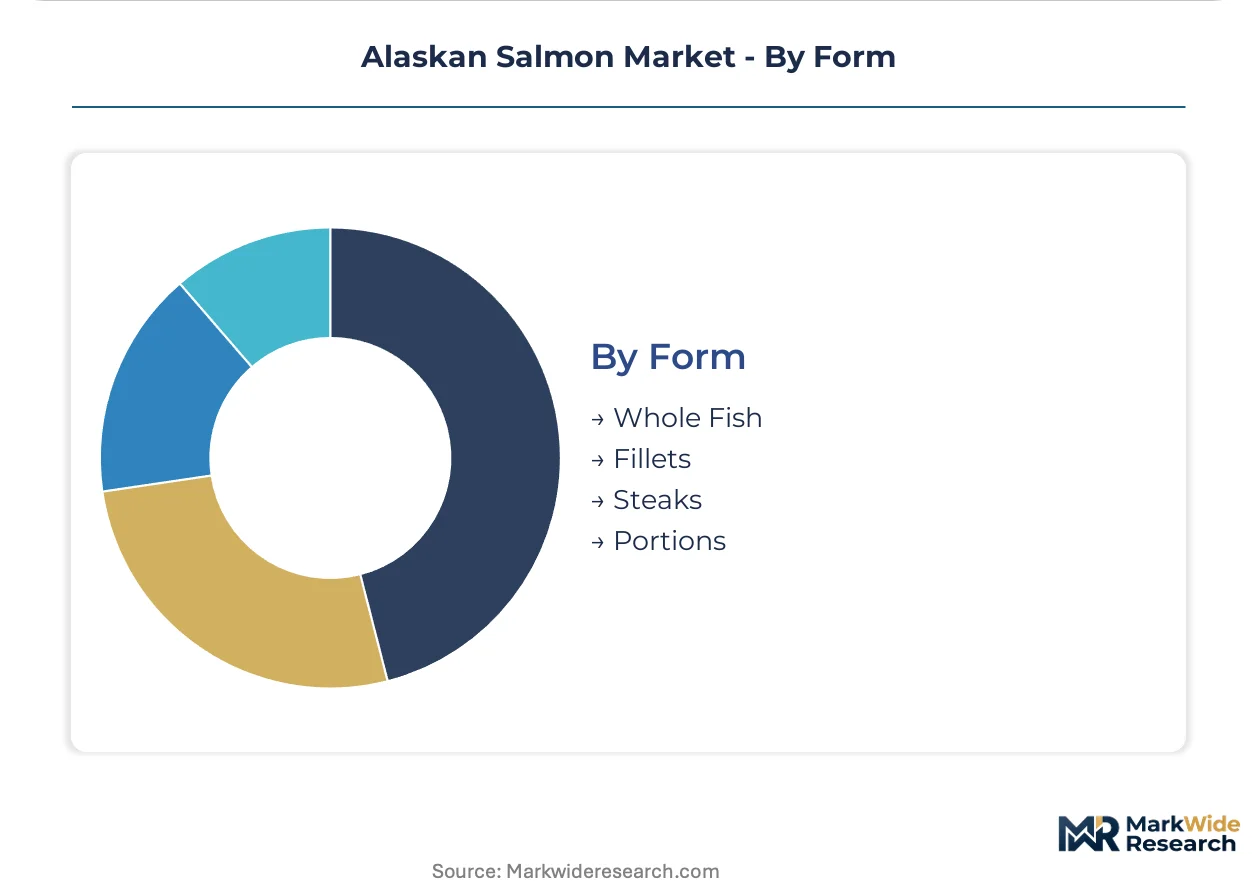
- Whole Fish:H&G (headed and gutted) and round (intact) forms dominate Asian export markets where reprocessing labor costs favor destination-country fabrication. Chinese and Japanese importers specify ice-glaze percentages and container temperature protocols.
- Fillets:Pinbone-out and pinbone-in specifications separate foodservice from retail channels. Automated trimming lines at Kodiak and Bristol Bay plants reduce labor dependency but require volume throughput to justify capital deployment.
- Steaks:Cross-section cuts from larger chinook and sockeye specimens serve white-tablecloth portion control. Thickness consistency and skin-on/skin-off options create SKU proliferation that challenges inventory management.
- Portions:Individually quick-frozen (IQF) and vacuum-packed units target home meal preparation convenience. Retail packaging formats emphasize recipe-ready positioning with marinade and sauce pairings.
Whole fish moves the most tonnage. Portions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pacific Northwest metropolitan markets absorb fresh and frozen fillets for retail and foodservice channels, while Asian export destinations favor whole round and H&G forms for destination-country reprocessing. Domestic direct-to-consumer subscription programs concentrate in coastal California and urban Northeast corridors.
Pacific Northwest
Seattle and Portland retail cooperatives prioritize MSC-certified sourcing with quarterly chain-of-custody audits. Washington State Department of Agriculture enforces cold-chain documentation for interstate seafood shipments. The Puget Sound processing cluster handles the majority of fresh air-freight volume to Los Angeles and San Francisco wholesale terminals.
California
Los Angeles and San Francisco fine-dining channels rotate suppliers quarterly, demanding flexible inventory positioning for menu volatility. California Department of Public Health mandates HACCP compliance for seafood distributors operating through Port of Oakland reefer terminals. San Diego-based direct-to-consumer operators pilot carbon-labeling verification for ESG-scored procurement.
Alaska
Bristol Bay and Kodiak plants process peak July-August sockeye and coho runs under NOAA Fisheries escapement mandates. Alaska Department of Fish and Game administers hatchery supplementation programs in Prince William Sound. The Aleutian Islands catcher-processor fleet operates under electronic monitoring regulations replacing human observer coverage.
Japan
Tokyo and Osaka importers specify ice-glaze percentages and container temperature protocols for whole round salmon. Japan's Ministry of Health, Labour and Welfare enforces food sanitation law compliance for imported seafood. The Tsukiji and Toyosu market terminals remain dominant distribution hubs for Alaskan sockeye reprocessing into sushi-grade applications.
China
Shanghai and Dalian reprocessing hubs absorb H&G forms for value-added fabrication and re-export. China Customs implements cold-chain inspection protocols for Alaskan seafood imports through Qingdao and Ningbo ports. The Yangtze River Delta concentration of ready-meal manufacturers purchases frozen fillets for portion-packaging operations.
Alaskan Salmon Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Alaskan salmon processing. The upper tier controls captive fleet access and multi-year cold storage contracts that buffer NOAA quota volatility. Mid-scale operators concentrate on craft smoking techniques and direct-to-consumer freezer programs. Competitive moves center on backward integration into catcher-processor fleet ownership and geographic expansion through Asian distribution partnerships.
Within the integrated processing tier, Trident Seafoods Corporation and Ocean Beauty Seafoods exemplify vertical control from harvest through retail distribution. Peter Pan Seafoods Inc. occupies a specialist position in value-added fillet and portion products. These three entities represent distinct strategic postures: fleet-scale integration, foodservice network dominance, and premium retail channel focus respectively.
| Leading Market Players |
|---|
| Trident Seafoods Corporation |
| Ocean Beauty Seafoods |
| Peter Pan Seafoods Inc. |
| Icicle Seafoods |
| Silver Bay Seafoods |
| Copper River Seafoods |
| Wild Alaskan Company |
| Great Alaska Seafood |
| Iliamna Fish Co. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between catcher-processor fleets and shore-side plants lock in supply access and price visibility across Alaska's remote processing infrastructure. These agreements buffer NOAA's escapement-based quota volatility while committing buyers to minimum volume thresholds that stabilize plant throughput economics.
Pricing Analysis
Contract-based long-term offtake dominates pricing structure, with spot markets absorbing seasonal surplus and quality downgrades. Price differentiation rests on MSC certification tier and species oil content, with chinook and sockeye commanding premium positioning over pink and chum. Cost compression in foodservice channels is intensifying because restaurant procurement teams compress contract cycles from annual to quarterly terms. Household direct-to-consumer subscribers show least price sensitivity, while institutional food manufacturers absorb volume at thin margins.
Supply Chain Analysis
Bristol Bay's July-August run timing chokepoint concentrates processing capacity utilization and labor recruitment pressure within a narrow harvest window. Raw material flows draw from Southeast Alaska troll fisheries, Prince William Sound hatchery terminals, and Bering Sea catcher-processor operations. Single-source vulnerability runs through H-2B visa-dependent processing labor pools at remote Kodiak and Dutch Harbor plants. Distribution runs through Anchorage air cargo hubs and Seattle reefer terminals for domestic retail, with Asian export moving via containerized H&G forms through Tacoma and Oakland ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic monitoring mandates and blockchain traceability platforms are disrupting information asymmetries that historically protected incumbent margin structures. This regulatory-technological inflection compresses broker layers and redirects value capture toward verified-source operators.
For Market Incumbents: Compound cold-storage capacity in Anchorage and Seattle to buffer NOAA quota volatility and secure preferred retail allocation slots. Deepen backward integration into catcher-processor fleet ownership to defend against subscription box disintermediation. Prioritize MSC certification renewal timelines as Costco and Whole Foods procurement teams tighten chain-of-custody audit frequency.
For New Entrants and Emerging Players: Differentiate on carbon-labeling verification to capture ESG-scored procurement demand from San Diego-based direct-to-consumer operators and Los Angeles fine-dining channels. Target the smoked salmon craft segment where alder and fruitwood techniques command sustained price premiums over industrial alternatives. Launch through regional grocery cooperative pilot programs in Portland and Seattle that pilot QR-code lot tracking at point-of-sale.
For Investors and Strategic Acquirers: Fleet-scale processors with captive cold storage and Asian distribution partnerships represent the most defensible acquisition archetype in a consolidating market. Long-term viability hinges on quota stability and certification maintenance rather than volume expansion. Watch NOAA escapement performance data releases as the signal to watch for quota adjustment direction and processor allocation slot availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catcher-Processor Fleet | Captive harvest access buffers NOAA quota volatility and secures raw material priority. |
| Blockchain Traceability Platform Deployment | QR-code verification at Seattle and Portland retail co-ops compresses opaque broker margins. |
| Craft Smoking Capacity Expansion | Alder and fruitwood cold-smoke techniques differentiate against industrial hot-smoke competitors. |
| Direct-to-Consumer Subscription Launch | Bypasses Sysco and US Foods consolidation that disadvantages independent processor access. |
| Omega-3 Nutraceutical Extraction Investment | Secondary revenue from processing waste streams diversifies beyond commodity fillet sales. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with Alaska Department of Fish and Game biologists, NOAA Fisheries enforcement officers, Bristol Bay plant managers, and Seattle wholesale terminal buyers; and secondary validation through NOAA escapement databases, Marine Stewardship Council certification registries, Alaska Department of Labor H-2B visa allocation records, and customs trade documentation. Bottom-up fleet capacity and processing throughput estimates triangulated against top-down consumption surveys in Pacific Northwest metro markets.
Across the projection horizon, the analytical framework modeled species-run timing, processing form depth, distribution channel economics, and end-user application requirements. CAGRs were derived from historical quota performance, hatchery supplementation program outputs, and channel-shift elasticity parameters. Forecast inputs incorporated electronic monitoring compliance cost trajectories and carbon-labeling regulatory development timelines.
The analysis sits within stated boundaries; outcomes outside sustained MSC certification eligibility and H-2B visa program continuity would require recalibration. Forecasts reflect assumptions regarding escapement threshold achievement and cold-chain infrastructure maintenance. Revision becomes warranted when diesel price volatility or farmed Atlantic substitution rates cross thresholds that alter relative cost positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish Processing Market
Seafood
Asian Sea Bass Market
Seafood
Mussel Extract Market
Seafood
Asia-Pacific Shrimp Market
Seafood
Seafood Processing Market
Seafood
North America Salmon Market
Seafood
Seafood Takeout Market
Seafood
Fish Protein Market
Seafood
Sea Biscuits Market
Seafood
Organic Salmon Market
Seafood
Food Clamshells Market
Seafood
Frozen Seafood Market
Seafood
Fish Fermentation Market
Seafood
North America Frozen and Canned Seafood Market
Seafood
Striped Bass Market
Seafood
Fish Meal Market