
 Europe Dried Scallop Market | 2026-2036
Europe Dried Scallop Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dried Scallop Market Insights
The EU Green Deal is recalibrating seafood sourcing requirements across European food service channels. Clearwater Seafoods leverages its integrated cold-chain infrastructure to secure premium positioning in Northern European markets. High Liner Foods sustains broad retail distribution across multiple EU member states through frozen-and-dried dual-format portfolios. Lund's Fisheries anchors its competitive stance on specialized harvesting partnerships with North Atlantic fisheries.
Dried scallop denotes the mollusk adductor muscle dehydrated to moisture content below 15 percent through controlled air-drying or freeze-drying, yielding a shelf-stable protein ingredient prized for umami concentration in broths and prepared foods. Natural Dried product lines command established volume leadership across European retail channels, while Ready-to-Eat formats capture accelerated growth from convenience-oriented urban consumers. Food Service distribution channels concentrate margin pools through contract supply relationships with restaurant groups and institutional catering operators.
EMA food-contact material standards and EFSA seafood safety thresholds govern import compliance and residue testing protocols for dried scallop shipments entering EU customs territory. REACH chemical safety regulations and EU Green Deal traceability mandates further shape supplier documentation burdens and sustainability certification requirements. Buyers must monitor evolving catch-certification schemes and carbon-border adjustment mechanisms to preserve uninterrupted market access.
Market Dynamics
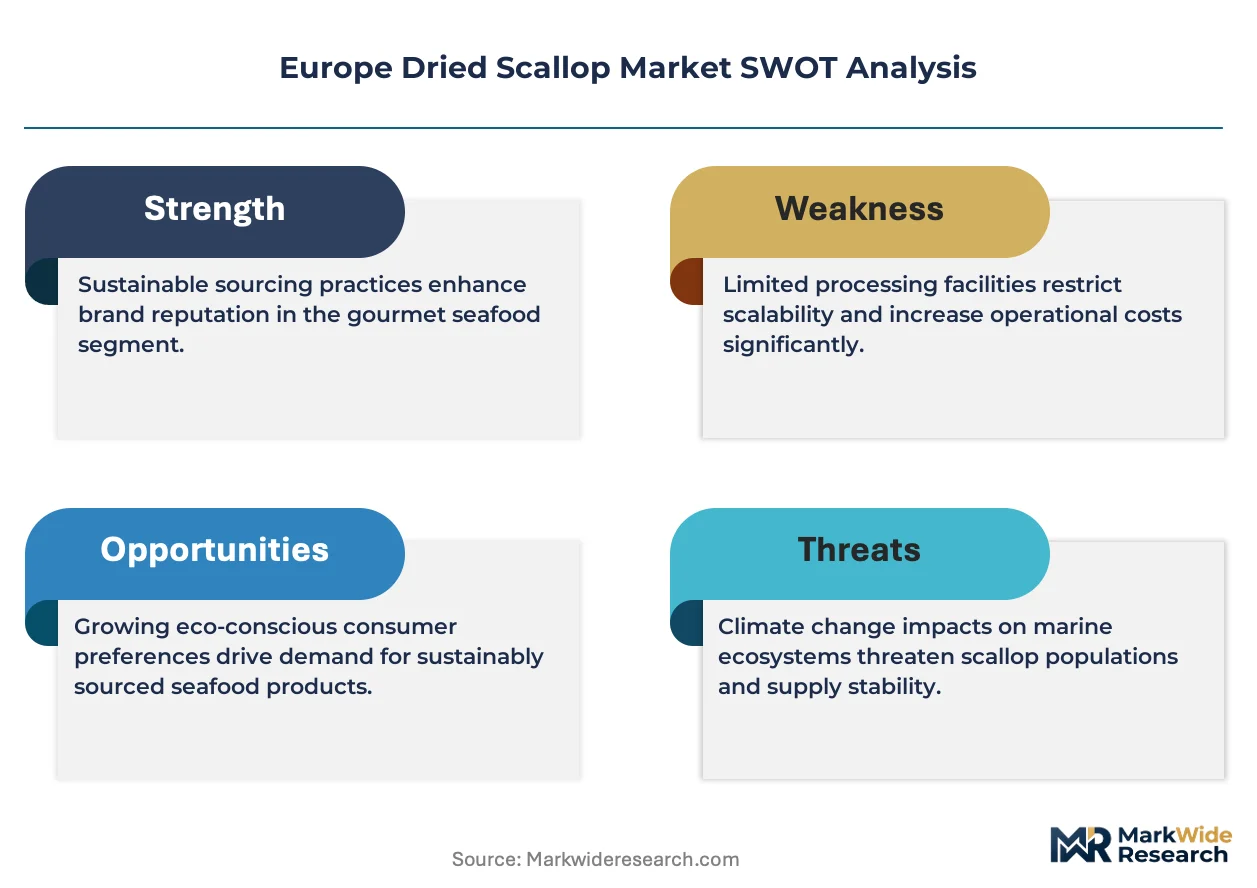
The EU Green Deal's traceability mandates and carbon-border adjustment mechanisms are restructuring dried scallop procurement across European food manufacturing, forcing suppliers to overhaul certification documentation and cold-chain carbon accounting to retain market access.
Growth Catalysts
- EU Green Deal sustainability certification:Mandatory catch-documentation schemes create competitive advantage for compliant North Atlantic suppliers entering French and Spanish retail channels.
- Freeze-drying technology maturation:Controlled sublimation processes preserve volatile flavor compounds, expanding ready-to-eat meal applications for urban convenience consumers in Italy.
- Food service contract consolidation:Institutional catering operators in Northern Europe are centralizing dried seafood procurement through multi-year supply agreements.
Market Restraints
- Input cost volatility:Wild scallop biomass fluctuations in the North Atlantic create raw material price instability for processors.
- Supply concentration risk:Landing volumes cluster around seasonal harvesting windows in specific North Atlantic fishery zones.
- Regulatory friction:EFSA residue testing protocols impose extended customs clearance timelines for non-EU origin shipments.
Strategic Opportunities
- Underpenetrated German retail:Premium dried seafood shelf space remains limited in German hypermarkets relative to Mediterranean markets.
- Plant-based broth convergence:Umami extraction technology from kombu and dried scallop waste streams enables hybrid flavor formulations.
- Direct-to-chef distribution:Bypassing traditional wholesale tiers through specialized seafood purveyors serving Michelin-tier restaurants in Paris and Barcelona.
Industry Challenges
- Specialized drying technician scarcity:Mastery of moisture-content control below 15 percent requires apprenticeship pipelines that European seafood processing regions have failed to maintain.
- Dual-format capex burden:Simultaneous investment in frozen and dried production lines strains mid-scale processor balance sheets.
- REACH documentation complexity:Chemical safety data sheet requirements for processing aids create compliance bottlenecks during supplier onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dried Scallop Market |
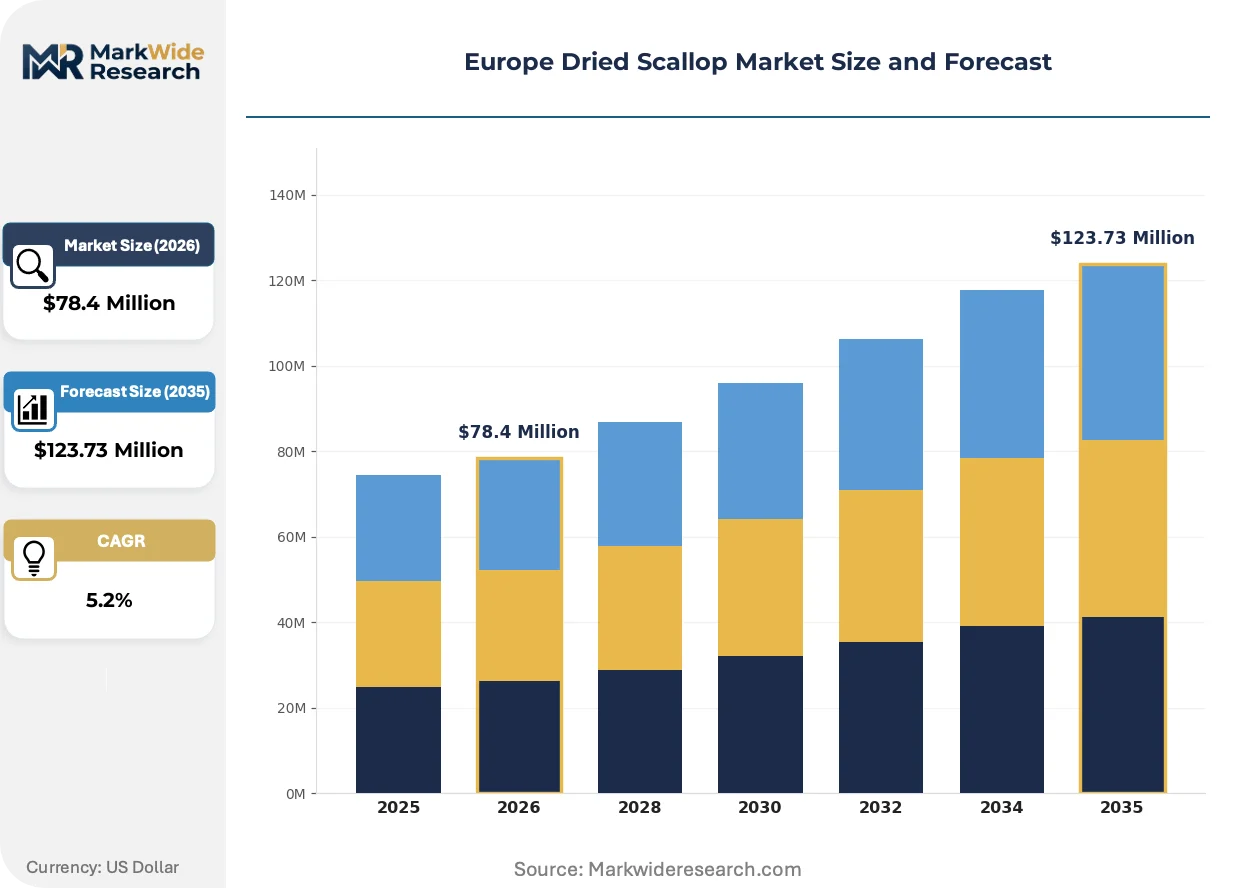
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $123.73 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Dried, Smoked, Flavored, Ready-to-Eat Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service End User: Retail Consumers, Restaurants, Food Manufacturers, Exporters Packaging Type: Bags, Cans, Vacuum Sealed, Bulk Packaging |
| Companies Covered | Clearwater Seafoods, High Liner Foods, Northern Wind, Seacore Seafood Inc, Lund's Fisheries, WHOLEY'S, Fruge Seafood Company, Hannaford Bros. Co., LLC, Blue Harvest Fisheries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dried Scallop Market Trends and Innovations
Automation of quality-assurance protocols and the tightening of sustainability verification standards are compressing supplier qualification timelines across European dried scallop distribution channels.
Hyperspectral imaging systems for moisture-content verification are automating batch-release decisions that previously required manual laboratory analysis. Mid-scale processors in Spain and Portugal are piloting these systems to reduce quality-control labor costs. The technology is automating compliance documentation for EFSA safety thresholds, shrinking the gap between harvest landing and EU customs clearance.
REACH chemical safety regulations now mandate extended substance-of-very-high-concern screening for food-contact materials used in dried seafood packaging. German and Dutch importers are requiring suppliers to submit full material composition disclosures before contract execution. Smaller North Atlantic harvesters lacking in-house regulatory affairs capacity are losing shelf access to integrated operators with dedicated compliance teams.
Urban food service buyers are consolidating purchasing through specialized seafood purveyors rather than broadline distributors. Restaurant groups in Lyon and Madrid now specify dried scallop origin and dehydration method in procurement tenders. This behavioral shift concentrates volume with suppliers offering batch-level traceability, compressing margins for undifferentiated commodity traders.
Europe Dried Scallop Market Segmentation
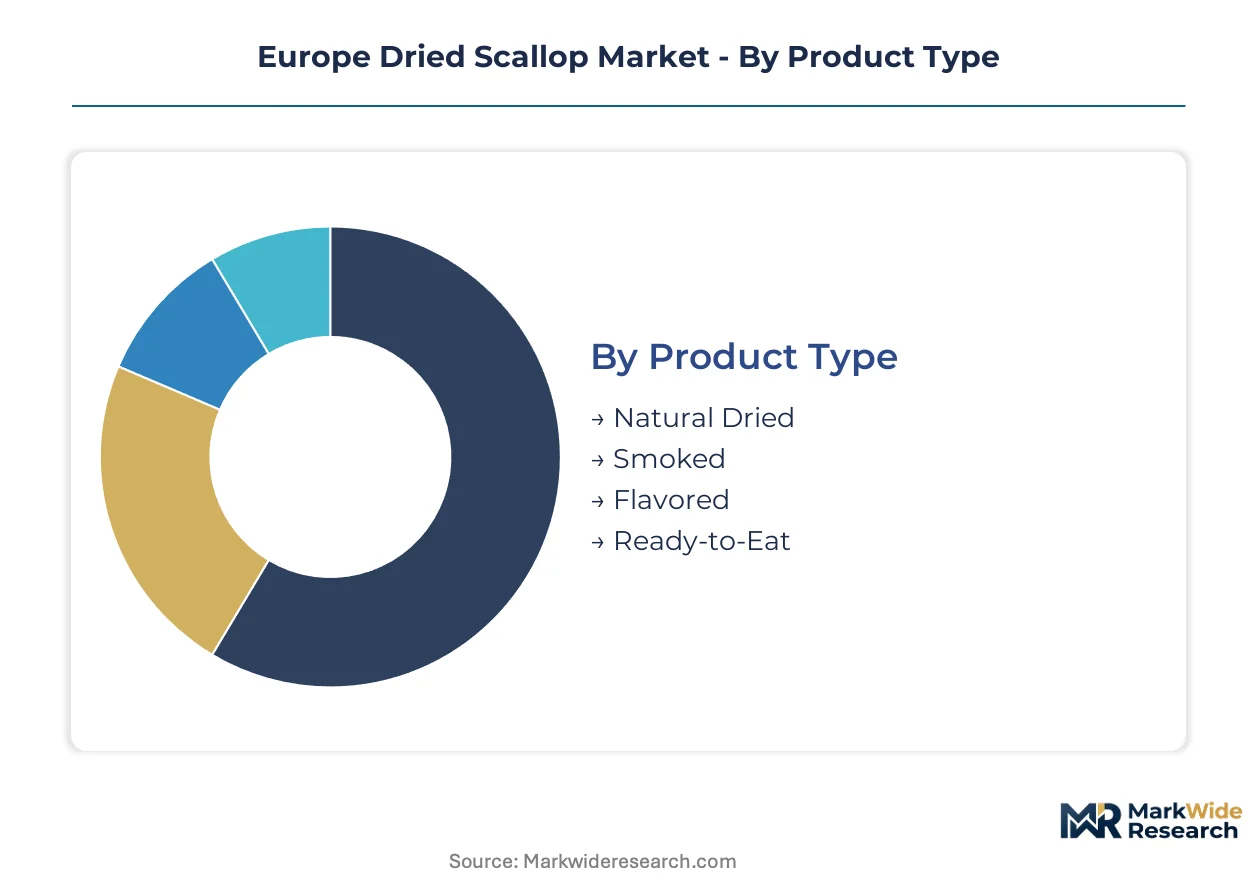
Segmentation in the Europe Dried Scallop Market reveals how procurement patterns diverge between artisanal food service buyers seeking batch-specific provenance and retail channels demanding standardized shelf-ready formats. Understanding these splits enables suppliers to align drying capacity investments with channel-specific margin structures and certification requirements.
Product Type:
Standardization versus craft differentiation defines competitive positioning across this category, with industrial-scale processors competing on consistency while artisanal dryers command premiums through heritage techniques.
- Natural Dried:The adductor muscle undergoes controlled air-drying to sub-15 percent moisture without additives, preserving native umami compounds. French and Spanish retail channels anchor volume demand, though EFSA residue testing protocols extend clearance timelines for non-EU origin shipments.
- Ready-to-Eat:Freeze-dried or low-temperature dehydrated scallops rehydrate instantly for convenience-oriented urban consumers in Italian metropolitan markets. Restaurant groups in Lyon and Madrid now specify dehydration method in procurement tenders, concentrating volume with suppliers offering batch-level traceability.
- Smoked:Cold-smoked variants using beech or oak impart regional flavor profiles prized by Northern European food service buyers.
- Flavored:Pre-seasoned formats with kombu or mushroom extracts target hybrid umami formulations in plant-forward broth applications.
Leading the category by volume: Natural Dried. Expanding most quickly: Ready-to-Eat.
Distribution Channel:
Margin capture varies sharply by channel control, with direct relationships to end-users yielding superior economics compared to wholesale intermediation.
- Food Service:Institutional catering operators in Northern Europe centralize dried seafood procurement through multi-year supply agreements, concentrating margin pools through contract supply relationships. Specialized seafood purveyors bypass traditional wholesale tiers to serve Michelin-tier restaurants in Paris and Barcelona.
- Specialty Stores:Curated retail environments in Mediterranean markets emphasize origin documentation and dehydration method transparency. These outlets sustain premium pricing for compliant North Atlantic suppliers entering French and Spanish retail channels.
- Supermarkets:German hypermarkets remain underpenetrated relative to Mediterranean markets, limiting shelf space for premium dried seafood.
- Online Retail:Direct-to-consumer platforms enable smaller North Atlantic harvesters to reach urban convenience buyers despite lacking in-house regulatory affairs capacity.
Dominant by revenue: Food Service. Steepest expansion trajectory: Specialty Stores.
End User:
Application sophistication determines specification stringency, with industrial buyers imposing stricter documentation burdens than household consumers.
- Restaurants:Chef-driven procurement in Lyon and Madrid specifies dried scallop origin and dehydration method, compressing margins for undifferentiated commodity traders. Urban food service buyers consolidate purchasing through specialized seafood purveyors rather than broadline distributors.
- Food Manufacturers:European food manufacturers expand dried scallop procurement for premium ready-meal formulations, requiring REACH chemical safety data sheets for processing aids.
- Retail Consumers:Convenience-oriented households in Italian cities drive accelerated growth in ready-to-eat formats.
- Exporters:Re-export operations face EU Green Deal traceability mandates and carbon-border adjustment mechanisms, forcing suppliers to overhaul certification documentation.
Highest volume concentration: Restaurants. Gaining share fastest: Food Manufacturers.
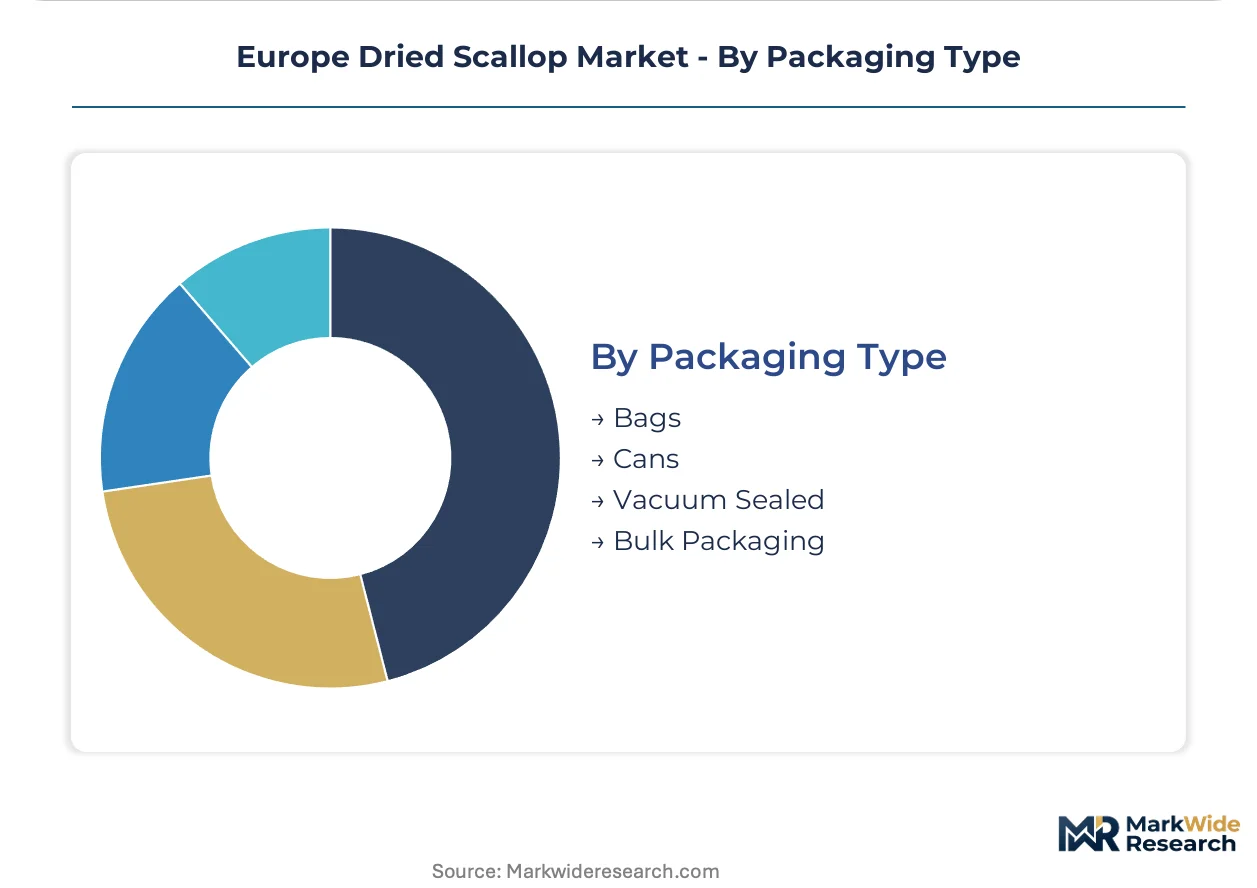
Packaging Type:
Packaging investment correlates with shelf-life extension requirements and regulatory compliance burdens across distribution distances.
- Vacuum Sealed:Oxygen-barrier films extend shelf stability while satisfying EMA food-contact material standards for extended storage. German and Dutch importers require full material composition disclosures before contract execution.
- Bulk Packaging:Food service and manufacturing buyers favor cost-efficient formats for high-throughput processing, though REACH substance-of-very-high-concern screening now applies to food-contact materials.
- Bags:Retail-oriented flexible packaging dominates Mediterranean supermarket shelves with resealable convenience features.
- Cans:Rigid metal packaging persists in traditional gift segments and long-haul export applications requiring maximum durability.
Volume leader: Bulk Packaging. Climbing the fastest: Vacuum Sealed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boulogne-sur-Mer anchors European dried scallop import processing, with its port infrastructure handling North Atlantic landings for redistribution across Mediterranean and Northern European channels. French food service distributors in this cluster supply Lyon restaurants and Parisian institutional catering operators.
France
Traditional seafood consumption in Provence-Alpes-Côte d'Azur sustains specialty store demand for natural dried formats. EFSA residue testing protocols govern import clearance at Marseille-Fos Port. Boulogne-sur-Mer processors supply Parisian restaurant groups specifying batch-level origin documentation.
Spain
Barcelona's Michelin-tier restaurants drive chef-driven procurement specifying dehydration methods in tenders. EU Green Deal traceability mandates recalibrate supplier certification requirements for Basque Country importers. Madrid-based distributors consolidate purchasing through specialized seafood purveyors bypassing wholesale tiers.
Italy
Urban convenience consumers in Milan and Rome accelerate ready-to-eat format adoption. REACH chemical safety data sheet requirements strain mid-scale processor compliance capacity. Emilia-Romagna food manufacturers expand dried scallop procurement for premium ready-meal formulations.
Germany
Premium dried seafood shelf space remains limited in German hypermarkets relative to Mediterranean markets. EMA food-contact material standards govern vacuum-sealed packaging composition disclosures. Hamburg importers require full material composition documentation before contract execution.
Netherlands
Rotterdam's cold-chain infrastructure serves as a redistribution hub for Northern European food service channels. Carbon-border adjustment mechanisms force suppliers to overhaul documentation for uninterrupted market access. Dutch institutional catering operators centralize procurement through multi-year supply agreements.
Europe Dried Scallop Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and traceability capabilities. The vendor base clusters around integrated cold-chain operators, specialized harvest partnerships, and dual-format processors. Three archetypes dominate: North Atlantic integrated harvesters with captive processing, European distributors with regulatory affairs capacity, and mid-scale artisanal dryers competing on heritage techniques. Competitive moves concentrate on M&A for cold-chain assets and strategic partnerships for sustainable certification.
Within the integrated harvester tier, Clearwater Seafoods and Lund's Fisheries represent archetypes of North Atlantic sourcing control. High Liner Foods occupies a position exemplifying dual-format portfolio breadth across frozen and dried segments. These three entities anchor the competitive structure through their respective emphases on infrastructure, harvesting partnerships, and retail distribution scale.
| Leading Market Players |
|---|
| Clearwater Seafoods |
| High Liner Foods |
| Northern Wind |
| Seacore Seafood Inc |
| Lund's Fisheries |
| WHOLEY'S |
| Fruge Seafood Company |
| Hannaford Bros. Co., LLC |
| Blue Harvest Fisheries |
| Others |
Pricing and Supply Chain Analysis
Family-owned North Atlantic harvesters anchor supply-side ownership patterns, concentrating pricing power among Boulogne-sur-Mer processors who control redistribution into French and Spanish retail channels. EU Green Deal traceability mandates force these mid-caps to absorb certification costs that integrated operators with dedicated compliance teams pass through as premiums.
Pricing Analysis
Umami-concentration yield anchors value-based pricing, with batch-level flavor compound testing commanding premiums from Lyon restaurant groups. Three-tier pricing structure across premium traceable, standard certified, and economy commodity levels separates suppliers by documentation depth. Pricing pressure stems from EFSA residue testing protocols extending customs clearance timelines for non-EU origin shipments. Food manufacturers exhibit highest price sensitivity due to REACH compliance documentation burdens, while Michelin-tier restaurants absorb premiums for batch-specific provenance.
Supply Chain Analysis
EU Green Deal local-content traceability mandates reshape sourcing toward North Atlantic fisheries with catch-documentation scheme compliance. Raw material flows concentrate on Canadian Maritimes, Icelandic waters, and Norwegian coastal zones. Processing depends on wild scallop biomass fluctuations, freeze-drying equipment availability, and specialized drying technician apprenticeship pipelines. Single-source vulnerability clusters around seasonal harvesting windows in specific fishery zones. Distribution runs through Rotterdam cold-chain infrastructure serving Northern European food service channels and Boulogne-sur-Mer redistribution into Mediterranean markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive North Atlantic harvesting partnerships defines the current competitive race, with processors securing landing rights to control input cost volatility and certification documentation quality.
For Market Incumbents: Anticipate margin compression from REACH substance-of-very-high-concern screening bottlenecks by building in-house regulatory affairs capacity. Consolidate specialized drying technician apprenticeship pipelines before demographic retirement waves hollow out craft knowledge. Channel control through direct-to-chef distribution in Paris and Barcelona insulates against wholesale tier disintermediation.
For New Entrants and Emerging Players: EU Green Deal sustainability certification in France and Spain opens a window for compliant North Atlantic suppliers to capture shelf space from documentation-deficient competitors. German hypermarkets remain the most penetrable geography given limited premium dried seafood shelf space relative to Mediterranean saturation. Ready-to-eat format specialization targeting Milan and Rome urban convenience consumers offers a defensible go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale processors with freeze-drying capex already deployed but balance sheets strained by dual-format investment burdens. Long-term viability hinges on securing sustainable certification moats before carbon-border adjustment mechanisms harden. Watch EFSA residue testing protocol harmonization with UK post-Brexit standards as an inflection signal for cross-channel trade friction.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Harvesting Partnerships | Captive North Atlantic landing rights stabilize raw material cost volatility against biomass fluctuations. |
| Freeze-Drying Capacity Expansion | Controlled sublimation preserves volatile flavor compounds for Italian ready-to-eat meal applications. |
| Sustainability Certification Program | EU Green Deal catch-documentation schemes create competitive advantage in French retail channels. |
| Direct-to-Chef Distribution Network | Bypassing wholesale tiers captures margin pools from Lyon and Barcelona restaurant procurement consolidation. |
| Regulatory Affairs Capability Buildout | In-house REACH and EFSA compliance teams reduce supplier onboarding bottlenecks for German importers. |
Research Methodology
Document review covered EU customs trade databases, EFSA seafood safety threshold documentation, and North Atlantic fishery landing statistics, complemented by interviews with Boulogne-sur-Mer processors, Rotterdam cold-chain operators, and Parisian institutional catering procurement directors. Primary fieldwork engaged dried seafood category managers at French and Spanish specialty retailers, compliance officers at German and Dutch importers, and Emilia-Romagna food manufacturing R&D leads. Secondary validation drew from EMA food-contact material standards filings, REACH substance-of-very-high-concern screening protocols, and EU Green Deal traceability mandate implementation guidance. Bottom-up segmentation modeling triangulated against top-down market sizing from trade flow analysis.
Historical volume trajectories cross-referenced against panel input from North Atlantic harvester associations and European food service distributor consortia shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include dehydration method, distribution channel control level, end-user application sophistication, and packaging format compliance burden. CAGRs derived from slope consensus across import volume trends, price trajectory indicators, and channel penetration saturation points. Industry-specific forecast inputs incorporated wild scallop biomass survey data and freeze-drying technology adoption curves among Spanish and Portuguese mid-scale processors.
Caveats apply where EFSA residue testing protocol revisions, North Atlantic fishery quota allocations, or carbon-border adjustment mechanism implementation timelines could materially shift the outlook. Forecasts reflect assumptions around certification scheme stability and cold-chain infrastructure investment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish Oil Market
Seafood
Groundfish Market
Seafood
Japan Frozen Seafood Market
Seafood
Oyster Meal Market
Seafood
Organic Salmon Market
Seafood
US Crustacean Market
Seafood
Sea Bream Market
Seafood
Striped Bass Market
Seafood
Sardine and Anchovy Umami Concentrate Systems Market
Seafood
Halibut Market
Seafood
Asia Pacific Canned Seafood Market
Seafood
North America Frozen and Canned Seafood Market
Seafood
Salmon Market
Seafood
Seafood Takeout Market
Seafood
Canned Anchovy Market
Seafood
Herring Market