
 North America Flavors and Fragrances Market | 2026-2036
North America Flavors and Fragrances Market Size, Share, and Industry Trends Forecast 2026-2036
North America Flavors and Fragrances Market Intelligence
Ingredient customization revenue is narrowing as large buyers consolidate formulation partnerships. Givaudan SA leverages captive botanical sourcing to secure supply continuity for natural flavor lines. Kerry Group anchors its position through backward integration into dairy and savory taste modulation. International Flavors & Fragrances competes by extending its bioscience platform across enzyme-derived flavor precursors.
Flavors and fragrances comprise volatile organic compounds, essential oil distillates, and synthetic aroma molecules engineered for olfactory stability and food-safe migration limits. These compositions serve to mask off-notes, enhance palatability, or confer brand-distinctive scent signatures in packaged goods and personal care items. Natural flavors and essential oils command premium positioning as beverage manufacturers reformulate away from artificial additives. Synthetic flavors retain volume dominance in bakery and confectionery applications where heat stability and cost predictability outweigh clean-label preferences. Aroma chemicals represent the fastest-expanding margin pool, driven by precision perfumery in cosmetic firms and niche household products.
FDA oversight of GRAS self-determination and EPA reporting on volatile organic compound emissions shape product development timelines and facility siting decisions across the United States. Health Canada and Mexico's national health regulator apply parallel but non-identical safety thresholds, fragmenting compliance architecture for cross-border suppliers. Stakeholders must monitor divergence between California's Proposition 65 warning requirements and federal labeling minimums, as this gap determines which formulations gain shelf access in the region's largest state economy.
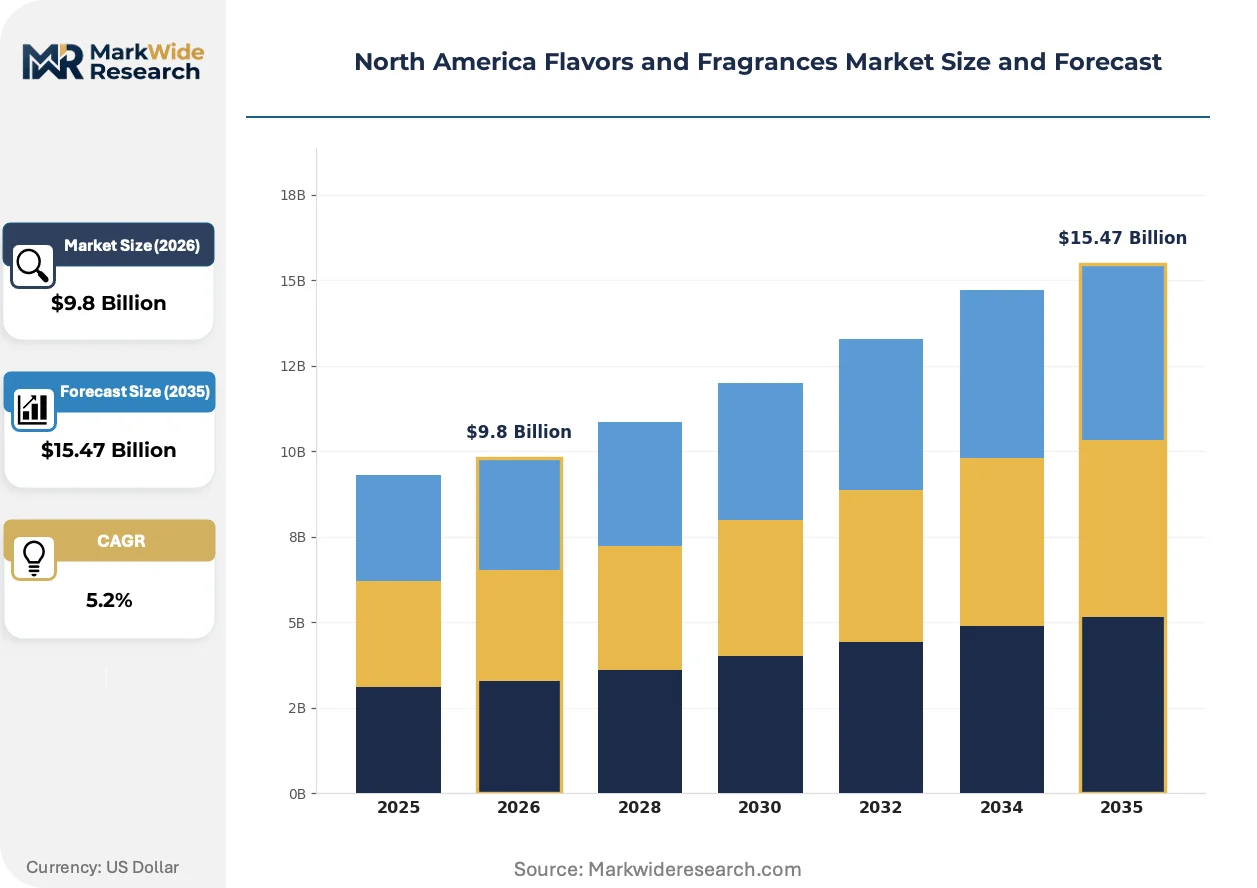
Market Dynamics
Clean-label beverage reformulation is compressing synthetic flavor margins while pulling capital toward captive botanical supply chains and extraction infrastructure across California and Mexico.
Growth Catalysts
- California Proposition 65 enforcement:Warning label requirements for synthetic additives are accelerating natural flavor substitution in personal care and packaged foods.
- Enzymatic bioconversion platforms:Bioscience-derived flavor precursors are reducing extraction yield volatility for heat-sensitive citrus and vanilla profiles.
- Mexico's food processing corridor:Multinational CPG manufacturing expansion near Querétaro and Guanajuato is concentrating demand for regional flavor compounding capacity.
Market Restraints
- Essential oil feedstock volatility:Climate-driven crop failures in Madagascar vanilla and Indian mint are compressing gross margins on natural flavor lines.
- GRAS self-determination scrutiny:FDA post-market surveillance of flavor additive safety claims is extending product launch timelines by 8-14 months.
- Heat stability ceiling:Natural flavor molecules degrade above 180°C, limiting penetration in high-temperature bakery and extruded snack applications.
Strategic Opportunities
- Precision fermentation scale-up:Microbial production of rare terpenes and lactones is opening supply of molecules previously constrained by agricultural harvests.
- EPA volatile organic compound exemptions:Reformulated fragrance compounds with reduced photochemical reactivity are gaining expedited registration pathways for household products.
- Direct-to-brand digital compounding:Mid-size beverage and cosmetics brands are bypassing traditional distributor networks for customized flavor development services.
Industry Challenges
- Flavor chemist talent scarcity:Retirement waves among senior formulation scientists are outpacing university pipeline output in the United States and Canada.
- Cross-border compliance fragmentation:Divergent maximum residue limits between FDA, Health Canada, and Mexico's national health regulator are forcing triple-registration strategies.
- Legacy ERP integration:Batch record digitization for traceability mandates is clashing with decades-old manufacturing execution systems at mid-tier compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Flavors and Fragrances Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.47 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Synthetic Flavors, Essential Oils, Aroma Chemicals Application: Beverages, Bakery, Confectionery, Personal Care End User: Food Manufacturers, Beverage Companies, Cosmetic Firms, Household Products Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | International Flavors & Fragrances, Symrise AG, Givaudan SA, dsm-firmenich, Sensient Technologies, Archer Daniels Midland Company, Kerry Group, MANE Group, Takasago International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Flavors and Fragrances Market Strategic Shifts & Innovations
Extraction technology convergence with synthetic biology is dissolving the traditional natural-versus-artificial formulation boundary, while regulatory disclosure mandates are rewriting competitive advantage around supply chain transparency.
Supercritical CO2 extraction with ethanol co-solvent modification is hybridizing with precision fermentation to produce botanical-derived flavor concentrates with standardized molecular profiles. Premium beverage brands in California and the Pacific Northwest are adopting these hybrid inputs at 3-4x the rate of conventional extract buyers. The technology is hybridizing procurement criteria, forcing compounders to maintain dual qualification standards for "natural" and "nature-identical" supply streams.
EPA reporting obligations for volatile organic compound emissions are tightening facility siting constraints for fragrance manufacturing in the United States. New source performance standards are requiring catalytic oxidizer installations at greenfield plants, adding $2-4 million in baseline capex. Aroma chemical producers with existing Gulf Coast infrastructure are expanding capacity rather than facing California and Northeast air quality district permitting delays.
Brand-agnostic flavor houses are losing share to captive innovation partnerships as CPG consolidators demand exclusive access to proprietary modulation technologies. Long-term formulation agreements with minimum volume commitments are displacing spot purchasing for core taste platforms. This concentration is most visible in dairy and savory categories, where Kerry Group and Givaudan SA have locked multi-year supply relationships with top-five North American food manufacturers.
North America Flavors and Fragrances Market Segmentation
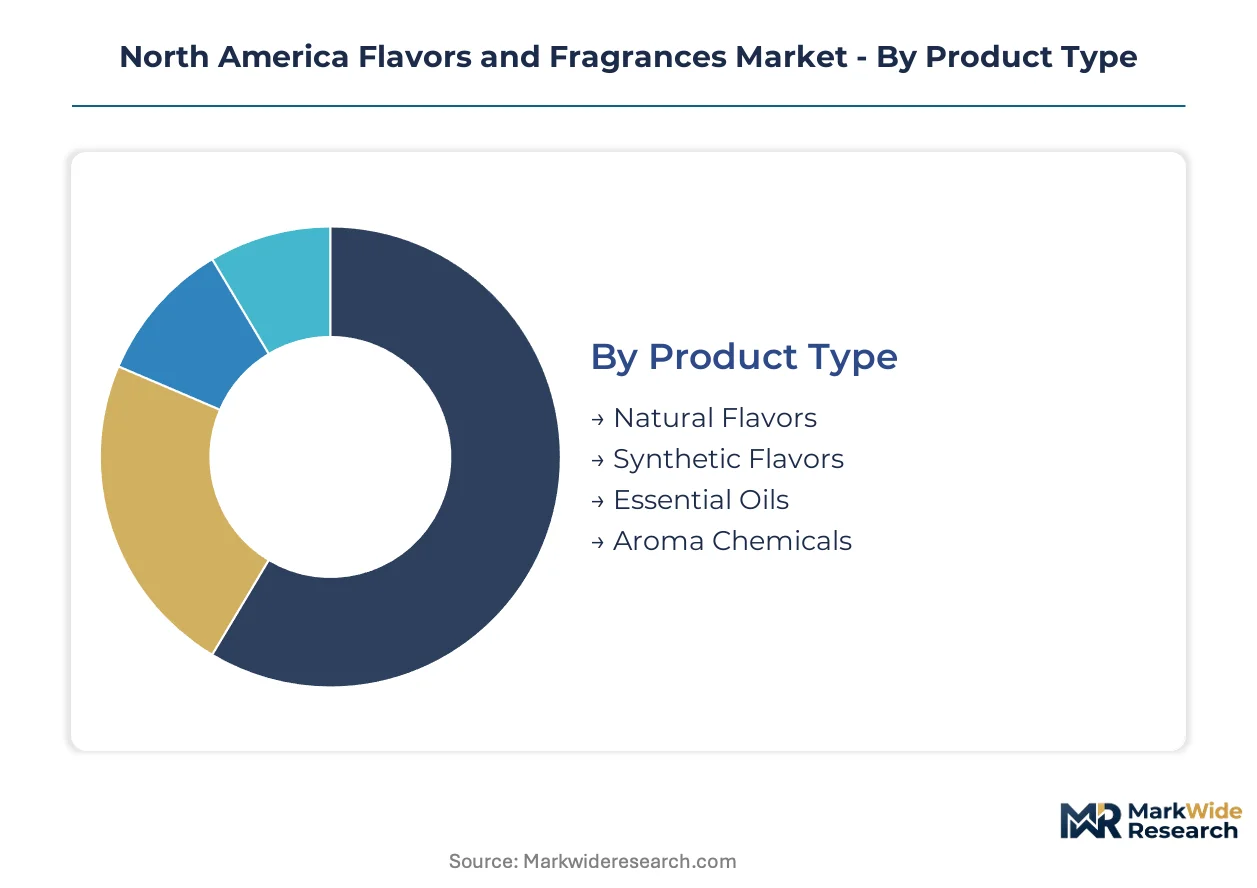
Segmentation in North American flavors and fragrances reveals divergent margin structures and inventory velocity patterns. Product type determines capital intensity in extraction infrastructure, while application channels dictate regulatory exposure and reformulation frequency.
Product Type:
Cycle times vary dramatically across this category, with aroma chemicals turning inventory fastest and essential oils exhibiting the longest procurement lead times due to agricultural seasonality.
- Natural Flavors:These comprise volatile organic compounds extracted from botanical sources through distillation, fermentation, or enzymatic processes. Beverage manufacturers in California's clean-label corridor drive procurement, though FDA GRAS documentation requirements extend qualification cycles. Essential oil feedstock volatility from Madagascar vanilla and Indian mint compresses gross margins unpredictably.
- Synthetic Flavors:Engineered aroma molecules deliver olfactory stability and precise migration limits for heat-intensive applications. Bakery and confectionery manufacturers across the Midwest and Southeast maintain volume dominance here, prioritizing cost predictability over clean-label positioning. Heat stability above 180°C enables penetration in extruded snack segments where natural alternatives degrade.
- Essential Oils:Steam-distilled or cold-pressed concentrates from citrus, mint, and spice botanicals. Personal care formulators in California's Proposition 65 compliance environment favor these for transparency positioning.
- Aroma Chemicals:Isolated molecular compounds synthesized or bioconverted for precision perfumery. Cosmetic firms and niche household product manufacturers in the Northeast concentrate demand for rare terpenes and lactones.
Synthetic flavors anchor the volume base while aroma chemicals gain share at the steepest rate.
Application:
Cost tier differentiation separates commodity formulation from premium positioning, with beverage and personal care commanding price premiums over bakery and confectionery.
- Beverages:Clean-label reformulation is compressing synthetic flavor margins while pulling capital toward captive botanical supply chains. California and Pacific Northwest brands adopt hybrid extraction-fermentation inputs at accelerated rates.
- Bakery:Heat stability requirements favor synthetic flavor molecules that withstand oven temperatures exceeding 180°C. Regional bread and snack manufacturers prioritize cost predictability over natural positioning.
- Confectionery:Hard candy and chocolate applications demand precise flavor release profiles and extended shelf stability. Midwest manufacturing clusters concentrate procurement volume.
- Personal Care:Proposition 65 warning requirements accelerate natural flavor substitution in fragrances and functional cosmetics. California's regulatory environment shapes formulation decisions nationwide.
Beverages command premium pricing tiers while personal care expands most quickly on regulatory tailwinds.
End User:
Customer type determines contract structure, with food manufacturers favoring long-term formulation agreements and household products maintaining spot purchasing flexibility.
- Food Manufacturers:Consolidated CPG players demand exclusive access to proprietary modulation technologies. Multi-year supply relationships with minimum volume commitments displace spot purchasing for core taste platforms.
- Beverage Companies:Mid-size brands bypass traditional distributor networks for customized flavor development services. Direct-to-brand digital compounding is reshaping procurement patterns.
- Cosmetic Firms:Precision perfumery requirements drive demand for rare terpenes and standardized molecular profiles. Bioscience-derived precursors reduce extraction yield volatility.
- Household Products:EPA volatile organic compound reporting obligations tighten formulation constraints. Reformulated compounds with reduced photochemical reactivity gain expedited registration pathways.
Food manufacturers anchor the volume base while beverage companies gain share at the steepest rate.
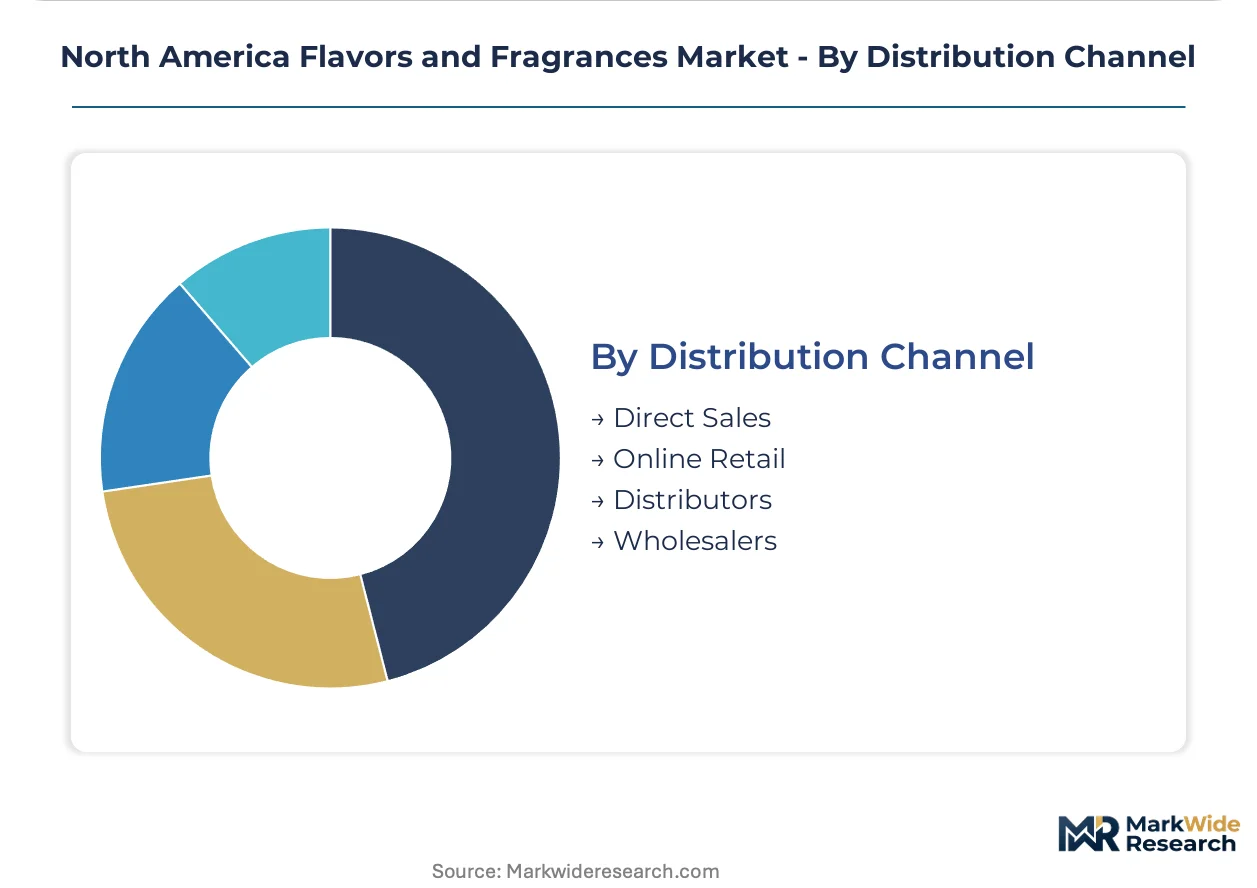
Distribution Channel:
Supply concentration varies by channel, with direct sales consolidating around large compounders and distributors fragmenting across regional specialists.
- Direct Sales:Long-term formulation agreements lock multi-year supply relationships with top-five North American food manufacturers. Captive innovation partnerships displace brand-agnostic flavor houses.
- Online Retail:Digital platforms enable mid-size beverage and cosmetics brands to access customized flavor development services without traditional distributor markups.
- Distributors:Regional networks serve smaller compounders lacking direct sales infrastructure. Legacy ERP integration challenges complicate batch record digitization for traceability mandates.
- Wholesalers:Volume aggregation for commodity flavor categories serves independent bakeries and regional confectionery manufacturers.
Direct sales anchors the volume base while online retail gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across the region. Mexican food processors prioritize cost-predictable synthetic formulations, while California beverage brands absorb premiums for botanical-derived inputs. Canadian personal care manufacturers occupy a middle tier, balancing clean-label positioning with cross-border supply efficiency.
United States
California's Proposition 65 enforcement accelerates natural flavor substitution in personal care and packaged foods. FDA GRAS self-determination scrutiny extends product launch timelines by 8-14 months nationwide. The Pacific Northwest beverage cluster adopts hybrid extraction-fermentation inputs at 3-4x the rate of conventional extract buyers.
Canada
Health Canada applies parallel but non-identical safety thresholds to FDA standards, fragmenting compliance architecture for cross-border suppliers. The country's national health regulator maintains stricter maximum residue limits on certain synthetic additives. Ontario and Quebec concentrate flavor compounding capacity serving both domestic CPG manufacturers and US export channels.
Mexico
Multinational CPG manufacturing expansion near Querétaro and Guanajuato concentrates demand for regional flavor compounding capacity. Mexico's national health regulator applies safety thresholds that diverge from both FDA and Health Canada standards. The Bajío Region food processing corridor anchors volume procurement for heat-stable synthetic flavors in bakery and extruded snack applications.
California
Proposition 65 warning requirements for synthetic additives reshape formulation decisions nationwide. EPA volatile organic compound reporting obligations tighten facility siting constraints for fragrance manufacturing. The state's personal care cluster drives premium positioning for essential oil-derived transparency in functional cosmetics.
Texas and Gulf Coast
Aroma chemical producers with existing Gulf Coast infrastructure expand capacity rather than face California and Northeast air quality district permitting delays. EPA new source performance standards require catalytic oxidizer installations at greenfield plants. The region's petrochemical feedstock access supports cost-competitive synthetic aroma molecule production.
North America Flavors and Fragrances Market Key Industry Players
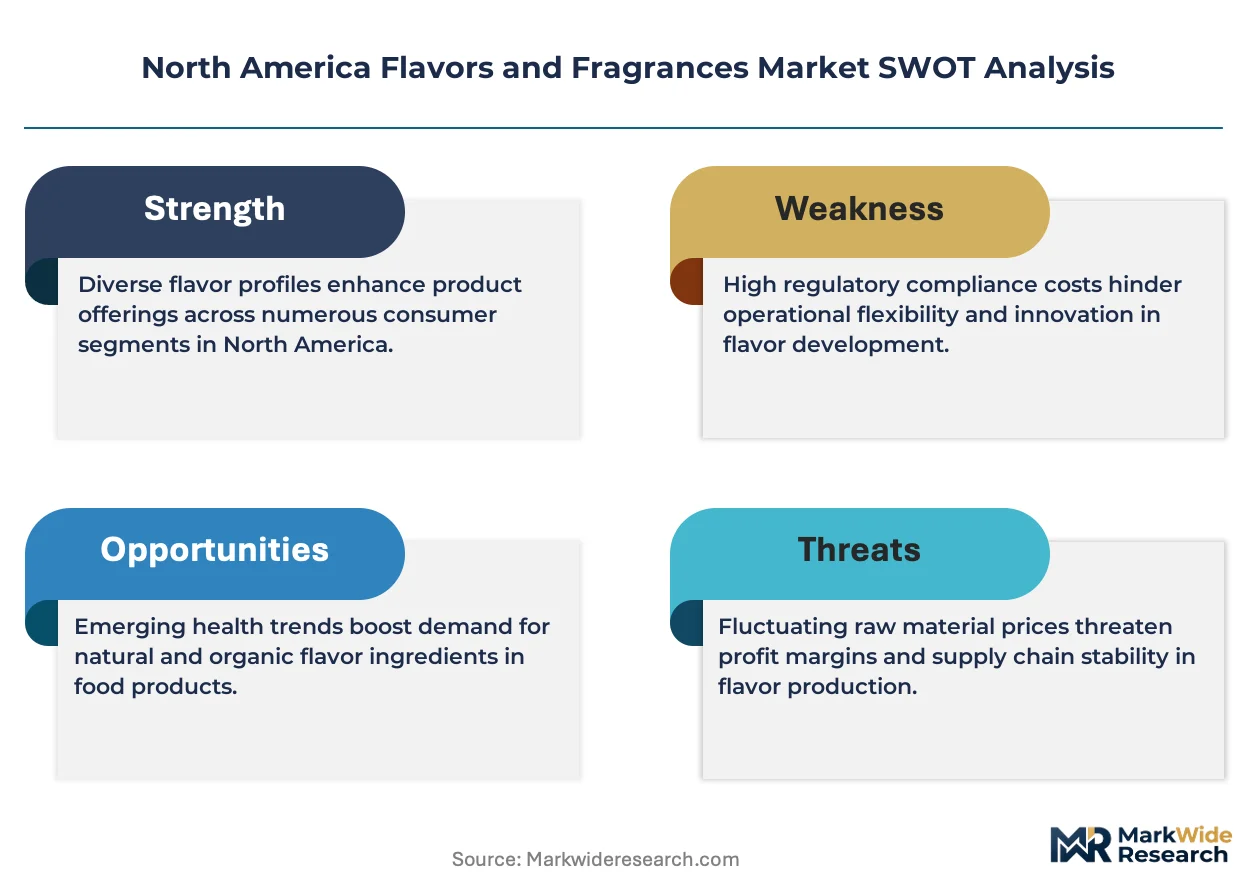
Capability concentration sits with bioscience-integrated compounders; scale advantage sits with diversified ingredient conglomerates. The vendor base stratifies across three tiers: captive innovation partners locking multi-year supply agreements, brand-agnostic flavor houses serving spot markets, and regional distributors aggregating commodity volumes. Strategic archetypes include backward-integrated dairy specialists, precision fermentation scale-ups, and direct-to-brand digital compounders. Dominant competitive moves encompass exclusive formulation partnerships displacing spot purchasing, and captive botanical supply chain construction securing extraction yield continuity.
Among Switzerland-based specialists, Givaudan SA and Firmenich (now dsm-firmenich) exemplify the captive supply archetype through botanical sourcing integration. Ireland-anchored Kerry Group represents backward integration into taste modulation platforms. These three entities occupy positions within the premium-tier partnership vector that consolidated CPG manufacturers increasingly favor over transactional supplier relationships.
| Leading Market Players |
|---|
| International Flavors & Fragrances |
| Symrise AG |
| Givaudan SA |
| dsm-firmenich |
| Sensient Technologies |
| Archer Daniels Midland Company |
| Kerry Group |
| MANE Group |
| Takasago International Corporation |
| Others |
Cost & Logistics Intelligence
Madagascar vanilla and Indian mint crop concentration anchors margin volatility for natural flavor lines, pushing compounders to diversify procurement across Mexico's captive botanical projects and precision fermentation alternatives. This upstream dependency pattern concentrates pricing power with agricultural harvest cycles while downstream buyers absorb premiums for supply continuity.
Pricing Analysis
Long-term formulation agreements with minimum volume commitments drive lifetime value for consolidated CPG manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates certified organic botanical extracts from conventional natural grades and synthetic alternatives. Cost compression in synthetic flavor tiers is intensifying because beverage reformulation pulls volume toward natural substitutes. Regional bread and snack manufacturers exhibit highest price sensitivity, while California personal care brands absorb premiums for Proposition 65-compliant transparency positioning.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for aroma chemical precursors. Feedstock concentration in Madagascar, India, and Indonesia for essential oils combines with China and Germany for synthetic aroma molecules. The supply chain draws from agricultural harvest cycles for botanical inputs and petrochemical derivatives for synthetic molecules. Single-source vulnerability in Madagascar vanilla and Indian mint compresses margins unpredictably. Distribution runs through direct sales relationships with top-five food manufacturers and digital platforms for mid-size beverage brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation scale-up for rare terpenes signals early-cycle expansion, with microbial production opening supply previously constrained by agricultural harvests. This technology tailwind is accelerating penetration across cosmetic and beverage applications.
For Market Incumbents: Harden captive botanical supply chains through backward integration into extraction infrastructure across California and Mexico. Secure exclusive formulation partnerships with consolidated CPG manufacturers before spot purchasing displacement accelerates. Invest in enzymatic bioconversion platforms to reduce yield volatility for heat-sensitive citrus and vanilla profiles. For New Entrants and Emerging Players: Establish a beachhead in direct-to-brand digital compounding for mid-size beverage and cosmetics brands bypassing traditional distributor networks. Target the Pacific Northwest beverage cluster with hybrid extraction-fermentation inputs. Lead with customized flavor development services and transparent supply chain documentation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with precision fermentation scale-ups holding microbial production capabilities for rare terpenes and lactones. Five-to-ten year viability hinges on regulatory acceptance of bioscience-derived molecules as natural-qualified inputs. Watch FDA GRAS determination timelines for enzymatic flavor precursors as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Botanical Supply Chain Construction | Madagascar vanilla and Indian mint volatility forces backward integration into California and Mexican extraction infrastructure. |
| Precision Fermentation Scale-Up | Microbial production of rare terpenes dissolves traditional natural-versus-artificial formulation boundaries for cosmetic firms. |
| Long-Term Formulation Partnerships | Exclusive agreements with minimum volume commitments displace spot purchasing for core taste platforms at top-five food manufacturers. |
| Direct-to-Brand Digital Compounding | Mid-size beverage brands in California and the Pacific Northwest bypass distributor markups for customized flavor development. |
| EPA VOC Compliance Investment | Catalytic oxidizer installations at greenfield plants address new source performance standards for fragrance manufacturing. |
Research Approach
Cross-validation between flavor chemist interviews and customs trade data anchors the qualitative findings in this analysis. Primary discussions with formulation scientists at compounders, procurement leads at beverage manufacturers, regulatory affairs specialists, and plant managers at extraction facilities combined with secondary review of FDA GRAS notifications, EPA emission filings, Health Canada safety thresholds, and SEC disclosures from listed ingredient suppliers. Bottom-up volume modeling and top-down market sizing triangulate across these inputs.
Calibration against historical growth patterns and segment elasticity parameters shapes the analytical framework across the projection horizon. Segmentation dimensions include product type, application channel, end-user archetype, and distribution method. CAGRs derive from regression analysis of adoption curves and penetration rates. Industry-specific inputs encompass enzymatic bioconversion yield improvements and Proposition 65 enforcement intensity indices.
Stress conditions across essential oil feedstock availability, FDA GRAS scrutiny timelines, and cross-border regulatory divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about precision fermentation scale-up rates and clean-label reformulation momentum. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Smoked Dextrose Market
Flavorings and Food Additives
Smoked Condensates Market
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
Oryzanol Market
Flavorings and Food Additives
Global Ginger Extract Market
Flavorings and Food Additives
United States Food Flavor Market
Flavorings and Food Additives
Food Flavors & Flavor Enhancers Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Global Floral Flavors Market
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
Taste Modulators Market
Flavorings and Food Additives
Bergamot Extract Market
Flavorings and Food Additives
FTNF Flavors Market
Flavorings and Food Additives
North America Food Flavor Market
Flavorings and Food Additives
Food Aroma Market
Flavorings and Food Additives
Flavanones Market