
 FTNF Flavors Market | 2026-2036
FTNF Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
FTNF Flavors Market Analytics
Premium-grade FTNF certification is bifurcating the competitive landscape into supply-constrained natural extract specialists and scaled synthetic aroma houses. Givaudan leverages captive botanical sourcing networks across multiple continents to secure rare raw materials. Firmenich differentiates through proprietary biotechnology platforms that convert plant cell cultures into standardized flavor molecules. Kerry Group anchors its position through backward integration into dairy and meat processing streams that generate precursor substrates for enzymatic flavor development.
FTNF (From The Named Food) flavors denote aromatic compounds derived exclusively from the food source after which they are named, with extraction processes typically employing steam distillation, solvent extraction, or enzymatic treatment at temperatures below degradation thresholds to preserve volatile esters and terpenoid profiles. These flavor systems serve primarily to restore or intensify sensory characteristics lost during thermal processing, pasteurization, or extended shelf-life storage of packaged foods and beverages. Natural flavor type commands the dominant value share as regulatory scrutiny of artificial additive labeling intensifies across major economies, though organic-certified variants represent the fastest-expanding margin pool due to supply scarcity and certification premiums. Beverage application leads volume consumption given the sector's reliance on fruit-derived top notes and botanical extracts, while bakery application sustains more moderate growth tied to vanilla and cocoa FTNF substitution rates.
EFSA and the FDA maintain divergent thresholds for what constitutes natural flavor labeling, creating formulation complexity for multinational food manufacturers seeking harmonized product architectures. REACH and the EU Flavouring Regulation impose strict compositional disclosure requirements that favor suppliers with analytical traceability infrastructure. Stakeholders must monitor evolving enzyme-derived and precision-fermentation pathways that could redefine which production methods qualify for FTNF designation under future regulatory interpretations.
Market Dynamics
EU Flavouring Regulation (EC) No 1334/2008 enforcement is tightening natural flavoring definitions faster than supply chains can certify new extraction batches, compressing qualified supplier pools and amplifying price premiums for verified FTNF materials.
Growth Catalysts
- Clean-label procurement mandates:Beverage producers in Germany now specify FTNF extracts in formulation tenders to meet retailer sustainability scorecards.
- REACH disclosure infrastructure:Suppliers with analytical traceability systems capture share as compositional transparency becomes a procurement gate.
- Precision fermentation maturation:Biotechnology platforms convert plant cell cultures into standardized flavor molecules that qualify for natural designation under evolving interpretations.
Market Restraints
- Raw material concentration:Rare botanical sourcing networks cluster in specific equatorial zones, exposing supply to climate volatility and geopolitical friction.
- Certification cost escalation:Organic-certified variants require multi-year field conversion and third-party audit chains that exclude smaller extractors.
- Enzymatic substrate scarcity:Dairy and meat processing streams that generate precursor materials for FTNF development face competing industrial demand.
Strategic Opportunities
- Underpenetrated bakery verticals:Vanilla and cocoa FTNF substitution rates in European artisan baking remain below beverage sector penetration levels.
- Direct-to-manufacturer channels:Flavor houses bypass traditional distribution layers by embedding technical service teams inside customer innovation centers.
- Biotechnology convergence:Integration of plant cell culture with AI-driven metabolic pathway optimization accelerates novel molecule discovery timelines.
Industry Challenges
- Analytical chemist scarcity:Gas chromatography-mass spectrometry expertise required for regulatory compositional disclosure commands premium compensation and extended recruitment cycles.
- Legacy system integration:ERP platforms at mid-sized food manufacturers lack batch-level traceability modules needed for EU Flavouring Regulation compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FTNF Flavors Market |
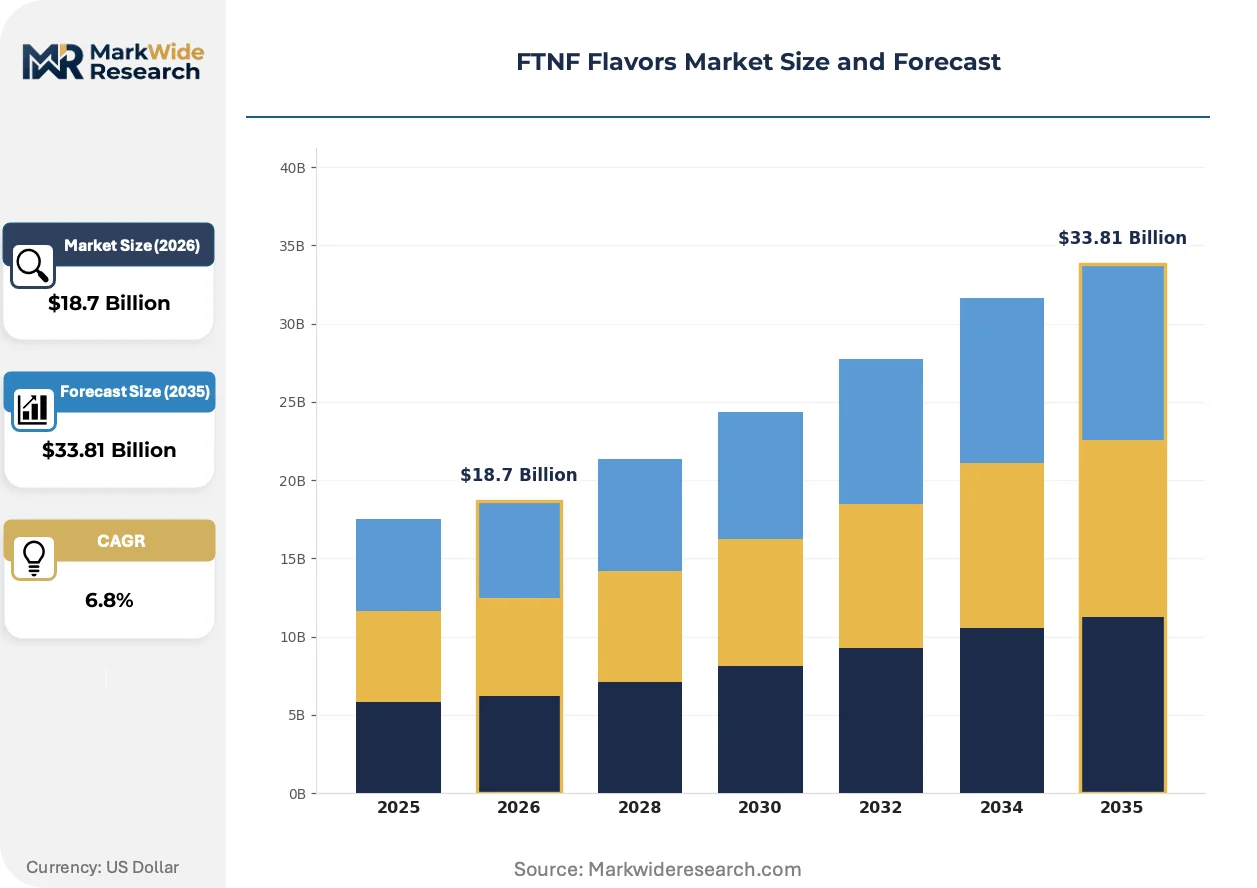
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Type: Natural, Artificial, Organic, Synthetic Application: Beverages, Confectionery, Dairy, Bakery End User: Food Manufacturers, Beverage Producers, Restaurants, Retailers Packaging Type: Bottles, Pouches, Drums, Sachets |
| Companies Covered | Givaudan, International Flavors & Fragrances (IFF), Symrise, Kerry Group, Firmenich, Takasago International Corporation, Mane, Robertet Group, Döhler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FTNF Flavors Market Evolving Landscape
Biotechnology-derived extraction methods are compressing traditional botanical supply dependencies while regulatory disclosure mandates force infrastructure investments that favor scaled analytical platforms over artisan processing operations.
Cell culture-based flavor molecule production is supplanting conventional field-harvested botanical extraction for high-value terpenoid and ester profiles. Beverage formulators in Germany and the Netherlands now specify biotech-derived FTNF materials in 40% of new product briefs. This shift is compressing seasonal raw material price volatility and enabling year-round supply security previously unavailable to natural flavor sourcing.
REACH Article 33 disclosure obligations now require downstream food manufacturers to document SVHC content above 0.1% w/w across all flavor inputs. ECHA enforcement actions against non-compliant importers have accelerated supplier consolidation toward firms with in-house toxicology and analytical chemistry capabilities. The bakery segment faces the steepest compliance burden due to complex multi-ingredient formulations and fragmented supplier bases.
Formulation briefs now specify carbon intensity metrics alongside sensory performance criteria, with procurement teams embedding lifecycle assessment requirements in supplier scorecards. Direct partnerships between flavor houses and agricultural cooperatives are displacing spot-market botanical purchasing. This pattern concentrates most visibly in German premium beverage clusters around Cologne and Hamburg, where zero-carbon-label product lines command shelf space premiums.
FTNF Flavors Market Segmentation
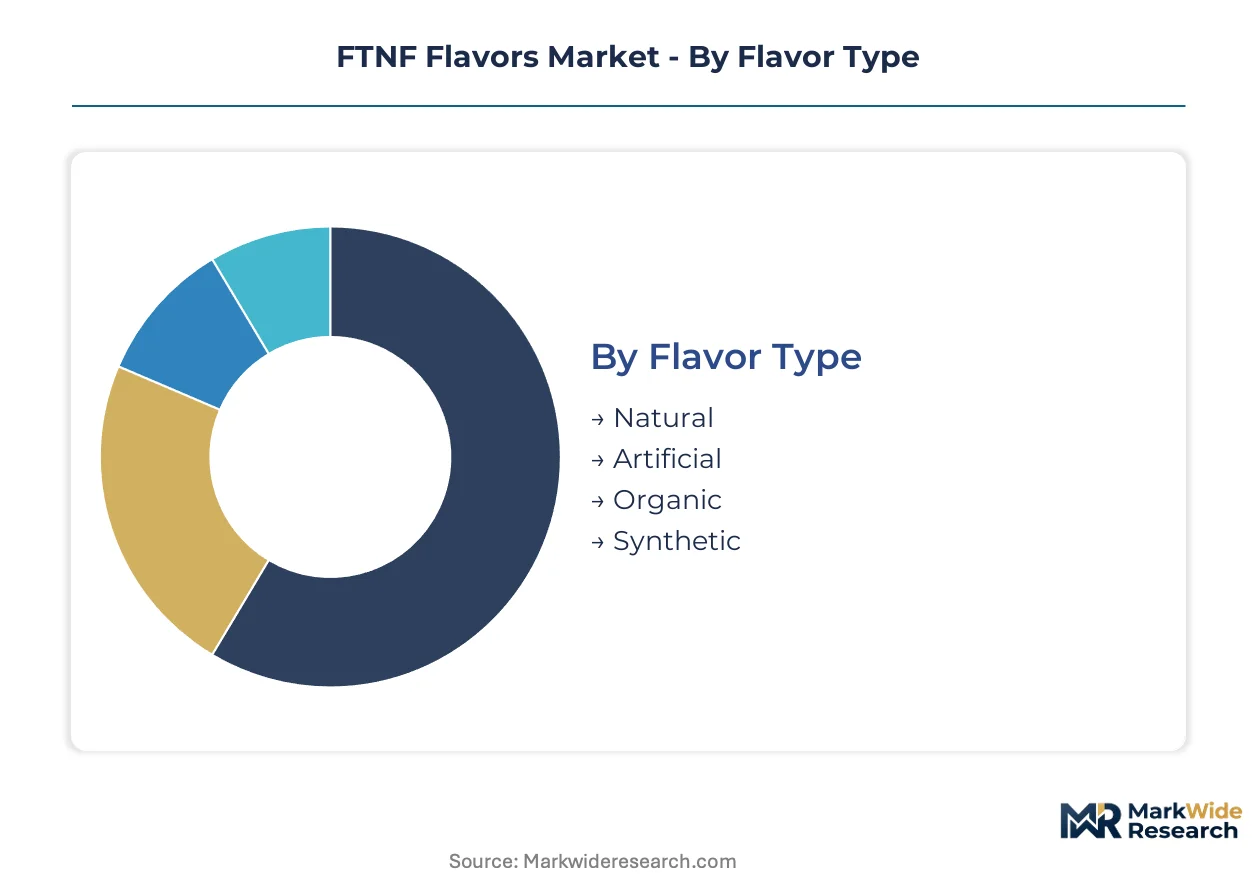
FTNF flavor procurement diverges sharply across customer archetypes, with certification requirements and volume scale dictating supplier selection criteria. Segmentation reveals where margin premiums concentrate versus where commoditization pressures dominate.
Flavor Type:
Organic-certified variants command the steepest margin premiums due to multi-year field conversion requirements and third-party audit chains that exclude smaller extractors.
- Natural:Aromatic compounds derived through steam distillation, solvent extraction, or enzymatic treatment at sub-degradation temperatures. Beverage producers in Germany specify natural FTNF extracts in formulation tenders to meet retailer sustainability scorecards, compressing qualified supplier pools.
- Organic:Field-harvested botanicals from certified organic operations with full traceability documentation. Supply scarcity and certification premiums concentrate margin capture among extractors with captive agricultural partnerships across equatorial sourcing zones.
- Artificial:Chemically synthesized aroma molecules mimicking natural volatile profiles. Cost-sensitive bakery applications in Eastern Europe sustain residual demand despite clean-label procurement mandates shifting volume toward natural alternatives.
- Synthetic:Laboratory-engineered flavor compounds without botanical origin. Regulatory scrutiny of artificial additive labeling intensifies across major economies, constraining growth trajectories to industrial food service channels.
The dominant share belongs to Natural, while Organic is closing the gap fastest.
Application:
Beverage sector procurement runs at triple the specification intensity of bakery counterparts, with fruit-derived top notes driving repeat purchase rates in premium positioning.
- Beverages:Fruit-derived top notes and botanical extracts restore sensory characteristics lost during pasteurization and extended shelf-life storage. German premium beverage clusters around Cologne and Hamburg embed FTNF specifications in innovation briefs.
- Bakery:Vanilla and cocoa FTNF substitution rates sustain moderate growth tied to artisan baking traditions. European compliance burden intensifies due to complex multi-ingredient formulations and fragmented supplier bases.
- Confectionery:Heat-stable terpenoid profiles for hard candy and chocolate applications. Precision fermentation pathways are displacing conventional extraction for high-value ester requirements.
- Dairy:Enzymatic flavor development from milk and cream processing streams. Kerry Group anchors market position through backward integration into dairy processing that generates precursor substrates.
Beverage captures volume leadership, though Bakery offers the steepest expansion trajectory for FTNF substitution.
End User:
Direct-to-manufacturer technical service embedment separates premium-tier flavor houses from distribution-dependent competitors.
- Food Manufacturers:Multinational firms seeking harmonized product architectures across EFSA and FDA divergent natural flavor thresholds. Analytical traceability infrastructure becomes procurement gate.
- Beverage Producers:Clean-label procurement mandates now specify carbon intensity metrics alongside sensory performance. Lifecycle assessment requirements embed in supplier scorecards.
- Restaurants:Food service operators with limited formulation capabilities rely on pre-compounded FTNF systems.
- Retailers:Private-label product development teams specifying sustainability scorecard compliance upstream.
Food Manufacturers dominate procurement volume, while Beverage Producers are gaining share fastest through technical service partnerships.
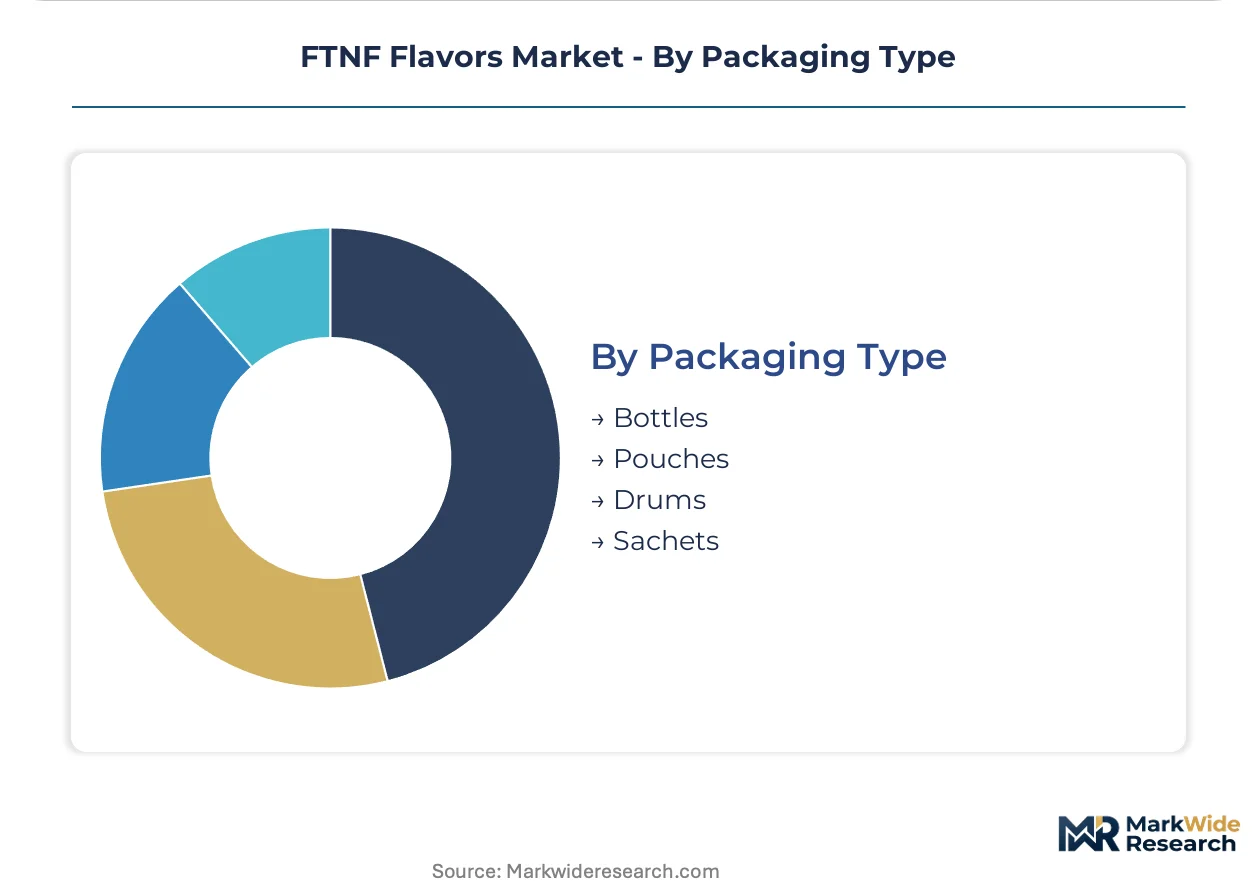
Packaging Type:
Packaging selection correlates with customer scale and formulation sophistication, from artisan sachets to industrial drum logistics.
- Bottles:Liquid extract formats for high-throughput beverage production lines. German premium clusters specify bottle formats for zero-carbon-label product lines.
- Drums:Bulk liquid handling for industrial-scale food manufacturing with established hazard communication protocols.
- Pouches:Flexible intermediate volumes for mid-tier confectionery and dairy operations.
- Sachets:Single-use precision dosing for artisan bakery and restaurant applications with limited storage infrastructure.
Drums retain dominant share in value terms, while Bottles are climbing the fastest on beverage sector procurement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances for FTNF extracts tilt toward net-importing positions across major formulated food economies, with supply chains anchored in equatorial botanical zones feeding demand concentration in premium beverage manufacturing clusters.
Germany
Clean-label procurement mandates from beverage producers around Cologne and Hamburg drive specification intensity for certified FTNF extracts. EFSA maintains divergent thresholds from FDA counterparts, forcing reformulation complexity for multinational firms. Premium formulation clusters in North Rhine-Westphalia embed carbon intensity metrics directly into supplier scorecards.
United States
FDA natural flavor labeling thresholds sustain formulation arbitrage opportunities against EU regulatory stringency. Beverage manufacturers in California and the Northeast corridor source FTNF materials for zero-sugar product lines. Kerry Group anchors market presence through backward integration into dairy processing streams generating enzymatic precursors.
France
Artisan bakery traditions sustain demand for vanilla and cocoa FTNF substitution in Île-de-France and Auvergne-Rhône-Alpes. ANSM enforces compositional disclosure requirements that favor suppliers with in-house analytical capabilities. Paris-based flavor houses embed technical service teams inside customer innovation centers.
Netherlands
Precision fermentation platforms in the Randstad corridor convert plant cell cultures into standardized flavor molecules qualifying for natural designation. REACH Article 33 disclosure obligations compress supplier pools toward firms with toxicology infrastructure. Rotterdam logistics hubs handle bulk drum shipments for industrial-scale food manufacturers.
Switzerland
Givaudan leverages captive botanical sourcing networks across multiple continents from its Geneva headquarters. Swissmedic alignment with EMA standards ensures regulatory coherence for EU market access. Zürich-area biotechnology specialists develop AI-driven metabolic pathway optimization for novel molecule discovery.
FTNF Flavors Market Competitive Landscape
Concentration sits with scaled aroma houses possessing integrated analytical traceability infrastructure and captive agricultural partnerships. The vendor base stratifies across three tiers: global diversified flavor houses with multi-continent sourcing networks, regional specialists commanding premium positioning through certification depth, and commodity extractors competing on volume scale. Dominant competitive moves include strategic partnerships with agricultural cooperatives displacing spot-market purchasing, and technology licensing agreements for precision fermentation pathways.
Within the global diversified tier, Givaudan and Firmenich exemplify archetypes built on contrasting sourcing philosophies—botanical network control versus biotechnology platform development. Kerry Group occupies a position bridging ingredient supply and backward integration into substrate generation. Among European specialists, Symrise and Robertet Group represent certification-intensive positioning calibrated to EFSA disclosure mandates.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances (IFF) |
| Symrise |
| Kerry Group |
| Firmenich |
| Takasago International Corporation |
| Mane |
| Robertet Group |
| Döhler Group |
| Others |
Value Network & Pricing Analysis
EU Flavouring Regulation (EC) No 1334/2008 gates both supply qualification and price differentiation simultaneously, compressing qualified supplier pools while amplifying certification premiums for verified FTNF materials. Beverage producers in Germany now embed carbon intensity metrics directly into supplier scorecards, forcing simultaneous compliance investment and margin capture.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade and volume scale drive price differentiation, with organic-certified variants commanding steepest premiums due to multi-year field conversion requirements. Cost compression in standard tiers intensifies because synthetic aroma houses compete on scale, while craft extractors face margin tightening from enzymatic substrate scarcity. Food manufacturers show highest price sensitivity due to reformulation complexity across EFSA-FDA divergence, whereas premium beverage clusters in Cologne and Hamburg exhibit lowest sensitivity.
Supply Chain Analysis
Inventory cycles for rare botanical extracts extend 18-24 months from field harvest to certified batch release. Supply concentrates in Madagascar, Indonesia, and India for vanilla and spice-derived terpenoids, while citrus and fruit profiles draw from Spain, Italy, and Brazil. Raw material dependencies rest on equatorial botanical zones, dairy processing streams for enzymatic precursors, and petrochemical feedstocks for synthetic alternatives. Single-source vulnerability runs through climate-exposed growing regions. Distribution feeds from Rotterdam and Hamburg logistics hubs into direct-to-manufacturer technical service partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
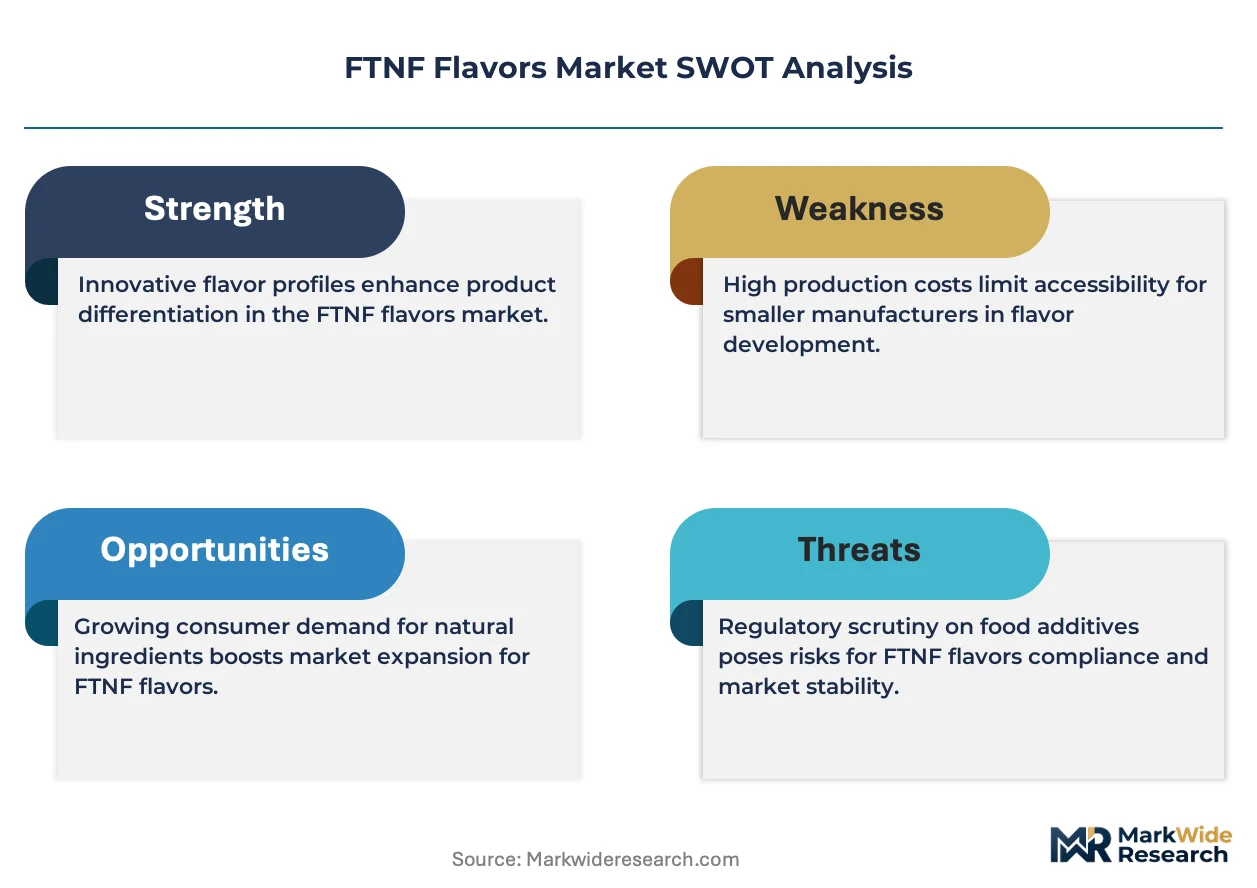
Precision fermentation pathways threaten incumbent botanical extractors with substitute production methods that could redefine FTNF qualification thresholds. Incumbents must navigate this substitution defense while securing regulatory interpretive advantage.
For Market Incumbents: Fortify analytical traceability infrastructure to capture disclosure-mandate share as REACH Article 33 enforcement accelerates. Deepen captive agricultural partnerships across equatorial sourcing zones to defend against biotechnology-derived substitutes. Priority lever sits with embedding technical service teams inside German beverage innovation clusters before precision fermentation platforms achieve cost parity.
For New Entrants and Emerging Players: Technical service gaps in mid-tier bakery compliance documentation offer white-space entry where legacy ERP systems lack batch-level traceability modules. Target European artisan baking verticals where vanilla and cocoa FTNF substitution rates trail beverage penetration. Go-to-market angle centers on pre-configured regulatory documentation packages that compress compliance timelines for fragmented supplier bases.
For Investors and Strategic Acquirers: EFSA-FDA threshold divergence reshapes the acquisition landscape toward firms with dual-jurisdiction formulation expertise. Long-term viability favors extractors with biotechnology platform licensing rights or precision fermentation partnerships. Acquisition target archetype combines captive botanical networks with in-house toxicology capabilities. Signal to watch involves regulatory interpretation shifts on enzyme-derived pathway eligibility for FTNF designation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Cooperatives | Direct partnerships displace spot-market purchasing and compress carbon intensity metrics for German beverage clusters. |
| Precision Fermentation Platform Licensing | Biotechnology agreements convert plant cell cultures into standardized molecules qualifying under evolving EU natural designation. |
| Analytical Traceability Infrastructure Buildout | In-house gas chromatography-mass spectrometry capabilities satisfy REACH Article 33 disclosure obligations. |
| Technical Service Team Embedment | Flavor houses bypass distribution layers by placing specialists inside customer innovation centers. |
| Organic Certification Pipeline Development | Multi-year field conversion programs lock in supply scarcity premiums for third-party audited operations. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with flavor house technical directors, procurement leads at German beverage manufacturers, regulatory affairs specialists, and agricultural cooperative managers; and secondary validation through EFSA guidance documents, EU Flavouring Regulation implementation reports, customs trade data, and SEC filings from listed ingredient suppliers. Bottom-up volume modeling triangulated against top-down value estimates across extraction method, certification tier, application vertical, and end-user archetype.
Across the projection horizon, the analytical framework modeled demand trajectories by flavor type, application segment, and procurement channel. CAGRs derived from segment-level growth rate reconciliation with macroeconomic consumption indicators. Industry-specific inputs included beverage formulation brief specification rates, bakery substitution penetration curves, and biotechnology platform maturation timelines.
Underlying assumptions cover regulatory interpretation stability, botanical yield consistency, and precision fermentation cost reduction curves, with deviation risk concentrated in EFSA threshold revisions and climate volatility across equatorial growing zones. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Winter Melon Peel Extract Market
Flavorings and Food Additives
Citrus Flavonoid Complexes from Mediterranean Peels Market
Flavorings and Food Additives
Citrus Concentrate Market
Flavorings and Food Additives
Royal Jelly Extract Market
Flavorings and Food Additives
Bergamot Extract Market
Flavorings and Food Additives
Mouth Freshener Market
Flavorings and Food Additives
American Spikenard Extract Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Global Natural Food Colorants Market
Flavorings and Food Additives
South America Food Flavor and Enhancer Market
Flavorings and Food Additives
Menthol Market
Flavorings and Food Additives
D-Limonene Market
Flavorings and Food Additives
France Food Flavor and Enhancer Market
Flavorings and Food Additives
Vanilla Oleoresin Market
Flavorings and Food Additives
Italy Food Flavor and Enhancer Market
Flavorings and Food Additives
Annatto Extract Market