
 Lecithin Oleoresin Market | 2026-2036
Lecithin Oleoresin Market Size, Share, and Industry Trends Forecast 2026-2036
Lecithin Oleoresin Market Analytics
Food manufacturer procurement is consolidating around fewer, larger suppliers capable of certifying non-GMO and allergen-free lecithin streams. Cargill leverages its integrated oilseed processing network to secure raw material continuity across multiple continents. Archer Daniels Midland anchors North American supply through extensive crushing and refining infrastructure. Lipoid GmbH specializes in high-purity pharmaceutical and nutraceutical grades that command premium positioning.
Lecithin oleoresin comprises a complex mixture of phospholipids, glycolipids, and neutral lipids extracted from oil-bearing seeds or egg yolk, typically containing 60-97% acetone-insoluble matter depending on refinement grade; manufacturers employ degumming, solvent extraction, or supercritical CO2 methods to isolate the phospholipid fraction for use as natural emulsifiers, wetting agents, and dispersants across food, cosmetic, and pharmaceutical systems. Soy lecithin retains volume leadership due to established supply chains and cost efficiency, though sunflower lecithin gains share fastest as European food processors reformulate away from allergen-labeled ingredients. Nutraceutical applications in softgel encapsulation and liposomal delivery systems concentrate margin pools away from commodity food grades.
EU REACH and EFSA govern residual solvent limits and novel food approvals for lecithin oleoresin entering European formulations, while FDA GRAS status and FSMA traceability mandates shape US market access requirements. Organic certification under USDA National Organic Program and EU Organic Regulation creates additional segmentation between conventional and certified supply tiers. Stakeholders must monitor evolving phospholipid concentration standards and origin verification protocols to maintain formulation eligibility across major import jurisdictions.
Market Dynamics
European food manufacturers are consolidating procurement around non-GMO lecithin streams as EU REACH and GMO disclosure rules harden supplier qualification barriers, forcing upstream oilseed processors to segregate supply chains by origin certification grade.
Growth Catalysts
- Sunflower lecithin substitution:European bakery and confectionery formulators are accelerating reformulation away from soy-derived allergens to meet clean-label consumer expectations and avoid mandatory allergen declarations.
- Nutraceutical encapsulation demand:Softgel manufacturers and liposomal drug delivery developers are sourcing high-purity phospholipid fractions for bioavailability enhancement in pharmaceutical and dietary supplement applications.
- EU Organic Regulation expansion:Certified organic lecithin oleoresin commands supply priority as processors seek dual organic-non-GMO qualification for premium positioning in continental retail channels.
Market Restraints
- Sunflower seed supply volatility:Black Sea region crop instability and weather-driven yield fluctuations constrain raw material predictability for European crushing operations.
- Pharmaceutical-grade purification costs:Supercritical CO2 extraction and multi-stage degumming equipment require capital intensity that limits viable producer entry to established oilseed majors.
- Synthetic emulsifier substitution:Polyglycerol esters and sucrose esters compete on cost in mass-market food applications where phospholipid functionality is not specification-critical.
Strategic Opportunities
- India nutraceutical manufacturing:CDSCO regulatory alignment and FSSAI functional food approvals create entry pathways for pharmaceutical-grade lecithin in domestic softgel and liposomal production.
- Cell-cultured meat applications:Alternative protein developers require plant-derived emulsifiers for fat structuring and mouthfeel engineering in hybrid and cultivated meat formulations.
- Direct-to-manufacturer digital platforms:Specialty chemical distributors are building certified-origin traceability tools that bypass traditional broker layers for mid-size food processor accounts.
Industry Challenges
- Phospholipid assay standardization:Inconsistent acetone-insoluble matter testing protocols across EU, US, and Asian laboratories create specification disputes between suppliers and pharmaceutical formulators.
- Origin verification infrastructure:Blockchain and mass-balance certification systems require cross-supplier data integration that smaller crushers lack technical capacity to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lecithin Oleoresin Market |
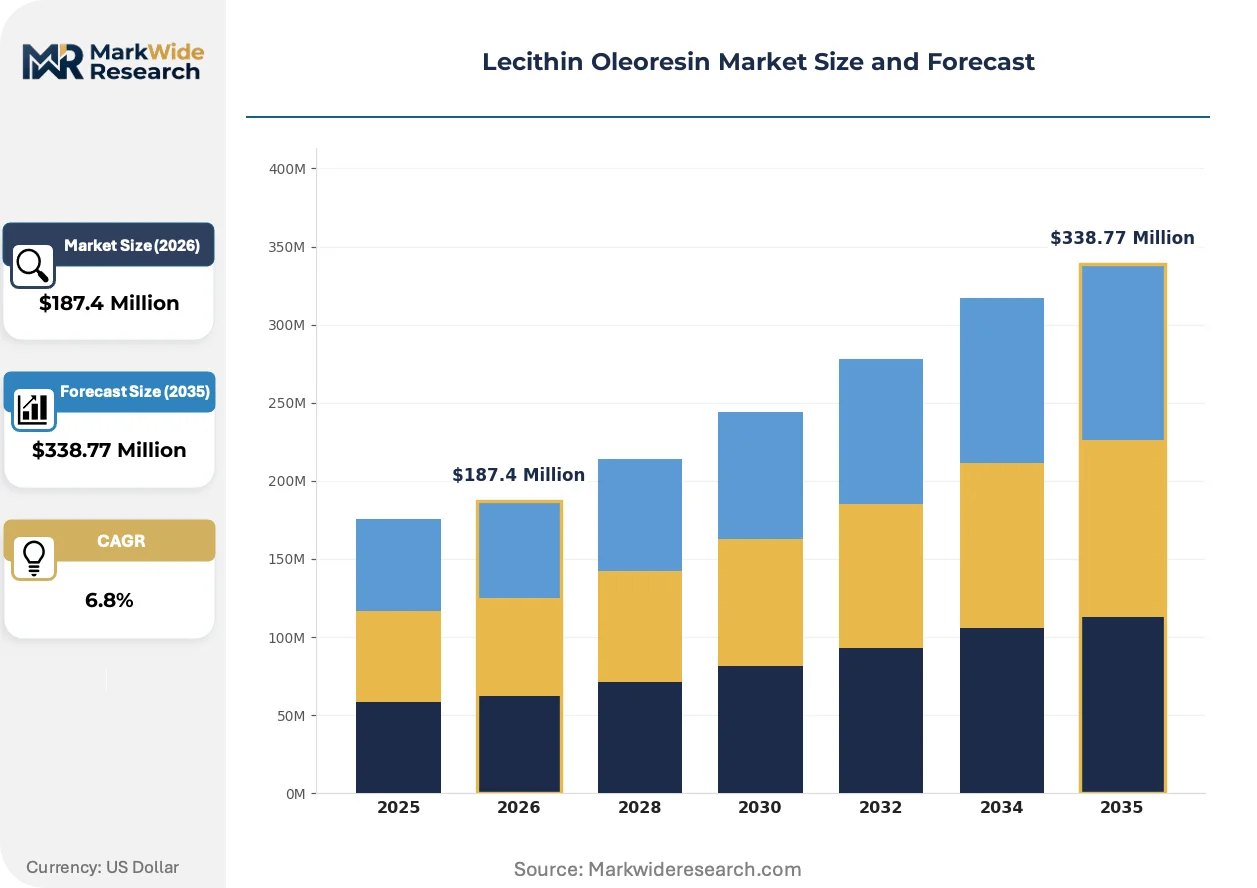
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunflower Lecithin, Soy Lecithin, Egg Lecithin, Others Application: Food Processing, Nutraceuticals, Personal Care, Animal Feed Form: Liquid, Powder, Granule, Emulsion End User: Food Manufacturers, Dietary Supplement Companies, Cosmetic Brands, Pet Food Companies |
| Companies Covered | Archer Daniels Midland, Cargill, Bunge Limited, International Flavors & Fragrances, Wilmar International, Lipoid GmbH, American Lecithin Company, Stern-Wywiol Gruppe, Lecico GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lecithin Oleoresin Market Evolving Landscape
Process intensification and regulatory digitization are compressing traditional qualification timelines while demand-side certification requirements fragment supply tiers into origin-verified specialty streams.
Supercritical CO2 extraction systems are automating phospholipid fractionation with solvent-free output that meets pharmaceutical residual limits without downstream distillation steps. German and Swiss nutraceutical contract manufacturers are adopting these units fastest, replacing hexane-based batch processes that require ECHA-registered solvent handling. The technology is automating quality assurance documentation that previously demanded manual batch testing and third-party laboratory verification.
EU REACH substance registration deadlines are tightening residual solvent thresholds for lecithin oleoresin imports, forcing non-EU crushers to retrofit extraction infrastructure or exit European pharmaceutical supply tiers. ECHA enforcement of updated safety data sheet requirements is redirecting commodity-grade volumes toward food applications where thresholds remain less stringent. French and Italian formulators are prioritizing ECHA-registered suppliers to preempt authorization bottlenecks in high-purity ingredient procurement.
Certification-driven supplier selection is concentrating procurement authority within technical sourcing functions that evaluate origin documentation alongside price and phospholipid concentration. European food manufacturers are consolidating vendor lists to three to five qualified suppliers capable of dual organic-non-GMO certification with full traceability. This behavioral shift is most pronounced in German retail private-label supply chains where EDEKA and REWE group sustainability specifications mandate third-party verified lecithin streams.
Lecithin Oleoresin Market Segmentation
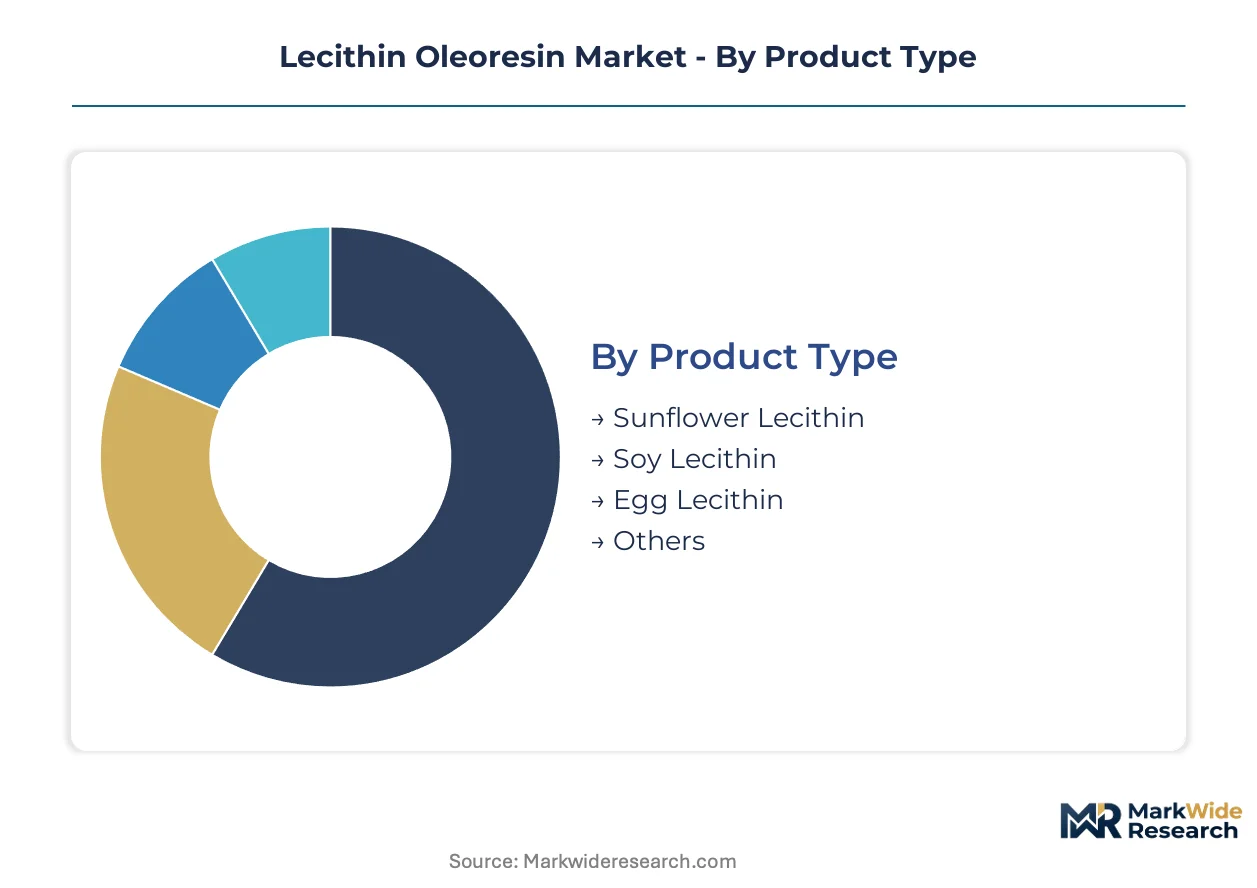
Lecithin oleoresin segmentation reflects divergent purity standards and certification requirements across food, pharmaceutical, and cosmetic value chains. Specification tiers separate commodity emulsifiers from high-phospholipid fractions commanding premium positioning in encapsulation and liposomal delivery systems.
Product Type:
Phospholipid concentration and allergen profile distinguish sourcing decisions across extraction origins.
- Sunflower Lecithin:Non-GMO and allergen-free status drives fastest share gain in European bakery and confectionery reformulation. German and French processors prioritize sunflower streams to eliminate mandatory soy allergen labeling under EU regulation.
- Soy Lecithin:Established crushing infrastructure and cost efficiency maintain volume leadership across mass-market food applications. Supply concentrates in North American and South American oilseed processing corridors with integrated degumming capacity.
- Egg Lecithin:High phosphatidylcholine content suits pharmaceutical liposome manufacturing; supply limited by egg yolk raw material constraints.
- Others:Rapeseed and cottonseed lecithin serve regional niche applications where local oilseed processing creates captive supply.
Mature deployment sits with soy lecithin. Newer deployment is concentrated in sunflower lecithin.
Application:
End-use functionality requirements fragment the market into specification tiers with divergent residual solvent and phospholipid assay standards.
- Food Processing:Emulsification and anti-staling functions in bakery, chocolate, and margarine applications constitute the largest volume tier. Clean-label reformulation in European retail channels accelerates sunflower substitution.
- Nutraceuticals:Softgel encapsulation and liposomal nutrient delivery demand 90%+ phospholipid purity with supercritical CO2 extraction. Swiss and German contract manufacturers anchor demand for pharmaceutical-grade fractions.
- Personal Care:Skin penetration enhancement and emulsion stabilization in premium cosmetics utilize deoiled lecithin grades; supply concentrates with specialty lipid distributors serving formulators in France and Italy.
- Animal Feed:Pellet binding and fat emulsification in aquaculture and pet nutrition absorb lower-purity fluid lecithin volumes at compressed margins.
Volume concentration remains in food processing. Margin expansion concentrates in nutraceuticals.
Form:
Physical state selection aligns with manufacturing process integration and storage stability requirements.
- Liquid:Standard fluid lecithin dominates bulk food manufacturing for ease of pump transfer and direct dosing into chocolate conching and margarine emulsification systems.
- Powder:Spray-dried and deoiled powders enable dry-blend compatibility in bakery premixes and instant beverage applications; demand clusters with European industrial bakeries.
- Granule:Low-dust handling properties suit pharmaceutical tableting and capsule filling operations where precise metering is critical.
- Emulsion:Pre-hydrated aqueous dispersions simplify incorporation into water-based cosmetic formulations and beverage emulsions.
Liquid form anchors commodity procurement. Powder and granule formats are expanding most quickly in convenience food and pharmaceutical manufacturing.
End User:
Procurement sophistication varies sharply between specification-driven pharmaceutical buyers and cost-optimized commodity food processors.
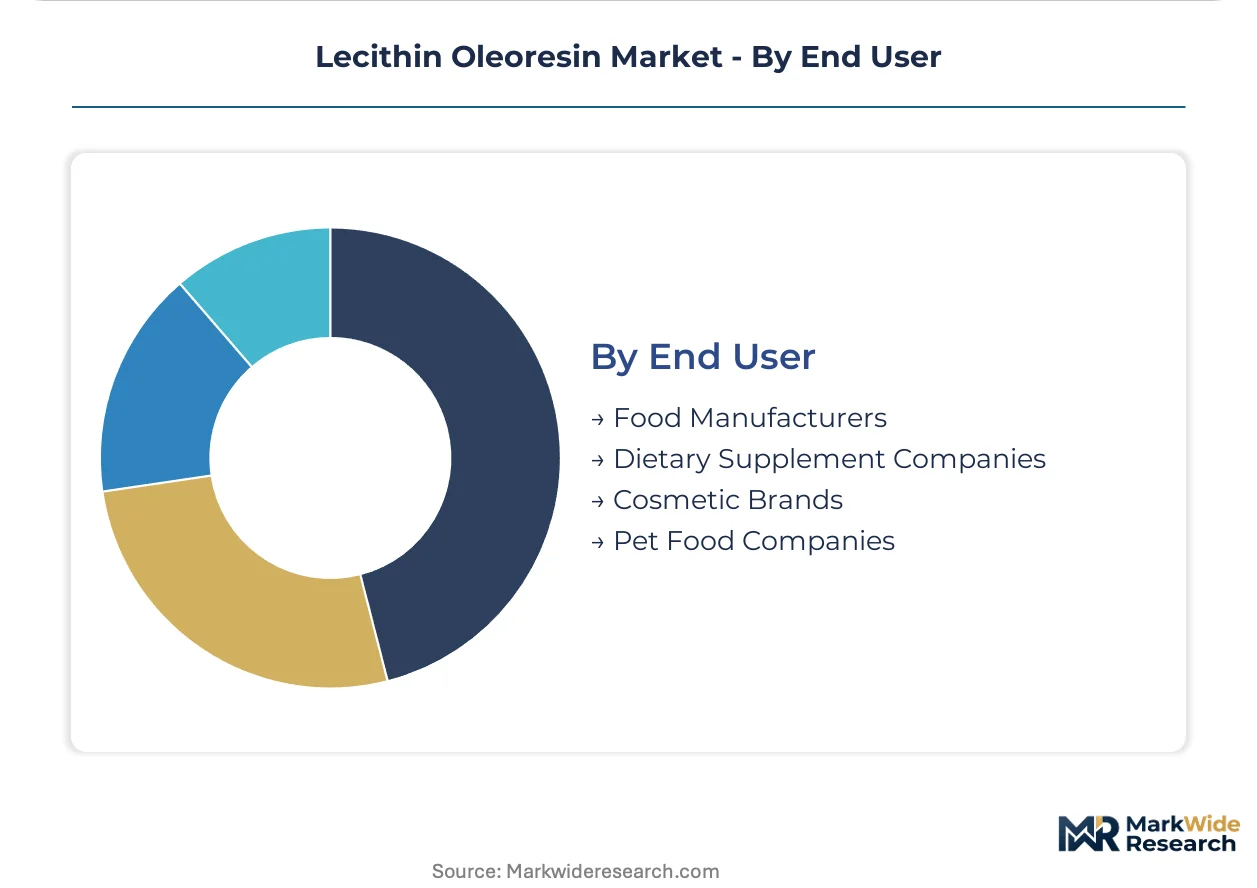
- Food Manufacturers:Industrial bakeries, confectioners, and margarine producers constitute the foundational demand base with consolidated supplier qualification around dual organic-non-GMO certification.
- Dietary Supplement Companies:Softgel and liposomal product developers source high-purity phospholipid fractions with full ECHA-registered documentation for European market access.
- Cosmetic Brands:Premium skincare formulators in France and Switzerland specify deoiled and hydrogenated lecithin grades for oxidative stability in emulsion systems.
- Pet Food Companies:Palatability enhancement and fat digestibility applications in premium pet nutrition utilize standard fluid lecithin at scaled volumes.
Procurement standardization is deepest among food manufacturers. Technical specification intensity is highest among dietary supplement companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for lecithin oleoresin concentrates in European food manufacturing corridors, where clean-label reformulation and non-GMO certification requirements reshape supplier qualification. German and French processors anchor premium-grade procurement, while North American crushing infrastructure maintains commodity volume leadership.
Germany
Industrial bakeries and confectionery manufacturers in the Rhine-Ruhr and Bavaria regions drive demand for sunflower-derived lecithin streams. ECHA REACH substance registration mandates tighten residual solvent thresholds for pharmaceutical-grade imports. The Stuttgart industrial corridor hosts contract manufacturers adopting supercritical CO2 extraction systems to meet EFSA purity specifications for nutraceutical encapsulation.
United States
Soy lecithin crushing capacity concentrates in the Midwest oilseed processing belt, supplying mass-market food emulsification at scale. FDA GRAS status and FSMA traceability mandates shape supplier documentation requirements for domestic and export-bound formulations. Chicago-area distributors consolidate procurement for national bakery and chocolate manufacturers seeking integrated supply security.
France
Premium cosmetics formulators in the Île-de-France and Provence-Alpes-Côte d'Azur clusters specify deoiled lecithin grades for oxidative stability in skincare emulsions. ANSM oversight of cosmetic ingredient safety intersects with EU REACH compliance for residual solvent verification. Lyon-based specialty lipid distributors serve pharmaceutical and personal care manufacturers with certified-origin documentation.
India
Softgel and liposomal nutraceutical manufacturers in Maharashtra and Gujarat create demand for high-phospholipid fractions as CDSCO regulatory alignment progresses. FSSAI functional food approvals establish pathways for pharmaceutical-grade lecithin in domestic dietary supplement production. The Mumbai-Pune industrial corridor attracts contract manufacturing investment targeting export markets and domestic premium positioning.
Switzerland
Nutraceutical contract manufacturers in the Basel and Zurich regions anchor European demand for pharmaceutical-grade phospholipid fractions. Swissmedic oversight of active pharmaceutical ingredients reinforces stringent residual solvent and origin verification protocols. Swiss processors prioritize ECHA-registered suppliers to maintain market access across EU and domestic formulation channels.
Lecithin Oleoresin Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade specialization and certified-organic positioning. The market structures around three archetypes: integrated oilseed majors with captive crushing and degumming infrastructure, specialty phospholipid refiners focused on high-purity nutraceutical grades, and regional distributors building traceability platforms for mid-size processor accounts. Competitive moves concentrate on backward integration into oilseed sourcing and strategic partnerships with certification bodies to secure dual organic-non-GMO qualification.
Among integrated oilseed processors, Archer Daniels Midland and Cargill exemplify scale-driven supply security across multiple continents. Lipoid GmbH occupies a position within the specialty refiner tier, representing pharmaceutical-grade purification expertise. These three anchors illustrate the competitive spectrum from commodity volume leadership to premium fractionation specialization, with each archetype pursuing distinct qualification strategies aligned to end-use specification intensity.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Cargill |
| Bunge Limited |
| International Flavors & Fragrances |
| Wilmar International |
| Lipoid GmbH |
| American Lecithin Company |
| Stern-Wywiol Gruppe |
| Lecico GmbH |
| Others |
Value Network & Pricing Analysis
EU REACH substance registration deadlines gate qualified supply access and premium-tier pricing eligibility for lecithin oleoresin entering European pharmaceutical formulations. Crushers lacking ECHA-registered extraction infrastructure face automatic disqualification from high-purity procurement channels, compressing viable supplier pools and concentrating pricing power among integrated oilseed majors with compliant solvent-handling systems.
Pricing Analysis
Volume concentration in standard fluid lecithin for food emulsification diverges sharply from margin capture in pharmaceutical-grade phospholipid fractions. Three-tier pricing structure across premium, standard, and economy levels separates supercritical CO2-extracted nutraceutical grades from hexane-processed food tiers and unrefined feed applications. Pricing pressure stems from synthetic emulsifier substitution in mass-market bakery and confectionery segments where phospholipid functionality is not specification-critical. Commodity food processors exhibit highest price sensitivity, while Swiss and German softgel manufacturers absorb premium positioning for ECHA-registered supply with full traceability documentation.
Supply Chain Analysis
Reverse-logistics flows for solvent recovery and degumming residue reprocessing anchor cost efficiency at integrated crushing facilities in Germany, France, and the United States. Raw material supply draws from Black Sea sunflower seed corridors, North American soybean belts, and European rapeseed processing networks. Single-source vulnerability concentrates in Ukrainian and Russian sunflower seed exports subject to weather-driven yield fluctuations and trade disruption. Distribution runs through specialty lipid distributors in Lyon and Chicago, with direct-to-manufacturer digital platforms emerging for mid-size processor accounts seeking certified-origin bypass of traditional broker layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market structures as a vertical-integration race where upstream control over non-GMO oilseed sourcing and downstream certification investment determine qualified supplier status. Players are pursuing captive crushing capacity and dual organic-non-GMO qualification as the decisive upstream lever.
For Market Incumbents: Extend ECHA-registered extraction infrastructure into sunflower processing corridors to preempt authorization bottlenecks. Acquire or joint-venture with Black Sea region crushers to secure non-GMO seed supply continuity against weather and geopolitical disruption. Synthetic emulsifier competition in commodity food tiers demands backward integration into organic-certified oilseed sourcing to defend margin position in premium segments. For New Entrants and Emerging Players: Launch via direct-to-manufacturer digital platforms targeting mid-size European bakery and confectionery processors seeking certified-origin traceability without broker markups. White-space concentration sits with pharmaceutical-grade sunflower lecithin for Indian softgel manufacturers as CDSCO regulatory alignment progresses. Cell-cultured meat developers require plant-derived emulsifiers for fat structuring, creating specification-driven entry with novel application positioning. For Investors and Strategic Acquirers: ECHA enforcement of updated safety data sheet requirements is the leading indicator that commodity-grade suppliers without registered extraction infrastructure will exit European pharmaceutical supply tiers. Long-term viability over a multi-year horizon favors specialty phospholipid refiners with supercritical CO2 purification expertise and dual organic-non-GMO certification capability. Acquisition target archetype: mid-scale crushers with technical capacity to implement blockchain origin verification and mass-balance certification systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Non-GMO Oilseed Sourcing | Captive sunflower supply secures EU REACH compliance and eliminates third-party origin verification dependencies. |
| Supercritical CO2 Extraction Capacity Expansion | Pharmaceutical-grade output meets EFSA residual solvent limits without downstream distillation infrastructure. |
| Dual Organic-Non-GMO Certification Investment | EDEK and REWE group sustainability specifications mandate third-party verified lecithin streams in German retail. |
| Direct-to-Manufacturer Digital Platform Launch | Certified-origin traceability tools bypass traditional broker layers for mid-size food processor accounts. |
| Indian Nutraceutical Manufacturing Partnership | FSSAI functional food approvals create entry pathways for pharmaceutical-grade lecithin in domestic softgel production. |
Research Methodology
Trade databases, ECHA substance registration filings, and EU organic certification registries formed the secondary backbone for supply-side mapping and regulatory qualification tracking. Primary interviews with oilseed procurement directors, pharmaceutical formulation scientists, and specialty lipid distributors validated extraction technology adoption patterns and certification investment timelines. Bottom-up and top-down triangulation cross-referenced crushing capacity disclosures against end-use demand segmentation across food, nutraceutical, and pharmaceutical channels.
Bottom-up modeling built from individual country-level crushing capacity, phospholipid concentration grades, and certification tier penetration across the projection horizon. Segmentation dimensions spanned extraction origin, phospholipid purity tier, application specification intensity, and regional regulatory cluster. CAGRs derived from weighted average of historical volume trajectories and forward-looking substitution elasticities for sunflower versus soy lecithin streams. Forecast inputs incorporated Black Sea crop yield volatility indices and ECHA enforcement timeline assumptions for residual solvent threshold compliance.
Black Sea supply disruption, ECHA authorization bottleneck formation, and synthetic emulsifier cost breakthroughs are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and substitution elasticity parameters. Practitioners should monitor ECHA substance registration completion rates, Ukrainian sunflower seed planting forecasts, and polyglycerol ester pricing indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Brazil Food Colorants Market
Flavorings and Food Additives
Flavor Masking Agents Market
Flavorings and Food Additives
Keto Friendly Flavors Market
Flavorings and Food Additives
Orange Peel Extract Market
Flavorings and Food Additives
Chicken Flavor Market
Flavorings and Food Additives
Marshmallow Root Extract Market
Flavorings and Food Additives
South America Flavors and Fragrances Market
Flavorings and Food Additives
North America Flavors and Fragrances Market
Flavorings and Food Additives
Beef Flavors Market
Flavorings and Food Additives
Food Texturizers Market
Flavorings and Food Additives
Natural Flavors Market
Flavorings and Food Additives
Carvone Market
Flavorings and Food Additives
North America Food Colorants Market
Flavorings and Food Additives
Flavor Ingredients Market
Flavorings and Food Additives
Fenchol Market
Flavorings and Food Additives
Asia-Pacific Food Flavor Market