
 Smoked Condensates Market | 2026-2036
Smoked Condensates Market Size, Share, and Industry Trends Forecast 2026-2036
Smoked Condensates Market Analytics
REACH compliance on polycyclic aromatic hydrocarbon limits is broadening the cost-of-entry calculus for new smoke condensate suppliers. Kerry Group PLC leverages captive pyrolysis technology to sustain batch-to-batch consistency across European food manufacturing accounts. Red Arrow International LLC anchors its position through backward integration into hardwood feedstock sourcing in North America. Sensient Technologies Corporation differentiates via specialized extraction protocols that navigate tightening contaminant thresholds in premium applications.
Smoked condensates are concentrated aqueous extracts produced through controlled wood pyrolysis, typically containing phenolic compounds, carbonyls, and organic acids that confer antimicrobial and flavoring properties to processed proteins. Liquid smoke formulations command the largest share of product-type revenue due to their dosing precision in industrial meat processing, while natural smoke variants are gaining fastest among clean-label product lines where synthetic additives face formulation restrictions. The food preservation application retains mature volume fundamentals, though flavoring agents extract higher per-kilogram margins from artisanal sauce and marinade producers seeking differentiated smoke profiles.
The EU's EFSA sets maximum residue benchmarks for benzo(a)pyrene in smoke-flavored foods, while the FDA governs GRAS status for liquid smoke additives in US commerce, and Japan's Food Sanitation Act enforces import testing for pyrolysis-derived flavorings. These overlapping regimes compel manufacturers to maintain parallel certification dossiers, raising working capital requirements but also creating defensible positions for laboratories with validated analytical methods. Stakeholders must monitor pending MDR-equivalent classification discussions in Europe that could reclassify certain smoke extracts as novel food ingredients, triggering substantial safety dossier obligations.
Market Dynamics
REACH's tightening polycyclic aromatic hydrocarbon documentation requirements are forcing smoke condensate suppliers to rebuild their analytical infrastructure, compressing margins for importers while advantaging domestic European producers with captive laboratory capacity.
Growth Catalysts
- Clean-label formulation mandates:Processed meat manufacturers in Germany are replacing synthetic smoke additives with natural liquid smoke variants to meet retailer clean-label specifications.
- REACH purity thresholds:The European Union's pyrolysis-derived substance framework is accelerating qualification of domestic suppliers who can demonstrate batch-to-batch contaminant consistency.
- Artisanal sausage cluster expansion:Small-scale meat processors in Bavaria and Baden-Württemberg are scaling procurement of precision-dosed liquid smoke for regional specialty products.
Market Restraints
- Hardwood feedstock volatility:Beech and hickory supply fluctuations in North American sourcing regions create input cost instability for pyrolysis operators.
- EFSA residue benchmarking:The European Food Safety Authority's benzo(a)pyrene maximum limits impose expensive chromatographic testing burdens on every production lot.
- Traditional smoking substitution ceiling:Premium cured meat segments in Italy and Spain retain consumer preference for chamber-smoked products over liquid alternatives.
Strategic Opportunities
- Clean-label sauce marinades:Artisanal condiment producers in France are qualifying smoke condensates for differentiated barbecue and Worcestershire formulations.
- EFSA novel food ingredient pathway:Pending reclassification discussions could create first-mover advantage for suppliers who pre-file comprehensive safety dossiers.
- Plant-based protein flavoring:European meat-alternative manufacturers are testing smoke condensates to replicate traditional cured profiles in mycelium and pea-protein products.
Industry Challenges
- Validated analytical method scarcity:Commercial laboratories capable of ISO 17025-compliant PAH quantification for smoke condensates are concentrated in Germany and the Netherlands, creating testing bottlenecks.
- Parallel certification complexity:Manufacturers must maintain separate GRAS documentation for FDA, EFSA dossiers for REACH, and Food Sanitation Act compliance for Japanese importers, multiplying regulatory affairs headcount.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoked Condensates Market |
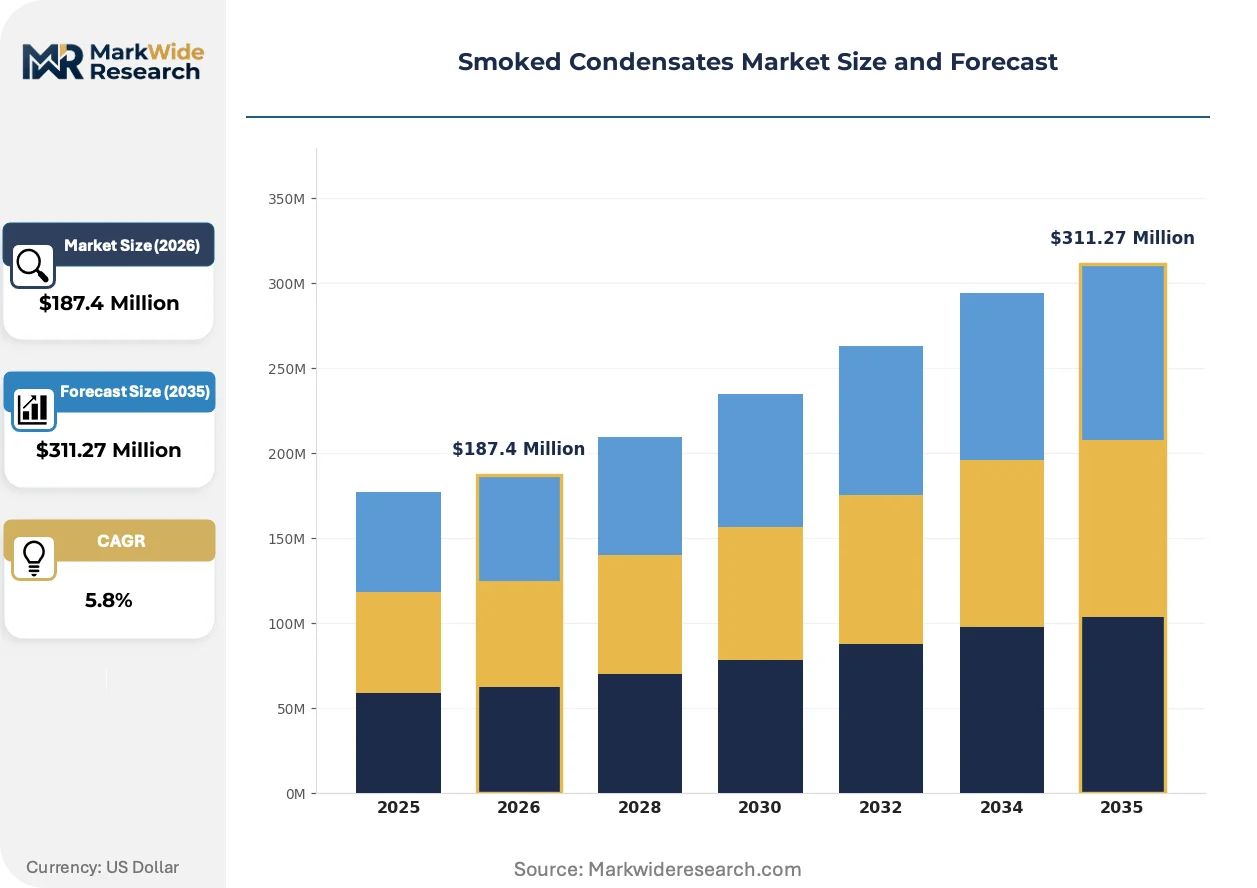
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Smoke, Wood Smoke, Natural Smoke, Synthetic Smoke Application: Food Preservation, Flavoring Agents, Marinades, Barbecue Sauces Packaging Type: Bottles, Pouches, Drums, Canisters End User: Food Industry, Restaurants, Catering Services, Retail Markets |
| Companies Covered | Kerry Group PLC, Red Arrow International LLC, MSK Ingredients, Sensient Technologies Corporation, Cargill, Incorporated, Archer Daniels Midland Company, Ruteinberg Ingredients BV, The Kraft Heinz Company, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoked Condensates Market Evolving Landscape
Controlled pyrolysis automation is compressing batch-to-batch variability while regulatory convergence around contaminant thresholds is forcing consolidation in analytical capabilities. Procurement patterns are fragmenting as artisanal buyers demand customized smoke profiles distinct from industrial standard formulations.
Membrane filtration technology is unifying phenolic compound recovery with carbonyl fraction separation in a single processing stage. Mid-sized German meat processors are adopting these integrated systems to reduce solvent use and waste streams. The technology is unifying quality control with environmental compliance, collapsing what were previously separate capital expenditure decisions into single equipment procurement cycles.
REACH's 2023 update to pyrolysis-derived substance registration requirements is mandating full supply chain disclosure from hardwood harvest through final condensation. Importers from North American feedstock regions face extended dossier preparation timelines. German domestic suppliers with vertically integrated forestry partnerships are capturing accelerated qualification pathways from ECHA.
Buyer concentration among industrial meat processors is fragmenting as specialty sausage producers in Bavaria establish direct supplier relationships bypassing traditional distribution intermediaries. These smaller accounts demand customized phenolic intensity profiles and shorter minimum order quantities. The shift is most visible in southern Germany, where regional butcher cooperatives are pooling procurement to access formulation services previously reserved for multinational accounts.
Smoked Condensates Market Segmentation
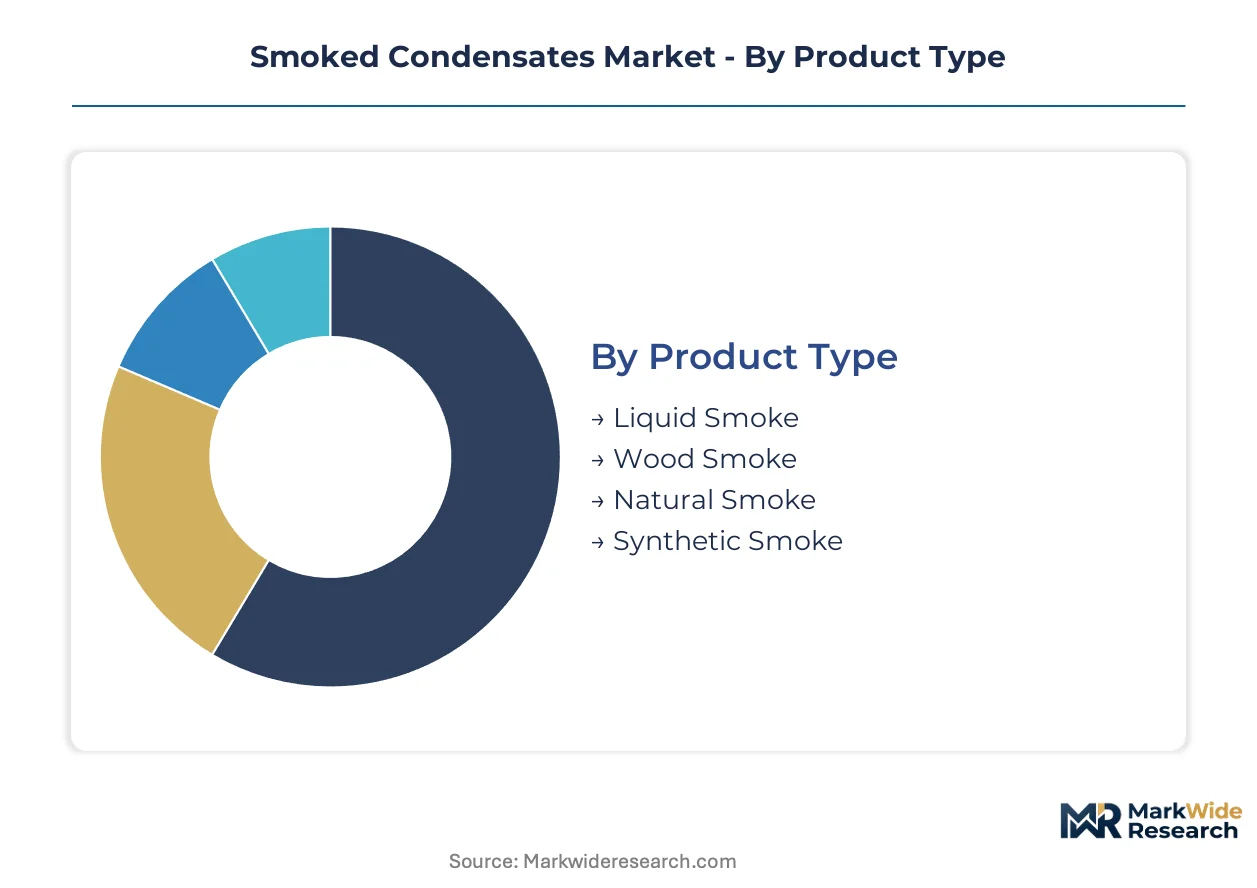
Procurement patterns in smoked condensates diverge sharply between industrial meat processors seeking dosing precision and artisanal producers demanding customized phenolic profiles. Understanding these segment boundaries clarifies where formulation services command premium positioning versus where standard specifications dominate purchasing decisions.
Product Type:
Upgrade cycles in smoke condensate procurement are accelerating as REACH documentation requirements render older synthetic formulations uneconomical to maintain.
- Liquid Smoke:Aqueous solutions of phenolic compounds, carbonyls, and organic acids produced through controlled hardwood pyrolysis. Industrial meat processors in Germany are consolidating procurement of precision-dosed variants to replace traditional chamber smoking while meeting EFSA benzo(a)pyrene benchmarks.
- Natural Smoke:Condensates derived exclusively from hardwood combustion without synthetic carriers or petroleum-based solvents. Clean-label mandates from French and German retailers are displacing artificial smoke additives in premium sausage and bacon product lines.
- Wood Smoke:Fractionated extracts capturing specific volatile compounds from single-species hardwood pyrolysis.
- Synthetic Smoke:Laboratory-compounded flavor mixtures mimicking smoke characteristics through chemically synthesized phenolics.
Volume placements concentrate in Liquid Smoke; the faster expansion belongs to Natural Smoke.
Application:
Margin structures across applications separate mature preservation uses from emerging flavoring opportunities where per-kilogram pricing sustains wider spreads.
- Food Preservation:Antimicrobial smoke condensate applications extending shelf life of cured meats through phenolic bacteriostatic action. Large-scale processors in Bavaria continue standardizing liquid smoke dosing in cooked ham and frankfurter production.
- Flavoring Agents:Concentrated smoke extracts dosed for sensory profile rather than antimicrobial function. Artisanal sauce producers in France are qualifying specialized condensates for differentiated barbecue and Worcestershire formulations commanding formulation service premiums.
- Marinades:Ready-to-apply smoke-infused liquid preparations for protein pre-treatment.
- Barbecue Sauces:Finished condiments incorporating smoke condensates as primary flavor notes.
Food Preservation absorbs the largest shipment volumes; Flavoring Agents extract the steepest margin premiums.
Packaging Type:
Packaging selection tracks order scale and handling automation, with industrial buyers favoring bulk formats and artisanal accounts requiring smaller dispensing units.
- Drums:Industrial-grade bulk containers ranging from 200 to 1000 liters for high-volume meat processing operations. German industrial processors are standardizing drum procurement with integrated pumping systems to reduce handling labor and contamination risk.
- Bottles:Rigid containers from 250 milliliters to 5 liters for precision dosing in small-batch production. Regional butcher cooperatives in Baden-Württemberg are pooling procurement to access bottle-format supply chains previously reserved for multinational accounts.
- Pouches:Flexible film containers for space-efficient storage and reduced shipping weight.
- Canisters:Pressurized or sealed metal containers for oxygen-sensitive formulations.
Drum shipments dominate tonnage movements; Bottle demand is climbing the fastest among specialty meat processors.
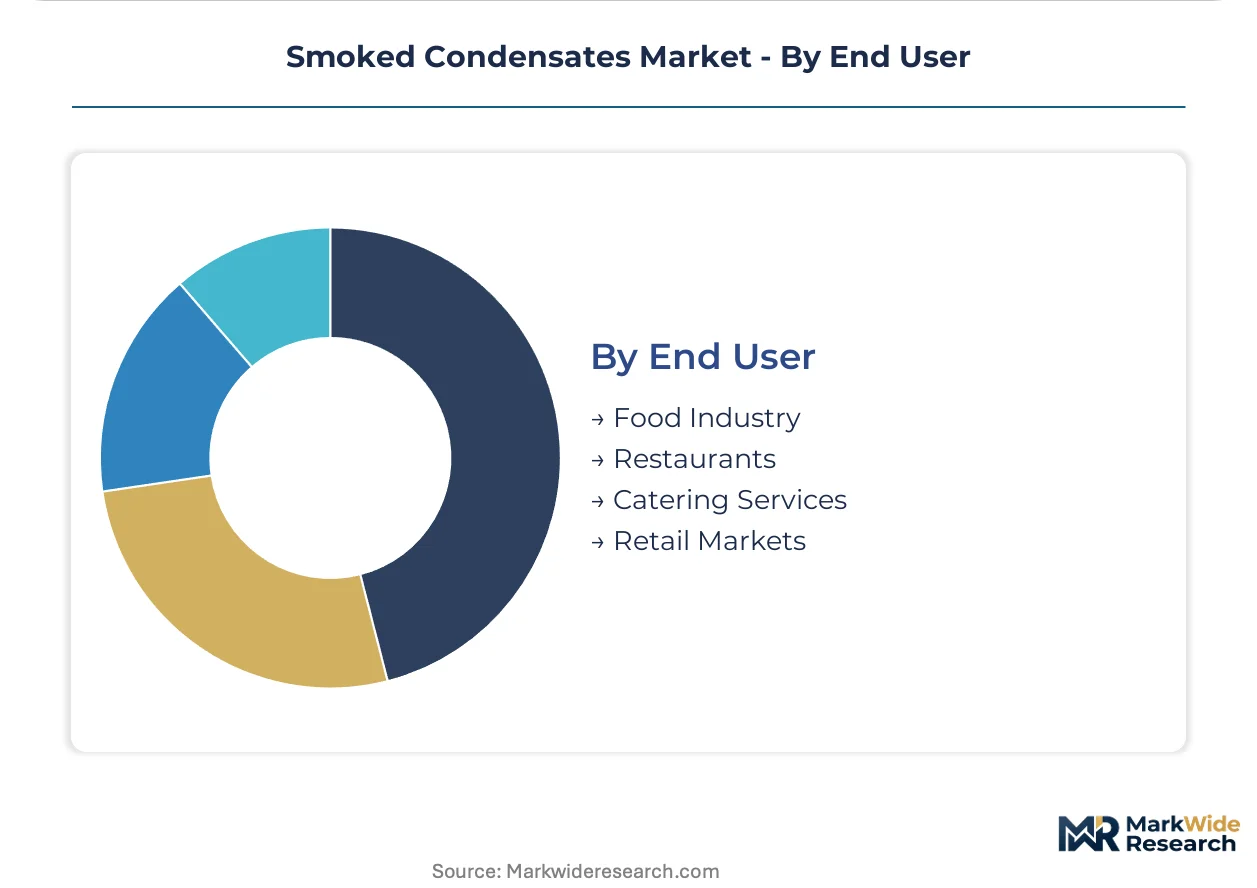
End User:
Customer-type segmentation reveals diverging specification requirements between formulation-integrated food manufacturers and service-sector buyers purchasing finished preparations.
- Food Industry:Integrated meat and condiment manufacturers incorporating smoke condensates into production processes. Processed meat manufacturers across Germany are expanding technical service contracts with domestic condensate suppliers to navigate REACH purity documentation.
- Restaurants:Foodservice operations applying smoke condensates for menu item preparation. Independent barbecue specialists in Berlin and Munich are sourcing small-format natural smoke variants for house-made sauce differentiation.
- Catering Services:Large-scale meal preparation operations requiring consistent smoke flavor across batch production.
- Retail Markets:Packaged goods channels including supermarkets and specialty food stores.
The Food Industry anchors procurement volume; Restaurants are gaining share fastest as smokehouse-style menu proliferation extends beyond traditional barbecue concepts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement intensity concentrates in Germany, where industrial meat processors and artisanal sausage makers are simultaneously qualifying domestic smoke condensate suppliers. Regional patterns diverge sharply between REACH-regulated European markets with stringent purity documentation and FDA-governed North American channels where GRAS status drives formulation decisions.
Germany
Bavarian industrial meat processors and Baden-Württemberg artisanal cooperatives are expanding technical service contracts with domestic condensate suppliers. ECHA's REACH 2023 pyrolysis-derived substance registration update mandates full supply chain disclosure, advantaging vertically integrated German producers with captive forestry partnerships over importers facing extended dossier timelines.
United States
Large-scale protein processors in the Midwest and Southeast are standardizing liquid smoke dosing systems to replace traditional chamber smoking. FDA GRAS status requirements for pyrolysis-derived flavorings create a distinct regulatory pathway from European frameworks, with hardwood feedstock sourcing concentrated in Appalachian and Ozark hardwood regions.
France
Artisanal sauce and condiment producers in Île-de-France and Auvergne-Rhône-Alpes are qualifying specialized smoke condensates for premium barbecue and Worcestershire formulations. ANSM and DGCCRF enforcement of EFSA-aligned benzo(a)pyrene maximum residue limits drives chromatographic testing investment among importers.
Japan
Processed seafood and meat manufacturers in the Kanto and Kansai industrial corridors are testing smoke condensates for traditional cured profile replication. METI-aligned Food Sanitation Act import testing requirements for pyrolysis-derived flavorings compel foreign suppliers to maintain parallel certification dossiers distinct from FDA or EFSA pathways.
Italy
Premium cured meat segments in Emilia-Romagna and Lombardy retain strong consumer preference for traditional chamber-smoked products over liquid alternatives. EFSA residue benchmarking applies uniformly, yet artisanal producers in Parma and Modena maintain heritage smoking methods that limit smoke condensate penetration in high-margin protected designation segments.
Smoked Condensates Market Competitive Landscape
German and Dutch producers anchor one tier with captive laboratory capacity for REACH-compliant PAH quantification; North American specialists hold feedstock advantages through hardwood sourcing control. The vendor structure stratifies across three archetypes: integrated flavor houses with pyrolysis technology, regional condensate specialists with forestry partnerships, and diversified ingredient distributors with formulation service capabilities. Consolidation pressure intensifies as EFSA novel food ingredient reclassification discussions favor suppliers with pre-filed safety dossiers, while capacity expansion concentrates in membrane filtration automation and analytical method validation.
Within the integrated flavor house tier, Kerry Group PLC and Sensient Technologies Corporation exemplify archetypes combining captive pyrolysis technology with batch-to-batch consistency protocols. Among North American feedstock-anchored players, Red Arrow International LLC occupies a position representing backward integration into hardwood sourcing control. These three entities illustrate how regulatory compliance infrastructure and supply chain positioning separate defensible market positions from commodity condensate trading.
| Leading Market Players |
|---|
| Kerry Group PLC |
| Red Arrow International LLC |
| MSK Ingredients |
| Sensient Technologies Corporation |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Ruteinberg Ingredients BV |
| The Kraft Heinz Company |
| Ingredion Incorporated |
| Others |
Value Network & Pricing Analysis
Captive pyrolysis integration among German and Dutch producers anchors both supply security and premium pricing power, as REACH-compliant analytical infrastructure creates barriers that importers cannot easily replicate. This vertical control over hardwood feedstock through forestry partnerships compresses cost variability while supporting margin premiums for batch-to-batch consistency guarantees demanded by Bavarian meat processors.
Pricing Analysis
Volume placements in liquid smoke formulations extract lower per-kilogram returns than specialized natural smoke variants serving clean-label mandates. Pricing stratifies across REACH-certified premium tiers, FDA-aligned GRAS documentation tiers, and economy grades lacking full regulatory dossiers. Cost compression in economy tiers is intensifying because hardwood feedstock volatility in North American sourcing regions transmits directly to spot-market condensate pricing. Artisanal sausage cooperatives in Baden-Württemberg show the highest price sensitivity due to pooled procurement constraints, while industrial meat processors in Bavaria prioritize consistency premiums over unit cost minimization.
Supply Chain Analysis
Direct-to-food-manufacturer channels handle industrial-scale demand from Bavarian ham and frankfurter processors, while specialty distributors serve fragmented artisanal accounts in southern Germany. Geographic supply concentration centers on Germany, the Netherlands, and the United States, with German producers drawing from vertically integrated beech and oak forestry partnerships. Raw material dependencies rest on hardwood feedstock quality, pyrolysis equipment maintenance schedules, and chromatographic reagent availability for PAH testing. Single-source vulnerability in ISO 17025-compliant analytical laboratories concentrated in Germany and the Netherlands creates qualification bottlenecks that extend importer lead times.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated analytical laboratory capacity operates as the binding constraint propping pricing power for incumbent suppliers with captive certification infrastructure. REACH documentation burdens prevent rapid capacity expansion, sustaining margin premiums for qualified domestic producers.
For Market Incumbents: Hedge against hardwood feedstock volatility through long-term forestry partnerships in German and Appalachian sourcing regions. Deepen backward integration into pyrolysis equipment automation to compress batch-to-batch variability that EFSA benzo(a)pyrene thresholds increasingly penalize. Prioritize pre-filing of novel food ingredient safety dossiers ahead of pending EFSA reclassification discussions to secure first-mover qualification pathways.
For New Entrants and Emerging Players: E-commerce-enabled direct procurement platforms targeting artisanal butcher cooperatives in Baden-Württemberg and Bavaria offer the most penetrable entry vector. These pooled buyers demand smaller minimum order quantities and customized phenolic profiles that incumbent industrial-focused suppliers underserve. A formulation-service-first go-to-market angle, bundling smoke profile customization with regulatory documentation support, differentiates against commodity condensate traders.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated flavor houses seeking REACH-compliant European manufacturing capacity. Long-term viability across the analysis window favors suppliers with captive pyrolysis technology and validated analytical methods rather than distribution-only intermediaries. Watch for EFSA novel food ingredient reclassification finalization as the inflection signal that will trigger consolidation among dossier-prepared versus unprepared suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardwood Forestry | Secures feedstock quality consistency required for REACH pyrolysis-derived substance registration. |
| Membrane Filtration Technology Deployment | Unifies phenolic recovery with carbonyl separation, collapsing separate capital expenditure decisions. |
| ISO 17025 Analytical Laboratory Certification | Creates defensible positioning as commercial PAH testing capacity concentrates in Germany and Netherlands. |
| Novel Food Ingredient Dossier Pre-filing | Captures accelerated ECHA qualification pathways ahead of pending EFSA reclassification discussions. |
| Artisanal Cooperative Procurement Pooling | Opens bottle-format supply chains to small-batch meat processors bypassing traditional distribution intermediaries. |
Research Methodology
Trade databases, ECHA registration filings, and food industry customs records formed the secondary backbone for supply-side mapping. Primary interviews with pyrolysis equipment operators, regulatory affairs managers at condensate suppliers, procurement leads at Bavarian meat processors, and laboratory directors at ISO 17025-certified testing facilities provided demand-side validation. Bottom-up shipment data from German drum and bottle format distributors was triangulated against top-down capacity estimates from hardwood pyrolysis operators across the analysis window.
Historical trendline analysis of liquid smoke and natural smoke procurement volumes informed the projection framework. Segmentation dimensions modeled include product type, application function, packaging format, and end-user category alongside regulatory compliance tier. CAGRs were derived through regression analysis of documented shipment patterns and validated against capacity expansion announcements from membrane filtration equipment providers. Forecast inputs incorporated REACH documentation timeline assumptions and hardwood feedstock price sensitivity coefficients.
The model holds under stable EFSA residue benchmarking and REACH pyrolysis-derived substance registration requirements; deviation in novel food ingredient reclassification timing or hardwood supply disruption severity would shift volume and value trajectories. Forecasts reflect documented assumptions regarding laboratory qualification bottlenecks and artisanal procurement fragmentation. Periodic stress-testing of base assumptions against ECHA enforcement patterns and feedstock market developments is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Browning Solutions Market
Flavorings and Food Additives
Vanilla Extract Market
Flavorings and Food Additives
Dry Powder Flavors Market
Flavorings and Food Additives
North America Licorice Extract Market
Flavorings and Food Additives
Argentina Food Flavor and Enhancer Market
Flavorings and Food Additives
China Food Colorants Market
Flavorings and Food Additives
Bergamot Extract Market
Flavorings and Food Additives
Keto Friendly Flavors Market
Flavorings and Food Additives
Global Ginger Extract Market
Flavorings and Food Additives
Clean Label Flavors Market
Flavorings and Food Additives
Egypt Food Flavor and Enhancer Market
Flavorings and Food Additives
Nature Identical Flavorings Market
Flavorings and Food Additives
Taste Modulators Market
Flavorings and Food Additives
Water-Soluble Flavors Market
Flavorings and Food Additives
Neotame Market
Flavorings and Food Additives
Pumpkin Spice Products Market