
 Natural Flavors and Fragrances Market | 2026-2036
Natural Flavors and Fragrances Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Flavors and Fragrances Market Intelligence
The distinction between food manufacturers and cosmetic companies as separate buyer archetypes is collapsing as both seek multifunctional, natural ingredients. Givaudan leverages its scale in both flavor and fragrance divisions to serve this converged demand. International Flavors & Fragrances Inc. differentiates through its R&D platforms developing cross-application solutions. Symrise competes by offering certified sustainable raw material streams for both food and personal care end-uses.
Natural flavors and fragrances are complex preparations obtained from plant or animal sources through processes like distillation, extraction, or fermentation. These ingredients are designed to impart specific taste and scent profiles in consumer goods. Essential oils and natural extracts represent the dominant product types by volume. The food & beverage application holds the largest market share, though personal care applications are expanding rapidly due to consumer preference for plant-based ingredients.
Regulatory frameworks create distinct market conditions. The US FDA maintains specific definitions for what constitutes a 'natural flavor', while the EU's REACH regulation governs the chemical safety assessment of fragrance ingredients. Navigating these divergent standards is a critical competency for suppliers. Success for market participants depends on securing transparent, traceable supply chains to validate natural claims for consumers.
Market Dynamics
The market's central tension lies in reconciling consumer demand for clean-label transparency with the agricultural and logistical complexities of securing traceable, consistent raw material streams. This pressure forces investment in supply chain verification technologies and sustainable sourcing protocols.
Growth Catalysts
- EU Green Deal:The Farm to Fork strategy promotes sustainable food systems, directly influencing the sourcing of raw materials for natural flavors used in European food and beverage products and increasing demand for certified ingredients.
- Consumer Preferences:Heightened consumer focus on plant-based and "free-from" products in the United States and Germany drives expansion for natural fragrances and extracts within the personal care and cosmetics sectors.
- Extraction Technologies:Advances in supercritical fluid extraction and molecular distillation enable higher-purity, solvent-free essential oils and oleoresins from botanicals, expanding their functional use in sensitive applications like infant nutrition.
Market Restraints
- Input Cost Volatility:Climate-driven disruptions to crop yields, such as for vanilla in Madagascar or citrus in Brazil and the United States, create unpredictable raw material costs and supply chain instability for key ingredients.
- Regulatory Divergence:Conflicting definitions of what constitutes a 'natural flavor' between the US FDA and European food safety authorities create significant compliance and formulation hurdles for global manufacturers.
- Technical Limitations:The inherent instability of certain natural colorants and fragrances when exposed to heat, light, or oxygen limits their viability in products requiring long shelf life or undergoing harsh processing.
Strategic Opportunities
- Geographic Expansion:Underpenetrated markets for premium, natural personal care products in Southeast Asian economies, including Thailand and Malaysia, offer significant growth runways for sophisticated natural fragrances.
- Functional Ingredients:The emergence of functional fragrances in wellness and aromatherapy products, designed to elicit specific moods or cognitive benefits, opens a new, high-margin application segment beyond traditional perfumery.
- Biotechnology Integration:Fermentation-based production of high-value flavor molecules like vanillin offers a scalable, non-agricultural alternative that decouples supply from the climatic and geopolitical risks of traditional cultivation.
Industry Challenges
- Certification Hurdles:The extensive time and cost required to secure and maintain certifications such as USDA Organic or Non-GMO Project Verified for complex, multi-ingredient supply chains pose a significant barrier to entry for smaller suppliers.
- Talent Scarcity:A shortage of flavorists and perfumers with deep expertise in formulating with variable, complex natural materials constrains the research and development capacity of ingredient houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Flavors and Fragrances Market |
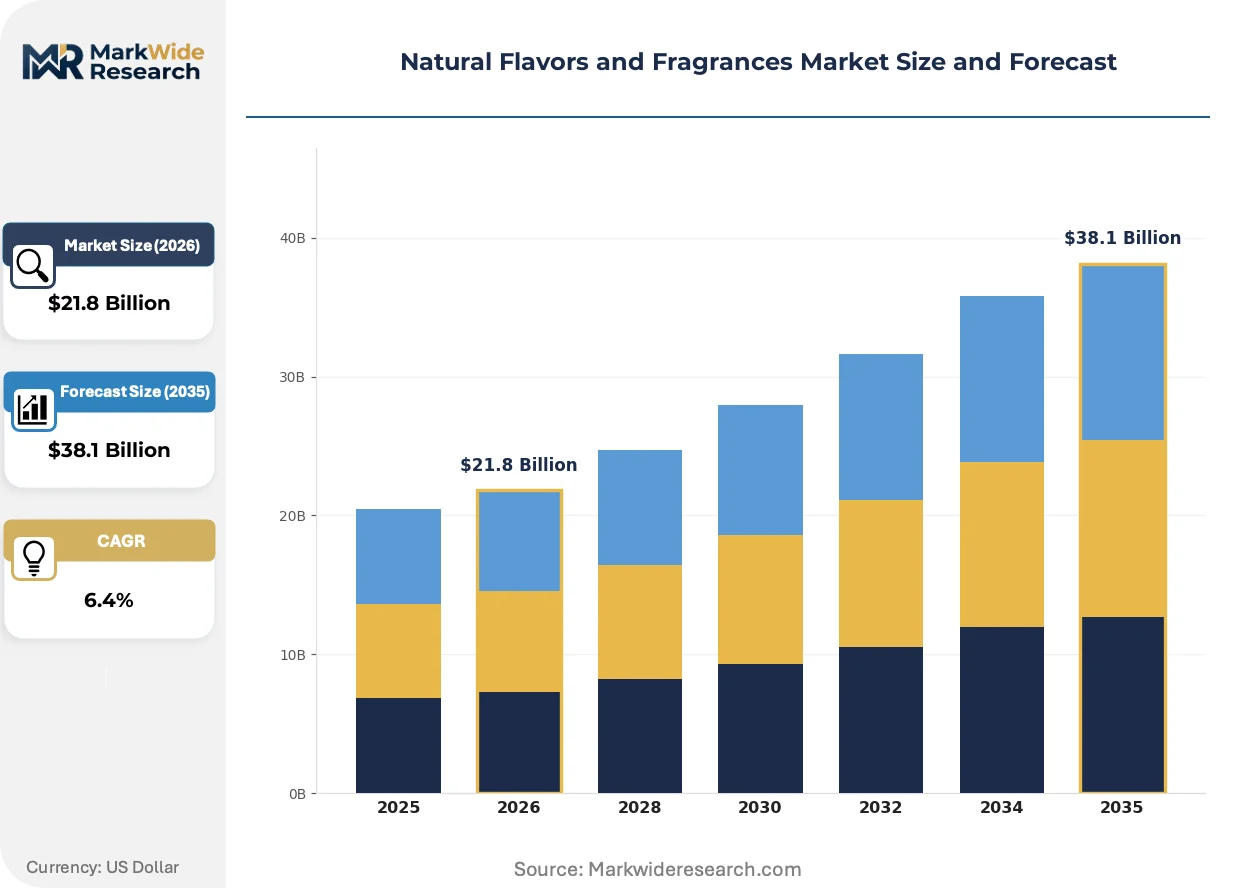
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $38.1 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Natural Extracts, Oleoresins, Natural Flavoring Substances Application: Food & Beverage, Cosmetics, Household Products, Personal Care End User: Food Manufacturers, Cosmetic Companies, Household Brands, Fragrance Houses Distribution Channel: Direct Sales, Online Retail, Distributors, Specialty Stores |
| Companies Covered | Givaudan, International Flavors & Fragrances Inc., DSM-Firmenich, Symrise, Takasago International Corporation, Sensient Technologies Corporation, Kerry Group, MANE, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Flavors and Fragrances Market Strategic Shifts & Innovations
A focus on industrializing nature defines the current innovation cycle, as suppliers apply biotechnologies and data analytics to de-risk and scale volatile agricultural supply chains. This shift prioritizes consistency and verifiable origin over artisanal production methods.
AI-driven sensory analysis platforms map chemical compounds to taste and scent profiles, creating digital fingerprints for raw materials. Food and beverage manufacturers adopt these tools to accelerate product development and ensure consistency. This technology is fragmenting the traditional role of the human sensory panel, augmenting it with data-driven analysis for quality control.
The Corporate Sustainability Reporting Directive (CSRD) in the European Union mandates detailed disclosure on supply chain environmental and social impacts. This regulation forces flavor and fragrance houses to implement robust traceability systems for ingredients sourced from Africa and Southeast Asia. The food and beverage segment is most affected, requiring suppliers to provide verifiable data on water usage and biodiversity.
Consumer purchasing decisions are evolving from a simple check for "natural" on the ingredient list to a demand for proof of sustainable and ethical sourcing. This shift disrupts procurement models that prioritized cost, replacing them with partnerships based on transparent supply chains. This trend is most prominent in European and North American personal care markets, where brand storytelling around origin is a key differentiator.
Natural Flavors and Fragrances Market Segmentation
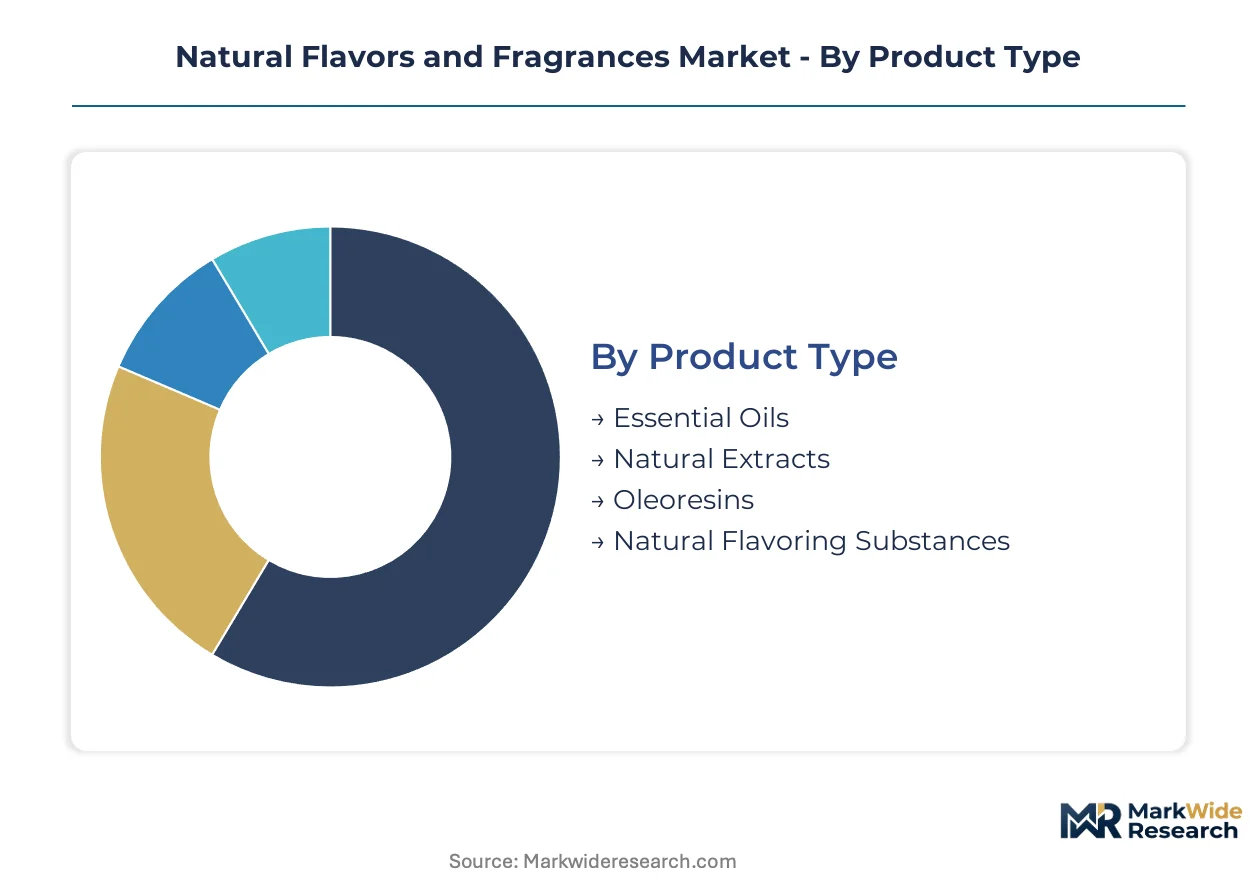
Understanding market segmentation reveals the diverse pathways through which natural flavors and fragrances reach consumers. This granular analysis distinguishes distinct product forms, end-use applications, and consumer segments driving demand. Segmentation clarifies the specific functional requirements and regulatory landscapes shaping ingredient formulation and supply chain strategies.
Product Type:
Margin pools within the product type category often concentrate in highly purified and specialized natural extracts.
- Essential Oils:These concentrated hydrophobic liquids contain volatile aroma compounds from plants, obtained typically by distillation. Demand for essential oils is concentrating in the United States personal care market due to consumer preference for aromatherapy and plant-based ingredients.
- Natural Extracts:These are complex mixtures derived from botanicals using solvents, capturing a broader range of non-volatile and volatile compounds. Global food and beverage manufacturers increasingly seek natural extracts for clean-label product development, driven by the EU Green Deal's sustainable sourcing mandates.
- Oleoresins:These semi-solid extracts contain both volatile and non-volatile compounds, providing concentrated flavor and color. Citrus-derived oleoresins are particularly sought by food manufacturers in Germany.
- Natural Flavoring Substances:These individual chemical substances are isolated from natural sources through physical or enzymatic processes. They find application in infant nutrition due to their defined purity profiles.
Essential Oils hold installed capacity. Natural Extracts are rotating up the share rankings.
Application:
Specific applications dictate ingredient purity and regulatory compliance for natural flavor and fragrance compounds.
- Food & Beverage:This application integrates natural flavors for taste enhancement and clean-label appeal across diverse product categories. The segment holds the largest market share, driven by consumer demand for plant-based offerings in European food products.
- Personal Care:This segment incorporates natural fragrances and extracts for scent, skin benefits, and "free-from" product positioning. Personal care applications are expanding rapidly in North America due to consumer focus on botanical ingredients.
- Cosmetics:Natural fragrances and extracts provide sensorial attributes and functional benefits in cosmetic formulations. Manufacturers differentiate products through certified sustainable raw materials.
- Household Products:Natural flavors and fragrances enhance the consumer experience in cleaning agents and air fresheners. Demand focuses on biodegradable and non-toxic formulations.
Food & Beverage drives current volume. Personal Care exhibits the steepest expansion trajectory.
End User:
Customer types vary significantly by procurement capabilities and branding requirements within the natural ingredient market.
- Food Manufacturers:These companies integrate natural flavors into a wide array of products, requiring consistent supply and regulatory compliance with US FDA and European food safety authorities. They prioritize traceable supply chains to validate natural claims for consumers.
- Cosmetic Companies:These entities utilize natural fragrances and extracts for product differentiation and to meet consumer demand for plant-based personal care items. They focus on sustainable sourcing protocols and brand storytelling around ingredient origin.
- Household Brands:These brands incorporate natural fragrances into cleaning and home care products, seeking cost-effective and stable solutions. They value ingredients with certified eco-friendly profiles.
- Fragrance Houses:These specialized firms develop complex natural fragrance compositions for various industries. They require a broad palette of high-purity essential oils and extracts.
Food Manufacturers account for substantial procurement. Cosmetic Companies are gaining share among specialized buyers.
Distribution Channel:
Distribution channels reflect varying scales of delivery and customer relationships for natural flavor and fragrance ingredients.
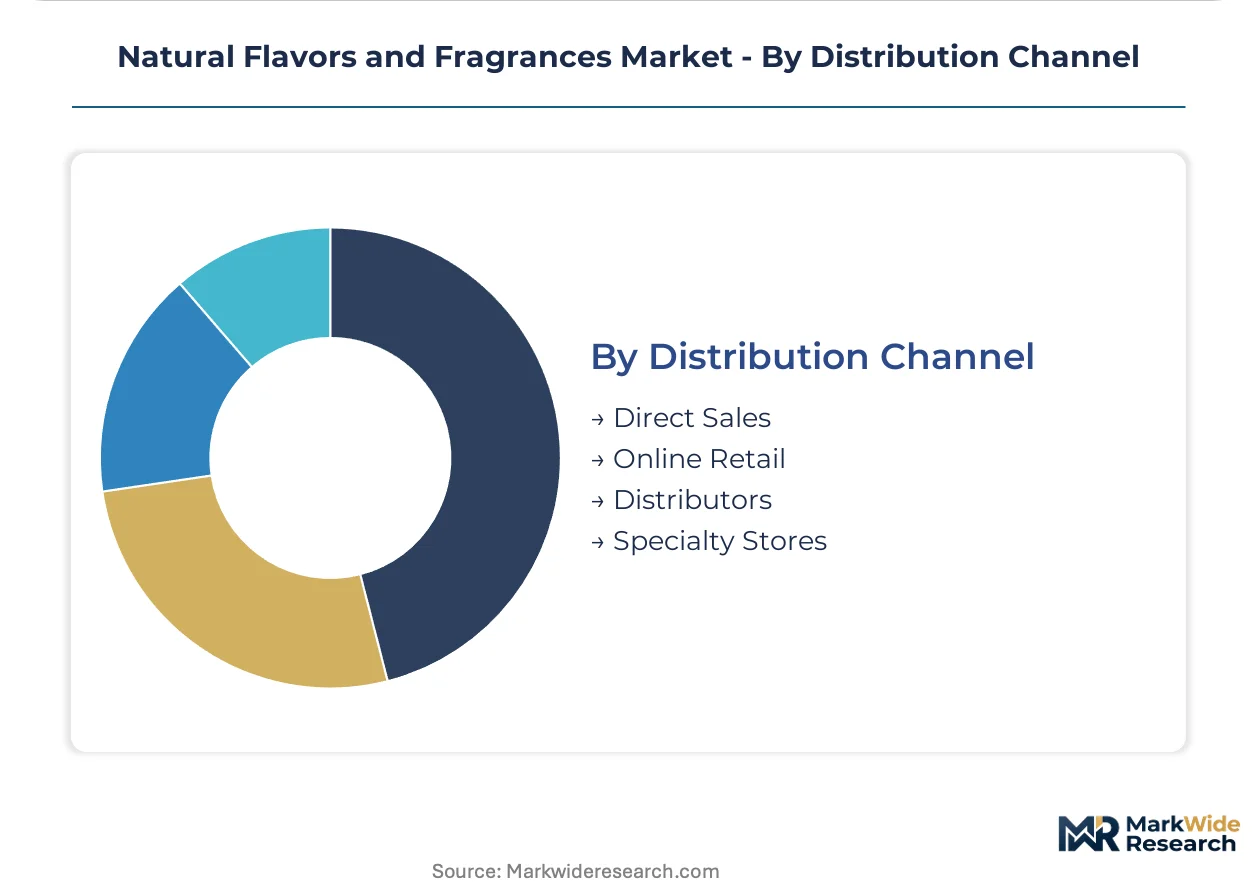
- Direct Sales:Manufacturers engage in direct sales for large-volume orders and custom formulations, fostering close technical collaboration with major clients. This channel ensures direct oversight of supply chain integrity and specific client needs.
- Distributors:These intermediaries manage logistics and provide regional market access for a diverse portfolio of natural ingredients, serving smaller manufacturers and specialized end-users. They offer flexibility and localized technical support across various geographies.
- Online Retail:This channel facilitates access for smaller businesses and specialized product lines, emphasizing transparency and ingredient information. It supports niche markets for artisanal and certified organic products.
- Specialty Stores:These outlets cater to consumers seeking premium, natural personal care and aromatherapy products. They often feature brands with strong origin stories and sustainability claims.
Direct Sales facilitates broad market reach. Online Retail is expanding through digital platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Major international shipping lanes facilitate the global trade of natural flavor and fragrance raw materials and finished products. This infrastructure underpins the market's reach, allowing diverse botanicals to reach processing centers and consumer markets worldwide. Robust logistical networks are essential for maintaining consistent supply chains.
United States
Demand for plant-based and "free-from" products drives natural fragrance and extract expansion in personal care. The US FDA maintains specific definitions for 'natural flavor', shaping product development and labeling. New Jersey's chemical corridor, particularly around cities like Princeton, serves as a hub for flavor and fragrance R&D and production.
Germany
Consumer preference for clean-label offerings in food and personal care fuels demand for natural ingredients. The EU Green Deal's Farm to Fork strategy directly influences sustainable sourcing for European food products. Hamburg, a major port city, concentrates import and processing activities for botanicals and citrus-derived oleoresins.
Thailand
Underpenetrated markets for premium natural personal care products offer significant growth runways for sophisticated natural fragrances. Thailand's Ministry of Public Health regulates cosmetic ingredients, influencing natural extract formulations. Bangkok's industrial parks attract investment in manufacturing facilities for personal care and aroma products.
Malaysia
Expanding consumer interest in plant-based ingredients in Southeast Asia drives opportunities for natural flavors and fragrances. Malaysia's National Pharmaceutical Regulatory Agency (NPRA) oversees safety standards for cosmetic and food ingredients. The Klang Valley region emerges as a key distribution and processing center for imported botanical raw materials.
France
European consumer demand for traceable and ethically sourced ingredients strengthens the market for natural fragrances in cosmetics. The EU's REACH regulation governs chemical safety assessment for fragrance components, ensuring compliance. Grasse, historically the world's perfume capital, continues to innovate in natural extract production and perfumery.
Natural Flavors and Fragrances Market Key Industry Players
Concentration sits with large, multinational flavor and fragrance houses that operate across both food and personal care segments. The market exhibits a tiered structure, with a few dominant players alongside numerous specialized ingredient providers and regional niche firms. These entities often leverage their extensive R&D platforms to develop cross-application solutions, bridging the gap between taste and scent. Strategic partnerships, capacity expansion, and geographic diversification are common competitive moves among these firms seeking to secure raw material access and expand market reach.
Within the integrated flavor and fragrance solutions tier, Givaudan, a Switzerland-based entity, exemplifies a company with broad portfolios across both taste and scent. International Flavors & Fragrances Inc., an American corporation, further represents the scale-driven end of the market, serving diverse end-use applications globally. Symrise AG, a German firm, also occupies a position among these major players, emphasizing certified sustainable raw material streams and leveraging its expertise in both food and personal care. These entities collectively anchor the industry's capacity for complex ingredient development and global supply chain management, often through direct sales channels.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances Inc. |
| DSM-Firmenich |
| Symrise |
| Takasago International Corporation |
| Sensient Technologies Corporation |
| Kerry Group |
| MANE |
| ADM |
| Others |
Cost & Logistics Intelligence
Biotechnological production of high-value flavor molecules like vanillin simultaneously reshapes supply geography and pricing economics. This shift mitigates climate-driven volatility previously tied to agricultural sources, influencing cost stability for key flavor ingredients.
Pricing Analysis
Contract-based long-term offtake agreements, often with volume-discount tiering, characterize the dominant pricing model. Price differentiation stems from the certification level, such as USDA Organic or Non-GMO Project Verified, and the degree of customization required for specific formulations. Pricing pressure stems from input cost volatility, particularly for botanicals like vanilla and citrus, due to climate disruptions. Household Brands demonstrate the highest price sensitivity, while specialized Fragrance Houses are less sensitive given their unique composition requirements.
Supply Chain Analysis
Madagascar anchors global vanilla bean production, while Brazil and the United States concentrate citrus fruit supply for oleoresins. The supply chain draws from botanical extracts and essential oils as core raw material dependencies. Climate-driven crop yield disruptions, exemplified by vanilla in Madagascar, present a significant structural supply chain risk. Distribution runs through Direct Sales for major multinational clients, supplemented by Distributors providing regional market access and technical support for smaller manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Natural Flavors and Fragrances market offers a defensive moat due to regulatory entrenchment, as navigating diverse global standards creates significant barriers for new entrants. This ensures established players maintain market position.
For Market Incumbents:Consolidate specialized ingredient portfolios to offer comprehensive, cross-application solutions, mitigating the threat from emerging biotechnology firms offering fermentation-based alternatives. Invest in sustainable sourcing protocols and advanced R&D in extraction technologies for higher purity extracts. This strategy defends against input cost volatility and strengthens clean-label claims, reinforcing market leadership.
For New Entrants and Emerging Players:Anchor in underpenetrated Southeast Asian markets for premium natural personal care products, leveraging local botanical diversity and a strong focus on ethical sourcing. Target functional fragrances designed for wellness and aromatherapy applications, which represent a high-margin niche. A go-to-market angle emphasizing transparent supply chain storytelling and digital platforms can facilitate direct consumer engagement.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with mid-cap ingredient houses specializing in certified sustainable raw materials or advanced extraction technologies, offering attractive targets. The market demonstrates long-term viability over the next decade, driven by sustained consumer demand for natural, clean-label products. A signal to watch is increased M&A activity among biotechnology firms focused on scalable, fermentation-based flavor molecule production.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Biotechnology facilities for fermentation-based flavor production reduce reliance on volatile agricultural supply. |
| Green Manufacturing Transition | Implementing solvent-free extraction methods for essential oils meets consumer demand for cleaner processing. |
| Long-term Supply Agreement | Securing multi-year contracts for vanilla beans from Madagascar stabilizes raw material costs. |
| Product Launch | Introducing new functional fragrance lines for aromatherapy expands high-margin application segments. |
| Geographic Expansion | Establishing R&D centers in Southeast Asia accesses novel botanicals and local market insights. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary validation from regulatory filings anchors the qualitative findings. This involved discussions with flavorists, perfumers, procurement leads, R&D directors, and sustainability officers. Secondary data sources included US FDA guidelines, EU REACH regulations, corporate sustainability reports, and trade association publications, supporting bottom-up and top-down triangulation.
Sensitivity analysis informs the comprehensive analytical framework used to project market dynamics across the analysis window. The model incorporates segmentation dimensions including product type, application, end user, distribution channel, and regional regulatory environment. Compound annual growth rates were derived from historical market data and projected demand drivers, with crop yield forecasts for key botanicals and consumer preference shifts as industry-specific inputs.
Decision-makers should treat outputs as directional under base assumptions of stable regulatory frameworks and predictable climate patterns; material deviation would warrant model refresh. Forecasts reflect these assumptions, acknowledging that significant geopolitical disruptions or unforeseen technological breakthroughs could revise projections. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Citrus Flavonoid Complexes from Mediterranean Peels Market
Flavorings and Food Additives
North America Licorice Extract Market
Flavorings and Food Additives
North America Food Flavor Market
Flavorings and Food Additives
Sea Urchin and Roe Flavor Ingredients Market
Flavorings and Food Additives
Global Acerola Extracts Market
Flavorings and Food Additives
Fenchol Market
Flavorings and Food Additives
Flavor Modulators Market
Flavorings and Food Additives
Farnesol Market
Flavorings and Food Additives
United States Food Flavor Market
Flavorings and Food Additives
Oryzanol Market
Flavorings and Food Additives
Oil Soluble Flavors Market
Flavorings and Food Additives
Roast Flavoring Market
Flavorings and Food Additives
Tangerine Peel Extract Market
Flavorings and Food Additives
Lemon Oil Market
Flavorings and Food Additives
Global Ginger Extract Market
Flavorings and Food Additives
North America Food Colorants Market