
 Food Grade Magnesium Derivatives Market | 2026-2036
Food Grade Magnesium Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Magnesium Derivatives Market Intelligence
Direct procurement by large-scale food and nutraceutical manufacturers is reconfiguring traditional distribution networks for magnesium derivatives. K+S Aktiengesellschaft leverages its extensive mining and processing scale to serve these large accounts globally. Compass Minerals specializes in high-purity magnesium chloride sourced from natural brines. Grecian Magnesite differentiates through its focus on specific carbonate and oxide grades for specialized food applications.
Food grade magnesium derivatives are inorganic or organic magnesium salts purified to meet stringent food safety and quality specifications, often produced via precipitation and calcination. They function as pH adjusters, anti-caking agents, and essential mineral fortifiers in processed foods and supplements. Magnesium oxide dominates the food additives segment by volume for processing functions. In contrast, magnesium citrate represents the fastest-growing product type, driven by high-bioavailability demand in the nutraceuticals and dietary supplements space.
The market operates under strict regulatory oversight from bodies like the US FDA and the European Food Safety Authority (EFSA). These agencies, along with standards like the Food Chemicals Codex (FCC), set purity criteria and limits on heavy metals. Compliance with these diverse international regulations, including those from China's SAMR, is critical for global market access. Future success depends on manufacturers' ability to maintain consistent, certified quality across multiple jurisdictions.
Market Dynamics
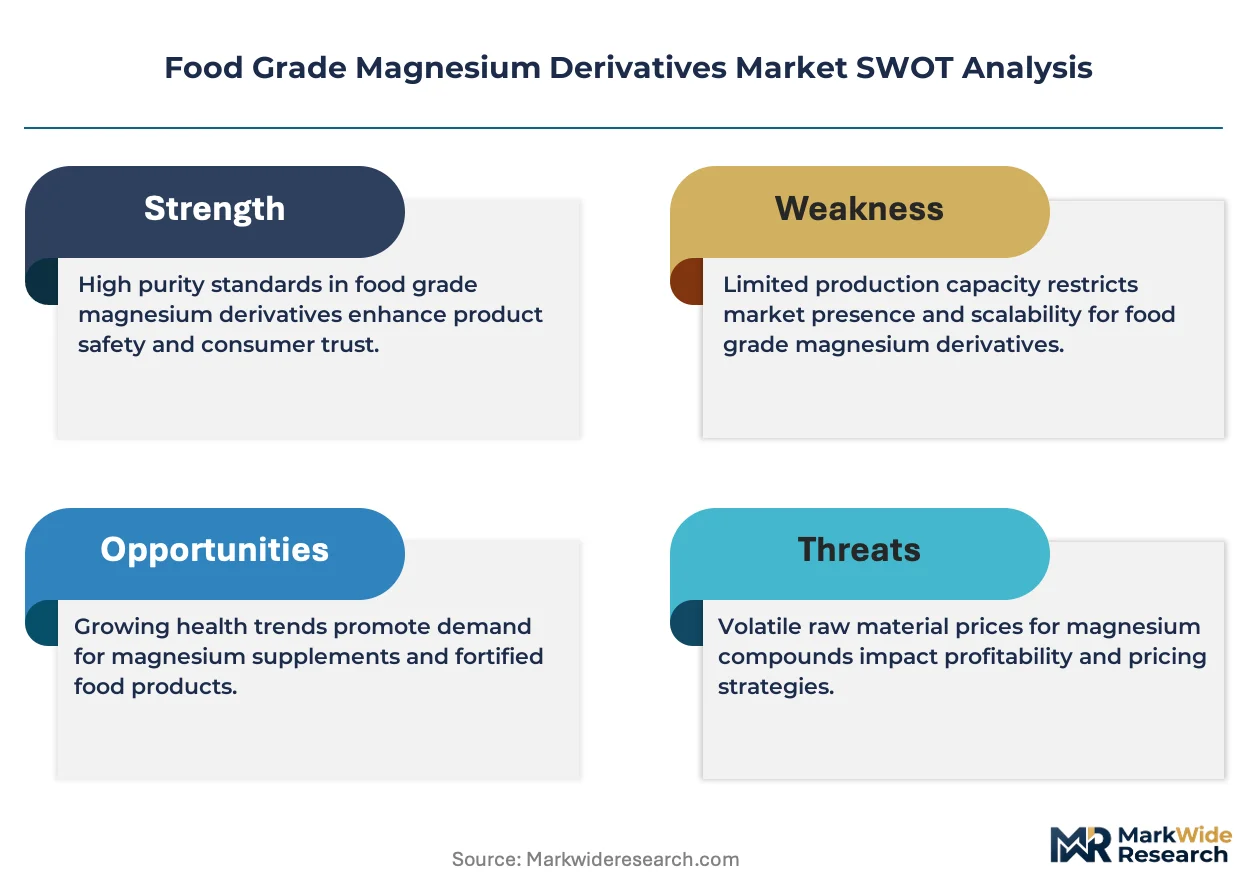
The market's central dynamic is the tension between magnesium derivatives serving as high-volume, low-cost processing aids and their role as high-value, scientifically-backed functional ingredients. This bifurcation influences everything from production technology and pricing to regulatory engagement and supply chain structure.
Growth Catalysts
- Nutraceutical Demand:Consumer focus on preventative health and wellness is driving the fortification of foods, beverages, and dietary supplements with bioavailable magnesium forms like citrate and malate for bone, muscle, and nerve health.
- Clean Label Movement:The use of magnesium carbonate and oxide as natural anti-caking agents, pH regulators, and color retention aids in processed foods aligns with consumer demand for simpler, more recognizable ingredient lists.
- Regulatory Fortification Guidelines:Mandates and recommendations from bodies like the US FDA and Europe's EFSA concerning mineral content in specific food categories encourage manufacturers to incorporate food grade magnesium, creating sustained demand.
Market Restraints
- Energy Price Volatility:The production of magnesium oxide via calcination is an energy-intensive process, making its cost structure highly sensitive to fluctuations in global natural gas and electricity prices, impacting final product pricing.
- Geographic Source Concentration:High-purity magnesium sources, such as specific magnesite deposits or natural salt brines like those at the Great Salt Lake, are geographically concentrated, creating potential supply chain vulnerabilities and logistical costs.
- Complex Regulatory Compliance:Manufacturers face significant administrative and testing burdens to simultaneously comply with the distinct purity standards and heavy metal limits set by the US FDA, EFSA, and China's SAMR.
Strategic Opportunities
- Specialized Nutrition Applications:There is significant potential in developing highly purified, targeted magnesium compounds for specialized nutritional products, including infant formula, clinical nutrition, and foods for specific medical purposes.
- Bioavailability Innovation:Research into novel organic magnesium salts and chelated forms that offer superior absorption, solubility, or targeted physiological benefits presents a pathway to differentiate products beyond commodity grades.
- Southeast Asian Market Penetration:Expanding food processing and supplement industries in countries like Vietnam, Indonesia, and Thailand offer new growth frontiers for suppliers who can navigate regional distribution and regulatory requirements.
Industry Challenges
- Maintaining Batch Consistency:Ensuring consistent purity, particle size, and density from lot to lot is a significant operational challenge that requires rigorous process controls and extensive quality assurance testing to meet Food Chemicals Codex (FCC) specifications.
- Segregated Supply Chains:Preventing cross-contamination between industrial-grade and food-grade magnesium derivatives requires dedicated production lines, storage facilities, and transportation logistics, adding complexity and cost.
- Formulator Education Gap:A persistent challenge involves educating food and supplement formulators on the functional and bioavailability differences among various magnesium salts, which influences purchasing decisions beyond simple cost-per-kilogram metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Magnesium Derivatives Market |
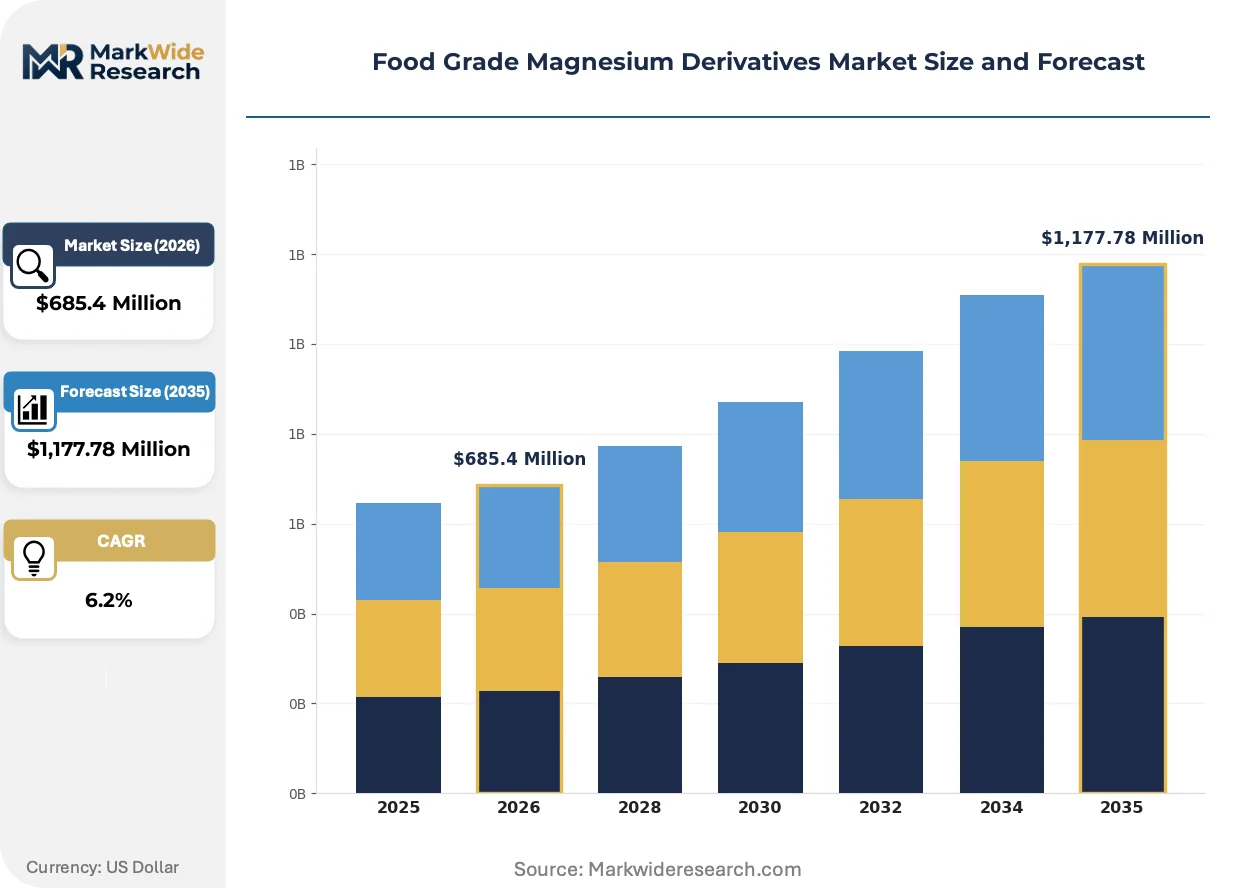
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnesium Hydroxide, Magnesium Carbonate, Magnesium Citrate, Magnesium Oxide Application: Food Additives, Nutraceuticals, Dietary Supplements, Food Preservation Form: Powder, Granule, Tablet, Liquid End User: Food & Beverage, Pharmaceuticals, Personal Care, Animal Nutrition |
| Companies Covered | OLE Chemical Co., Ltd., Ibar Northeast, Grecian Magnesite, K+S Aktiengesellschaft, NikoMag, Compass Minerals, Sinwon Industrial Co., Ltd., Hawkins, Martin Marietta Magnesia Specialties, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Magnesium Derivatives Market Strategic Shifts & Innovations
A fundamental bifurcation defines the market's evolution, splitting it between commodity-like processing aids and specialized, high-margin functional ingredients. This divergence is pushing producers to choose between scale-driven efficiency for bulk products and innovation-driven value for nutraceutical applications.
Co-processed and chelated magnesium compounds, which bind the mineral to organic acids or amino acids, are gaining traction. The nutraceutical and functional beverage sectors are rapidly adopting these forms for their superior solubility and bioavailability compared to standard inorganic salts. This development is hybridizing the boundary between a simple mineral and a complex, high-performance ingredient, enabling novel product formulations.
Heightened enforcement of GB standards for food additives by China's State Administration for Market Regulation (SAMR) is compelling suppliers to upgrade their quality control systems. This regulatory pressure requires more comprehensive documentation and testing for market access, impacting both domestic producers and international exporters. The dietary supplement segment, a major consumer of magnesium citrate and oxide, is most directly affected by these stricter compliance demands.
Large-scale buyers in the food and nutraceutical industries are altering procurement patterns by establishing direct sourcing relationships with primary magnesium derivative producers. This model bypasses traditional chemical distributors, allowing major brands to secure supply, control quality specifications, and potentially lower costs through volume purchasing. The shift is most visible in North America, where large consumer packaged goods companies leverage their scale to manage their supply chains more directly.
Food Grade Magnesium Derivatives Market Segmentation
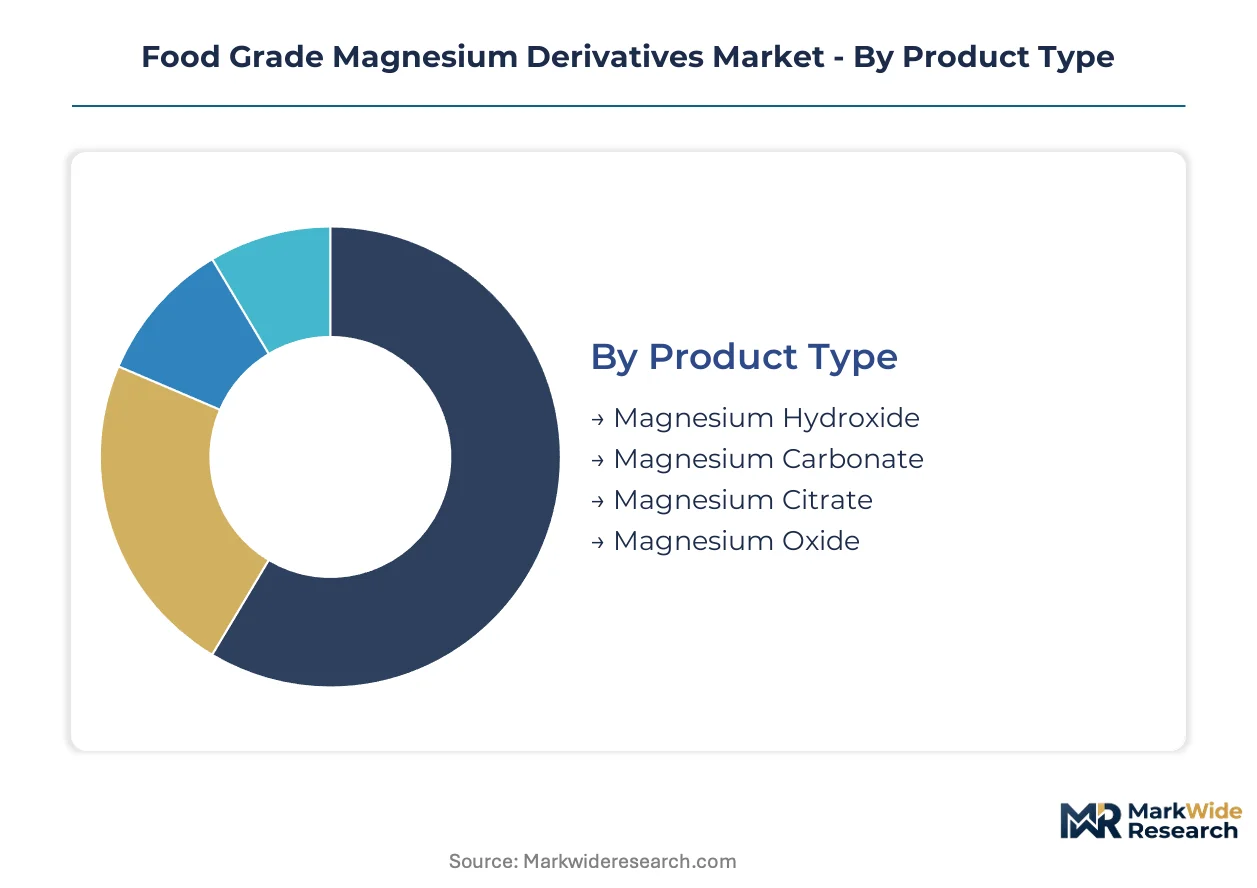
Understanding the varied applications and product forms of food grade magnesium derivatives is critical for market participants. Segmentation highlights the distinct value propositions and regulatory landscapes influencing different product types and end-user industries.
Product Type:
The product type segment spans from mature, high-volume processing aids to rapidly emerging, high-value functional ingredients.
- Magnesium Oxide:This inorganic magnesium salt is often produced via calcination and serves as a primary processing aid. It dominates the food additives segment by volume for pH adjustment and anti-caking functions in processed foods and supplements in China.
- Magnesium Citrate:An organic magnesium salt chelated with citric acid, it offers superior bioavailability and solubility compared to inorganic forms. Demand for magnesium citrate is rapidly expanding in nutraceuticals and dietary supplements for bone, muscle, and nerve health.
- Magnesium Hydroxide:Used as an antacid and laxative in pharmaceutical applications, it also functions as a pH regulator in some food processing.
- Magnesium Carbonate:Functions as an anti-caking agent and pH regulator in food processing, aligning with clean label initiatives.
Magnesium Oxide handles the majority of throughput; Magnesium Citrate is the fastest mover on share.
Application:
Volume concentration differentiates applications, from commodity processing aids to specialized health-focused ingredients.
- Food Additives:Magnesium derivatives function as pH adjusters, anti-caking agents, and processing aids within this high-volume segment. Large-scale food manufacturers utilize these for functional properties in a wide array of processed foods.
- Nutraceuticals:This segment incorporates bioavailable magnesium forms for specific health benefits, such as bone and muscle support. Demand is driven by consumer focus on preventative health and wellness, particularly in North America and Europe.
- Dietary Supplements:Focuses on specific magnesium forms like citrate for mineral fortification, supporting daily nutritional intake.
- Food Preservation:Magnesium derivatives contribute to extending shelf life and maintaining food quality in certain applications.
The Food Additives segment holds the largest volume; Nutraceuticals exhibit the steepest expansion trajectory.
Form:
Customer type preference dictates the dominant form, with industrial users favoring bulk and consumers valuing convenience.
- Powder:This fine particulate form offers high surface area, facilitating dissolution and dispersion in various formulations. It is preferred by large-scale food and nutraceutical manufacturers for bulk processing and ingredient blending.
- Tablet:A compressed solid form, tablets often contain binders and excipients for controlled release or precise dosage. This form dominates the dietary supplement sector, offering consumer convenience and accurate dosing.
- Granule:Offers improved flowability and reduced dusting compared to powder, suitable for certain blending processes.
- Liquid:Provides enhanced solubility and ease of incorporation into beverages and specific clinical nutrition formulations.
Powder forms are critical for industrial users; Tablet forms are gaining share in consumer-facing products.
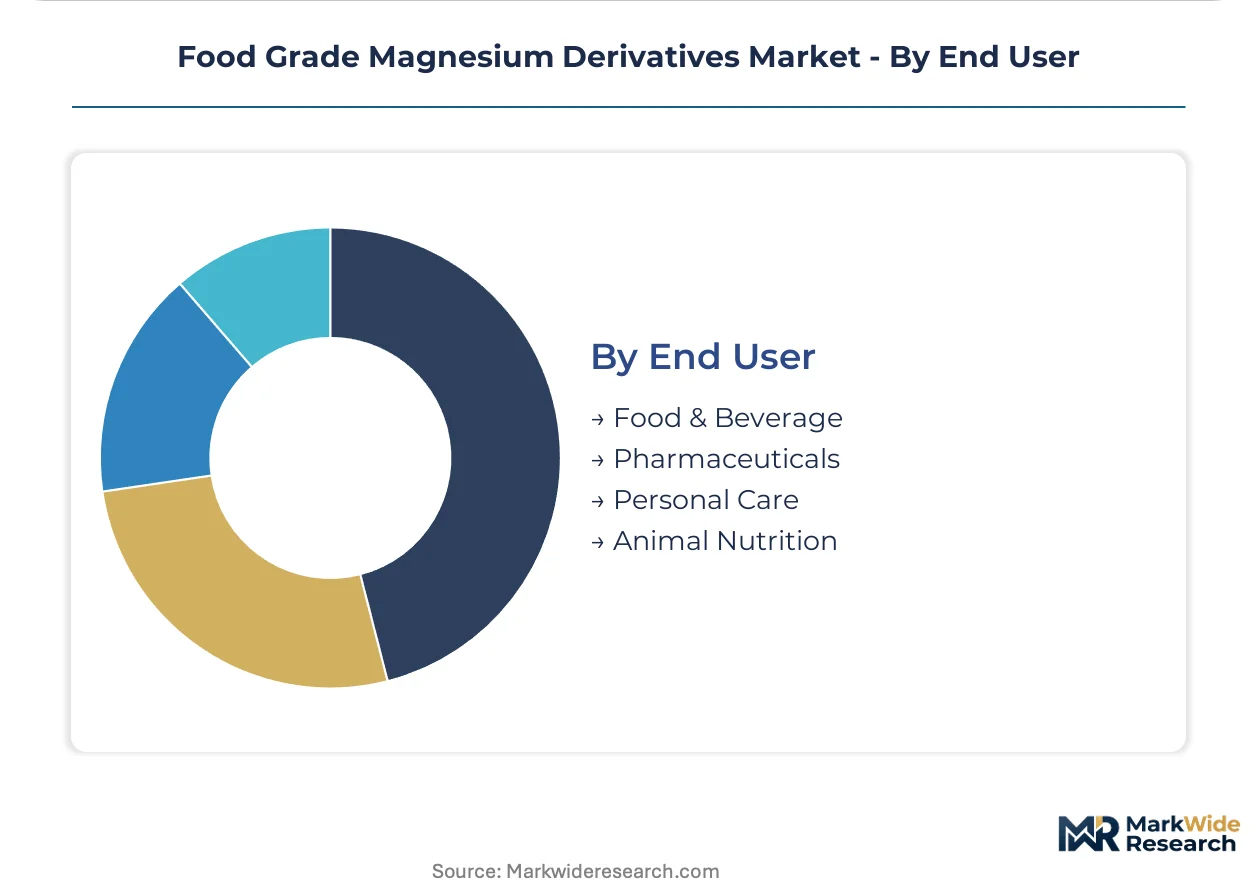
End User:
Margin profiles vary significantly across end-user segments, reflecting differing purity requirements and regulatory burdens.
- Food & Beverage:This segment utilizes magnesium derivatives across a broad spectrum for pH regulation, anti-caking, and mineral fortification. Demand expands with the global growth of processed foods and functional beverages, particularly in Asia-Pacific.
- Pharmaceuticals:This sector demands ultra-high purity magnesium salts for active pharmaceutical ingredients and excipients. Demand is driven by stringent regulatory requirements from agencies like the US FDA and Europe's EMA.
- Personal Care:Magnesium derivatives find application in cosmetics and topical products for skin health and formulation stability.
- Animal Nutrition:Incorporated into feed formulations to support animal health, bone density, and metabolic functions.
Food & Beverage drives the primary volume; Pharmaceuticals command premium pricing due to purity demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global trade routes, facilitated by major international shipping ports, underpin the widespread distribution of food grade magnesium derivatives. These logistics networks enable manufacturers to access diverse raw material sources and serve growing end-user markets. Efficient supply chains are crucial for delivering specialized ingredients to food and nutraceutical producers worldwide.
United States
The United States market sees strong demand from the nutraceutical sector, particularly for high-bioavailability magnesium forms in dietary supplements. US FDA regulations rigorously define purity criteria and permissible additive levels for food grade ingredients. Major food and beverage manufacturing centers, such as those in the Midwest, consistently integrate these derivatives into new product formulations.
China
China's expanding food processing and dietary supplement industries represent a significant demand driver for food grade magnesium derivatives. The State Administration for Market Regulation (SAMR) actively enforces stringent GB standards for food additives, impacting both domestic and international suppliers. Industrial clusters in the Yangtze River Delta region concentrate both production capacity and a substantial portion of end-user manufacturers.
Germany
Germany demonstrates robust demand for food grade magnesium derivatives within its sophisticated functional food and nutraceutical sectors. The European Food Safety Authority (EFSA) plays a central role in setting purity and safety standards that manufacturers must meet for market access. Chemical and food ingredient production facilities in North Rhine-Westphalia contribute significantly to both supply and application development.
India
India's burgeoning processed food market and rising consumer health awareness drive demand for mineral fortification in various products. The Food Safety and Standards Authority of India (FSSAI) establishes comprehensive regulations for food additives and dietary supplements. Food manufacturing hubs in states such as Maharashtra and Gujarat are significant consumers of these functional ingredients.
Food Grade Magnesium Derivatives Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the food grade magnesium derivatives supply chain. The market exhibits a tiered structure, with large-scale producers providing commodity grades and specialized firms focusing on high-purity functional ingredients. Strategic archetypes include global chemical conglomerates, regional mineral processors, and niche nutraceutical ingredient suppliers. Dominant competitive moves involve capacity expansion to leverage economies of scale and portfolio diversification into higher-value organic salts.
Within the global market, Germany-based K+S Aktiengesellschaft exemplifies a large-scale producer leveraging extensive mining and processing capabilities for broad market coverage. Compass Minerals, an Inc.-structured company, represents a specialist focusing on high-purity magnesium chloride sourced from natural brines. Grecian Magnesite, a Greece-based entity, occupies a position differentiated by its focus on specific carbonate and oxide grades for specialized food applications. These companies anchor different segments of the market, from bulk supply to targeted ingredient solutions.
| Leading Market Players |
|---|
| OLE Chemical Co., Ltd. |
| Ibar Northeast |
| Grecian Magnesite |
| K+S Aktiengesellschaft |
| NikoMag |
| Compass Minerals |
| Sinwon Industrial Co., Ltd. |
| Hawkins |
| Martin Marietta Magnesia Specialties |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta's concentrated production capacity for magnesium oxide directly influences global pricing stability for commodity grades. Logistical efficiencies from this hub dictate cost structures for bulk food additives worldwide.
Pricing Analysis
Pricing stratifies across premium, standard, and economy tiers based on purity and volume. Certification levels, such as Food Chemicals Codex (FCC) compliance, drive significant price differentiation for specialized grades. Energy price volatility, particularly for calcination processes, exerts downward pressure on margins for magnesium oxide producers. Nutraceutical manufacturers show lower price sensitivity for high-bioavailability forms compared to bulk food additive buyers.
Supply Chain Analysis
High-purity magnesium feedstock draws from concentrated sources in China and the United States' Great Salt Lake brines. Production relies heavily on magnesite deposits and natural brines. Geographic concentration creates single-source vulnerability, particularly for specialized grades. Downstream distribution runs through direct procurement relationships with large food and nutraceutical manufacturers, bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food grade magnesium derivatives market presents a fragmentation opportunity. Heightened consumer focus on preventative health and wellness creates distinct niches for specialized, high-bioavailability forms.
For Market Incumbents: Harden core processing aid businesses by investing in energy efficiency for calcination, mitigating energy price volatility. Expand capacity in China to meet regional GB standard compliance, addressing regulatory shifts. Leverage extensive mining assets for backward integration, controlling raw material costs against emerging entrants. Diversify product portfolios into organic magnesium salts through R&D partnerships.
For New Entrants and Emerging Players: Southeast Asian food and supplement markets represent significant underpenetration. Target these regions with novel, highly bioavailable magnesium compounds for functional beverages. Focus on specific applications like infant formula, where specialized nutrition commands premium pricing. A direct-to-manufacturer sales approach can establish early market share.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized ingredient firms with strong R&D in chelated magnesium forms. Long-term viability rests with companies capable of consistent, certified quality across multiple regulatory regimes. Acquisition targets should include mid-sized manufacturers with proprietary purification processes or unique raw material access. The signal to watch is accelerating adoption of novel organic forms in clinical nutrition.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases supply of commodity magnesium oxide for global food processing. |
| Portfolio Diversification | Introduces high-value organic magnesium salts for nutraceutical applications. |
| Regulatory Compliance Investment | Ensures market access in China under stricter GB standards for food additives. |
| Direct Sourcing Agreements | Secures supply and quality control for large food and beverage manufacturers. |
| Bioavailability R&D Partnership | Develops advanced chelated magnesium forms for superior absorption. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association reports, and company annual statements. Interviews with R&D directors, procurement specialists, regulatory affairs managers, and quality assurance leads across the value chain informed the analysis. This approach ensured robust data validation and stakeholder perspective integration. Bottom-up and top-down triangulation verified market size and growth projections.
Forecast inputs considered historical market data, production capacities, and end-user demand trends across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, form, and end-user industry. CAGRs were derived from a weighted average of historical growth and anticipated future drivers. Key inputs included nutraceutical consumption rates and food additive regulatory changes.
Macroeconomic conditions sit as an overlay; deviation in global energy prices or raw material availability would shift the trajectory of the market. Forecasts reflect assumptions regarding regulatory stability and consumer health trends. Cross-checking against national food safety authority reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Bread Emulsifier Market
Food Additives and Ingredients
Cook-Up Starch Market
Food Additives and Ingredients
Glandular Ingredients Market
Food Additives and Ingredients
Food Grade Distilled Monoglyceride Market
Food Additives and Ingredients
Europe Food Enzymes Market
Food Additives and Ingredients
Cream of Tartar Market
Food Additives and Ingredients
China Food Emulsifiers Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Global Fatty Acids Market
Food Additives and Ingredients
Octadecanedioic Acid (ODDA) Market
Food Additives and Ingredients
Dairy Starter Culture Market
Food Additives and Ingredients
Natural Solubilizers Market
Food Additives and Ingredients
Food Processing Ingredients Market
Food Additives and Ingredients
Flavor Encapsulation Market
Food Additives and Ingredients
Global Integrated Food Ingredient Market