
 Food Aroma Market | 2026-2036
Food Aroma Market Size, Share, and Industry Trends Forecast 2026-2036
Food Aroma Market Foresight
Flavor-as-a-service contracts, where suppliers retain ownership of proprietary formulations and charge subscription-style access fees, is shifting how food and beverage manufacturers budget for aroma inputs. Givaudan leverages its captive biotechnology pipeline to lock in long-term supply agreements with multinational beverage brands. Symrise anchors its competitive position through deep backward integration into vanilla and citrus cultivation across Madagascar and Brazil. Kerry Group differentiates by bundling aroma systems with integrated taste-modulation platforms, reducing client formulation cycle times.
Food aromas comprise volatile organic compounds, essential oils, and synthetic molecules engineered to deliver specific olfactory profiles at concentrations measured in parts per million within finished goods. These formulations mask off-notes, enhance perceived sweetness, and extend flavor persistence across shelf-stable and refrigerated applications. Natural flavors and essential oils command premium positioning as clean-label momentum redirects procurement budgets away from petroleum-derived synthetics. Spray-dry and emulsion forms are capturing disproportionate growth in bakery and confectionery applications where thermal stability and controlled release determine performance. Synthetic flavors still dominate volume in snack applications where cost thresholds and heat resistance requirements limit natural alternatives.
EFSA evaluates novel aroma substances under evolving food additive protocols, while REACH compliance obligations constrain which synthetic precursors European flavor houses may source. The EU Green Deal's chemical sustainability targets are forcing reformulation investments that favor bio-fermented and upcycled aroma feedstocks. FDA GRAS self-determination pathways in the United States create divergent market access timelines compared with EMA-mandated pre-market authorizations. Stakeholders must monitor regulatory divergence between Brussels and Washington to anticipate which aroma platforms will face accelerated compliance costs versus preferential market entry.
Market Dynamics
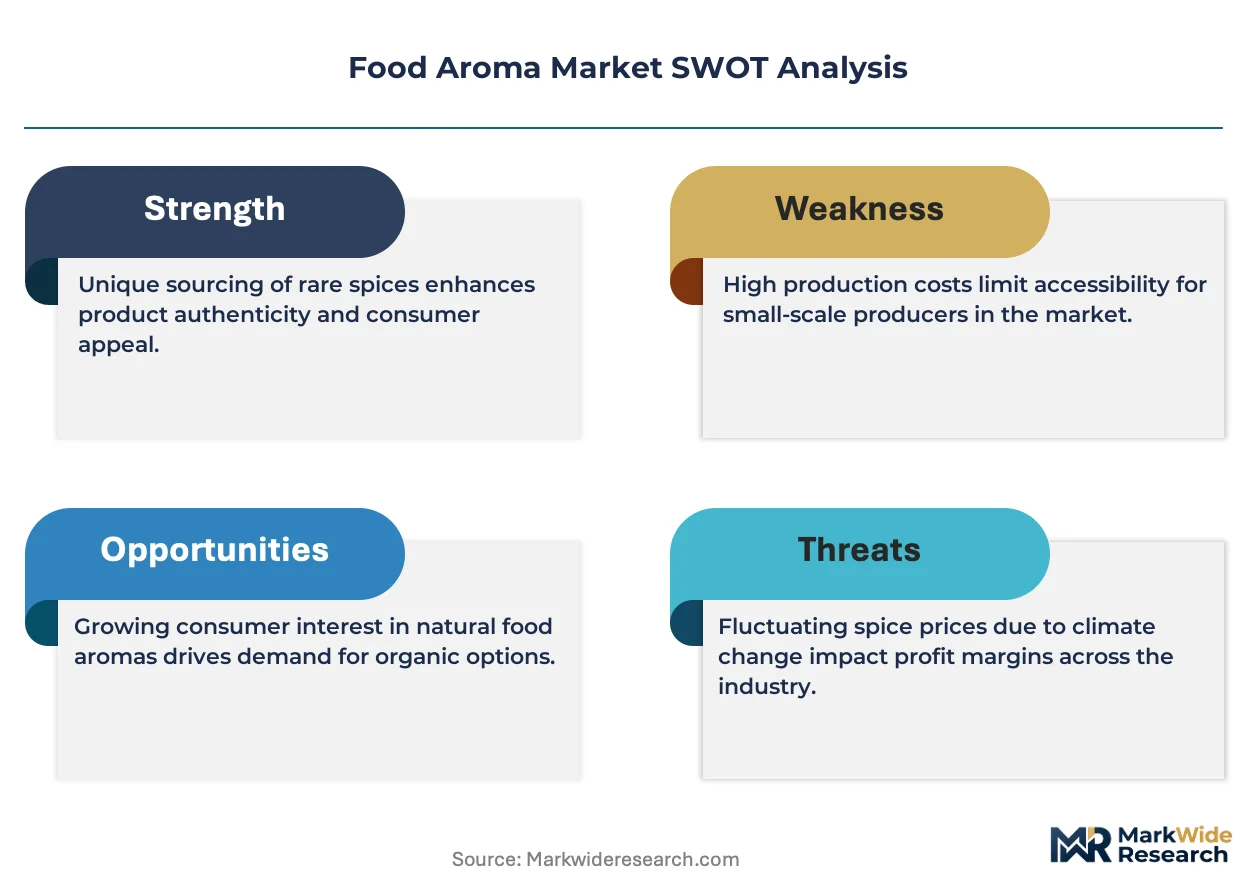
Clean-label mandates from Brussels are forcing beverage and bakery manufacturers to abandon petroleum-derived synthetics, triggering a supply-side scramble for bio-fermented alternatives that retain thermal stability and cost parity.
Growth Catalysts
- EU Green Deal chemical sustainability targets:The framework mandates phase-down of fossil-based feedstocks, compelling flavor houses to accelerate bio-fermentation capacity investments across the continent.
- Co-located R&D clusters in Germany:Flavor houses and beverage producers are converging innovation facilities near ingredient hubs, compressing formulation cycle times and tightening supplier-producer collaboration.
- Spray-dry encapsulation advances:Thermal stability improvements in bakery and confectionery applications are unlocking natural aroma adoption where heat resistance previously blocked entry.
Market Restraints
- Vanilla and citrus cultivation concentration:Symrise and competitors face geographic lock-in to Madagascar and Brazil for key natural feedstocks, exposing supply chains to climate and political volatility.
- REACH compliance cost escalation:ECHA registration requirements for novel synthetic precursors are extending development timelines and elevating R&D burn rates for European flavor houses.
- Natural-to-synthetic cost gap:Essential oil and bio-fermented inputs carry 40-80% premiums over petroleum-derived equivalents, constraining penetration in price-sensitive snack applications.
Strategic Opportunities
- Upcycled feedstock valorization:EU Green Deal circular economy incentives are creating first-mover advantages for aroma producers converting agricultural side-streams into compliant volatile compounds.
- Flavor-as-a-service subscription models:Suppliers retaining proprietary formulation ownership can capture recurring revenue streams while locking multinational beverage brands into long-term technical dependencies.
- Integrated taste-modulation bundling:Aroma-taste platform combinations that reduce client reformulation cycles represent white space distinct from commodity ingredient supply.
Industry Challenges
- Biotechnology talent scarcity:Strain engineering and metabolic pathway optimization expertise remains concentrated among a handful of specialized research institutions, constraining in-house capability builds.
- GRAS-EMA regulatory divergence:FDA self-determination pathways and EMA pre-market authorization timelines create parallel compliance burdens for aroma substances seeking transatlantic market access.
- Legacy formulation retrofit complexity:Shelf-stable and refrigerated product lines require complete sensory revalidation when substituting natural for synthetic aroma systems, extending go-to-market intervals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Aroma Market |
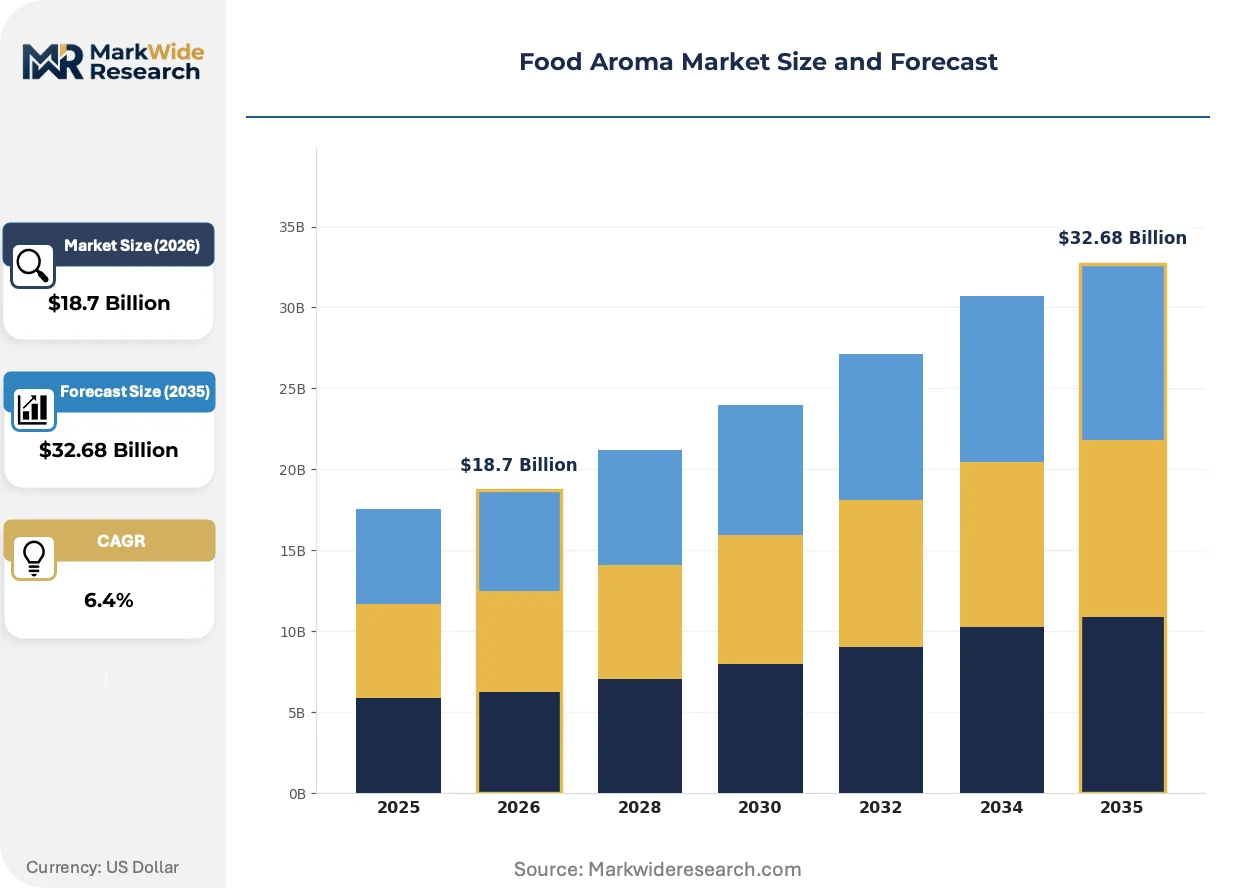
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Synthetic Flavors, Essential Oils, Oleoresins, Extracts Application: Beverages, Confectionery, Bakery, Dairy Products, Snacks End User: Food & Beverage Manufacturers, Flavor Houses, Restaurants, Food Processors Form: Liquid, Powder, Spray Dry, Emulsion, Gel |
| Companies Covered | Symrise, Kerry Group, Givaudan, MANE, Takasago International, DSM-Firmenich, Sensient Technologies, Archer Daniels Midland, International Flavors & Fragrances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Aroma Market Shifts & Advancements
Biotechnology pipelines and regulatory chemistry frameworks are converging to redefine how volatile compounds are sourced, validated, and commercialized across food and beverage value chains.
Precision fermentation platforms are automating the production of rare terpenes and esters previously extracted from scarce botanicals. Givaudan and specialized biotech suppliers are deploying these systems to secure captive supply agreements with multinational beverage brands. The technology is automating cost curve compression for natural-identical molecules that previously commanded extreme premiums.
REACH authorization protocols under ECHA jurisdiction are tightening precursor sourcing restrictions for European flavor houses. The regulatory friction is redirecting R&D investment toward bio-fermented and enzymatic synthesis pathways that bypass petroleum-derived intermediates. German and Swiss formulation facilities are experiencing the most acute compliance cost pressures as registration dossier requirements expand.
Clean-label procurement mandates are consolidating buyer power among multinational beverage and bakery manufacturers with dedicated sustainability compliance teams. Traditional distributor networks are losing share to direct technical partnerships where aroma suppliers embed staff within client innovation centers. Germany exhibits the most pronounced channel compression as flavor houses and producers co-locate R&D functions to accelerate reformulation timelines.
Food Aroma Market Segmentation
Aroma systems serve either as standalone functional ingredients or embedded within integrated taste-modulation platforms. Procurement patterns diverge sharply between these integration modes, with embedded systems commanding longer development cycles but higher switching costs.
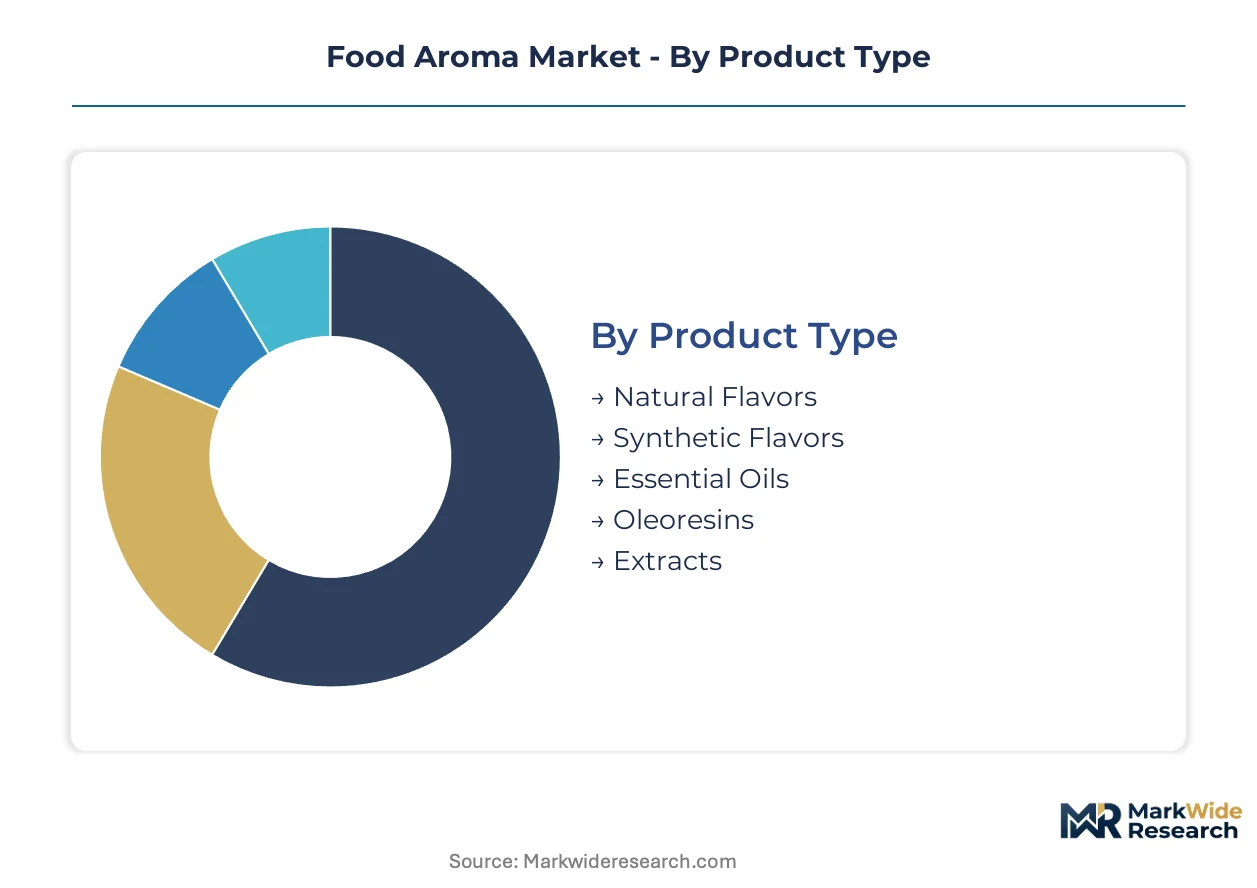
Product Type:
Standalone natural aroma ingredients compete against petroleum-derived synthetics, while embedded biotechnology platforms lock clients into proprietary supply relationships.
- Natural Flavors:Bio-fermented and botanical-derived volatile compounds engineered to replicate specific olfactory profiles. Beverage manufacturers in Germany are concentrating procurement budgets here as EU Green Deal timelines force abandonment of fossil-based feedstocks. Clean-label mandates from Brussels accelerate reformulation investments despite 40-80% cost premiums over synthetic equivalents.
- Synthetic Flavors:Petroleum-derived molecules offering thermal stability and cost parity in heat-intensive applications. Snack manufacturers retain these formulations where REACH compliance costs and natural-to-synthetic price gaps block substitution. ECHA registration requirements for novel precursors extend development timelines and elevate R&D burn rates.
- Essential Oils:Distilled botanical extracts capturing complete terpene profiles from source materials.
- Oleoresins:Solvent-extracted concentrated aroma fractions with extended shelf stability.
- Extracts:Water or alcohol-based infusions preserving volatile compound complexity.
Synthetic flavors lead volumes today; natural flavors are gaining share fastest.
Application:
Cost tier stratification separates premium-positioned applications with reformulation flexibility from price-sensitive categories where synthetic retention persists.
- Beverages:Clean-label procurement mandates from multinational manufacturers with dedicated sustainability compliance teams. Co-located R&D clusters in Germany compress formulation cycle times as flavor houses embed technical staff within client innovation centers. Thermal stability requirements are less stringent than bakery applications, enabling broader natural adoption.
- Confectionery:Spray-dry encapsulation advances unlock natural aroma penetration where heat resistance previously blocked entry. Controlled-release requirements demand sophisticated emulsion systems that mask off-notes and extend flavor persistence across shelf-stable distribution.
- Bakery:Extreme thermal stress during baking limits natural alternatives in mass-market applications.
- Dairy Products:Refrigerated distribution allows broader natural formulation acceptance with shorter shelf-life constraints.
- Snacks:Cost thresholds and high-temperature processing sustain synthetic dominance despite clean-label pressure elsewhere.
Snacks lead volumes today; beverages are climbing the fastest.
End User:
Customer type determines whether aroma procurement flows through distributor networks or direct technical partnerships with embedded supplier staff.
- Food & Beverage Manufacturers:Consolidating buyer power through dedicated sustainability compliance teams that bypass traditional distribution channels. Direct technical partnerships now dominate as suppliers embed formulation scientists within client R&D facilities. Germany exhibits the most pronounced channel compression.
- Flavor Houses:Acting as both suppliers and customers depending on captive biotechnology capabilities and backward integration depth.
- Restaurants:Fragmented demand concentrated in premium positioning and limited-batch applications.
- Food Processors:Volume-focused procurement with limited technical integration and higher price sensitivity.
Food and beverage manufacturers lead volumes today; flavor houses are expanding most quickly through captive platform investments.
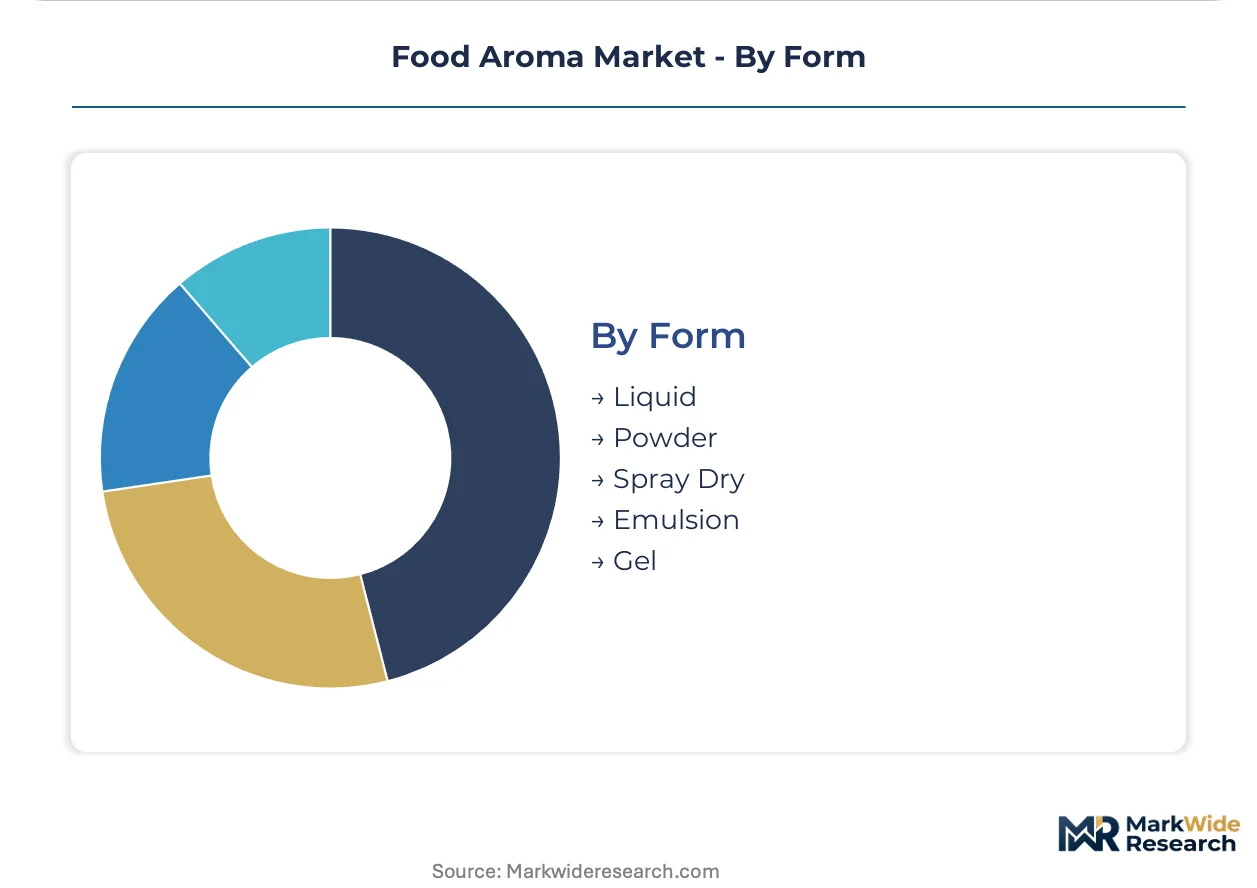
Form:
Supply concentration for thermal-stability technologies creates margin differentiation between basic liquid delivery and advanced encapsulation systems.
- Liquid:Standard solvent-based delivery for ambient-stable applications with minimal processing stress.
- Powder:Simple drying processes for dry-mix applications with moderate shelf-life requirements.
- Spray Dry:Encapsulation technology protecting volatile compounds through high-temperature processing and enabling controlled release. Advances here are unlocking natural aroma adoption in bakery and confectionery where heat resistance previously constrained formulation options.
- Emulsion:Oil-in-water systems delivering precise droplet size distribution for mouthfeel and stability optimization. Integrated taste-modulation platforms bundle these with aroma systems to reduce client reformulation cycle times.
- Gel:Structured delivery matrices for extended-release applications in confectionery and specialty products.
Liquid forms lead volumes today; spray dry and emulsion systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates more flavor house R&D investment than any other European country, while the United States maintains broader application diversity across beverage and snack segments. Regulatory divergence between Brussels and Washington shapes divergent procurement timelines.
Germany
Beverage manufacturers and flavor houses are co-locating innovation facilities near ingredient hubs in Bavaria and North Rhine-Westphalia. The EU Green Deal mandates phase-down of fossil-based feedstocks, compelling accelerated bio-fermentation capacity investments. Cologne and Hamburg host the densest clusters of technical partnerships where suppliers embed staff within client R&D centers.
United States
Snack manufacturers retain synthetic formulations where cost thresholds block natural substitution, while beverage brands drive clean-label procurement. FDA GRAS self-determination pathways create faster market access timelines than European pre-market authorizations. Chicago and New Jersey concentration reflects legacy flavor house presence and proximity to major food processors.
France
Luxury confectionery and bakery applications sustain premium positioning for natural essential oils despite higher input costs. EFSA evaluates novel aroma substances under evolving food additive protocols that extend development timelines. Paris and Lyon anchor formulation expertise clusters serving export-oriented producers.
Switzerland
Specialized biotechnology talent concentrates around Zurich and Basel, supporting strain engineering capabilities for rare terpene production. REACH compliance obligations constrain synthetic precursor sourcing, redirecting investment toward enzymatic synthesis. Swissmedic alignment with EMA procedures ensures regulatory coherence with EU market requirements.
Brazil
Citrus cultivation concentration in São Paulo and Minas Gerais supplies key natural feedstocks for global flavor houses. Climate volatility and agricultural policy shifts expose supply chains to disruption risk. ANVISA regulatory frameworks govern food additive approvals with timelines diverging from both FDA and EMA pathways.
Food Aroma Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated biotechnology platforms capturing premium positioning while commodity distributors serve price-sensitive applications. Market structure tilts toward consolidation among firms with captive cultivation assets or precision fermentation capabilities. Three archetypes dominate: backward-integrated agricultural operators, biotechnology pipeline owners, and integrated taste-modulation platform bundlers. Capacity expansion in bio-fermentation and strategic partnerships for upcycled feedstock access represent the dominant competitive moves.
Among biotechnology-anchored specialists, Givaudan and DSM-Firmenich exemplify the platform-ownership archetype through captive strain engineering capabilities. Symrise occupies a distinct position through upstream control over vanilla and citrus cultivation in Madagascar and Brazil. Kerry Group represents the integrated-solutions tier, bundling aroma systems with adjacent taste technologies to compress client reformulation cycles.
| Leading Market Players |
|---|
| Symrise |
| Kerry Group |
| Givaudan |
| MANE |
| Takasago International |
| DSM-Firmenich |
| Sensient Technologies |
| Archer Daniels Midland |
| International Flavors & Fragrances |
| Others |
Supply & Pricing Matrix
Vanilla and citrus cultivation costs in Madagascar and Brazil cascade through three pricing tiers downstream, with EU Green Deal compliance premiums separating premium natural extracts from standard synthetics and economy petroleum-derived alternatives.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for bio-fermented aroma systems as Givaudan and DSM-Firmenich expand precision fermentation facilities. Three-tier pricing structure across premium natural-identical molecules, standard botanical extracts, and economy synthetic compounds governs procurement. Price differentiation hinges on REACH certification status and volume scale, with snack manufacturers exhibiting acute sensitivity while beverage brands absorb premiums for clean-label positioning. Cost compression in the synthetic tier intensifies because petroleum feedstock volatility and ECHA registration burdens erode margins.
Supply Chain Analysis
Returns of spent citrus biomass to extraction facilities in São Paulo and Minas Gerais anchor circular feedstock flows for upcycled aroma production. Supply concentration spans Madagascar for vanilla, Brazil for citrus terpenes, and Germany for biotechnology platforms. Raw material dependencies encompass vanilla orchids, citrus peel stock, and engineered yeast strains for precision fermentation. Single-source vulnerability in Madagascar exposes global natural vanilla supply to cyclone disruption. Distribution runs through direct technical partnerships where flavor houses embed staff within beverage manufacturer R&D centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Food Aroma Market functions as a geographic-arbitrage play between EU Green Deal compliance costs in Europe and FDA GRAS self-determination pathways in the United States, with regulatory divergence creating 12-18 month market access gaps.
For Market Incumbents: To counter biotechnology talent scarcity, Symrise and Kerry Group should deepen backward integration into captive cultivation assets while accelerating co-location of R&D facilities near client innovation clusters in Bavaria and North Rhine-Westphalia. Certification investment in REACH-compliant bio-fermentation capacity represents the critical defensive lever against emerging precision fermentation specialists. For New Entrants and Emerging Players: Precision fermentation platforms for rare terpenes offer entry white space as established players face legacy retrofit burdens. Target upcycled feedstock valorization in agricultural side-streams where EU circular economy incentives reduce input cost disadvantages. A flavor-as-a-service subscription model bypasses capital-intensive formulation asset builds while locking beverage brands into technical dependencies. For Investors and Strategic Acquirers: Consolidation pressure builds where backward-integrated agricultural operators lack biotechnology pipelines to meet EU chemical sustainability mandates. Long-term viability favors firms with dual capabilities in cultivation control and strain engineering. Acquisition targets should display captive supply agreements with multinational beverage brands. Monitor ECHA registration timeline extensions for novel synthetic precursors as inflection signals for bio-fermentation valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Assets | Madagascar vanilla orchid control secures supply against climate volatility. |
| Precision Fermentation Capacity Expansion | German biotechnology hubs compress cost curves for natural-identical molecules. |
| Flavor-as-a-Service Platform Launch | Subscription revenue models lock multinational beverage brands into dependencies. |
| Upcycled Feedstock Partnership | EU Green Deal circular economy incentives valorize agricultural side-streams. |
| Co-located R&D Facility Investment | Bavaria and North Rhine-Westphalia clusters compress client reformulation cycles. |
Research Methodology
Coverage spans Germany, the United States, France, Switzerland, and Brazil, with primary inputs from each market cluster. The approach combines structured interviews with flavor house R&D directors, beverage manufacturer procurement leads, biotechnology platform engineers, and regulatory affairs specialists with secondary validation through ECHA registration databases, FDA GRAS notices, EU Green Deal policy documents, and customs trade flow records. Bottom-up demand modeling triangulates against top-down supply capacity assessments.
Granularity-level framing applies country-specific regulatory pathway modeling, application-level thermal stability requirements, and end-user procurement mode differentiation. Segmentation dimensions encompass product type, application, end user, and form across the projection horizon. CAGRs derive from trend extrapolation of bio-fermentation cost compression curves and synthetic precursor compliance cost escalation. Industry-specific inputs include REACH authorization timeline probabilities and spray-dry encapsulation technology adoption rates.
The model holds under stable EU Green Deal implementation timelines; deviation in EFSA novel food additive protocols or Madagascar agricultural policy would shift natural aroma supply projections. Practitioners should monitor ECHA substance evaluation backlog and Brazilian citrus harvest forecasts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Hops Essential Oil Market
Flavorings and Food Additives
Chokeberry Extract Market
Flavorings and Food Additives
Feed Flavors, Sweeteners and Natural Enhancers Market
Flavorings and Food Additives
Pine Bark Extract Market
Flavorings and Food Additives
Natural Food Colors and Flavors Market
Flavorings and Food Additives
Food Texturizers Market
Flavorings and Food Additives
Natural Flavor Extract Market
Flavorings and Food Additives
FTNF Flavors Market
Flavorings and Food Additives
Middle East Food Premix Market
Flavorings and Food Additives
Flavor Emulsions Market
Flavorings and Food Additives
Canola Lecithin Market
Flavorings and Food Additives
North America Food Flavor Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
Global Sterols Market
Flavorings and Food Additives
Cholic Acid Market
Flavorings and Food Additives
Flavoring Agents Market