
 Coloring Foodstuffs Market | 2026-2036
Coloring Foodstuffs Market Size, Share, and Industry Trends Forecast 2026-2036
Coloring Foodstuffs Market Outlook
REACH compliance is realigning the cost-of-entry calculus for European coloring foodstuff suppliers, forcing reformulation investments that favor firms with captive extraction capabilities. Sensient Technologies leverages its vertical integration from botanical sourcing to finished color systems, sustaining margin control across volatile raw material cycles. Chr. Hansen Holding A/S dominates fermentation-derived carotenoid production, while GNT Group anchors its position through proprietary spirulina extraction patents that block commodity replication.
Coloring foodstuffs comprise water-soluble or oil-dispersible preparations derived from fruits, vegetables, algae, or minerals, standardized to defined color intensity measured via spectrophotometric absorbance at specific wavelengths, primarily functioning to restore or enhance visual appeal in processed foods. Natural Colors command the widest application breadth across Beverages and Dairy Products, though margin pools concentrate in customized Color Additives for confectionery where batch consistency requirements exclude generic suppliers. Powder forms lead manufacturing economics at scale, while Liquid formats capture premium positioning in cold-process Beverage lines where reconstitution speed determines throughput.
EFSA novel food assessments, EU Green Deal sustainability disclosures, and FDA color additive petitions collectively shape product development pipelines and cross-border market access timelines for suppliers serving dual jurisdictions. The EU's F-Gas Regulation indirectly pressures synthetic dye production energy footprints, while India's FSSAI import clearance protocols create procedural friction for botanical concentrate entrants. Stakeholders must monitor regulatory divergence between jurisdictions where mutual recognition agreements fail to cover emerging fermentation-derived colorants.
Market Dynamics
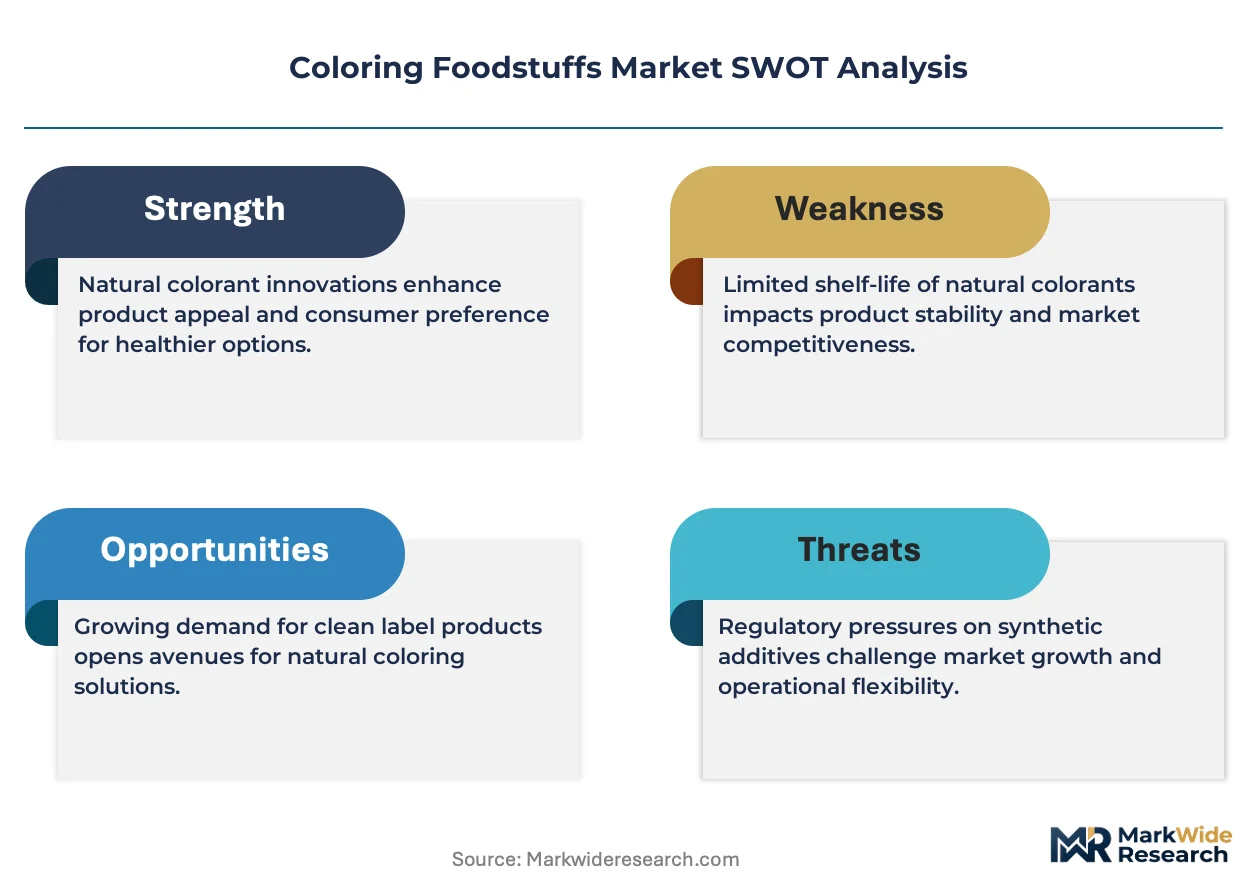
EFSA's novel food assessments and the EU's clean-label directives are tightening synthetic dye permissions, forcing beverage producers across Germany and France to expand anthocyanin-based concentrate procurement and reshaping supplier selection criteria around reformulation timelines.
Growth Catalysts
- Clean-label mandates:EFSA novel food assessments and EU directives are accelerating synthetic dye substitution across Western European premium dairy and bakery segments.
- Fermentation-derived carotenoids:Advanced bioprocessing technologies are expanding production scalability for microbial colorants in beverage applications.
- Spirulina extraction patents:Proprietary extraction methods are securing supply chain control for algae-based blue colorants in confectionery.
Market Restraints
- Raw material volatility:Botanical sourcing cycles for anthocyanin concentrates create margin pressure during adverse harvest conditions.
- Regulatory friction:India's FSSAI import clearance protocols impose procedural delays on botanical concentrate market entry.
- Technical color stability:Anthocyanin pH sensitivity limits application breadth in neutral-pH dairy systems.
Strategic Opportunities
- Cold-process beverage lines:Liquid format color systems are capturing premium positioning where reconstitution speed determines throughput.
- EU Green Deal disclosures:Sustainability certification requirements are creating first-mover advantages for suppliers with verified carbon footprints.
- Fermentation technology convergence:Precision fermentation combined with metabolic engineering is opening novel pigment biosynthesis pathways.
Industry Challenges
- Spectrophotometric standardization:Batch-to-batch absorbance consistency requires skilled quality control personnel that suppliers struggle to retain.
- Dual-jurisdiction compliance:EFSA and FDA petition timelines create product development pipeline bottlenecks for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coloring Foodstuffs Market |
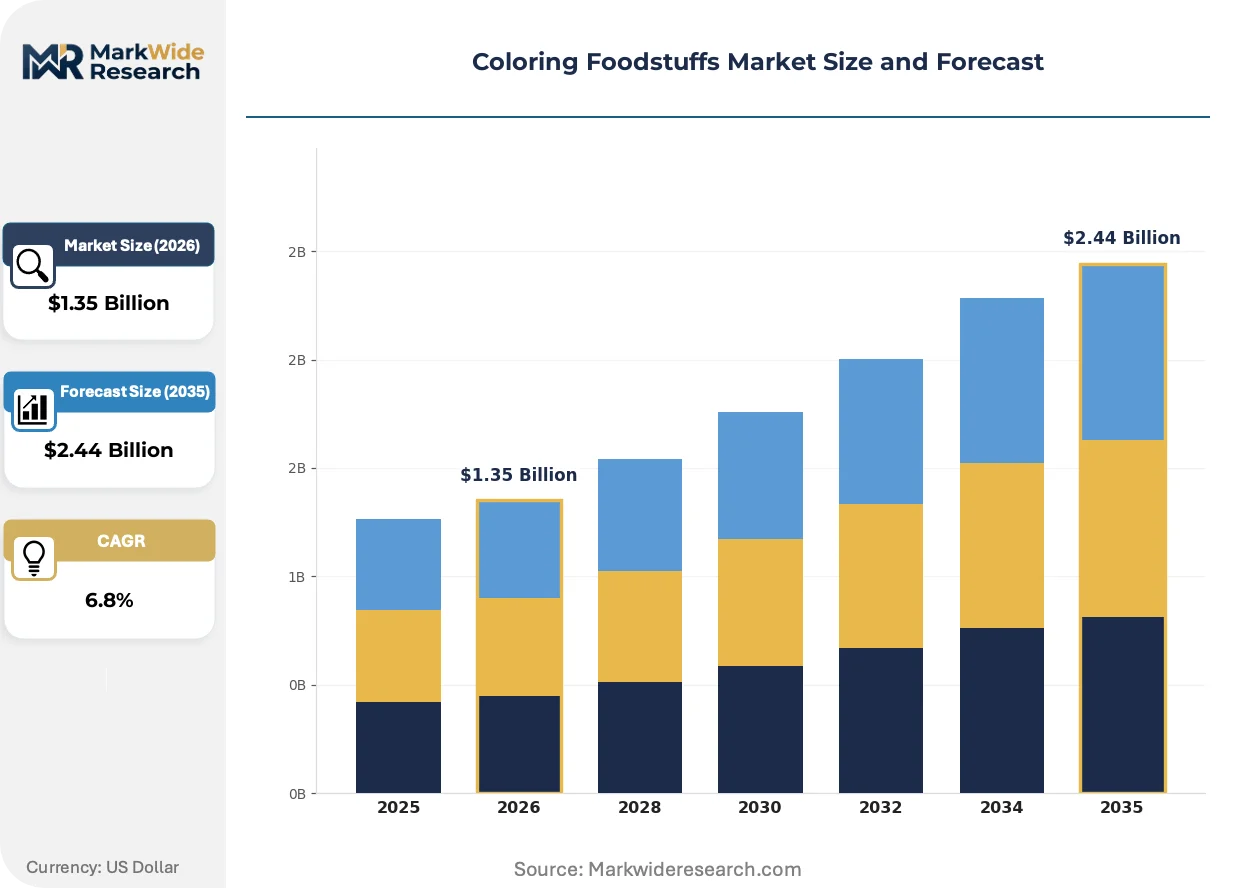
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.44 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colors, Synthetic Dyes, Color Additives, Food Colorants Application: Beverages, Confectionery, Dairy Products, Bakery Form: Liquid, Powder, Gel, Paste End User: Food Manufacturers, Beverage Producers, Restaurants, Home Cooks |
| Companies Covered | Sensient Technologies Corporation, DSM, Cargill Incorporated, GNT Group, Chr. Hansen Holding A/S, Dohler Group, BASF SE, Archer Daniels Midland, Givaudan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coloring Foodstuffs Market Strategic Shifts
Reformulation timelines now determine supplier selection in premium segments, compressing development cycles and favoring integrated extraction-to-color-system capabilities over commodity concentrate trading.
Supercritical CO2 extraction technology is consolidating control over carotenoid and chlorophyll recovery yields. Beverage manufacturers in Germany and France are adopting these systems at accelerated pace to secure anthocyanin supply. This consolidation is compressing the supplier base by disqualifying traders lacking captive extraction infrastructure.
REACH compliance is realigning cost-of-entry calculus for European coloring foodstuff suppliers. The regulation forces reformulation investments that favor firms with in-house extraction capabilities over import-dependent competitors. Powder format manufacturing economics are most affected as energy-intensive drying operations face heightened scrutiny.
Buyer concentration in Western European premium dairy is compressing switching cycles and unbundling after-sales technical support from color supply contracts. Large dairy processors now demand dedicated formulation chemists embedded at supplier facilities. This pattern is most visible in French and German reformulation programs targeting synthetic dye elimination.
Coloring Foodstuffs Market Segmentation
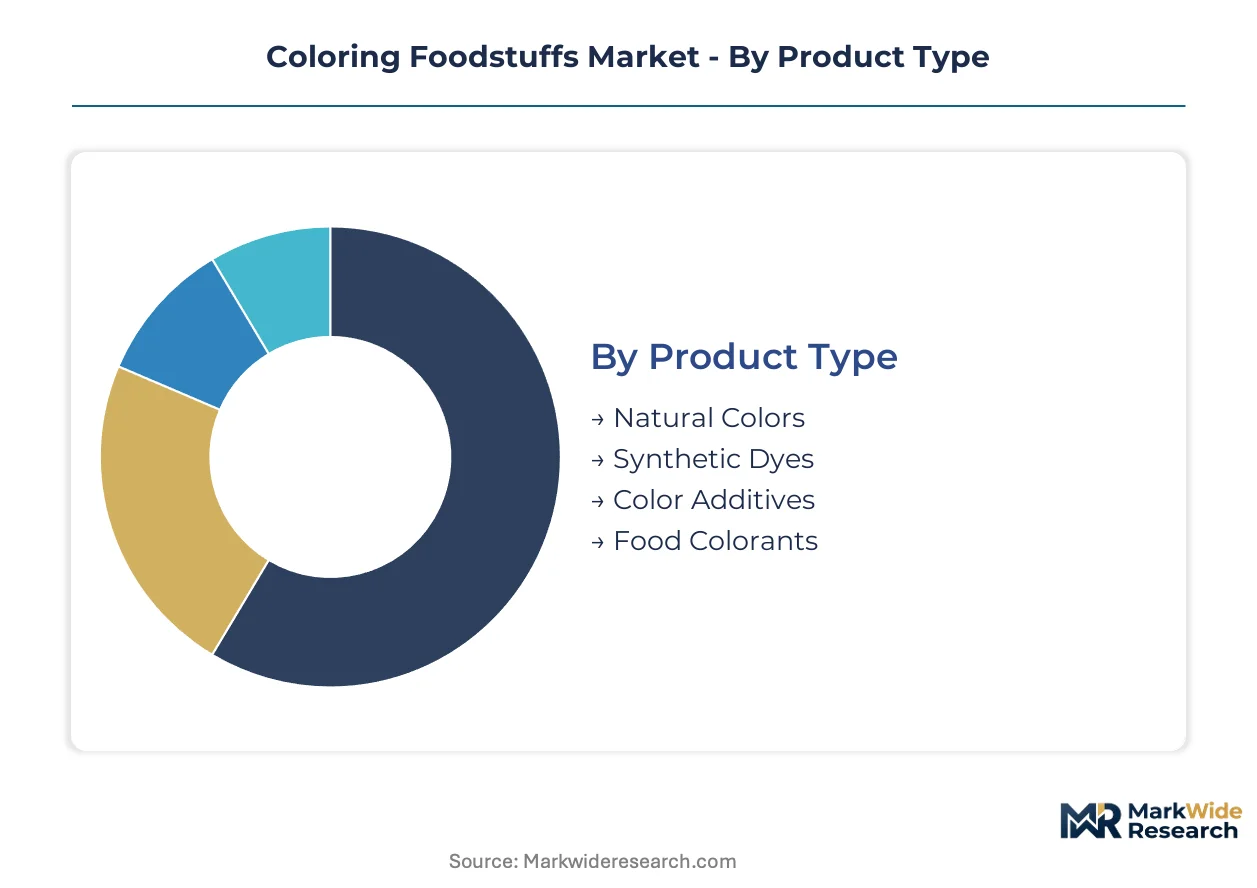
Segmentation in coloring foodstuffs determines procurement economics and technical service requirements. Powder formats dominate manufacturing scale while liquid systems command premiums in cold-process lines. End-user concentration in Western European premium dairy and French bakery segments reshapes supplier selection criteria around reformulation speed.
Product Type:
Integration depth separates standalone color systems from embedded formulation components across extraction and standardization tiers.
- Natural Colors:Water-soluble or oil-dispersible preparations derived from fruits, vegetables, algae, or minerals, standardized to spectrophotometric absorbance specifications. Demand concentrates in German and French beverage reformulation programs where EFSA novel food assessments accelerate anthocyanin concentrate procurement timelines.
- Color Additives:Highly concentrated preparations designed for precise dosing in high-volume manufacturing environments. Margin pools concentrate in confectionery applications where batch consistency requirements exclude generic suppliers and demand dedicated formulation chemists embedded at supplier facilities.
- Synthetic Dyes:Chemically manufactured colorants facing tightening permissions under EU clean-label directives.
- Food Colorants:Broad category spanning both natural and synthetic sources with varying regulatory classifications.
Volume placements concentrate in Natural Colors; the faster expansion belongs to Color Additives.
Application:
Cost tier stratification separates premium reformulation programs from commodity color replacement across end-use categories.
- Beverages:Anthocyanin-based concentrates serve as primary synthetic dye replacements in cold-process lines where reconstitution speed determines throughput. German and French producers are expanding procurement as clean-label directives tighten formulation windows.
- Dairy Products:Premium segments in Western Europe drive demand for pH-stable carotenoid systems. Technical color stability challenges limit anthocyanin deployment in neutral-pH applications, favoring fermentation-derived alternatives with embedded supplier technical support.
- Confectionery:Batch consistency requirements create margin concentration for customized color systems with proprietary spirulina extraction capabilities.
- Bakery:Heat-stable natural color preparations face thermal degradation constraints in oven-process applications.
Revenue concentrates in Beverages; steepest expansion trajectory belongs to Dairy Products.
Form:
Supply concentration favors powder manufacturing economics at scale while liquid formats capture service-embedded premiums.
- Powder:Spray-dried or freeze-dried preparations offering extended shelf stability and reduced transport costs. Manufacturing economics favor high-volume production though energy-intensive drying operations face heightened scrutiny under REACH compliance and EU Green Deal sustainability disclosures.
- Liquid:Ready-to-use dispersions eliminating reconstitution steps in continuous processing lines. Premium positioning in cold-process beverage manufacturing where throughput speed determines operational economics and supplier selection.
- Gel:Viscous preparations targeting precise dosing control in artisanal and small-batch applications.
- Paste:High-solids formats for concentrated color delivery in limited-moisture formulations.
Volume concentrates in Powder; premium expansion belongs to Liquid.
End User:
Customer type stratification separates integrated manufacturer procurement from fragmented foodservice and household demand.
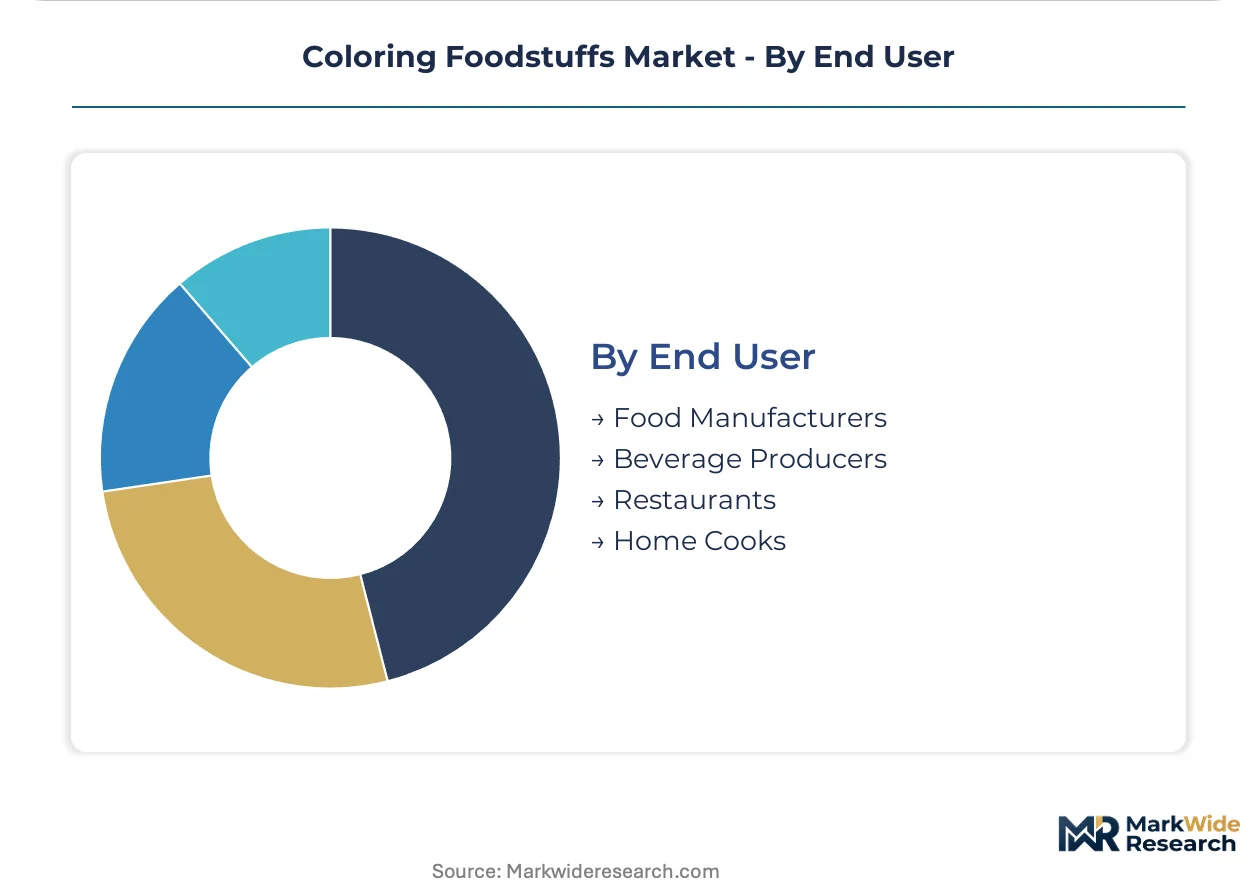
- Food Manufacturers:Large-scale processors with captive formulation capabilities and dedicated supplier quality agreements. Buyer concentration in Western European premium dairy compresses switching cycles and unbundles technical support from supply contracts.
- Beverage Producers:Specialized manufacturing lines requiring rapid reconstitution color systems with verified carbon footprints for EU Green Deal compliance.
- Restaurants:Foodservice operators with intermittent demand patterns and limited technical specification requirements.
- Home Cooks:Retail-packaged color preparations distributed through grocery and specialty channels with minimal formulation support needs.
Procurement volume concentrates in Food Manufacturers; service intensity expansion belongs to Beverage Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bavaria and Baden-Württemberg concentrate extraction infrastructure investment, drawing fermentation technology providers and supercritical CO2 equipment manufacturers into clustered supply networks.
Germany
Beverage reformulation programs in Bavaria and North Rhine-Westphalia drive anthocyanin concentrate procurement. REACH compliance forces captive extraction investments, disqualifying import-dependent traders. The Stuttgart industrial corridor anchors supercritical CO2 equipment deployment for carotenoid recovery.
France
Premium dairy processors in Brittany and Normandy compress supplier switching cycles. ANSM and EFSA novel food assessments accelerate synthetic dye substitution timelines. The Paris-Saclay biocluster concentrates fermentation-derived pigment R&D partnerships.
United States
California and New Jersey beverage manufacturers petition FDA for expanded natural color additive approvals. Clean-label procurement from Midwest dairy processors creates cross-border formulation service demand. The Chicago metropolitan area anchors liquid color system distribution logistics.
India
Maharashtra and Gujarat food manufacturers face FSSAI import clearance friction on botanical concentrates. Domestic spirulina cultivation in Tamil Nadu reduces raw material import dependency. The Hyderabad-Visakhapatnam corridor attracts extraction technology licensing agreements.
China
Yangtze River Delta beverage producers adopt fermentation-derived carotenoids under stricter GB standards enforcement. NMPA alignment with international colorant specifications accelerates multinational supplier entry. The Shandong Peninsula concentrates spray-drying capacity for powder format exports.
Coloring Foodstuffs Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across extraction technology tiers. Market structure consolidates around three archetypes: integrated botanical processors with captive farming, fermentation technology licensors with metabolic engineering capabilities, and formulation service providers embedding technical chemists at customer facilities. Dominant competitive moves include backward integration into raw material sourcing and strategic partnerships securing proprietary extraction patents.
Within the integrated processing tier, Sensient Technologies Corporation and GNT Group exemplify archetypes combining upstream botanical control with finished color system manufacturing. Chr. Hansen Holding A/S occupies a distinct position representing fermentation-derived specialty production. These three entities anchor the competitive landscape through differentiated technology foundations rather than scale-driven commodity positioning.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| DSM |
| Cargill Incorporated |
| GNT Group |
| Chr. Hansen Holding A/S |
| Dohler Group |
| BASF SE |
| Archer Daniels Midland |
| Givaudan |
| Others |
Value Chain & Pricing Dynamics
Anthocyanin concentrate procurement costs cascade through three pricing tiers based on reformulation service bundling, with German beverage producers absorbing premiums for embedded technical support while spot-market traders face margin compression from REACH compliance investments.
Pricing Analysis
Lead-time-driven pricing stratifies across premium, standard, and economy tiers, with cold-process beverage manufacturers paying premiums for 48-hour liquid color system delivery while dairy processors negotiate long-term offtake contracts for pH-stable carotenoid supplies. Price differentiation hinges on spectrophotometric certification grade and EU Green Deal carbon footprint verification, with fermentation-derived pigments commanding brand premiums over botanical extracts. Cost compression in powder formats is intensifying because energy-intensive spray-drying operations face heightened scrutiny under F-Gas Regulation disclosures. Food manufacturers exhibit highest price sensitivity due to buyer concentration, while confectionery specialists prioritize batch consistency over unit cost.
Supply Chain Analysis
Freight cost volatility from spirulina cultivation zones in Tamil Nadu to European extraction facilities is reshaping regional procurement patterns, with Maharashtra and Gujarat processors building domestic drying capacity to circumvent FSSAI clearance friction. Raw material sourcing draws from Indian algae farms, German supercritical CO2 equipment networks, and French fermentation bioclusters. Single-source vulnerability concentrates in proprietary spirulina extraction patents held by integrated processors. Distribution runs through technical service-embedded contracts rather than commodity spot channels, with liquid format logistics anchored in Chicago metropolitan distribution hubs for North American beverage manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-derived carotenoid technologies are displacing legacy botanical extraction methods, compressing supplier selection windows around bioprocessing capabilities and metabolic engineering partnerships.
For Market Incumbents: Acquire captive supercritical CO2 extraction infrastructure to defend margin pools against precision fermentation entrants. Backward integration into spirulina cultivation in Tamil Nadu reduces raw material volatility exposure. Secure embedded formulation chemist contracts with French premium dairy processors before switching cycles lock in competitor relationships. For New Entrants and Emerging Players: Begin with pH-stable color system development for neutral-pH dairy applications where anthocyanin technical limitations exclude incumbent botanical suppliers. Target Indian domestic market penetration leveraging FSSAI procedural familiarity against import-dependent competitors. Pursue licensing partnerships with Paris-Saclay biocluster research programs for fermentation pigment pathways. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap extraction technology licensors in Germany's Stuttgart industrial corridor facing REACH compliance capital constraints. Five-to-ten year viability hinges on metabolic engineering patent portfolios rather than commodity concentrate trading positions. Monitor EFSA novel food assessment timelines as inflection indicators for cross-border market access valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Tamil Nadu spirulina farms reduce FSSAI clearance dependency for Indian processors. |
| Supercritical CO2 Equipment Deployment | Bavarian beverage manufacturers secure anthocyanin supply chain control against traders. |
| Fermentation Technology Licensing | Paris-Saclay biocluster partnerships accelerate microbial pigment biosynthesis pathways. |
| Embedded Technical Service Contracts | Brittany dairy processors unbundle formulation chemist support from commodity supply agreements. |
| Carbon Footprint Certification Investment | EU Green Deal disclosures create first-mover positioning for verified supply chain emissions. |
Study Parameters
Multi-period observation of anthocyanin procurement volumes, fermentation capacity expansions, and EFSA assessment timelines anchored the trend analysis, supplemented by interviews with extraction technology providers, beverage formulation chemists, dairy procurement directors, and FSSAI regulatory consultants. Secondary validation drew from EU novel food application databases, REACH registration filings, Indian customs botanical import records, and SEC disclosures from listed color system manufacturers. Bottom-up segment sizing triangulated against top-down macroeconomic consumption indicators.
Input-output matrices mapped extraction capacity utilization against end-use demand across beverage, dairy, confectionery, and bakery applications over the projection horizon. Segmentation dimensions modeled include product type tier, application heat-stability requirements, format dispersibility specifications, and end-user technical service intensity. CAGRs were derived from regression analysis of historical procurement patterns and regulatory-driven substitution elasticities, incorporating spirulina cultivation yield forecasts and supercritical CO2 equipment deployment pipelines.
Underlying measurement precision varies by segment; fermentation-derived colorants carry tighter precision than botanical concentrates due to standardized bioprocessing controls. Forecasts reflect assumptions about EFSA assessment velocity and FSSAI clearance streamlining that stakeholder operating contexts may revise. Stakeholders should weight assumptions against their own regulatory engagement timelines and captive extraction investment capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Winter Melon Peel Extract Market
Flavorings and Food Additives
1-Decanol Market
Flavorings and Food Additives
Water-Soluble Flavors Market
Flavorings and Food Additives
Farnesol Market
Flavorings and Food Additives
Sea Urchin and Roe Flavor Ingredients Market
Flavorings and Food Additives
France Food Flavor and Enhancer Market
Flavorings and Food Additives
Flavoring Oil Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Chicory Extract Market
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
Culinary Essence Market
Flavorings and Food Additives
Food Aroma Market
Flavorings and Food Additives
Lemon Extract Market
Flavorings and Food Additives
China Food Colorants Market
Flavorings and Food Additives
Flavor Compounds Market
Flavorings and Food Additives
Flavor Masking Agents Market