
 North America Food Flavor Market | 2026-2036
North America Food Flavor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Flavor Market Analytics
Flavor chemist and food scientist shortages across the United States and Canada is unwinding near-term innovation capacity at multiple suppliers. Givaudan SA leverages captive biotechnology labs in California to sustain proprietary natural extraction pipelines. International Flavors & Fragrances Inc. anchors North American beverage partnerships through its applied sensory science centers. Symrise AG competes by dominating high-intensity sweetener-flavor masking combinations for reduced-sugar applications.
Food flavor encompasses volatile and non-volatile compounds engineered to impart taste, aroma, and mouthfeel characteristics to consumable products, typically formulated at parts-per-million to percent-level concentrations using solvent carriers, emulsifiers, and stability enhancers. These formulations serve industrial food production by standardizing sensory profiles across batches, masking off-notes from functional ingredients, and enabling clean-label positioning. Natural extracts command premium positioning among food manufacturers seeking regulatory-compliant label claims, while artificial flavorings retain volume leadership in cost-sensitive snack and confectionery segments. Flavor emulsions represent the fastest-growing product category as beverage brands reformulate for oil-soluble flavor dispersion in reduced-sugar liquid applications.
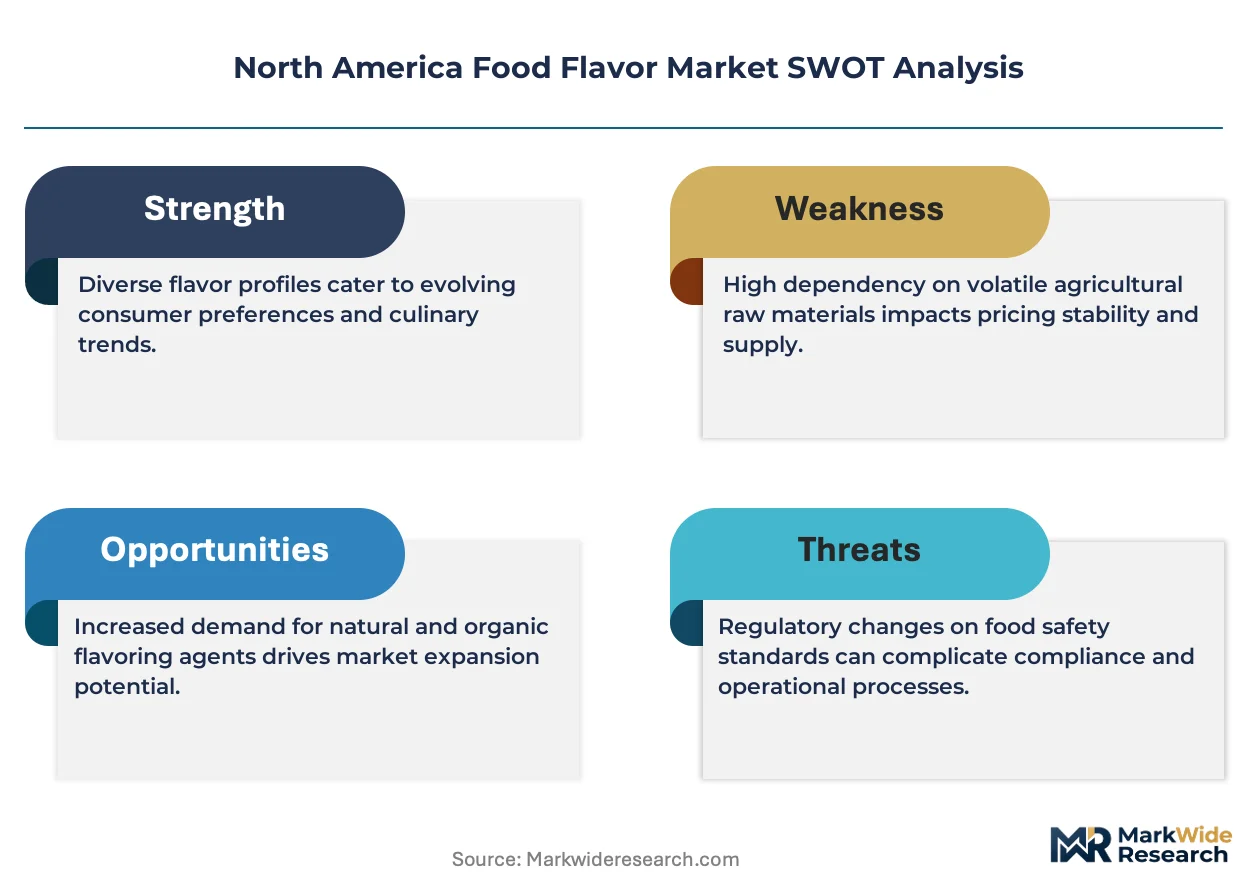
The FDA governs flavor ingredient safety through its food additive and GRAS notification programs, while Health Canada maintains parallel evaluation requirements under its Food and Drug Regulations, creating dual compliance burdens for cross-border suppliers. The USDA Organic seal and Non-GMO Project verification increasingly gate retail access for natural-positioned flavor lines across both countries. Stakeholders must monitor emerging state-level labeling mandates in California and New York that could fragment formulation standards faster than federal harmonization efforts can adapt.
Market Dynamics
Clean-label mandates from major retail chains are forcing reformulation across the North American food flavor supply chain, compressing artificial flavor volumes while expanding natural extract capacity requirements.
Growth Catalysts
- Biotech fermentation:Precision fermentation methods now yield natural-identical flavor molecules at commercial scale, reducing extraction costs for vanilla and citrus profiles.
- Reduced-sugar beverage mandates:Restaurant chains across the United States are driving demand for high-intensity sweetener masking solutions in fountain drink reformulations.
- USDA Organic certification:The seal's retail penetration above thirty-five percent in natural grocery channels gates shelf access for flavor suppliers serving premium-positioned CPG brands.
Market Restraints
- Vanilla bean supply concentration:Eighty percent of global natural vanilla originates from Madagascar, exposing North American extract suppliers to cyclone-driven price volatility.
- GRAS notification backlog:FDA's flavor ingredient review queue extends eighteen to twenty-four months, delaying novel natural molecule commercialization.
- Clean-label cost premium:Natural extracts command three to seven times the cost of artificial equivalents, constraining adoption in private-label snack segments.
Strategic Opportunities
- Upcycled flavor precursors:Fruit and vegetable processing waste streams in California's Central Valley offer captive feedstock for natural extract production.
- Quebec fermentation clusters:Montreal's expanding biotech infrastructure provides North American flavor houses with regional alternatives to European contract manufacturing.
- State-level labeling mandates:California's proposed flavor disclosure requirements would accelerate demand for fully traceable natural ingredient supply chains.
Industry Challenges
- Flavor chemist scarcity:Retirement waves among senior formulation scientists at US suppliers are outpacing university pipeline output from food science programs.
- Dual compliance architecture:Cross-border suppliers must maintain parallel GRAS and Health Canada Food and Drug Regulations documentation, doubling regulatory affairs headcount requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Flavor Market |
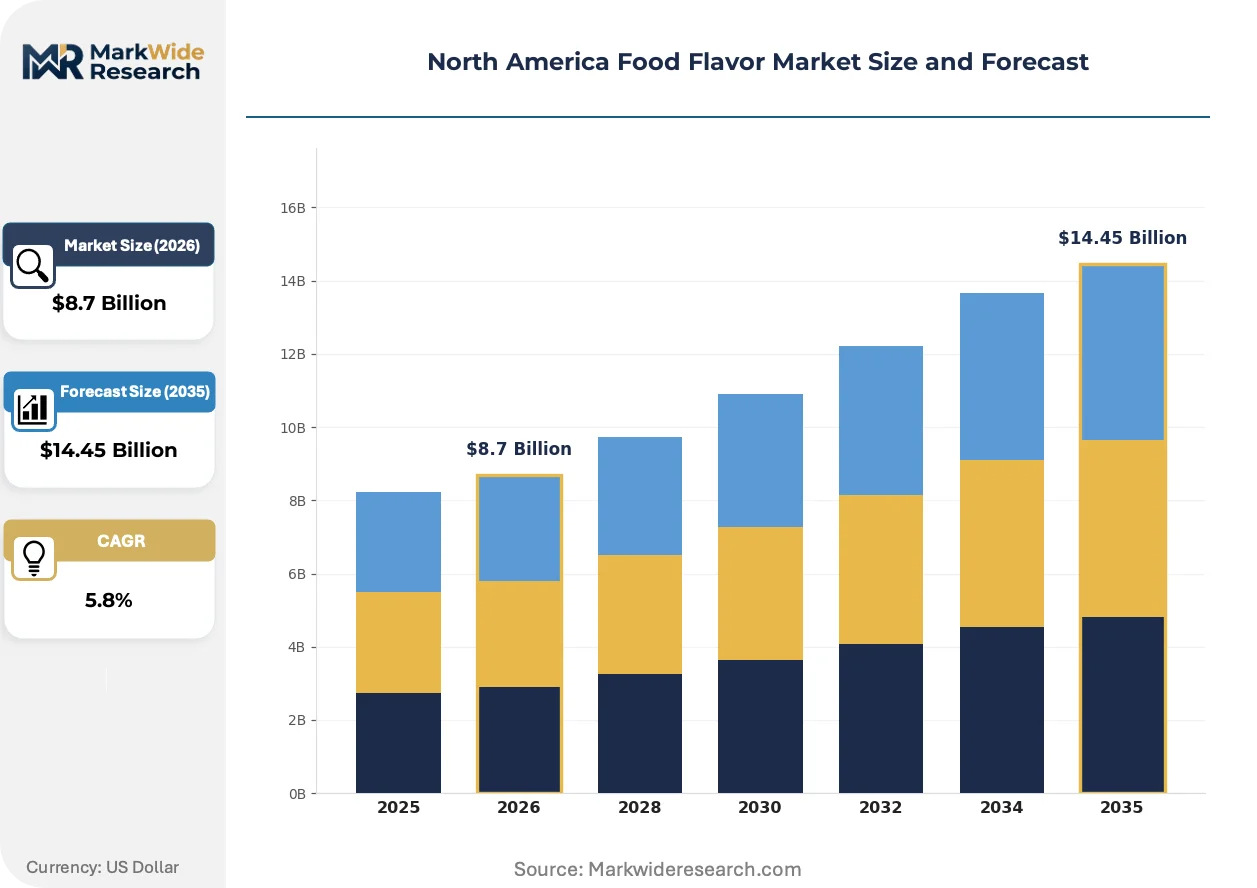
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Extracts, Artificial Flavorings, Flavor Compounds, Flavor Emulsions Application: Snacks, Beverages, Bakery, Confectionery End User: Food Manufacturers, Restaurants, Catering Services, Retailers Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Givaudan SA, International Flavors & Fragrances Inc., Symrise AG, DSM-Firmenich AG, Kerry Group plc, Sensient Technologies Corporation, Archer Daniels Midland Company, Firmenich SA, Takasago International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Flavor Market Evolving Landscape
Biotechnology and regulatory transparency requirements are converging to reshape how North American flavor houses develop, manufacture, and document their ingredient portfolios.
Precision fermentation is decomposing the traditional agricultural supply chain for high-value flavor molecules. Beverage manufacturers in the United States are adopting biotech-derived natural-identical compounds at accelerating rates for citrus and berry profiles. This technology is compressing lead times from growing season dependency to bioreactor batch cycles, enabling year-round supply stability previously unattainable with crop-based extraction.
Health Canada's updated Food and Drug Regulations guidance on natural flavor labeling is tightening definitional boundaries between extract-derived and chemically-synthesized molecules. Canadian food manufacturers must now document provenance chains for natural claims, increasing analytical testing spend. The regulatory friction falls heaviest on mid-sized suppliers serving private-label retailers, who lack vertical integration into raw material sourcing.
Direct sourcing contracts between CPG brands and biotechnology developers are bypassing traditional flavor house distribution networks. Major restaurant chains now negotiate molecule-specific supply agreements, unbundling formulation services from ingredient procurement. The disintermediation is most visible in California and Texas, where beverage brand R&D facilities cluster near fermentation manufacturing sites.
North America Food Flavor Market Segmentation
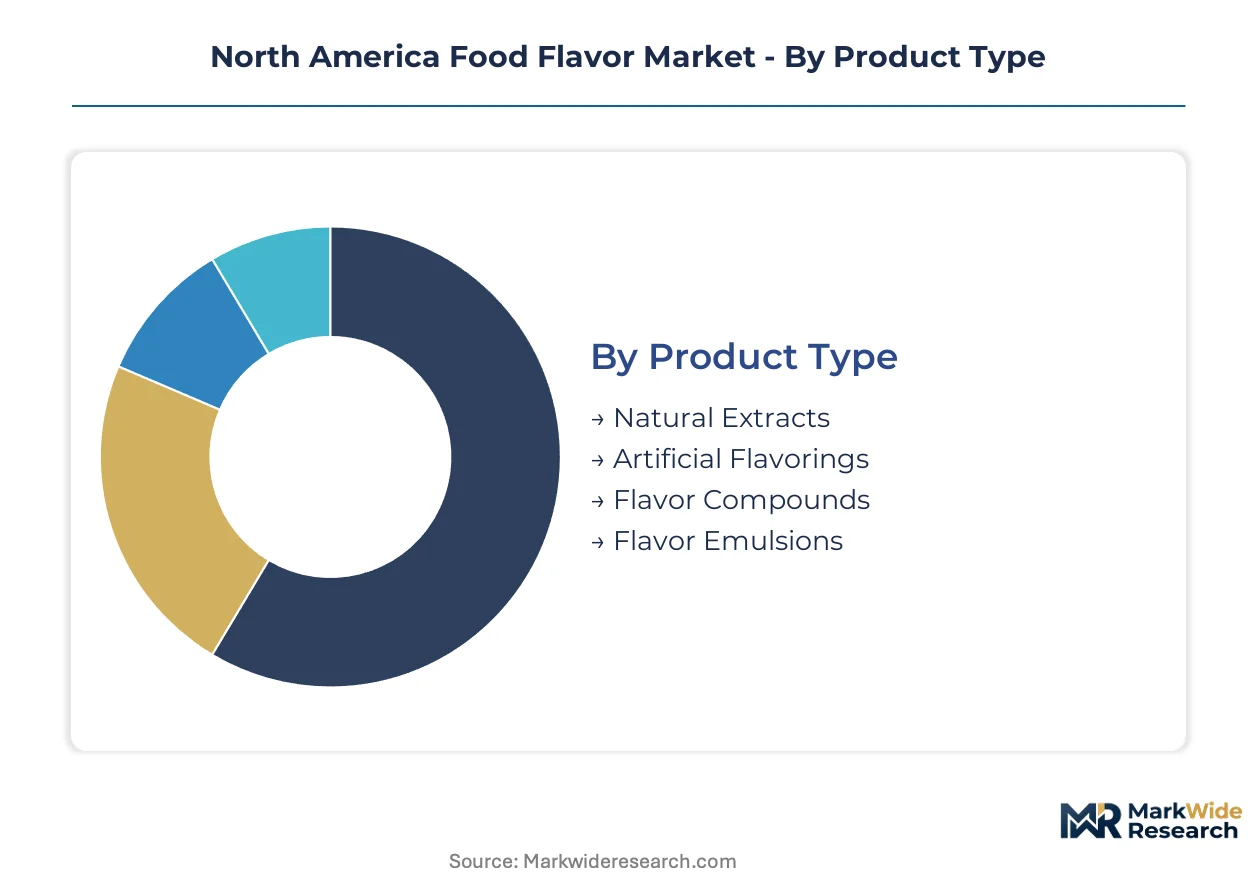
Segmentation in the North America Food Flavor Market reveals how formulation requirements diverge across regulatory environments, end-use specifications, and procurement scale. Understanding these divides enables suppliers to align capacity investments with the highest-margin demand pools.
Product Type:
Channel mix varies sharply by product type: natural extracts flow predominantly through direct sales to CPG manufacturers seeking provenance documentation, while artificial flavorings and emulsions move through distributors serving cost-sensitive private-label producers.
- Natural Extracts:Derived from botanical, animal, or microbial sources through distillation, solvent extraction, or enzymatic processing. These formulations carry USDA Organic and Non-GMO Project verification requirements that gate retail access in premium grocery channels. Demand concentrates in California and the Pacific Northwest, where beverage manufacturers reformulate for clean-label positioning under state-level disclosure mandates.
- Flavor Emulsions:Oil-in-water dispersions stabilized by gum arabic or modified starches, engineered for uniform flavor distribution in reduced-sugar liquid applications. Restaurant chains across Texas and Florida drive procurement volume for fountain drink reformulations requiring high-intensity sweetener masking.
- Artificial Flavorings:Chemically synthesized molecules engineered to replicate natural taste profiles at lower cost. Private-label snack manufacturers in the Midwest rely on distributor networks for standardized flavor procurement.
- Flavor Compounds:Concentrated single-molecule or simple-blend ingredients supplied to compound flavor houses for further formulation. Biotechnology developers in Montreal and California supply natural-identical variants through direct contracting.
By volume, artificial flavorings leads. By growth pace, flavor emulsions is climbing the fastest.
Application:
Cost tier stratification separates applications: beverages and confectionery absorb premium natural extracts, while snacks and bakery tolerate artificial alternatives where price elasticity constrains reformulation budgets.
- Beverages:Encompass carbonated soft drinks, functional waters, ready-to-drink teas, and alcoholic products requiring flavor stability across shelf-life and temperature variation. Major CPG brands in the Northeast and California anchor demand for biotech-derived citrus and berry profiles.
- Snacks:Includes savory chips, extruded products, and seasoned nuts where flavor adhesion and heat stability determine performance. Artificial flavorings dominate private-label procurement through distributor channels in the Southeast.
- Bakery:Covers bread, pastry, and cake applications where Maillard reaction compatibility and oven stability are critical. Regional bakeries in the Midwest source vanilla and butter flavor compounds through wholesale networks.
- Confectionery:Comprises chocolate, hard candy, and chewing gum requiring precise flavor release kinetics. Premium positioning in natural grocery channels drives natural extract adoption among artisanal producers.
Beverages commands the highest absolute spend per formulation. Snacks delivers the steepest volume expansion trajectory.
End User:
Customer type determines contract structure: food manufacturers negotiate multi-year supply agreements with technical service attachments, while restaurants and catering services purchase through spot markets or distributor programs.
- Food Manufacturers:Industrial-scale producers of packaged goods requiring batch-to-batch consistency and regulatory documentation for export. CPG headquarters in Chicago, Minneapolis, and New York anchor direct sales relationships with major flavor houses.
- Restaurants:Chain operators and independent establishments sourcing fountain syrup flavors, seasoning blends, and menu-specific formulations. Quick-service chains in Texas and California drive high-intensity sweetener masking demand.
- Catering Services:Event and institutional foodservice operations requiring bulk flavor procurement with flexible delivery scheduling. Regional distributors serve this fragmented segment through wholesale channels.
- Retailers:Private-label brand owners specifying flavor profiles for store-brand products across multiple categories. Supermarket chains in the Northeast and Midwest leverage volume for cost-competitive artificial flavoring procurement.
Food manufacturers generate the largest contract values. Restaurants are expanding procurement fastest.
Distribution Channel:
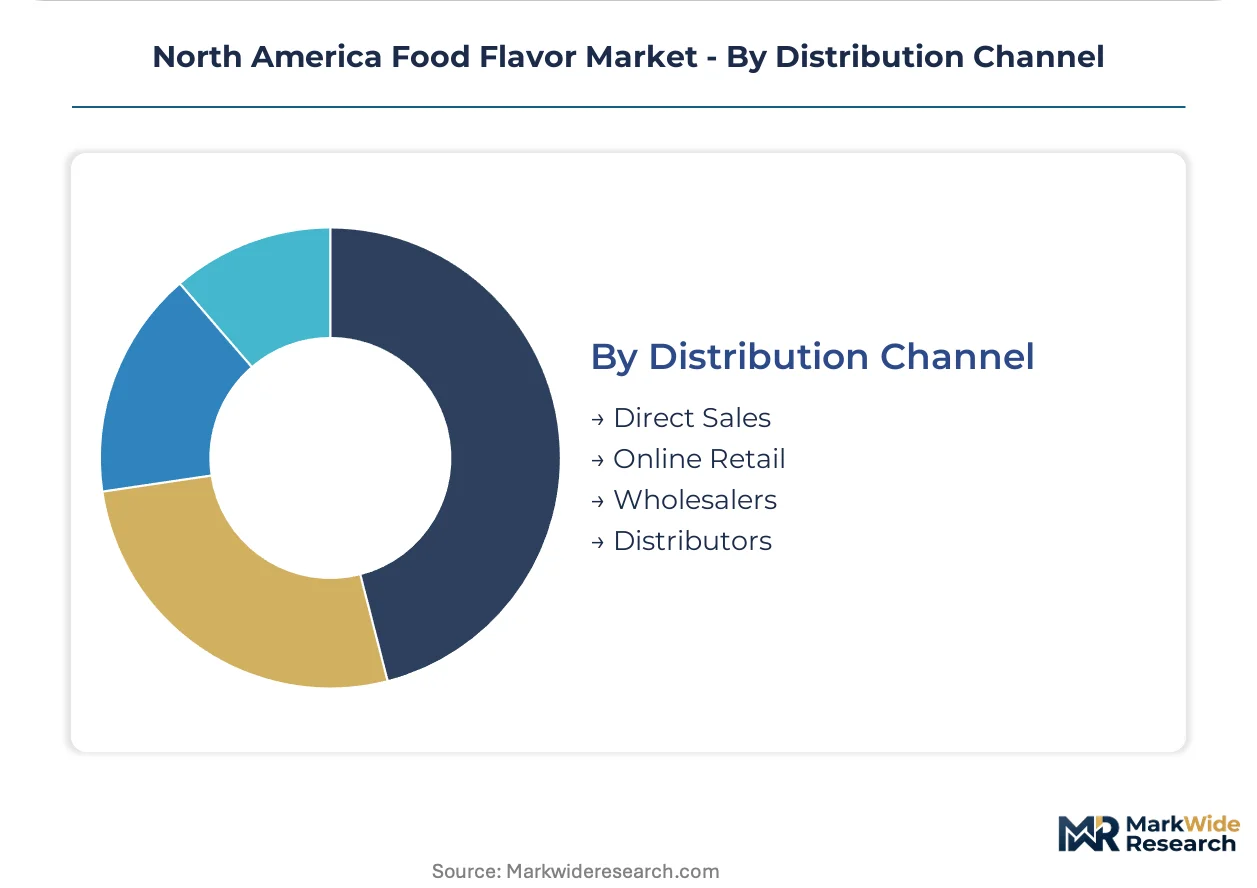
Supply concentration shapes channel selection: direct sales dominate where technical collaboration and regulatory documentation are required, while online retail and wholesalers serve fragmented, price-sensitive demand.
- Direct Sales:Manufacturer-to-customer relationships encompassing formulation development, sensory testing, and regulatory compliance support. Major CPG brands and restaurant chains in the United States and Canada rely on this channel for proprietary flavor development.
- Distributors:Regional and national intermediaries holding inventory for just-in-time delivery to mid-sized manufacturers and foodservice operators. The Southeast and Midwest show highest distributor penetration for artificial flavoring volume.
- Wholesalers:Bulk suppliers serving small manufacturers, artisanal producers, and institutional buyers with standardized product lines. Quebec and Ontario host concentrated wholesale activity for natural extract distribution.
- Online Retail:E-commerce platforms enabling small-batch procurement by startups, research kitchens, and specialty food producers. California's entrepreneurial food ecosystem drives highest online transaction velocity.
Distributors handle the greatest transaction volume. Direct sales capture the highest margin per dollar.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA flavor ingredient guidance and Health Canada Food and Drug Regulations create the dual compliance architecture governing North American formulation standards. The United States concentrates procurement volume from major CPG headquarters and restaurant chain R&D facilities. Cross-border suppliers navigate parallel documentation requirements while state-level mandates in California and New York introduce additional complexity.
United States
Major CPG brands and quick-service restaurant chains anchor formulation demand across the Midwest and California. FDA GRAS notification backlogs extending eighteen to twenty-four months delay novel natural molecule commercialization for domestic suppliers. Biotechnology fermentation clusters in California's Central Valley and Boston-Cambridge corridor yield natural-identical flavor molecules at commercial scale.
Canada
Health Canada's tightened natural flavor labeling definitions increase analytical testing spend for mid-sized suppliers serving private-label retailers. Montreal's expanding biotech infrastructure provides regional alternatives to European contract manufacturing for precision fermentation. Quebec and Ontario host concentrated wholesale distribution networks for natural extract procurement.
Mexico
Beverage manufacturers in the Bajío region and Mexico City Metro adopt flavor emulsions for reduced-sugar fountain drink reformulations. COFEPRIS regulatory alignment with FDA frameworks facilitates cross-border supply chain integration for multinational flavor houses. Guadalajara's food processing corridor drives demand for cost-competitive artificial flavoring in snack seasoning applications.
North America Food Flavor Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American food flavor supply chain. The market structure consolidates around integrated multinational houses with captive biotechnology capabilities, while mid-sized regional suppliers compete on formulation service intensity. Three archetypes dominate: vertically integrated biotech-forward houses, sensory science specialists with applied research centers, and distributor-dependent commodity flavor suppliers. Competitive moves concentrate on precision fermentation capacity expansion and direct sourcing contracts that bypass traditional distribution networks.
Among Switzerland-anchored multinational houses, Givaudan SA and Firmenich SA exemplify the biotechnology-forward archetype with integrated natural extraction pipelines. International Flavors & Fragrances Inc. represents the sensory science specialist model through applied research facilities serving beverage partnerships. Symrise AG occupies a position in high-intensity sweetener-flavor masking combinations for reduced-sugar applications. These three companies sit within distinct strategic vectors rather than direct overlap, with each anchoring a different capability premium in the competitive structure.
| Leading Market Players |
|---|
| Givaudan SA |
| International Flavors & Fragrances Inc. |
| Symrise AG |
| DSM-Firmenich AG |
| Kerry Group plc |
| Sensient Technologies Corporation |
| Archer Daniels Midland Company |
| Firmenich SA |
| Takasago International Corporation |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four-month FDA GRAS notification queues compress pricing power for novel natural molecules while concentrating margin capture among established suppliers with pre-cleared ingredient portfolios. This lead-time asymmetry rewards backward-integrated flavor houses controlling captive extraction pipelines and punishes mid-sized competitors dependent on external biotech fermentation contract capacity.
Pricing Analysis
United States-Canada price spreads of three-to-seven times separate natural extracts from artificial equivalents, with California and Pacific Northwest beverage manufacturers absorbing the steepest premiums for USDA Organic-verified provenance. Three-tier pricing structure across premium natural-identical, standard botanical-extracted, and economy synthetic tiers stratifies procurement by certification grade and volume scale. Cost compression in artificial flavorings intensifies as private-label snack manufacturers in the Midwest leverage distributor networks for spot-market purchasing. Food manufacturers demonstrate lowest price sensitivity due to reformulation lock-in costs, while restaurant chains exhibit highest elasticity in fountain drink flavor procurement.
Supply Chain Analysis
Strategic stockpiling of Madagascar vanilla bean inventories dominates natural extract procurement, contrasting with just-in-time artificial flavoring flows through Midwest distributor networks. Eighty percent concentration of global vanilla supply in Madagascar, Indonesia, and Papua New Guinea exposes North American extract houses to cyclone-driven commodity volatility. Raw material dependencies on citrus peel waste, fermentation feedstocks, and gum arabic stabilizers tether formulation costs to agricultural yield cycles. Single-source vulnerability in high-value botanicals drives premium pricing for traceable supply chains. Distribution runs through direct sales channels for CPG technical partnerships and wholesale networks for fragmented foodservice demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flavor formulation services and recurring sensory testing contracts expand faster than commodity ingredient sales, creating attach-rate opportunities for suppliers pivoting from molecule transactions to integrated taste-engineering partnerships.
For Market Incumbents: Shield proprietary natural extraction pipelines through captive biotechnology capacity in California and Montreal fermentation clusters. Consolidate formulation scientist talent pools through targeted acquisition of regional flavor houses facing retirement-wave capability gaps. Defend margin position by locking multi-year direct sourcing contracts with major beverage brands before biotech developers can bypass traditional distribution networks. For New Entrants and Emerging Players: Differentiate on upcycled feedstock provenance from California Central Valley fruit and vegetable processing waste streams. Target Quebec's expanding biotech infrastructure as the most penetrable geography for precision fermentation contract manufacturing. Pursue white-space opportunities in high-intensity sweetener masking for reduced-sugar fountain drink reformulations across Texas and Florida quick-service chains. For Investors and Strategic Acquirers: Long-term, this sits as a capability-scarcity play because flavor chemist retirement waves are outpacing university pipeline output across United States and Canada food science programs. Acquisition targets should display vertical integration into natural-identical molecule production or applied sensory science centers serving beverage partnerships. Watch FDA GRAS notification processing velocity as the signal indicating whether novel natural molecule commercialization timelines compress or extend.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Biotech-derived natural-identical molecules reduce dependency on Madagascar vanilla cyclone exposure. |
| Direct Sourcing Contract Negotiation | Beverage brands in California and Texas bypass traditional flavor house distribution networks for molecule-specific supply. |
| Applied Sensory Science Center Investment | Technical service attachments lock multi-year relationships with CPG headquarters in Chicago and Minneapolis. |
| Upcycled Feedstock Supply Chain Development | California Central Valley waste streams offer captive raw material sourcing for natural extract cost compression. |
| Dual Compliance Documentation Architecture | Parallel GRAS and Health Canada Food and Drug Regulations systems gate cross-border supplier market access. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with flavor chemists, regulatory affairs directors at CPG manufacturers, restaurant chain R&D procurement leads, and biotechnology fermentation specialists; and secondary validation through FDA GRAS notification databases, Health Canada Food and Drug Regulations guidance documents, USDA Organic certification records, and customs trade data on vanilla bean and citrus extract imports. Bottom-up triangulation across ingredient volume flows and top-down reconciliation against CPG reformulation expenditure patterns anchored market sizing.
Across the projection horizon, the analytical framework modeled demand by product type, application category, end-user archetype, and distribution channel complexity. CAGRs derived from segment-level growth drivers including clean-label mandate penetration, precision fermentation adoption curves, and reduced-sugar beverage reformulation timelines. Forecast inputs incorporated biotech fermentation capacity expansion schedules in California and Montreal, state-level labeling mandate progression in California and New York, and vanilla bean harvest yield volatility indices.
Material uncertainties — FDA GRAS notification backlog duration, cyclone frequency in Madagascar supply zones, and state-level flavor disclosure mandate implementation timing — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory harmonization pace and biotechnology cost curves. Revision becomes warranted when Health Canada natural flavor definitional enforcement intensity or California state mandate adoption crosses thresholds altering clean-label reformulation economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Marshmallow Root Extract Market
Flavorings and Food Additives
Europe Food Flavor Market
Flavorings and Food Additives
Anthocyanin Food Colors Market
Flavorings and Food Additives
South America Food Flavor and Enhancer Market
Flavorings and Food Additives
Global Chicory Market
Flavorings and Food Additives
Asia-Pacific Food Colorants Market
Flavorings and Food Additives
Modified Lecithin Market
Flavorings and Food Additives
Tangerine Peel Extract Market
Flavorings and Food Additives
Menthol Market
Flavorings and Food Additives
Flavor Ingredients Market
Flavorings and Food Additives
Mouth Freshener Market
Flavorings and Food Additives
Australia Vanilla Flavor Market
Flavorings and Food Additives
Basil Oil Market
Flavorings and Food Additives
Yeast Based Savory Flavors Market
Flavorings and Food Additives
Feed Flavors, Sweeteners and Natural Enhancers Market
Flavorings and Food Additives
Egypt Food Colorants Market