
 Food Flavors & Flavor Enhancers Market | 2026-2036
Food Flavors & Flavor Enhancers Market Size, Share, and Industry Trends Forecast 2026-2036
Food Flavors & Flavor Enhancers Market Insights
Natural extracts and fermentation-derived molecules is restructuring cost structures across flavor portfolios, displacing petroleum-based synthetics in mid-tier applications. Givaudan S.A. leverages its botanical sourcing network to secure supply continuity for clean-label programs. International Flavors & Fragrances Inc. anchors its position through integrated biotechnology capabilities spanning enzyme engineering and microbial strain development. Firmenich SA differentiates via proprietary captive production of key aroma chemicals in Switzerland and Singapore.
Food flavors and flavor enhancers comprise volatile and non-volatile compounds—esters, aldehydes, pyrazines, nucleotides, and amino acid derivatives—formulated at parts-per-million to parts-per-thousand concentrations to modify sensory perception of taste and aroma in processed foods. Their primary commercial purpose is to restore flavor intensity lost during thermal processing, extended shelf-life packaging, or fat and sodium reduction in reformulated products. Natural flavors and flavor enhancers command expanding margin pools as food manufacturers absorb premium costs to meet retailer clean-label requirements. Beverage applications lead volume absorption due to high reformulation frequency in carbonated soft drinks and functional waters. Powder forms dominate industrial procurement for dry seasoning blends and instant beverage bases.
FDA GRAS self-affirmation and FEMA expert panel evaluations govern new flavor substance approvals in the United States, while EFSA and EU Regulation 1333/2008 dictate permitted flavoring substances and maximum levels across member states. These frameworks create divergent compliance costs that favor multi-regional players with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving definitions of natural status under pending EU botanicals legislation and corresponding state-level initiatives in California and New York.
Market Dynamics
Clean-label mandates from retailers are compressing reformulation cycles across beverage and processed food portfolios, forcing manufacturers to replace petroleum-derived synthetics with botanical extracts and fermentation-derived molecules at unprecedented speed.
Growth Catalysts
- EU Green Deal compliance:REACH-aligned botanical extraction platforms redirect capital expenditure toward renewable feedstock processing. Food manufacturers absorb premium input costs to maintain shelf placement.
- Beverage reformulation intensity:Carbonated soft drink and functional water producers cycle flavors quarterly to match competitor launches. Powder flavor procurement volumes expand for instant beverage bases.
- China domestic premiumization:Local food manufacturers scale clean-label product lines for tier-one urban consumers. SAMR labeling enforcement accelerates natural flavor substitution rates.
Market Restraints
- Vanillin supply concentration:Petrochemical and guaiacol-derived vanillin production clusters in China and Germany expose buyers to feedstock volatility from crude oil and creosote markets.
- Regulatory fragmentation:FDA GRAS self-affirmation diverges from EFSA positive list requirements under EU Regulation 1333/2008. Multi-regional players bear duplicated toxicology study costs.
- Natural extract yield variability:Climate-dependent botanical sourcing from Madagascar, Indonesia, and India creates batch-to-batch inconsistency in vanilla and citrus terpene profiles.
Strategic Opportunities
- Precision fermentation scale-up:Microbial strain engineering for rare terpenes and lactones reduces dependency on tropical agriculture. Biotechnology firms partner with flavor houses for captive molecule production.
- Direct-to-manufacturer digital platforms:E-procurement portals bypass traditional distributor markups for mid-sized food processors. Sample-to-production workflows compress from months to weeks.
- California clean-label legislation:State-level initiatives restricting artificial flavor declarations create preemptive demand for natural alternatives ahead of federal alignment.
Industry Challenges
- Flavor chemist talent scarcity:Cross-training in gas chromatography-mass spectrometry and sensory science lags industry expansion. Universities lack dedicated flavor chemistry degree tracks.
- Clean-label certification timelines:Third-party non-GMO and organic verification extends new product launch schedules by 8-14 months. Parallel regulatory submissions strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Flavors & Flavor Enhancers Market |
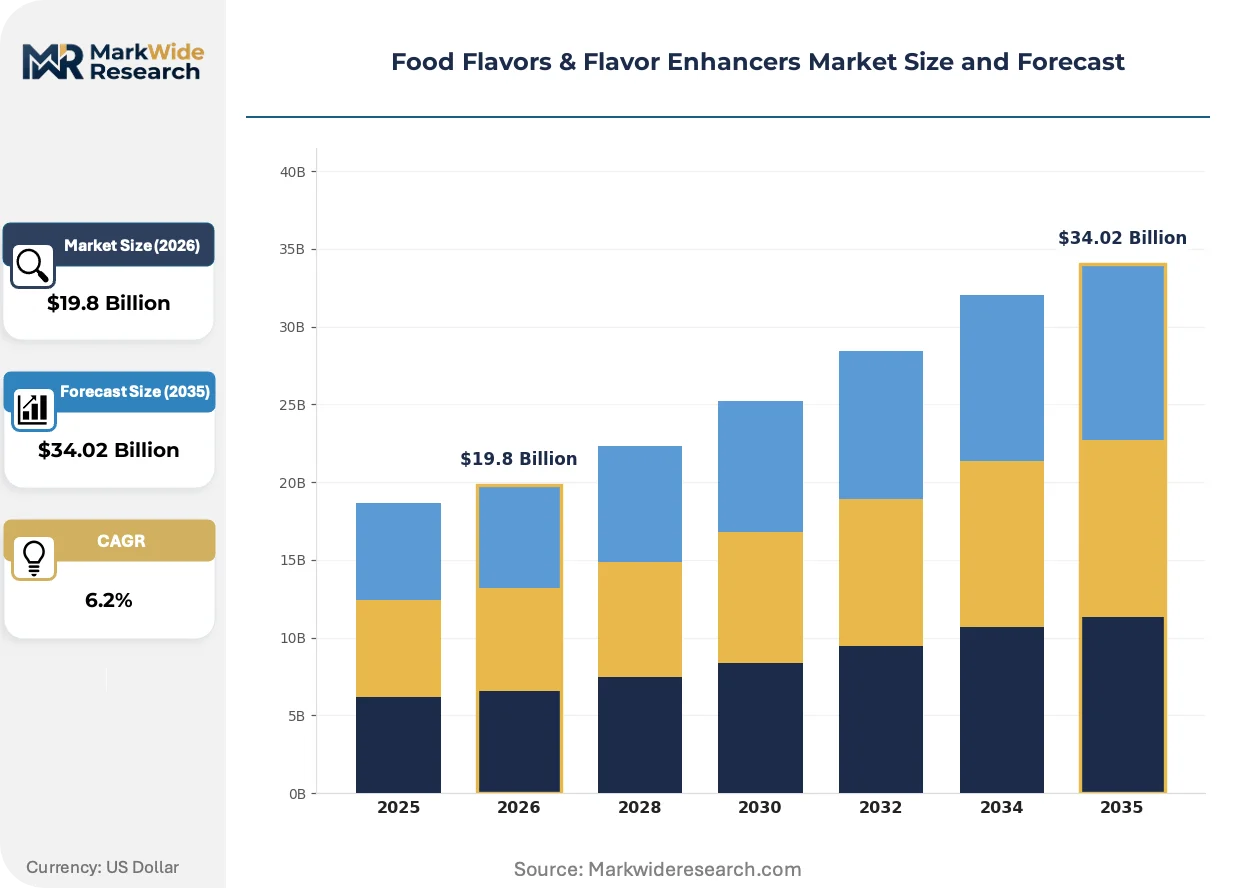
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $34.02 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Flavor Enhancers, Essential Oils Application: Beverages, Bakery, Snacks, Dairy Products Form: Liquid, Powder, Paste, Granular End User: Food Manufacturers, Beverage Companies, Restaurants, Retail Stores |
| Companies Covered | Givaudan S.A., International Flavors & Fragrances Inc., Firmenich SA, Symrise AG, Takasago International Corporation, Kerry Group Plc, Ajinomoto Co., Inc., Archer Daniels Midland Company, Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Flavors & Flavor Enhancers Market Trends and Innovations
Biotechnology platforms are rewriting cost structures for aroma molecules previously extracted from scarce botanicals. Regulatory divergence between major economies is fragmenting product development pipelines. Buyer procurement patterns are compressing supplier qualification cycles.
Precision fermentation for key aroma chemicals is converging with traditional extraction methods in hybrid production portfolios. Beverage manufacturers adopt biotech-derived molecules for cost stability in high-volume applications. The technology is converging with solvent extraction to create dual-source supply security for citral and nootkatone.
EU botanicals legislation pending under EFSA review is redefining permissible natural flavor definitions. The framework threatens to disqualify certain solvent-extracted materials from clean-label claims. Botanical houses in France and Switzerland accelerate supercritical CO2 investment to preempt compliance gaps.
Retailer-driven specification sheets now mandate natural status ahead of price negotiations. Food manufacturers bypass traditional flavor distributors for direct biotechnology partnerships. This pattern concentrates most visibly in North American and Western European beverage supply chains where private-label penetration is deepest.
Food Flavors & Flavor Enhancers Market Segmentation
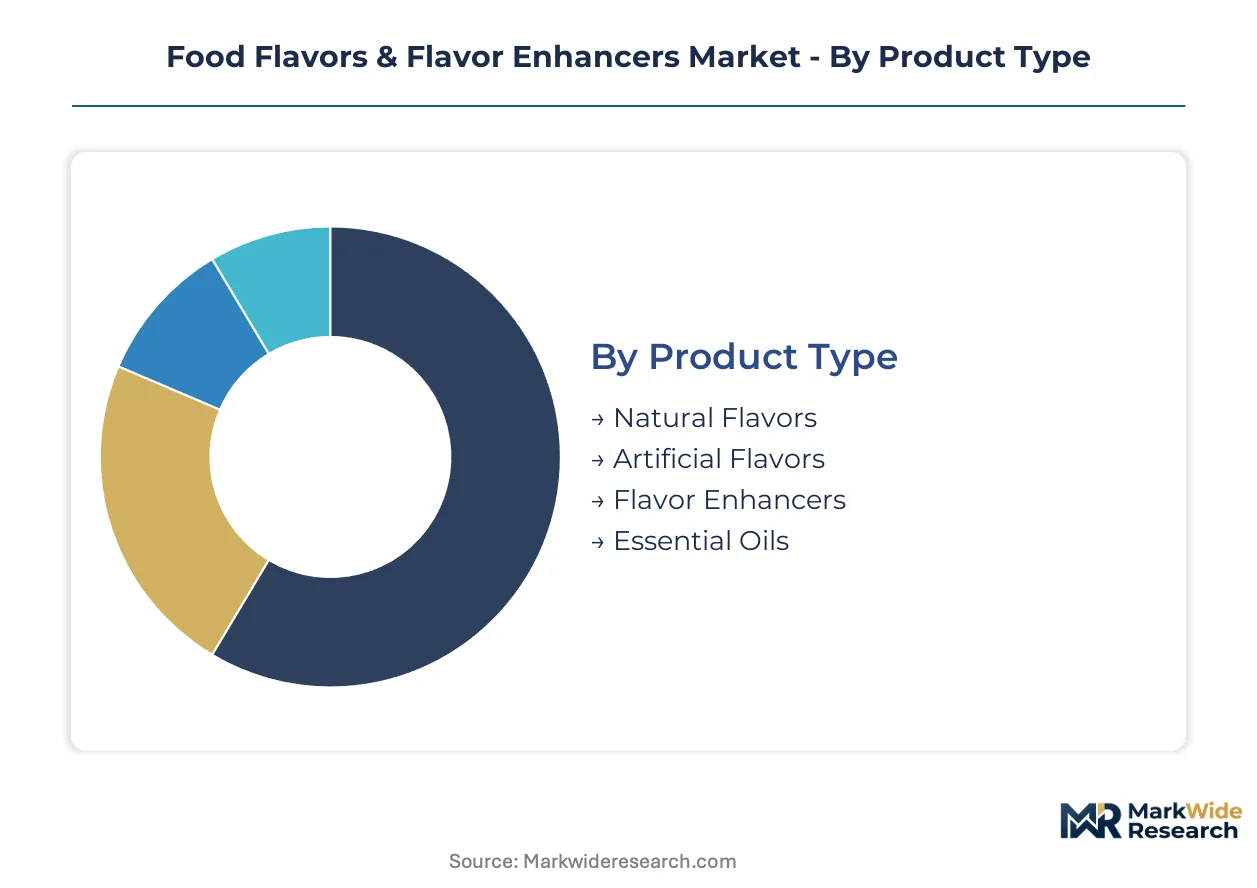
Segmentation in the Food Flavors & Flavor Enhancers Market reveals how regulatory burden, application intensity, and procurement scale reshape supplier priorities. Each dimension carries distinct certification requirements and margin structures that determine competitive positioning.
Product Type:
Natural Flavors carry organic and non-GMO verification burdens through USDA NOP and EU 2018/848 compliance. Artificial Flavors navigate FDA GRAS self-affirmation with lower documentation overhead. Flavor Enhancers face EFSA positive-list restrictions under EU Regulation 1333/2008. Essential Oils require ISO 9001 and HACCP alignment for pharmaceutical-adjacent applications.
- Natural Flavors:Botanical extracts and fermentation-derived molecules formulated from plant, animal, or microbial sources. Demand concentrates in premium beverage reformulations across Germany and France as retailers enforce clean-label specifications. EFSA botanicals legislation pending review threatens to disqualify certain solvent-extracted materials.
- Artificial Flavors:Petroleum-derived synthetics including esters, aldehydes, and pyrazines manufactured through chemical synthesis. Procurement persists in cost-sensitive snack applications within China and India where SAMR and FSSAI labeling enforcement lags Western standards. Feedstock volatility from crude oil markets compresses margin stability.
- Flavor Enhancers:Nucleotides, amino acid derivatives, and yeast extracts that amplify existing taste perception without contributing distinct aroma. Food manufacturers in Japan integrate these compounds for sodium reduction programs under METI nutritional guidelines.
- Essential Oils:Terpene-rich volatile fractions extracted via steam distillation or cold pressing from citrus, mint, and spice botanicals. Swiss and French botanical houses prioritize supercritical CO2 processing to preempt EU compliance gaps.
Natural Flavors sits at the top of the volume ranking, with Flavor Enhancers climbing the fastest.
Application:
Application segmentation tracks reformulation frequency and thermal processing intensity. Beverage producers cycle flavors quarterly, demanding rapid supplier response. Bakery applications require heat-stable formulations that resist degradation during oven exposure.
- Beverages:Carbonated soft drinks, functional waters, and ready-to-drink teas requiring precise flavor dosing at parts-per-million concentrations. Powder flavor procurement expands for instant beverage bases in China as domestic manufacturers scale premium lines.
- Bakery:Breads, pastries, and biscuits needing heat-stable flavor systems that survive Maillard reaction temperatures. French and Italian industrial bakeries drive demand for encapsulated flavor technologies.
- Snacks:Extruded and fried products relying on topical seasoning blends with high flavor loadings. US and Mexican processors absorb premium natural costs to maintain retail shelf placement.
- Dairy Products:Yogurt, ice cream, and flavored milk applications demanding lipid-compatible flavor systems. German dairy cooperatives specify fermentation-derived molecules for clean-label positioning.
Beverages captures the largest procurement volumes, with Snacks expanding most quickly.
Form:
Form selection determines handling infrastructure, shelf-life extension, and dissolution performance. Liquid forms dominate high-volume continuous processing. Powder forms optimize logistics for dry blend operations.
- Liquid:Solvent-based or aqueous solutions offering precise metering in automated dosing systems. US beverage bottlers prefer liquid concentrates for tank-farm operations.
- Powder:Spray-dried or plated carriers enabling dry seasoning blends and instant beverage bases. Chinese food manufacturers scale powder procurement for instant noodle and soup applications.
- Paste:High-viscosity suspensions containing suspended particulates for bakery and confectionery fillings. Italian pasta sauce producers specify paste forms for viscosity control.
- Granular:Agglomerated particles balancing flowability with rapid hydration. Japanese seasoning houses utilize granular forms for tabletop dispenser compatibility.
Powder sits at the top of the volume ranking, with Liquid climbing the fastest.
End User:
End user segmentation distinguishes procurement scale, technical sophistication, and distributor dependency. Food manufacturers negotiate direct supply agreements. Restaurants and retail stores rely on distributor intermediaries.
- Food Manufacturers:Industrial processors of packaged goods with dedicated procurement teams and quality assurance infrastructure. Nestlé and Unilever-scale buyers bypass distributors for direct biotechnology partnerships.
- Beverage Companies:Carbonated soft drink and functional water producers with quarterly reformulation cycles. PepsiCo and Coca-Cola system suppliers absorb premium natural costs for clean-label compliance.
- Restaurants:Foodservice operators sourcing through broadline distributors with limited technical specification control. US chain restaurants face California clean-label legislation restricting artificial flavor declarations.
- Retail Stores:Private-label developers and specialty food retailers with fragmented procurement volumes. European discounters concentrate specification power to mandate natural status ahead of price negotiations.
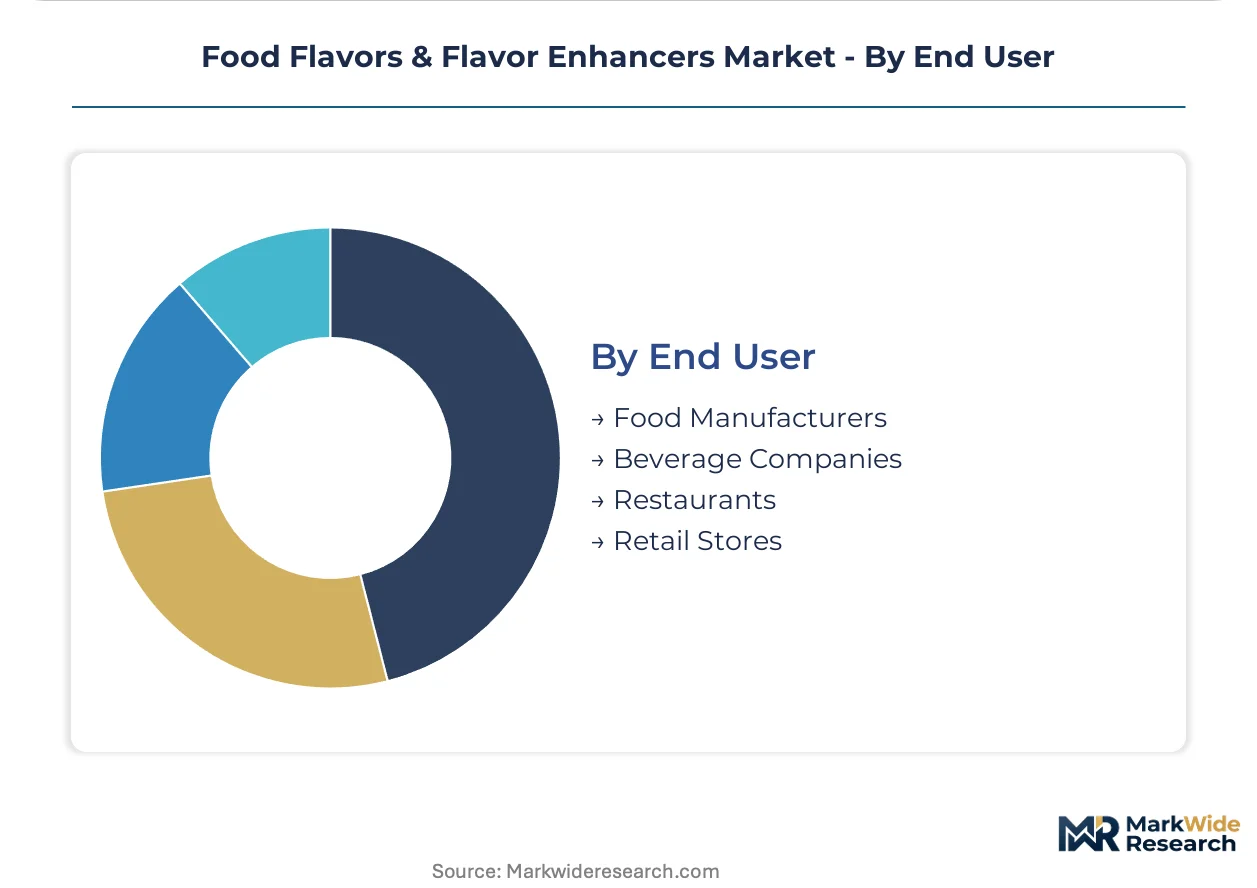
Food Manufacturers sits at the top of the volume ranking, with Beverage Companies climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flavor production clusters in Switzerland and Singapore anchor biotechnology scale-up for fermentation-derived molecules. Regulatory divergence between FDA GRAS self-affirmation and EFSA positive-list requirements shapes capital deployment across jurisdictions.
United States
Beverage manufacturers in Atlanta and Chicago drive quarterly reformulation cycles for carbonated soft drinks. California clean-label legislation restricts artificial flavor declarations ahead of federal alignment. Midwest dairy cooperatives specify fermentation-derived molecules for clean-label positioning in yogurt and flavored milk.
Germany
Industrial bakeries in Munich and Hamburg demand heat-stable encapsulated flavor systems for Maillard reaction temperatures. EU Green Deal compliance redirects investment toward REACH-aligned botanical extraction platforms. Bavarian botanical houses accelerate supercritical CO2 processing to preempt EFSA botanicals legislation gaps.
China
Domestic food manufacturers in Shanghai and Guangzhou scale premium clean-label product lines for tier-one urban consumers. SAMR labeling enforcement accelerates natural flavor substitution rates. Pearl River Delta instant noodle producers expand powder flavor procurement for soup applications.
France
Retail discounters in Paris and Lyon concentrate specification power to mandate natural status ahead of price negotiations. EFSA botanicals legislation pending review threatens to disqualify certain solvent-extracted materials. Grasse-based botanical houses prioritize organic certification for essential oil exports.
Japan
Seasoning houses in Tokyo and Osaka integrate nucleotides and yeast extracts for sodium reduction programs under METI nutritional guidelines. Kansai-region processors utilize granular forms for tabletop dispenser compatibility. Precision fermentation partnerships reduce dependency on tropical agriculture for rare terpenes.
Food Flavors & Flavor Enhancers Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance infrastructure and biotechnology scale. The vendor base organizes around three tiers: integrated flavor houses with captive fermentation capacity, botanical specialists with supercritical extraction assets, and commodity processors serving cost-sensitive applications. Strategic moves concentrate on precision fermentation scale-up and direct-to-manufacturer digital platform deployment.
Within the integrated biotechnology tier, Givaudan S.A. and International Flavors & Fragrances Inc. exemplify archetypes combining enzyme engineering with microbial strain development. Firmenich SA occupies a position emphasizing proprietary captive production of key aroma chemicals. These Swiss and US-origin entities anchor competitive positioning through regulatory affairs infrastructure spanning FDA GRAS self-affirmation and EFSA positive-list compliance.
| Leading Market Players |
|---|
| Givaudan S.A. |
| International Flavors & Fragrances Inc. |
| Firmenich SA |
| Symrise AG |
| Takasago International Corporation |
| Kerry Group Plc |
| Ajinomoto Co., Inc. |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Others |
Pricing and Supply Chain Analysis
Food manufacturer procurement teams at Nestlé-scale buyers and PepsiCo-system suppliers concentrate specification power, anchoring a contract-based long-term offtake pricing model that absorbs premium natural input costs to secure clean-label compliance and retail shelf placement.
Pricing Analysis
Input-cost pass-through from tropical botanicals and fermentation feedstocks dominates pricing structures, with premium-mid-economy pricing differentiation separating organic-certified natural extracts from conventional fermentation-derived molecules and petroleum-based synthetics. Certification grade under USDA NOP and EU 2018/848, plus volume scale commitments, drive price spreads. Cost compression in mid-tier artificial flavors is intensifying because crude oil volatility feeds guaiacol-derived vanillin instability. Snack processors in China and India exhibit highest price sensitivity; German dairy cooperatives and French retail discounters absorb premiums with least resistance.
Supply Chain Analysis
Vanilla and citrus terpene supply rests on agricultural networks in Madagascar, Indonesia, and India, with precision fermentation capacity emerging in Switzerland and Singapore as a hedge against climate-dependent yield variability. Key inputs span vanilla orchids, citrus peels, and microbial feedstocks for engineered strains. Single-source vulnerability concentrates in Chinese and German petrochemical vanillin clusters exposed to creosote market disruptions. Distribution runs through integrated flavor houses with captive biotechnology capacity, bypassing traditional distributors for direct manufacturer partnerships in North American and Western European beverage supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food Flavors & Flavor Enhancers Market functions as a stable compounder, with clean-label regulatory mandates across FDA, EFSA, and SAMR jurisdictions providing durable demand visibility for natural and fermentation-derived alternatives.
For Market Incumbents: To counter precision fermentation scale-up by biotechnology specialists, integrated flavor houses should deepen backward integration into microbial strain engineering partnerships and expand supercritical CO2 extraction capacity in Switzerland and France to preempt EFSA botanicals legislation compliance gaps. For New Entrants and Emerging Players: Precision fermentation platforms for rare terpenes and lactones offer the most penetrable wedge, targeting sodium reduction flavor enhancer applications in Japan under METI nutritional guidelines through direct-to-manufacturer digital procurement portals that compress sample-to-production workflows. For Investors and Strategic Acquirers: Food manufacturers with captive clean-label reformulation pipelines are the most active acquirer in this space, seeking biotechnology capabilities to secure supply continuity. Long-term viability centers on fermentation-derived molecule cost parity with botanical extraction. Watch EFSA botanicals legislation finalization as the critical inflection signal for asset repricing across European botanical houses.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial strain engineering for rare terpenes reduces dependency on Madagascar vanilla and Indonesian citrus agriculture. |
| Supercritical CO2 Processing Investment | French and Swiss botanical houses preempt EU Regulation 1333/2008 compliance gaps for clean-label certification. |
| Direct-to-Manufacturer Digital Platform | E-procurement portals bypass distributor markups and compress qualification cycles for mid-sized processors. |
| Backward Integration into Biotechnology | Integrated flavor houses secure captive supply of fermentation-derived molecules for beverage reformulation. |
| Regulatory Affairs Infrastructure Expansion | Multi-regional players duplicate toxicology studies to bridge FDA GRAS self-affirmation and EFSA positive-list divergence. |
Research Methodology
Bottom-up beverage and processed food modeling reconciled against top-down botanical extraction and fermentation capacity tracking forms the analytical core. Primary interviews with flavor chemists, procurement leads at multinational food manufacturers, regulatory affairs directors, and supercritical CO2 extraction plant managers combine with secondary validation from FDA GRAS notices, EFSA flavoring substance evaluations, SAMR labeling directives, FEMA expert panel publications, and EU customs trade data for natural extract flows.
Historical trendline analysis across natural flavor substitution rates, reformulation cycle frequencies, and biotechnology capacity buildouts informs the projection framework. Segmentation dimensions span product type, application intensity, form factor, and end-user procurement scale, with CAGRs derived from slope-consistency testing against input-cost trajectories and regulatory enforcement timelines. Forecast inputs include climate yield variability indices for tropical agriculture and precision fermentation unit cost curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA botanicals legislation finalization, California clean-label initiative federal alignment, and vanillin feedstock volatility from crude oil markets. A small set of regulatory triggers and agricultural yield shocks warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Fiber Syrup Market
Flavorings and Food Additives
Natural Acerola Cherry Extract Market
Flavorings and Food Additives
Oleoresin Market
Flavorings and Food Additives
Orange Peel Extract Market
Flavorings and Food Additives
Orange Terpenes Market
Flavorings and Food Additives
Dry Powder Flavors Market
Flavorings and Food Additives
Africa Food Flavor Market
Flavorings and Food Additives
Argentina Food Flavor and Enhancer Market
Flavorings and Food Additives
Natural Flavors Market
Flavorings and Food Additives
Egypt Food Colorants Market
Flavorings and Food Additives
FTNF Flavors Market
Flavorings and Food Additives
Neotame Market
Flavorings and Food Additives
Global Flavors Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
Global Natural Food Flavors Market
Flavorings and Food Additives
Flavanones Market