
 Carob Chocolate Market | 2026-2036
Carob Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Carob Chocolate Market Intelligence
Health-conscious consumers seeking caffeine-free options are bifurcating the market, shifting purchasing power toward specialized health food stores. The Australian Carob Co. leverages its "tree-to-bar" production to control quality for provenance-focused buyers. The Hain Celestial Group, Inc. sustains its position through extensive distribution networks in North America and Europe. NOW Foods specializes in carob powder as a bulk ingredient for food manufacturers and home consumers.
Carob chocolate is a confectionary product derived from the dried and roasted pods of the carob tree, Ceratonia siliqua. It serves as a chocolate substitute, distinguished by its natural sweetness and absence of theobromine and caffeine. Powder and chips product forms see high volume usage within the bakeries and food services end-user segments for ingredient applications. Finished bars, distributed through online channels and specialty stores, represent a higher-margin category targeting direct consumer sales.
In the United States, the FDA's food labeling requirements govern how ingredients and nutritional information are presented on carob products. Similarly, the European Food Safety Authority (EFSA) sets strict criteria for any health or nutritional claims made on packaging. Navigating these distinct international food codes for marketing and allergen declarations remains a critical task for manufacturers seeking wider distribution.
Market Dynamics
The central structural force shaping the Carob Chocolate Market is the convergence of consumer demand for functional, "free-from" foods and tightening food labeling regulations. Mandates from the FDA and EFSA force transparency, which producers leverage to market carob's natural benefits.
Growth Catalysts
- Caffeine-Free Demand:A growing consumer segment seeking to avoid caffeine and theobromine for health or dietary reasons provides a dedicated customer base for carob-based confectionery products.
- Clean Labeling Regulations:Updated food labeling requirements from regulators like the FDA encourage transparent marketing, allowing manufacturers to clearly highlight carob's natural, caffeine-free, and lower-fat properties.
- Food Service Application:The bakery and food service industries are increasing their use of carob powder and chips as a bulk ingredient for developing allergen-free and health-oriented menu items.
Market Restraints
- Geographic Supply Concentration:Cultivation of the carob tree is heavily concentrated in Mediterranean climates, making the global supply chain vulnerable to regional climate events and agricultural challenges in countries like Spain.
- Higher Input Costs:Compared to the massive scale of cocoa production, the niche cultivation of carob leads to higher raw material costs, which translates to a premium price point for finished goods.
- Consumer Perception:Carob continues to battle a legacy perception as a mere substitute for chocolate, which can limit its appeal among mainstream consumers not actively seeking a chocolate alternative.
Strategic Opportunities
- Geographic Expansion:There is an opportunity to introduce carob products into underpenetrated health-conscious markets in Asia, such as Japan and South Korea, where functional snacks are gaining popularity.
- Product Line Extension:Development of new product formats beyond bars and chips, such as carob-based spreads, syrups, and ready-to-drink beverages, can open new categories for consumption.
- Functional Fortification:Formulating carob products with added functional ingredients like probiotics, vitamins, or plant-based proteins can enhance their appeal to health-focused consumers and command premium pricing.
Industry Challenges
- Certification Complexity:Obtaining and maintaining multiple international organic, non-GMO, and fair-trade certifications is a costly and administratively burdensome task for producers targeting global distribution.
- Quality Consistency:Ensuring a consistent flavor profile and quality from carob pods sourced from various agricultural suppliers presents a significant operational challenge for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carob Chocolate Market |
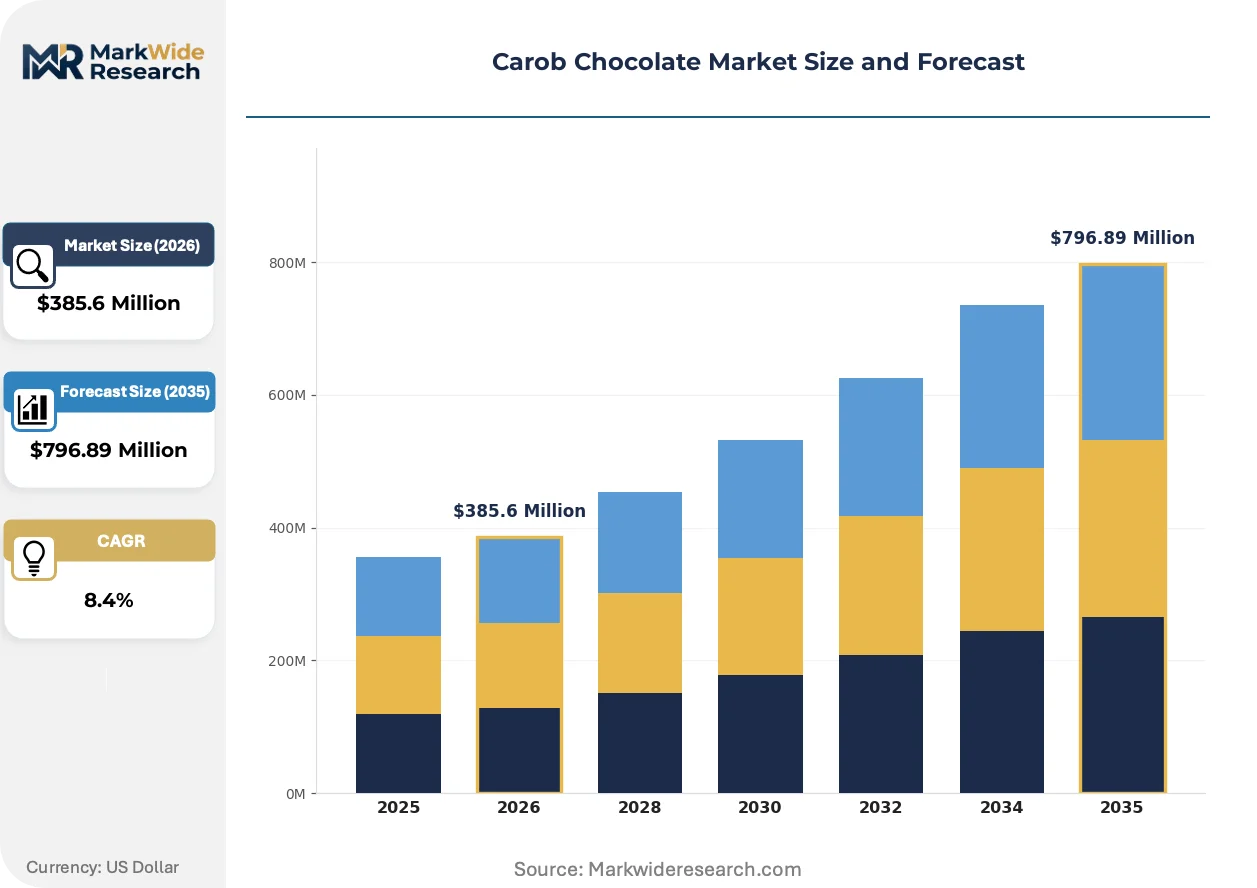
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bars, Chips, Powder, Coating End User: Retailers, Bakeries, Cafés, Health Food Stores Packaging Type: Bags, Boxes, Pouches, Bulk Distribution Channel: Online, Supermarkets, Specialty Stores, Food Services |
| Companies Covered | The Carob Kitchen, D&D Chocolates, The Hain Celestial Group, Inc., NOW Foods, Carob World, The Australian Carob Co., Foundations Food, Iswari, Missy J's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carob Chocolate Market Strategic Shifts & Innovations
Product innovation is shifting the market's identity from a simple chocolate alternative to a distinct, premium ingredient class. This evolution is driven by processing technology advancements, stricter labeling rules, and new direct-to-consumer purchasing behaviors.
Advanced micro-grinding techniques are creating ultra-fine carob powders that offer superior solubility and texture. Food manufacturers, particularly in the functional beverage and dairy-alternative sectors, are adopting these powders. This improved ingredient quality is supplanting traditional, coarser carob flours in premium formulations, enabling a smoother mouthfeel and wider application in high-value products.
Stringent food information regulations from bodies like the U.S. FDA and the European Food Safety Authority (EFSA) mandate clear nutritional and ingredient declarations. This regulatory environment forces manufacturers to be explicit about product attributes, including the absence of stimulants like caffeine. The specialty and health food store channel is most impacted, as it uses these validated "free-from" claims as a primary marketing tool.
Consumer purchasing behavior is moving away from incidental retail discovery toward intentional buys through online channels and specialty health stores. This direct-to-consumer shift disrupts traditional distribution models dominated by large grocers. This pattern is most pronounced in developed markets like Germany and Australia, where brand stories around provenance and production methods strongly influence buyer choice.
Carob Chocolate Market Segmentation
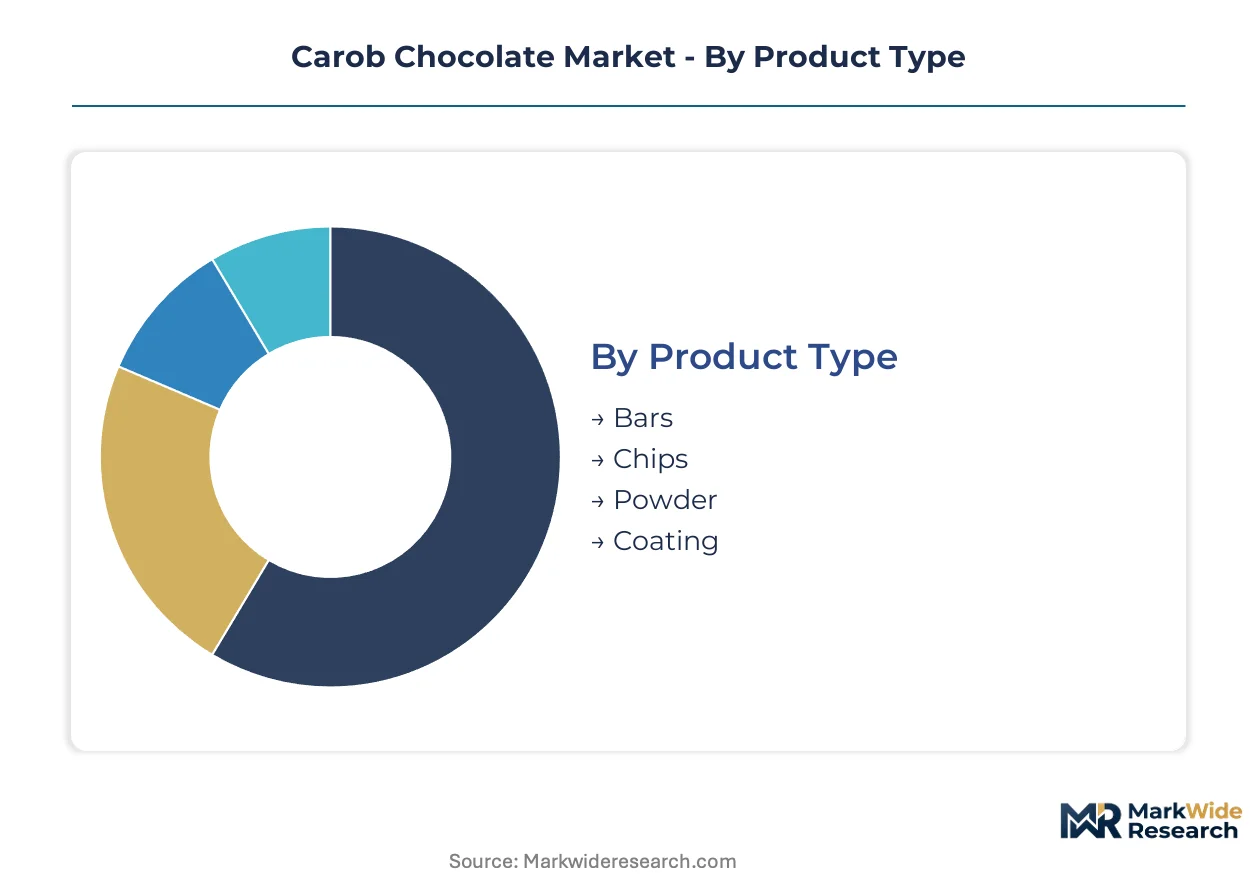
The Carob Chocolate Market segmentation provides a granular view of product forms, end-user applications, packaging solutions, and distribution pathways. This detailed breakdown helps manufacturers align product development and marketing strategies with specific consumer needs and channel requirements. Understanding these segments is crucial for identifying growth pockets and optimizing market penetration efforts.
Product Type:
Regulatory mandates influence how carob chocolate product types are formulated and marketed, particularly regarding ingredient transparency and health claims.
- Powder:This form represents the foundational ingredient derived from dried and roasted carob pods, offering natural sweetness and a caffeine-free profile. Food manufacturers widely adopt carob powder for functional beverages, dairy alternatives, and baking applications, particularly in health-oriented product lines.
- Bars:Finished carob chocolate bars serve as a direct-to-consumer confectionary product, often positioned as a premium or specialty item. These bars target consumers seeking a chocolate substitute with specific dietary benefits, frequently sold through online channels and health food stores.
- Chips:Carob chips are small, solid pieces used primarily as an ingredient in baking, cereals, and trail mixes. They provide a convenient, pre-portioned option for adding carob flavor and texture to various food products.
- Coating:Carob coating is a ready-to-use ingredient for confectionery and snack manufacturers, offering a chocolate-like shell for various food items. It caters to producers creating allergen-friendly or caffeine-free treats.
Carob Powder handles the majority of throughput; Carob Bars are the fastest mover on share.
End User:
Different end-user segments demand carob chocolate products tailored to their specific operational needs and customer preferences.
- Health Food Stores:These specialized retailers cater to consumers with specific dietary needs and preferences, offering a curated selection of carob chocolate products. Health food stores leverage carob's "free-from" attributes, such as being caffeine-free and naturally sweet, as primary marketing points.
- Bakeries:The bakery industry utilizes carob powder and chips as bulk ingredients for developing allergen-free and health-oriented menu items. Carob provides a versatile, natural sweetener and chocolate alternative for a range of baked goods, from cookies to cakes.
- Retailers:General retailers, including supermarkets and grocery stores, distribute carob chocolate products to a broader consumer base. These channels focus on accessibility and convenience for mainstream consumers exploring healthier confectionery options.
- Cafés:Cafés incorporate carob products into beverages and desserts, offering caffeine-free and alternative menu items. Carob powder can be used in lattes, smoothies, and baked goods to expand their health-conscious offerings.
Health Food Stores drive the largest revenue generation; Cafés exhibit the most dynamic expansion.
Packaging Type:
Packaging types for carob chocolate reflect both consumer convenience and industrial volume requirements.
- Bulk:Bulk packaging caters primarily to food service providers, industrial manufacturers, and large-scale bakeries requiring significant quantities of carob powder or chips. This format prioritizes cost-effectiveness and operational efficiency for high-volume users.
- Bags:Bags are a common retail packaging format for carob chips and powders, offering resealable options for consumer convenience. This type is prevalent in grocery stores and health food sections for home use.
- Boxes:Boxes are frequently used for premium carob chocolate bars or gift sets, offering enhanced product protection and aesthetic appeal. This packaging conveys a higher perceived value for specialty items.
- Pouches:Pouches provide a flexible, lightweight, and often resealable option for carob snacks or smaller quantities of powder. This packaging type appeals to consumers seeking convenience and portion control.
Volume concentration rests with Bulk packaging; Pouches are rapidly gaining traction.
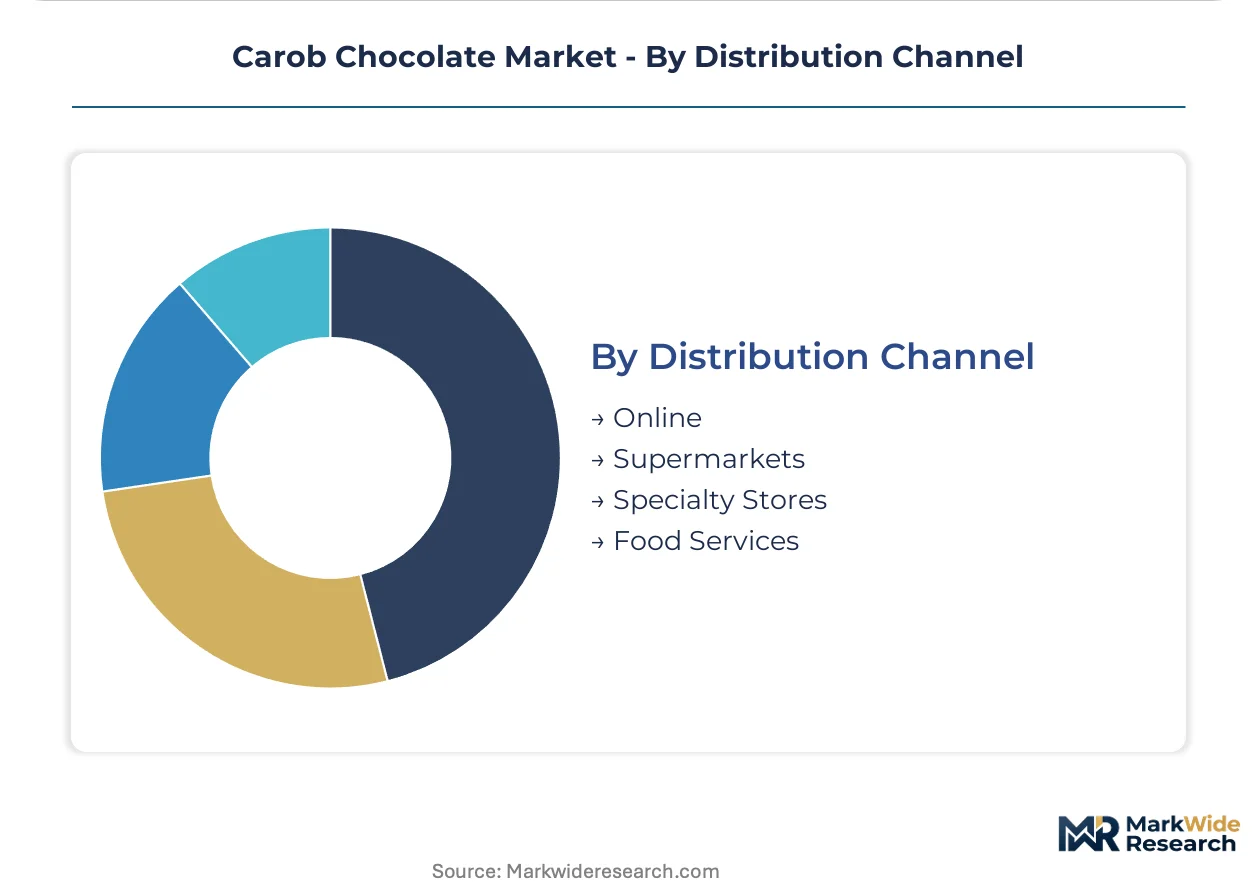
Distribution Channel:
Distribution channels for carob chocolate products demonstrate varying margin structures and reach different consumer demographics.
- Online:E-commerce platforms serve as a crucial channel for direct-to-consumer sales, enabling niche brands to reach a global audience. Online sales capitalize on provenance-focused buyers and those seeking specific dietary products not readily available locally.
- Specialty Stores:Specialty stores, including health food stores and organic markets, stock a curated selection of carob chocolate products, emphasizing their natural and "free-from" attributes. These stores provide expert advice and cater to a discerning, health-conscious clientele.
- Supermarkets:Supermarkets offer broad accessibility for carob chocolate products, making them available to mainstream consumers alongside traditional confectionery items. This channel focuses on convenience and wider market penetration for established brands.
- Food Services:The food services channel involves the supply of carob ingredients, such as powder and chips, to bakeries, cafes, and restaurants. This B2B segment focuses on bulk orders and consistent quality for ingredient applications.
Online channels command the highest average transaction value; Food Services are expanding their footprint most significantly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration influences regional market development for carob chocolate, particularly among health-conscious consumers. This demand shift empowers specialized health food stores and online platforms in developed markets. Regulatory frameworks also dictate product formulation and marketing strategies across distinct geographies.
United States
Consumers in the United States increasingly seek caffeine-free alternatives and clean label products, driving demand for carob chocolate. The FDA's food labeling requirements ensure transparent ingredient and nutritional information for carob products. Major health food store chains in urban centers like New York and Los Angeles significantly boost product visibility and sales.
Germany
German consumers show strong interest in functional foods and "free-from" products, aligning with carob chocolate's attributes. The European Food Safety Authority (EFSA) sets stringent criteria for health and nutritional claims on food packaging. Berlin's vibrant organic food scene and numerous specialty retailers actively promote premium carob bars.
Australia
Australian buyers prioritize provenance and natural ingredients, creating a strong market for carob products. The Therapeutic Goods Administration (TGA) influences how health-related claims are presented on food and supplements. The Australian Carob Co., based in rural South Australia, exemplifies the "tree-to-bar" production model for local and export markets.
Japan
Japanese consumers are increasingly interested in functional snacks and health-conscious confectionery, offering a growth opportunity for carob. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates food additives and functional food ingredients. Tokyo's innovative food sector actively introduces new carob-based spreads and ready-to-drink beverages.
United Kingdom
Demand in the United Kingdom comes from consumers with specific dietary needs and those seeking alternative confectionery. The UK Food Standards Agency (FSA) governs food information and safety standards for all products. London's independent health food shops and growing online retailers are expanding the reach of carob products.
Carob Chocolate Market Key Industry Players
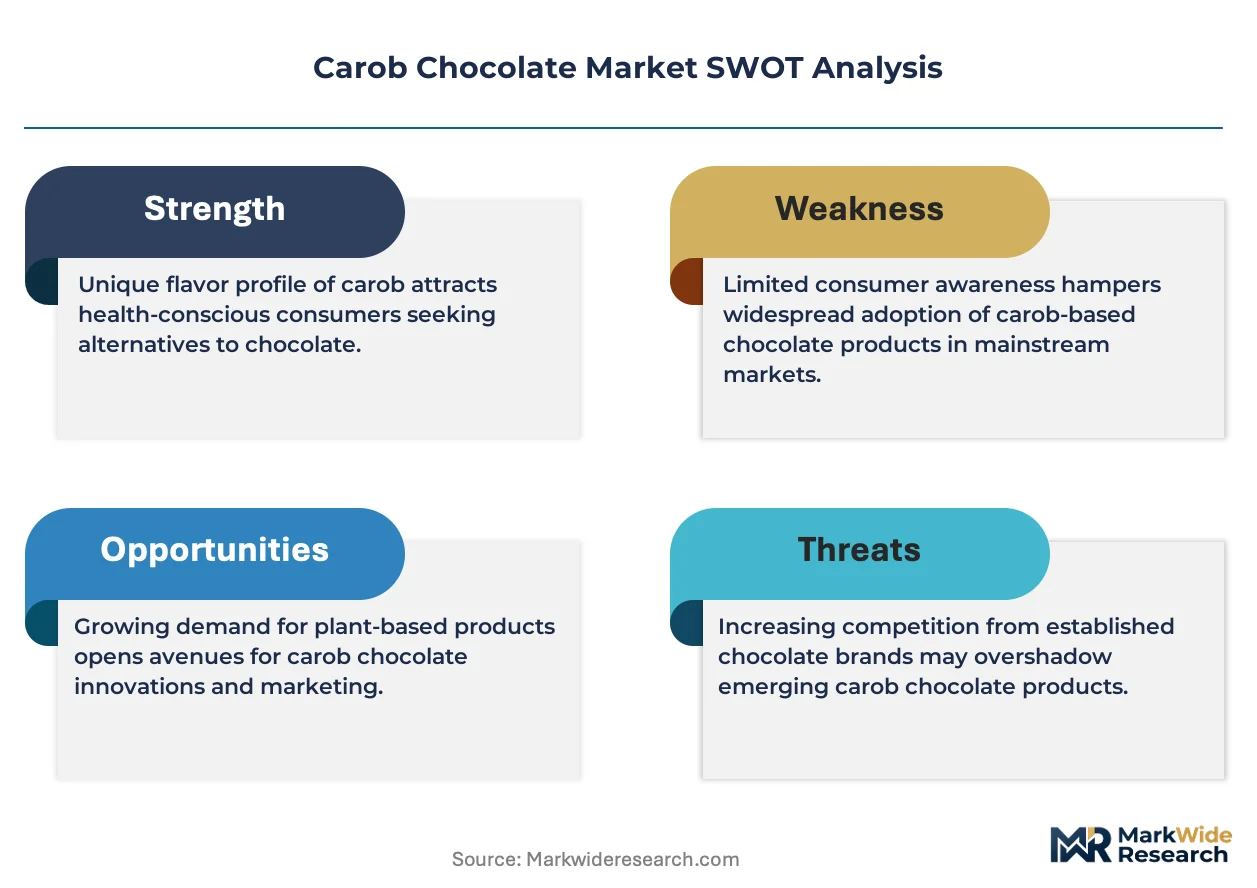
Player mix skews toward specialized niche brands and ingredient suppliers within the carob chocolate market. The market structure remains fragmented, with distinct tiers emerging between bulk ingredient providers and finished product manufacturers. Strategic archetypes include boutique producers, large-scale ingredient suppliers, and diversified food conglomerates. Dominant competitive moves include geographic expansion into underpenetrated markets and extensive product line extension.
Among the established entities, The Hain Celestial Group, Inc. exemplifies a larger food conglomerate leveraging extensive distribution networks in North America and Europe. NOW Foods occupies a position as a significant ingredient supplier, specializing in bulk carob powder for various food manufacturers. The Australian Carob Co. represents a boutique producer archetype, emphasizing "tree-to-bar" production and provenance for discerning buyers.
| Leading Market Players |
|---|
| The Carob Kitchen |
| D&D Chocolates |
| The Hain Celestial Group, Inc. |
| NOW Foods |
| Carob World |
| The Australian Carob Co. |
| Foundations Food |
| Iswari |
| Missy J's |
| Others |
Cost & Logistics Intelligence
Updated food labeling regulations from the FDA and EFSA gate both supply qualification for carob products and price differentiation for certified "free-from" options. This regulatory environment directly influences market access and premium pricing strategies.
Pricing Analysis
Cost-plus contract patterns, often indexed to raw carob pod prices, dominate bulk ingredient transactions for food manufacturers. Price differentiation stems from certification levels, such as organic or fair-trade status, and brand premium for provenance-focused products like "tree-to-bar" carob bars. Pricing pressure stems from higher input costs for niche carob cultivation compared to large-scale cocoa production. Health food stores and direct-to-consumer buyers for premium bars exhibit lower price sensitivity, while bakeries and food service providers purchasing bulk carob powder are more price-sensitive.
Supply Chain Analysis
Inventory and lead-time observations reveal a supply chain anchored by seasonal agricultural cycles. Geographic supply concentration for carob pods centers on Mediterranean climates, particularly in Spain, Italy, and Australia. Raw material dependencies include carob pods and specialized roasting/grinding equipment. A structural supply chain risk involves regional climate events or agricultural challenges impacting carob tree yields. Distribution runs through a dual model, with bulk ingredients supplied to food manufacturers and finished goods distributed via online channels and specialty retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Carob Chocolate Market exhibits a shift in buyer power, driven by the fragmentation of health-conscious consumers seeking specialized dietary products.
For Market Incumbents:Secure long-term supply contracts for carob pods to mitigate geographic supply concentration risks and ensure raw material consistency. Invest in advanced processing technologies to create ultra-fine carob powders, addressing demands from functional beverage and dairy-alternative sectors. The threat of mainstream chocolate brands entering the carob space necessitates continuous product innovation and robust certification investment. Control over distribution networks, especially in North America and Europe, remains a critical lever for sustaining market position.
For New Entrants and Emerging Players:Anchor in underpenetrated health-conscious markets in Asia, such as Japan and South Korea, where demand for functional snacks is rising. Target product line extension into new formats like carob-based spreads, syrups, and ready-to-drink beverages to open novel consumption categories. The most penetrable segment for new brands involves direct-to-consumer sales through online channels, emphasizing unique provenance and "free-from" claims as a primary go-to-market angle.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting in an upward direction across the specialized processing and certification segments, indicating a need for strategic investment. The long-term viability of the carob chocolate market remains strong within the functional food and alternative confectionery categories. Acquisition target archetypes include niche brands with established "free-from" positioning or companies possessing proprietary micro-grinding technologies. The signal to watch for further investment opportunities is the growth in functional food certifications and mainstream retailer adoption of premium carob products.
| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Expansion into Asia | Accesses new health-conscious consumer bases in Japan and South Korea. |
| Product Line Diversification | Creates new consumption occasions with carob-based spreads and beverages. |
| Functional Fortification Research | Enhances product appeal with added probiotics or plant-based proteins. |
| Direct-to-Consumer Channel Investment | Captures higher margins and strengthens brand relationship with buyers. |
| Sustainable Sourcing Certification | Appeals to provenance-focused consumers and ensures supply chain resilience. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and rigorous secondary validation. Primary insights came from health food store owners, carob product manufacturers, and food service procurement managers. Secondary sources included FDA filings, EFSA guidance documents, and agricultural statistics from carob-producing regions, ensuring bottom-up and top-down triangulation.
The forecasting boundary extends over the projection horizon, utilizing a quantitative model to assess market dynamics. Segmentation dimensions modeled included product type, end-user applications, packaging solutions, distribution channels, and regional demand patterns. Compound annual growth rates were derived from historical data and projected market shifts, incorporating inputs such as evolving consumer dietary trends and regulatory changes in food labeling.
Decision-makers should treat outputs as directional under base assumptions, including stable carob cultivation conditions and consistent regulatory enforcement; material deviation would warrant model refresh. Unforeseen climate events impacting carob harvests or rapid shifts in consumer preferences represent key risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Macarons Market
Confectionery
CBD-Infused Confectionery Market
Confectionery
Canada Chocolate Market
Confectionery
Sugar-Free Gumballs Market
Confectionery
Caramel Market
Confectionery
Vegan Gummy Candy Market
Confectionery
Middle-East and Africa Compound Chocolate Market
Confectionery
Bean-To-Bar Chocolate Market
Confectionery
Middle East and Africa Chocolate Market
Confectionery
Dietary Chocolate Products Market
Confectionery
Caramel Chocolate Market
Confectionery
India Chocolate Market
Confectionery
Ice Cream Coating Market
Confectionery
Jellies and Gummies Market
Confectionery
North America Compound Chocolate Market
Confectionery
North America Sugar Confectionery Market