
 Oryzanol Market | 2026-2036
Oryzanol Market Size, Share, and Industry Trends Forecast 2026-2036
Oryzanol Market Analysis
Buyer concentration among health supplement producers is restructuring procurement dynamics across the oryzanol value chain. Oryza Oil & Fat Chemical Co. Ltd. leverages its integrated rice bran oil extraction infrastructure to dominate supply of high-purity fractions. Ricela Group of Companies anchors South Asian raw material flows through backward control over rice milling coproduct streams. Kangcare Bioindustry Co. Ltd. specializes in pharmaceutical-grade refinement, competing on certification depth rather than volume scale.
Oryzanol comprises a mixture of ferulic acid esters of sterols and triterpene alcohols extracted primarily from rice bran oil, typically containing 1-3% by weight in crude bran and concentrated to 90%+ purity for commercial applications; it functions as a natural antioxidant, cholesterol modulator, and UV-absorbing agent across food preservation, nutraceutical, and cosmetic formulations. Rice bran oil as a source category leads volume throughput due to established extraction economics and coproduct availability from rice milling, while nutraceuticals as an application segment captures the fastest growth trajectory as consumers shift toward plant-derived cholesterol management solutions. Powder and capsule forms command margin premiums over liquid extracts because of dosing precision and stability in finished supplement formats.
FDA dietary supplement regulations and cGMP compliance requirements shape product standards for U.S. market access, while EFSA novel food assessments govern European incorporation into fortified foods. Japan's Ministry of Health, Labour and Welfare maintains positive listing requirements for functional food ingredients, directly influencing formulation decisions by domestic and export-oriented manufacturers. Stakeholders must monitor evolving pharmacopeial monograph standards for sterol ester content and ferulic acid specification thresholds across multiple jurisdictions.
Market Dynamics
Buyer consolidation among nutraceutical formulators is compressing supplier margins while simultaneously demanding higher purity grades and documented ferulic acid specifications from rice bran extractors.
Growth Catalysts
- FDA Dietary Supplement cGMP Enforcement:Tightened purity verification requirements are disqualifying low-grade oryzanol suppliers and redirecting procurement toward certified extractors capable of 90%+ ferulic acid documentation.
- Japan's Functional Food Positive Listing System:Ministry of Health, Labour and Welfare approval of oryzanol for cholesterol management claims creates a regulatory template that export-oriented manufacturers replicate for adjacent Asian markets.
- Supercritical CO2 Extraction:Adoption of solvent-free concentration methods by pharmaceutical-grade refiners enables sterol ester preservation at thresholds meeting pharmacopeial monograph standards.
Market Restraints
- Rice Bran Supply Concentration:Over 70% of global rice milling coproduct flows through South Asian processors, creating geographic vulnerability to monsoon-driven harvest volatility and export restriction cascades.
- Phytosterol Substitution:Soy-derived beta-sitosterol and pine sterol formulations compete directly on cholesterol management positioning, often at lower unit economics for mass-market supplement brands.
- EFSA Novel Food Assessment Delays:European fortification applications face 18-24 month evaluation timelines that freeze formulation investments by food manufacturers seeking cholesterol-reduction claims.
Strategic Opportunities
- Cosmeceutical UV-Absorption Applications:Oryzanol's natural photoprotective properties position it as a mineral sunscreen alternative in Korean and Japanese skincare formulations targeting clean beauty positioning.
- India's Nutraceutical PLI Scheme:Production-linked incentives for domestic value-added extraction create cost-competitive supply bases for export to Middle Eastern and African markets.
- Direct-to-Consumer Capsule Channels:Subscription supplement platforms bypass traditional distributor markups, enabling premium pricing for single-ingredient oryzanol products with transparent supply chain storytelling.
Industry Challenges
- Analytical Chemist Shortage:Ferulic acid quantification via HPLC and sterol ester profiling require specialized technicians that rice bran processors struggle to recruit outside established pharmaceutical corridors.
- Multi-Jurisdictional Monograph Harmonization:Divergent specification thresholds between USP, EP, and JP standards force manufacturers to maintain parallel inventory batches or absorb reformulation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oryzanol Market |
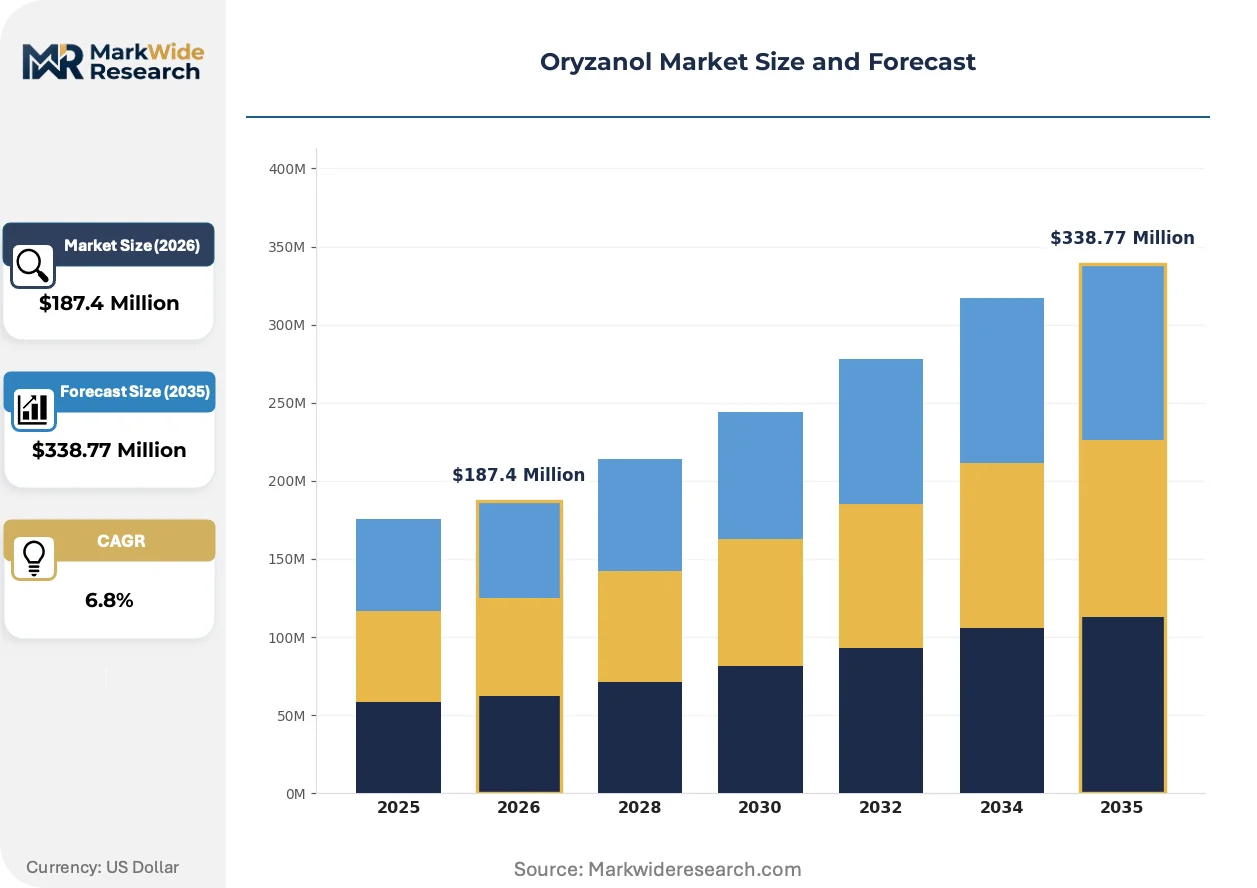
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat Germ Oil, Rice Bran Oil, Sunflower Oil, Palm Oil Application: Food Industry, Pharmaceutical Industry, Nutraceuticals, Cosmetics End User: Food Manufacturers, Health Supplement Producers, Cosmetic Brands, Pharmaceutical Companies Form: Liquid, Powder, Gel, Capsule |
| Companies Covered | NutriScience Innovations, LLC, Santa Cruz Biotechnology, Inc., Oryza Oil & Fat Chemical Co. Ltd., Jining Ankang Pharmaceutical Co. Ltd., Kangcare Bioindustry Co. Ltd., TSUNO Group, Alfa Chemistry, KRBL Limited, Ricela Group of Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oryzanol Market Emerging Trajectories
Extraction technology maturation and regulatory claim standardization are converging to reposition oryzanol from commodity antioxidant to precision nutraceutical ingredient with documented clinical endpoints.
Supercritical fluid extraction systems are expanding into commercial-scale rice bran oil processing, replacing hexane-based methods that degrade heat-sensitive sterol esters. Japanese and Korean pharmaceutical contract manufacturers are retrofitting existing botanical extraction lines to handle oryzanol concentration at tonnage scales previously reserved for tocopherol production. This capital deployment is compressing the premium gap between food-grade and pharmaceutical-grade fractions.
REACH registration requirements for sterol ester imports into the European Union are forcing non-EU extractors to submit full toxicological dossiers or partner with EU-based formulators holding existing substance registrations. The industrial consequence is a bifurcation between suppliers capable of regulatory data generation and those confined to Asian domestic markets. Nutraceutical brands targeting European distribution are consolidating procurement around REACH-registered sources despite 15-20% price premiums.
Long-term supply agreements with documented ferulic acid specifications are displacing spot market purchasing among mid-sized supplement brands. Direct contracts with rice bran oil processors eliminate multiple broker layers that previously obscured origin documentation. This procurement consolidation is most visible in the United States, where FDA cGMP audit trails now require supplier qualification records that spot transactions cannot satisfy.
Oryzanol Market Segmentation
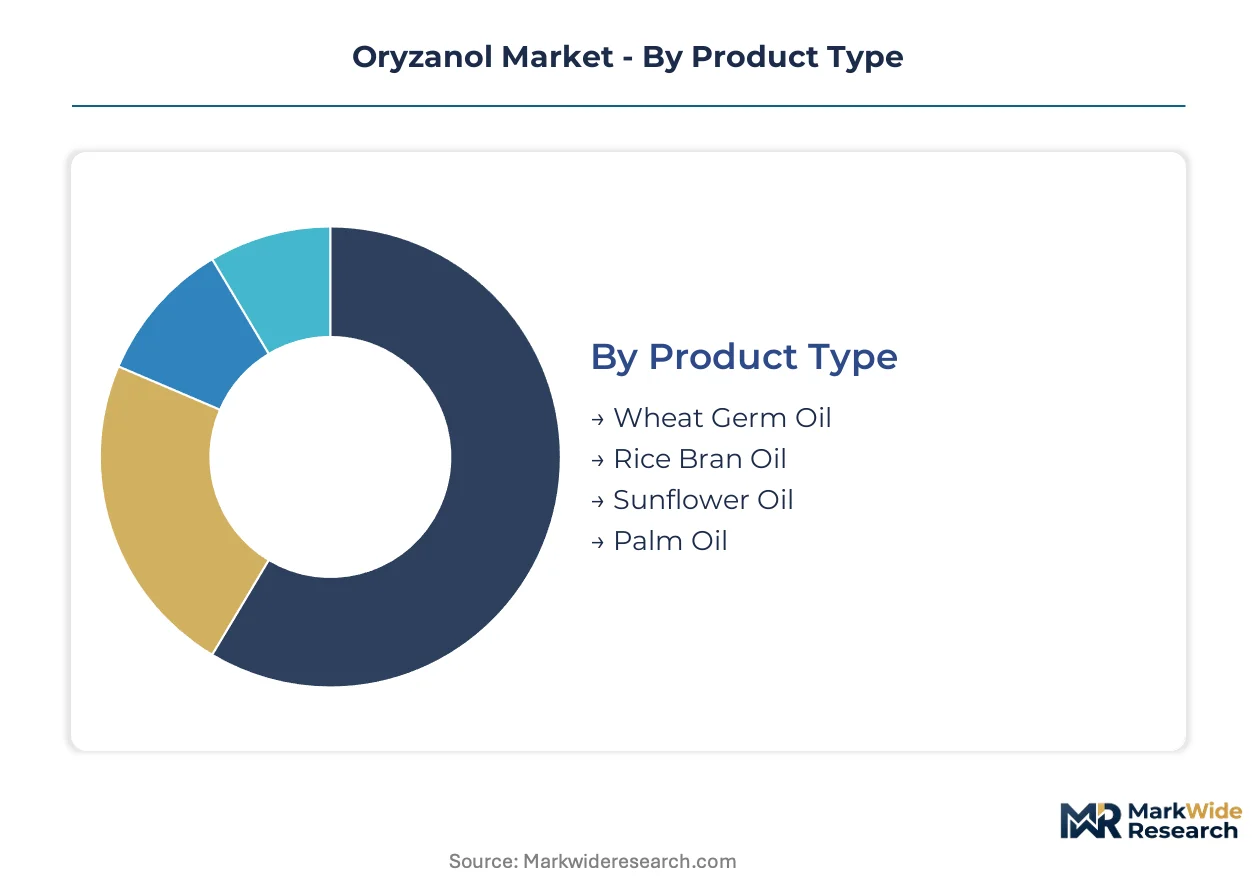
Oryzanol sourcing and formulation decisions track evolving extraction economics and end-use certification requirements. Manufacturers upgrade from commodity oils to refined concentrates as regulatory documentation demands intensify across pharmaceutical and nutraceutical channels.
Product Type:
Feedstock selection determines achievable purity thresholds and ferulic acid concentration profiles, with processors upgrading from crude oils to refined extracts as specification requirements tighten.
- Rice Bran Oil:Dominates commercial extraction due to 1-3% native oryzanol content and established coproduct economics from rice milling operations. Japanese and South Korean pharmaceutical contract manufacturers concentrate procurement here for pharmacopeial-grade refinement. Volume placements concentrate in rice bran oil; the faster expansion belongs to wheat germ oil.
- Wheat Germ Oil:Contains comparable sterol ester complexes with distinct tocopherol co-fractions that appeal to clean-label cosmetic formulators. German and French skincare manufacturers source this feedstock for UV-absorption applications where rice-derived positioning carries allergen labeling complications.
- Sunflower Oil:Offers lower native concentrations requiring more intensive concentration steps, limiting adoption to specialty antioxidant applications in Eastern European food preservation.
- Palm Oil:Competes on raw material scale but faces sustainability certification barriers that restrict uptake among European and North American nutraceutical brands.
Refiners with supercritical CO2 capabilities extract premium margins from rice bran and wheat germ fractions while commodity hexane processors handle palm and sunflower volumes.
Application:
End-use certification depth separates margin tiers, with pharmaceutical and nutraceutical channels demanding documentation that food and cosmetic applications often bypass.
- Nutraceuticals:Captures steepest expansion trajectory as cholesterol management claims drive consumer pull through direct-to-consumer capsule channels. FDA cGMP compliance and ferulic acid specification documentation separate qualified suppliers from commodity extractors.
- Pharmaceutical Industry:Requires sterol ester preservation at thresholds meeting USP, EP, and JP monograph standards. Japanese PMDA and Korean MFDS registration pathways favor extractors with dedicated pharmaceutical-grade production lines.
- Food Industry:Concentrates volume in Asian markets where Japan's Ministry of Health, Labour and Welfare positive listing system enables functional food positioning.
- Cosmetics:Korean and Japanese skincare formulators exploit natural UV-absorption properties for mineral sunscreen alternatives in clean beauty positioning.
Regulatory documentation requirements stratify supplier access, with nutraceutical and pharmaceutical channels consolidating procurement around certified extractors.
End User:
Procurement sophistication varies sharply across customer categories, with health supplement producers and pharmaceutical companies driving specification upgrades that food manufacturers often defer.
- Health Supplement Producers:U.S.-based brands facing tightened FDA dietary supplement regulations scale procurement of 90%+ purity fractions with documented ferulic acid specifications. Direct contracting with rice bran oil processors eliminates documentation gaps that spot market purchasing creates.
- Pharmaceutical Companies:Demand REACH-registered sources for European market access despite price premiums, consolidating procurement around extractors capable of toxicological dossier generation.
- Food Manufacturers:Prioritize volume scale and cost efficiency in Asian functional food applications where positive listing requirements govern formulation decisions.
- Cosmetic Brands:Korean and Japanese clean beauty positioning drives interest in natural photoprotective claims with supply chain transparency requirements.
Buyer consolidation among health supplement and pharmaceutical customers compresses supplier margins while simultaneously demanding purity upgrades that commodity extractors cannot satisfy.
Form:
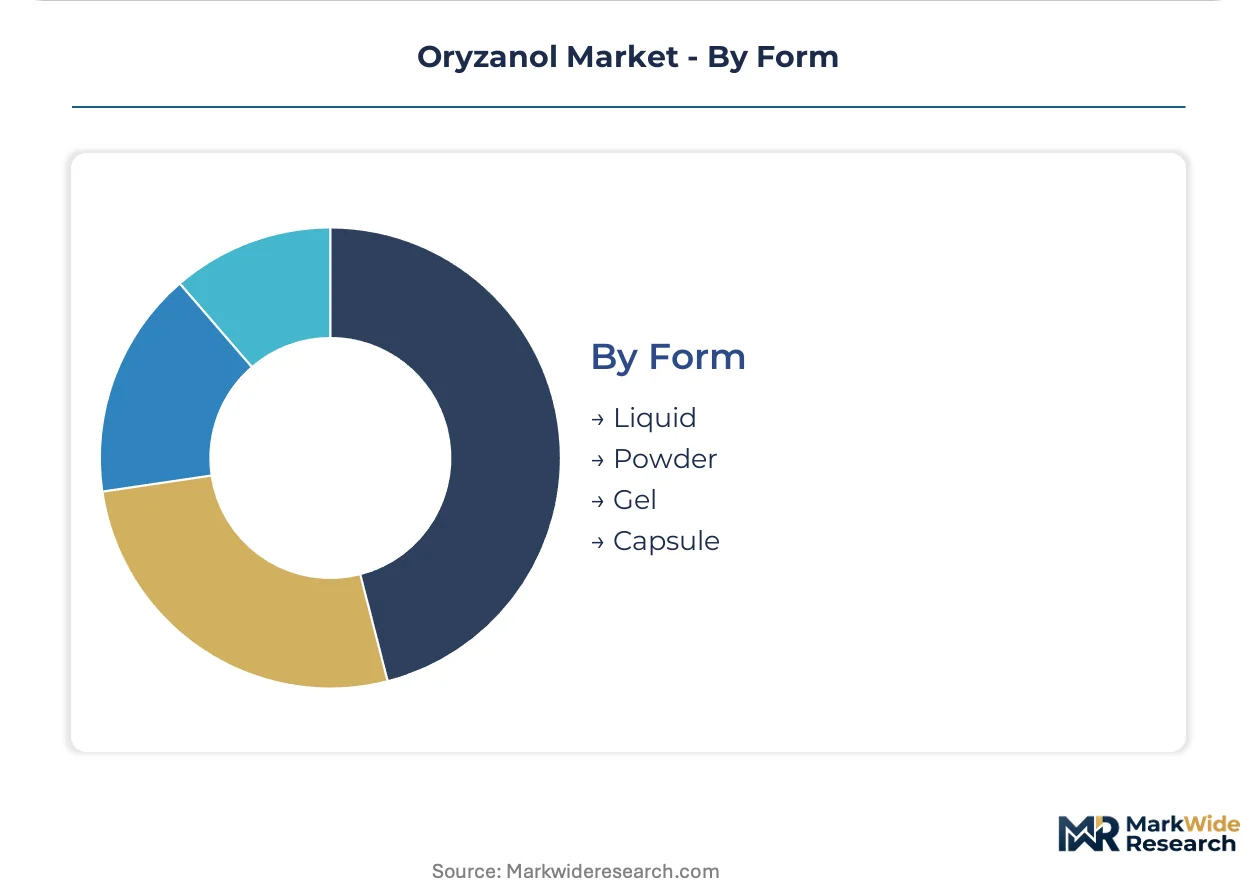
Dosing precision and stability requirements determine format selection, with solid forms commanding premium positioning over liquid extracts in finished product applications.
- Capsule:Delivers margin premiums through dosing precision and consumer convenience in direct-to-consumer subscription channels. U.S. and Japanese supplement brands favor this format for single-ingredient oryzanol products with transparent supply chain storytelling.
- Powder:Enables flexible formulation integration across multiple finished product categories, with pharmaceutical-grade micronization supporting tableting operations.
- Liquid:Concentrates in food industry applications and cosmetic formulations where solubility and blending simplicity outweigh stability concerns.
- Gel:Serves topical cosmetic applications where skin penetration and sensory properties drive formulation decisions.
Finished format selection tracks end-use channel requirements, with capsule and powder forms gaining share in premium nutraceutical positioning while liquid retains food industry volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan concentrates the most sophisticated oryzanol demand, with health supplement producers in the United States and nutraceutical formulators across Asia-Pacific scaling procurement of certified extracts. Regulatory claim pathways and extraction infrastructure determine regional competitive positioning.
Japan
TSUNO Group and domestic nutraceutical manufacturers anchor supply chains for rice bran-derived extracts. The Ministry of Health, Labour and Welfare maintains positive listing requirements for functional food ingredients, directly influencing formulation decisions by export-oriented manufacturers. Tokyo-Osaka industrial corridors house pharmaceutical-grade refiners capable of meeting pharmacopeial monograph standards.
United States
Health supplement producers scale procurement of oryzanol-enriched formulations as FDA dietary supplement regulations tighten purity and labeling requirements for bioactive compounds. FDA cGMP enforcement redirects procurement toward certified extractors capable of 90%+ ferulic acid documentation. California and New Jersey supplement manufacturing clusters drive specification upgrades among rice bran oil processors.
India
KRBL Limited and Ricela Group of Companies control South Asian raw material flows through backward integration into rice milling coproduct streams. The Production-Linked Incentive scheme for domestic value-added extraction creates cost-competitive supply bases for export to Middle Eastern and African markets. Punjab and Haryana rice processing belts concentrate extraction infrastructure.
China
Jining Ankang Pharmaceutical Co. Ltd. and Kangcare Bioindustry Co. Ltd. specialize in pharmaceutical-grade refinement, competing on certification depth rather than volume scale. The National Medical Products Administration governs registration pathways for sterol ester ingredients entering clinical applications. Shandong and Jiangsu provinces host supercritical CO2 extraction facilities serving export markets.
South Korea
Cosmeceutical formulators exploit oryzanol's natural UV-absorption properties for mineral sunscreen alternatives in clean beauty positioning. The Ministry of Food and Drug Safety regulates functional cosmetic claims involving photoprotective ingredients. Seoul-Incheon bioclusters integrate oryzanol into skincare formulations targeting domestic and Southeast Asian distribution.
Oryzanol Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade certification and cosmeceutical specialization. The supplier base stratifies between commodity rice bran oil processors and dedicated extractors capable of ferulic acid documentation. Three archetypes dominate: integrated rice millers with captive bran supplies, pharmaceutical contract manufacturers with supercritical extraction capabilities, and specialist refiners competing on purity grades. Capacity expansion and strategic partnerships with nutraceutical brands constitute the dominant competitive moves.
Within the integrated processor tier, Oryza Oil & Fat Chemical Co. Ltd. and Ricela Group of Companies exemplify backward control over raw material flows. TSUNO Group represents the Japanese functional food specialist archetype, while Kangcare Bioindustry Co. Ltd. occupies a position emphasizing certification depth. These named entities anchor industry-level commentary on extraction economics and regulatory compliance without implying specific strategic actions or market positions.
| Leading Market Players |
|---|
| NutriScience Innovations, LLC |
| Santa Cruz Biotechnology, Inc. |
| Oryza Oil & Fat Chemical Co. Ltd. |
| Jining Ankang Pharmaceutical Co. Ltd. |
| Kangcare Bioindustry Co. Ltd. |
| TSUNO Group |
| Alfa Chemistry |
| KRBL Limited |
| Ricela Group of Companies |
| Others |
Supply Flow & Price Mechanics
Analytical chemist scarcity in Shandong and Jiangsu provinces widens the spread between pharmaceutical-grade and commodity-grade oryzanol pricing tiers, as HPLC-capable technicians command wage premiums that smaller rice bran processors cannot absorb.
Pricing Analysis
Volume throughput concentrates in commodity rice bran oil fractions while margin capture concentrates in certified extracts. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered pharmaceutical grades from food-grade concentrates and crude oil commodities. Cost compression in the standard tier is intensifying because buyer consolidation among nutraceutical formulators demands ferulic acid documentation without premium-tier certification depth. Health supplement producers in the United States demonstrate the least price sensitivity due to FDA cGMP audit trail requirements, while Asian food manufacturers remain most responsive to per-kilogram differentials.
Supply Chain Analysis
Workforce-availability constraints in Japanese and Korean pharmaceutical corridors limit supercritical CO2 extraction capacity expansion despite equipment installation. Geographic supply concentration centers on India, China, and Japan for extraction infrastructure, with South Asian rice milling operations feeding raw bran streams. The value chain draws from rice bran oil, wheat germ oil, and specialized sterol ester concentrates as primary inputs. Single-source vulnerability runs through South Asian rice milling coproduct flows, where monsoon-driven harvest volatility cascades into export restriction risk. Distribution runs through direct long-term supply agreements that displace spot market purchasing among mid-sized supplement brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oryzanol market functions as a cost-of-compliance story where FDA cGMP enforcement and REACH registration requirements erect barrier-to-entry moats that favor extractors with documented toxicological dossiers and pharmacopeial-grade production lines.
For Market Incumbents: Lock in backward integration into rice milling coproduct streams to defend against phytosterol substitution threats from soy-derived beta-sitosterol competitors. Secure dedicated pharmaceutical-grade production lines in Shandong and Jiangsu provinces to capture certification investment premiums from European nutraceutical brands consolidating procurement around REACH-registered sources.
For New Entrants and Emerging Players: The 15-20% price-point gap between REACH-registered pharmaceutical grades and uncertified commodity concentrates creates white-space opportunity in cosmeceutical UV-absorption applications for Korean and Japanese clean beauty formulators. Target direct-to-consumer capsule channels with transparent supply chain storytelling as the most penetrable route, bypassing traditional distributor markups through subscription supplement platforms.
For Investors and Strategic Acquirers: Re-rating potential sits with supercritical CO2-equipped pharmaceutical contract manufacturers given Japan's Functional Food Positive Listing System expansion into adjacent Asian markets. Extractors with dual USP-JP monograph compliance demonstrate strongest long-term viability through the projection horizon. Watch EFSA novel food assessment timelines as the critical signal for European fortification market unlock.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Enables sterol ester preservation at pharmacopeial thresholds demanded by PMDA and MFDS registrants. |
| REACH Registration Completion | Unlocks European nutraceutical procurement consolidation despite 15-20% price premiums over uncertified alternatives. |
| Backward Integration into Rice Milling | Secures captive bran supply from South Asian processors vulnerable to monsoon-driven export restrictions. |
| Direct-to-Consumer Capsule Launch | Bypasses distributor markups through subscription platforms targeting U.S. health supplement producers. |
| Cosmeceutical UV-Absorption Partnership | Positions natural photoprotective claims with Korean Ministry of Food and Drug Safety functional cosmetic registrants. |
Methodological Framework
Trade databases, pharmacopeial monograph registries, and customs export records formed the secondary backbone, supplemented by primary interviews with rice bran oil extraction plant managers, nutraceutical procurement leads, pharmaceutical regulatory affairs directors, and cosmetic formulator R&D heads. Bottom-up and top-down triangulation validated volume estimates across feedstock categories and application segments.
Bottom-up modeling tracked extraction capacity, purity grade throughput, and end-use certification requirements while top-down analysis cross-referenced regulatory filing patterns and import-export flow data. Segmentation dimensions included feedstock source, application channel, end-user procurement sophistication, and finished formulation format. CAGRs were derived from fitted growth curves calibrated to documented capacity expansion announcements and regulatory approval timelines.
Inputs from FDA cGMP inspection databases and EFSA novel food assessment registries were available through the study window; gaps in real-time South Asian rice milling coproduct volume data introduce uncertainty bands around near-term supply projections. Forecasts reflect assumptions regarding regulatory harmonization pace and extraction technology adoption curves. A small set of triggers—monsoon severity indices, REACH registration completion rates, and EFSA assessment queue lengths—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Flavoring Agents Market
Flavorings and Food Additives
Clean Label Flavors Market
Flavorings and Food Additives
Japan Food Flavor and Enhancer Market
Flavorings and Food Additives
Citrus-Based Sugar-Reduction Flavor Modulators Market
Flavorings and Food Additives
Licorice Extract Market
Flavorings and Food Additives
Water Flavoring Drop Market
Flavorings and Food Additives
Dry Powder Flavors Market
Flavorings and Food Additives
Farnesol Market
Flavorings and Food Additives
Asia-Pacific Flavor and Fragrance Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Flavor Masking Agents Market
Flavorings and Food Additives
All-Natural Flavors System Market
Flavorings and Food Additives
Ginkgo Biloba Extract Market
Flavorings and Food Additives
Browning Solutions Market
Flavorings and Food Additives
Citrus Aromatic Fractions for Mood Support Market
Flavorings and Food Additives
Russia Food Flavor and Enhancer Market